
 Medical Claims Processing Services Market | 2026-2036
Medical Claims Processing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Claims Processing Services Market Insights
India is rewriting how back-office medical claims infrastructure scales for Western payers. UnitedHealth Group leverages captive development centers in Hyderabad and Bengaluru to sustain cost-advantaged processing capacity for U.S. insurers. Cognizant Technology Solutions anchors a similar model, competing on automation depth rather than labor arbitrage alone. Change Healthcare differentiates through cloud-native architecture that positions it for federal interoperability mandates.
Medical claims processing services encompass the verification, adjudication, and payment settlement of healthcare reimbursement requests through electronic data interchange protocols, typically processing claims within 30 days under CMS guidelines. The primary purpose is to reduce administrative waste while ensuring accurate provider compensation and patient cost-sharing calculation. Automated processing leads service type segmentation due to labor cost pressures and error-rate reduction targets, while AI solutions within technology segmentation represent the fastest-expanding margin pool as natural language extraction from clinical documentation matures. Outsourced services occupy a stable, high-volume tier serving mid-market insurers lacking in-house IT scale.
FDA oversight of clinical decision support tools increasingly shapes which AI-enabled claims platforms gain market access, while HIPAA security rules and CMS interoperability standards dictate data architecture investments across vendor portfolios. The EU AI Act and GDPR create parallel compliance burdens for processors serving multinational insurers with European policyholders. Stakeholders must monitor whether CMS final rules on price transparency and prior authorization automation will force legacy system replacements or allow modular API overlays.
Market Dynamics
The transition from fee-for-service to value-based reimbursement is compressing claims processing timelines and demanding real-time adjudication capabilities that legacy infrastructure cannot deliver.
Growth Catalysts
- CMS Interoperability Mandates:Federal rules requiring standardized API access for patient data exchange are forcing payers to modernize core systems, creating replacement demand for cloud-native platforms.
- AI-Enabled Clinical Documentation:Natural language processing tools are extracting diagnosis and procedure codes directly from unstructured physician notes, reducing manual coding labor and error rates.
- United States Hospital Consolidation:Health system mergers are centralizing procurement power and favoring vendors with enterprise-scale automation and multi-state compliance capabilities.
Market Restraints
- HIPAA Security Rule Compliance Costs:Encryption, access logging, and breach notification requirements impose ongoing infrastructure investments that disadvantage smaller regional processors.
- Cloud Concentration Risk:Dominance of Amazon Web Services, Microsoft Azure, and Google Cloud for healthcare workloads creates single-point-of-failure exposure and limited negotiating leverage on pricing.
- Legacy System Technical Debt:COBOL-based mainframe environments at established insurers resist modular API integration, slowing platform modernization cycles.
Strategic Opportunities
- India Captive Delivery Centers:Hyderabad and Bengaluru offer actuarial and clinical coding talent pools at structural cost advantages for Western payer back-office operations.
- FDA Clinical Decision Support Oversight:Regulatory clarity on AI-enabled prior authorization tools creates first-mover advantages for platforms with validated algorithmic transparency.
- Real-Time Claims Adjudication:Instant payment settlement at point-of-service is displacing 30-day batch cycles, opening subscription revenue models for transaction-layer infrastructure.
Industry Challenges
- Certified Medical Coder Shortage:AAPC-credentialed professionals are concentrated in urban United States markets, creating wage inflation and quality variability for remote-first operations.
- Interoperability Standard Fragmentation:Competing FHIR implementation guides across CMS, private payers, and health information exchanges multiply integration testing burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Claims Processing Services Market |
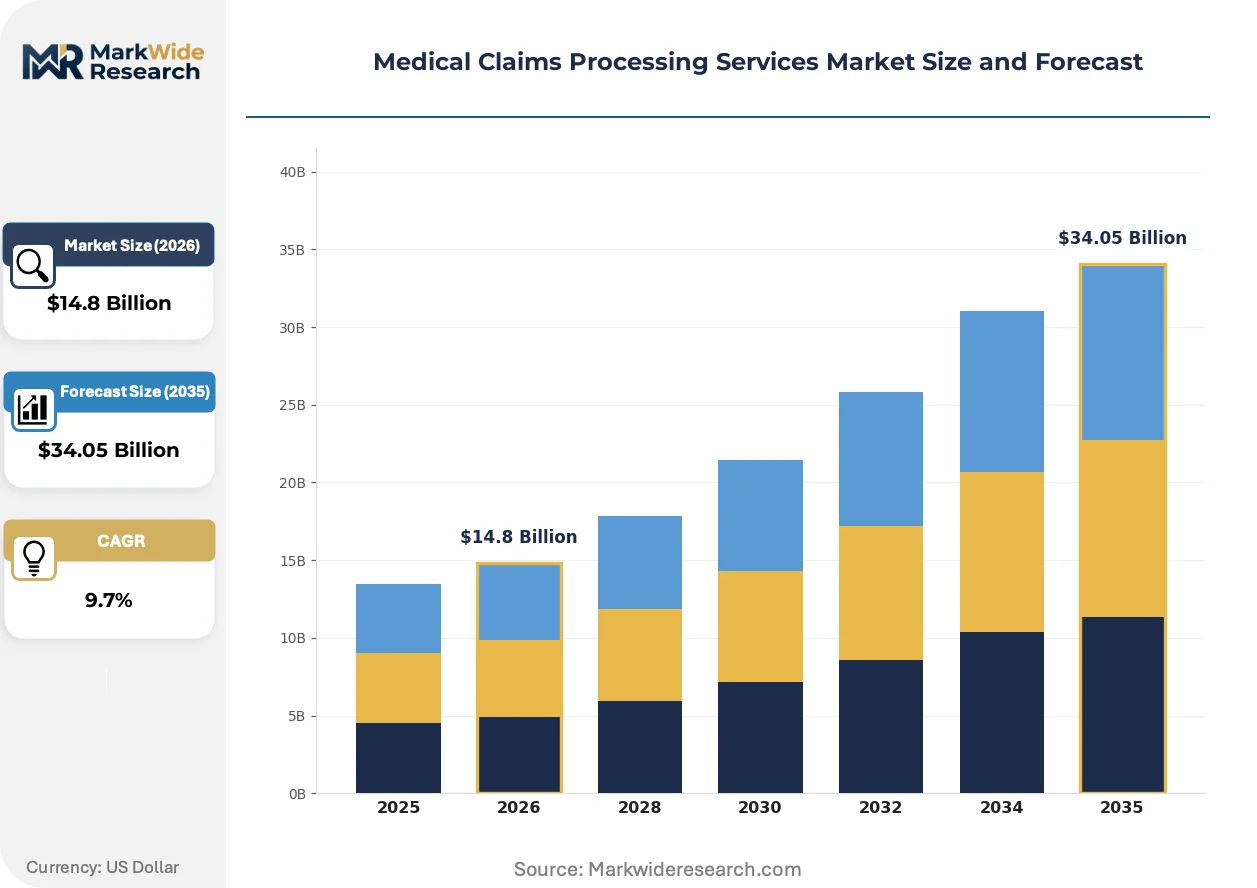
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $34.05 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Automated Processing, Manual Processing, Hybrid Processing, Outsourced Services End User: Hospitals, Clinics, Insurance Providers, Third-Party Administrators Technology: AI Solutions, RPA, Cloud-Based Platforms, Legacy Systems Billing Method: Fee-for-Service, Capitation, Value-Based Billing, Global Budgets |
| Companies Covered | UnitedHealth Group, McKesson Corporation, Athenahealth, Quest Diagnostics, Cerner Corporation, Change Healthcare, Conduent, Cognizant Technology Solutions, eClinicalWorks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Claims Processing Services Market Trends and Innovations
Cloud-native architecture and machine learning are converging to compress claims processing from batch cycles to real-time adjudication, while regulatory pressure on price transparency is exposing historical pricing opacity.
Distributed ledger infrastructure is virtualizing the trust layer between payers and providers. Blockchain-enabled smart contracts are automating payment settlement upon verified service delivery, eliminating reconciliation delays. Large national insurers are piloting these networks for out-of-network claims where traditional EDI protocols fail. The technology is virtualizing intermediary functions previously performed by clearinghouses and manual audit teams.
The EU AI Act's risk classification system is reshaping vendor development priorities for multinational insurers. High-risk AI systems used in prior authorization decisions now require conformity assessments, technical documentation, and human oversight protocols. United States-based platforms with European policyholders must maintain dual compliance tracks, favoring modular architectures that isolate algorithmic components for jurisdiction-specific validation.
Point-of-service payment models are displacing retrospective reimbursement cycles. Patients and providers now expect immediate cost estimates and adjudication, compressing the traditional 30-day window to under 60 seconds. This behavioral shift is most visible in United States ambulatory surgery centers and urgent care chains, where consumer satisfaction scores increasingly depend on billing transparency at encounter completion rather than post-visit statement accuracy.
Medical Claims Processing Services Market Segmentation
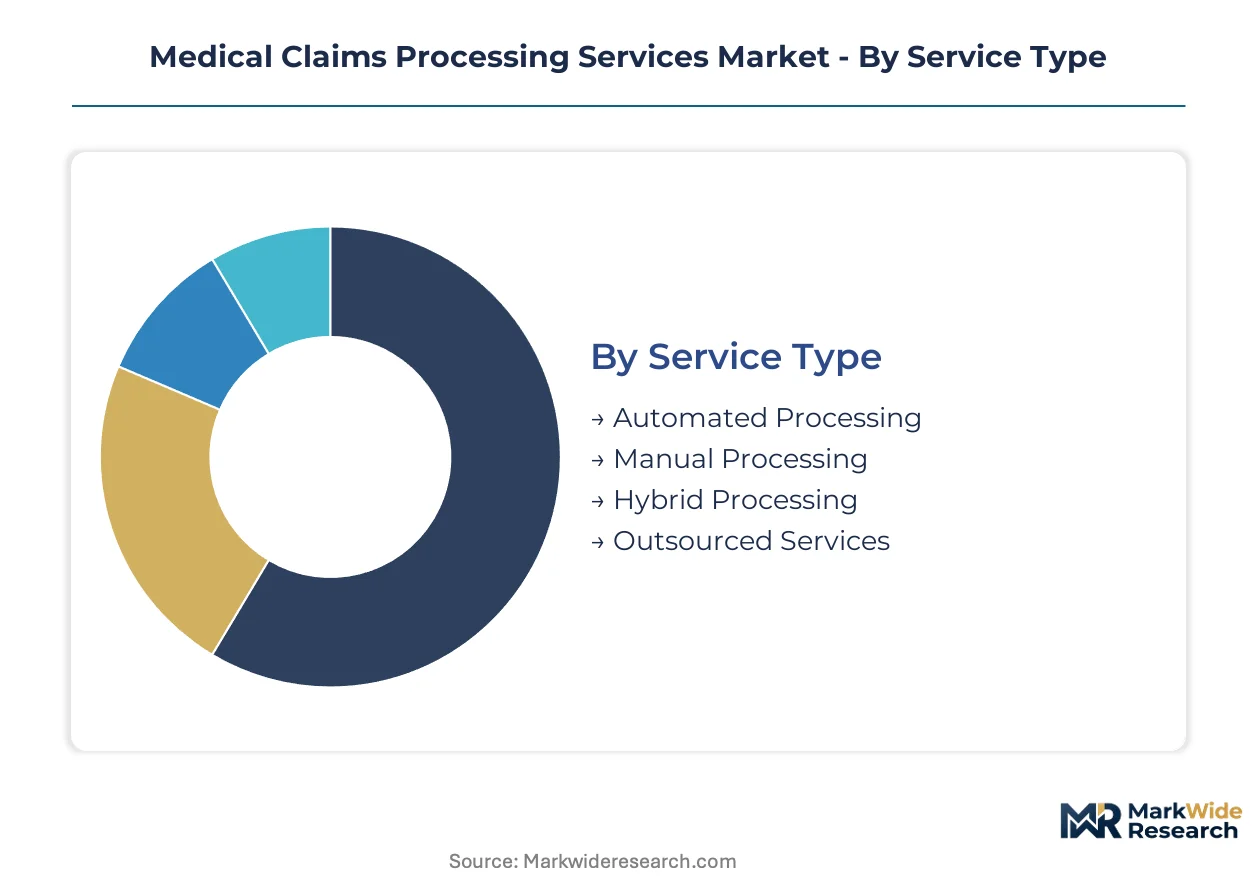
Medical claims processing services fragment across service delivery models, technology architectures, and reimbursement methodologies. Each segmentation dimension carries distinct margin profiles and compliance burdens that reshape vendor competitive positioning.
Service Type:
After-sales service intensity varies dramatically across processing modalities, with automated platforms demanding continuous algorithmic retraining while outsourced arrangements require persistent quality auditing.
- Automated Processing:Rules-based engines and machine learning pipelines handle claim validation, coding verification, and payment calculation without human intervention. United States health systems facing CMS prior authorization automation mandates are concentrating procurement here, though algorithmic bias audits add compliance overhead.
- Outsourced Services:Third-party vendors assume full operational responsibility for claims adjudication workflows, typically serving mid-market insurers lacking captive IT scale. Hyderabad and Bengaluru delivery centers anchor cost-competitive capacity for Western payers, with AAPC-certified coder shortages constraining quality consistency.
- Manual Processing:Human reviewers handle complex claims requiring clinical judgment or exception handling. Demand concentrates in out-of-network arbitration and specialty pharmacy claims where automated confidence scores fall below threshold.
- Hybrid Processing:Combines automated pre-screening with human escalation pathways for edge cases. This architecture dominates among regional Blue Cross plans modernizing from legacy batch systems.
Automated processing holds the largest share; momentum sits with outsourced services as labor arbitrage and cloud delivery models mature.
End User:
Customer scale and procurement sophistication create tiered demand patterns across the care continuum.
- Hospitals:Enterprise health systems with centralized revenue cycle operations command multi-year platform contracts. UnitedHealth Group and Change Healthcare anchor infrastructure serving these consolidated buyers, with real-time adjudication capabilities now table stakes for system-wide EHR integration.
- Insurance Providers:National and regional payers maintain captive processing centers or hybrid outsourced arrangements. HIPAA security rule compliance investments and CMS interoperability API mandates are forcing core system replacements among Medicare Advantage specialists.
- Clinics:Ambulatory surgery centers and urgent care chains prioritize point-of-service payment estimation tools. Consumer satisfaction metrics now hinge on immediate cost transparency rather than retrospective statement accuracy.
- Third-Party Administrators:Self-insured employer plans and Taft-Hartley funds rely on TPA intermediaries for claims management. These buyers favor modular platforms with flexible benefit configuration and multi-state regulatory compliance.
Insurance providers command the highest contract values; clinics are expanding most quickly as consumer-directed payment models proliferate.
Technology:
Architecture choices determine compliance trajectory and margin expansion potential across vendor portfolios.
- AI Solutions:Natural language processing extracts diagnosis and procedure codes from unstructured clinical documentation, reducing manual coding labor. FDA clinical decision support oversight and EU AI Act high-risk system classifications are creating dual compliance tracks for multinational insurers.
- Cloud-Based Platforms:Native cloud architecture enables elastic capacity for seasonal claim volume spikes and rapid API deployment for interoperability mandates. AWS, Azure, and Google Cloud concentration creates single-point-of-failure exposure and limited pricing leverage.
- RPA:Robotic process automation handles repetitive data entry and system-to-system reconciliation tasks. These tools bridge legacy mainframe environments and modern cloud infrastructure without full platform replacement.
- Legacy Systems:COBOL-based mainframe environments persist at established insurers with decades of technical debt. Modular API overlays are preferred to rip-and-replace strategies given migration risk and cost.
Cloud-based platforms dominate current procurement; AI solutions are gaining share fastest as clinical documentation automation matures.
Billing Method:
Reimbursement model evolution is compressing processing timelines and demanding new technical capabilities.
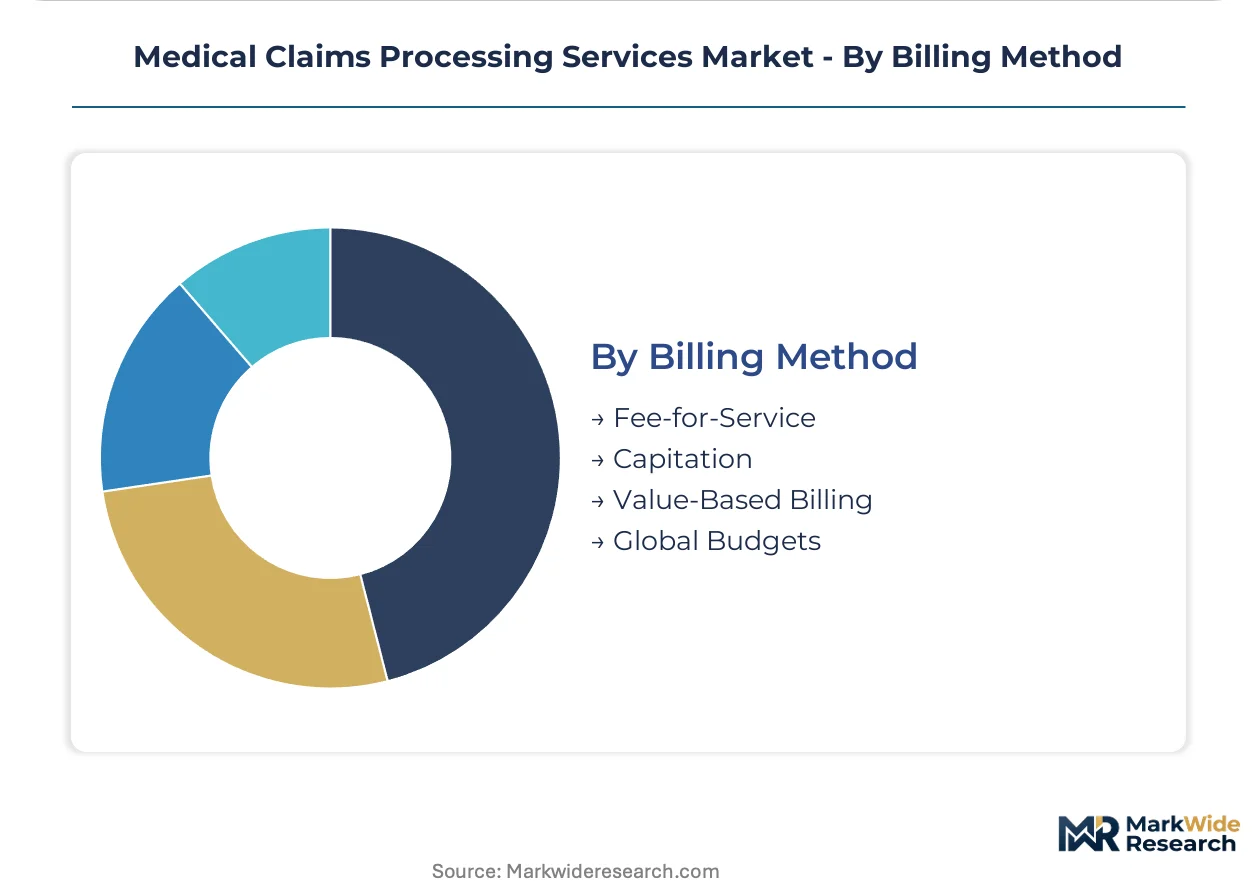
- Value-Based Billing:Ties provider compensation to quality metrics and patient outcomes rather than service volume. Claims platforms must integrate clinical data feeds and risk adjustment calculations that fee-for-service infrastructure cannot support.
- Fee-for-Service:Traditional retrospective reimbursement based on submitted procedure codes. This method retains volume among specialty providers and out-of-network claims where contractual rates do not exist.
- Capitation:Fixed per-member-per-month payments require prospective risk stratification and utilization management integration. Medicare Advantage growth is sustaining demand for capitation-ready platforms.
- Global Budgets:All-payer fixed allocations for hospital systems, prevalent in Maryland and international single-payer environments. These arrangements eliminate individual claim adjudication in favor of population-level reconciliation.
Fee-for-service retains the largest transaction volume; value-based billing shows the steepest expansion trajectory as CMS accelerates alternative payment model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
HIPAA security rule enforcement by the US Department of Health and Human Services anchors the dominant geography for medical claims processing services, with CMS interoperability mandates creating replacement demand across enterprise payers and health systems.
United States
Hospital consolidation and value-based reimbursement transition drive procurement of real-time adjudication platforms. CMS prior authorization automation rules force legacy system modernization among Medicare Advantage specialists. UnitedHealth Group and Change Healthcare anchor enterprise-scale infrastructure serving multi-state health systems from processing hubs in Minnesota and Tennessee.
India
Captive delivery centers in Hyderabad and Bengaluru supply actuarial talent and AAPC-certified coding capacity to Western payers at structural cost advantages. The country's IT services regulatory framework under MeitY enables cross-border data processing for healthcare clients. Cognizant Technology Solutions competes from Chennai and Pune on automation depth rather than labor arbitrage alone.
Germany
The EU AI Act's high-risk system classification shapes development priorities for AI-enabled prior authorization tools serving European policyholders. GDPR compliance requirements impose dual-track architecture investments on multinational processors. Berlin and Munich host compliance engineering clusters isolating algorithmic components for jurisdiction-specific validation.
United Kingdom
NHS Digital interoperability standards and NHSX data architecture mandates create procurement specifications distinct from US-centric platforms. London's fintech infrastructure supports real-time payment settlement pilots for point-of-service models. The city's regulatory technology cluster addresses conformity assessment requirements for clinical decision support exports.
Canada
Provincial health authority procurement centralization favors vendors with bilingual compliance and multi-payer configuration capabilities. Health Canada oversight of medical device software classification affects AI-enabled claims platform market access. Toronto's health informatics cluster develops FHIR implementation guides for pan-Canadian interoperability.
Medical Claims Processing Services Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. Enterprise-scale payers and health systems consolidate procurement around vendors with multi-state compliance automation and cloud-native architecture. Three archetypes dominate: integrated health services conglomerates with captive processing infrastructure; pure-play technology vendors competing on interoperability API depth; and IT services specialists delivering cost-optimized back-office capacity from offshore delivery centers. Competitive moves center on vertical integration into adjacent revenue cycle services and strategic partnerships with EHR platform vendors.
Within the integrated services tier, UnitedHealth Group and Change Healthcare exemplify enterprise-scale positioning through captive infrastructure and cloud-native architecture respectively. Cognizant Technology Solutions anchors the IT services specialist archetype, competing from Indian delivery centers on automation capabilities. These three entities represent distinct strategic postures: vertical integration, federal interoperability readiness, and offshore cost optimization.
| Leading Market Players |
|---|
| UnitedHealth Group |
| McKesson Corporation |
| Athenahealth |
| Quest Diagnostics |
| Cerner Corporation |
| Change Healthcare |
| Conduent |
| Cognizant Technology Solutions |
| eClinicalWorks |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in United States-based certified medical coder pools drives pricing divergence between automated platforms and labor-dependent outsourced services. Cloud-native vendors capture rate premiums through real-time adjudication capabilities while Hyderabad and Bengaluru delivery centers compress costs for Western payers seeking back-office scale.
Pricing Analysis
Geographic price spreads between United States domestic processing and India-based delivery centers reach three-to-one ratios for equivalent coding services. Pricing stratifies across premium, standard, and economy tiers based on automation depth and HIPAA compliance certification levels. Cost compression in manual processing tiers is intensifying because AAPC-credentialed talent concentrates in urban United States markets. Insurance providers with captive infrastructure show lowest price sensitivity; regional third-party administrators face acute margin pressure from subscription SaaS alternatives.
Supply Chain Analysis
Tariff exposure between United States and India for cross-border data processing services creates compliance architecture costs for multinational insurers. Supply concentrates in the United States for cloud infrastructure and FDA-validated AI platforms, and in India for clinical coding labor and actuarial analytics. The supply chain draws from AWS Azure and Google Cloud for compute capacity, from AAPC-certified training pipelines for human capital, and from FHIR standard libraries for interoperability tooling. Single-source vulnerability in cloud concentration risk threatens continuity for enterprise-scale payers. Distribution runs through direct enterprise sales to consolidated health systems and through channel partners serving mid-market regional insurers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among consolidated United States hospital systems and national payers, forcing vendors toward enterprise-scale automation investments or niche specialization. Health system mergers have reduced procurement counterparties by two-thirds in major metropolitan markets over recent consolidation waves.
For Market Incumbents: Pre-empt displacement by modular API-native competitors through backward integration into adjacent revenue cycle services and captive acquisition of India-based delivery capacity. HIPAA security rule enforcement creates compliance moats for established platforms with existing infrastructure investments. R&D priority sits with FDA clinical decision support validation for prior authorization automation tools. For New Entrants and Emerging Players: Build out white-space presence in point-of-service payment estimation for United States ambulatory surgery centers and urgent care chains, where consumer satisfaction metrics now hinge on immediate cost transparency. The most penetrable segment comprises mid-market regional Blue Cross plans modernizing from legacy COBOL batch systems. Go-to-market leverage rests on FHIR-native interoperability architecture that reduces integration testing burdens versus incumbent overlay approaches. For Investors and Strategic Acquirers: Capital is best deployed toward cloud-native platforms with validated AI documentation extraction capabilities and established India delivery footprints. Long-term viability over the coming decade favors vendors positioned for CMS prior authorization automation mandates and EU AI Act high-risk system compliance. The signal to watch is FDA issuance of clinical decision support guidance documents that will determine market access timelines for algorithmic prior authorization tools.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Clinical Decision Support Validation | Regulatory clarity from FDA creates first-mover advantage for AI-enabled prior authorization platforms. |
| India Delivery Center Expansion | Hyderabad and Bengaluru capacity anchors cost-advantaged processing for Western payer back-office operations. |
| FHIR-Native Platform Architecture | Native interoperability compliance reduces integration burdens from CMS mandates and private payer requirements. |
| Point-of-Service Payment Integration | Real-time adjudication at encounter completion captures ambulatory surgery center and urgent care procurement. |
| EU AI Act Compliance Engineering | Conformity assessment capabilities open multinational insurer contracts with European policyholder exposure. |
Research Methodology
A standing panel of revenue cycle executives, health system CIOs, payer operations directors, and AAPC-certified coding managers provided ongoing calibration across the research program. Primary interviews with these stakeholders combined with secondary validation from CMS Medicare cost reports, hospital procurement databases, GPO contracts, and SEC filings from publicly traded healthcare IT vendors. Bottom-up triangulation across service type deployments and top-down reconciliation against aggregate payer IT spending produced convergent estimates.
Scenario bracketing anchored the analytical framework across the projection horizon, with sensitivity testing for CMS interoperability rule implementation timing and AI regulatory pathway outcomes. Segmentation dimensions modeled include service delivery modality, technology architecture tier, end-user scale category, and reimbursement methodology type. CAGRs derived from logistic diffusion curves for automation adoption and elasticity-adjusted demand functions for labor-dependent services. Forecast inputs incorporated health system merger pipelines and certified coder graduation rates from AAPC-accredited programs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native entrants or accelerated FDA enforcement actions would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Intellectual Property Liability Insurance Market
Insurance
Europe Mobile Phone Insurance Market
Insurance
Canada Cyber (Liability) Insurance Market
Insurance
Spain Group Health Insurance Market
Insurance
Factory and Warehouse Insurance Market
Insurance
United Kingdom Car Insurance Market
Insurance
United States Insurance Brokerage Market
Insurance
Saudi Arabia Travel Insurance Market
Insurance
Insurance Aggregators Market
Insurance
Drone Insurance Market
Insurance
Singapore Property and Casualty Insurance Market
Insurance
Cyber Liability Insurance Market
Insurance
Sri Lanka Cyber (Liability) Insurance Market
Insurance
Aircraft Insurance Market
Insurance
Asia-Pacific Mobile Phone Insurance Market
Insurance
US Travel Insurance Market