
 Telematics-Based Auto Insurance Market | 2026-2036
Telematics-Based Auto Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Telematics-Based Auto Insurance Market Insights
Cellular connectivity modules are pivoting toward lower-cost LTE-M and NB-IoT chipsets, compressing hardware economics for insurers and enabling broader policyholder penetration. Progressive Corporation leverages its Snapshot program to sustain first-mover advantage in usage-based pricing, while State Farm Mutual Automobile Insurance Company anchors its market position through exclusive OEM data partnerships with Ford and General Motors. Octo Telematics competes on claims analytics depth, differentiating its platform with crash reconstruction algorithms that reduce loss adjustment expenses.
Telematics-based auto insurance denotes coverage where premiums derive from measured driving behavior, vehicle usage, and real-time risk signals transmitted via OBD II ports, smartphone sensors, or embedded vehicle modems; actuarial models ingest acceleration, braking, mileage, and time-of-day data to price policies at individual rather than demographic granularity. Pay-How-You-Drive pricing models now command the deepest margin pools as insurers tie premiums to measured risk rather than proxy variables, while embedded telematics systems represent the fastest-growing technology channel as automotive OEMs pre-install connectivity hardware at the factory. Fleet operators constitute the most concentrated end-user segment, with commercial vehicle pools generating recurring high-value data streams that sustain insurer profitability.
The National Association of Insurance Commissioners coordinates state-level regulatory frameworks across the United States, while the EU AI Act imposes algorithmic transparency obligations on automated underwriting decisions in Europe; GDPR consent architectures further constrain how insurers process geolocation and behavioral data, elevating compliance costs but also creating barriers to unregulated entrants. The Federal Trade Commission monitors data broker practices in the US, shaping how LexisNexis Risk Solutions and similar aggregators may combine telematics with credit and claims histories. Stakeholders must monitor evolving state-by-state privacy legislation and OEM data access negotiations to secure sustainable supply of driving behavior signals.
Market Dynamics
Smartphone-based data collection is compressing hardware costs and democratizing access to usage-based pricing, while OEM-embedded connectivity is consolidating data supply chains under vehicle manufacturer control.
Growth Catalysts
- LTE-M and NB-IoT chipset economics:Cellular module costs are falling below dedicated OBD-II hardware price points, enabling insurers to reach mass-market policyholders previously excluded by upfront device investments.
- Fleet operator risk management mandates:Commercial vehicle pools are adopting telematics to satisfy safety compliance requirements and reduce liability exposure across logistics and last-mile delivery operations.
- EU AI Act algorithmic transparency rules:Automated underwriting decisions in Europe now require explainable risk scoring, accelerating insurer investment in consent-managed data architectures that build policyholder trust.
Market Restraints
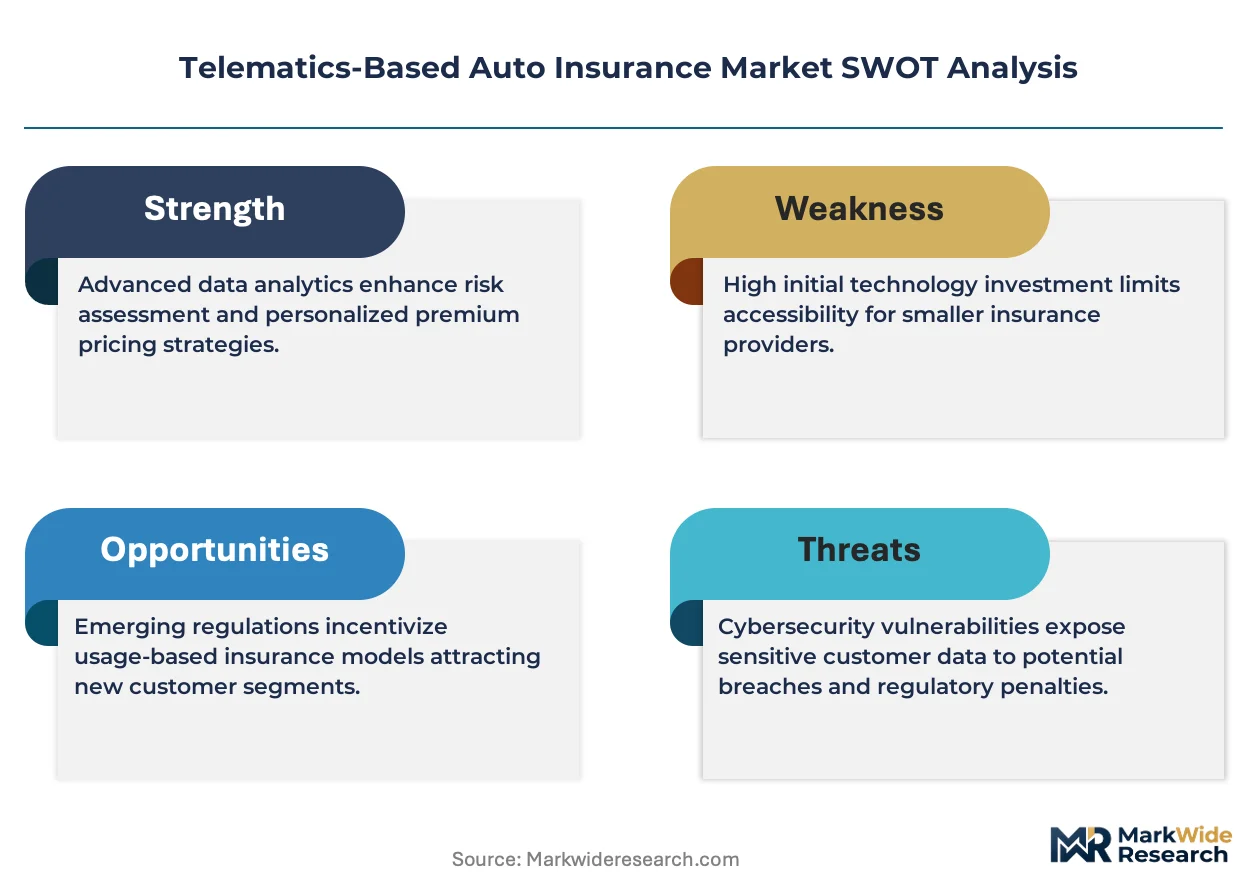
- GDPR geolocation consent friction:European insurers face elevated compliance costs and data processing restrictions that constrain real-time behavioral pricing models and limit historical data retention.
- OEM data gatekeeping concentration:Ford, General Motors, and other manufacturers control embedded modem access, extracting licensing fees that compress insurer margins and create supply dependency.
- Smartphone sensor accuracy variance:Accelerometer and GPS drift across device manufacturers introduces noise into braking and cornering measurements, degrading actuarial model precision for app-based programs.
Strategic Opportunities
- India's uninsured motorist population:Low penetration of traditional auto coverage combined with smartphone density creates white space for mobile-first usage-based products targeting two-wheeler and entry-level four-wheeler segments.
- Embedded OEM-telematics convergence:Factory-installed connectivity hardware is unifying data streams from advanced driver-assistance systems with insurance pricing engines, enabling crash prediction models that preempt claims.
- Usage-based commercial line expansion:Pay-per-mile and pay-how-you-drive products for small business fleets represent an underpenetrated channel with higher policy values and lower customer acquisition costs than personal lines.
Industry Challenges
- Actuarial talent scarcity in behavioral data science:Insurers compete for data scientists capable of translating raw telematics signals into tariff-ready risk scores, with compensation inflation compressing underwriting department budgets.
- Legacy policy administration system integration:Core insurance platforms built for annual renewal cycles require expensive middleware development to ingest real-time driving data and trigger dynamic premium adjustments.
- Cross-border data localization compliance:Divergent national requirements on where telematics data must reside create architectural complexity for multinational insurers operating across European and Asia-Pacific markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telematics-Based Auto Insurance Market |
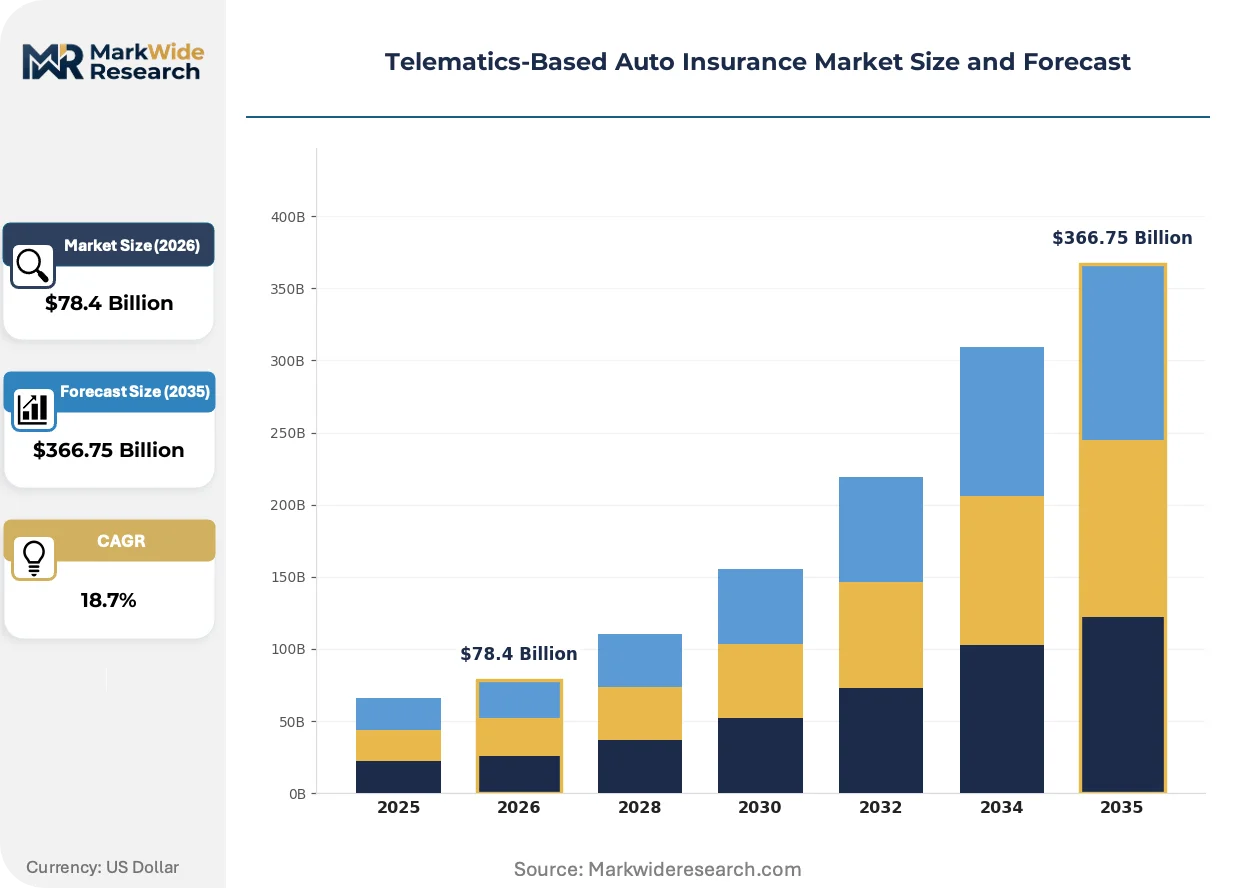
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $366.75 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Pricing Model: Pay-As-You-Drive, Pay-How-You-Drive, Flat Rate, Performance-Based Telematics Technology: OBD II Devices, Smartphone Apps, Black Box Systems, Embedded Telematics End User: Private Car Owners, Fleet Operators, Commercial Vehicles, Rideshare Services Insurance Type: Comprehensive Insurance, Third Party Liability, Collision Insurance, Usage-Based Insurance |
| Companies Covered | Cambridge Mobile Telematics, Octo Telematics, Progressive Corporation, State Farm Mutual Automobile Insurance Company, Allstate Corporation, Trimble, LexisNexis Risk Solutions, The Floow, Agero, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telematics-Based Auto Insurance Market Trends and Innovations
Telematics infrastructure is converging around two competing data capture modalities—smartphone sensors versus embedded vehicle hardware—each reshaping insurer-OEM relationships and policyholder acquisition economics.
Edge computing on vehicle modems is unifying raw sensor processing with privacy-preserving analytics. Automotive OEMs are deploying this architecture to pre-filter driving behavior data before transmission to insurers. The approach compresses data transfer costs while satisfying GDPR minimization principles, enabling real-time risk scoring without exposing granular geolocation trails.
The EU AI Act's automated decision-making provisions are mandating algorithmic audit trails for premium calculations. European insurers must now document how telematics inputs translate into pricing outputs, creating documentation burdens that favor established carriers with compliance infrastructure over insurtech entrants. Germany's KBA and France's CNIL are coordinating enforcement priorities that elevate consent granularity requirements.
Fleet managers are consolidating vendor relationships by demanding bundled telematics-hardware-insurance packages. Traditional broker channels are losing share to direct OEM and insurer partnerships that embed coverage at vehicle point-of-sale. This pattern is most visible in United States commercial auto lines, where national logistics operators negotiate enterprise-wide data sharing agreements with manufacturers.
Telematics-Based Auto Insurance Market Segmentation
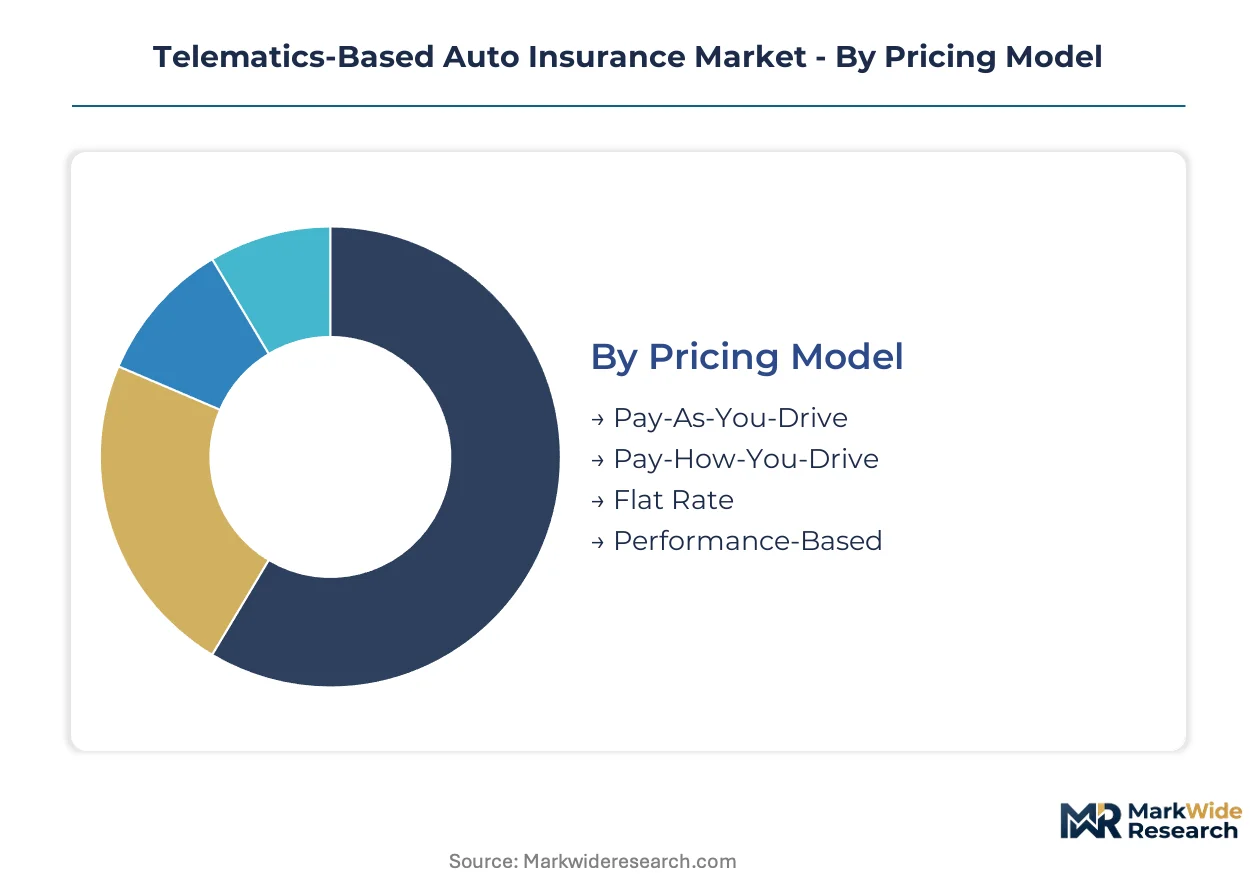
Premium differentiation in telematics-based auto insurance depends on granular segmentation across pricing models, data capture technologies, and end-user risk profiles. Insurers calibrate product architecture to match behavioral data availability with regulatory constraints in each target jurisdiction.
Pricing Model:
Standardization dominates mileage-based offerings while customization intensity rises with behavioral granularity.
- Pay-As-You-Drive:Mileage-metered premiums suit low-usage policyholders in urban Germany and the Netherlands where annual distance caps align with environmental policy incentives. German KBA registration data integration enables automated odometer verification, reducing fraud exposure for domestic carriers.
- Pay-How-You-Drive:Acceleration, braking, and cornering telemetry command the deepest underwriting margins. Progressive Snapshot and similar programs concentrate in the United States where state-level regulatory heterogeneity allows rapid pricing iteration.
- Flat Rate:Simplified pricing persists in markets with immature telematics infrastructure or strict rate-filing requirements.
- Performance-Based:Gamified rewards tied to safety scores attract younger demographics in smartphone-dense markets.
Most installed capacity flows through Pay-As-You-Drive. Expansion is steepest in Pay-How-You-Drive.
Telematics Technology:
Hardware economics stratify by installation burden and data fidelity requirements.
- OBD II Devices:Plug-in modules deliver standardized vehicle diagnostics across post-1996 vehicle fleets. United States commercial auto lines favor this modality for mixed-vendor fleet pools where embedded OEM compatibility varies.
- Smartphone Apps:Accelerometer and GPS fusion eliminates hardware logistics, democratizing access in India and Southeast Asian markets where device penetration exceeds vehicle connectivity infrastructure.
- Black Box Systems:Hardwired installations with battery backup support crash reconstruction for high-value commercial fleets and young-driver programs in the United Kingdom.
- Embedded Telematics:Factory-installed modems unify ADAS data streams with insurance pricing engines. Ford and General Motors negotiate exclusive data licensing agreements that constrain third-party insurer access.
Smartphone Apps capture the broadest policyholder base. Embedded Telematics climbs the fastest as OEMs consolidate data control.
End User:
Risk concentration and data scale determine insurer prioritization across user categories.
- Private Car Owners:Individual policyholders generate fragmented data streams but represent volume scale in personal auto lines. United States direct-to-consumer channels target this segment with app-based enrollment minimizing acquisition friction.
- Fleet Operators:Commercial vehicle pools produce recurring high-value telemetry with enterprise-grade consent management. Logistics operators in the United States negotiate bundled hardware-insurance contracts with OEMs.
- Commercial Vehicles:Heavy-duty trucking and last-mile delivery fleets face OSHA-aligned safety mandates that telematics satisfies.
- Rideshare Services:Uber and Lyft driver pools require hybrid personal-commercial coverage with trip-level data segmentation.
Fleet Operators concentrate the highest premium density. Rideshare Services expands most quickly as platform economics normalize insurance as a driver cost component.
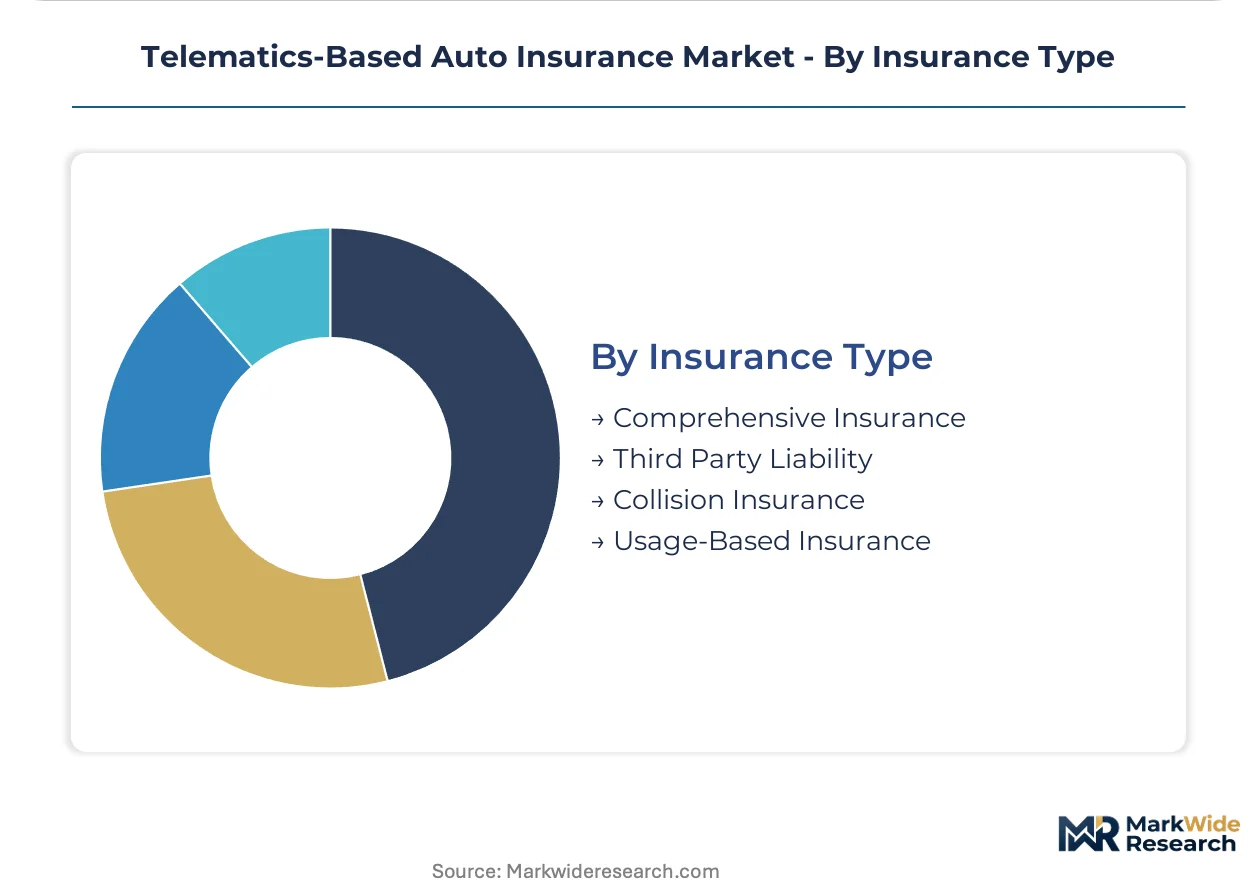
Insurance Type:
Product bundling reflects jurisdictional compulsory coverage floors and optional protection demand.
- Comprehensive Insurance:Full peril coverage integrates telematics for theft recovery and weather damage verification. German and French markets favor this structure where regulatory minimums exceed liability-only thresholds.
- Third Party Liability:Mandatory coverage in EU member states uses telematics primarily for fraud detection rather than pricing differentiation.
- Collision Insurance:Crash reconstruction algorithms reduce loss adjustment expenses, concentrating demand among high-value vehicle owners.
- Usage-Based Insurance:Modular products unbundle coverage by time, distance, or behavior, attracting price-sensitive segments in competitive personal lines markets.
Third Party Liability dominates policy count. Usage-Based Insurance gains share fastest as insurers disaggregate traditional annual contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Detroit's automotive corridor anchors telematics insurance development through embedded OEM partnerships. Insurer concentration in Michigan and Ohio correlates with factory-installed modem deployment. Regulatory fragmentation across state insurance commissioners shapes product rollout velocity.
United States
Progressive and State Farm scale usage-based programs through exclusive Ford and General Motors data partnerships. State-level rate filing heterogeneity allows rapid pricing iteration absent federal preemption. Texas and California concentrate policyholder acquisition through direct-to-consumer app channels.
Germany
KBA registration data integration enables automated odometer verification for Pay-As-You-Drive products. GDPR consent architectures constrain real-time behavioral pricing while elevating compliance investment. Munich and Stuttgart host insurer-OEM negotiation clusters for embedded telematics access.
United Kingdom
Black box installations dominate young-driver programs with crash reconstruction requirements. The Financial Conduct Authority monitors algorithmic pricing fairness in automated underwriting. London concentrates insurtech development for smartphone-based data collection.
India
Smartphone density exceeds vehicle connectivity infrastructure, democratizing app-based enrollment. IRDAI regulatory sandbox approvals accelerate mobile-first product pilots for two-wheeler segments. Mumbai and Bangalore anchor digital insurer headquarters targeting uninsured motorist populations.
France
CNIL enforcement priorities elevate consent granularity requirements for geolocation processing. Comprehensive coverage mandates exceed liability-only thresholds, integrating telematics for theft recovery. Paris hosts EU AI Act compliance coordination between carriers and automotive suppliers.
Telematics-Based Auto Insurance Market Competitive Landscape
Global majors compete with regional champions across data capture modalities and OEM access channels. Market structure stratifies between hardware-enabled insurers, software analytics specialists, and embedded platform integrators. Three archetypes dominate: legacy carriers with proprietary telematics programs, automotive OEMs controlling factory-installed connectivity, and data aggregators combining telematics with supplementary risk signals. Competitive moves concentrate on exclusive OEM partnership negotiations and consent-managed data architecture development.
Within the legacy carrier archetype, Progressive Corporation and State Farm Mutual Automobile Insurance Company exemplify scale-driven program deployment through direct policyholder acquisition. Octo Telematics occupies a specialist position in claims analytics depth. Cambridge Mobile Telematics anchors smartphone-based data collection innovation. These entities collectively represent the competitive tension between hardware-agnostic app approaches and embedded OEM-telematics convergence.
| Leading Market Players |
|---|
| Cambridge Mobile Telematics |
| Octo Telematics |
| Progressive Corporation |
| State Farm Mutual Automobile Insurance Company |
| Allstate Corporation |
| Trimble |
| LexisNexis Risk Solutions |
| The Floow |
| Agero |
| Others |
Pricing and Supply Chain Analysis
Fleet operator procurement mandates for multi-source data architectures are forcing insurers to qualify redundant telematics hardware suppliers, compressing chipset margins while elevating compliance investment across pricing tiers.
Pricing Analysis
Input-cost pass-through from LTE-M and NB-IoT module economics shapes premium structures across the market. Three-tier pricing stratifies across hardware-enabled, smartphone-app, and embedded-OEM delivery models, with differentiation anchored in data fidelity and crash reconstruction depth. Pricing pressure intensifies in smartphone-dependent tiers as accelerometer noise degrades model precision and forces discounting. Fleet operators exhibit lowest price sensitivity due to bundled safety compliance value, while individual policyholders in emerging markets resist hardware procurement costs.
Supply Chain Analysis
Dual-sourcing requirements from United States and German fleet operators mandate multi-supplier qualification for cellular connectivity modules, compressing procurement leverage for dedicated OBD-II manufacturers. Component supply concentrates in Taiwan, South Korea, and China for chipset fabrication, while final assembly distributes across Mexico and Eastern Europe. Raw material dependencies span silicon wafers, lithium-ion backup cells, and automotive-grade resins. Single-source vulnerability concentrates in embedded modem firmware licensing from Ford and General Motors. Distribution runs through direct OEM partnerships and insurer-procured hardware logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's algorithmic transparency mandate compounds regulatory compliance spend into a durable demand driver for consent-managed data architectures, entrenching carriers with pre-built audit infrastructure.
For Market Incumbents: Cement exclusive OEM data partnerships before embedded telematics consolidation hardens supply access. Defend pricing power by integrating crash reconstruction algorithms that reduce loss adjustment expenses below app-based competitors. Vertical integration into edge-computing vehicle modems hedges against manufacturer gatekeeping. For New Entrants and Emerging Players: The EU AI Act in Europe opens a window for compliance-native architectures that incumbent legacy systems cannot retrofit cost-effectively. Target India's uninsured two-wheeler population with smartphone-first enrollment minimizing hardware logistics. Pursue IRDAI sandbox approvals as the go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with claims analytics specialists possessing proprietary crash reconstruction IP. Long-term viability favors entities that unify telematics data with supplementary risk signals from credit and property records. Watch OEM data licensing fee escalation as the inflection indicator for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| OEM Data Partnership Negotiation | Secures exclusive embedded telematics access from Ford and General Motors before supply consolidation. |
| Consent-Managed Architecture Investment | Builds GDPR and EU AI Act compliance infrastructure that insurtech entrants cannot replicate rapidly. |
| Smartphone Sensor Fusion R&D | Reduces accelerometer drift through algorithmic calibration, narrowing fidelity gaps with embedded hardware. |
| Fleet Operator Direct Channel | Bypasses traditional broker economics through enterprise-wide bundled hardware-insurance contracts. |
| Edge Computing Platform Deployment | Pre-filters driving behavior data on vehicle modems to satisfy GDPR minimization and reduce transfer costs. |
Research Methodology
Multiple input streams — executive interviews with insurer underwriting leads, procurement discussions with fleet operators, and secondary validation against regulatory filings — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured perspectives from actuarial data scientists, OEM platform engineers, and telematics hardware procurement specialists. Secondary sources encompassed NAIC state rate filings, EU AI Act implementation guidance, KBA registration databases, and SEC disclosures from listed carriers.
Data-stream reconciliation anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled include pricing model granularity, telematics capture modality, end-user risk concentration, and insurance product bundling structure. CAGRs derived from fitted growth curves incorporating policyholder penetration rates, hardware cost decline trajectories, and regulatory compliance spend intensity. Industry-specific forecast inputs captured OEM embedded modem deployment schedules and fleet operator safety mandate adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under GDPR enforcement escalation or OEM data licensing fee spikes. Deviation in EU AI Act audit granularity requirements would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Internet of Things Insurance Market
Insurance
Commercial Cyber Insurance Market
Insurance
Global Home Insurance Market
Insurance
Middle East Business Income Insurance Market
Insurance
Horse Insurance Market
Insurance
North America Car Insurance Aggregators Market
Insurance
China Parametric Insurance Market
Insurance
Greece Property and Casualty Insurance Market
Insurance
Marine Cargo Insurance Market
Insurance
Norway Cyber (Liability) Insurance Market
Insurance
Commercial Earthquake Insurance Market
Insurance
Aerial Imaging in Insurance Service Market
Insurance
China Liability Insurance Market
Insurance
Intellectual Property Insurance Market
Insurance
Jewelry Insurance Market
Insurance
Critical Illness Insurance Market