
 Bancassurance in ASEAN Market | 2026-2036
Bancassurance in ASEAN Market Size, Share, and Industry Trends Forecast 2026-2036
Bancassurance in ASEAN Market Outlook
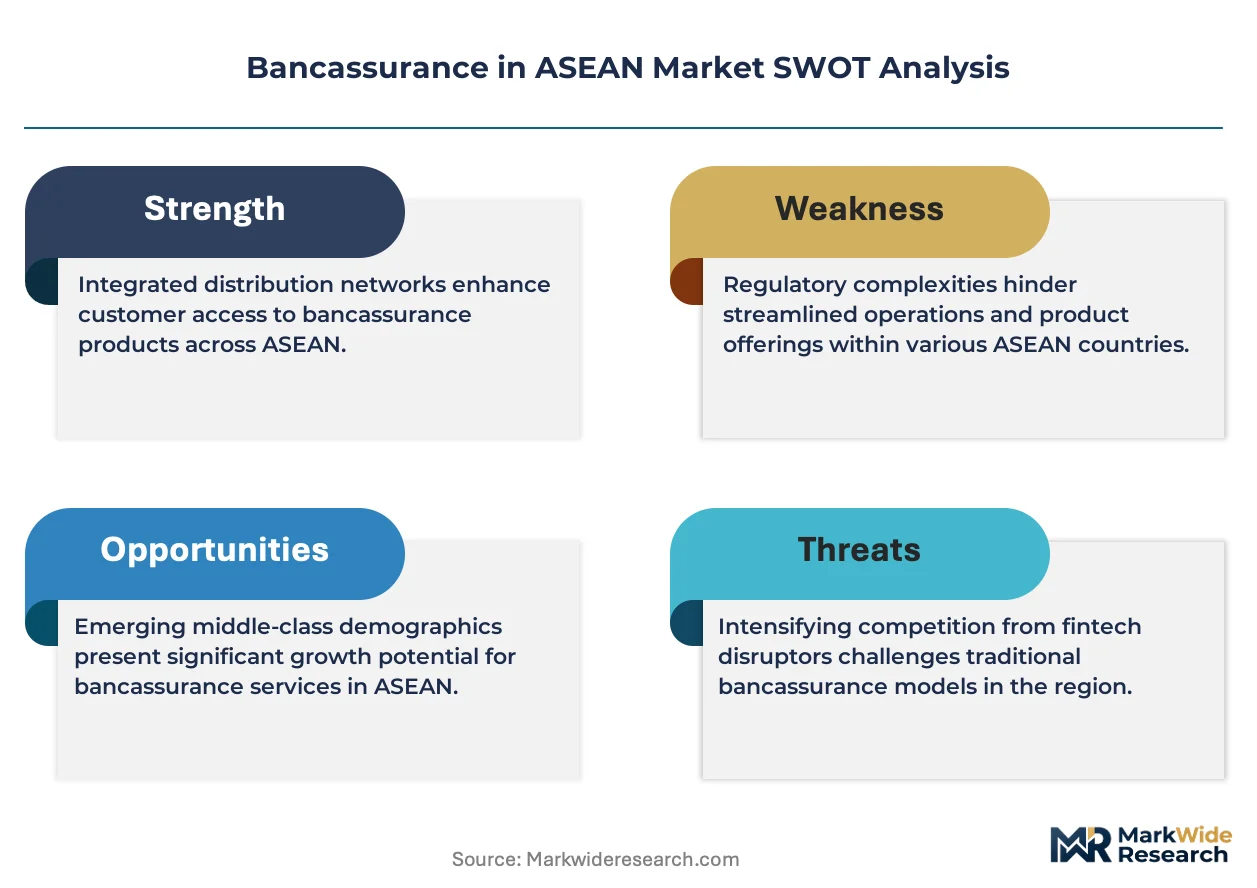
ASEAN Sustainable Banking Standards is realigning capital allocation toward insurance products with embedded ESG criteria. AIA Group leverages its pan-Asian agency-bank hybrid network to distribute protection-linked savings products. Prudential plc anchors its ASEAN footprint through bancassurance partnerships with systemic banks in Malaysia and Indonesia. Etiqa competes on takaful-bancassurance integration, sustaining dual-channel dominance in its home Malaysian market.
Bancassurance denotes the distribution of insurance products through banking channels, combining credit risk assessment infrastructure with actuarial underwriting to deliver policies at point-of-sale transactional touchpoints. Its primary commercial purpose centers on customer lifetime value extraction from deposit bases while lowering insurer customer acquisition costs relative to traditional agency models. Retail banking channels command the largest premium flow volume due to branch density and teller-assisted conversion, though private banking segments concentrate margin pools through investment-linked products and high-touch advisory wrappers. Life insurance products dominate premium income across cooperative banks in the Philippines and Vietnam, while health insurance riders attach to commercial banking lending products in Singapore and Thailand.
Bank Negara Malaysia's bancassurance operational guidelines, Otoritas Jasa Keuangan distribution regulations in Indonesia, and Monetary Authority of Singapore's fair dealing framework collectively govern product suitability, commission disclosure, and cooling-off provisions across the region. These standards shape demand by mandating transparent fee structures and restricting tied-selling arrangements that previously distorted product matching. Stakeholders must monitor evolving digital insurance licensing regimes as central banks determine whether technology platforms qualify as bank-channel equivalents for regulatory capital and consumer protection purposes.
Market Dynamics
Digital onboarding infrastructure is compressing distribution economics across Southeast Asian banking channels, with e-KYC mandates from monetary authorities eliminating physical branch dependencies for policy origination.
Growth Catalysts
- OJK Distribution Regulations:Indonesia's financial authority mandates transparent commission disclosure and cooling-off provisions, improving consumer trust and conversion rates in bank-channel insurance sales.
- Embedded health riders:Commercial banking lending products in Singapore and Thailand now attach hospitalization coverage at point-of-credit disbursement, expanding protection penetration among secured-loan customers.
- Underbanked-to-insured pipeline:Rural cooperative banks in the Philippines deploy teller-assisted microinsurance conversion, leveraging existing deposit relationships to overcome traditional agency acquisition costs.
Market Restraints
- Legacy core banking integration:Insurer policy administration systems require expensive API middleware to connect with bank transaction databases, raising unit economics for sub-scale partnerships.
- Commission rate compression:ASEAN Sustainable Banking Standards restrict fee structures on ESG-linked products, squeezing distributor margins compared to conventional savings-linked policies.
- Dual licensing complexity:Technology platforms seeking bank-channel equivalence must satisfy both central bank digital payment rules and insurance conduct standards, extending time-to-market.
Strategic Opportunities
- Vietnam rural penetration:Provincial joint-stock banks with dense district-level networks remain underserved by international carriers, offering first-mover positioning in agricultural credit-protection bundles.
- Investment-linked wrappers:Private banking segments across Kuala Lumpur and Jakarta seek unit-linked products with advisory overlays, commanding premium fee structures absent from retail term-life.
- Biometric KYC convergence:Facial recognition liveness detection combined with national ID databases enables fully remote policy issuance, eliminating branch dependency for millennial customer segments.
Industry Challenges
- Actuarial-banking talent scarcity:Professionals capable of bridging credit risk scoring with mortality underwriting command compensation premiums exceeding standalone bank or insurer benchmarks.
- Product suitability automation:Algorithmic recommendation engines must satisfy MAS fair dealing framework requirements while processing real-time transactional data for instant policy quoting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bancassurance in ASEAN Market |
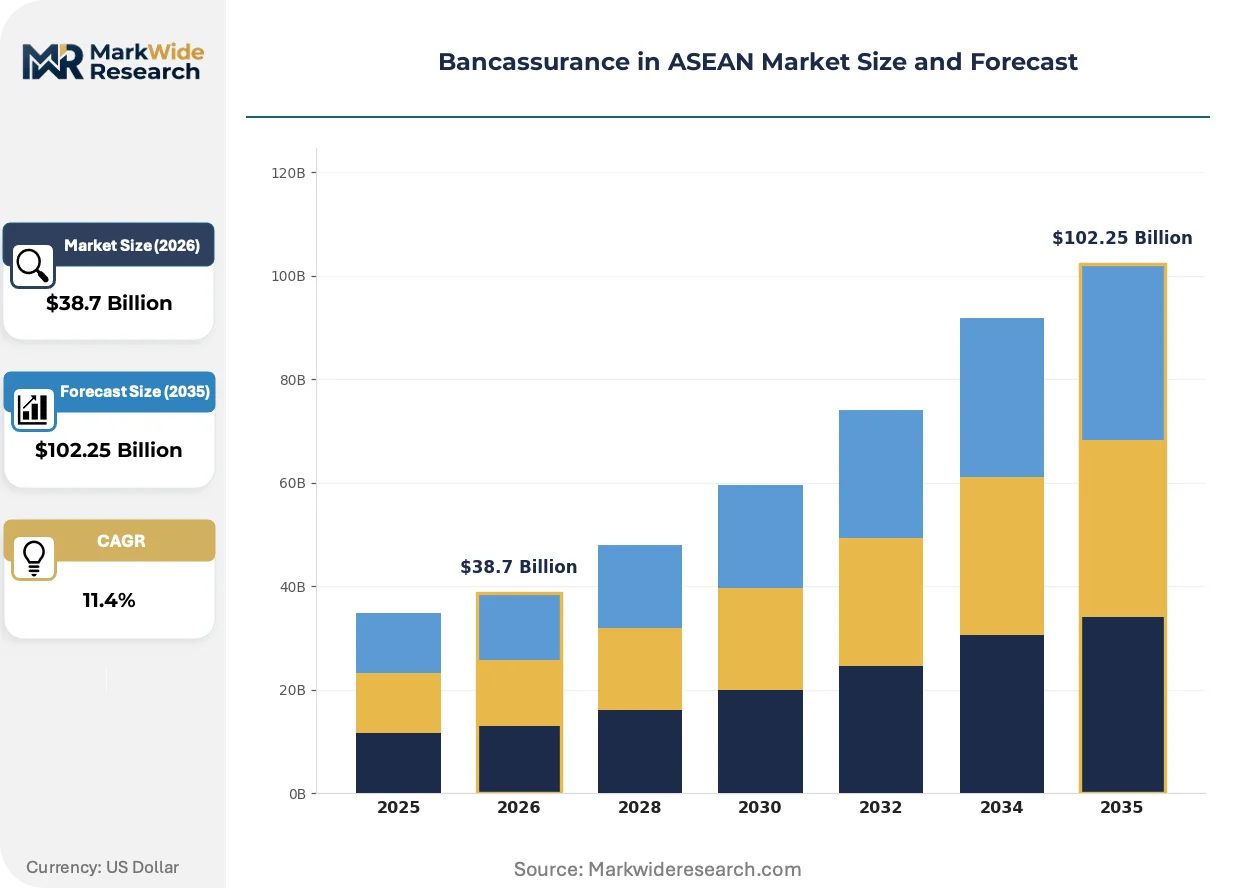
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Distribution Channel: Retail Banking, Commercial Banking, Private Banking, Cooperative Banks Product Type: Life Insurance, Health Insurance, General Insurance, Investment-Linked Products Client Type: Individual Customers, Small Enterprises, Corporates, High Net-Worth Individuals Pricing Model: Fixed Premium, Flexible Premium, Pay-as-You-Go, Tiered Pricing |
| Companies Covered | Etiqa, Sun Life Financial, AIA Group, Bangkok Bank, Allianz, Prudential plc, Great Eastern Holdings, Maybank, AXA Mandiri Financial Services, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bancassurance in ASEAN Market Strategic Shifts
Technology convergence between banking core systems and insurance policy engines is eliminating manual handoffs, while regulatory sandboxes test whether platform economics can replicate branch-based trust mechanisms.
API-first policy administration is overtaking batch-file integration between bank and insurer systems. Regional universal banks in Thailand and Malaysia now demand real-time data exchange for instant underwriting decisions. This compression is collapsing the traditional 48-hour quotation cycle into sub-minute point-of-sale completion.
Bank Negara Malaysia's bancassurance operational guidelines now mandate independent product suitability review for investment-linked sales. The framework requires documented justification when recommended premiums exceed 30 percent of customer verified income. Private banking relationship managers in Penang and Johor Bahru are restructuring advisory workflows to embed compliance checkpoints before proposal generation.
Millennial policyholders across Jakarta and Manila now initiate coverage research through mobile banking applications rather than agent referrals. This channel migration forces insurers to compress product disclosure into interactive digital formats replacing printed benefit illustrations. Vietnam's tech-savvy urban depositors demonstrate the strongest preference for self-service policy comparison tools integrated with existing banking dashboards.
Bancassurance in ASEAN Market Segmentation
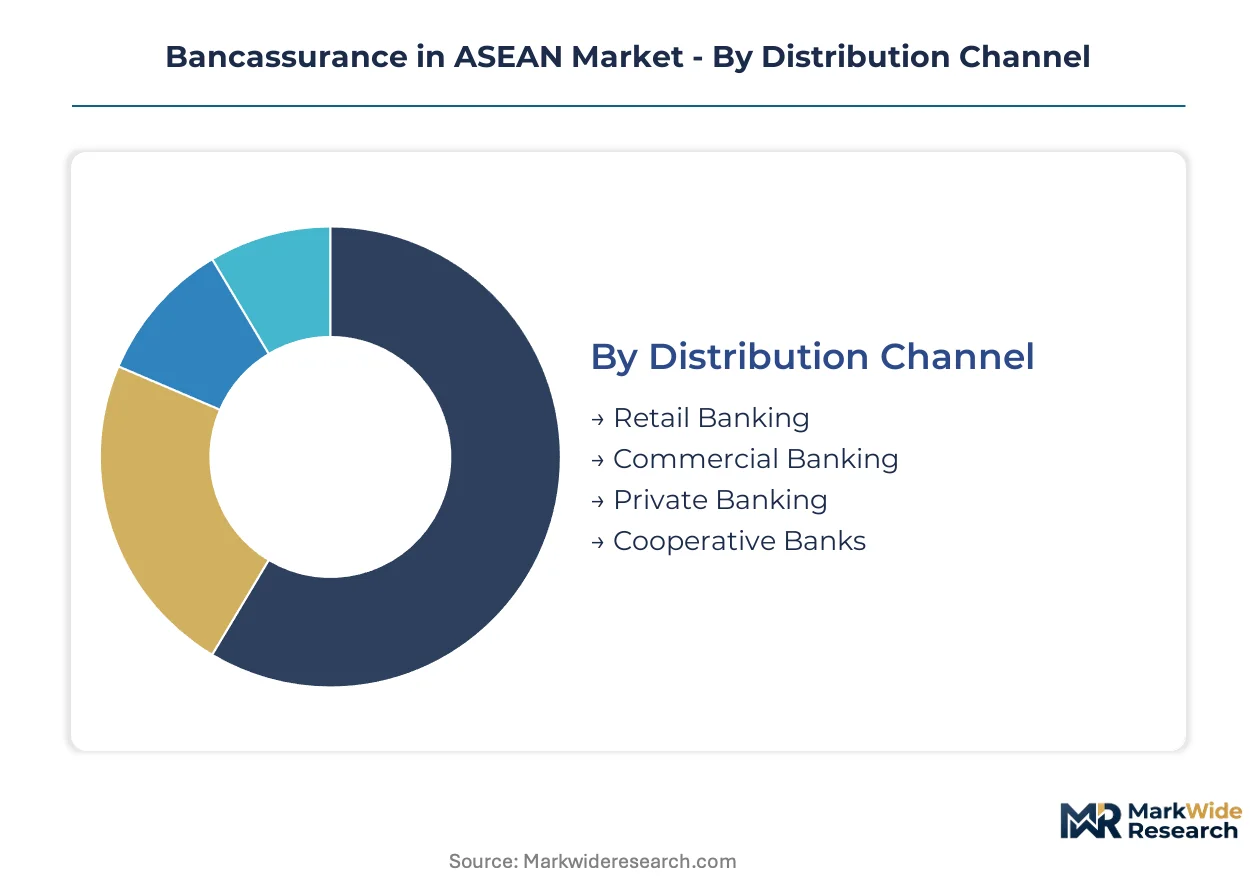
Bancassurance economics vary sharply by channel density and product complexity. Segment-specific capital requirements determine partnership structures between insurers and banking networks across Southeast Asia.
Distribution Channel:
Retail banking channels demand the heaviest upfront technology investment for core system integration and branch staff training programs.
- Retail Banking:Dense branch networks across Indonesia and Thailand require API middleware connecting legacy core banking to insurer policy engines. Teller-assisted conversion leverages deposit relationships for microinsurance penetration in underbanked districts.
- Commercial Banking:Corporate relationship managers attach health riders to working capital facilities at point-of-credit disbursement. Singapore and Thailand lead this segment where secured-loan customers receive embedded protection without separate underwriting.
- Private Banking:High-touch advisory wrappers support unit-linked product distribution in Kuala Lumpur and Jakarta.
- Cooperative Banks:Rural Philippine networks deploy simplified microinsurance products through existing member deposit structures.
Most installed capacity flows through Retail Banking. Expansion is steepest in Private Banking.
Product Type:
Product development costs scale with actuarial complexity and regulatory filing requirements across ASEAN jurisdictions.
- Life Insurance:Term-life and endowment products dominate premium flow through cooperative banks in Vietnam and the Philippines. Mortality underwriting integrates with credit risk scoring for instant approval at rural branch touchpoints.
- Investment-Linked Products:Unit-linked wrappers command premium fee structures in private banking segments across Malaysia and Singapore. Bank Negara Malaysia mandates independent suitability review when recommended premiums exceed thirty percent of verified income.
- Health Insurance:Hospitalization riders attach to commercial lending products with simplified e-KYC onboarding.
- General Insurance:Credit-protection bundles penetrate agricultural lending portfolios in Vietnam's provincial joint-stock banks.
Life Insurance captures the largest premium volume. Investment-Linked Products are gaining share fastest among affluent urban depositors.
Client Type:
Customer acquisition economics improve with existing banking relationship depth and transactional data availability.
- Individual Customers:Millennial policyholders across Jakarta and Manila initiate coverage research through mobile banking applications rather than agent referrals. Digital onboarding platforms compress disclosure into interactive formats replacing printed benefit illustrations.
- High Net-Worth Individuals:Concentrated in Singapore and Kuala Lumpur private banking segments, this group demands advisory overlays on protection-linked savings products with estate planning integration.
- Small Enterprises:Trade credit insurance distributes through commercial banking channels with working capital facilities.
- Corporates:Group policies and key-person coverage flow through relationship-managed commercial portfolios.
Individual Customers generate the highest policy count. High Net-Worth Individuals deliver the steepest margin expansion.
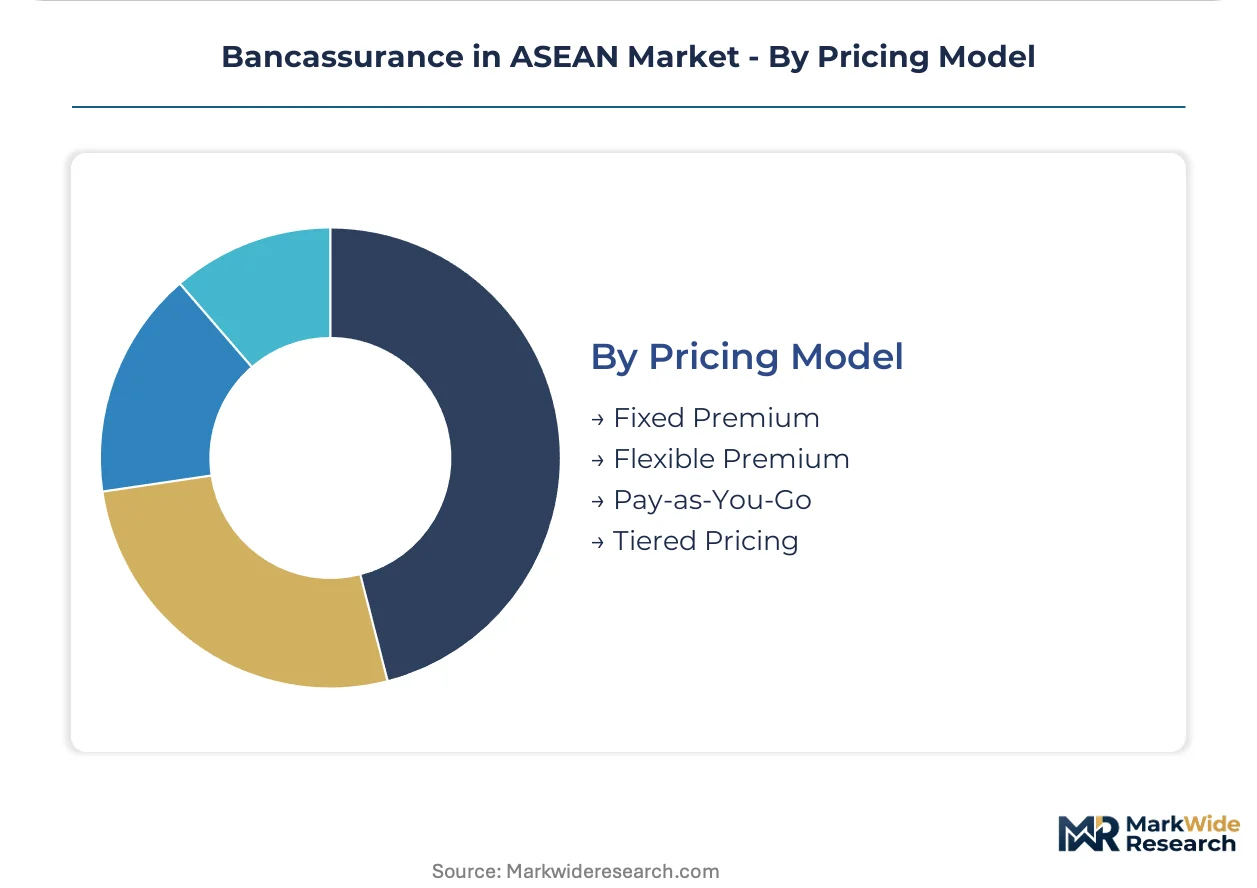
Pricing Model:
Premium structure flexibility determines product-market fit across income-diverse ASEAN populations.
- Fixed Premium:Level-term products suit salaried depositors with predictable income streams across Thai and Indonesian retail networks. Simplified underwriting supports instant issuance without medical examination.
- Flexible Premium:Adjustable contribution schedules accommodate seasonal income patterns among agricultural borrowers in Vietnam's rural banking cooperatives.
- Pay-as-You-Go:Microinsurance products link premiums to transaction frequency in Philippine cooperative banking.
- Tiered Pricing:Risk-stratified premium bands align with customer verified income documentation under Bank Negara Malaysia suitability requirements.
Fixed Premium structures dominate transaction volume. Flexible Premium models show the strongest uptake trajectory in rural penetration strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bancassurance operations in Southeast Asia trace their modern scaling to Singapore's development as a regional financial hub during the 1990s, when universal banks first integrated insurance distribution into private wealth advisory. This institutional template subsequently diffused across Indonesia, Thailand, and Malaysia through regulatory harmonization and cross-border carrier expansion.
Indonesia
Rural cooperative banks and provincial joint-stock networks drive microinsurance penetration among agricultural borrowers. Otoritas Jasa Keuangan distribution regulations mandate transparent commission disclosure and cooling-off provisions that reshape product matching. Jakarta-headquartered carriers leverage dense branch infrastructure across Java to convert deposit relationships into protection coverage.
Thailand
Commercial banking channels attach hospitalization riders to secured-lending products at point-of-credit disbursement. Bank of Thailand supervision of bancassurance partnerships enforces fair dealing standards on investment-linked sales. Bangkok-based universal banks command retail premium flow through teller-assisted conversion in provincial branch networks.
Singapore
Private banking segments concentrate margin pools through unit-linked products with estate planning integration. Monetary Authority of Singapore's fair dealing framework governs product suitability and restricts tied-selling arrangements. The city-state's wealth management hub status attracts regional high-net-worth individuals seeking advisory-wrapped protection solutions.
Malaysia
Takaful-bancassurance integration sustains dual-channel distribution through Islamic banking windows. Bank Negara Malaysia operational guidelines mandate independent suitability review when recommended premiums exceed thirty percent of verified income. Kuala Lumpur and Johor Bahru private banking centers restructure advisory workflows to embed compliance checkpoints.
Vietnam
Underbanked populations in provincial districts intersect with rising middle-class asset protection needs. State Bank of Vietnam e-KYC mandates enable digital onboarding that eliminates physical branch dependencies. Ho Chi Minh City and Hanoi urban depositors demonstrate strongest preference for self-service policy comparison tools integrated with mobile banking dashboards.
Bancassurance in ASEAN Market Competitive Environment
Capital-heavy insurers with captive banking networks compete with asset-light carriers relying on third-party distribution agreements. The market structure tilts toward partnership-based models where underwriting expertise separates from channel control. Three archetypes dominate: pan-Asian carriers with hybrid agency-bank networks, domestic insurers anchored to systemic banking relationships, and takaful specialists integrating Islamic finance distribution. Competitive moves concentrate on exclusive bancassurance partnerships and API-first technology integration that compresses policy issuance cycles.
Within the pan-Asian carrier tier, AIA Group and Prudential plc represent partnership-heavy distribution models spanning multiple ASEAN jurisdictions. Etiqa occupies a position exemplifying takaful-bancassurance integration within its home market structure. Domestic banking-insurance combinations including Maybank and Bangkok Bank anchor regional presence through captive distribution control. These entities sit within competitive positions defined by regulatory licensing depth and core banking integration maturity rather than product differentiation alone.
| Leading Market Players |
|---|
| Etiqa |
| Sun Life Financial |
| AIA Group |
| Bangkok Bank |
| Allianz |
| Prudential plc |
| Great Eastern Holdings |
| Maybank |
| AXA Mandiri Financial Services |
| Others |
Value Chain & Pricing Dynamics
Pan-Asian carriers with sovereign-wealth backing anchor supply-side discipline across ASEAN bancassurance corridors, converting captive banking relationships into pricing power that resists commission compression from regional regulators. Their capital depth enables sustained investment in API infrastructure that smaller asset-light competitors cannot match, entrenching tiered access economics.
Pricing Analysis
Three-tier pricing structure across premium advisory, standard retail, and economy microinsurance levels governs ASEAN bancassurance economics. Premium differentiation hinges on relationship-manager touch density and embedded estate-planning complexity for high-net-worth segments, while rural cooperative channels compete on transaction-linked micro-premium granularity. Cost compression in standard retail tiers intensifies as Bank Negara Malaysia and Otoritas Jasa Keuandan mandate fee transparency, squeezing distributor margins. Individual customers in Indonesian provincial networks exhibit highest price elasticity, whereas Singapore private banking clients accept advisory-overlay premiums without volume negotiation.
Supply Chain Analysis
Regulatory licensing from Bank Negara Malaysia, Otoritas Jasa Keuandan, and Monetary Authority of Singapore gates carrier access to banking distribution infrastructure across the region. Policy administration technology concentrates in Singapore, Malaysia, and Thailand where universal banks command dense branch networks. Core system modernization draws from cloud-native middleware providers and legacy mainframe integrators. Single-source vulnerability persists in biometric KYC verification services tethered to national ID databases. Distribution runs through exclusive bancassurance partnerships rather than open-architecture marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bancassurance economics favor margin expansion through digital onboarding cost reduction and advisory-fee premiumization in private banking segments. API-first infrastructure investments compress policy issuance cycles while compliance automation sustains suitability-documentation quality.
For Market Incumbents: Deploy exclusive partnership renewal leverage to lock out emerging digital-native carriers from provincial joint-stock bank networks in Vietnam and Indonesia. Anchor defensive positioning through backward integration into core banking middleware, reducing dependency on third-party API vendors. Counter commission-disclosure regulatory pressure by restructuring product mix toward investment-linked wrappers where fee transparency mandates preserve margin pools. For New Entrants and Emerging Players: Embedded-finance platform routes through e-wallet and super-app ecosystems offer white-space penetration without legacy branch infrastructure. Target agricultural credit-protection bundles in Vietnam's district-level banking cooperatives where international carriers maintain minimal presence. Pursue regulatory sandbox admission for remote biometric KYC issuance to establish bank-channel equivalence without physical teller dependency. For Investors and Strategic Acquirers: Regional universal banks with captive insurance licenses are the most active acquirer in this space, seeking underwriting capability to complement deposit-gathering dominance. Long-term viability centers on technology integration maturity rather than standalone actuarial excellence. Monitor central bank digital licensing rulings on platform-channel equivalence as inflection signal for asset-light carrier valuations.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Core System Integration | Real-time data exchange with Bank Negara Malaysia-compliant policy engines collapses issuance cycles. |
| Exclusive Bancassurance Partnership | Locked distribution through Indonesian provincial joint-stock banks secures rural penetration economics. |
| Biometric KYC Platform Launch | Facial recognition liveness detection satisfies Otoritas Jasa Keuandan remote onboarding mandates. |
| Takaful-Bancassurance Integration | Islamic banking window access in Malaysia and Indonesia captures dual-channel premium flow. |
| Advisory Workflow Restructuring | Compliance checkpoint embedding before proposal generation satisfies suitability review requirements. |
Study Parameters
Multiple input streams — executive interviews with regional carrier distribution heads, regulatory filing analysis from ASEAN monetary authorities, and proprietary banking partnership databases — were reconciled to construct market sizing. Primary fieldwork encompassed discussions with bancassurance operations directors, digital channel strategists, compliance officers at universal banks, and policy administration technology vendors. Secondary validation drew from Otoritas Jasa Keuandan distribution regulation filings, Bank Negara Malaysia bancassurance guideline updates, Monetary Authority of Singapore fair dealing framework circulars, and insurer annual report segment disclosures. Bottom-up partnership revenue estimates were cross-checked against top-down premium flow aggregates from banking sector statistical releases.
Historical premium trajectory was cross-referenced against panel input from carrier strategy teams to establish baseline growth patterns across the projection horizon. The analytical framework modeled segmentation across distribution channel density, product actuarial complexity, client relationship depth, and regulatory jurisdiction clustering. CAGRs were derived from trend extrapolation adjusted for digital adoption inflection points and regulatory implementation timelines. Forecast inputs incorporated e-KYC mandate rollout schedules, branch network expansion plans from Philippine and Vietnamese cooperative banking federations, and private banking asset-growth projections from Kuala Lumpur and Singapore wealth management centers.
The model assumes a particular technology adoption path; alternative pathways for fully decentralized blockchain-based policy issuance would alter the outlook. Forecasts reflect embedded assumptions regarding sustained regulatory harmonization across ASEAN monetary authorities and stable sovereign credit ratings for key banking sectors. A model refresh is warranted upon material change in central bank digital licensing frameworks or biometric KYC infrastructure deployment timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Marine Freight Insurance Market
Insurance
Earthquake Insurance Market
Insurance
Canada Property and Casualty Insurance Market
Insurance
Germany Property and Casualty Insurance Market
Insurance
Asia-Pacific Mobile Phone Insurance Market
Insurance
Liability Insurance Market
Insurance
China Business Income Insurance Market
Insurance
Global SME Insurance Market
Insurance
Usage-Based Insurance (UBI) Market
Insurance
Compulsory Third Party (CTP) Insurance Market
Insurance
Europe EV Insurance Market
Insurance
Disability Insurance Market
Insurance
United Kingdom Parametric Insurance Market
Insurance
India Parametric Insurance Market
Insurance
Europe Health Insurance Market
Insurance
MENA Health and Medical Insurance Market