
 Social Media Analytics-Based Insurance Market | 2026-2036
Social Media Analytics-Based Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Social Media Analytics-Based Insurance Market Analytics
The capital-intensity divergence between cloud-native insurtech platforms and legacy data providers is redrawing competitive boundaries in social media analytics for insurance. Oracle leverages its enterprise database infrastructure to anchor large-scale sentiment processing for tier-one carriers. SAS Institute Inc. differentiates through specialized statistical modeling tools that underwriters embed directly into pricing workflows. International Business Machines Corporation sustains relevance via Watson's natural language processing capabilities applied to claims verification.
Social media analytics-based insurance refers to the systematic extraction, processing, and actuarial application of publicly available social media data to inform underwriting decisions, detect fraud patterns, and personalize policy offerings. The technology typically ingests unstructured text, image metadata, and geolocation signals through APIs, then applies machine learning classifiers to generate risk scores or behavioral profiles that integrate with core insurance systems. Risk Assessment leads product type adoption because carriers prioritize loss prevention over post-sale engagement, while Claims Management represents the fastest-growing segment as social evidence accelerates fraud investigation cycles. Machine Learning dominates the technology stack for predictive scoring, though Natural Language Processing is gaining ground as insurers analyze multilingual customer sentiment across markets.
The EU AI Act and GDPR constrain how European carriers deploy automated profiling from social sources, while the US state insurance commissioners are developing guidance on algorithmic fairness that affects cross-border product design. HIPAA creates additional boundaries when health insurers attempt to correlate social behavior with medical underwriting in the United States. Stakeholders must monitor evolving regulatory thresholds for explainable AI and consent frameworks before scaling social data integration into standard pricing models.
Market Dynamics
The EU AI Act's risk-classification framework for automated decision-making is fragmenting how carriers deploy social media data into underwriting workflows, forcing tier-one insurers to maintain parallel compliance architectures across jurisdictions.
Growth Catalysts
- Fraud Detection Acceleration:Social media evidence compresses claims investigation cycles by surfacing timestamped behavioral contradictions that adjusters previously uncovered through months of manual discovery.
- GDPR Article 22 Challenges:European carriers investing in explainable AI architectures for automated profiling are creating competitive moats as regulators scrutinize black-box scoring models.
- Geofencing Integration:Usage-based auto insurers combine social location data with telematics to refine dynamic pricing models for commercial fleet policies.
Market Restraints
- API Cost Volatility:Platform data access fees from major social networks create unpredictable input cost structures for mid-size carriers without enterprise-scale negotiating leverage.
- Consent Architecture Fragmentation:The absence of standardized consumer authorization frameworks across US state insurance commissioners forces redundant legal engineering for multi-state product rollouts.
- Optical Character Recognition Limitations:Image-based risk signals from social posts remain unreliable for automated extraction, requiring costly human verification layers.
Strategic Opportunities
- Micro-Insurance Distribution:Embedded social media analytics enable parametric crop insurance penetration in India's agricultural districts through smartphone-based risk assessment.
- Natural Language Processing Convergence:Multilingual sentiment engines combined with computer vision create unified behavioral scoring for cross-border health and travel policies.
- IRA Climate Disclosure Rules:US property insurers leverage social media wildfire and flood imagery to satisfy federal climate risk reporting mandates while refining exposure models.
Industry Challenges
- Actuarial Data Science Talent Scarcity:Underwriters with dual competency in traditional pricing and machine learning feature engineering command premium compensation that strains carrier cost structures.
- Core System Integration Complexity:Policy administration platforms from the 1990s lack API architectures capable of ingesting real-time social data streams without middleware investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Social Media Analytics-Based Insurance Market |
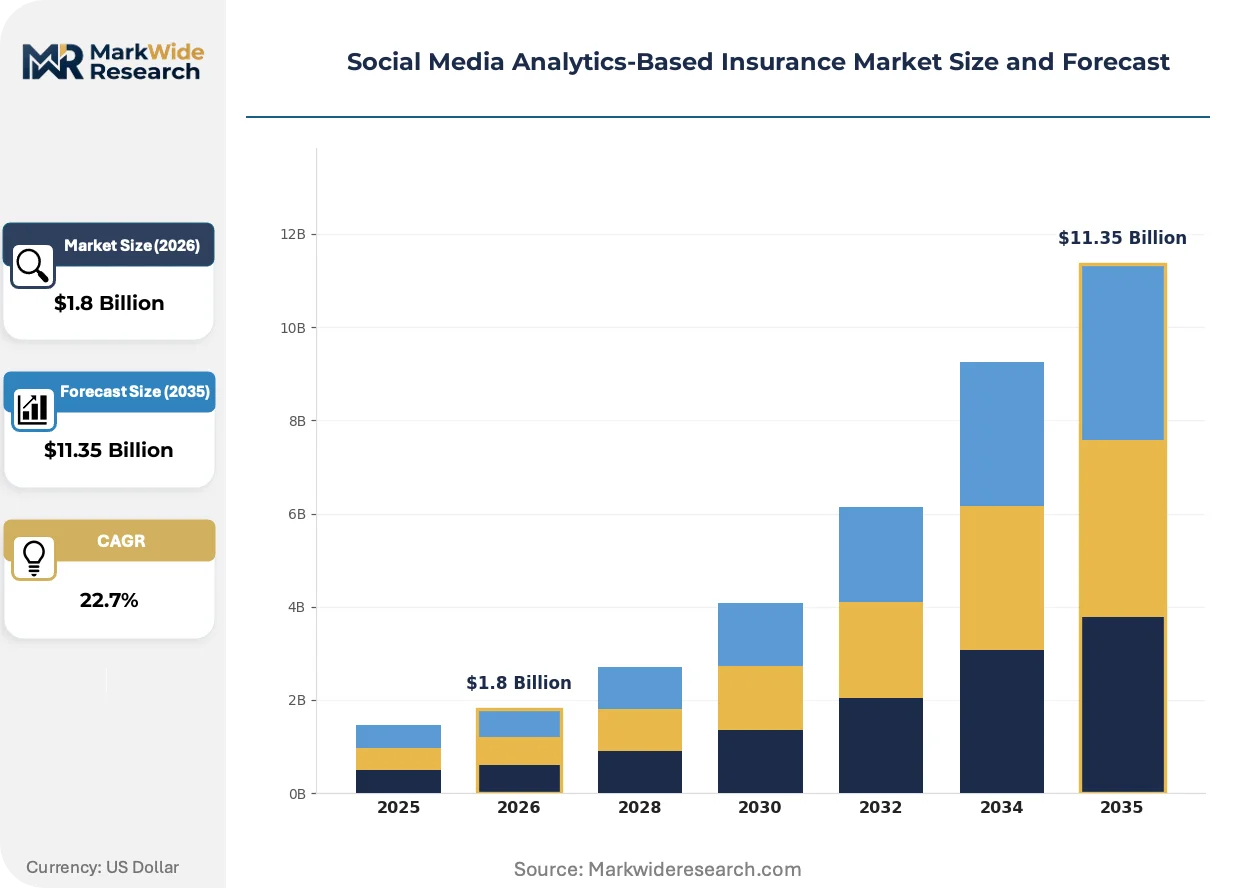
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $11.35 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Premium Analytics, Risk Assessment, Customer Insights, Claims Management Technology: Machine Learning, Natural Language Processing, Big Data, Cloud Computing End User: Insurance Providers, Brokers, Underwriters, Insurtech Firms Application: Fraud Detection, Customer Segmentation, Market Research, Policy Pricing |
| Companies Covered | Oracle, Meltwater, Digimind, Hootsuite Inc., Sprout Social Inc., Brandwatch, International Business Machines Corporation, Salesforce, Inc., SAS Institute Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Social Media Analytics-Based Insurance Market Evolving Landscape
Generative AI tools for synthetic training data creation are reshaping how carriers validate social media risk models without exposing actual consumer profiles to compliance exposure.
Federated learning architectures are fragmenting across the property and casualty segment, enabling carriers to train behavioral models on decentralized social datasets without centralizing sensitive consumer information. Mid-size regional insurers in the United States adopt these privacy-preserving techniques fastest as they lack the legal resources of national carriers for traditional data pooling agreements. The approach compresses time-to-market for new risk scores while reducing GDPR and state-level regulatory exposure.
The EU AI Act's high-risk system classification for insurance pricing algorithms is forcing European carriers to maintain human-in-the-loop review protocols for social media-derived risk adjustments. German and French regulators now require documented override rates and bias testing before algorithmic models receive supervisory approval. Health and life insurers face the steepest compliance burden as medical underwriting from behavioral data triggers the strictest oversight tier.
Buyer concentration among commercial policyholders is compressing sales cycles for social media analytics vendors as large enterprises demand outcome-based pricing tied to measurable fraud reduction. Risk managers at Fortune 500 firms now embed social data verification requirements directly into broker RFPs, displacing traditional reference-based underwriting for directors and officers coverage. The shift is most pronounced in technology and financial services verticals where reputational risk carries premium weight.
Social Media Analytics-Based Insurance Market Segmentation
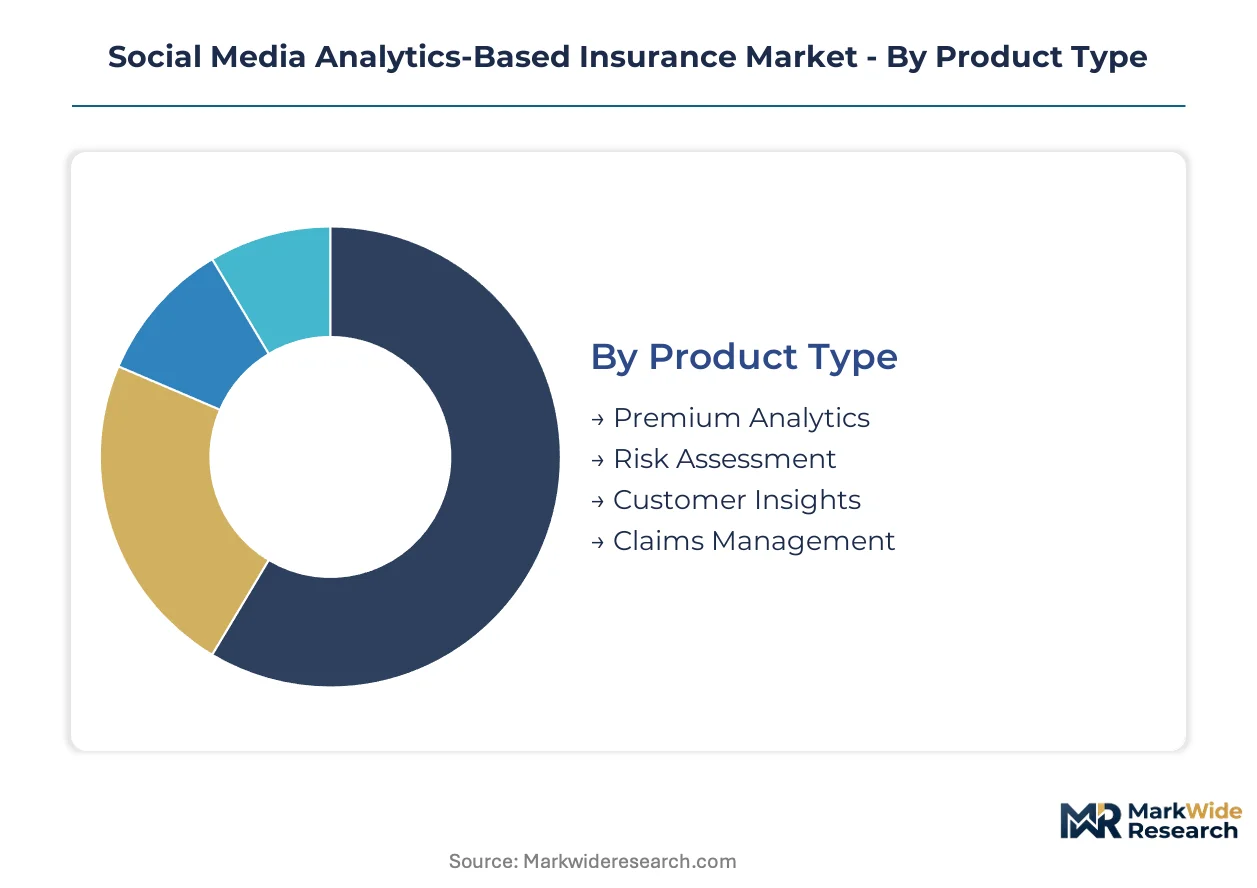
Segmentation in social media analytics-based insurance reveals how carriers allocate technology spend across divergent risk management priorities. Product type and technology stack choices determine regulatory exposure, integration complexity, and competitive differentiation for tier-one carriers versus regional specialists.
Product Type:
Risk Assessment and Premium Analytics face intensifying substitution pressure from embedded telematics and IoT sensor networks that bypass social data entirely for certain policy lines.
- Risk Assessment:Core underwriting engines ingest geolocation signals, image metadata, and behavioral timestamps to generate dynamic risk scores. Property and casualty carriers in the United States prioritize this segment for commercial fleet and homeowners policies where social evidence supplements traditional credit-based pricing. GDPR Article 22 compliance costs in Europe constrain deployment velocity for automated profiling features.
- Claims Management:Fraud investigation platforms surface timestamped behavioral contradictions across social posts to accelerate cycle times. This segment is expanding most quickly as adjusters integrate social evidence with traditional SIU workflows, particularly for disability and workers compensation claims where physical activity posts contradict reported injuries.
- Premium Analytics:Pricing optimization tools aggregate sentiment trends and network influence metrics to refine rate adequacy. Mid-size carriers lacking proprietary data assets license these capabilities from specialized vendors.
- Customer Insights:Engagement analytics map policyholder lifecycle touchpoints to reduce churn and identify cross-sell moments. Life insurers deploy these tools for annuity retention programs.
Risk Assessment anchors the volume base while Claims Management gains share at the steepest rate.
Technology:
Technology stack selection tracks carrier maturity, with cloud-native insurtechs prioritizing elastic infrastructure while legacy carriers emphasize on-premise statistical packages for regulatory defensibility.
- Machine Learning:Predictive classifiers trained on historical claims outcomes identify anomalous social behavioral patterns correlated with fraud probability. Tier-one carriers maintain proprietary feature engineering teams for model differentiation. United States auto insurers deploy gradient-boosted models combining social location data with telematics for usage-based pricing.
- Natural Language Processing:Multilingual sentiment engines extract emotional valence and topic clusters from unstructured post content. European carriers invest heavily here to satisfy EU AI Act explainability requirements for algorithmic decision-making.
- Big Data:Distributed processing architectures handle petabyte-scale social graph analysis for enterprise fraud consortiums. Infrastructure costs limit adoption to national carriers with dedicated data engineering functions.
- Cloud Computing:Elastic compute resources enable burst processing during catastrophic event monitoring when social media volumes spike. Regional insurers leverage managed services to avoid capital expenditure on dedicated hardware.
Machine Learning dominates current deployment while Natural Language Processing shows the steepest adoption trajectory among compliance-conscious European carriers.
End User:
End user segmentation reflects organizational data science maturity, with insurance providers and insurtech firms pursuing divergent build-versus-buy strategies for social analytics capabilities.
- Insurance Providers:Tier-one carriers with captive data science teams develop proprietary social risk models integrated into core policy administration platforms. These organizations face the steepest regulatory scrutiny from state insurance commissioners on algorithmic fairness testing.
- Insurtech Firms:Cloud-native startups leverage API-first social data pipelines to differentiate on speed-to-quote for micro-insurance products. Indian agricultural insurtechs exemplify this model with smartphone-based crop risk assessment.
- Brokers:Intermediaries license white-label social verification tools to enhance placement services for commercial accounts. Fortune 500 risk managers now embed social data requirements directly into broker RFPs for directors and officers coverage.
- Underwriters:Individual pricing specialists embed social signals into manual review workflows for high-value commercial policies. Human-in-the-loop protocols satisfy EU AI Act high-risk system classification requirements.
Insurance Providers command the largest technology budgets while Insurtech Firms expand their user base most aggressively.
Application:
Application segmentation tracks the insurance value chain, with fraud detection and policy pricing representing opposite ends of the maturity spectrum for social data integration.
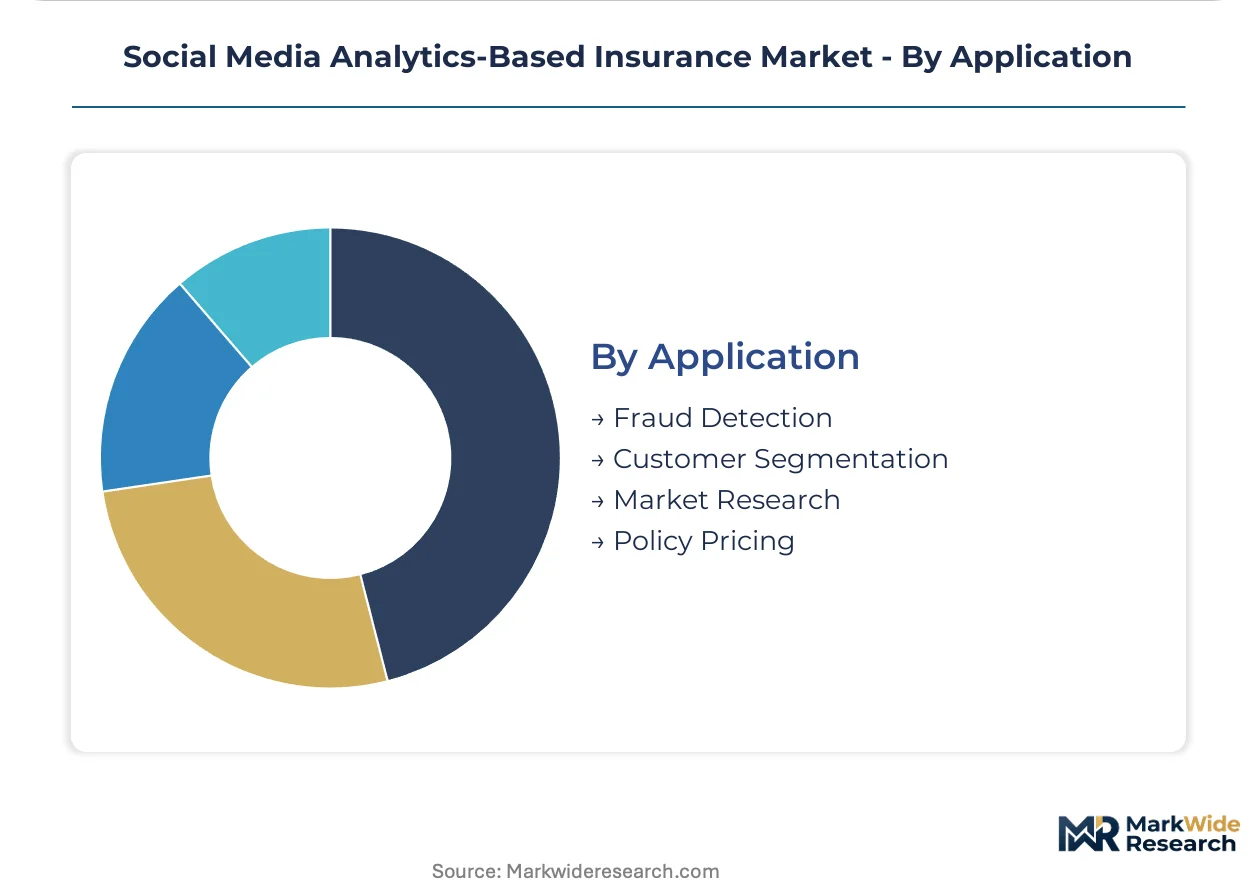
- Fraud Detection:Investigative units analyze social media timelines to identify behavioral inconsistencies with claimed injuries or losses. Timestamped geolocation data from posts frequently contradicts reported accident circumstances. This application delivers the most measurable ROI through claims cost reduction.
- Policy Pricing:Actuarial teams incorporate social behavioral scores into rating algorithms for risk-appropriate premium setting. United States property insurers leverage wildfire and flood imagery from social posts to refine exposure models and satisfy IRA climate disclosure mandates.
- Customer Segmentation:Marketing functions cluster policyholders by social influence metrics and lifestyle indicators for targeted product development. Life insurers identify high-net-worth prospects through network analysis.
- Market Research:Competitive intelligence teams monitor brand sentiment and coverage gap discussions to inform product innovation. Social listening identifies emerging risk categories before traditional loss data accumulates.
Fraud Detection generates the most concentrated demand while Policy Pricing shows the steepest growth trajectory as carriers expand algorithmic underwriting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India demonstrate the highest price elasticity for smartphone-based crop risk assessment, while Fortune 500 risk managers in the United States pay premiums for integrated fraud detection platforms. European carriers face compliance-driven cost inflation that compresses vendor margins.
United States
State insurance commissioners in California, New York, and Texas issue divergent guidance on algorithmic fairness testing, forcing carriers to maintain redundant compliance architectures. The IRA climate disclosure rules drive property insurers toward social media wildfire imagery for exposure modeling. Silicon Valley insurtech clusters and Hartford's legacy carrier concentration create dual innovation poles with conflicting data governance philosophies.
Germany
GDPR Article 22 and the EU AI Act's high-risk system classification impose strict human-in-the-loop requirements for automated profiling in underwriting. The KBA and BaFin coordinate on explainable AI standards for insurance pricing algorithms. Munich's reinsurance hub and Frankfurt's regulatory infrastructure anchor continental compliance engineering, with carriers investing heavily in documented override rate systems.
India
Agricultural micro-insurance penetration drives demand for smartphone-based parametric crop risk assessment through social media location signals. The RBI and IRDAI develop sandbox frameworks for insurtech data sourcing while BIS standards shape API interoperability. Bangalore's insurtech startup density and Mumbai's national carrier headquarters concentrate smartphone-first distribution innovation for rural markets.
United Kingdom
FCA guidance on consumer duty and algorithmic transparency shapes how carriers deploy social sentiment for pricing optimization. The Information Commissioner's Office scrutinizes automated decision-making in insurance with particular attention to protected characteristics. London's Lloyd's market and Edinburgh's data science clusters specialize in commercial lines fraud investigation using social evidence for high-value claims.
Japan
METI's AI governance guidelines and the Personal Information Protection Commission's evolving standards constrain behavioral data integration in life and health underwriting. Aging demographics drive demand for social media analytics in customer retention rather than risk selection. Tokyo's insurtech corridor and Osaka's regional carrier networks focus on churn prediction models using lifestyle sentiment signals.
Social Media Analytics-Based Insurance Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with enterprise software incumbents leveraging database infrastructure against cloud-native challengers. The market structure reflects a bifurcation between carriers demanding end-to-end platforms and those assembling best-of-breed components. Three archetypes dominate: infrastructure-anchored incumbents with enterprise distribution, API-first specialists with vertical insurance expertise, and consulting-embedded analytics providers. Competitive moves concentrate on strategic partnerships with core system vendors and geographic expansion through regulatory-compliant data architectures.
Within the infrastructure-anchored tier, Oracle and International Business Machines Corporation occupy positions reflecting decades of enterprise insurance relationships, while SAS Institute Inc. exemplifies the statistical modeling specialist archetype with direct underwriting workflow integration. These entities represent contrasting approaches to the compliance-versus-innovation tension facing carriers, with their positioning shaped by legacy system entrenchment versus cloud-native flexibility.
| Leading Market Players |
|---|
| Oracle |
| Meltwater |
| Digimind |
| Hootsuite Inc. |
| Sprout Social Inc. |
| Brandwatch |
| International Business Machines Corporation |
| Salesforce, Inc. |
| SAS Institute Inc. |
| Others |
Value Network & Pricing Analysis
Ninety-day API access contract cycles now govern pricing power across the social media analytics-based insurance supply chain, compressing margins for mid-size carriers lacking enterprise-scale negotiating leverage with platform data providers while amplifying tier-one insurers' cost advantages through volume commitments.
Pricing Analysis
Extended service contracts and algorithmic model retraining fees now drive lifetime value capture for social media analytics vendors. Pricing stratifies across premium, standard, and economy tiers based on API call volume scale and GDPR compliance certification level. Cost compression in the mid-market tier is intensifying because platform data access fees from major social networks create unpredictable input cost structures. Fortune 500 risk managers demonstrate lowest price sensitivity, while Indian agricultural micro-insurance distributors show highest elasticity.
Supply Chain Analysis
Single-source dependency on Twitter/X and Meta platform APIs creates a chokepoint that underwrites supply fragility for carriers dependent on real-time social data ingestion. The technology stack draws from United States cloud infrastructure providers, Indian software engineering talent pools, and European compliance consulting networks. Tariff exposure on cross-border data transfer services represents the dominant structural risk. Distribution runs through direct enterprise sales teams for tier-one carriers and API-first self-serve platforms for insurtech startups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates durable competitive positioning, as EU AI Act compliance architectures and state-level insurance commissioner guidance require multi-year investment cycles that new entrants cannot easily replicate.
For Market Incumbents: Consolidate API access negotiating power through carrier consortiums to counter platform data fee volatility. Deepen backward integration into proprietary natural language processing model development to reduce dependency on third-party sentiment engines. Lock in certification investments for GDPR Article 22 explainable AI standards before regulatory thresholds tighten further.
For New Entrants and Emerging Players: Mid-market regional insurers' core system integration gaps present white-space entry points where legacy policy administration platforms lack API architectures for real-time social data ingestion. Target United States commercial fleet underwriters with usage-based pricing modules that combine telematics with social geolocation signals. Pursue outcome-based pricing contracts tied to measurable fraud reduction metrics.
For Investors and Strategic Acquirers: Carve-out targets emerge from enterprise software parents seeking to divest non-core insurance analytics units with captive carrier relationships but under-optimized cloud architectures. Five-to-ten year viability hinges on regulatory compliance tooling rather than raw predictive accuracy. Monitor EU AI Act enforcement actions against black-box scoring models as the critical inflection signal for explainable AI vendor valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Deployment | Privacy-preserving model training satisfies GDPR requirements while reducing data pooling legal costs for regional carriers. |
| Core System API Integration | Middleware partnerships with legacy policy administration vendors unlock real-time social data ingestion for established insurers. |
| Explainable AI Certification | Documented override rate systems satisfy BaFin and state insurance commissioner algorithmic fairness testing mandates. |
| Parametric Micro-Insurance Launch | Smartphone-based crop risk assessment penetrates Indian agricultural districts through RBI sandbox framework approvals. |
| Climate Risk Data Partnership | Social media wildfire imagery integration satisfies IRA disclosure rules while refining property exposure models. |
Research Methodology
A spread of perspectives from chief data officers at tier-one carriers, insurtech platform engineers, state insurance commissioner staff, and social media API product managers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, EU AI Act regulatory texts, NAIC guidance documents, and carrier earnings call transcripts. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Segmentation dimensions modeled span product type, technology stack, end user category, and application across the analysis window. CAGRs derived from historical adoption curves, regulatory implementation timelines, and technology diffusion patterns in adjacent insurance analytics markets. Forecast inputs incorporated API cost trajectory assumptions and compliance cost inflation factors specific to automated profiling regulations.
Forecasts assume regulatory continuity in EU AI Act enforcement and state-level insurance commissioner guidance; material policy shifts would require re-modeling of deployment velocity assumptions. Practitioners should keep alternative scenarios live as algorithmic fairness testing standards and platform data access terms evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Aerial Imaging in Insurance Service Market
Insurance
Musical Instrument Insurance Market
Insurance
Canada House Insurance Market
Insurance
Bancassurance Market
Insurance
Middle East and Africa Travel Insurance Market
Insurance
Europe EV Insurance Market
Insurance
General Insurance Market
Insurance
United States Dental Insurance Market
Insurance
Reinsurance Market
Insurance
Europe Embedded Insurance Market
Insurance
Europe Road Assistance Insurance Market
Insurance
B2B2C Insurance Market
Insurance
Asia-Pacific Usage-Based Insurance Market
Insurance
Global Sports Insurance Market
Insurance
Peru Insurance Market
Insurance
Japan Bancassurance Market