
 UAE PVC Pipes Market | 2026-2036
UAE PVC Pipes Market Size, Share, and Industry Trends Forecast 2026-2036
UAE PVC Pipes Market Intelligence
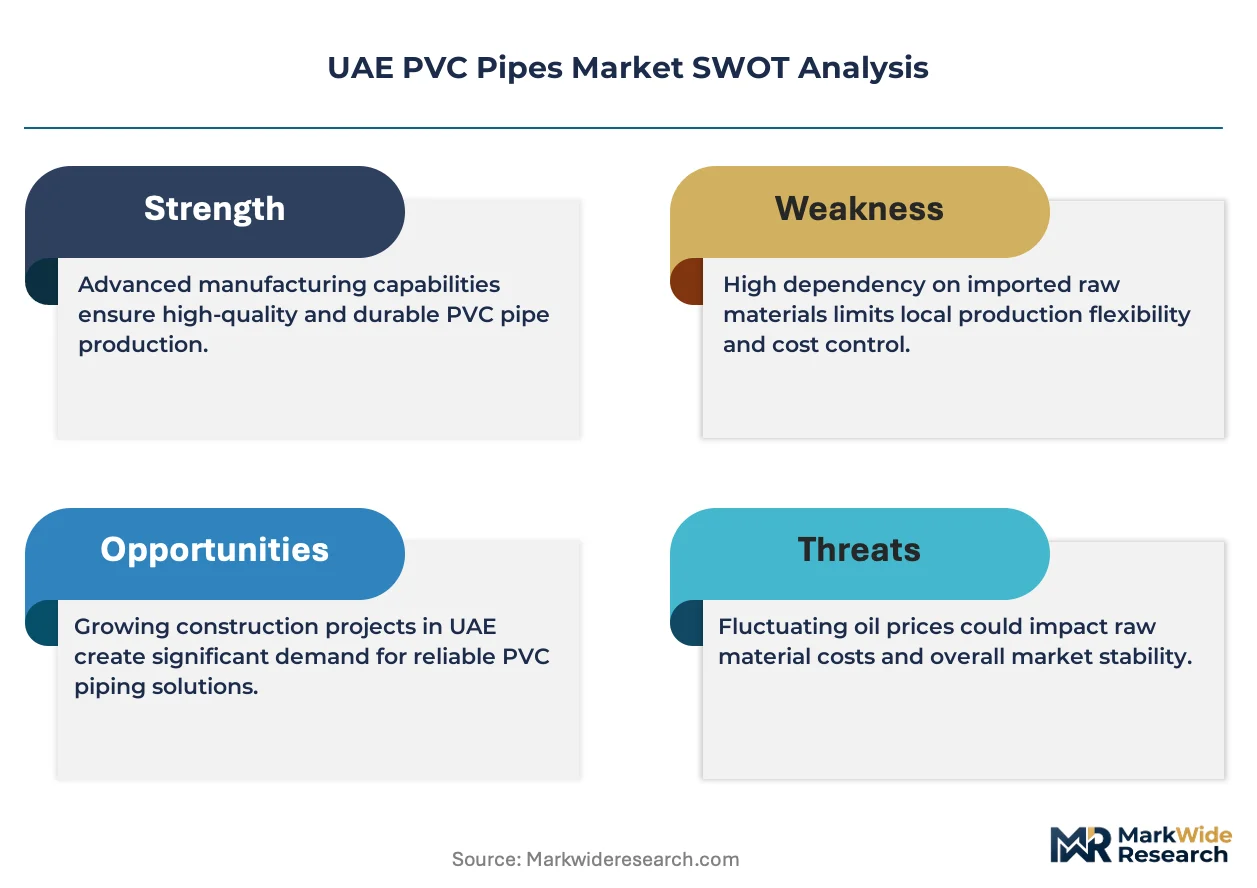
ESMA certification for potable water contact materials is bifurcating the competitive landscape into qualified and non-qualified suppliers. Hepworth Group leverages its extrusion scale to dominate specification-grade municipal contracts. Aliaxis Group sustains margin through backward integration into compounding operations. National Plastic Factory anchors its position via channel control across Emirates distribution networks.
PVC pipes are thermoplastic conduits manufactured through continuous extrusion of polyvinyl chloride resin with stabilizer and lubricant additives, typically formulated for pressure ratings from 6 to 16 bar and diameters spanning 20 mm to 630 mm, serving primarily to transport fluids and protect electrical cabling across built environments. Schedule 40 wall thickness specifications occupy the volume core of residential and light commercial construction, while PVC-O biaxially oriented pipe represents the fastest-growing structural category due to its 40% material reduction at equivalent pressure performance. Water supply applications command the dominant value share, though electrical conduit segments are deepening as smart building mandates proliferate across Gulf Cooperation Council jurisdictions.
MOHAP health material safety standards and ESMA quality conformity schemes jointly determine product eligibility for infrastructure tenders, with failure to maintain dual compliance triggering automatic disqualification from federal procurement frameworks. Abu Dhabi Department of Municipalities and Transport specifications further layer emirate-specific testing protocols that filter supplier participation. Stakeholders must monitor evolving green building certification requirements that increasingly specify recycled content thresholds and lifecycle carbon disclosures for embedded piping systems.
Market Dynamics
UAE infrastructure procurement is bifurcating around ESMA certification compliance, with specification-grade contracts concentrating among qualified extruders while non-certified suppliers retreat to non-potable drainage segments. District cooling network expansion is accelerating demand for large-diameter pressure-rated piping across Abu Dhabi and Dubai mega-projects.
Growth Catalysts
- District Cooling Infrastructure:Abu Dhabi Department of Municipalities and Transport specifications mandate PVC for district cooling distribution networks, creating dedicated demand for 315mm to 630mm diameter pressure pipes in new developments.
- MOHAP Health Material Standards:Federal potable water safety regulations are disqualifying uncertified products from healthcare and hospitality tenders, redirecting procurement toward ESMA-qualified supply chains.
- Smart Building Mandates:Gulf Cooperation Council jurisdictions are embedding electrical conduit requirements into building codes, expanding PVC deployment for low-voltage cabling protection across commercial construction.
Market Restraints
- Chlor-Alkali Feedstock Volatility:Electrolysis-based chlorine production costs fluctuate with natural gas and electricity pricing, compressing extrusion margins for non-integrated compounders.
- High-Density Polyethylene Substitution:HDPE pipe is capturing trenchless installation and seismic-zone applications where flexibility outweighs PVC's cost advantage.
- ESMA Compliance Timeline:Extended laboratory testing and factory audit cycles delay market entry for new suppliers, entrenching incumbent positions in municipal tender pools.
Strategic Opportunities
- PVC-O Biaxial Orientation:Oriented pipe technology enables 40% material reduction at equivalent pressure ratings, offering margin expansion for producers who retrofit extrusion lines.
- Ras Al Khaimah Industrial Zone:Underdeveloped northern emirate infrastructure presents first-mover advantage for certified suppliers establishing distribution depots outside Abu Dhabi-Dubai concentration.
- Recycled Content Mandates:Emerging green building certification requirements specifying post-industrial PVC incorporation create differentiation pathway for compounders with closed-loop sourcing.
Industry Challenges
- Dual Certification Burden:Simultaneous MOHAP health material and ESMA quality conformity maintenance requires dedicated regulatory affairs staffing that strains mid-scale producers.
- Legacy Specification Inertia:Consulting engineers in established Dubai developments specify traditional PVC-U grades despite PVC-O performance advantages, slowing technology transition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE PVC Pipes Market |
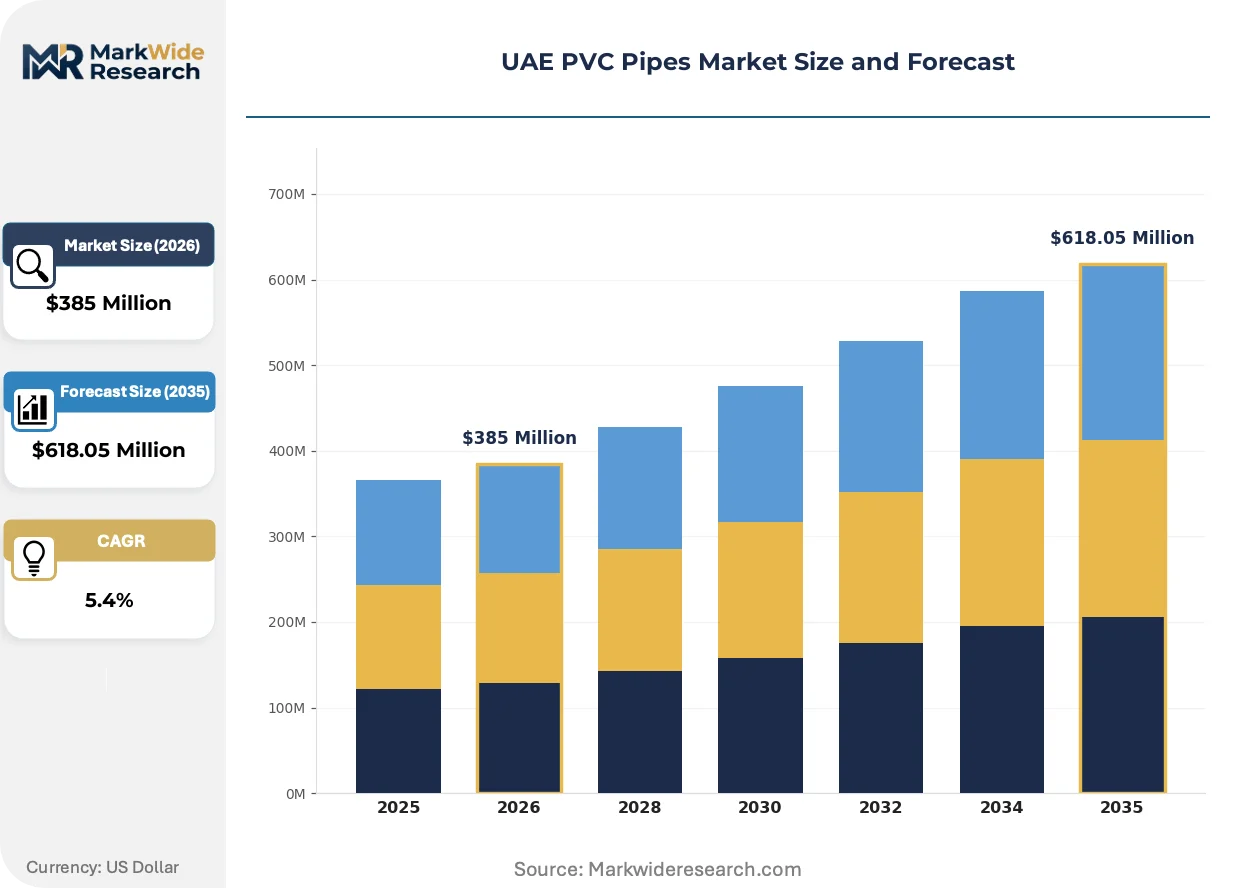
| Market Size in 2026 | $385 Million |
| Market Size in 2035 | $618.05 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Schedule 40, Schedule 80, PVC-O, PVC-M End User: Construction, Agriculture, Automotive, Infrastructure Application: Water Supply, Drainage, Irrigation, Electrical Conduit Manufacturing Process: Extrusion, Injection Molding, Blow Molding, Thermoforming |
| Companies Covered | Hepworth Group, Aliaxis Group, National Plastic Factory, Gulf Plastic Industries, Future Pipe Industries, Cosmoplast Industrial Company, Union Pipes Industry, Polyfab Plastic Industry, Shamo Plast Industries Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE PVC Pipes Market Strategic Shifts & Innovations
Material science advances and procurement digitization are restructuring competitive advantage around lifecycle performance metrics rather than unit cost alone. Specification authority is migrating from general contractors to engineering consultancies with specialized piping expertise.
PVC-O biaxially oriented pipe is decomposing the traditional PVC-U volume core by delivering equivalent pressure performance with substantially reduced wall thickness. District cooling operators in Dubai South and Masdar City are specifying oriented pipe for trunk mains to reduce trenching depths and bedding costs. This technology is decomposing the cost structure of large-diameter infrastructure projects by enabling lighter handling equipment and faster joint assembly.
ESMA's tightened potable water contact material protocols are disqualifying legacy additive packages that relied on lead-based stabilizers. Compounders must reformulate with calcium-zinc or organotin alternatives, increasing raw material costs but opening federal tender access. Municipal water departments in Al Ain and Sharjah are now requiring batch-specific migration testing certificates, shifting supplier qualification from product-type to production-run verification.
Engineering-procurement-construction firms are consolidating specification authority through centralized material pre-approval databases that filter distributor offerings before project bidding. Local distributors without direct extruder partnerships are losing specification influence as EPCs demand mill certificates and traceability documentation. This concentration is most visible in Dubai's mega-project pipeline where NOC consortiums mandate approved vendor lists with sub-24-hour technical response requirements.
UAE PVC Pipes Market Segmentation
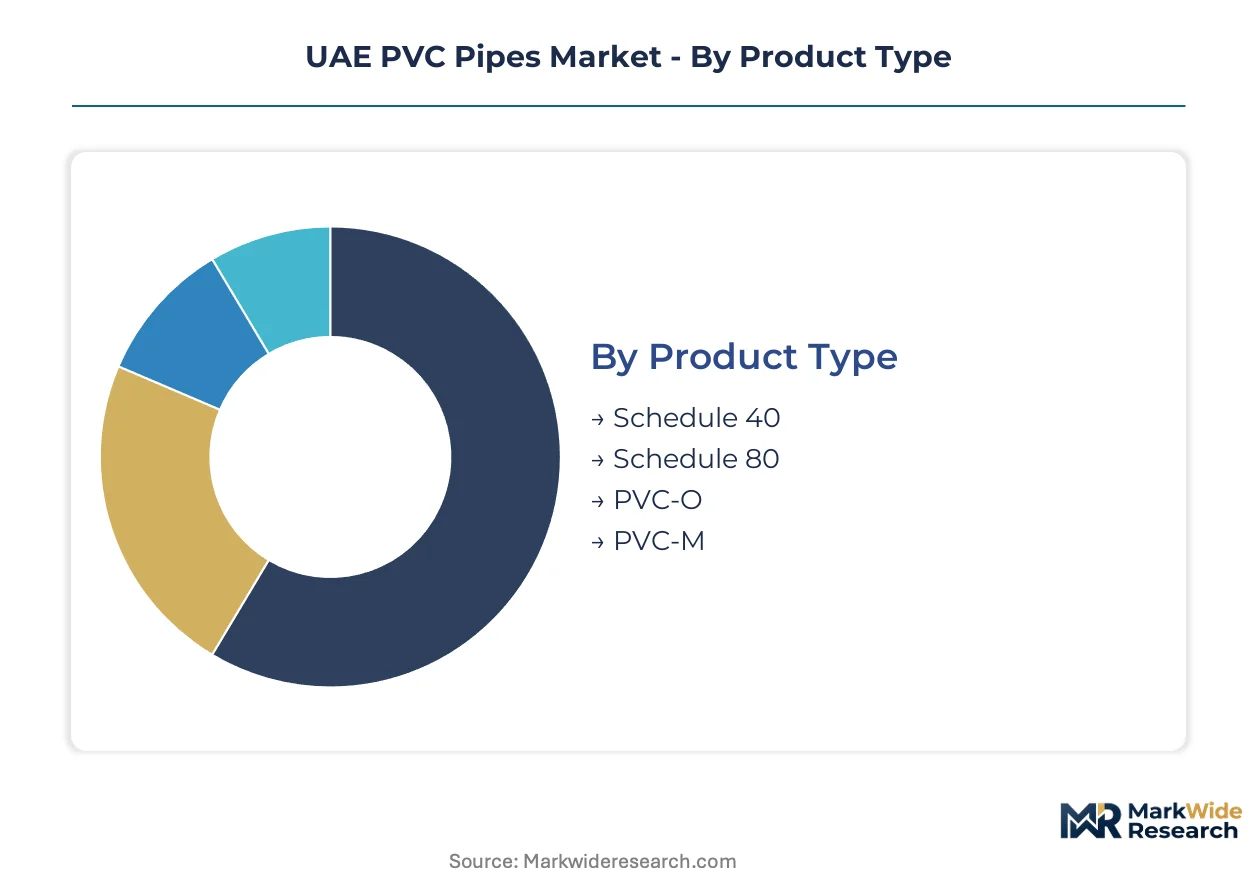
Segmentation in the UAE PVC pipes market reveals how specification pressure and certification requirements fragment procurement patterns across product grades and end-use applications. Understanding these divisions exposes where HDPE substitution threatens incumbent positions and where ESMA compliance creates defensive moats.
Product Type:
Schedule 40 faces the most acute substitution pressure from HDPE in trenchless applications, while specialty grades command specification premiums through performance differentiation.
- Schedule 40:Standard wall thickness formulation dominates residential and light commercial construction with pressure ratings from 6 to 10 bar. Demand concentrates in Dubai's villa developments where cost-sensitive contractors specify this grade for non-critical drainage, though ESMA potable water restrictions are narrowing its addressable market.
- PVC-O:Biaxially oriented molecular structure delivers equivalent pressure performance with 40% material reduction versus conventional grades. Abu Dhabi Department of Municipalities and Transport specifications for district cooling trunk mains are accelerating adoption across Masdar City and Al Reem Island mega-projects.
- Schedule 80:Thicker wall construction rated for 12 to 16 bar pressure serves industrial process piping and high-rise plumbing risers.
- PVC-M:Modified impact-resistant formulation targets seismic zones and difficult soil conditions where ductility requirements exceed standard PVC-U capabilities.
Schedule 40 anchors the volume base while PVC-O gains share at the steepest rate.
End User:
Construction procurement concentrates in Abu Dhabi and Dubai, while agriculture and automotive segments operate under lighter regulatory scrutiny with thinner margin profiles.
- Construction:General contractors and specialty trades account for the dominant value pull, spanning residential towers, commercial complexes, and hospitality developments. Dubai South and Expo City legacy projects specify large-diameter pressure piping for district cooling distribution networks.
- Infrastructure:Federal and emirate-level water authorities drive specification-grade demand with mandatory ESMA and MOHAP dual certification. Sharjah Electricity and Water Authority tenders require batch-specific migration testing that filters supplier participation.
- Agriculture:Farm operators and greenhouse developers source lower-pressure irrigation piping with minimal regulatory overlay, exposing this segment to price competition from unqualified extruders.
- Automotive:Wiring harness protection and fluid routing applications represent a niche volume pool with specialized diameter and flexibility requirements.
Infrastructure commands the specification high ground while construction delivers the deepest volume throughput.
Application:
Water supply applications carry the heaviest compliance burden, whereas electrical conduit is expanding through smart building code mandates with lighter certification requirements.
- Water Supply:Potable water distribution and transmission mains face the strictest ESMA contact material protocols, disqualifying legacy lead-stabilized formulations. Federal procurement frameworks now require production-run verification rather than product-type approval.
- Electrical Conduit:Low-voltage cabling protection for commercial and residential buildings is deepening as Gulf Cooperation Council jurisdictions embed conduit requirements into smart building codes. Dubai Municipality technical regulations now mandate dedicated pathways for data and power cabling.
- Drainage:Non-potable wastewater and stormwater systems operate under lighter material safety standards, attracting price-competitive supply from non-certified producers.
- Irrigation:Landscape and agricultural water distribution prioritizes cost efficiency over pressure rating, concentrating procurement in lower-tier product grades.
Water supply anchors specification value while electrical conduit expands most quickly through regulatory embedding.
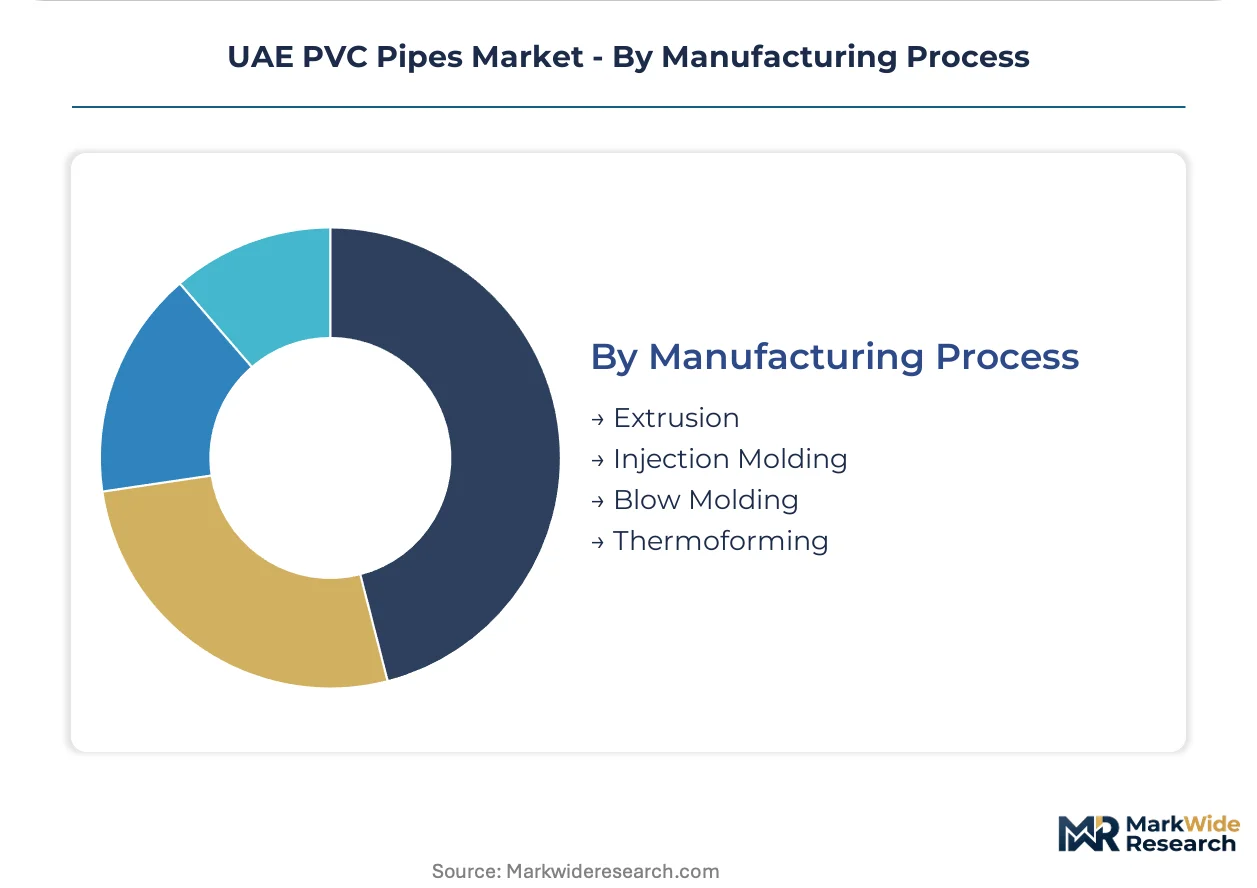
Manufacturing Process:
Process selection determines scale economics and product range breadth, with extrusion dominating infrastructure-grade output and secondary processes serving specialized geometries.
- Extrusion:Continuous profile production of pipe and conduit in diameters from 20 mm to 630 mm represents the volume core of UAE manufacturing capacity. Integrated compounders with captive resin supply command margin advantage in municipal tender pools.
- Injection Molding:Fitting and junction component fabrication enables complete system supply for contractors requiring matched pressure-rated assemblies. Ras Al Khaimah industrial zone development is attracting molders seeking lower operating costs outside Abu Dhabi-Dubai concentration.
- Blow Molding:Hollow vessel production for tanks and reservoirs serves niche water storage applications with limited overlap to mainstream piping demand.
- Thermoforming:Sheet-based shaping of custom profiles addresses specialized architectural and industrial applications with batch-scale production economics.
Extrusion commands the capacity base while injection molding deepens system integration value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specification-grade procurement concentrates in emirate-level water authorities and district cooling operators with ESMA certification requirements filtering supplier participation across the federation.
Dubai
Dubai South and Expo City legacy developments sustain demand for large-diameter pressure piping in district cooling trunk mains. Dubai Municipality technical regulations mandate dedicated electrical conduit pathways for smart building data and power cabling. Jebel Ali industrial zone hosts extrusion capacity serving both local mega-projects and re-export markets.
Abu Dhabi
Abu Dhabi Department of Municipalities and Transport specifications explicitly mandate PVC for district cooling distribution networks across Masdar City and Al Reem Island. MOHAP health material safety standards operate alongside ESMA quality conformity schemes to determine federal tender eligibility. Khalifa Industrial Zone compounders supply specification-grade material for municipal water authority contracts.
Sharjah
Sharjah Electricity and Water Authority tenders require batch-specific migration testing certificates that filter supplier participation to ESMA-qualified extruders. Lower-tier drainage and irrigation segments attract price-competitive supply from non-certified producers operating outside federal procurement frameworks. Hamriyah Free Zone injection molders produce fitting assemblies for contractors requiring matched pressure-rated systems.
Northern Emirates
Ras Al Khaimah industrial zone development presents first-mover opportunity for certified suppliers establishing distribution infrastructure outside Abu Dhabi-Dubai concentration. Underdeveloped water utility networks in Ajman, Umm Al Quwain, and Fujairah operate with lighter regulatory overlay than federal tender pools. Saqr Port proximity offers logistics advantage for compounders targeting export markets across the Gulf.
UAE PVC Pipes Market Key Industry Players
Player mix skews toward integrated compounders with captive resin supply and dedicated regulatory affairs staffing. Three tiers structure participation: multinational extrusion groups with emirate-level specification authority, mid-scale national producers with distribution network control, and price-competitive non-certified suppliers retreating to drainage segments. Dominant competitive moves include backward integration into compounding operations and strategic partnerships with engineering-procurement-construction firms for pre-approval database placement.
Within the multinational tier, Hepworth Group and Aliaxis Group occupy positions shaped by extrusion scale and compounding integration respectively. National Plastic Factory anchors the mid-scale segment through Emirates distribution network control. Gulf Plastic Industries and Future Pipe Industries exemplify regional specialists competing on proximity to northern emirate infrastructure projects.
| Leading Market Players |
|---|
| Hepworth Group |
| Aliaxis Group |
| National Plastic Factory |
| Gulf Plastic Industries |
| Future Pipe Industries |
| Cosmoplast Industrial Company |
| Union Pipes Industry |
| Polyfab Plastic Industry |
| Shamo Plast Industries Ltd. |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day ESMA certification lead times for new product introductions compress pricing power for non-qualified suppliers while amplifying margin capture among incumbent compounders with pre-approved formulations. This inventory-to-certification gap tightens procurement options for federal tender pools and redirects specification-grade demand toward integrated extruders with captive testing capacity.
Pricing Analysis
Cost-plus contracts with chlorine and ethylene indexation dominate municipal procurement frameworks, insulating qualified suppliers from feedstock volatility while exposing non-integrated compounders to margin compression. Price differentiation hinges on ESMA certification tier and pressure rating grade, with specification-grade PVC-O commanding premiums over standard PVC-U. Pricing pressure stems from HDPE substitution in trenchless applications, where flexibility requirements override PVC's cost advantage. Drainage contractors exhibit highest price sensitivity, while district cooling operators prioritize lifecycle performance over unit cost.
Supply Chain Analysis
Saudi Arabia and Qatar anchor regional chlor-alkali feedstock supply, with UAE-based compounders drawing caustic soda and chlorine derivatives from Gulf petrochemical complexes. Resin formulation rests on ethylene feedstock from Saudi crackers, stabilizer additives from European specialty chemical producers, and lubricant packages subject to REACH compliance. Single-source vulnerability concentrates in organotin stabilizer supply from Southeast Asian producers. Distribution runs through Emirates-level distributor networks with Jebel Ali and Khalifa Industrial Zone serving as consolidation hubs for re-export and local project fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE PVC pipes market sits in early-cycle recovery as district cooling infrastructure deployment accelerates across Abu Dhabi and Dubai mega-projects. Federal tender pool expansion and ESMA certification tightening create defensive positioning opportunities for prepared suppliers.
For Market Incumbents: Consolidate specification authority through backward integration into compounding operations and captive ESMA testing capacity. Deepen engineering-procurement-construction pre-approval database placement to lock out non-qualified competitors. Prioritize PVC-O line retrofits to capture material efficiency premiums in district cooling trunk main specifications. For New Entrants and Emerging Players: Technical response capability gaps in northern emirate infrastructure projects create entry pathways outside Abu Dhabi-Dubai concentration. Target Ras Al Khaimah industrial zone distribution depot establishment before incumbent network extension. Pursue recycled-content compounding partnerships to differentiate under emerging green building certification mandates. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across PVC-O biaxial orientation retrofit investments, favoring asset-light compounder acquisitions over greenfield extrusion builds. Acquire mid-scale extruders with existing ESMA qualification and Emirates distribution control. Monitor HDPE pricing spreads as substitution inflection indicator for PVC demand elasticity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compounding | Captive resin supply insulates margins from chlor-alkali volatility and secures ESMA batch consistency. |
| PVC-O Line Retrofit Investment | Biaxial orientation technology enables 40% material reduction at equivalent pressure ratings for district cooling specifications. |
| Recycled Content Partnership | Post-industrial PVC sourcing agreements position suppliers for green building certification compliance thresholds. |
| Northern Emirates Distribution Expansion | Ras Al Khaimah depot establishment captures first-mover advantage in underdeveloped utility infrastructure markets. |
| EPC Pre-Approval Database Placement | Engineering-procurement-construction vendor list inclusion filters tender access and consolidates specification authority. |
Research Approach
A spread of perspectives from extrusion plant managers, municipal procurement officers at Abu Dhabi Department of Municipalities and Transport, distributor channel partners, and ESMA regulatory affairs specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through ESMA conformity scheme documentation, UAE customs trade data, and SEC filings from multinational parent companies. Bottom-up demand modeling across district cooling, water supply, and electrical conduit applications triangulated against top-down infrastructure spending forecasts.
Segmentation dimensions modeled include product grade tier, pressure rating specification, end-use application, and emirate-level regulatory cluster across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating chlor-alkali feedstock pricing, ESMA certification timeline assumptions, and HDPE substitution threat parameters. Forecast inputs incorporated Abu Dhabi Department of Municipalities and Transport specification evolution and Dubai Municipality smart building code embedding timelines.
Material uncertainties — feedstock cost volatility, ESMA protocol amendments, and HDPE pricing spreads — sit outside the modeled envelope. Forecasts reflect assumptions subject to revision should MOHAP health material standards tighten beyond current trajectories or district cooling deployment schedules shift. Recalibration cycles align with material shifts in federal procurement framework updates and emirate-level infrastructure spending announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
HPLC Fused Silica Tube Market
Pipes and Tubes
Metal Pipe Market
Pipes and Tubes
Pipes and Fittings Market
Pipes and Tubes
Plastic Pipes and Fittings Market
Pipes and Tubes
Galvanized Iron Pipes Market
Pipes and Tubes
GRP Pipe Market
Pipes and Tubes
Stainless Steel Welded Pipes Market
Pipes and Tubes
Spain PVC Pipes Market
Pipes and Tubes
FRP Pipes and Tanks Market
Pipes and Tubes
Steel Tubes Market
Pipes and Tubes
Weld Overlay Process Clad Pipes Market
Pipes and Tubes
PVDF Pipes Market
Pipes and Tubes
GRE Pipes Market
Pipes and Tubes
Stainless Steel Tank Container Market
Pipes and Tubes
Saw Pipes Market
Pipes and Tubes
Cryogenic Pipes Market