
 Global Architectural Paint Oxide Market | 2026-2036
Global Architectural Paint Oxide Market Size, Share, and Industry Trends Forecast 2026-2036
Global Architectural Paint Oxide Market Foresight
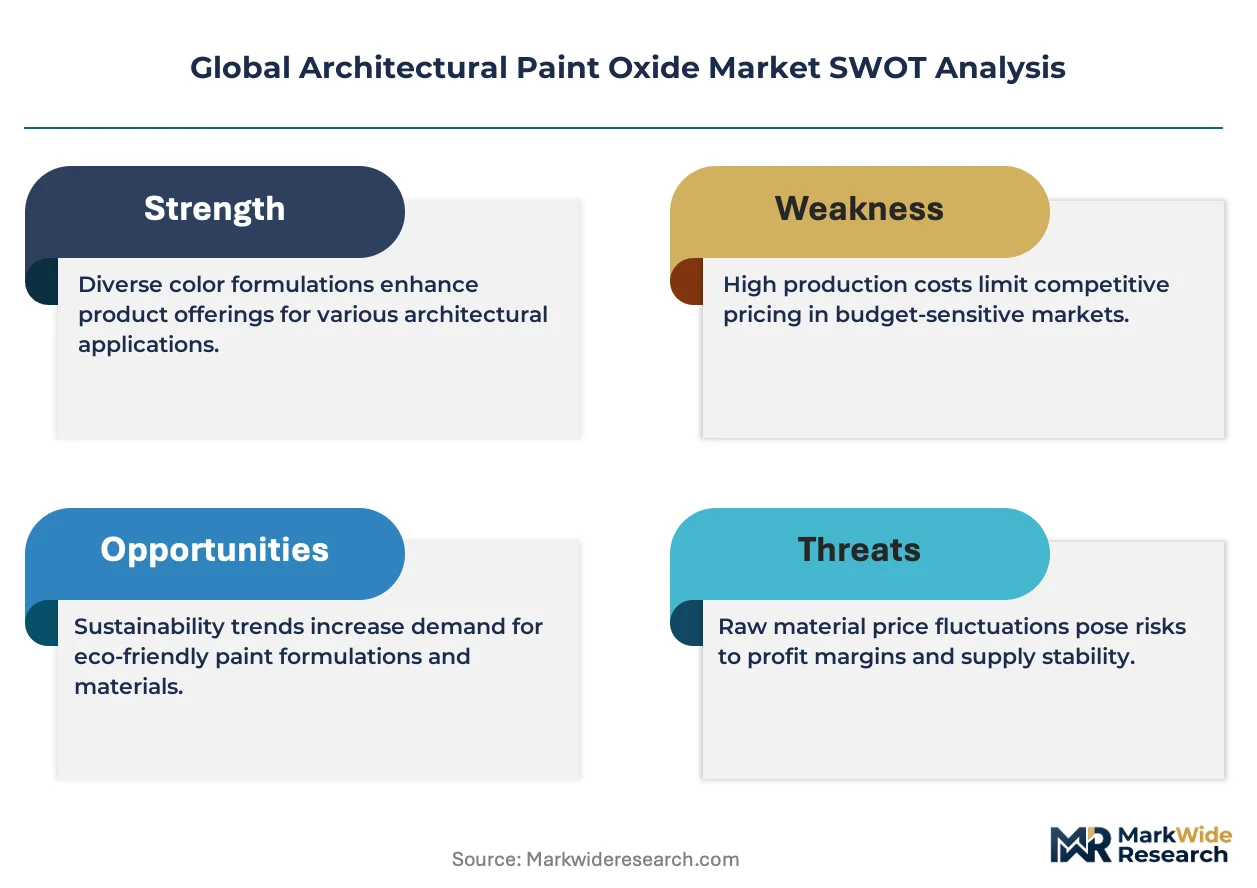
The capital-intensity divergence between integrated oxide producers and regional blenders is collapsing as environmental compliance costs equalize. BASF leverages captive chloride-process titanium dioxide capacity to sustain margin structures across European coating value chains. AkzoNobel anchors its position through water-based technology leadership, while PPG Industries competes via specialized iron oxide portfolios for North American commercial facades.
Architectural paint oxides comprise inorganic pigment compounds, primarily titanium dioxide with refractive indices exceeding 2.5, engineered to confer opacity, UV resistance, and color stability in coating films. These materials function as the dominant light-scattering phase in architectural coatings, determining hiding power, chalking resistance, and exterior durability under cyclic weathering. Titanium dioxide formulations lead volume demand across residential and commercial applications, while iron oxide pigments concentrate margin pools in heritage restoration and specialized facade coatings where earth-tone specifications predominate. Zinc oxide segments are gaining structural share in anti-microbial interior systems, though solvent-based technology categories face contraction pressure from tightening VOC regulations in multiple jurisdictions.
EPA oversight under the Toxic Substances Control Act and REACH registration requirements in Europe are reshaping permissible oxide chemistries, particularly for cadmium and chromium compounds in architectural applications. China's MEE enforces dual carbon goals that restrict sulfate-process titanium dioxide expansion, redirecting investment toward cleaner chloride-route capacity. India BIS certification mandates for architectural coating raw materials are tightening import specifications, altering supply qualification protocols for multinational oxide suppliers. Stakeholders must monitor evolving substance restriction lists and process emission standards to anticipate which oxide chemistries will retain formulation access across priority construction markets.
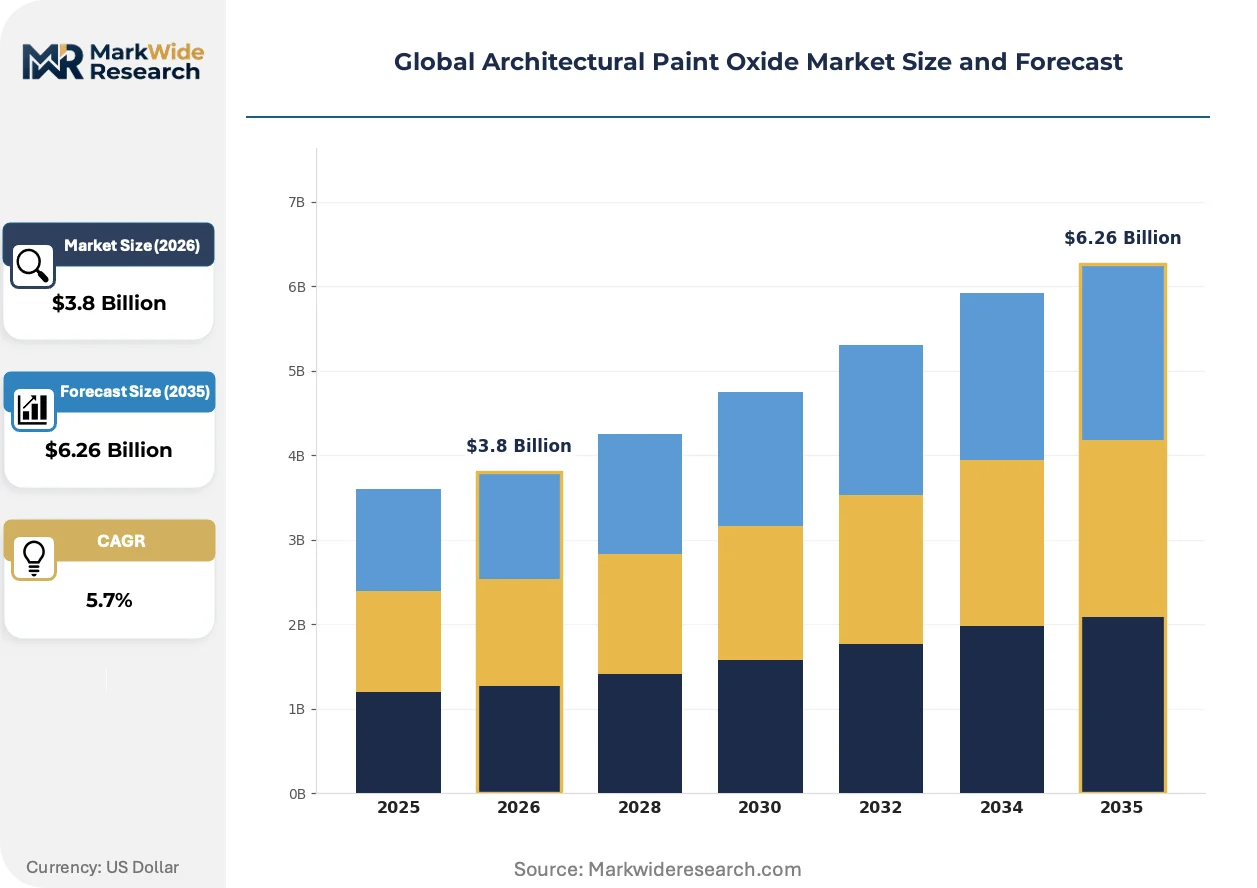
Market Dynamics
Chloride-process titanium dioxide capacity expansion is compressing sulfate-route margins while REACH substance restrictions force reformulation across European coating value chains. Water-based dispersion technologies are capturing specification share from solvent-borne systems as MEE dual carbon enforcement tightens in China.
Growth Catalysts
- Urban renewal mandates:China's megacity clusters are accelerating oxide consumption through green building certification requirements and facade refurbishment programs.
- REACH registration compliance:ECHA substance evaluation protocols are redirecting formulation chemistry toward compliant titanium dioxide systems in architectural coatings.
- Low-VOC technology transition:Water-based titanium dioxide dispersions are displacing solvent-borne alternatives in residential exterior applications across multiple jurisdictions.
Market Restraints
- Feedstock concentration:Ilmenite and rutile supply concentrates in Australian and South African mining jurisdictions, exposing processors to export restriction risk.
- Process emission limits:MEE enforcement of dual carbon goals restricts sulfate-process expansion, constraining low-cost capacity additions in China.
- Technical substitution:Calcium carbonate extenders and precipitated silica are capturing volume in interior flat coatings where hiding power requirements moderate.
Strategic Opportunities
- Heritage restoration specialization:Iron oxide pigments for earth-tone facade specifications remain underpenetrated in European conservation architecture.
- Anti-microbial interior systems:Zinc oxide segments are expanding specification access through EPA-registered coating formulations for healthcare and institutional buildings.
- EU Green Deal alignment:Carbon border adjustment mechanisms are creating preference premiums for chloride-process titanium dioxide with verified emission profiles.
Industry Challenges
- Formulation chemistry expertise:Water-based dispersion stabilization requires specialized colloid chemistry capabilities scarce among regional blenders.
- Certification timeline compression:BIS import specification tightening in India is extending supply qualification protocols for multinational oxide suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Architectural Paint Oxide Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Titanium Dioxide, Zinc Oxide, Iron Oxide, Chromium Oxide, Cobalt Oxide, Cadmium Oxide Technology: Solvent-Based, Water-Based, Powder Coating, Epoxy, Acrylic, Alkyd Application: Residential Buildings, Commercial Complexes, Institutional Buildings, Sports Facilities, Hospitality Structures, Cultural Sites End User: Paint Manufacturers, Construction Companies, Renovation Contractors, Interior Designers, Property Developers, Facade Specialists |
| Companies Covered | Nippon Paint Holdings Co., Ltd, RPM International, The Sherwin-Williams Company, BASF, Jotun, PPG Industries, Asian Paints Ltd., Kansai Paint Co., Ltd., AkzoNobel N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Architectural Paint Oxide Market Shifts & Advancements
Active reformulation across architectural coating value chains is fragmenting incumbent pigment specifications while creating entry points for specialized oxide producers. Technology convergence between dispersion chemistry and application equipment is compressing development cycles.
Surface-treated titanium dioxide grades with enhanced dispersibility in high-PVC water-based formulations are fragmenting specification standards across residential coating segments. Mid-tier coating manufacturers are adopting these modified oxides to reduce milling energy and shorten production cycles. The technology is fragmenting traditional supplier hierarchies by enabling regional compounders to meet premium hiding power specifications without captive chloride-process capacity.
REACH authorization requirements for chromium-based pigments are eliminating certain colorant chemistries from architectural facade specifications. Coating formulators are reformulating heritage restoration and commercial earth-tone applications toward compliant iron oxide and complex inorganic color alternatives. European specification writers are responding by tightening colorfastness testing protocols to ensure substituted pigments meet 25-year durability benchmarks.
Buyer concentration among national retail coating brands is compressing switching cycles and forcing pigment suppliers into direct specification relationships. Large-format home improvement retailers are consolidating approved supplier lists and demanding consolidated oxide procurement across multiple colorant lines. North American commercial facade contractors are most affected, with project specifications increasingly written around retailer-preferred coating systems rather than architect-specified pigment grades.
Global Architectural Paint Oxide Market Segmentation
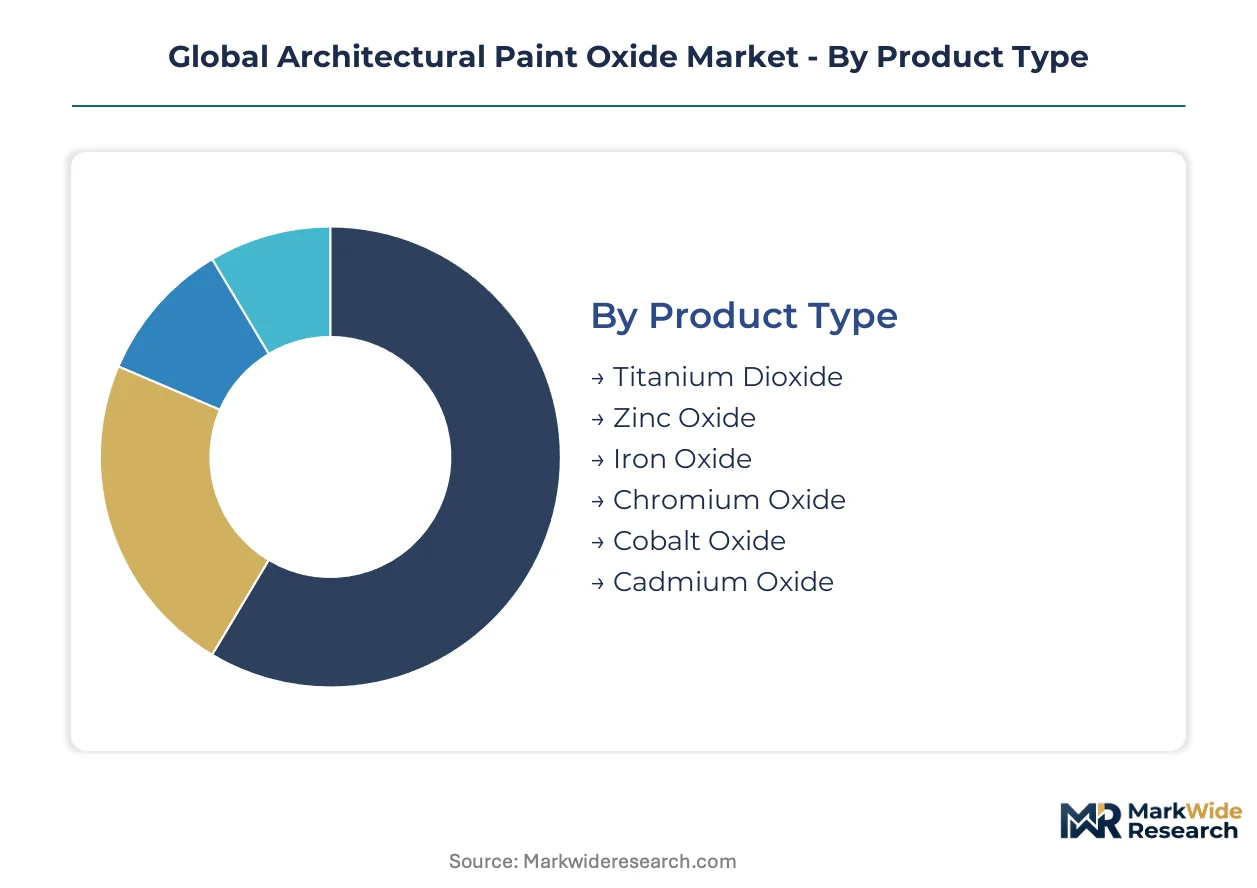
Architectural paint oxide demand fragments across product chemistries, formulation technologies, and construction end-uses with divergent specification requirements. Understanding these segment boundaries reveals where margin pools concentrate and which substitution dynamics threaten incumbent positions.
Product Type:
Domestic production of titanium dioxide dominates Chinese and Indian supply chains, while European and North American markets rely heavily on imported chloride-process grades. Export-led segments face tighter REACH and EPA registration scrutiny than regionally consumed alternatives.
- Titanium Dioxide:Chloride-process and sulfate-process variants serve as the primary light-scattering phase with refractive indices exceeding 2.5. Chinese urban renewal projects and green building mandates in Shanghai, Beijing, and Guangzhou-Shenzhen megacity clusters are accelerating consumption of water-dispersible grades.
- Iron Oxide:Synthetic and natural earth-tone pigments deliver facade color stability in heritage restoration specifications. Demand concentrates in European conservation architecture across Italy, France, and Germany where REACH chromium restrictions have redirected formulation toward compliant alternatives.
- Zinc Oxide:UV-absorbing and anti-microbial grades are gaining specification in EPA-registered interior healthcare coatings.
- Chromium Oxide:REACH authorization requirements are eliminating this chemistry from European architectural applications.
- Cobalt Oxide:Drier accelerator applications in alkyd systems face solvent-borne technology contraction.
- Cadmium Oxide:TSCA and REACH substance restrictions have largely excluded this segment from compliant coating formulations.
Titanium Dioxide holds the largest share; momentum sits with Zinc Oxide.
Technology:
Cost-tier stratification separates premium water-based dispersions from economy solvent-borne systems, with powder coating occupying a mid-tier position on capital equipment requirements.
- Water-Based:Low-VOC dispersions with specialized colloid stabilization chemistry are displacing solvent alternatives in residential exterior specifications. MEE dual carbon enforcement in China and EPA VOC regulations in the United States are accelerating this transition across new construction and refurbishment segments.
- Solvent-Based:Alkyd and urethane-modified systems retain share in industrial maintenance and heritage restoration where drying time and substrate compatibility outweigh regulatory pressure.
- Powder Coating:Zero-VOC thermoset applications concentrate in commercial facade aluminum extrusion and steel substrate specifications.
- Epoxy:Two-component systems dominate institutional flooring and high-traffic interior specifications.
- Acrylic:Emulsion polymers serve residential exterior durability requirements with superior UV resistance.
- Alkyd:Solvent-borne and water-reducible variants face structural decline from tightening VOC limits.
Water-Based formulations command volume leadership; Powder Coating climbs the fastest on commercial facade demand.
Application:
Customer-type concentration varies sharply, with property developers and national retailers driving specification in residential and commercial segments versus architect-led selection for cultural and institutional projects.
- Residential Buildings:Single-family and multi-family exterior coatings represent the dominant volume outlet for titanium dioxide opacity grades. Home improvement retailer consolidation in the United States and Germany is compressing approved supplier lists and standardizing oxide specifications across private-label brands.
- Commercial Complexes:Office, retail, and mixed-use facades demand 25-year colorfastness performance with iron oxide and complex inorganic colorant systems. North American commercial facade contractors face buyer concentration pressure as project specifications shift toward retailer-preferred coating systems.
- Institutional Buildings:Schools, hospitals, and government facilities prioritize EPA-registered anti-microbial zinc oxide systems for interior high-touch surfaces.
- Sports Facilities:Stadium and arena specifications balance durability with aesthetic flexibility across coating chemistries.
- Hospitality Structures:Hotel and resort facades emphasize premium appearance retention with surface-treated titanium dioxide grades.
- Cultural Sites:Museum and heritage building restoration requires specialized earth-tone iron oxide pigments with documented batch consistency for color matching.
Residential Buildings anchor volume demand; Cultural Sites offer the steepest expansion trajectory on heritage restoration specialization.
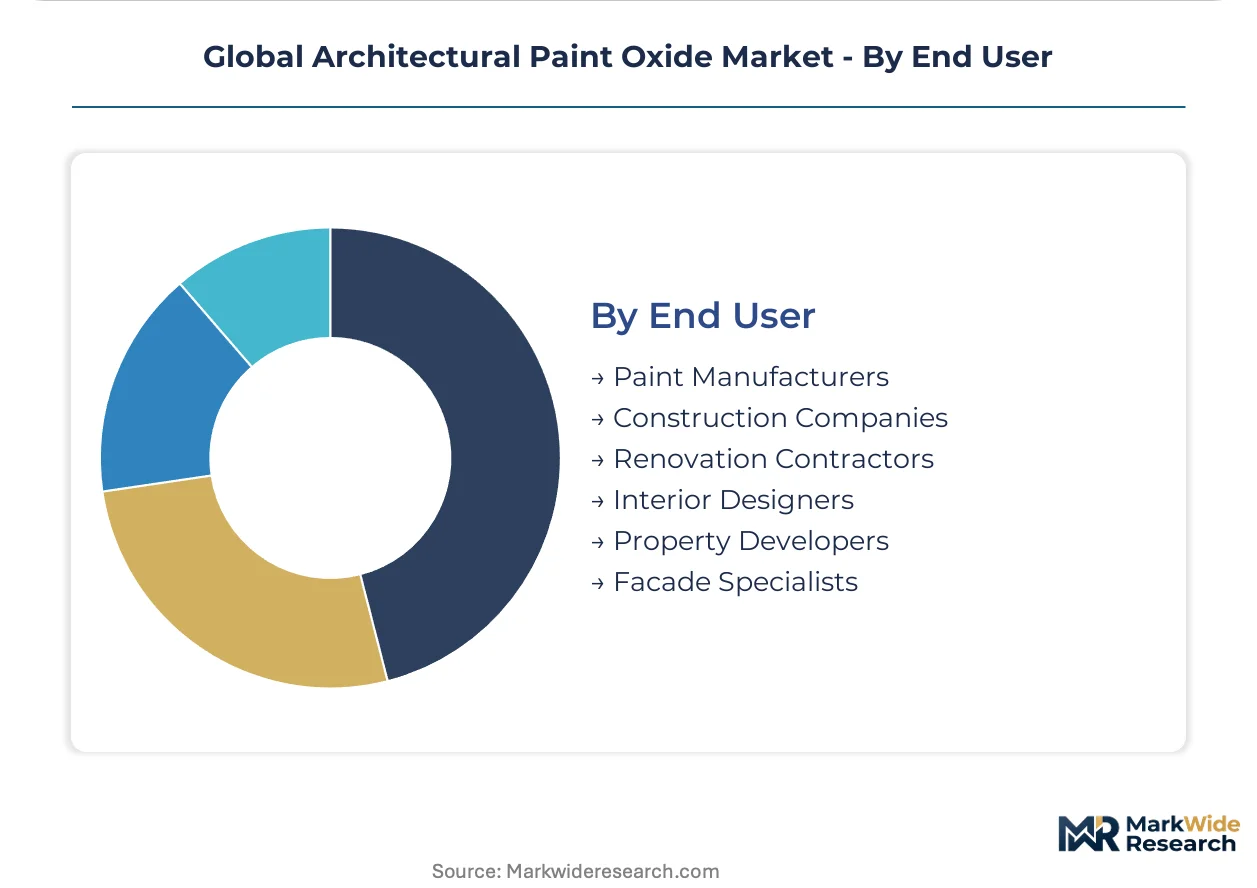
End User:
Supply concentration tilts toward paint manufacturers with captive formulation expertise, while downstream construction intermediaries face capability scarcity in dispersion chemistry.
- Paint Manufacturers:Integrated formulators with in-house milling and dispersion capabilities control specification access for surface-treated titanium dioxide grades. BASF, AkzoNobel, and PPG Industries leverage direct supplier relationships to secure chloride-process supply priority.
- Construction Companies:General contractors and specialty applicators procure through distributor channels with limited oxide chemistry influence.
- Renovation Contractors:Refurbishment specialists in European conservation markets specify iron oxide pigments for earth-tone facade restoration.
- Interior Designers:Specification influence concentrates in premium residential and hospitality segments.
- Property Developers:Large-scale multi-family and commercial projects drive volume procurement through national coating brand relationships.
- Facade Specialists:Technical contractors with application equipment expertise influence powder coating and high-performance system selection.
Paint Manufacturers retain the largest share; Renovation Contractors are gaining specification influence fastest on heritage project concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China and India exhibit high price elasticity as sulfate-process capacity competes aggressively, while European and North American purchasers prioritize REACH-compliant chloride grades with verified emission profiles regardless of cost premium.
China
Urban renewal mandates across Shanghai, Beijing, and Guangzhou-Shenzhen megacity clusters are accelerating titanium dioxide consumption for facade refurbishment. MEE enforcement of dual carbon goals restricts sulfate-process expansion, redirecting investment toward cleaner chloride-route capacity. Domestic producers in Shandong and Sichuan provinces are consolidating to meet green building certification requirements.
United States
Residential exterior coatings drive volume demand as homeowners prioritize low-VOC water-based formulations. EPA oversight under the Toxic Substances Control Act shapes permissible oxide chemistries, particularly for cadmium compounds. Gulf Coast chemical manufacturing clusters supply chloride-process titanium dioxide to national coating brands consolidating approved supplier lists.
Germany
Heritage restoration specifications concentrate demand for iron oxide pigments in conservation architecture across Bavaria and North Rhine-Westphalia. REACH authorization requirements eliminate chromium-based colorants from facade applications. BASF leverages captive chloride-process capacity to sustain margin structures across European coating value chains.
India
Green building mandates in Maharashtra and Gujarat are accelerating oxide consumption for commercial and residential construction. BIS certification tightening extends supply qualification protocols for multinational titanium dioxide suppliers. Domestic production capacity in Tamil Nadu and Karnataka serves regional coating manufacturers expanding water-based formulation capabilities.
Japan
Specialized facade coatings for seismic-resistant structures demand high-performance titanium dioxide grades with documented batch consistency. METI industrial standards govern architectural coating raw material specifications. Osaka-based coating formulators are adopting surface-treated oxide grades to reduce milling energy in high-PVC water-based systems.
Global Architectural Paint Oxide Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated chemical conglomerates with captive chloride-process capacity control premium specification access, while regional compounders compete on price in standard-grade segments. Three strategic archetypes dominate: multinational integrated producers, Asian national champions, and specialized regional blenders. Capacity expansion and portfolio diversification toward water-based dispersion technologies represent the dominant competitive moves.
Among integrated chemical conglomerates, BASF and AkzoNobel occupy positions exemplifying technology-led competitive strategy, while PPG Industries anchors the specialized iron oxide portfolio segment. Asian national champions including Nippon Paint Holdings and Kansai Paint represent scale-driven regional consolidation. These named entities serve as archetype anchors rather than exhaustive market coverage, with competitive dynamics flowing from their structural positioning across formulation technology, geographic footprint, and regulatory compliance capabilities.
| Leading Market Players |
|---|
| Nippon Paint Holdings Co., Ltd |
| RPM International |
| The Sherwin-Williams Company |
| BASF |
| Jotun |
| PPG Industries |
| Asian Paints Ltd. |
| Kansai Paint Co., Ltd. |
| AkzoNobel N.V. |
| Others |
Supply & Pricing Matrix
REACH registration requirements and ECHA substance evaluation protocols gate both supply qualification timelines and price differentiation tiers simultaneously across European architectural coating value chains. Compliance certification costs compress margins for non-integrated regional blenders while creating premium capture opportunities for chloride-process titanium dioxide suppliers with verified emission profiles.
Pricing Analysis
After-sales service bundling and technical formulation support drive lifetime value capture for oxide suppliers serving national coating brands. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and volume commitment scale. Pricing pressure stems from sulfate-route capacity compression in China as MEE dual carbon enforcement constrains low-cost expansion. National retail chains exhibit highest price sensitivity, while heritage restoration specialists accept substantial premiums for batch-consistent iron oxide grades.
Supply Chain Analysis
Inventory cycles extend to 8-12 weeks for surface-treated titanium dioxide grades as chloride-process capacity concentrates in the United States, Germany, and Japan. Feedstock ilmenite and rutile draw from Australian and South African mining jurisdictions, exposing processors to export restriction risk. Single-source vulnerability concentrates in chloride-route titanium tetrachloride intermediates. Distribution runs through integrated chemical distributors serving national paint manufacturers with direct mill supply relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calcium carbonate extenders and precipitated silica substitution threats in interior flat coatings demand active formulation defense from incumbent oxide suppliers. Incumbents must navigate technical displacement while reinforcing premium positioning in high-performance exterior applications.
For Market Incumbents: Consolidate chloride-process capacity control through backward integration into titanium tetrachloride intermediates or long-term offtake agreements with Australian rutile miners. Lock in REACH-compliant certification status ahead of ECHA substance evaluation timelines to foreclose regional blender access to premium specification tiers. Prioritize water-based dispersion technology R&D to match MEE enforcement trajectories in Chinese megacity clusters.
For New Entrants and Emerging Players: Differentiate on heritage restoration specialization with earth-tone iron oxide portfolios targeting European conservation architecture specifications. Penetrate the underdeveloped zinc oxide anti-microbial segment through EPA-registered coating partnerships for healthcare and institutional buildings. Pursue direct specification relationships with facade specialists rather than competing for national retailer approved supplier list slots.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across water-based dispersion technology segments as colloid chemistry capabilities become scarcer. Five-to-ten year viability favors integrated producers with captive chloride-route capacity and verified carbon emission profiles. Target acquisition archetype: mid-tier regional compounders with surface-treated oxide formulation expertise but lacking feedstock security. Signal to watch: BIS certification timeline compression in India extending supply qualification protocols and consolidating multinational supplier positions.
| Strategic Initiative | Industry Significance |
|---|---|
| Chloride-Process Capacity Expansion | MEE dual carbon enforcement in China redirects investment toward cleaner production routes with verified emission profiles. |
| Water-Based Dispersion Technology Leadership | Specialized colloid chemistry capabilities capture specification share from solvent-borne systems under tightening VOC regulations. |
| Heritage Restoration Portfolio Development | REACH chromium restrictions create white-space for compliant iron oxide pigments in European conservation architecture. |
| Anti-Microbial Zinc Oxide Registration | EPA-registered coating formulations expand specification access in healthcare and institutional building segments. |
| Backward Integration into Rutile Supply | Australian and South African mining jurisdiction control reduces feedstock concentration risk for integrated processors. |
Research Methodology
A spread of perspectives from plant managers at integrated oxide producers, procurement leads at national coating brands, distribution channel partners, and technical R&D directors converged on the working assumptions. Primary interviews combined with secondary validation against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and ECHA registration databases. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Segmentation dimensions modeled span product chemistry tier, formulation technology type, construction end-use application, and regional production hub concentration across the analysis window. CAGRs derived from historical trajectory analysis and forward-looking regulatory enforcement schedules. Industry-specific forecast inputs incorporate MEE dual carbon implementation timelines and REACH authorization phase-out schedules.
Material uncertainties — regulatory enforcement intensity, feedstock export restriction events, and technical substitution rates in interior coatings — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision as substance restriction lists and process emission standards evolve. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Photochromic Pigments Market
Dyes and Pigments
Asia Pacific Hair Colorants Market
Dyes and Pigments
Europe Pigments Market
Dyes and Pigments
Colorants Market
Dyes and Pigments
South America Hair Colorants Market
Dyes and Pigments
Carmine Market
Dyes and Pigments
High Performance Pigments Market
Dyes and Pigments
Erythrosine Market
Dyes and Pigments
Titanium Dioxide Color Market
Dyes and Pigments
Phthalocyanine Pigments Market
Dyes and Pigments
Quinacridone Pigments Market
Dyes and Pigments
White Pigment Market
Dyes and Pigments
Phycoerythrin Market
Dyes and Pigments
Resin Pigments Market
Dyes and Pigments
Pearl Pigment Market
Dyes and Pigments
Global Cosmetic Pigments Market