
 Pipes and Fittings Market | 2026-2036
Pipes and Fittings Market Size, Share, and Industry Trends Forecast 2026-2036
Pipes and Fittings Market Outlook
Cross-linked polyethylene is rebalancing cost-performance economics in potable water distribution, displacing legacy metal systems in residential and commercial builds. JM Eagle Inc. leverages integrated resin-to-pipe manufacturing across North American facilities. China Lesso Group Holdings anchors its position through massive scale in polymer extrusion for drainage and irrigation networks. Georg Fischer LLC differentiates via precision-engineered piping systems for industrial process applications.
Pipes and fittings constitute engineered conduit assemblies—manufactured from thermoplastics, thermosets, or metal alloys in diameters ranging from fractional inches to several meters—that transport fluids, gases, and slurries under pressure or gravity flow across building, utility, and process infrastructure. HDPE dominates trenchless and underground installation categories due to fusion-welded joint integrity and fatigue resistance. Water supply applications command the largest revenue pool, while irrigation segments in arid climate zones exhibit the fastest volume expansion. PVC sustains mature margins in residential drainage through formulation efficiencies and established distribution channels.
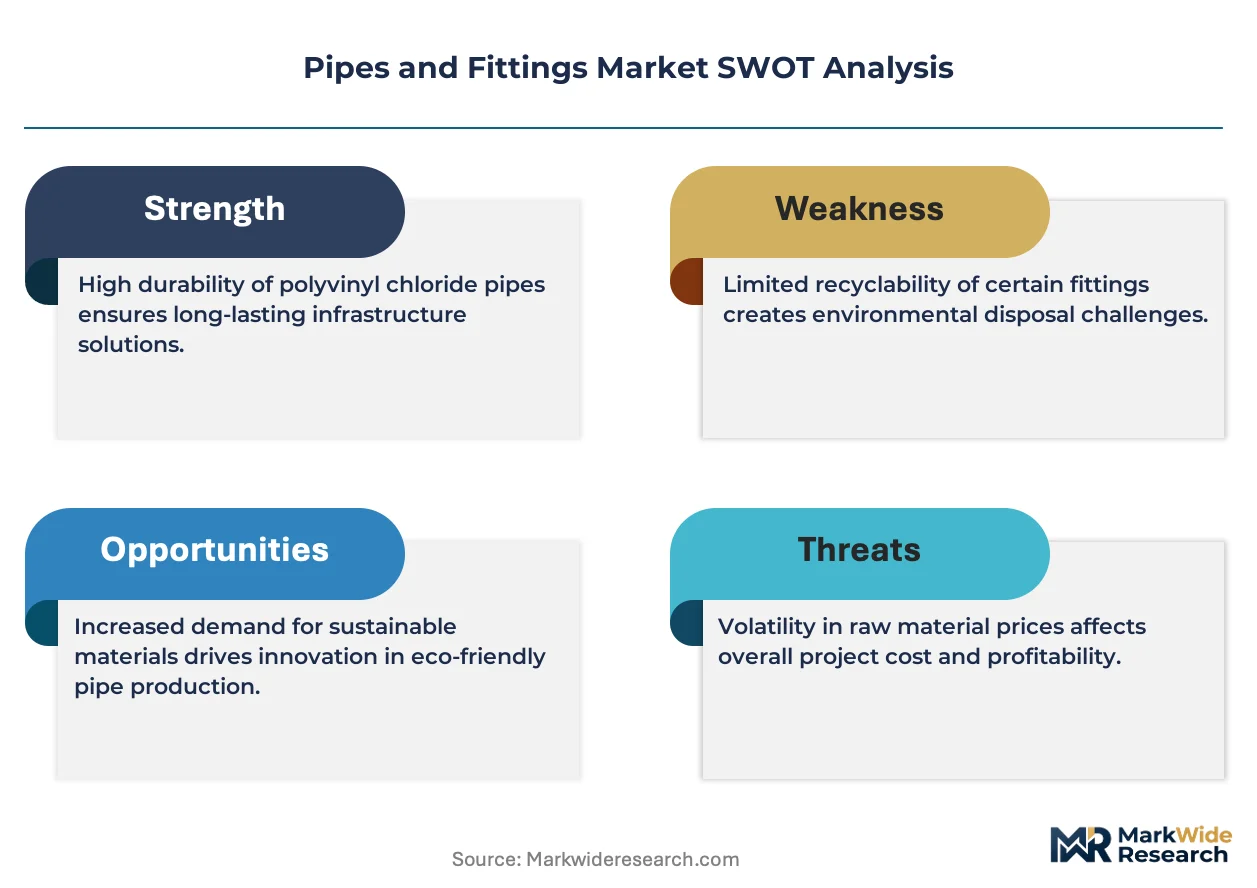
EPA lead-and-copper rules and NSF/ANSI 61 potable water certifications shape material eligibility and product substitution patterns in the United States. India's BIS certification for polymer pipes and China's GB/T standards for pressure-rated systems enforce quality floors that filter subscale suppliers. Stakeholders must monitor regulatory tightening on embedded carbon and chemical migration limits, as compliance costs will redistribute margin pools toward vertically integrated compounders with certified testing laboratories.
Market Dynamics
Cross-linked polyethylene fusion-welding protocols are compressing installation timelines and labor requirements across municipal water infrastructure, forcing incumbent metal-pipe manufacturers to retool extrusion lines or cede residential distribution share to polymer compounders with certified joining systems.
Growth Catalysts
- India's Jal Jeevan Mission:The rural household tap water mandate is accelerating procurement of HDPE distribution networks in Bihar, Uttar Pradesh, and Maharashtra.
- EPA Lead and Copper Rule revisions:Stricter lead action thresholds are disqualifying legacy brass and soldered copper systems from potable water retrofits in older US housing stock.
- Trenchless rehabilitation methods:Cured-in-place pipe lining and horizontal directional drilling are expanding addressable infrastructure without surface excavation disruption.
Market Restraints
- Resin price volatility:Ethylene and propylene feedstock swings compress margin predictability for extrusion-dependent manufacturers.
- Chlorinated PVC substitution limits:Regulatory friction from ECHA REACH restrictions constrains CPVC deployment in European potable applications despite thermal performance advantages.
- Fusion equipment concentration:Specialized electrofusion and butt-fusion machinery supply concentrates among German and Austrian capital equipment producers.
Strategic Opportunities
- Desalination brine conveyance:Saudi Arabia's Red Sea and Persian Gulf plant expansions require corrosion-resistant thermoset piping for high-salinity transport.
- China's dual carbon compliance:Low-emission extrusion incentives favor domestic manufacturers with captive renewable power and electric melting furnaces.
- Smart leak detection integration:Sensor-embedded polymer pipes combining pressure monitoring with acoustic sensing are creating premium product tiers.
Industry Challenges
- Certification timeline compression:NSF/ANSI 61 and WRAS potable water approvals require 18-24 month validation cycles that delay new compound formulations.
- Skilled fusion technician scarcity:Butt-fusion and electrofusion joint integrity depends on certified operators, constraining deployment velocity in remote geographies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pipes and Fittings Market |
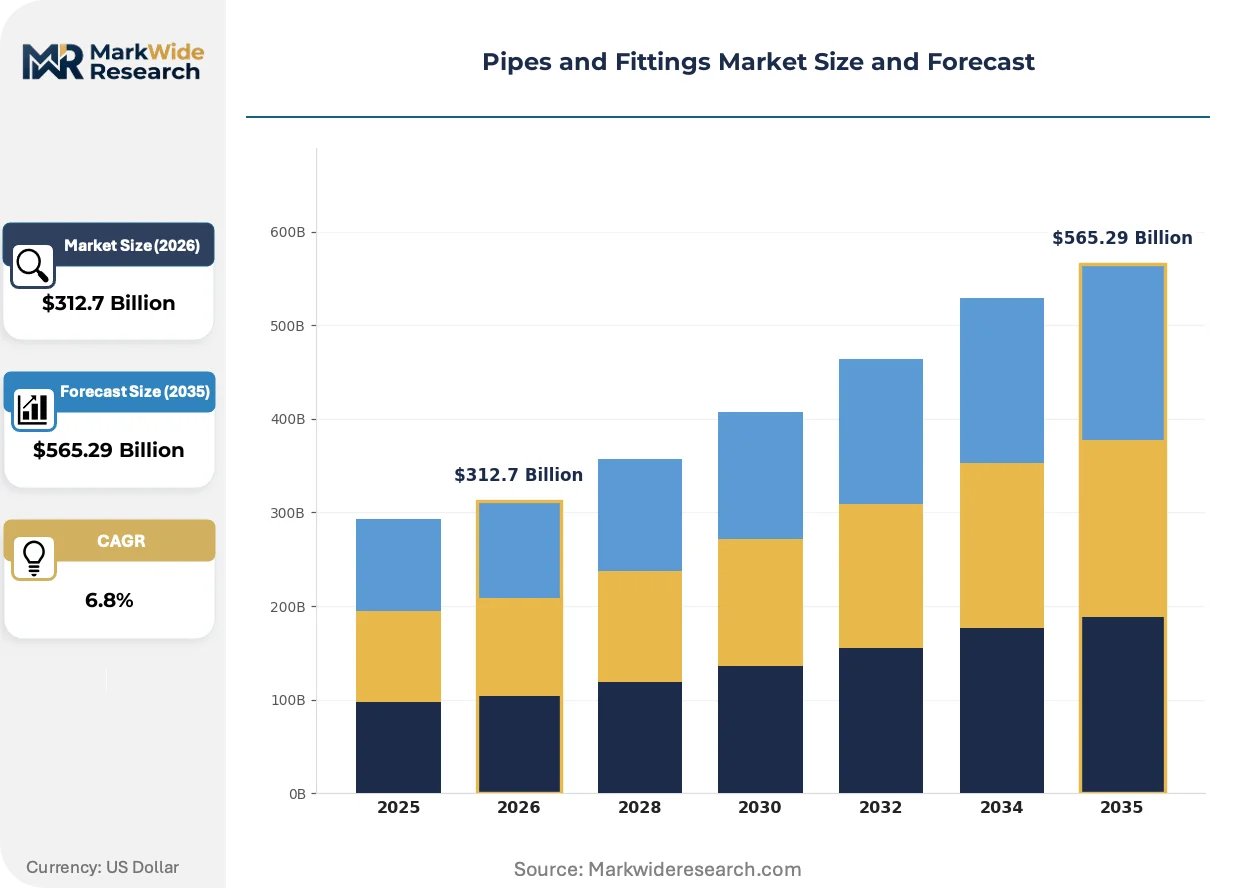
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $565.29 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PVC, CPVC, PEX, HDPE Application: Water Supply, Drainage, HVAC, Irrigation End User: Construction, Industrial, Residential, Commercial Installation Type: Above Ground, Underground, Surface Mounted, Embedded |
| Companies Covered | JM Eagle Inc., Astral Ltd., Advanced Drainage Systems Inc, NIBCO INC., Finolex Industries Ltd., Aliaxis Group SA, China Lesso Group Holdings, Georg Fischer LLC, Charlotte Pipe and Foundry Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pipes and Fittings Market Strategic Shifts
Material science advances and regulatory chemistry restrictions are converging to reshape product roadmaps, with manufacturers racing to validate next-generation compounds before legacy formulations face phased prohibition.
PE-RT (polyethylene of raised temperature resistance) is consolidating specification dominance in underfloor heating and district energy distribution across Northern European residential construction. Specifiers in Germany and Denmark specify PE-RT for its flexibility and oxygen-barrier coextrusion compatibility. The technology is consolidating supply relationships toward compounders with in-house material testing and long-term hydrostatic stress certification.
China's updated GB/T 13663 standards for polyethylene pressure pipes impose stricter long-term hydrostatic strength testing and traceability requirements. Domestic producers must maintain batch records and third-party laboratory validation. Export-oriented manufacturers in Zhejiang and Guangdong provinces are most affected, accelerating investment in automated pressure-testing equipment.
Engineering-procurement-construction firms are consolidating vendor lists and demanding single-source accountability for material supply and installation warranty. Tier-one contractors in Australia's mining and water sectors now specify polymer pipe packages with 25-year performance guarantees. This concentration is visible most acutely in Queensland's coal seam gas gathering systems and Perth's suburban water main renewals.
Pipes and Fittings Market Segmentation
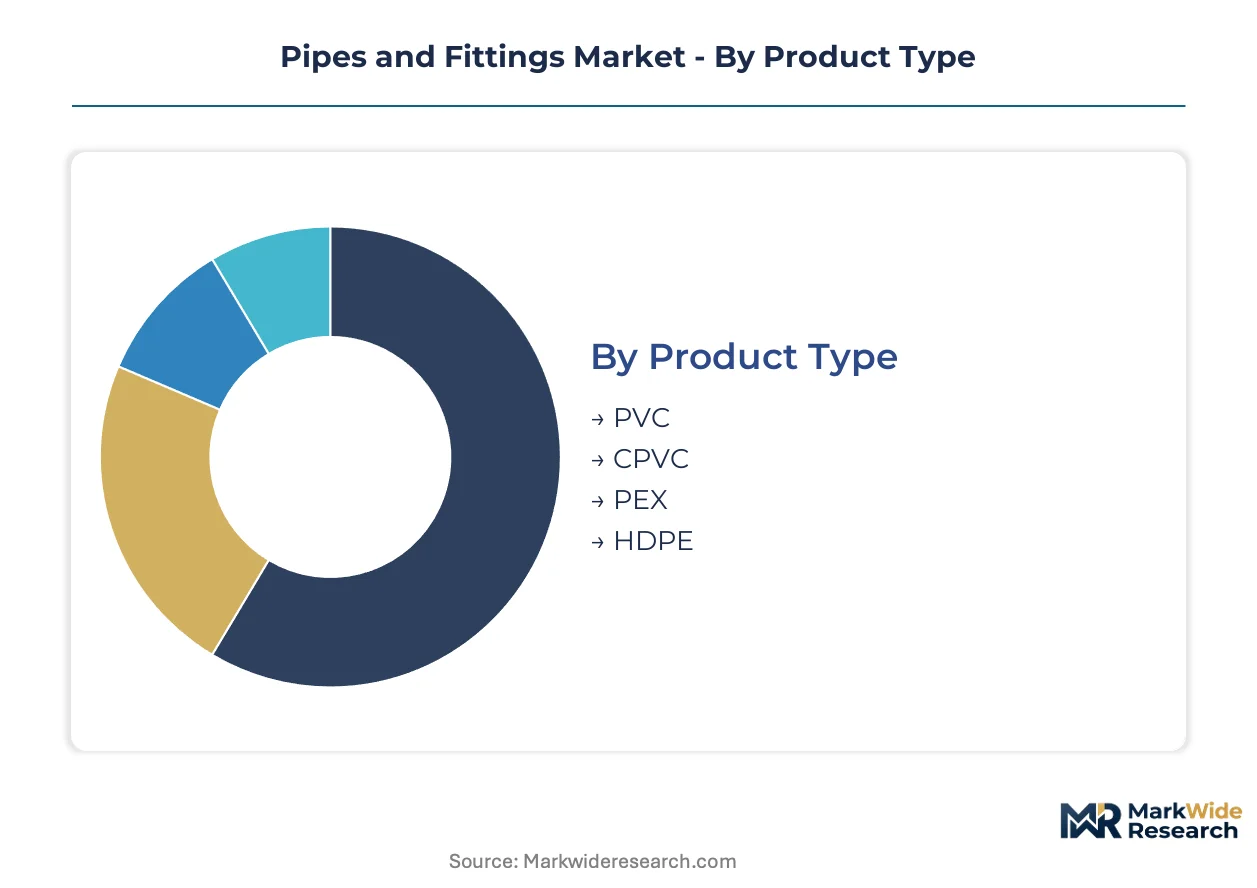
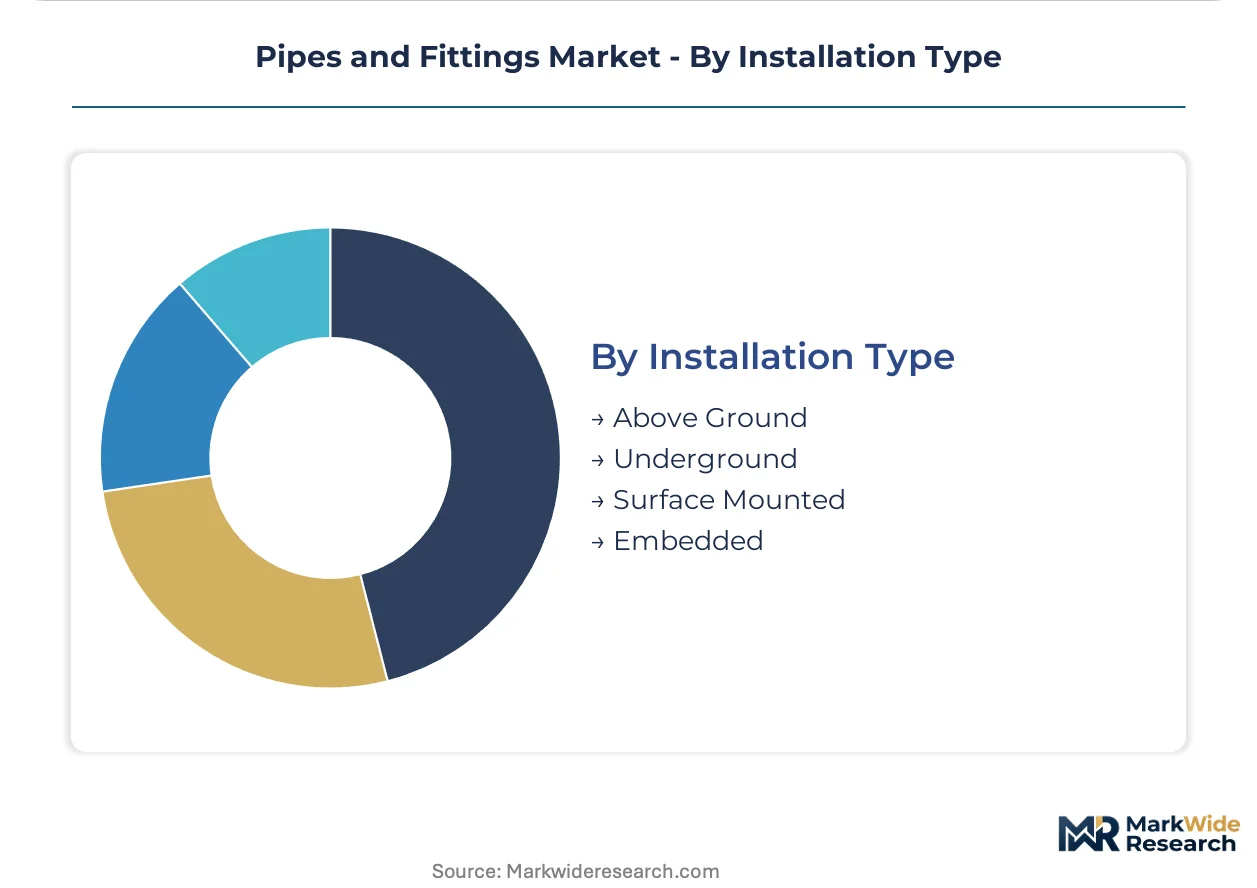
Pipes and fittings segmentation reveals distinct performance profiles across material chemistry, installation environment, and end-use intensity. Material selection drives lifecycle economics, while installation type determines labor skill requirements and project scheduling constraints.
Product Type:
Polymer systems span standalone pressure-rated distribution networks through embedded radiant heating circuits, with fusion requirements and thermal limits dictating integration depth.
- HDPE:Fusion-welded joint integrity enables trenchless installation in municipal water mains and mining slurry transport. India's Jal Jeevan Mission procurement in Bihar and Maharashtra concentrates demand for large-diameter distribution networks. Resin price volatility constrains margin predictability for extrusion-dependent manufacturers.
- PVC:Formulation efficiencies sustain mature margins in residential drainage and non-pressure sanitary systems. Established distribution channels in North American home improvement retail anchor volume concentration. Lead-free stabilization requirements under EPA regulations filter subscale compounders from potable water eligibility.
- PEX:Flexibility and freeze resistance suit residential plumbing retrofits and radiant floor heating circuits. Oxygen-barrier coextrusion variants command specification in European district energy distribution.
- CPVC:Chlorinated formulation extends thermal performance for hot water distribution in commercial buildings. ECHA REACH restrictions constrain deployment in European potable applications despite temperature advantages.
HDPE leads volumes today; PEX is gaining share fastest in residential construction corridors.
Application:
Demand intensity varies by fluid pressure requirements, chemical exposure severity, and regulatory certification burden across building and infrastructure end-uses.
- Water Supply:Pressure-rated systems for potable distribution command the largest revenue pool. NSF/ANSI 61 and WRAS certifications enforce 18-24 month validation cycles for new compound formulations. China's GB/T 13663 standards impose batch traceability requirements that accelerate investment in automated pressure-testing equipment.
- Irrigation:Arid climate zones in Saudi Arabia and Australia's Murray-Darling basin exhibit steepest volume expansion. UV-stabilized HDPE and lay-flat PVC configurations dominate center-pivot and drip-line installations.
- Drainage:Gravity-flow sanitary and stormwater systems prioritize cost efficiency over pressure ratings. PVC sustains specification dominance through established installer familiarity and socket-joint installation speed.
- HVAC:Chilled water distribution and condensate removal require corrosion resistance and thermal expansion accommodation. PE-RT consolidates specification in Northern European underfloor heating through oxygen-barrier compatibility.
Water supply anchors revenue concentration; irrigation climbs fastest in water-stressed geographies.
End User:
Procurement sophistication scales with project scale, from residential owner-specified systems through industrial process engineering mandates.
- Construction:General contractors consolidate vendor lists and demand single-source accountability for material supply and installation warranty. Australia's EPC firms in Queensland coal seam gas and Perth water main renewals specify 25-year performance guarantees.
- Residential:Homeowner-driven replacement cycles favor push-fit and crimp-joint systems that minimize specialized labor requirements. PEX displacement of copper accelerates in older US housing stock subject to EPA lead action thresholds.
- Commercial:Facility managers prioritize lifecycle cost over first-cost in hotel, hospital, and institutional builds. CPVC thermal performance advantages compete against PEX flexibility in high-rise pressure zones.
- Industrial:Process engineers specify precision-engineered systems for chemical resistance and pressure cycling fatigue. Desalination brine conveyance in Saudi Arabia's Red Sea plant expansions requires corrosion-resistant thermoset piping.
Construction channels dominate project value; residential retrofits expand addressable volume most rapidly.
Installation Type:
Surface disruption tolerance and access constraints determine method selection, with buried systems requiring fusion-certified technicians and above-ground installations prioritizing mechanical joint speed.
- Underground:Trenchless rehabilitation via cured-in-place pipe lining and horizontal directional drilling expands addressable infrastructure without excavation disruption. HDPE fusion-welded integrity dominates municipal water main renewals.
- Above Ground:Exposed mechanical and fire suppression systems prioritize UV resistance and thermal expansion accommodation. Support spacing and hanger specifications vary by material stiffness and operating temperature.
- Embedded:Radiant heating and cooling circuits in concrete slabs require oxygen-barrier properties and long-term hydrostatic stress certification. PE-RT specification consolidates toward compounders with in-house material testing.
- Surface Mounted:Retrofit plumbing in existing structures favors flexibility and minimal wall penetration. PEX ring-and-crimp systems reduce installation timeline compared to soldered copper alternatives.
Underground installation commands capital project value; embedded systems expand most quickly in energy-efficient building codes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhejiang and Guangdong provinces anchor polymer pipe manufacturing capacity, with automated pressure-testing investments accelerating under GB/T 13663 traceability mandates. India's Jal Jeevan Mission and Saudi Arabia's desalination expansions are redistributing demand toward water-stressed geographies.
United States
EPA lead-and-copper rule revisions are disqualifying legacy brass systems from potable retrofits in older housing stock. NSF/ANSI 61 certification requirements filter subscale compounders from municipal procurement eligibility. JM Eagle Inc. leverages integrated resin-to-pipe manufacturing across North American facilities serving residential distribution networks.
China
Dual carbon goals and updated GB standards are pushing manufacturers toward low-emission extrusion processes with captive renewable power. MEE enforcement of batch traceability requirements accelerates automated testing equipment adoption. Export-oriented producers in Zhejiang province face the steepest compliance investment curves.
India
Jal Jeevan Mission procurement concentrates in Bihar, Uttar Pradesh, and Maharashtra for rural household tap water distribution. BIS certification for polymer pipes enforces quality floors that filter unqualified suppliers from government tenders. HDPE network deployment dominates municipal modernization corridors.
Germany
PE-RT specification consolidates in Northern European underfloor heating and district energy distribution. ECHA REACH restrictions on chlorinated formulations constrain CPVC deployment despite thermal performance advantages. Precision-engineered piping specialists serve industrial process applications with long-term performance guarantees.
Saudi Arabia
Red Sea and Persian Gulf desalination plant expansions require corrosion-resistant thermoset piping for high-salinity brine conveyance. Arid climate irrigation infrastructure drives UV-stabilized HDPE procurement for center-pivot installations. EPC firms specify 25-year performance warranties for critical process systems.
Pipes and Fittings Market Competitive Environment
Global majors compete with regional champions across manufacturing scale and certification depth, creating tiered procurement access. The vendor base stratifies between integrated resin-to-pipe compounders, specialized industrial fabricators, and regional extrusion specialists serving municipal infrastructure. Three archetypes dominate: scale-driven integrated manufacturers, precision-engineered industrial specialists, and emerging-market cost optimizers. Competitive moves concentrate on backward integration into resin supply and geographic expansion through EPC partnership anchoring.
Within the scale-driven tier, JM Eagle Inc. and China Lesso Group Holdings exemplify integrated manufacturing archetypes spanning resin compounding through finished pipe distribution. Georg Fischer LLC occupies a precision-engineered position serving industrial process applications with certified joining systems. Astral Ltd. and Finolex Industries Ltd. represent India-focused specialists capturing Jal Jeevan Mission procurement through BIS-certified product ranges.
| Leading Market Players |
|---|
| JM Eagle Inc. |
| Astral Ltd. |
| Advanced Drainage Systems Inc |
| NIBCO INC. |
| Finolex Industries Ltd. |
| Aliaxis Group SA |
| China Lesso Group Holdings |
| Georg Fischer LLC |
| Charlotte Pipe and Foundry Co. |
| Others |
Value Chain & Pricing Dynamics
China's dual carbon goals and updated GB standards gate qualified supply access and premium-tier pricing power, filtering subscale extruders from government procurement eligibility while rewarding domestic manufacturers with captive renewable power and certified testing laboratories.
Pricing Analysis
Ethylene and propylene feedstock volatility passes through to finished pipe pricing with variable lag, compressing margin predictability for extrusion-dependent manufacturers. Three-tier pricing structure across premium certified, standard compliant, and economy unbranded levels separates NSF/ANSI 61 validated systems from basic drainage grades. Cost compression in standard grades is intensifying because resin price swings and certification timeline burdens redistribute margin pools toward vertically integrated compounders. Municipal procurement officers exhibit lowest price sensitivity due to lifecycle cost mandates, while residential contractors in emerging markets remain most cost-responsive.
Supply Chain Analysis
NSF/ANSI 61 and WRAS certification requirements gate supply chain participation, enforcing 18-24 month validation cycles that filter unqualified compounders from potable water eligibility. Manufacturing concentrates in China, India, and Germany, with Zhejiang and Guangdong provinces anchoring polymer extrusion capacity. Raw material supply draws from ethylene crackers, PVC resin producers, and additive compounders. Single-source vulnerability concentrates in specialized electrofusion and butt-fusion machinery from German and Austrian capital equipment producers. Distribution runs through EPC contractor vendor lists and established building materials wholesalers serving municipal infrastructure and residential construction channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Pipes and Fittings Market represents a late-cycle quality story as procurement shifts toward certified fusion-welded systems with 25-year performance guarantees in Australia's mining and water sectors.
For Market Incumbents: Deploy backward integration into resin compounding to defend margin position against feedstock volatility and emerging-market cost optimizers. JM Eagle Inc. and China Lesso Group Holdings exemplify this lever through captive resin supply. Incumbents must accelerate automated pressure-testing equipment investment to meet China's GB/T 13663 traceability mandates before export-oriented producers in Zhejiang face disqualification. For New Entrants and Emerging Players: Capture white-space in smart leak detection integration, where sensor-embedded polymer pipes combining pressure monitoring with acoustic sensing create premium product tiers underserved by legacy extruders. India's Jal Jeevan Mission rural distribution networks offer penetrable volume, with BIS certification as the essential go-to-market credential for government tender eligibility. For Investors and Strategic Acquirers: Roll-up economics work for regional extrusion specialists with certified testing laboratories because certification timeline compression and skilled fusion technician scarcity create durable moats against unqualified competition. Target compounders with in-house material testing and long-term hydrostatic stress certification. The signal to watch is EPA lead-and-copper rule enforcement intensity accelerating copper displacement in older US housing stock.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive ethylene and propylene sourcing shields JM Eagle from feedstock volatility compressing extrusion margins. |
| Automated Pressure-Testing Equipment Deployment | GB/T 13663 traceability mandates in China filter export-oriented producers lacking batch record capabilities. |
| Smart Sensor-Embedded Pipe Development | Pressure monitoring and acoustic sensing integration creates premium tiers for Australia's 25-year warranty specifications. |
| Certified Fusion Technician Training Programs | Electrofusion and butt-fusion joint integrity constraints limit deployment velocity in remote geographies. |
| Desalination Brine Conveyance System Qualification | Saudi Arabia's Red Sea plant expansions require corrosion-resistant thermoset piping validated for high-salinity transport. |
Study Parameters
Multiple input streams — executive interviews with polymer pipe manufacturers, procurement officers at EPC contractors, and regulatory compliance specialists — were reconciled against secondary validation from EPA enforcement records, BIS certification databases, and customs trade data. Plant managers at extrusion facilities, municipal water authority engineers, and distribution channel partners provided operational perspective. Bottom-up volume modeling and top-down market sizing were triangulated to constrain estimate variance.
Data-stream reconciliation across product type, application intensity, end-user procurement sophistication, and installation environment dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories and value-per-unit assumptions. Forecast inputs incorporated resin price elasticity, certification timeline distributions, and infrastructure spend correlations from water-stressed geographies.
Resin price volatility, regulatory tightening on embedded carbon, and fusion equipment supply concentration are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about certification adoption rates and infrastructure procurement continuity. A model refresh is warranted upon material change in EPA lead-and-copper rule enforcement thresholds or China's dual carbon compliance acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Hydrogen Tube Skids Market
Pipes and Tubes
Spain PVC Pipes Market
Pipes and Tubes
Acid Resistant Pipe Market
Pipes and Tubes
Europe Line Pipe Market
Pipes and Tubes
Multiflex Tubes Market
Pipes and Tubes
Qatar PVC Pipe Market
Pipes and Tubes
Collapsible Metal Tubes Market
Pipes and Tubes
Oman PVC Pipes Market
Pipes and Tubes
Saudi Arabia PPR Pipes Market
Pipes and Tubes
China Industrial Hoses Market
Pipes and Tubes
Carbon Steel Pipe Fittings Market
Pipes and Tubes
HDPE Corrugated Pipe Market
Pipes and Tubes
US Cold Drawn Seamless Steel Pipes Market
Pipes and Tubes
Stainless Steel Welded Pipes Market
Pipes and Tubes
Coiled Tubing Manufacturing Market
Pipes and Tubes
Global Tracer Wires Market