
 Metal Pipe Market | 2026-2036
Metal Pipe Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Pipe Market Intelligence
The scarcity of certified high-pressure welders is reorganizing project execution timelines for energy and chemical processing infrastructure. Tenaris leverages its specialized production of seamless pipes for high-specification oil and gas applications. ArcelorMittal competes on its vast global production scale and diversified product portfolio, serving multiple end-user segments from construction to automotive. China Baowu Steel Group anchors a significant portion of the carbon steel pipe supply chain.
Metal pipes are hollow cylindrical sections, typically manufactured through processes like electric resistance welding or seamless extrusion from materials such as carbon steel or copper. They primarily serve to transport fluids, gases, and slurries or provide structural support in construction and industrial applications. Carbon steel pipes constitute the largest material segment due to their cost-effectiveness, while stainless steel offers superior corrosion resistance for chemical processing. Within applications, oil & gas transportation remains a high-value segment, though water supply systems represent a larger volume base.
Product specifications are governed by standards from organizations like the American Petroleum Institute (API) for oil and gas applications and CE marking requirements in Europe. In the United States, EPA regulations on drinking water quality influence material choices, such as the preference for copper or specially coated steel pipes. Navigating the complex interplay between material cost volatility and evolving regional environmental mandates will be critical for manufacturers' long-term profitability.
Market Dynamics
The market's momentum is defined by large-scale infrastructure projects, especially in water and energy, running against the critical constraint of specialized labor. A widespread scarcity of certified high-pressure welders is directly impacting project timelines and cost structures for major installations.
Growth Catalysts
- Jal Jeevan Mission:India's national initiative to provide household tap water connections is driving massive procurement of steel and ductile iron pipes by municipal utilities, creating a significant volume base.
- Energy Infrastructure Modernization:Upgrades to aging oil and gas pipeline networks in North America and the Middle East, aimed at improving safety and efficiency, sustain demand for high-specification seamless and welded pipes.
- Advanced Alloy Development:The introduction of new corrosion-resistant alloys extends pipe lifecycles in harsh chemical processing and marine environments, justifying premium pricing and opening new performance-driven application segments.
Market Restraints
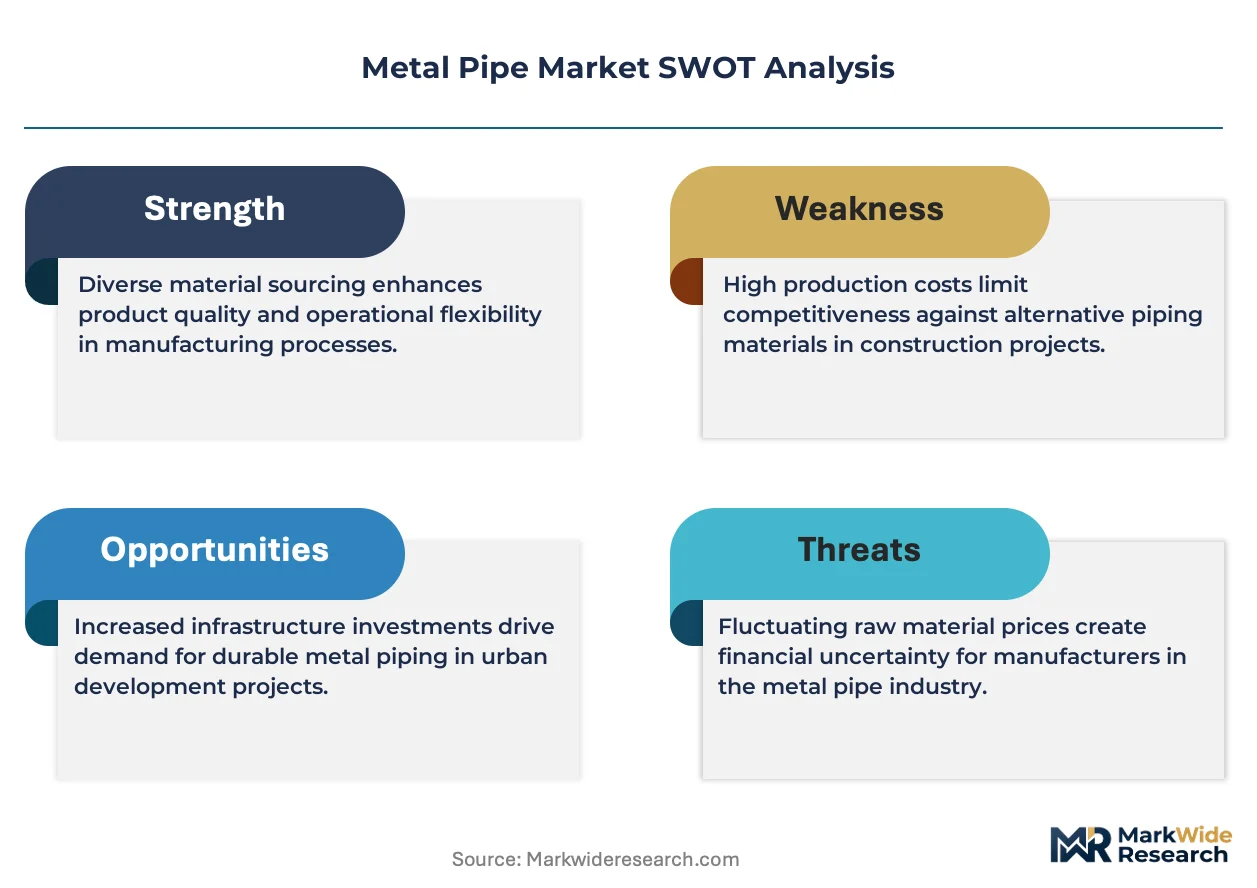
- Raw Material Volatility:Fluctuations in the prices of key inputs like steel coil, copper, and nickel create significant margin pressure and complicate long-term project bidding for pipe manufacturers.
- Polymer Pipe Encroachment:In low-pressure, small-diameter applications like residential plumbing and irrigation, high-density polyethylene (HDPE) and PVC pipes present a lower-cost, corrosion-free alternative to traditional metal pipes.
- Logistical Complexity:Transporting large-diameter, heavy-wall pipes over long distances is capital-intensive and logistically challenging, adding substantial costs and lead time, particularly for remote project sites.
Strategic Opportunities
- Hydrogen Transport Networks:The build-out of infrastructure for hydrogen production, storage, and transport creates a new high-value segment for specialized steel alloy pipes capable of resisting hydrogen embrittlement.
- Sub-Saharan African Water Systems:Underdeveloped water and sanitation infrastructure across many Sub-Saharan African nations represents a long-term growth frontier for basic carbon steel and ductile iron pipes as development projects accelerate.
- Digital Twin Services:Offering integrated sensor technology and digital twin modeling for pipeline integrity monitoring allows manufacturers to move into higher-margin, service-based recurring revenue streams beyond the initial product sale.
Industry Challenges
- Welder and Fitter Scarcity:A persistent shortage of welders certified for high-pressure and exotic alloy applications delays project execution in the energy and chemical sectors, creating bottlenecks for EPC contractors.
- Navigating Divergent Standards:Manufacturers selling to a global customer base must manage a complex matrix of certifications, including API for oil and gas, CE marking in Europe, and specific national water quality standards from regulators like the US EPA.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Pipe Market |
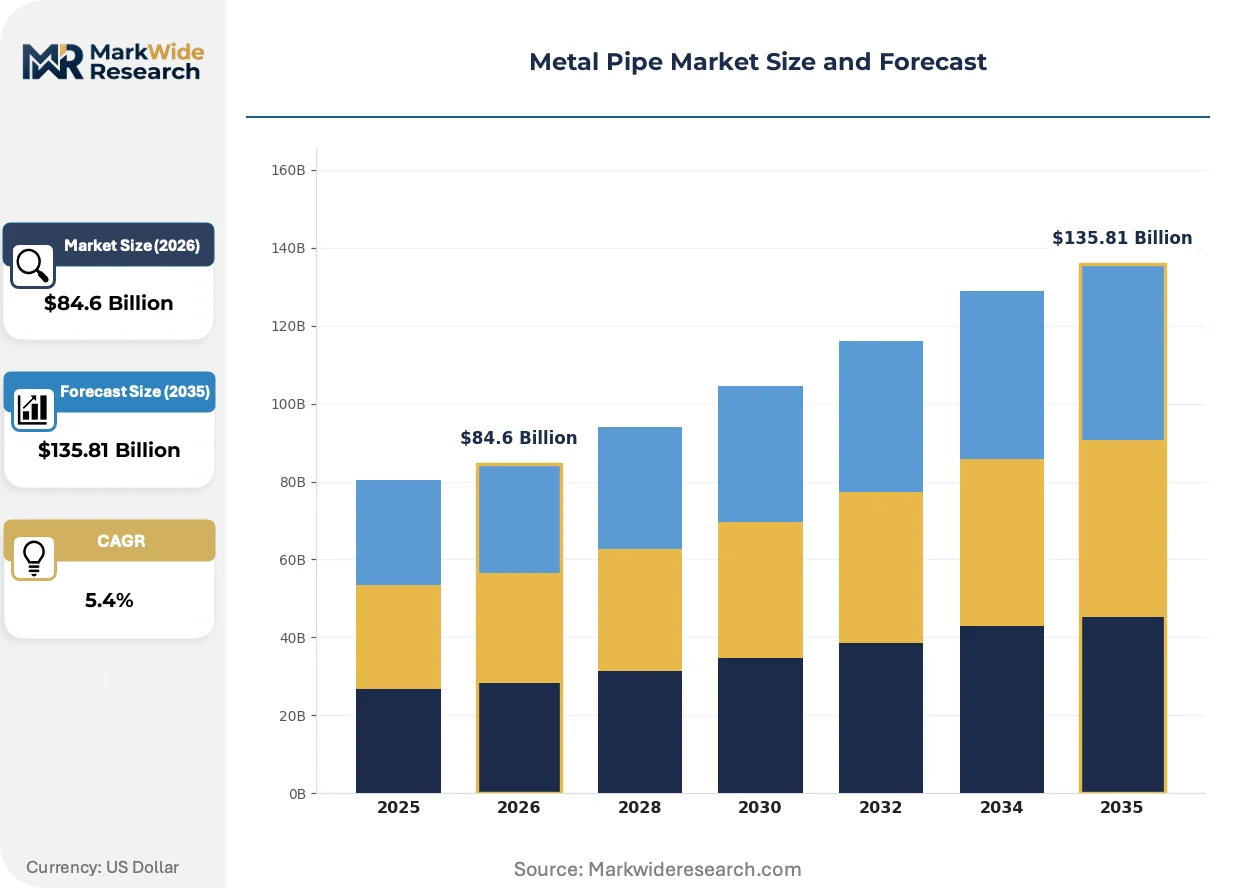
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $135.81 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Carbon Steel, Stainless Steel, Copper, Aluminum, Alloy Steel, Brass Application: Oil & Gas Transportation, Water Supply Systems, HVAC Systems, Structural Support, Chemical Processing, Power Generation End User: Energy Companies, Construction Firms, Chemical Manufacturers, Utilities Providers, Infrastructure Developers, Transportation Agencies Coating Type: Galvanized, Epoxy, Polyethylene, Zinc, Bituminous, Fusion Bonded Epoxy |
| Companies Covered | Nippon Steel Corporation, Jiangsu Changbao Steel Tube, ArcelorMittal, China Baowu Steel Group, United States Steel Corporation, Tenaris, Tata Steel, TMK Group, Vallourec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Pipe Market Strategic Shifts & Innovations
Material science advancements and digital integration are transforming metal pipes from passive conduits into intelligent infrastructure components. This evolution prioritizes lifecycle performance, data generation, and operational efficiency over simple material transport, fundamentally altering product value propositions.
Advanced Material Integration and Smart Pipes
Embedded sensor technology provides real-time data on flow, pressure, and corrosion within pipelines. Industrial and municipal operators are adopting this technology to enable predictive maintenance and leak detection. This integration of electronics into the pipe wall is miniaturizing the monitoring apparatus from external clamps to non-intrusive, embedded systems.
Carbon-Focused Regulatory Frameworks
The European Union's Carbon Border Adjustment Mechanism (CBAM) imposes levies on imported carbon-intensive goods, including steel products. This regulation directly impacts the cost competitiveness of steel pipes imported from regions with less stringent emissions standards. Consequently, manufacturers exporting to the EU are forced to document and potentially pay for their carbon footprint.
Lifecycle Procurement Models
Project owners in the energy sector are increasingly bundling pipe procurement with long-term integrity management and maintenance services. This shift moves away from transactional, component-level purchasing toward lifecycle partnerships with manufacturers or specialized service firms. The trend is most prominent in deepwater oil and gas projects where operational reliability is paramount.
Metal Pipe Market Segmentation
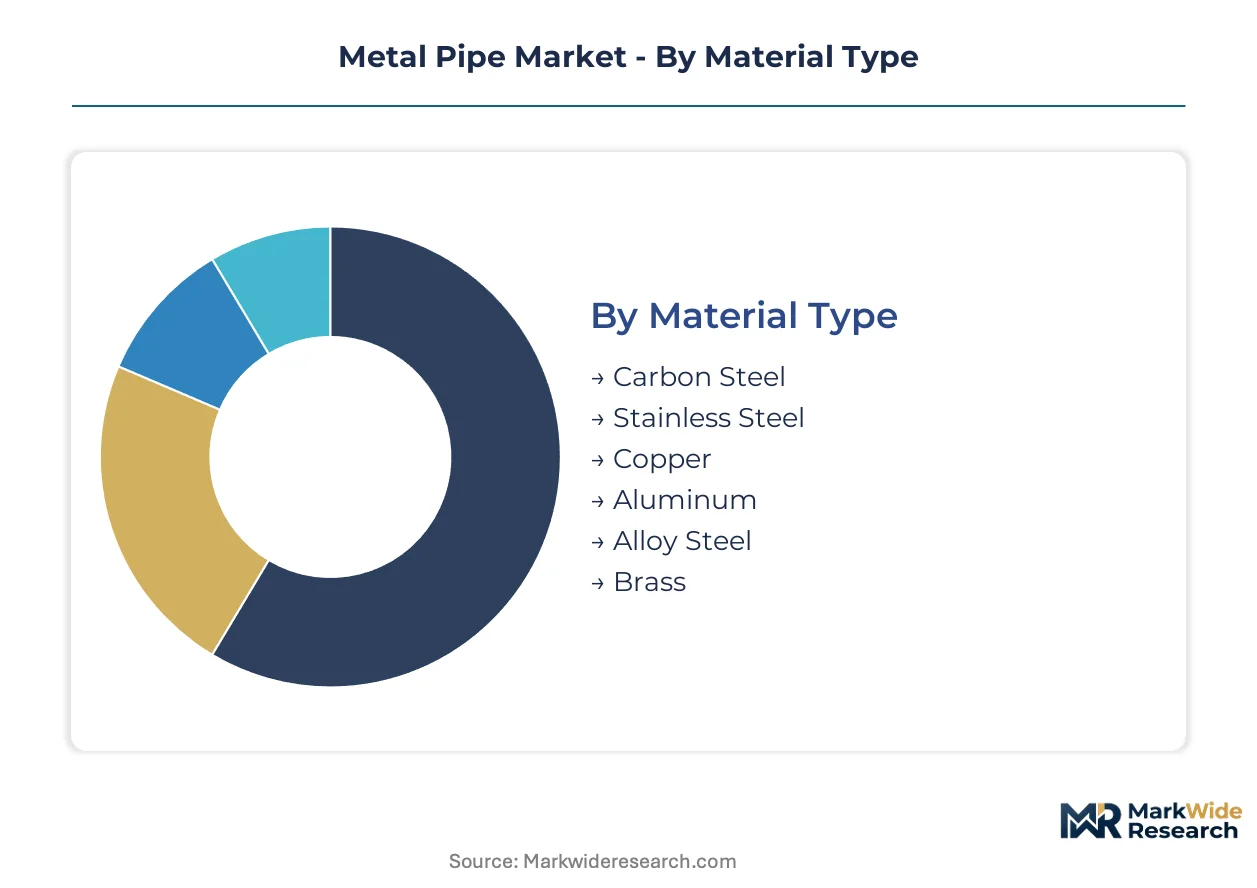
The Metal Pipe Market exhibits a complex segmentation driven by diverse material requirements, application-specific performance needs, and end-user demands across various industries. Understanding these distinct segments is critical for manufacturers to align product development and market strategies effectively.
Material Type:
The geographic distribution of material preferences for metal pipes often reflects regional resource availability and specific infrastructure demands.
- Carbon Steel:These pipes constitute the largest material segment due to their cost-effectiveness and versatility in structural support and general fluid transport. Demand concentrates significantly in India, where government-led projects like the Jal Jeevan Mission stimulate procurement by utilities providers.
- Stainless Steel:Valued for superior corrosion resistance and high strength, stainless steel pipes are critical in chemical processing and harsh marine environments. The development of advanced corrosion-resistant alloys enhances product lifecycle and performance in these demanding applications.
- Copper:Preferred for drinking water systems and plumbing due to its antimicrobial properties and corrosion resistance. EPA regulations in the United States often influence material choices for potable water infrastructure.
- Aluminum:Known for its lightweight properties and corrosion resistance, aluminum pipes find niche applications in aerospace, automotive, and specific HVAC systems.
- Alloy Steel:These pipes incorporate additional elements to enhance strength, toughness, and resistance to specific environmental conditions. They are essential for high-pressure oil and gas applications and power generation facilities.
- Brass:An alloy of copper and zinc, brass pipes are used in plumbing fixtures, decorative applications, and specialized industrial components requiring specific malleability.
Carbon Steel commands the established base. The steepest expansion runs through Stainless Steel.
Application:
The varied applications for metal pipes reflect distinct operational requirements and customer procurement patterns.
- Oil & Gas Transportation:This high-value segment demands specialized seamless and welded pipes capable of withstanding extreme pressures and corrosive media. Upgrades to aging oil and gas pipeline networks in North America sustain this demand for high-specification products.
- Water Supply Systems:Representing a larger volume base, these systems require pipes for municipal infrastructure, including potable water distribution and wastewater collection. India's Jal Jeevan Mission drives massive procurement of steel and ductile iron pipes for household tap water connections.
- HVAC Systems:Metal pipes are integral for conveying refrigerants, chilled water, and hot water in heating, ventilation, and air conditioning installations. Commercial and industrial building projects drive consistent demand for these systems.
- Structural Support:Hollow cylindrical sections provide essential load-bearing capabilities in construction, infrastructure, and industrial frameworks. Construction firms utilize these pipes extensively for foundational integrity.
- Chemical Processing:Requires pipes with superior corrosion resistance and specific material compositions to safely transport aggressive chemicals. Advanced alloy development directly benefits this demanding application segment.
- Power Generation:Utilizes metal pipes for steam lines, cooling water systems, and fuel transport in thermal, nuclear, and hydroelectric power plants.
Water supply systems drive significant volume, while oil and gas transportation commands premium value.
End User:
End-user segments exhibit varying procurement complexities and project scales, influencing pipe specifications and supplier relationships.
- Energy Companies:These entities procure high-specification pipes for oil and gas exploration, production, and refining, prioritizing reliability and advanced alloys for harsh environments. The scarcity of certified high-pressure welders directly impacts project timelines for these companies.
- Utilities Providers:Drive large-volume demand for water and wastewater infrastructure, notably through government-backed initiatives like India's Jal Jeevan Mission. These providers focus on durability and cost-effectiveness for extensive networks.
- Construction Firms:Utilize metal pipes for structural elements, plumbing, and HVAC systems within residential, commercial, and industrial building projects. These firms often prioritize cost-effectiveness and readily available materials.
- Chemical Manufacturers:Require specialized corrosion-resistant pipes for their process lines, demanding materials that can withstand aggressive chemical media and high temperatures. Material science advancements are crucial for this sector.
- Infrastructure Developers:Focus on large-scale public works projects such as bridges, tunnels, and transportation networks, which demand robust and long-lasting pipe solutions for drainage and structural components.
- Transportation Agencies:Procure pipes for drainage systems, culverts, and structural elements within road, rail, and port infrastructure projects.
Utilities providers ensure a stable volume base, while energy companies drive innovation in high-performance materials.
Coating Type:
The selection of pipe coating types is dictated by environmental exposure and specific performance requirements, particularly for corrosion protection.
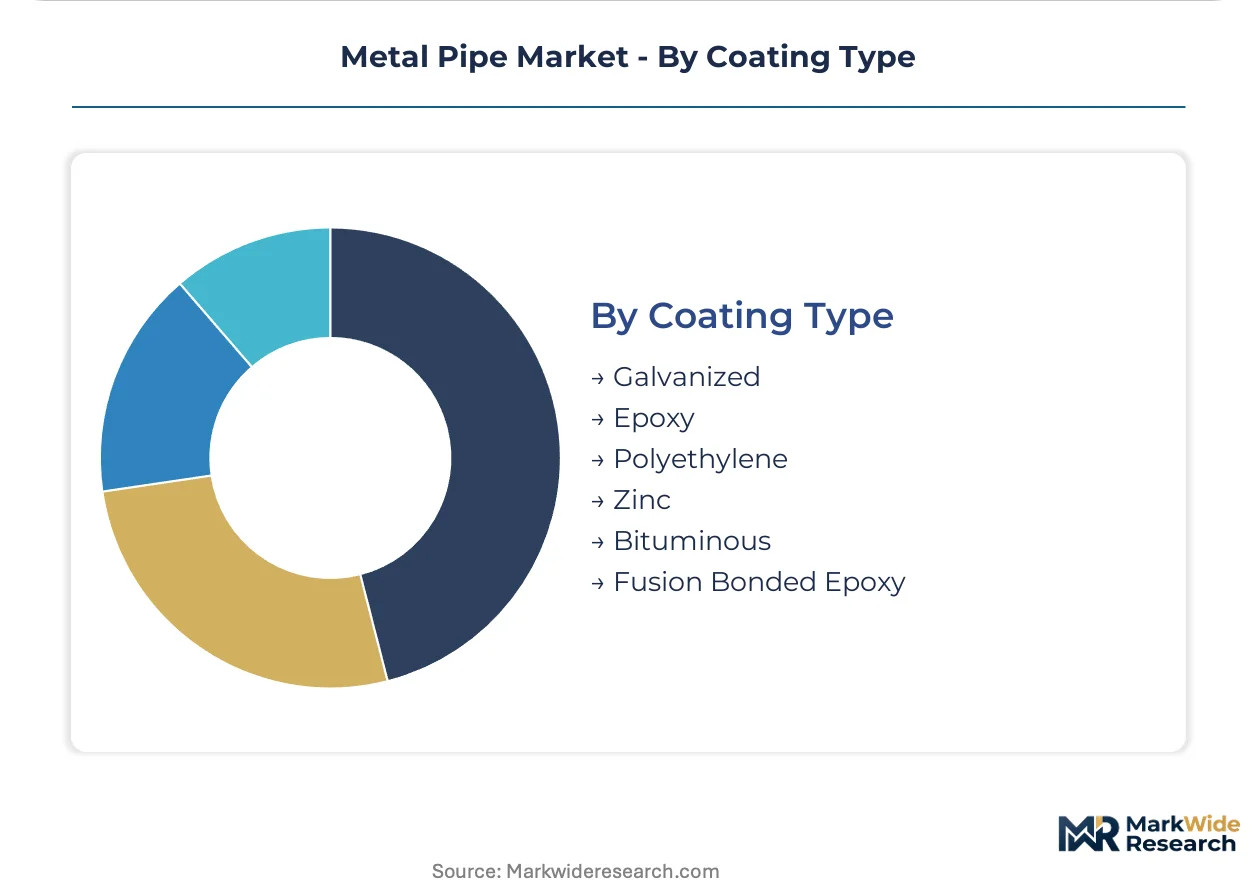
- Galvanized:This coating involves applying a protective zinc layer to steel pipes, primarily used for corrosion resistance in general construction and water systems. Demand is widespread across municipal infrastructure projects requiring durable, cost-effective protection.
- Fusion Bonded Epoxy:A thermosetting epoxy powder coating applied to steel pipes, offering excellent corrosion protection for oil and gas pipelines. This coating enhances product lifecycle and performance in harsh underground and marine environments.
- Epoxy:Provides a durable, corrosion-resistant layer for both internal and external pipe surfaces, suitable for water and wastewater applications. This coating extends the operational life of pipes in various environments.
- Polyethylene:Offers good chemical resistance and flexibility, commonly used as an external coating for buried pipes in water, gas, and sewage distribution networks.
- Zinc:Applied as a sacrificial layer to prevent rust on steel, often used as a base coat in multi-layer protection systems for enhanced durability.
- Bituminous:A tar-based coating providing basic corrosion and abrasion protection, frequently applied to buried pipes in less aggressive soil conditions.
Galvanized coatings offer standard protection, while Fusion Bonded Epoxy addresses specialized high-performance needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's government-led initiatives significantly influence material choices and procurement patterns for metal pipes across various applications. The market exhibits distinct regional dynamics, driven by infrastructure development, energy projects, and environmental regulations. Specific national policies and local industrial concentrations shape demand for different material types and product specifications.
India
The Jal Jeevan Mission, a national initiative, drives massive procurement of steel and ductile iron pipes by municipal utilities. India's Bureau of Indian Standards (BIS) sets quality benchmarks for these materials, ensuring product reliability. Utilities providers nationwide are experiencing heightened demand for water infrastructure components.
United States
Upgrades to aging oil and gas pipeline networks sustain demand for high-specification seamless and welded pipes. The Environmental Protection Agency (EPA) regulations on drinking water quality influence material choices for potable water infrastructure. The Gulf Coast region, with its extensive energy infrastructure, remains a significant hub for pipe procurement.
China
China Baowu Steel Group anchors a significant portion of the carbon steel pipe supply chain, supporting vast construction and industrial applications. China's GB standards dictate product specifications for steel pipes used in infrastructure and manufacturing. Industrial hubs like the Yangtze River Delta concentrate demand for diverse metal pipe solutions.
Germany
Advanced alloy development for chemical processing and power generation facilities fuels demand for specialized metal pipes. CE marking requirements ensure product compliance for pipes sold across the European Union. The Ruhr Valley region, a traditional center for heavy industry, continues to drive demand for high-performance steel products.
Saudi Arabia
Energy infrastructure modernization and new oil and gas projects create substantial demand for high-pressure alloy steel pipes. Saudi Aramco's stringent standards govern material and operational requirements for pipelines. The Eastern Province, home to major oil and gas production facilities, is a key procurement center.
Metal Pipe Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the metal pipe market, creating a tiered competitive structure. The market is characterized by a mix of vertically integrated steel producers and specialized pipe manufacturers. Competitive moves often involve portfolio diversification into higher-value alloys or strategic partnerships for large-scale infrastructure projects.
Integrated steel giants, such as ArcelorMittal, leverage their vast global production scale and diversified product portfolios, serving multiple end-user segments from construction to automotive. China Baowu Steel Group anchors a significant portion of the carbon steel pipe supply chain, demonstrating immense volume capability. Conversely, Tenaris exemplifies a specialist approach, focusing its specialized production on seamless pipes for high-specification oil and gas applications, where performance and reliability are paramount.
| Leading Market Players |
|---|
| Nippon Steel Corporation |
| Jiangsu Changbao Steel Tube |
| ArcelorMittal |
| China Baowu Steel Group |
| United States Steel Corporation |
| Tenaris |
| Tata Steel |
| TMK Group |
| Vallourec |
| Others |
Cost & Logistics Intelligence
Manufacturing scale economies directly shape the supply concentration within the metal pipe market, influencing price floors for standard products. This structural dynamic affects how raw material cost fluctuations are absorbed or passed through to various end-user segments.
Pricing Analysis
Geographic price spreads for metal pipes reflect regional manufacturing costs and specific certification requirements. Contract-based long-term offtake agreements define pricing for large infrastructure projects, while transactional per-unit pricing applies to smaller construction volumes. Price differentiation stems from quality grades, specific certifications like API for oil and gas, and geographic delivery costs. Pricing softness currently affects commodity-grade carbon steel pipes due to raw material volatility. Utilities providers exhibit higher price sensitivity for large-volume procurement, whereas energy companies prioritize performance and reliability for specialized alloy pipes.
Supply Chain Analysis
Inbound logistics costs, particularly for large-diameter, heavy-wall pipes, add significant expense to the metal pipe supply chain. Supply concentration centers in China, India, and the United States, where major steel producers operate. The supply chain draws heavily from raw materials such as steel coil, copper, and nickel. Raw material price volatility represents a significant structural risk, complicating long-term project bidding. Distribution for high-specification pipes often involves direct sales channels to energy companies, while construction firms source through regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The metal pipe market is entering a cyclical recovery, driven by renewed global infrastructure spending on water systems and energy modernization projects.
For Market Incumbents: Secure long-term raw material contracts to mitigate price volatility, a persistent threat to margins. Invest in advanced alloy research and development for hydrogen transport networks to counter polymer pipe encroachment in traditional segments. Pursue strategic partnerships with EPC contractors to ensure consistent demand for high-specification products.
For New Entrants and Emerging Players: Certification fast-track programs for new materials, such as specialized alloys for hydrogen applications, represent a significant opportunity. Target underdeveloped water and sanitation infrastructure in Sub-Saharan African nations, a penetrable segment for basic carbon steel pipes. Offer integrated digital twin services alongside product sales as a differentiated go-to-market angle.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialists in advanced alloys and digital integration services. Long-term viability hinges on companies capable of navigating evolving environmental mandates and specialized labor shortages. The increasing adoption of embedded sensor technology in pipes is a specific signal to watch as an inflection indicator for future growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Alloy R&D | Enhances pipe performance in harsh environments and opens new segments like hydrogen transport. |
| Digital Twin Service Integration | Creates recurring revenue streams and improves pipeline integrity monitoring for operators. |
| Long-term Raw Material Offtake | Stabilizes input costs, protecting manufacturer margins against commodity price volatility. |
| Capacity Expansion in India | Addresses massive procurement demand from government-led initiatives like the Jal Jeevan Mission. |
| Specialized Welder Training Programs | Mitigates project execution delays caused by the persistent scarcity of certified high-pressure welders. |
Research Approach
The analysis maps key metal pipe sub-sectors, each validated through extensive primary interviews with industry stakeholders. These included utilities procurement managers, energy project engineers, construction firm purchasing agents, and material science R&D directors. Secondary data sources, such as industry association reports, government infrastructure spending reports, company financial filings, and trade publications, provided further context. Bottom-up and top-down triangulation methods ensured data consistency and accuracy.
Outputs were validated against external benchmarks to ensure the analytical framework's consistency over the projection horizon. The modeling period incorporated segmentation dimensions including material type, application, end-user, coating type, and regional infrastructure spend. Compound Annual Growth Rates were derived from historical trends and projected future demand drivers, informed by planned pipeline projects and municipal water infrastructure budgets.
Decision-makers should treat outputs as directional under current geopolitical stability and raw material supply chain assumptions; material deviation would warrant model refresh. Specific risk factors, including unforeseen technological disruptions or sudden shifts in environmental regulations, could revise forecasts. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Carbon Steel Pipe Fittings Market
Pipes and Tubes
Stainless Steel Plumbing Pipes Market
Pipes and Tubes
HDPE Corrugated Pipe Market
Pipes and Tubes
Aluminium Tubes for OPC Drum Market
Pipes and Tubes
Glass Reinforced Plastic (GRP) Piping Market
Pipes and Tubes
Chlorinated Polyvinyl Chloride (Cpvc) Pipes Market
Pipes and Tubes
Steel Pipes and Tubes Market
Pipes and Tubes
Global Butt Weld Fittings Market
Pipes and Tubes
France PVC Pipes Market
Pipes and Tubes
ESR Tubes Market
Pipes and Tubes
Global Fiberglass Pipe Market
Pipes and Tubes
Global PEX (Cross-Linked Polyethylene) Market
Pipes and Tubes
Europe Pipe Market
Pipes and Tubes
Weld Overlay Process Clad Pipes Market
Pipes and Tubes
Duplex Stainless Steel Pipe Market
Pipes and Tubes
Industrial Blast Hoses Market