
 FRP Pipes and Tanks Market | 2026-2036
FRP Pipes and Tanks Market Size, Share, and Industry Trends Forecast 2026-2036
FRP Pipes and Tanks Market Foresight
India is rewriting capacity assumptions for FRP pipe manufacturing as domestic composites clusters scale filament winding output for water infrastructure. Future Pipe Industries leverages regional distribution networks across the Middle East and Southeast Asia. Ershigs anchors its position through deep specialization in corrosion-resistant tank systems for chemical processing. National Oilwell Varco dominates offshore oil and gas applications with high-pressure FRP riser technology.
Fiber-reinforced polymer pipes and tanks are cylindrical pressure vessels and conduits manufactured from thermosetting resin matrices reinforced with glass, carbon, or aramid fibers, typically produced via filament winding or resin transfer molding to achieve strength-to-weight ratios exceeding steel by four to six times. These structures primarily transport corrosive fluids, store chemicals, and protect fire suppression water supplies in environments where metallic corrosion would compromise system integrity. Filament winding commands the technology segment through its automation compatibility and repeatable mechanical properties in high-volume pipe production. Water treatment leads application demand as municipal agencies replace aging ductile iron with zero-corrosion FRP distribution networks. Chemical processing sustains premium pricing for dual-laminate and vinyl ester tank constructions requiring NSF and ASTM certification.
EPA corrosion protection mandates and NSF/ANSI 61 drinking water standards shape North American product specifications, while India's BIS certification requirements for composite pressure vessels govern import eligibility and domestic manufacturer licensing. REACH chemical compliance in Europe restricts certain styrene-based resin formulations, redirecting formulation R&D toward bio-based vinyl ester alternatives. Stakeholders must monitor evolving potable water contact regulations and filament winding automation economics to time capacity investments against municipal infrastructure replacement cycles.
Market Dynamics
Filament winding automation is compressing unit economics for FRP pipe manufacturers while EPA corrosion mandates accelerate municipal replacement cycles for aging metallic infrastructure.
Growth Catalysts
- EPA Corrosion Protection Mandates:US municipal water utilities face accelerated replacement deadlines for deteriorating ductile iron networks, directing capital toward zero-corrosion FRP distribution systems.
- India's Industrial Corridor Buildout:Central government infrastructure spending concentrates demand for chemical-resistant storage and transport systems across Gujarat, Maharashtra, and Tamil Nadu manufacturing hubs.
- Automated Filament Winding:Robotics integration in pipe production lines reduces labor content and improves laminate consistency for high-volume municipal contracts.
Market Restraints
- Styrene Resin Volatility:Unsaturated polyester feedstock costs fluctuate with crude oil derivatives, compressing margins for standard-grade pipe manufacturers without vinyl ester upgrade paths.
- European REACH Compliance:ECHA restrictions on certain styrene-based formulations force reformulation R&D toward bio-based alternatives, extending product certification timelines.
- Steel Price Arbitrage:Temporary metallic commodity softness in select Asian markets revives competitive pressure for non-corrosive applications where FRP penetration remains incomplete.
Strategic Opportunities
- Desalination Infrastructure Expansion:Saudi Arabia and UAE coastal utilities require large-diameter FRP intake and outfall systems resistant to saltwater corrosion and biofouling.
- Fire Suppression Water Storage:California and Texas building codes increasingly mandate corrosion-resistant tank systems for high-rise and industrial facility sprinkler reserves.
- Digital Twin Integration:IoT sensor embedding in filament-wound pressure vessels enables predictive maintenance contracts for chemical processing operators.
Industry Challenges
- Filament Winding Technician Shortage:Specialized laminate programming and robotics calibration skills lag automation deployment, constraining capacity expansion at mid-tier fabricators.
- NSF/ANSI 61 Certification Backlogs:Potable water contact approvals face extended laboratory queue times, delaying product launches for municipal bidding windows.
- Legacy Steel System Integration:FRP flange standards and metallic adapter compatibility create field installation complexity during brownfield retrofit projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | FRP Pipes and Tanks Market |
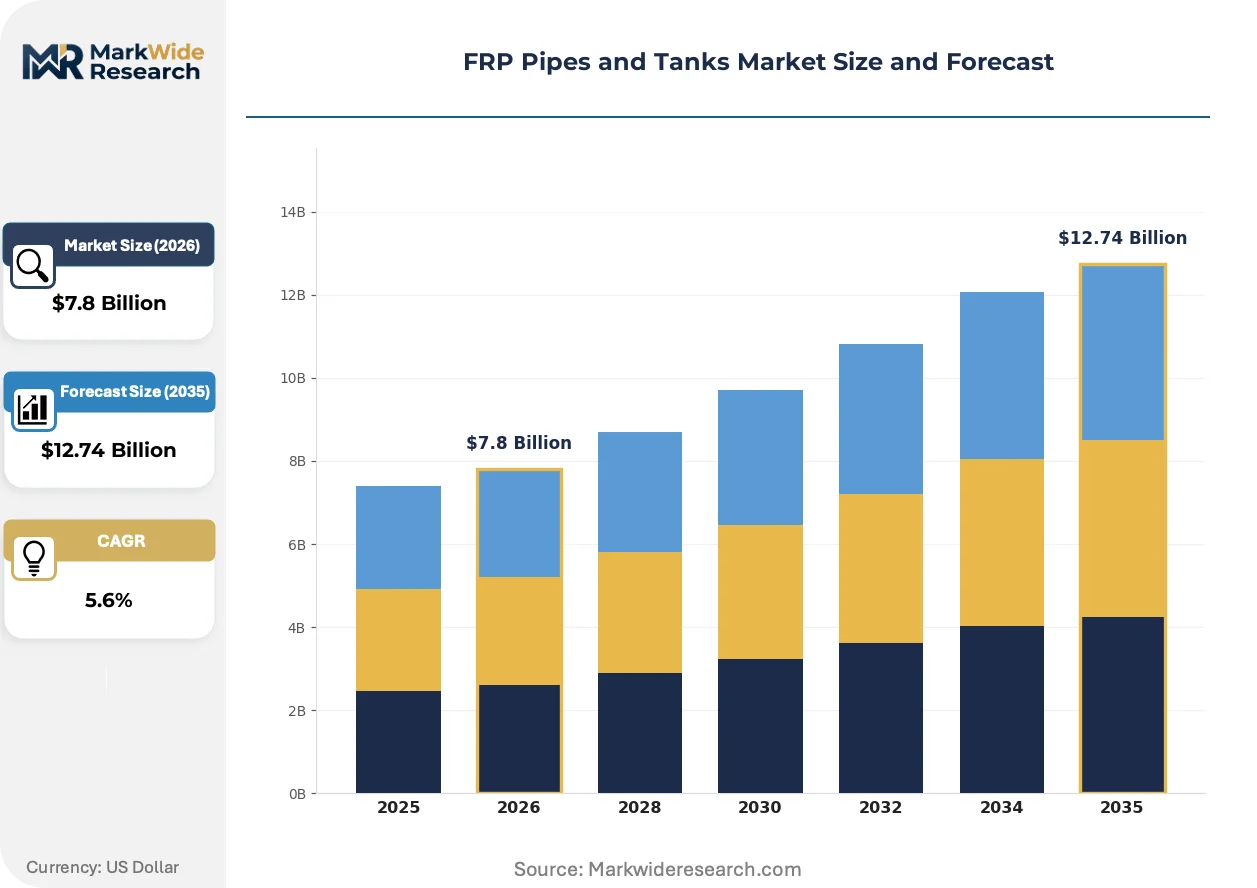
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.74 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sections, Coils, Pipes, Tanks, Fittings Technology: Filament Winding, Hand Layup, Spray Up, Pultrusion, Resin Transfer Molding Application: Water Treatment, Chemical Processing, Agriculture Irrigation, Oil & Gas, Fire Protection End User Industry: Municipal Corporations, Energy Providers, Agricultural Sector, Fire Services |
| Companies Covered | Enduro Composites, HOBAS Pipe USA, Future Pipe Industries, Lianyungang Zhongfu Lianzhong Composites Group Co., Ltd., Fibrex Corporation, National Oilwell Varco, Ershigs, Hengrun Group Co., Ltd., Amiantit Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
FRP Pipes and Tanks Market Shifts & Advancements
Digital manufacturing integration and regulatory chemistry restrictions are rewiring how FRP fabricators compete on speed, certification breadth, and resin formulation differentiation.
Real-time quality monitoring via embedded fiber optic sensors is digitizing filament winding operations. Large-diameter pipe producers in Germany and Japan deploy continuous strain measurement during cure cycles, reducing laminate defect rates and warranty exposure. The technology is digitizing quality assurance workflows that previously relied on destructive batch testing.
REACH chemical compliance in Europe restricts traditional styrene-based resin systems. ECHA regulatory pressure forces reformulation toward bio-derived vinyl ester chemistries, elevating R&D spend for export-oriented manufacturers. German and Dutch compounders now lead pilot production of lignin-modified thermosets targeting potable water certification.
Buyers increasingly unbundle installation from equipment supply in municipal water contracts. Engineering-procurement-construction firms now self-perform FRP field jointing, compressing margins for traditional turnkey vendors. Texas and Florida utilities most aggressively drive this disaggregation, separating tank and pipe procurement from civil works bidding.
FRP Pipes and Tanks Market Segmentation
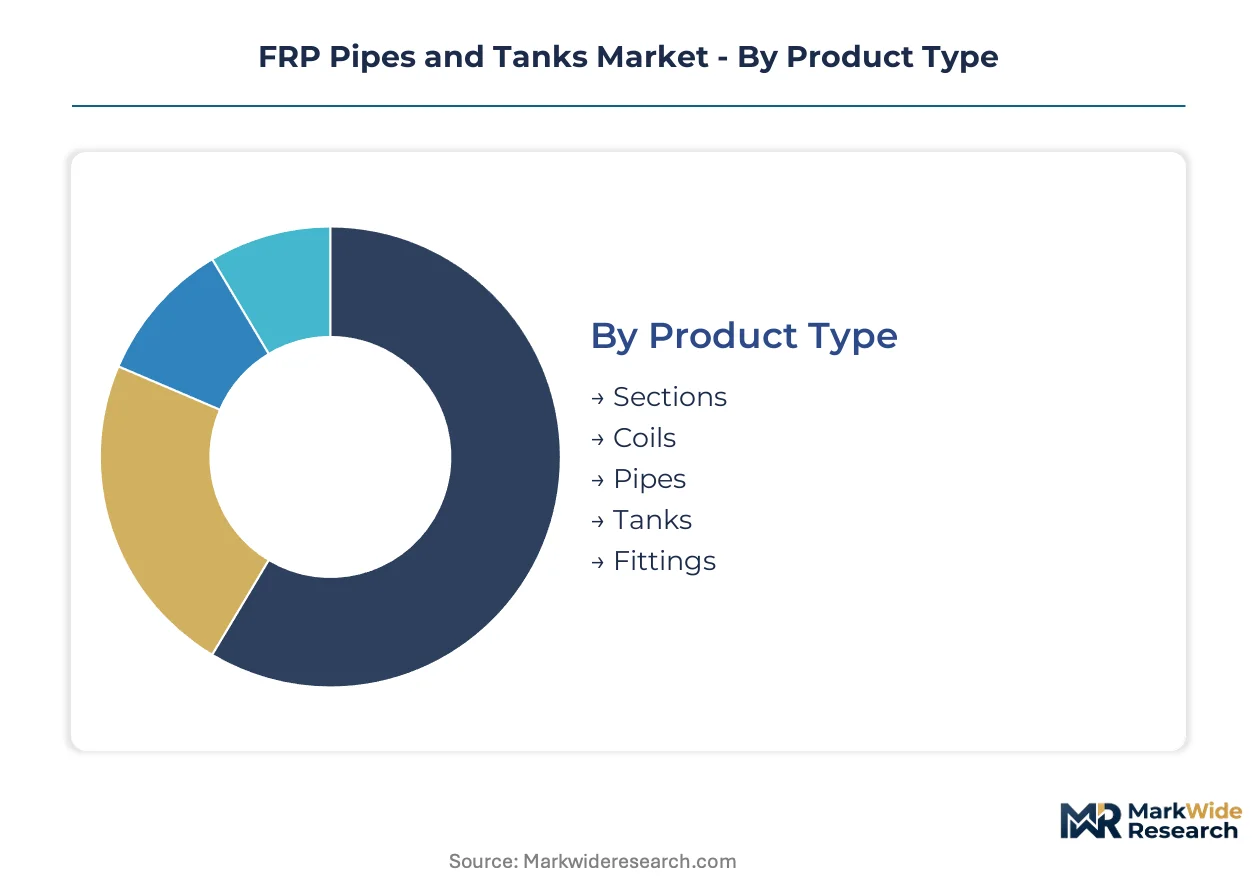
FRP pipe and tank procurement splits across four dimensions: product geometry, manufacturing process, fluid handling application, and institutional buyer type. Each segmentation layer reveals distinct margin structures, certification requirements, and automation investment thresholds that shape supplier positioning.
Product Type:
Product geometry spans five configurations from structural sections to precision fittings, each demanding different filament winding tooling and resin formulation strategies.
- Pipes:Cylindrical pressure vessels manufactured via continuous filament winding achieve consistent wall thickness for municipal water distribution. Demand concentrates in India's industrial corridor projects where BIS-certified pressure ratings govern procurement eligibility.
- Tanks:Vertical and horizontal storage vessels employ dual-laminate construction with corrosion-resistant liners for chemical containment. Chemical processing operators in Gujarat and Maharashtra specify vinyl ester interiors for acid storage applications.
- Sections:Structural profiles and channel configurations serve architectural and industrial framing applications requiring high strength-to-weight ratios.
- Coils:Continuous wound pipe delivered in transportable lengths reduces field jointing for remote agricultural and temporary industrial installations.
- Fittings:Elbows, tees, and flanges enable system connectivity between FRP and metallic pipeline segments, with molded and fabricated variants serving different pressure classes.
Established volume favors pipes; emerging adoption favors tanks.
Technology:
Manufacturing methods range from manual processes to fully automated systems, with capital intensity and output consistency determining competitive fit.
- Filament Winding:Automated fiber placement around rotating mandrels produces repeatable laminate structures for high-volume pipe contracts. Robotics integration in German and Japanese production lines compresses labor content while improving mechanical property consistency.
- Hand Layup:Manual resin and mat placement serves low-volume custom tank fabrication and complex fitting geometries where automation tooling proves uneconomical.
- Spray Up:Chopper gun deposition of resin and chopped roving enables rapid coverage of large mold surfaces for tank shells and structural panels.
- Pultrusion:Continuous pulling of resin-impregnated fiber through heated dies produces uniform structural sections and grating with tight dimensional tolerances.
- Resin Transfer Molding:Closed-mold injection of catalyzed resin achieves high surface finish quality for complex fittings and fire-rated components requiring precise flame retardant loading.
Filament winding commands municipal scale; hand layup retains custom tank margins.
Application:
Fluid handling environments impose distinct chemical resistance, pressure, and regulatory requirements that drive resin selection and laminate design.
- Water Treatment:Potable water distribution and wastewater conveyance systems specify NSF/ANSI 61 certified formulations. EPA corrosion protection mandates accelerate replacement of deteriorating ductile iron networks in US municipalities.
- Chemical Processing:Acid, caustic, and solvent containment demands dual-laminate construction with corrosion barriers. Saudi Aramco and UAE petrochemical operators specify high-pressure FRP for saltwater and hydrocarbon service.
- Agriculture Irrigation:Large-diameter low-pressure conduits transport irrigation water across extended distances, with coil formats reducing installation labor in remote field conditions.
- Oil & Gas:Offshore risers, flowlines, and storage systems require high-pressure ratings and fire resistance for platform and subsea installations.
- Fire Protection:Corrosion-resistant water storage tanks serve sprinkler system reserves, with California and Texas building codes mandating FRP for high-rise and industrial facility compliance.
Water treatment anchors procurement volume; fire protection exhibits steepest expansion trajectory.
End User Industry:
Buyer institutions range from municipal agencies to specialized service providers, each with distinct procurement protocols and technical specification authority.
- Municipal Corporations:City and regional water utilities issue large-diameter pipe contracts through competitive bidding, with NSF certification and automated winding quality records determining award eligibility. Texas and Florida agencies increasingly unbundle installation from equipment supply.
- Energy Providers:Power generation and oil field operators specify high-pressure FRP for cooling water, fire suppression, and hydrocarbon handling systems.
- Agricultural Sector:Irrigation districts and large farming operations prioritize coil-format delivery and field jointing simplicity over precision pressure ratings.
- Fire Services:Building code enforcement authorities and facility safety managers mandate corrosion-resistant tank systems for sprinkler reserve compliance in commercial and industrial construction.
Municipal contracts concentrate procurement scale; fire services drive specification tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Filament winding capacity clusters in Germany, the United States, India, Saudi Arabia, and Japan, with each geography deploying distinct regulatory frameworks and industrial strategies to capture municipal and chemical processing demand.
United States
EPA corrosion protection mandates accelerate ductile iron replacement in municipal water networks across Texas and Florida utilities. NSF/ANSI 61 drinking water standards govern potable water contact certification eligibility for FRP pipe suppliers. Houston-Gulf Coast petrochemical corridors sustain demand for high-pressure riser systems in offshore oil and gas applications.
Germany
ECHA REACH restrictions on styrene-based resin formulations redirect R&D investment toward lignin-modified bio-based vinyl ester alternatives. Continuous strain measurement via fiber optic sensors digitizes quality assurance in large-diameter pipe production lines. Bavarian and North Rhine-Westphalian composites clusters pilot automated filament winding for export-oriented municipal contracts.
India
BIS certification requirements for composite pressure vessels govern import eligibility and domestic manufacturer licensing across Gujarat and Maharashtra industrial corridors. Central government infrastructure spending concentrates demand for chemical-resistant storage systems in Tamil Nadu manufacturing hubs. Domestic composites clusters scale filament winding output for water infrastructure replacement cycles.
Saudi Arabia
Coastal desalination utilities require large-diameter FRP intake and outfall systems resistant to saltwater corrosion and biofouling in Red Sea and Arabian Gulf installations. SFDA and national water authority procurement protocols shape product specifications for potable water contact applications. Eastern Province petrochemical operators specify high-pressure FRP for hydrocarbon and saltwater service.
Japan
METI industrial standards and JIS certification frameworks govern pressure vessel design and manufacturing quality for domestic and export markets. Real-time quality monitoring systems in German-Japanese production partnerships reduce laminate defect rates through embedded sensor integration. Nagoya-Chubu manufacturing belts maintain precision filament winding capabilities for chemical processing and semiconductor facility applications.
FRP Pipes and Tanks Market Competitive Landscape
Integrated multinationals and specialized regional fabricators split the market across technology tiers, with automation scale and corrosion-resistant formulation expertise determining contract eligibility for municipal and industrial buyers. Market structure concentrates around three archetypes: filament winding automation leaders capturing high-volume water infrastructure awards, dual-laminate specialists commanding premium chemical processing margins, and regional distributors leveraging proximity to Middle East and Southeast Asian project sites. Competitive dynamics center on capacity expansion in Indian industrial corridors and strategic partnerships for desalination intake system deployment.
Among automation-scale specialists, National Oilwell Varco and Ershigs occupy distinct positions within the competitive hierarchy, with the former exemplifying offshore oil and gas application focus and the latter representing deep specialization in corrosion-resistant tank systems. Future Pipe Industries anchors regional distribution capabilities across Middle East and Southeast Asian markets. Chinese fabricators including Lianyungang Zhongfu Lianzhong Composites Group Co., Ltd. and Hengrun Group Co., Ltd. represent scale-driven production archetypes serving domestic infrastructure buildout and export contract manufacturing.
| Leading Market Players |
|---|
| Enduro Composites |
| HOBAS Pipe USA |
| Future Pipe Industries |
| Lianyungang Zhongfu Lianzhong Composites Group Co., Ltd. |
| Fibrex Corporation |
| National Oilwell Varco |
| Ershigs |
| Hengrun Group Co., Ltd. |
| Amiantit Group |
| Others |
Supply & Pricing Matrix
Filament winding equipment manufacturers in Germany and Japan anchor upstream concentration, directing margin capture toward automated pipe producers serving municipal water contracts while squeezing hand-layup tank fabricators dependent on manual labor inputs.
Pricing Analysis
EPA corrosion protection mandates and NSF/ANSI 61 certification requirements dictate the pricing tier structure across the FRP pipe and tank market. Three-tier pricing structure across premium, standard, and economy levels separates vinyl ester dual-laminate chemical tanks from polyester municipal water pipes and unsaturated polyester commodity fittings. Price differentiation hinges on certification grade and resin formulation sophistication, with vinyl ester systems commanding substantial premiums over standard polyester alternatives. Municipal corporations in Texas and Florida exhibit highest price sensitivity as they unbundle installation from equipment supply, while chemical processing operators in Gujarat and Saudi Arabia show lowest sensitivity due to corrosion failure costs. Cost compression in standard-grade pipe tiers is intensifying because of styrene resin volatility and crude oil derivative fluctuations.
Supply Chain Analysis
Contract manufacturing capacity concentrates among German-Japanese filament winding partnerships and Indian domestic composites clusters scaling automated output for water infrastructure. Raw material supply draws from Saudi Arabian and UAE petrochemical feedstocks for vinyl ester resins, Chinese glass fiber roving production, and European lignin-modified bio-based alternatives under REACH compliance. Single-source vulnerability characterizes specialized corrosion-resistant liner formulations from concentrated chemical compounders in Germany and the Netherlands. Distribution runs through regional distributors like Future Pipe Industries across Middle East and Southeast Asian project sites, with engineering-procurement-construction firms increasingly self-performing field jointing to compress traditional turnkey margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Municipal water utility procurement consolidation across Texas and Florida is shifting buyer power toward unbundled equipment-only contracts, fragmenting traditional turnkey vendor relationships and compressing margins for integrated suppliers.
For Market Incumbents: Entrench automation scale advantages through filament winding robotics integration in Indian industrial corridors, defending against Chinese fabricators leveraging cost-positioned export manufacturing. Deepen vinyl ester formulation expertise and dual-laminate construction capabilities to maintain premium positioning in chemical processing segments where corrosion resistance failure costs deter price competition. Prioritize NSF/ANSI 61 certification breadth to secure municipal bidding eligibility as EPA replacement deadlines accelerate.
For New Entrants and Emerging Players: Pursue fire suppression water storage specialization in California and Texas building code compliance markets, where corrosion-resistant tank mandates are tightening fastest and incumbent penetration remains incomplete. Target desalination intake and outfall system deployment across Saudi Arabian and UAE coastal utilities, leveraging regional project proximity and saltwater corrosion expertise gaps among established suppliers. Anchor go-to-market strategy through EPC partnership channels rather than direct municipal bidding.
For Investors and Strategic Acquirers: Capital is best deployed toward automation-scale specialists with filament winding robotics integration and established municipal water certification records, as these capabilities concentrate procurement eligibility for EPA-mandated replacement cycles. Long-term viability over the analysis window favors suppliers with backward integration into resin formulation and geographic diversification across Indian, Middle Eastern, and North American demand clusters. The signal to watch is BIS certification timeline compression in India, which would accelerate domestic manufacturer licensing and reshape import-competitive dynamics.
| Strategic Initiative | Industry Significance |
|---|---|
| Filament Winding Automation Scale-Up | Robotics integration in Indian and German production lines compresses labor content for municipal volume contracts. |
| Bio-Based Vinyl Ester Formulation | REACH-compliant lignin-modified thermosets from Dutch and German compounders redirect R&D investment away from restricted styrene systems. |
| Desalination Infrastructure Partnership | Large-diameter intake and outfall system deployment across Saudi Aramco and UAE coastal utilities anchors premium project pipelines. |
| Digital Twin Sensor Integration | Embedded fiber optic strain monitoring in Japanese-German production partnerships reduces laminate defect rates and warranty exposure. |
| Fire Suppression Tank Certification | California and Texas building code mandates for corrosion-resistant sprinkler reserves open specification-tightening growth corridors. |
Research Methodology
A standing panel of filament winding equipment engineers, municipal water utility procurement directors, chemical processing plant maintenance managers, and EPC project developers provided ongoing calibration across primary fieldwork and secondary validation. Primary interviews captured automation economics, certification timeline constraints, and brownfield retrofit installation complexity from stakeholders in Germany, India, Saudi Arabia, Japan, and the United States. Secondary sources included EPA corrosion protection mandate documentation, BIS certification requirements for composite pressure vessels, ECHA REACH restriction updates, NSF/ANSI 61 laboratory testing protocols, and customs trade data for glass fiber and resin feedstock flows. Bottom-up triangulation across product-type volume estimates and top-down validation against end-use industry capital expenditure patterns anchored forecast integrity.
Scenario bracketing around EPA replacement deadline acceleration, Indian industrial corridor spending trajectories, and REACH chemical compliance evolution shaped projection ranges across the modeling period. Segmentation dimensions modeled include product geometry, manufacturing process technology, fluid handling application, and institutional buyer type, with resin formulation grade and certification status as cross-cutting modifiers. CAGRs derived from volume trajectory analysis against historical infrastructure replacement cycles and filament winding capacity expansion announcements. Industry-specific forecast inputs incorporated municipal bidding window timing, desalination project development pipelines, and petrochemical operator maintenance schedules.
Sensitivities concentrate around EPA mandate enforcement variability, styrene resin price volatility, and BIS certification queue backlogs affecting Indian market entry timing. Forecasts reflect assumptions regarding filament winding automation adoption rates and REACH regulatory timeline adherence without chemical restriction expansion. Quarterly review of municipal procurement announcement flows, ECHA regulatory consultation outcomes, and Indian infrastructure budget allocation patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
US Cold Drawn Seamless Steel Pipes Market
Pipes and Tubes
Global Lance Tubes Market
Pipes and Tubes
Pneumatic Fittings Market
Pipes and Tubes
Europe Line Pipe Market
Pipes and Tubes
Oman PVC Pipes Market
Pipes and Tubes
Composite Pipes Market
Pipes and Tubes
Compressed Air Pipe Market
Pipes and Tubes
Steel Roll-On Tube Market
Pipes and Tubes
Global Polyolefin Pipes Market
Pipes and Tubes
Global Copper Pipes and Tubes Market
Pipes and Tubes
Steel Tubes Market
Pipes and Tubes
UAE PVC Pipes Market
Pipes and Tubes
Global Flexible Pipes Market
Pipes and Tubes
Welded Pipes Market
Pipes and Tubes
GCC PVC Pipes Market
Pipes and Tubes
HPLC Fused Silica Tube Market