
 Overlay Paper Market | 2026-2036
Overlay Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Overlay Paper Market Outlook
The gap between premium decorative overlays and commodity packaging grades is expanding as furniture OEMs demand certified low-emission substrates while bulk buyers prioritize cost minimization. Glatfelter leverages its specialty paper infrastructure to supply high-performance overlays for laminate flooring producers. Koehler Paper Group anchors its position through thermal and digital printing compatibility across European decorative markets. SURTECO Group differentiates via integrated decor design and print-to-laminate workflows.
Overlay paper consists of resin-impregnated or printable sheets, typically 20–80 gsm, engineered to bond with particleboard, MDF, or plywood substrates under heat and pressure to create durable decorative surfaces. Its primary purpose is to deliver aesthetic and protective finishes for furniture, flooring, and interior panel applications. Printable overlays dominate volume flows in furniture manufacturing where custom woodgrain and solid-color designs require rotogravure or digital printing flexibility. Transparent overlays capture expanding share in high-pressure laminate applications where substrate texture must remain visible beneath protective resin layers. Textured overlays command margin premiums in premium kitchen and bathroom cabinetry where tactile surface quality drives specification decisions.
EU REACH restrictions on formaldehyde emissions and the EU Green Deal circular-economy requirements are tightening substrate certification standards across European decorative laminate supply chains. Germany's KBA and France's ANSM enforce product safety protocols that extend into construction-material classifications, while ISO 14001 environmental management standards shape supplier qualification criteria. Stakeholders must monitor evolving chemical disclosure rules and recyclability mandates to maintain market access and avoid specification lockout by major panel producers.
Market Dynamics
EU REACH formaldehyde emission caps and the EU Green Deal circular-economy mandates are compressing the supplier base, forcing decorative laminate producers to requalify overlay paper sources against low-emission certification standards or face specification exclusion from engineered wood panel manufacturers.
Growth Catalysts
- EU Green Deal circular-economy procurement mandates:Public and private furniture tenders increasingly require recyclable, low-emission substrate documentation, pulling certified overlay paper volumes into laminate flooring and cabinetry supply chains.
- Engineered wood panel manufacturing clusters:Concentrated production around Cologne and Bielefeld in Germany sustains specialized consumption of high-performance printable and transparent overlay grades for just-in-time laminate bonding operations.
- Digital printing compatibility investments:Rotogravure and inkjet-ready overlay substrates enable furniture OEMs to compress design-to-production cycles for custom woodgrain and solid-color decorative surfaces.
Market Restraints
- Pulp and specialty chemical input volatility:Alpha-cellulose pulp and melamine resin prices fluctuate with energy and feedstock markets, compressing margin predictability for overlay paper converters serving cost-sensitive commodity laminate segments.
- Supply concentration in Central European specialty paper mills:Limited qualified production capacity for certified low-emission overlay grades creates bottleneck risk during demand surges in German and French decorative laminate manufacturing.
- Technical limitations in textured overlay replication:Tactile surface quality specifications for premium kitchen and bathroom cabinetry remain difficult to achieve consistently across high-speed laminate pressing operations, constraining volume scaling in margin-rich segments.
Strategic Opportunities
- Eastern European furniture manufacturing expansion:Polish and Romanian furniture export growth creates underpenetrated demand for certified overlay paper supplies not yet locked into incumbent Central European mill relationships.
- High-pressure laminate transparent overlay applications:Substrate-visible protective resin layers in commercial interior surfacing represent an emerging application segment with specification premiums attached to optical clarity and UV stability performance.
- CSRD sustainability disclosure requirements:Corporate sustainability reporting obligations across EU-listed companies are redirecting procurement toward overlay paper suppliers with documented lifecycle assessment data and circular-economy certification.
Industry Challenges
- Specialized coating and impregnation technician scarcity:Experienced operators capable of maintaining resin saturation uniformity across 20–80 gsm lightweight substrates are retiring faster than training pipelines replenish, constraining qualified production capacity expansion.
- Multi-certification compliance timeline compression:Simultaneous pursuit of ISO 14001 environmental management, REACH chemical disclosure, and national construction-material safety approvals extends supplier qualification cycles beyond typical contract renewal windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Overlay Paper Market |
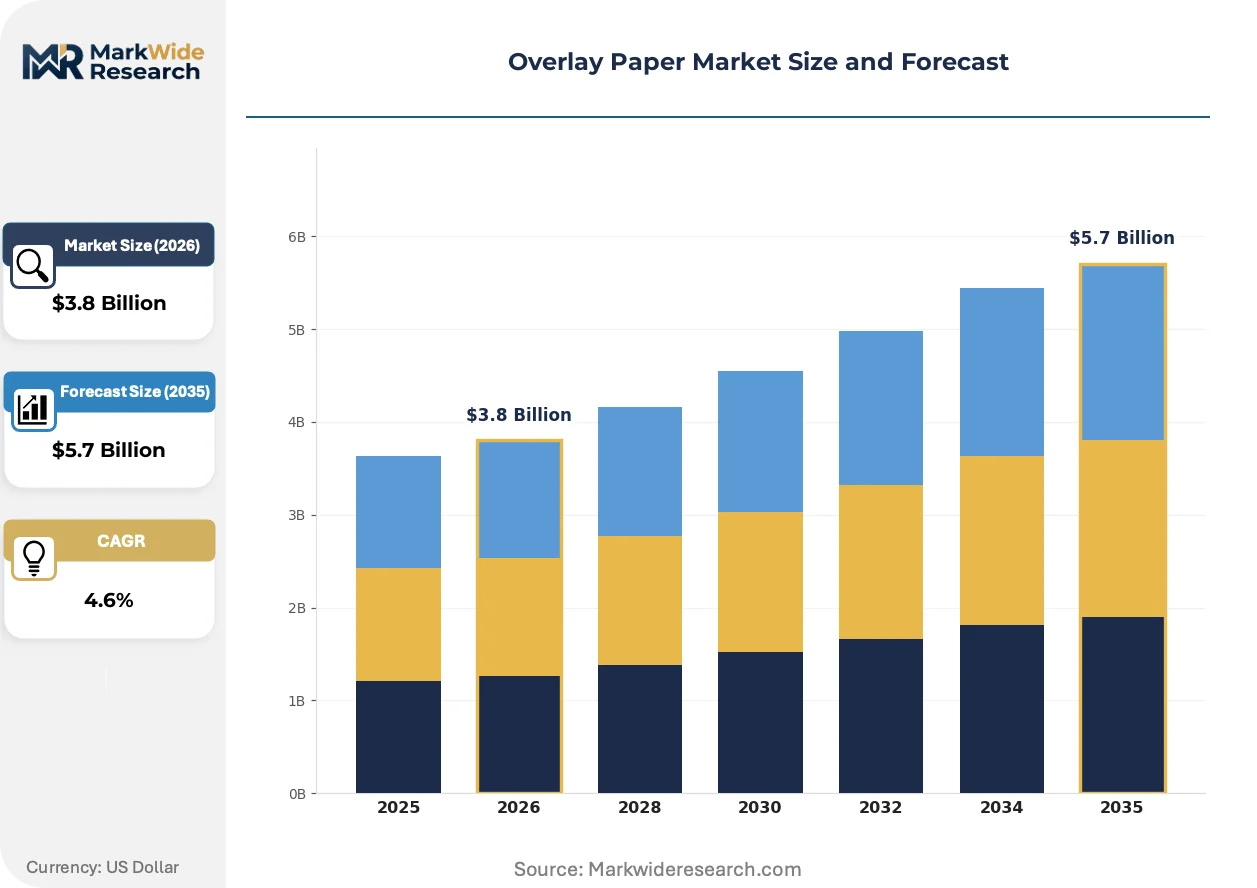
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Printable Overlay, Transparent Overlay, Textured Overlay, Color Overlay Application: Packaging, Printing, Crafting, Stationery Material: Polypropylene, Polyester, Paper, Vinyl Size: A4, A5, Letter, Custom |
| Companies Covered | Glatfelter, Koehler Paper Group, SURTECO Group, UPM-Kymmene Oyj, Schattdecor AG, Sappi Limited, Ahlstrom-Munksjö, 3M Company, Qifeng New Material, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Overlay Paper Market Strategic Shifts
Digital printing workflows and sustainability certification requirements are restructuring how decorative laminate producers specify, procure, and bond overlay paper substrates to engineered wood panels across European furniture and interior surfacing supply chains.
Water-based inkjet-compatible overlay substrates are converging with traditional rotogravure-grade specifications as furniture manufacturers seek single-source paper solutions spanning short-run custom designs and long-run standardized décors. German and Italian laminate flooring producers are piloting hybrid printing lines that switch between digital and analog modes without substrate changeover. This convergence is compressing the historical separation between premium custom-overlay and commodity standard-overlay supply tiers.
REACH chemical restrictions on formaldehyde emissions are tightening substrate certification standards across European decorative laminate supply chains. The regulation mandates disclosure of resin system composition and emission testing under standardized climate chamber protocols. German KBA and French ANSM enforcement of construction-material safety classifications extends these requirements into transport and public building applications, forcing overlay paper suppliers to maintain parallel certification documentation for cross-border panel sales.
Buyer consolidation among engineered wood panel producers is concentrating overlay paper procurement decisions into fewer technical specification teams at major laminate manufacturers. Long-term supply agreements with certified mills are displacing spot-market purchasing for emission-critical furniture and flooring applications. This concentration is most visible in Germany, where the largest particleboard and MDF producers have reduced qualified overlay paper suppliers from multiple regional sources to two or three certified partners per substrate category.
Overlay Paper Market Segmentation
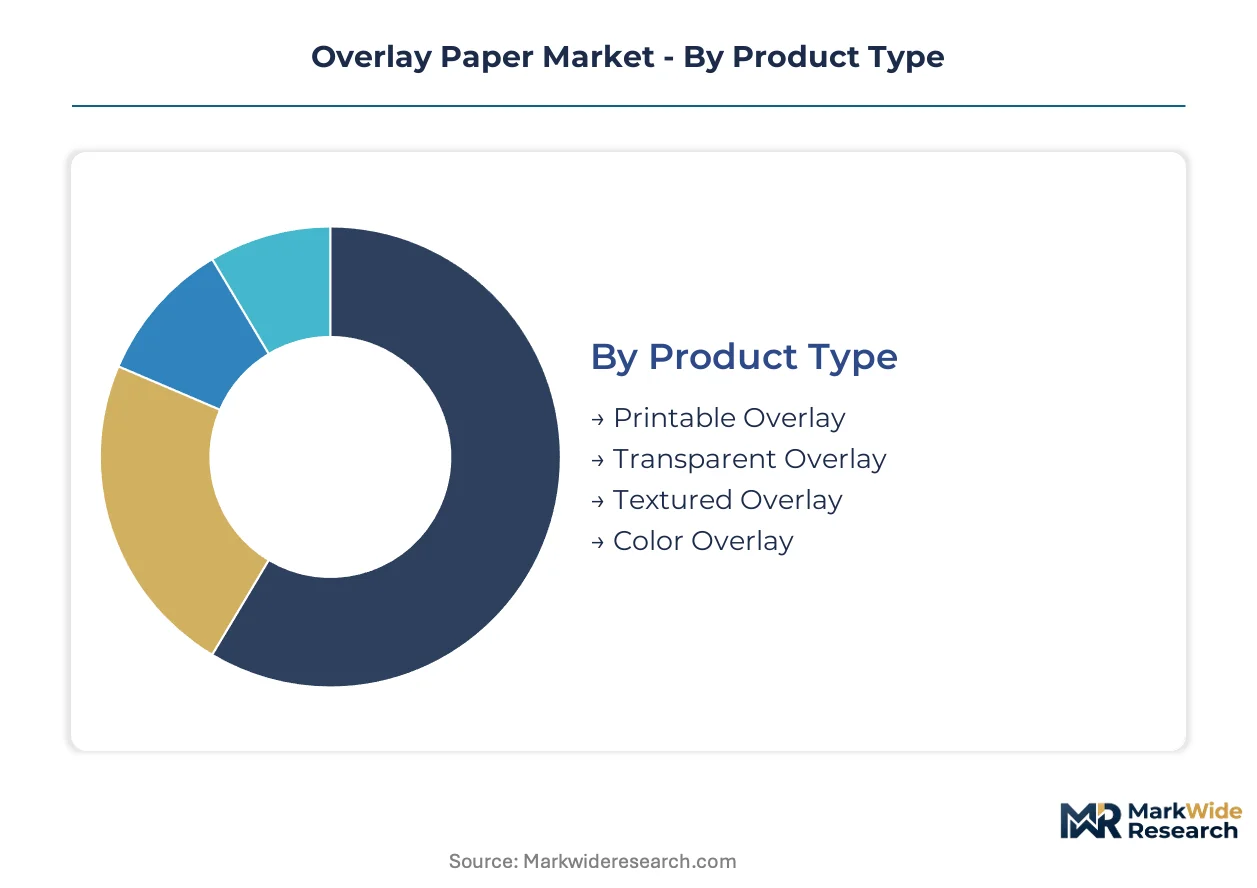
Overlay paper segmentation reveals how substrate specifications diverge between high-volume commodity flows and precision-engineered decorative applications. Understanding these category boundaries helps suppliers align production assets with the divergent certification and performance requirements of furniture OEMs versus bulk packaging buyers.
Product Type:
Customization intensity varies sharply across this category, from mass-produced printable grades to specification-locked textured variants requiring dedicated coating lines.
- Printable Overlay:Engineered for rotogravure and inkjet compatibility with surface porosity calibrated for water-based and solvent ink systems. Cologne and Bielefeld engineered wood panel clusters pull substantial volumes for just-in-time laminate bonding where design changeover frequency favors digital-ready substrates. REACH formaldehyde disclosure mandates are compressing supplier qualification cycles for emission-critical furniture applications.
- Transparent Overlay:Resin-impregnated sheets maintaining optical clarity for substrate-visible decorative finishes in high-pressure laminate applications. Commercial interior surfacing specifications in Germany and France attach premiums to UV stability performance and scratch resistance under standardized climate chamber testing.
- Textured Overlay:Tactile surface embossing for premium kitchen and bathroom cabinetry where haptic quality drives specification decisions among European furniture OEMs.
- Color Overlay:Pre-tinted substrates eliminating post-impregnation printing steps for solid-color decorative laminates serving standardized flooring and panel applications.
Most installed capacity flows through Printable Overlay. Expansion is steepest in Transparent Overlay.
Application:
Cost tier separation distinguishes precision decorative bonding from high-volume protective wrapping where substrate certification carries minimal weight.
- Packaging:Commodity-grade protective wrapping for industrial and consumer goods where cost minimization dominates procurement criteria and emission certification remains absent from specifications.
- Printing:Custom decorative surface production for furniture and flooring OEMs requiring rotogravure and digital workflow compatibility with documented low-emission resin systems under EU Green Deal circular-economy mandates.
- Crafting:Hobby and artisan applications consuming smaller format sheets with lower technical specifications and minimal regulatory compliance requirements.
- Stationery:Decorative and functional paper products for office and educational supply chains prioritizing printability over structural bonding performance.
Revenue concentration sits in Printing. Volume expansion runs fastest in Packaging.
Material:
Margin structure separates petroleum-derived synthetics from renewable fiber substrates facing divergent regulatory treatment under REACH chemical restrictions.
- Polypropylene:Thermoplastic film overlays offering moisture resistance and dimensional stability for exterior-facing laminate applications where synthetic durability outweighs recyclability concerns.
- Polyester:High-clarity film substrates for transparent overlay applications requiring superior optical properties and chemical resistance in commercial interior surfacing.
- Paper:Alpha-cellulose based sheets dominating decorative laminate supply chains where EU Green Deal circular-economy procurement mandates favor recyclable, low-emission substrates with documented lifecycle assessment data.
- Vinyl:PVC-based overlays serving cost-sensitive packaging and crafting segments facing increasing scrutiny under REACH plasticizer restrictions and construction-material safety classifications.
Certified production capacity clusters around Paper. Technical specification premiums attach to Polyester.
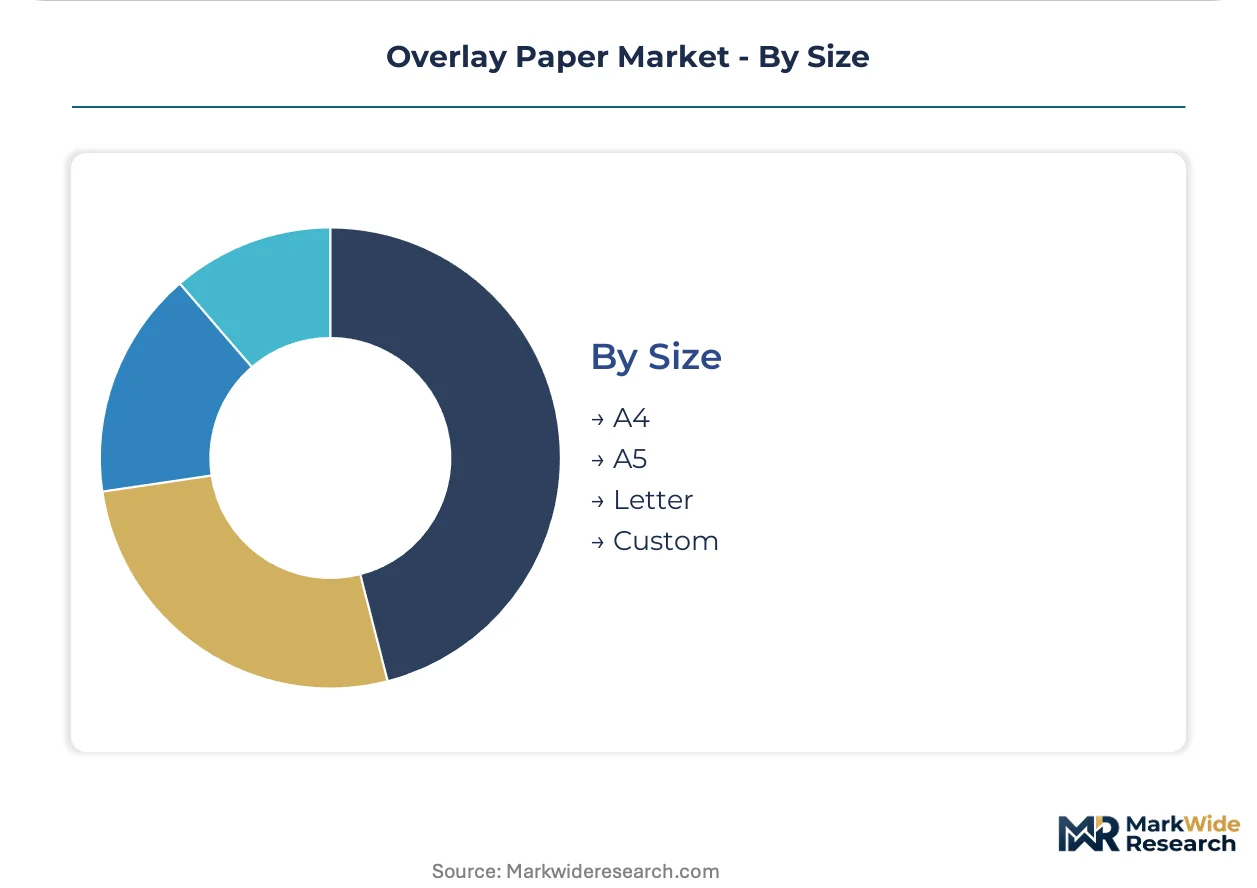
Size:
Customer type fragmentation splits between standardized format mass buyers and custom-dimension specialty purchasers with divergent tooling and logistics requirements.
- A4:Standardized dimension serving European office supply and small-format crafting markets with established distribution through wholesale stationery channels.
- A5:Reduced format for compact decorative applications and specialty packaging where material yield optimization drives specification.
- Letter:North American standard dimension capturing export-oriented production from European mills serving transatlantic furniture manufacturing supply chains.
- Custom:Dimension-on-demand production for large-format laminate flooring and panel manufacturers requiring just-in-time width and length specifications matched to pressing line configurations.
Volume throughput concentrates in A4. Specification premiums accumulate in Custom.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized coating technicians and resin impregnation specialists cluster around Central European paper mill regions, anchoring qualified production capacity for emission-certified overlay substrates. Their concentration in Germany's industrial heartland sustains just-in-time supply chains for engineered wood panel manufacturers. Geographic proximity between technical talent pools and laminate pressing operations compresses logistics costs and qualification timelines.
Germany
Engineered wood panel manufacturing clusters around Cologne and Bielefeld pull substantial volumes of printable and transparent overlay grades for laminate flooring production. KBA enforcement of construction-material safety classifications extends REACH formaldehyde disclosure requirements into transport and public building applications. The North Rhine-Westphalia region concentrates qualified specialty paper capacity serving just-in-time bonding operations for major particleboard and MDF producers.
France
ANSM product safety protocols drive specification requirements for overlay paper used in commercial interior surfacing and public furniture tenders. The EU Green Deal circular-economy procurement mandates redirect public sector laminate purchases toward certified low-emission substrates with documented lifecycle assessment data. Industrial concentration in the Grand Est and Auvergne-Rhône-Alpes regions supports decorative laminate production for export-oriented kitchen and bathroom cabinetry manufacturers.
Poland
Furniture export growth generates underpenetrated demand for certified overlay paper supplies not yet locked into incumbent Central European mill relationships. The country's national construction regulator enforces emission standards aligned with EU REACH frameworks for wood-based panels entering residential and commercial applications. Manufacturing zones around Poznań and Wrocław attract laminate flooring investments seeking proximity to German distribution networks.
Italy
Rotogravure and digital printing workflows for premium decorative surfaces sustain demand for inkjet-compatible overlay substrates with calibrated surface porosity. Lombardy and Veneto regional authorities administer building material certifications that incorporate REACH chemical disclosure requirements into local construction codes. The Brianza furniture district maintains specialized consumption of textured overlay grades for high-end kitchen and bathroom cabinetry specifications.
United States
EPA formaldehyde emission standards under the Toxic Substances Control Act shape overlay paper qualification requirements for laminate flooring imports and domestic production. The Southeast region concentrates engineered wood panel manufacturing around particleboard and MDF facilities serving residential construction markets. North Carolina and Virginia mill locations provide specialty paper capacity for decorative laminate producers seeking domestic sourcing alternatives to European supply chains.
Overlay Paper Market Competitive Environment
Capital-heavy producers compete with asset-light designers across a supplier base consolidating around certified low-emission substrate qualification. Integrated paper mills with in-house resin impregnation lines command procurement relationships with major panel manufacturers, while specialized converters without captive pulp supply face margin compression from alpha-cellulose input volatility. Three archetypes dominate: vertically integrated European specialty paper groups, Asian export-oriented coating specialists, and North American diversified materials conglomerates with decorative surfacing divisions. Competitive moves center on capacity expansion for water-based inkjet-compatible substrates and strategic partnerships with engineered wood panel producers seeking supply security.
Within the integrated European specialty paper tier, Glatfelter and Koehler Paper Group exemplify capital-intensive producers with established qualification status under REACH and EU Green Deal certification frameworks. SURTECO Group occupies a position bridging decor design and substrate supply, representing the workflow-integrated archetype that compresses design-to-production cycles for laminate manufacturers. These three entities anchor the qualified supplier base that major German and French panel producers have consolidated procurement around, displacing spot-market purchasing for emission-critical applications.
| Leading Market Players |
|---|
| Glatfelter |
| Koehler Paper Group |
| SURTECO Group |
| UPM-Kymmene Oyj |
| Schattdecor AG |
| Sappi Limited |
| Ahlstrom-Munksjö |
| 3M Company |
| Qifeng New Material |
| Others |
Value Chain & Pricing Dynamics
Captive resin impregnation lines at Central European specialty paper mills anchor supply positions for certified low-emission overlay grades, concentrating pricing power among qualified suppliers serving German and French engineered wood panel manufacturers under EU REACH formaldehyde disclosure mandates.
Pricing Analysis
Bundled decor design-to-print-to-laminate workflows command premium positioning against unbundled commodity substrate sales. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified transparent overlays for high-pressure laminates from uncertified printable grades serving cost-sensitive packaging buyers. Price differentiation rests on formaldehyde emission certification tier and digital printing compatibility investments. Cost compression in commodity printable grades is intensifying because alpha-cellulose pulp and melamine resin input volatility squeezes converter margins. Bulk packaging buyers exhibit highest price sensitivity; premium furniture OEMs prioritize certification documentation over unit cost.
Supply Chain Analysis
EU Green Deal circular-economy procurement mandates and domestic-content preferences in public furniture tenders are reshaping sourcing toward certified European mills with documented lifecycle assessment data. Geographic supply concentration centers on Germany, France, and Poland, with qualified capacity clustering around Cologne, Bielefeld, and the Grand Est region. Raw material dependencies draw from Nordic alpha-cellulose pulp suppliers and melamine resin producers tethered to natural gas feedstock markets. Single-source vulnerability runs through limited qualified production capacity for certified low-emission overlay grades during demand surges. Distribution runs through long-term supply agreements with major particleboard and MDF producers, displacing spot-market purchasing for emission-critical applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The overlay paper market functions as a stable compounder anchored by EU regulatory mandates that permanently elevate substrate certification requirements across European decorative laminate supply chains.
For Market Incumbents: Extend qualification documentation breadth to capture CSRD sustainability disclosure-driven procurement shifts among EU-listed furniture manufacturers. Deepen backward integration into alpha-cellulose pulp sourcing to buffer margin compression from energy-linked feedstock volatility. Incumbent mills must defend against Asian export-oriented coating specialists by accelerating water-based inkjet-compatible substrate capacity additions in Poland and Romania. For New Entrants and Emerging Players: The price-point gap between premium REACH-certified transparent overlays and economy-grade uncertified printable substrates creates entry space for mid-tier qualification investments. Polish furniture export growth represents the most penetrable geography, with underpenetrated demand for certified supplies not yet locked into incumbent Central European mill relationships. A technical certification-first go-to-market angle—front-loading ISO 14001 and REACH documentation—secures specification trials with engineered wood panel producers consolidating supplier bases. For Investors and Strategic Acquirers: Roll-up economics work for specialized coating and impregnation technicians because experienced operator scarcity constrains qualified production capacity expansion faster than training pipelines replenish. The five-to-ten-year viability window favors acquisition targets with captive resin impregnation lines and established German or French panel producer relationships. The inflection signal to watch is buyer consolidation momentum among engineered wood panel producers reducing qualified suppliers per substrate category from multiple regional sources to two or three certified partners.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Inkjet-Compatible Substrates | Captures furniture OEM demand for digital printing workflow flexibility under EU Green Deal mandates. |
| Backward Integration into Alpha-Cellulose Pulp | Buffers margin compression from energy-linked Nordic pulp feedstock price volatility. |
| REACH Certification Acceleration | Secures specification access as German KBA and French ANSM enforcement tightens construction-material classifications. |
| Long-term Supply Agreement with Panel Producers | Locks in volume commitments as buyer consolidation concentrates procurement decisions among fewer technical specification teams. |
| Joint Venture in Eastern European Manufacturing | Positions for Polish and Romanian furniture export growth with proximity to German distribution networks. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with resin impregnation line operators, procurement leads at engineered wood panel manufacturers, decorative laminate technical specification teams, and specialty paper mill coating technicians with secondary validation against customs and trade data, EU ECHA REACH registration databases, SEC filings from listed paper producers, and national construction-material safety approval registries. Bottom-up overlay paper consumption estimates by application and grade tier were triangulated against top-down engineered wood panel production forecasts.
Segment-weighting approaches distributed total market value across printable, transparent, textured, and color overlay product types; packaging, printing, crafting, and stationery applications; polypropylene, polyester, paper, and vinyl material categories; and A4, A5, letter, and custom size formats. CAGRs were derived from regression analysis of historical consumption patterns and forward projection of regulatory-driven substitution effects. Industry-specific forecast inputs incorporated EU Green Deal circular-economy procurement mandate implementation timelines and digital printing line conversion rates at German and Italian laminate flooring producers.
The model assumes a particular technology adoption path for water-based inkjet-compatible substrates; alternative pathways for rotogravure-digital hybrid printing would alter the outlook for substrate porosity specifications and resin system compatibility requirements. Forecasts reflect assumptions about REACH formaldehyde emission cap enforcement intensity and pulp feedstock price normalization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Recovered Paper Market
Paper Products
North America Medium-Density Fiberboard Market
Paper Products
Chemical Pulp Market
Paper Products
Pp Synthetic Paper Market
Paper Products
Paper Dry Strength Agents Market
Paper Products
Solar Paper Market
Paper Products
Digital Printing Paper Market
Paper Products
Canada Honeycomb Paper Market
Paper Products
Paper Goods Market
Paper Products
Paper Machine Systems Market
Paper Products
Global Cellulose Sponge Market
Paper Products
GCC Stone Paper Market
Paper Products
Woodfree Paper Market
Paper Products
White Top Testliner Market
Paper Products
Latex-Saturated Paper Market
Paper Products
Medical Grade Paper Market