
 GRE Pipes Market | 2026-2036
GRE Pipes Market Size, Share, and Industry Trends Forecast 2026-2036
GRE Pipes Market Outlook
Municipal water utilities is redrawing procurement priorities across the GRE Pipes landscape, displacing traditional steel-centric buyers in coastal and corrosive environments. Future Pipe Industries leverages its Middle East manufacturing footprint to anchor large-diameter contracts for desalination networks. Amiantit Company sustains competitive positioning through backward integration into raw glass fiber production. National Oilwell Varco dominates niche high-pressure segments tied to offshore oilfield service specifications.
Glass Reinforced Epoxy (GRE) Pipes consist of thermosetting epoxy resin matrices reinforced with E-glass or C-glass fiber filaments wound at controlled angles, yielding hoop tensile strengths exceeding 200 MPa and corrosion resistance to pH ranges of 1-14. These properties make GRE systems indispensable for transporting aggressive fluids, seawater, and hydrocarbons where metallic pipes suffer galvanic or chemical degradation. High-pressure product types command premium positioning due to thicker laminate construction and specialized resin formulations for downhole oil & gas applications. Oil & gas application segments concentrate margin pools in subsea tiebacks and sour service pipelines, while water supply applications expand fastest in desalination and wastewater reuse projects across water-stressed regions.
ISO 14692 and ASTM D2996 define laminate architecture and qualification testing for GRE Pipes, with NORSOK M-622 adding offshore-specific fire resistance and fatigue performance requirements that filter market access for non-certified suppliers. The US EPA and Saudi Aramco engineering standards further segment procurement by mandating third-party witnessed hydrostatic testing for critical infrastructure deployments. Buyers must monitor evolving dual-carbon regulations in China and the EU Green Deal's embodied carbon tracking requirements, as these frameworks threaten to recategorize thermoset composites against emerging bio-based thermoplastic alternatives in public tender evaluations.
Market Dynamics
Corrosion-driven infrastructure replacement cycles are compressing procurement timelines for pipeline operators, as Saudi Aramco engineering standards and EPA mandates force accelerated retirement of carbon steel systems in coastal and sour service environments.
Growth Catalysts
- Desalination capacity expansion:Saudi Arabia's water security programs are mandating corrosion-resistant transmission networks for seawater intake and brine discharge systems.
- ISO 14692 certification harmonization:Unified laminate qualification protocols are reducing supplier qualification friction across Middle Eastern oilfield procurement.
- Epoxy resin formulation advances:Novolac-modified thermoset matrices are extending service temperature ranges for downhole injection applications.
Market Restraints
- Raw material concentration:E-glass fiber supply concentrates in Chinese manufacturing clusters, exposing buyers to freight volatility and export licensing delays.
- Thermoset recyclability limitations:Cross-linked epoxy matrices lack end-of-life processing infrastructure, creating landfill liability under EU Green Deal embodied carbon tracking.
- Steel price cyclicality:Temporary carbon steel discounts during commodity troughs delay GRE conversion decisions among budget-constrained municipal utilities.
Strategic Opportunities
- Hydrogen transport adaptation:Permeation-resistant barrier layer development positions GRE systems for emerging hydrogen pipeline retrofit projects in Germany and the Netherlands.
- Modular fabrication methods:Field-winding equipment advances are enabling on-site large-diameter construction for remote mining and offshore platforms.
- Carbon border adjustment mechanisms:EU CBAM phase-in creates competitive positioning for low-embodied-carbon composite systems against imported metallic alternatives.
Industry Challenges
- Specialized welding technician scarcity:Butt-and-wrap joint certification programs lack training capacity to match installation demand in Saudi Arabia's project pipeline.
- Multi-standard compliance burden:Simultaneous adherence to ASTM D2996, NORSOK M-622, and Aramco specifications extends product development cycles by 8-14 months.
- Legacy asset integration complexity:Flange compatibility with existing ductile iron and steel infrastructure requires custom adapter fabrication for each municipal retrofit.
Report Scope
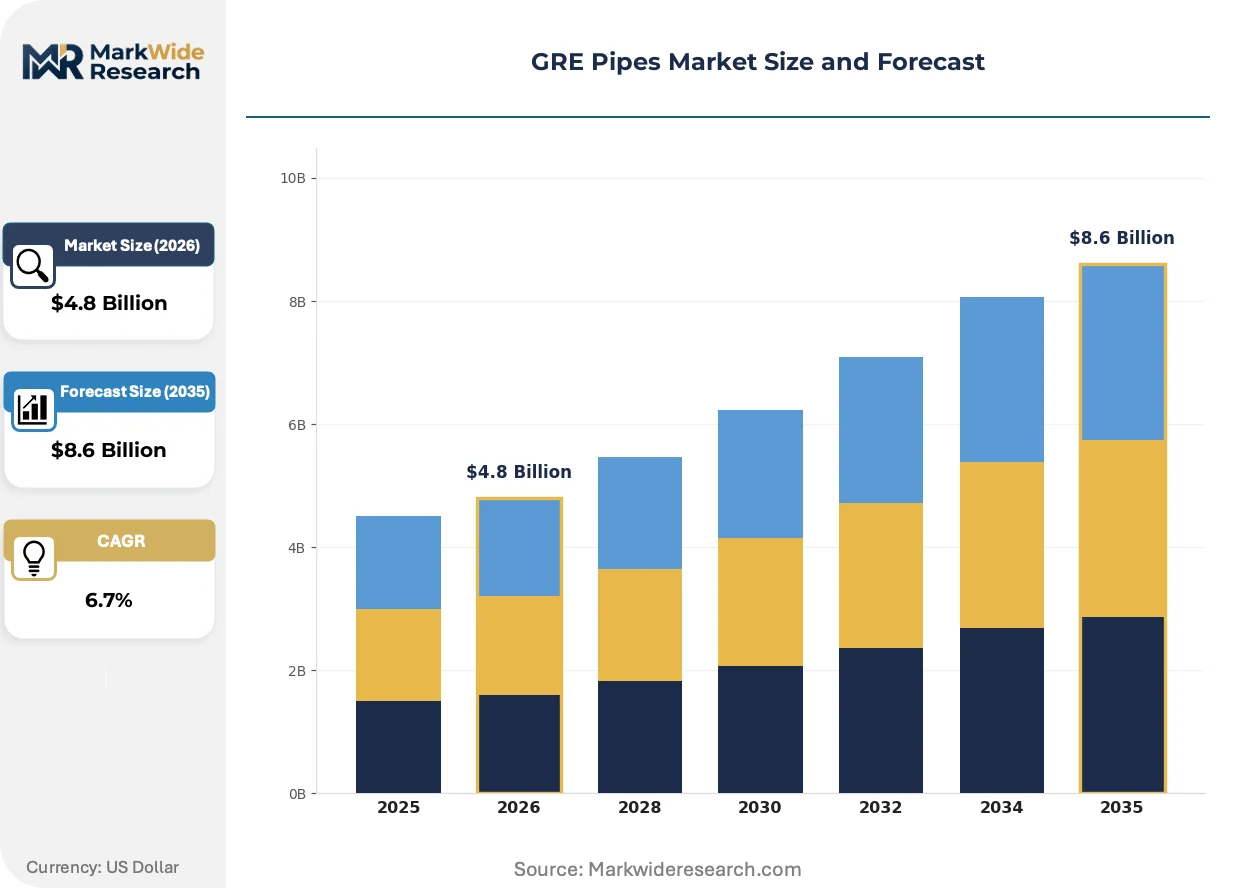
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GRE Pipes Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Pressure, Low-Pressure, Standard, Custom Application: Water Supply, Oil & Gas, Chemical Processing, Industrial Manufacturing End User: Construction, Oilfield Services, Utilities, Mining Size: Small Diameter, Medium Diameter, Large Diameter, Extra Large |
| Companies Covered | National Oilwell Varco, Amiantit Company, Future Pipe Industries, Amiblu Holding, Hobas Group, Lianyungang Zhongfu Lianzhong Composites Group, Hengrun Group, Graphite India Limited, Shawcor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GRE Pipes Market Strategic Shifts
Material science convergence and regulatory carbon accounting are forcing laminate architecture redesigns, while installation methodologies pivot toward reduced-field-labor approaches.
Filament winding automation is miniaturizing. Robotic layup systems now deploy portable units for on-site large-diameter pipe fabrication, compressing logistics costs for remote desert and offshore projects. Saudi desalination contractors are piloting containerized production cells that reduce imported finished pipe volumes by sixty percent. This distributed manufacturing model is miniaturizing the traditional centralized factory paradigm.
EU Green Deal embodied carbon disclosure mandates are tightening. The CSRD scope 3 reporting requirements now capture full lifecycle emissions from pipeline infrastructure procurement. Water utilities in the Netherlands and Denmark are embedding carbon intensity thresholds into tender evaluations, favoring suppliers with verified Environmental Product Declarations. Composite manufacturers are responding with bio-based epoxy pilot programs and recycled glass fiber incorporation.
Asset owner engineering teams are unbundling design from supply contracts. Traditional turnkey procurement is fragmenting into separate specification development, material supply, and installation service awards. This disaggregation is most pronounced in Australia's municipal water sector, where state-level procurement authorities now mandate competitive separation between laminate designers and pipe fabricators to prevent single-source lock-in.
GRE Pipes Market Segmentation
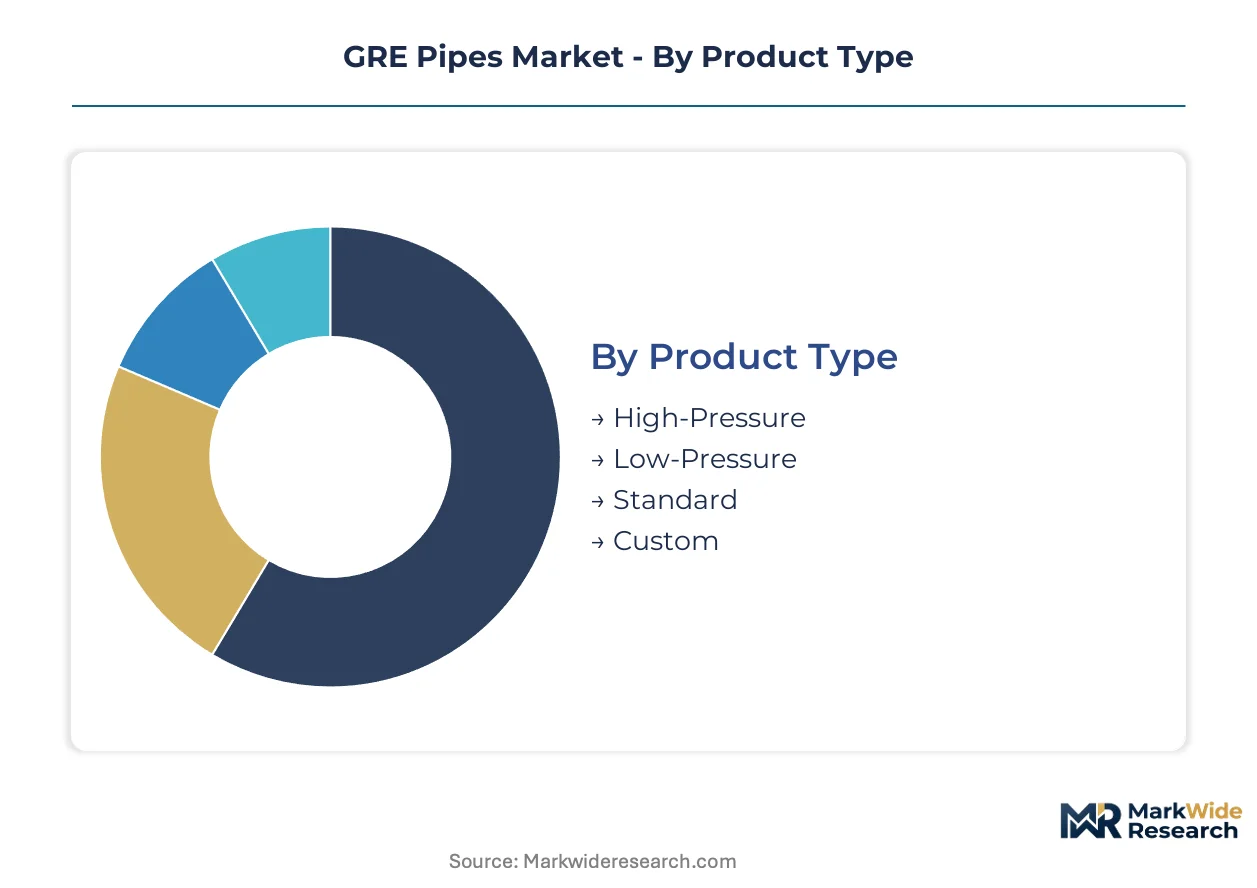
GRE Pipes procurement channels diverge sharply by pressure rating and end-use criticality, with oilfield contractors demanding certified high-pressure systems through direct mill relationships while municipal utilities source standard-pressure products via distributor networks. Understanding these channel dynamics enables suppliers to align certification investments with buyer access points.
Product Type:
Channel-mix patterns split between project-direct procurement for engineered pressure classes and stock-and-flow distribution for commodity specifications, with desalination contractors in Saudi Arabia and the UAE anchoring large-diameter high-pressure volumes through mill-direct contracts.
- High-Pressure:Thicker laminate construction with hoop tensile ratings exceeding 300 MPa serves downhole injection and subsea tieback applications. Saudi Aramco engineering standards mandate third-party witnessed hydrostatic testing for these systems, compressing qualified supplier pools to ISO 14692-certified fabricators with NORSOK M-622 fire resistance credentials.
- Low-Pressure:Reduced wall-thickness designs for gravity-flow wastewater and ventilation systems move through regional building-material distributors. Municipal procurement in the Netherlands and Denmark increasingly embeds EU Green Deal carbon intensity thresholds into low-pressure tender evaluations, favoring suppliers with verified Environmental Product Declarations.
- Standard:Mid-pressure specifications for general industrial process water circulate through MRO distributors and contractor yards across Middle Eastern construction corridors.
- Custom:Engineered laminate architectures for specialized chemical resistance or dimensional requirements require direct specification engagement with end-user engineering teams.
By volume, Standard products lead. By growth pace, High-Pressure systems are expanding most quickly on desalination and oilfield water injection demand.
Application:
Cost-tier stratification separates premium corrosion-resistant systems for aggressive fluid transport from economy-grade specifications for benign water service, with chemical resistance ratings and resin formulation sophistication driving price positioning.
- Water Supply:Desalination intake and brine discharge networks in Saudi Arabia, the UAE, and Qatar anchor demand for large-diameter GRE transmission systems. CSRD scope 3 reporting requirements in the Netherlands and Denmark now capture full lifecycle emissions from pipeline infrastructure procurement, shifting tender evaluations toward low-embodied-carbon composite alternatives.
- Oil & Gas:Sour service pipelines and subsea tiebacks command premium positioning due to NORSOK M-622 fatigue performance and fire resistance mandates. Novolac-modified epoxy matrices are extending service temperature ranges for downhole injection applications in Saudi Arabia's mature oilfields.
- Chemical Processing:pH 1-14 corrosion resistance specifications serve aggressive acid and caustic transport in Saudi Arabian petrochemical complexes.
- Industrial Manufacturing:Process cooling and utility water systems for remote mining and offshore platforms favor modular field-winding compatibility.
By revenue contribution, Oil & Gas dominates. By expansion trajectory, Water Supply is gaining share fastest on desalination capacity buildouts.
End User:
Customer-type concentration shapes sales force deployment, with integrated oilfield services requiring technical specification support while construction contractors prioritize logistics reliability and field joint training.
- Construction:Municipal infrastructure and commercial building projects across Middle Eastern coastal cities drive standard-pressure volume through contractor procurement channels.
- Oilfield Services:Schlumberger, Halliburton, and regional service companies specify high-pressure systems for water injection and produced water handling. Specialized butt-and-wrap joint certification programs lack training capacity to match installation demand in Saudi Arabia's project pipeline.
- Utilities:State-backed water authorities in Saudi Arabia, the UAE, and Qatar mandate corrosion-resistant transmission networks for seawater intake systems under national water security programs.
- Mining:Remote site requirements in Australia's Pilbara and Saudi Arabia's phosphate belt favor containerized field-winding production cells that reduce imported finished pipe volumes.
By project count, Construction leads. By contract value concentration, Oilfield Services is climbing the fastest.
Size:
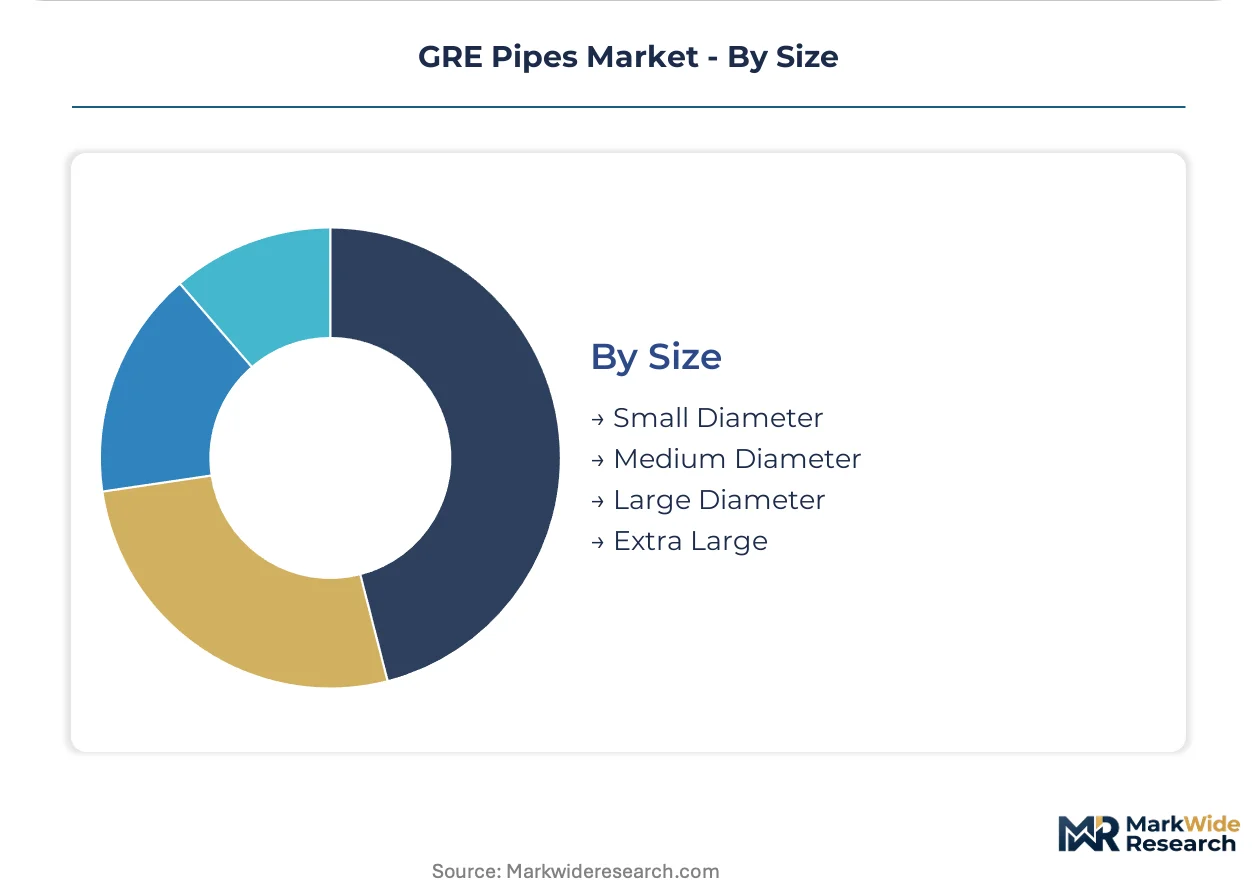
Supply concentration clusters in large-diameter manufacturing capability, with filament winding equipment scale economies favoring centralized production for extra-large specifications versus distributed field fabrication for smaller diameters.
- Small Diameter:Distribution networks and building service applications favor stock-and-flow procurement through plumbing and industrial distributors.
- Medium Diameter:Municipal distribution mains and industrial process lines balance transport economics against installation labor efficiency.
- Large Diameter:Desalination transmission networks in Saudi Arabia and the UAE require specialized mill capacity with mandrel diameters exceeding two meters. Future Pipe Industries leverages its Middle East manufacturing footprint to anchor these contracts.
- Extra Large:Seawater intake and outfall systems for mega-scale desalination plants demand custom-engineered laminate architectures with specialized resin formulations for fatigue resistance.
By installed length, Medium Diameter leads. By capital intensity per meter, Extra Large is advancing most steeply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ras Al-Khair desalination complex anchors Saudi Arabia's position as the world's largest GRE pipe procurement market, with transmission networks connecting industrial cities to Red Sea and Gulf coastlines.
Saudi Arabia
State-backed water security programs mandate corrosion-resistant transmission networks for seawater intake and brine discharge systems. Saudi Aramco engineering standards require third-party witnessed hydrostatic testing for high-pressure applications. The Eastern Province concentrates desalination and oilfield water injection projects, with Ras Al-Khair and Jubail Industrial City driving large-diameter contract volumes.
United Arab Emirates
Abu Dhabi's Taweelah and Al Mirfa mega-scale desalination plants anchor demand for extra-large diameter GRE systems. MOHAP technical specifications govern medical-grade water infrastructure procurement. Dubai's Jebel Ali industrial corridor hosts contractor yards stocking standard-pressure products for municipal distribution networks.
United States
EPA corrosion protection standards accelerate carbon steel replacement cycles in coastal municipal utilities. The Infrastructure Investment and Jobs Act channels funding toward resilient water infrastructure in Gulf Coast states. Texas and Florida concentrate procurement activity, with Houston's petrochemical corridor and Tampa Bay's desalination pilot projects driving specification-grade demand.
Netherlands
CSRD scope 3 reporting requirements now capture full lifecycle emissions from pipeline infrastructure procurement. EU Green Deal embodied carbon tracking mandates favor low-embodied-carbon composite alternatives in public tender evaluations. The Rotterdam-The Hague metropolitan region leads carbon-intensity threshold adoption for water utility procurement.
Australia
State-level procurement authorities mandate competitive separation between laminate designers and pipe fabricators to prevent single-source lock-in. The Pilbara mining region favors containerized field-winding production cells for remote site requirements. Western Australia's water utilities embed durability specifications for corrosive groundwater conditions in tender evaluations.
GRE Pipes Market Competitive Environment
Concentration sits with Middle East-based integrated manufacturers and offshore oilfield specialists. The supplier base stratifies across three tiers: ISO 14692-certified fabricators with NORSOK M-622 credentials, regional mill-direct producers serving desalination contractors, and distributor-dependent standard-pressure suppliers. Backward integration into raw glass fiber production and captive epoxy resin formulation represent the dominant competitive moves, compressing cost positions for qualified bidders.
Among Middle East-based fabricators, Future Pipe Industries and Amiantit Company occupy positions within the integrated manufacturer archetype, while National Oilwell Varco anchors the offshore oilfield specialist tier. These three entities exemplify contrasting strategic postures: mill-direct contracting for mega-scale desalination projects, backward integration into E-glass fiber production, and niche high-pressure certification for subsea applications respectively.
| Leading Market Players |
|---|
| National Oilwell Varco |
| Amiantit Company |
| Future Pipe Industries |
| Amiblu Holding |
| Hobas Group |
| Lianyungang Zhongfu Lianzhong Composites Group |
| Hengrun Group |
| Graphite India Limited |
| Shawcor |
| Others |
Value Chain & Pricing Dynamics
Ninety-day E-glass fiber order-to-delivery windows concentrate procurement leverage with Chinese suppliers, compressing margin buffers for ISO 14692-certified fabricators while amplifying pricing power for backward-integrated Middle East producers. This lead-time asymmetry stratifies the supplier base between mill-direct desalination contractors absorbing freight volatility and distributor-dependent municipal utilities facing inventory carrying cost penalties.
Pricing Analysis
Volume-discount tiering structures anchor project-based contracting for large-diameter desalination networks, with mill-direct awards commanding fifteen to thirty percent unit cost advantages over stock-and-flow procurement. Price differentiation separates NORSOK M-622 certified systems from standard-pressure alternatives, with Saudi Aramco engineering standards and third-party witnessed hydrostatic testing requirements widening certification-grade premiums. Cost compression in low-pressure municipal segments intensifies as Chinese E-glass fiber export licensing delays force spot-market resin sourcing. Budget-constrained construction contractors exhibit highest price sensitivity, while oilfield services prioritize performance guarantees over unit economics.
Supply Chain Analysis
Just-in-time filament winding feedstock management dominates centralized factory operations, yet Saudi desalination contractors increasingly favor strategic stockpiling of novolac-modified epoxy resins to hedge formulation availability risks. Geographic supply concentration centers on Chinese E-glass fiber manufacturing clusters, Saudi Arabian captive resin production, and German specialty chemical additive suppliers. Raw material dependencies rest on borosilicate glass melts, bisphenol-A derived epoxies, and anhydride curing agents. Single-source vulnerability concentrates in Chinese export licensing protocols for strategic glass fiber grades. Distribution runs through mill-direct contracting for engineered pressure classes and regional building-material distributors for standard-pressure specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection materializes as asset owners unbundle design from supply contracts, with Australia's competitive separation mandates fragmenting traditional turnkey procurement into interoperable specification-development and material-supply layers.
For Market Incumbents: Fortify backward integration into raw glass fiber production to offset Chinese supply concentration risks, while deepening NORSOK M-622 and Saudi Aramco certification portfolios against emerging bio-based thermoplastic substitutes. Captive epoxy resin formulation capabilities compress cost positions for qualified bidders in high-pressure oilfield segments. For New Entrants and Emerging Players: Specialized butt-and-wrap joint certification programs represent a service-layer gap where incumbents under-serve Saudi Arabia's accelerated project pipeline. Target containerized field-winding equipment deployment for remote mining and offshore platform applications, leveraging portable robotic layup systems to bypass centralized factory scale disadvantages. For Investors and Strategic Acquirers: Long-term, this sits as a carbon-accounting arbitrage play because EU Green Deal embodied carbon tracking and CBAM phase-in progressively favor low-embodied-carbon composite systems against imported metallic alternatives. Acquisition focus centers on ISO 14692-certified fabricators with verified Environmental Product Declarations and established mill-direct relationships with Saudi utilities. The signal to watch is carbon border adjustment mechanism expansion beyond pilot sectors into pipeline infrastructure procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into E-Glass Fiber Production | Captive borosilicate melt capacity insulates against Chinese export licensing volatility for strategic grades. |
| NORSOK M-622 Fire Resistance Certification | Offshore oilfield specification compliance filters market access for subsea tieback and sour service applications. |
| Containerized Field-Winding Deployment | Portable robotic production cells reduce imported finished pipe volumes by sixty percent for remote desert projects. |
| Environmental Product Declaration Verification | CSRD scope 3 reporting compliance secures tender preference in Netherlands and Denmark utility procurement. |
| Novolac-Modified Epoxy Formulation Development | Extended service temperature ranges capture downhole injection demand in Saudi Arabia's mature oilfields. |
Study Parameters
Cross-validation between primary interviews with desalination project engineers, oilfield services procurement directors, municipal utility specification managers, and composite fabricator technical directors anchors the qualitative findings, while secondary validation draws from customs trade data, EPA corrosion protection standard filings, ISO 14692 certification registries, and Saudi Aramco engineering standard disclosures. Bottom-up demand modeling triangulates against top-down market sizing across pressure rating, application, and regional procurement channel dimensions.
Sensitivity analysis frames volume and value outputs across the projection horizon, with segmentation modeling spanning high-pressure versus low-pressure product tiers, oilfield versus water supply applications, and mill-direct versus distributor procurement channels. CAGRs derive from historical contract award patterns and announced desalination capacity buildouts, incorporating Saudi water security program commitments and EU Green Deal carbon intensity threshold adoption curves as industry-specific forecast inputs.
Underlying assumptions cover sustained E-glass fiber supply availability, stable epoxy resin pricing bands, and continued ISO 14692 harmonization across Middle Eastern procurement authorities, with deviation risk concentrated in Chinese export licensing disruptions and accelerated bio-based thermoplastic substitution timelines. Revision becomes warranted when carbon border adjustment mechanism coverage thresholds cross into pipeline infrastructure procurement mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Global Lance Tubes Market
Pipes and Tubes
FEP Tubing Products Market
Pipes and Tubes
Pipes and Fittings Market
Pipes and Tubes
Global Copper Pipes and Tubes Market
Pipes and Tubes
Bahrain PVC Pipes Market
Pipes and Tubes
North America PVC Pipes Market
Pipes and Tubes
Global Cured-In-Place Pipe Market
Pipes and Tubes
Multiflex Tubes Market
Pipes and Tubes
Global Polypropylene Pipes Market
Pipes and Tubes
Global Tracer Wires Market
Pipes and Tubes
Coiled Tubing Manufacturing Market
Pipes and Tubes
Aluminum Pipe Market
Pipes and Tubes
United States Copper Pipes and Tubes Market
Pipes and Tubes
Qatar PVC Pipe Market
Pipes and Tubes
Europe Pipe Market
Pipes and Tubes
Agricultural Pipes and Tubes Market