
 UAE Genetic Testing Market | 2026-2036
UAE Genetic Testing Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Genetic Testing Market Intelligence
Hospital-based genetic diagnostics is shifting toward precision oncology and reproductive health, pulling sample volume away from general pathology workflows. M42 Genomics leverages its integrated health system footprint to capture high-complexity sequencing demand. NMC Genomics anchors its position through broad clinic-laboratory networks spanning multiple emirates. Freiburg Medical Laboratory Middle East differentiates via specialized rare disease and hereditary cancer panels.
Genetic testing encompasses laboratory analysis of DNA, RNA, chromosomes, and proteins to detect heritable mutations, carrier status, or disease predisposition, typically requiring extraction, amplification via polymerase chain reaction, and sequencing resolution down to single-nucleotide variants. Its primary purpose spans diagnostic confirmation, risk stratification, pharmacogenomic guidance, and reproductive planning across clinical settings. Diagnostic testing occupies the largest revenue share due to mandatory newborn screening programs and oncology diagnostic protocols, while next-generation sequencing represents the fastest-expanding technology segment as panel costs decline and turnaround times compress. Prenatal testing maintains premium positioning amid rising maternal age and expanded carrier screening mandates in Abu Dhabi and Dubai health authorities.
MOHAP and the country's national pharmaceutical regulator enforce genetic data protection standards and clinical laboratory accreditation requirements that shape market access and test validation protocols. The UAE's adoption of international quality frameworks including ISO 15189 for medical laboratories further elevates compliance thresholds for new entrants. Stakeholders must monitor evolving hereditary disease screening mandates and fertility benefit expansions as policy levers that will redistribute test volume across hospital, clinic, and independent laboratory channels.
Market Dynamics
The UAE genetic testing market is restructuring around precision medicine mandates from Dubai Health Authority and Abu Dhabi Department of Health, which are redirecting hospital capital toward molecular diagnostics infrastructure and away from conventional pathology equipment.
Growth Catalysts
- Expanded newborn screening mandates:MOHAP protocols now require tandem mass spectrometry and DNA sequencing for metabolic disorders, pulling volume into hospital laboratories.
- Oncology diagnostic protocols:Abu Dhabi health authorities mandate somatic mutation profiling for lung and colorectal cancer treatment selection, embedding genetic testing into standard care pathways.
- Fertility benefit expansions:Employer-sponsored health plans in Dubai increasingly cover preimplantation genetic testing, channeling demand through clinic-laboratory networks.
Market Restraints
- Reagent supply concentration:PCR master mixes and sequencing chemistries depend on single-source suppliers from the United States and Germany, exposing laboratories to customs delays and currency fluctuation.
- ISO 15189 accreditation timelines:Medical laboratory certification requires 12-18 month validation cycles that freeze test menu expansion for new entrants.
- Genetic counselor scarcity:The Emirates lacks accredited training programs, forcing laboratories to recruit from Lebanon and Jordan at premium compensation packages.
Strategic Opportunities
- Ras Al Khaimah and Fujairah penetration:Northern emirates operate with limited molecular diagnostics capacity, creating first-mover advantage for laboratory networks willing to establish satellite collection infrastructure.
- Pharmacogenomic integration:Cardiology and psychiatry departments in Abu Dhabi seek CYP2C19 and SLCO1B1 testing for clopidogrel and statin dosing, opening therapeutic areas beyond oncology.
- Direct-to-consumer channel emergence:Wellness platforms in Dubai now offer carrier screening and ancestry testing, bypassing physician gatekeepers for low-complexity assays.
Industry Challenges
- Bioinformatics pipeline integration:Hospital IT systems lack interoperability with variant interpretation platforms, forcing manual data transfer and delaying report turnaround.
- Variant of uncertain significance management:Clinical laboratories face escalating reclassification workloads as literature updates require amended patient reports and physician notification.
- Sample logistics in summer heat:Ambient temperature excursions during courier transport from Al Ain and Western Region compromise nucleic acid integrity for time-sensitive prenatal assays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Genetic Testing Market |
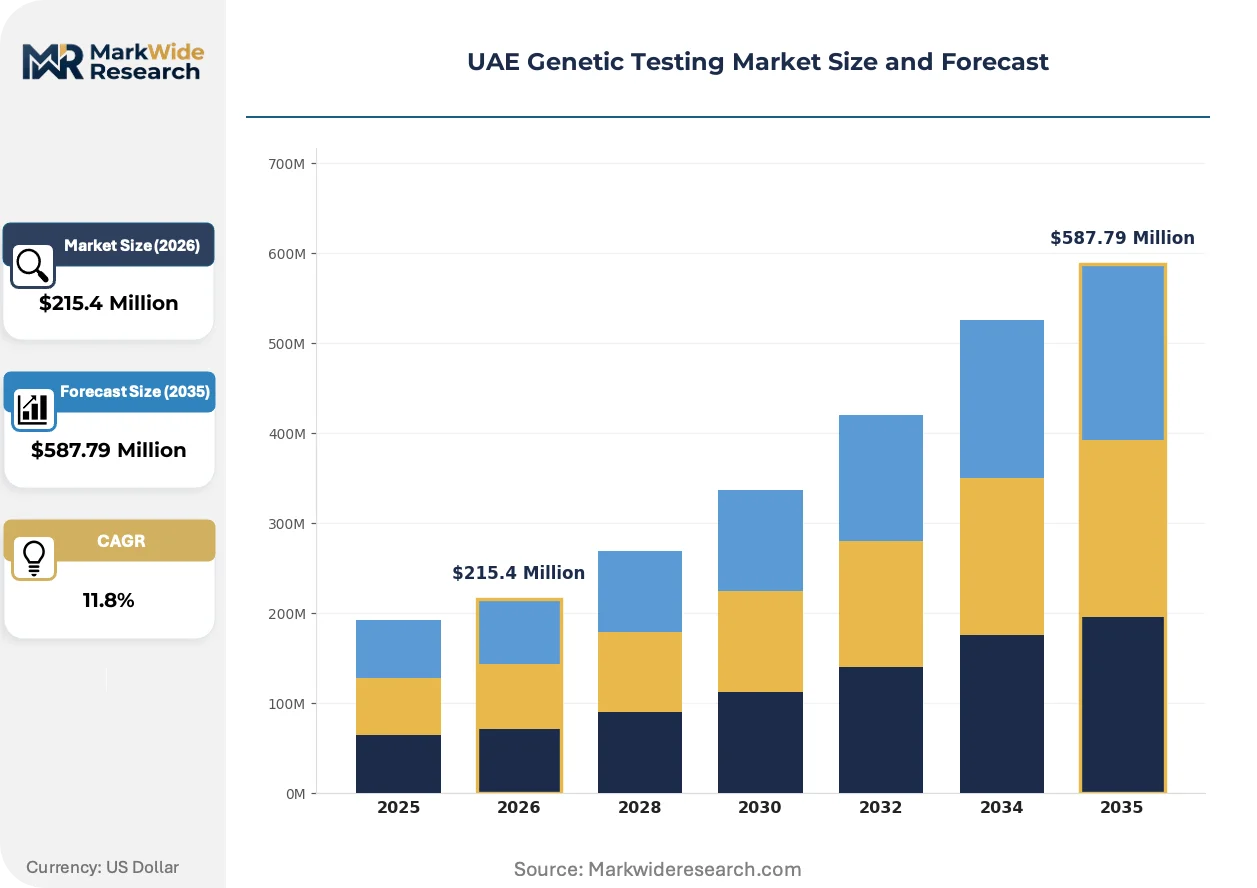
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $587.79 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carrier Testing, Predictive Testing, Diagnostic Testing, Prenatal Testing End User: Clinics, Hospitals, Laboratories, Research Institutions Technology: Next-Generation Sequencing, Sanger Sequencing, Microarray, Polymerase Chain Reaction Application: Oncology, Cardiovascular, Neurology, Rare Diseases |
| Companies Covered | Middle East Testing Services L.L.C, M42 Genomics, NMC Genomics, Mediclinic Middle East Genetics, Freiburg Medical Laboratory Middle East, Molecular Biology & Genetics Laboratory, NSG, IVI Middle East Fertility Clinic, Dubai Genetics Center, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Genetic Testing Market Strategic Shifts & Innovations
Long-read sequencing platforms and artificial intelligence variant classification are compressing diagnostic timelines while expanding the clinical utility of genetic data beyond rare disease into common complex conditions.
Third-generation sequencing technology from Pacific Biosciences and Oxford Nanopore is converging with cloud-based variant interpretation pipelines to resolve structural variants and repeat expansions that short-read platforms miss. Hospital laboratories in Dubai are piloting these systems for neurology and cardiology referrals where tandem repeat disorders dominate. The structural consequence is a bifurcation in laboratory capital allocation, with academic medical centers absorbing platform risk while community hospitals outsource complex cases.
MOHAP's updated genetic data protection standards now mandate encryption protocols and cross-border transfer restrictions that exceed baseline GDPR requirements. Clinical laboratories must reconfigure data architecture and vendor contracts to maintain compliance. Multi-emirate laboratory networks face the highest adaptation burden as they centralize bioinformatics while distributing sample processing.
Physician ordering patterns in Abu Dhabi are consolidating around integrated health system laboratories that bundle genetic testing with pathology and radiology services. Independent reference laboratories respond by unbundling interpretation-only services for hospitals with in-house sequencing capacity. This channel restructuring is most visible in oncology, where medical oncologists prefer single-source accountability for diagnostic and therapeutic decisions.
UAE Genetic Testing Market Segmentation
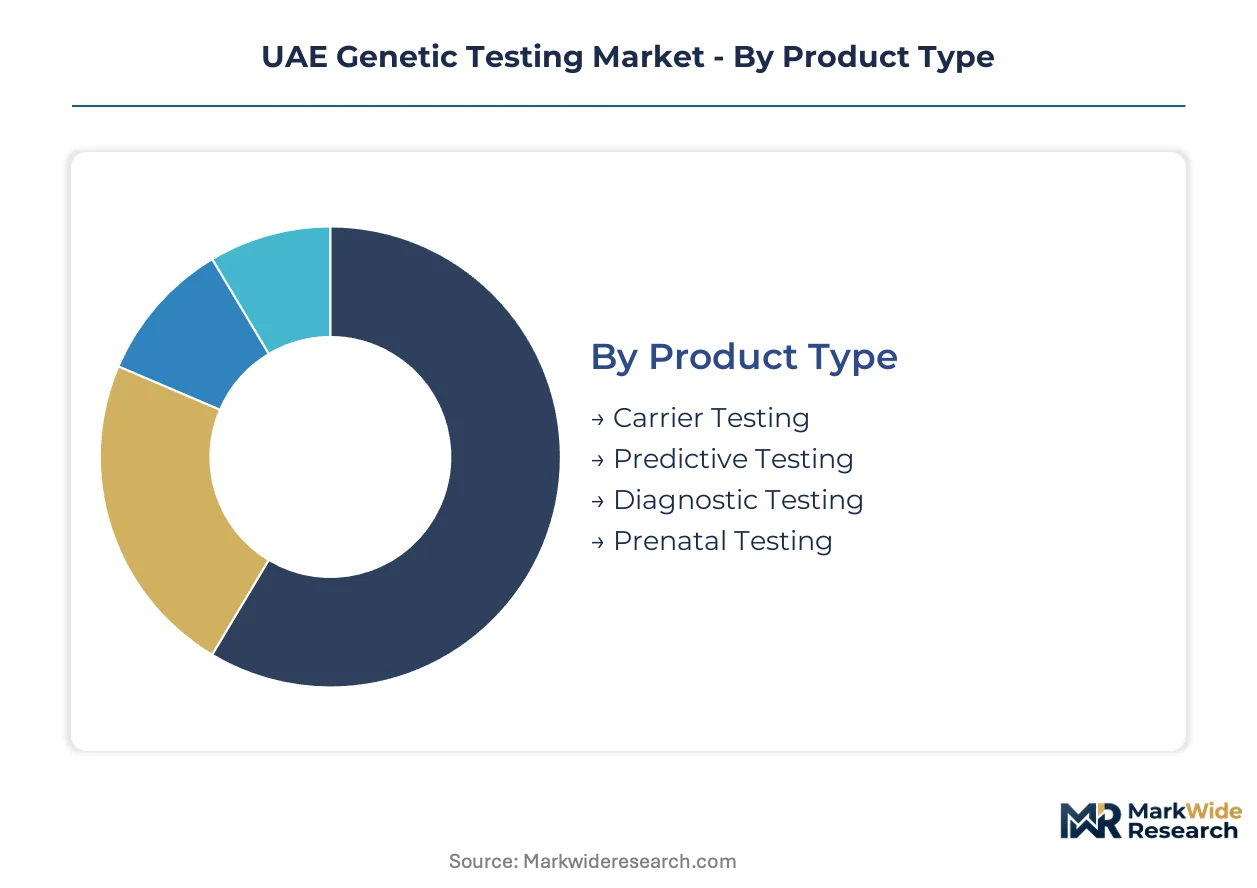
Genetic testing segmentation in the UAE reflects divergent supply chain configurations across product types, technologies, and clinical settings. Each dimension carries distinct procurement patterns, regulatory exposure, and margin structures that reshape competitive positioning among Dubai and Abu Dhabi laboratory networks.
Product Type:
Supply concentration for assay kits and reagent bundles varies sharply across testing categories, with MOHAP procurement rules favoring vertically integrated hospital laboratories for high-volume screening programs.
- Diagnostic Testing:Laboratory analysis confirms suspected genetic disorders through targeted mutation detection and chromosomal microarray. Dubai hospital laboratories absorb the bulk of newborn screening volume under MOHAP-mandated protocols for metabolic disorders.
- Prenatal Testing:Non-invasive fetal DNA screening and invasive diagnostic procedures detect chromosomal aneuploidies and single-gene disorders. Fertility clinics in Abu Dhabi channel demand through clinic-laboratory networks as employer-sponsored benefit expansions accelerate.
- Predictive Testing:Asymptomatic screening for hereditary cancer syndromes and late-onset neurological conditions. Premium positioning in Dubai medical tourism corridors attracts Gulf Cooperation Council patients seeking BRCA and Lynch syndrome panels.
- Carrier Testing:Preconception screening for autosomal recessive conditions prevalent in Arab populations. Expanded panels for thalassemia and sickle cell trait dominate Emirates Family Registry referrals.
Diagnostic testing absorbs the bulk of installed capacity; prenatal testing is expanding most quickly.
End User:
Customer type determines pricing power and test menu breadth, with integrated health systems capturing oncology and reproductive health volume while independent laboratories compete on turnaround time for routine screening.
- Hospitals:Academic medical centers in Dubai and Abu Dhabi deploy in-house sequencing infrastructure for precision oncology protocols. Capital allocation favors next-generation sequencing platforms under Department of Health diagnostic mandates.
- Laboratories:Reference laboratories process outsourced samples from clinics lacking molecular diagnostics capacity. Centralized bioinformatics operations in Dubai service satellite collection points across northern emirates.
- Clinics:Fertility and oncology outpatient settings generate preimplantation genetic testing and somatic mutation profiling referrals. Physician office laboratories in Dubai Healthcare City concentrate prenatal counseling workflows.
- Research Institutions:Khalifa University and NYU Abu Dhabi genomics centers drive validation studies for novel variant interpretation algorithms. Collaborative networks with European sequencing consortia expose procurement to euro-denominated reagent contracts.
Hospitals command the highest test complexity; laboratories are gaining share fastest through unbundled interpretation services.
Technology:
Platform selection dictates reagent supply chains, bioinformatics overhead, and technician training requirements that segment the vendor landscape between multinational suppliers and regional distributors.
- Next-Generation Sequencing:Massively parallel sequencing of targeted gene panels, whole exomes, and genomes with single-nucleotide and structural variant resolution. Dubai hospital laboratories compress turnaround times for oncology diagnostic protocols through in-house Illumina and Thermo Fisher deployments.
- Polymerase Chain Reaction:Amplification-based detection of known mutations with quantitative and qualitative readouts. Real-time PCR systems dominate carrier screening workflows in Abu Dhabi thalassemia prevention programs due to lower per-sample costs.
- Sanger Sequencing:First-generation capillary electrophoresis for targeted variant confirmation and small gene analysis. Declining utilization except for forensic applications and clinical research validation studies.
- Microarray:Comparative genomic hybridization and SNP arrays for copy number variation detection. Prenatal diagnostic laboratories retain platforms for constitutional anomaly detection when sequencing yields equivocal results.
Next-generation sequencing captures the steepest expansion trajectory; polymerase chain reaction retains the largest installed base.
Application:
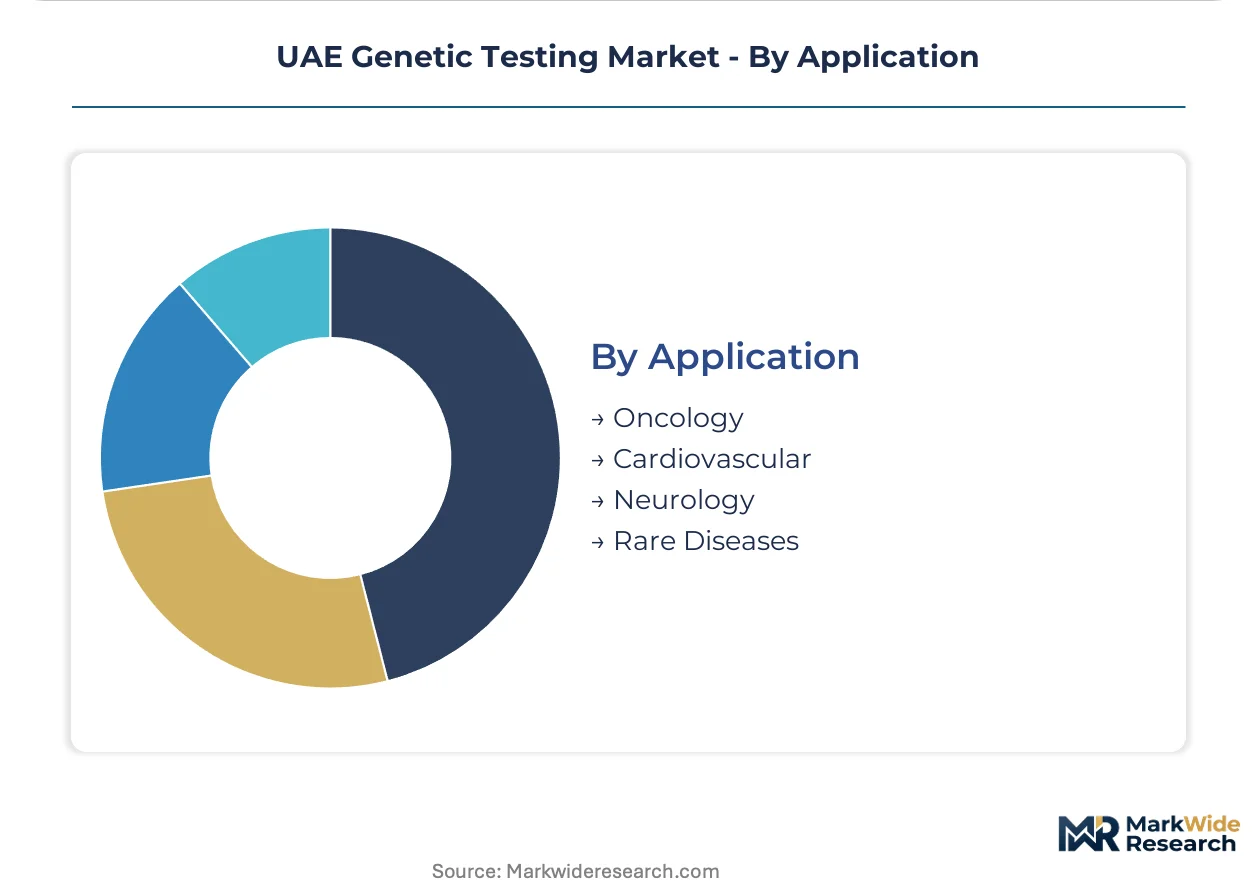
Clinical indication shapes reimbursement pathways and physician ordering patterns, with oncology and rare disease applications commanding premium pricing against commoditized cardiovascular risk panels.
- Oncology:Somatic mutation profiling for treatment selection and hereditary cancer syndrome identification. Abu Dhabi Department of Health mandates EGFR, KRAS, and BRAF testing for lung and colorectal cancer pathways.
- Rare Diseases:Exome and genome sequencing for Mendelian disorder diagnosis in pediatric and adult neurology referrals. Freiburg Medical Laboratory Middle East maintains specialized panels for Arab founder mutations.
- Cardiovascular:Pharmacogenomic dosing guidance and heritable cardiomyopathy screening. Cleveland Clinic Abu Dhabi cardiology departments pilot CYP2C19 testing for clopidogrel response.
- Neurology:Third-generation sequencing for repeat expansion disorders and mitochondrial DNA analysis. Dubai academic centers pilot Pacific Biosciences platforms for Huntington disease and fragile X referrals.
Oncology concentrates the highest revenue per test; rare disease applications are climbing the fastest as exome sequencing costs decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai Healthcare City and Abu Dhabi Healthcare City anchor genetic testing infrastructure through tax-advantaged free zones that concentrate laboratory capital and clinical research licensing.
Dubai
Fertility clinics and oncology centers drive preimplantation genetic testing and somatic mutation profiling volume. Dubai Health Authority mandates expanded carrier screening for employer-sponsored health plans. Dubai Healthcare City clusters M42 Genomics and Mediclinic Middle East Genetics facilities serving Gulf Cooperation Council medical tourism demand.
Abu Dhabi
Department of Health protocols require EGFR and KRAS testing for lung cancer treatment pathways. Cleveland Clinic Abu Dhabi and Sheikh Khalifa Medical City anchor precision oncology infrastructure. Masdar City health-tech incubators host bioinformatics startups supporting variant interpretation pipelines.
Sharjah
University Hospital Sharjah and Sharjah Institute of Medical Research expand molecular diagnostics capacity for rare disease referrals. Sharjah Health Authority coordinates thalassemia prevention programs with centralized carrier screening. University City laboratories process samples from northern emirate satellite collection points.
Northern Emirates
Ras Al Khaimah and Fujairah operate with limited in-house sequencing capacity, forcing sample transport to Dubai hubs. Ras Al Khaimah Economic Zone offers laboratory licensing incentives to attract satellite processing facilities. Fujairah port logistics corridors enable temperature-controlled courier routes reducing summer transit risk.
UAE Genetic Testing Market Key Industry Players
Top-tier vendors anchor hospital-laboratory networks, while independent reference laboratories compete on turnaround time and specialized panel breadth. The market structures around three strategic archetypes: integrated health system laboratories, independent reference laboratories with centralized bioinformatics, and fertility clinic-affiliated genetics centers. Competitive moves concentrate on unbundled interpretation services and satellite collection infrastructure in underpenetrated emirates.
Within the integrated health system tier, M42 Genomics and NMC Genomics exemplify the hospital-laboratory network model capturing high-complexity sequencing demand through captive patient flows. Freiburg Medical Laboratory Middle East occupies a specialist position emphasizing rare disease and hereditary cancer panels. These three entities represent distinct competitive vectors: vertical health system integration, multi-emirate clinic-laboratory networks, and European-affiliated specialized diagnostics.
| Leading Market Players |
|---|
| Middle East Testing Services L.L.C |
| M42 Genomics |
| NMC Genomics |
| Mediclinic Middle East Genetics |
| Freiburg Medical Laboratory Middle East |
| Molecular Biology & Genetics Laboratory |
| NSG |
| IVI Middle East Fertility Clinic |
| Dubai Genetics Center |
| Others |
Cost & Logistics Intelligence
Hospital laboratory procurement committees in Dubai and Abu Dhabi anchor volume concentration, locking in contract-based pricing for high-throughput sequencing platforms under MOHAP-mandated screening programs. This buyer concentration forces independent reference laboratories to compete on turnaround premiums for STAT oncology cases while absorbing reagent cost volatility.
Pricing Analysis
Expedited turnaround commands 15-25% premiums over standard 7-10 day reporting cycles, particularly for prenatal diagnostic windows. Pricing stratifies across premium STAT tiers, standard clinical workflows, and economy batch-processing queues for research institutions. Cost compression in economy tiers is intensifying because Dubai Health Authority reference lab networks are consolidating volume under single-source agreements. Research institutions exhibit highest price sensitivity due to grant-funded budgets, while fertility clinics demonstrate lowest sensitivity given employer-sponsored benefit coverage.
Supply Chain Analysis
Direct-to-hospital channels handle hyperscale demand from Dubai and Abu Dhabi health systems, with regional distributors serving satellite clinics in northern emirates. Reagent supply draws from concentrated manufacturing in the United States, Germany, and Singapore, with Illumina and Thermo Fisher chemistries dominating NGS workflows. PCR master mixes and sequencing consumables rest on single-source dependencies that expose laboratories to customs clearance delays at Jebel Ali port. Temperature-controlled logistics infrastructure mitigates nucleic acid degradation risk during summer ambient excursions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 15189 accreditation timelines function as a compliance moat, freezing test menu expansion for 12-18 months and rewarding laboratories with pre-existing certification infrastructure.
For Market Incumbents: Anticipate reimbursement compression from Dubai Health Authority bundled payment pilots by deepening bioinformatics interpretation capabilities that independent laboratories cannot replicate. Anchor capacity expansion in Ras Al Khaimah Economic Zone to capture northern emirate volume before satellite competitors establish collection infrastructure. Defend against unbundled interpretation-only services by integrating pathology, radiology, and genomics reporting under single-source accountability. For New Entrants and Emerging Players: MOHAP's expanded newborn screening mandates in Abu Dhabi open a window for specialized metabolic disorder panel providers with rapid validation capabilities. Target fertility clinic laboratory partnerships as the most penetrable channel, given employer-sponsored benefit expansions and limited in-house sequencing capacity. Pursue pharmacogenomic integration with Cleveland Clinic Abu Dhabi cardiology departments as a differentiated entry vector beyond saturated oncology pathways. For Investors and Strategic Acquirers: Distressed-cycle entries favor ISO 15189-accredited reference laboratories with established northern emirate courier networks during periods of reagent cost volatility. Long-term viability hinges on artificial intelligence variant interpretation capabilities that reduce manual reclassification workloads. Monitor Abu Dhabi Department of Health somatic mutation profiling mandate expansions beyond lung and colorectal cancer as the signal for platform utilization inflection.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 15189 Accreditation Investment | Accelerates MOHAP contract eligibility and freezes competitor test menu expansion timelines. |
| AI Variant Interpretation Platform Deployment | Reduces manual reclassification burden at Cleveland Clinic Abu Dhabi and Sheikh Khalifa Medical City. |
| Satellite Collection Infrastructure Expansion | Captures Ras Al Khaimah and Fujairah prenatal testing volume ahead of Dubai hub competitors. |
| Pharmacogenomic Test Menu Diversification | Opens CYP2C19 and SLCO1B1 revenue streams beyond saturated oncology diagnostic protocols. |
| Third-Generation Sequencing Platform Pilot | Resolves structural variants for neurology referrals at Dubai academic medical centers. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with laboratory directors, genetic counselors, fertility clinic operators, and MOHAP compliance officers. Bottom-up test volume modeling triangulated against top-down health authority procurement disclosures and hospital capital expenditure tracking. Analysis incorporated ISO 15189 accreditation databases, Department of Health diagnostic protocol mandates, and reagent import manifests through Jebel Ali customs.
Reconciliation of sample volume data from hospital laboratories, reference laboratory networks, and fertility clinic referral patterns generated consistent baseline estimates across the projection horizon. Segmentation dimensions encompassed product type, technology platform, clinical application, and end-user channel, with geographic splits across Dubai, Abu Dhabi, Sharjah, and northern emirates. CAGRs derived from test volume trajectory analysis, pricing trend assessment, and technology substitution curves for NGS versus PCR workflows.
The model assumes a particular technology adoption path; alternative pathways for long-read sequencing platform penetration would alter the outlook if third-generation systems achieve cost parity with short-read platforms earlier than projected. Forecasts reflect assumptions regarding MOHAP mandate expansion timelines, employer-sponsored fertility benefit coverage rates, and reagent supply chain stability. Periodic stress-testing of base assumptions is recommended, particularly regarding hereditary disease screening policy shifts and cross-border data transfer restriction enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Global Single-Cell Genome Sequencing Market
Genomics
Whole Exome Sequencing (WES) Market
Genomics
Rare Disease Genetic Testing Market
Genomics
Global Clinical Oncology Next Generation Sequencing Market
Genomics
Spatial Genomics and Transcriptomics Market
Genomics
Genomics Personalized Health Market
Genomics
Asia-Pacific Genetic Testing Market
Genomics
Next-Generation Sequencing Library Preparation Market
Genomics
Europe Whole Exome Sequencing Market
Genomics
Targeted DNA RNA Sequencing Market
Genomics
Global Artificial Intelligence in Genomics Market
Genomics
Retail Genomics Market
Genomics
Microbiome Sequencing Market
Genomics
Europe Digital PCR Market
Genomics
Microarray Scanners Market
Genomics
Next Generation Sequencing (NGS) Informatics Market