
 Europe Whole Exome Sequencing Market | 2026-2036
Europe Whole Exome Sequencing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Whole Exome Sequencing Market Foresight
Next-generation sequencing (NGS) is reconfiguring how whole exome analysis moves from research benches into clinical pipelines across European healthcare systems. Illumina Inc. leverages its installed base of sequencing instruments to sustain dominance in high-throughput exome workflows for academic medical centers. Thermo Fisher Scientific Inc. anchors its position through integrated sample-to-report solutions that streamline laboratory operations. QIAGEN differentiates with bioinformatics platforms that simplify variant interpretation for diagnostic users.
Whole exome sequencing captures protein-coding regions comprising approximately one percent of the human genome, using targeted enrichment followed by massively parallel sequencing to identify disease-causing variants with analytical sensitivity exceeding 99 percent at 20x coverage depth. Its primary purpose spans rare disease diagnosis, carrier screening, and pharmacogenomic profiling in clinical and research settings. Diagnostics applications lead the application segment as European health technology assessment bodies expand reimbursement for exome-based rare disease testing. Research laboratories represent the fastest-growing end user category, driven by cross-border genomic data sharing initiatives under the European 1+ Million Genomes Initiative. NGS technology occupies the dominant technology position, while Sanger sequencing retains niche utility for variant confirmation.
The European Medicines Agency (EMA) governs companion diagnostic approvals that increasingly incorporate exome-derived biomarkers, while the EU Medical Device Regulation (MDR) imposes stricter conformity requirements on sequencing-based in vitro diagnostics. The EU General Data Protection Regulation shapes how genomic data traverses borders between member state biobanks and clinical networks. Stakeholders must monitor evolving health technology assessment criteria across France's HAS, Germany's IQWiG, and England's NICE as these bodies determine reimbursement thresholds for clinical exome sequencing.
Market Dynamics
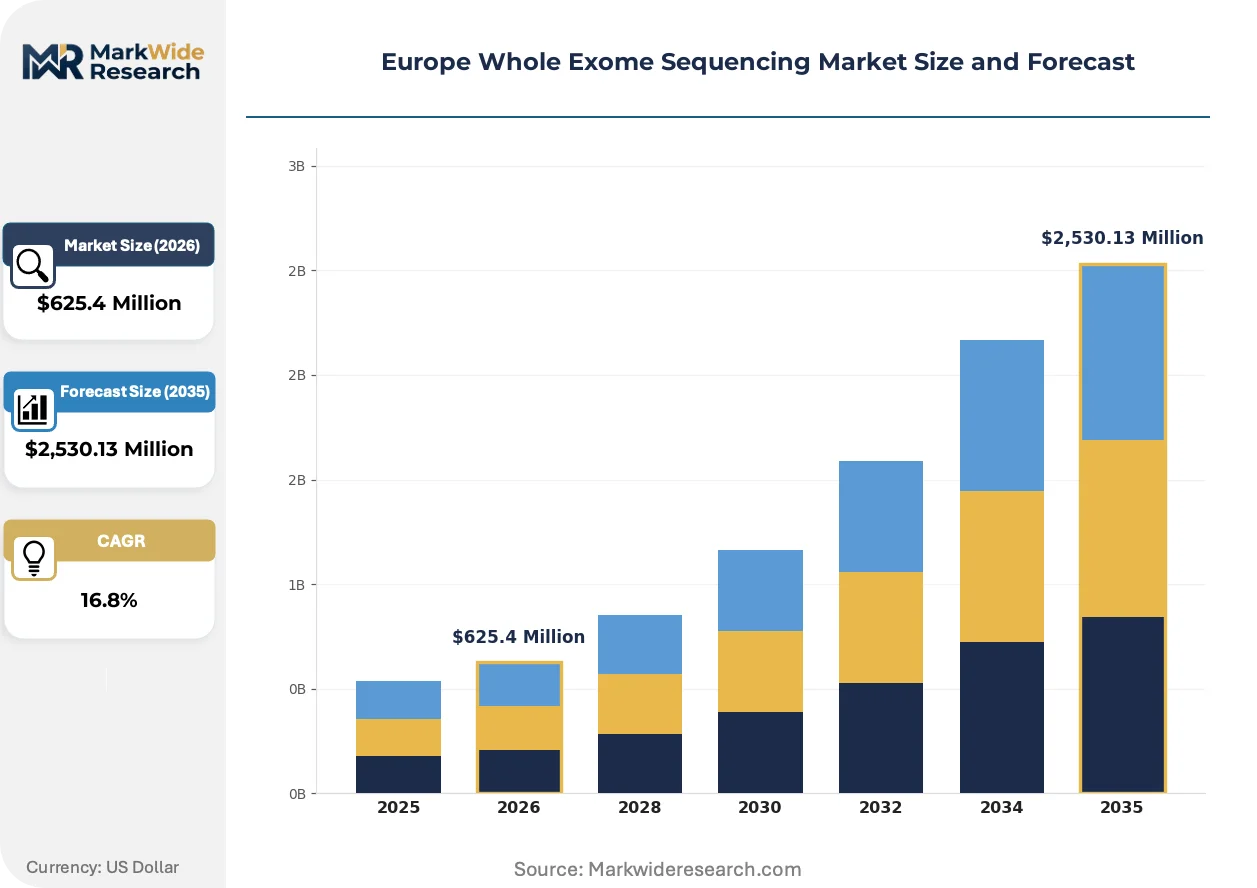
EU Medical Device Regulation (MDR) conformity requirements are compressing vendor timelines and forcing diagnostic laboratories to revalidate sequencing platforms, while Germany's IQWiG and France's HAS tighten reimbursement criteria for clinical exome testing.
Growth Catalysts
- European 1+ Million Genomes Initiative:Cross-border genomic data sharing frameworks accelerate research laboratory adoption of exome sequencing across member state biobank networks.
- EMA companion diagnostic pathway:Biomarker qualification procedures increasingly incorporate exome-derived signatures, expanding addressable indications for oncology testing.
- Targeted enrichment chemistry advances:Hybridization capture protocols reduce DNA input requirements, enabling analysis of degraded clinical samples from formalin-fixed tissue archives.
Market Restraints
- High consumables cost structure:Reagent and flow cell expenses dominate per-sample economics, constraining budget-constrained regional hospital laboratories.
- Variant interpretation bottleneck:Shortage of clinical geneticists and bioinformatics specialists limits report turnaround times in diagnostic workflows.
- GDPR data residency requirements:Cross-border patient data transfer restrictions fragment cloud-based analysis pipelines between national jurisdictions.
Strategic Opportunities
- Pharmacogenomic profiling expansion:Drug-gene interaction testing represents underpenetrated clinical application beyond rare disease diagnosis in European hospital networks.
- Polygenic risk score integration:Convergence of exome sequencing with common variant arrays enables combined monogenic and complex disease risk stratification.
- England's NHS Genomic Medicine Service:Centralized procurement and standardized test directories create volume concentration opportunity for qualified platform vendors.
Industry Challenges
- CE-IVDR certification timelines:Extended conformity assessment procedures for software-as-medical-device variant interpretation tools delay product launches.
- Laboratory information system integration:Custom middleware development requirements slow deployment in heterogeneous hospital IT environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Whole Exome Sequencing Market |
| Market Size in 2026 | $625.4 Million |
| Market Size in 2035 | $2,530.13 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Diagnostics, Research, Drug Development, Personalized Medicine End User: Hospitals, Academic Institutions, Research Laboratories, Pharmaceutical Companies Technology: Sanger Sequencing, NGS, Microarray, PCR-based Techniques Distribution Channel: Direct Sales, Online Sales, Third-party Distributors, Others |
| Companies Covered | Illumina Inc., Thermo Fisher Scientific Inc., QIAGEN, F. Hoffmann-La Roche Ltd, Eurofins Scientific SE, Oxford Nanopore Technologies PLC, Agilent Technologies Inc., BGI Group, PerkinElmer Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Whole Exome Sequencing Market Shifts & Advancements
Cloud-native bioinformatics pipelines are displacing on-premise compute infrastructure, while artificial intelligence variant prioritization tools compress analysis timelines. These shifts reshape how European diagnostic laboratories operationalize exome sequencing at scale.
Long-read sequencing platforms are digitizing structural variant detection in exome analysis, capturing copy number alterations and complex rearrangements invisible to short-read methods. Academic medical centers in Germany and the Netherlands are piloting hybrid workflows. This capability is digitizing differential diagnosis for neurodevelopmental disorders where chromosomal microarray previously required separate testing.
EU AI Act risk classification rules are tightening validation requirements for machine learning variant prioritization algorithms deployed in clinical decision support. Manufacturers must document training data provenance and performance across diverse European ancestries. Diagnostic software vendors serving France's HAS-accredited laboratories are restructuring quality management systems to address these conformity obligations.
Hospital network consolidation is concentrating purchasing authority into centralized genomics committees that negotiate multi-year sequencing service contracts. Independent clinical laboratories face exclusion from preferred vendor panels unless they demonstrate interoperability with electronic health record systems. This pattern is most pronounced in England's NHS regional genomic hubs and Spain's autonomous community health systems.
Europe Whole Exome Sequencing Market Segmentation
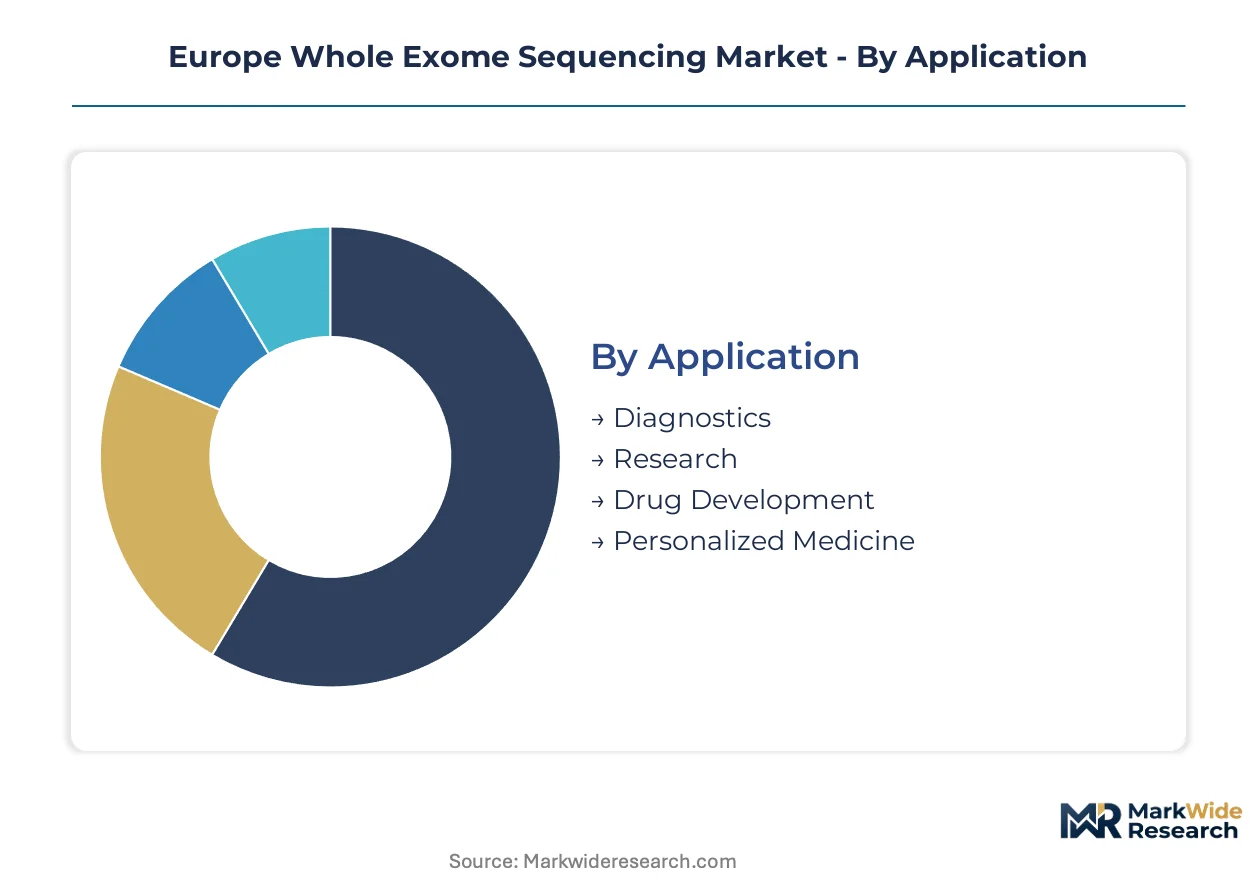
Whole exome sequencing serves distinct operational models across European healthcare systems. Application requirements diverge between clinical diagnostic workflows and research data generation, while procurement channels reflect institutional purchasing authority concentration.
Application:
Clinical use-cases span rare disease confirmation, oncology biomarker discovery, and pharmacogenomic profiling with varying reimbursement eligibility.
- Diagnostics:Hospital laboratories deploy exome sequencing for Mendelian disorder identification and hereditary cancer syndrome screening. Germany's IQWiG and France's HAS increasingly evaluate clinical utility evidence for rare disease test reimbursement, concentrating demand in accredited academic medical centers.
- Research:Cross-border genomic data sharing under the European 1+ Million Genomes Initiative drives biobank network expansion. Research laboratories in the Netherlands and Sweden prioritize population-scale cohort sequencing with federated analysis architectures that respect GDPR data residency constraints.
- Drug Development:Pharmaceutical sponsors integrate exome data into patient stratification strategies for precision oncology trials. EMA companion diagnostic pathways incentivize biomarker co-development with therapeutic candidates.
- Personalized Medicine:Polygenic risk score integration with monogenic findings enables combined disease susceptibility assessment. Pilot programs in England's NHS Genomic Medicine Service test clinical implementation frameworks.
Established volume favors Diagnostics; emerging adoption favors Research.
End User:
Procurement authority concentrates differently across institutional types, shaping vendor contract structures and service model requirements.
- Hospitals:Clinical genetics departments in Germany's university hospital networks operate CAP-accredited laboratories with embedded bioinformatics units. EU MDR conformity requirements for sequencing-based IVDs compress revalidation timelines for existing platforms.
- Academic Institutions:Medical school core facilities balance service provision with method development. Spain's autonomous community health systems consolidate sequencing procurement through regional genomics hubs.
- Research Laboratories:National biobank infrastructures in Denmark and Finland generate population reference datasets. Cloud-native analysis pipelines displace on-premise compute as data volumes scale.
- Pharmaceutical Companies:Contract research organizations in Switzerland and the United Kingdom manage outsourced sequencing for clinical trial patient screening. Centralized vendor qualification programs streamline multi-site study execution.
Hospital procurement dominates current spending; research laboratory expansion shows steepest trajectory.
Technology:
Platform selection trades analytical performance specifications against operational workflow integration requirements.
- Sanger Sequencing:Retains essential utility for variant confirmation and targeted resequencing of specific exons. Small diagnostic laboratories in Italy and Poland maintain capillary electrophoresis capacity for orthogonal validation.
- NGS:Hybridization capture protocols on short-read platforms deliver 20x coverage depth exceeding 99% analytical sensitivity for single nucleotide variant detection. Illumina sequencing chemistry dominates installed base concentration in European academic medical centers.
- Microarray:Chromosomal microarray precedes exome sequencing in neurodevelopmental disorder evaluation workflows. Cost constraints in regional hospital networks preserve array-based first-line testing.
- PCR-based Techniques:Amplicon sequencing approaches enable rapid turnaround for targeted gene panel analysis. Point-of-care applications remain limited by complex library preparation requirements.
NGS platforms command dominant share; long-read sequencing gains traction for structural variant detection.
Distribution Channel:
Channel strategy must align with institutional purchasing committee structures and capital equipment financing preferences.
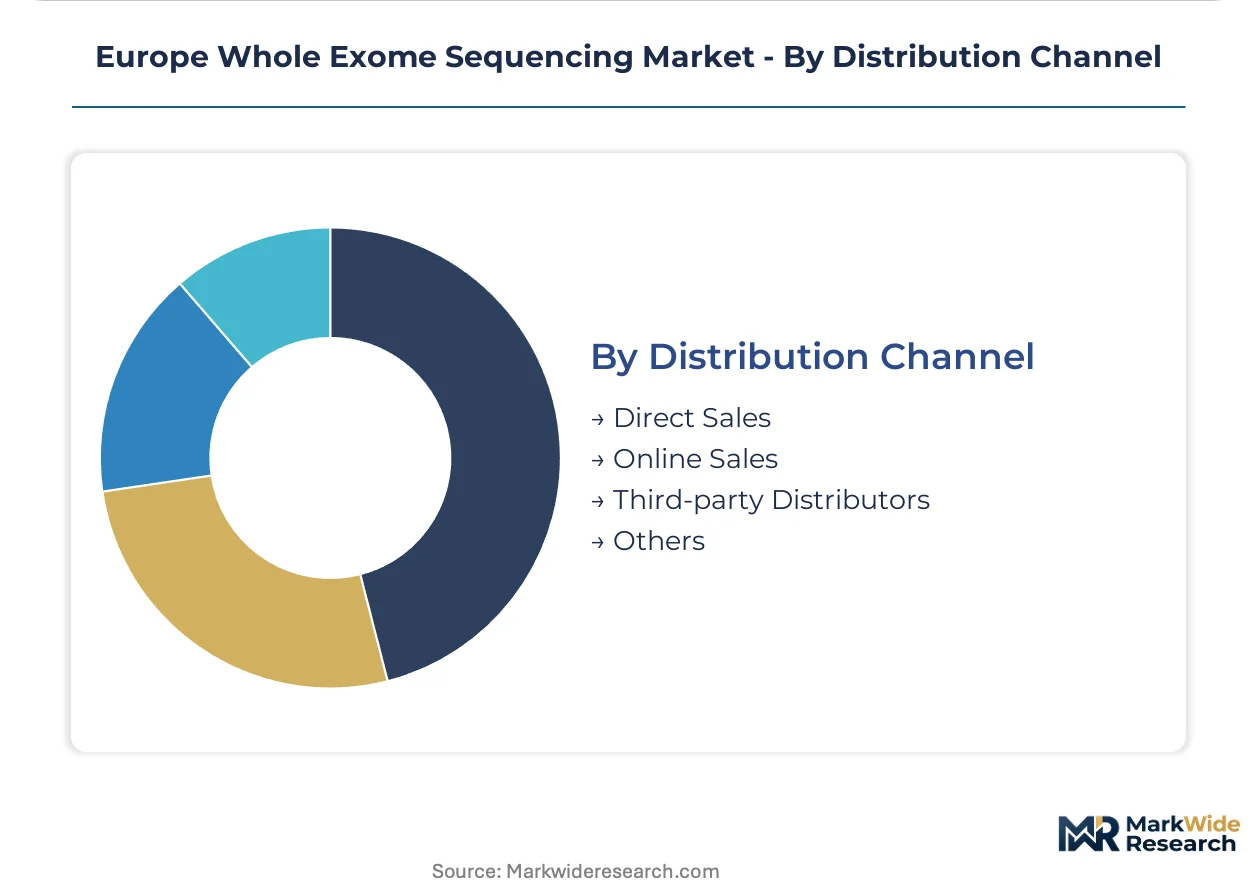
- Direct Sales:Instrument manufacturers deploy field application scientists for workflow optimization in high-volume sequencing centers. Multi-year reagent rental agreements reduce capital barriers for German hospital networks.
- Online Sales:Consumables procurement through e-commerce platforms serves small research groups with predictable demand patterns. France's HAS-accredited laboratories require documented supply chain traceability that constrains pure digital purchasing.
- Third-party Distributors:Regional specialists provide local technical support and inventory management for peripheral hospital laboratories. Distribution partnerships concentrate in Nordic countries with dispersed geographic coverage requirements.
- Others:Group purchasing organizations aggregate demand across England's NHS regional genomic hubs. Centralized procurement frameworks standardize platform selection and service level agreements.
Direct sales relationships secure high-volume accounts; distributor networks extend geographic reach in fragmented markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in Germany, the United Kingdom, and France concentrate purchasing authority for exome sequencing platforms, while research biobanks in the Netherlands and Sweden drive cross-border data generation under EU genomic sharing frameworks.
Germany
University hospital networks in Bavaria and Baden-Württemberg operate CAP-accredited clinical genetics laboratories with embedded bioinformatics units. Germany's IQWiG evaluates clinical utility evidence for rare disease test reimbursement, tightening access criteria for regional hospital laboratories. The Heidelberg and Berlin-Brandenburg precision medicine clusters integrate exome data into oncology workflows through multi-year sequencing service contracts.
United Kingdom
England's NHS Genomic Medicine Service centralizes procurement through seven regional genomic hubs, standardizing test directories and platform selection. NICE health technology assessments determine reimbursement thresholds for clinical exome sequencing in rare disease diagnosis. The Cambridge and London/Southeast clusters concentrate biopharma contract research activity for companion diagnostic development.
France
HAS-accredited hospital laboratories in Île-de-France and Auvergne-Rhône-Alpes face stricter conformity requirements under EU MDR for sequencing-based in vitro diagnostics. The country's national pharmaceutical regulator, ANSM, governs companion diagnostic approvals incorporating exome-derived biomarkers. The Paris-Saclay cluster anchors academic medical center adoption of hybrid capture protocols for oncology patient stratification.
Netherlands
Research laboratories in the Randstad region prioritize population-scale cohort sequencing with federated analysis architectures that respect GDPR data residency constraints. The country's national biobank infrastructure generates reference datasets under the European 1+ Million Genomes Initiative. Eindhoven-based health technology assessment bodies influence cross-border reimbursement policy for genomic diagnostics.
Sweden
National biobank infrastructures in Stockholm and Uppsala drive research laboratory expansion with cloud-native analysis pipelines displacing on-premise compute infrastructure. The country's precision medicine program tests clinical implementation frameworks for polygenic risk score integration with monogenic findings. Nordic distribution partnerships extend geographic coverage for peripheral hospital laboratories with dispersed procurement requirements.
Europe Whole Exome Sequencing Market Competitive Landscape
Channel-controlling players compete with product-specialist players across sequencing instrument, reagent, and bioinformatics software tiers. The vendor base clusters around three strategic archetypes: integrated platform providers with installed base concentration, sample-to-report solution specialists, and variant interpretation software vendors. M&A activity targets bioinformatics capabilities, while multi-year reagent rental agreements reduce capital barriers for hospital network procurement committees.
Among integrated platform providers, Illumina Inc. and Thermo Fisher Scientific Inc. exemplify scale-driven archetypes with field application scientist deployment for workflow optimization in high-volume sequencing centers. QIAGEN occupies a position within the bioinformatics tier, representing specialists in variant interpretation simplification for diagnostic users. These three companies anchor the competitive structure through distinct vectors: instrument installed base, integrated workflow solutions, and clinical decision support software.
| Leading Market Players |
|---|
| Illumina Inc. |
| Thermo Fisher Scientific Inc. |
| QIAGEN |
| F. Hoffmann-La Roche Ltd |
| Eurofins Scientific SE |
| Oxford Nanopore Technologies PLC |
| Agilent Technologies Inc. |
| BGI Group |
| PerkinElmer Inc. |
| Others |
Supply & Pricing Matrix
Heidelberg's precision medicine cluster anchors European reagent manufacturing capacity, concentrating supply-side leverage among three integrated platform providers whose multi-year service contracts with German hospital networks set regional price benchmarks for hybridization capture chemistry and sequencing consumables.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate reagent supply agreements, tying flow cell pricing to semiconductor substrate costs and oligonucleotide synthesis feedstock. Three-tier pricing structure across premium, standard, and economy levels separates CAP-accredited academic medical centers from regional hospital laboratories and research biobank facilities. Cost compression in the economy tier is intensifying because Spain's autonomous community health systems consolidate procurement through regional genomics hubs. Regional hospital laboratories exhibit highest price sensitivity due to fixed diagnostic budgets, while pharmaceutical sponsors demonstrate lowest sensitivity given companion diagnostic co-development timelines.
Supply Chain Analysis
Upstream feedstock for sequencing platforms draws from semiconductor fabrication in Taiwan, oligonucleotide synthesis in Germany, and optical component manufacturing in Japan. Critical inputs include silicon wafers for flow cell substrates, synthetic DNA probes for target enrichment, and laser diodes for signal detection. Single-source vulnerability concentrates in semiconductor-grade silicon supply from East Asian foundries. Distribution runs through direct field application scientist deployment for high-volume sequencing centers, with third-party distributors extending coverage to peripheral hospital laboratories in Nordic countries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
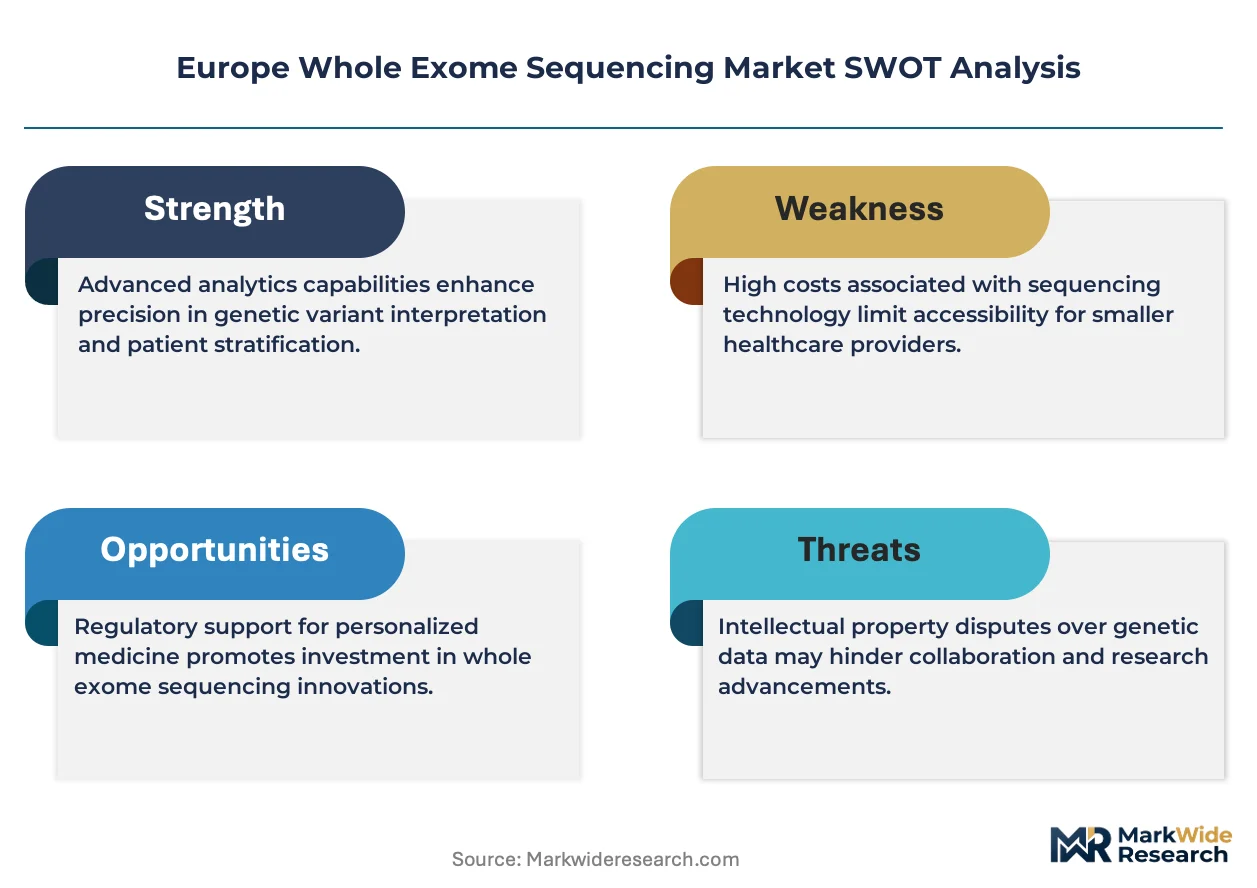
The market's expansion hinges on persistent scarcity of clinical geneticists and bioinformatics specialists capable of variant interpretation at diagnostic throughput scales, creating structural bottlenecks that favor vendors with embedded decision-support software.
For Market Incumbents: Insulate installed base concentration by embedding bioinformatics units within German university hospital networks and securing CE-IVDR certification for variant interpretation tools ahead of EU MDR enforcement timelines. Threat from long-read sequencing platforms necessitates hybrid workflow development. Vertical integration into cloud-native analysis pipelines represents the critical defensive lever. For New Entrants and Emerging Players: Build out pharmacogenomic profiling capabilities for England's NHS Genomic Medicine Service, where centralized procurement creates volume concentration opportunities for qualified platform vendors. The most penetrable segment sits in polygenic risk score integration pilots testing clinical implementation frameworks. Go-to-market angle should emphasize interoperability with electronic health record systems. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because reimbursement standardization across France's HAS, Germany's IQWiG, and England's NICE will concentrate purchasing authority into multi-year sequencing service contracts. Acquisition targets should display bioinformatics software assets with GDPR-compliant federated analysis architectures. Signal to watch is EMA companion diagnostic pathway expansion incorporating exome-derived biomarkers.| Strategic Initiative | Industry Significance |
|---|---|
| CE-IVDR Certification Pathway | Accelerates software-as-medical-device launches under EU MDR conformity requirements for HAS-accredited laboratories. |
| Hospital System Partnership | Secures preferred vendor status within England's NHS regional genomic hubs and Spain's autonomous community networks. |
| Reimbursement Strategy | Aligns clinical utility evidence generation with IQWiG and NICE health technology assessment criteria for rare disease testing. |
| Software Companion Development | Addresses variant interpretation bottlenecks through AI-powered prioritization tools compliant with EU AI Act risk classification. |
| Biobank Network Integration | Enables federated data analysis under European 1+ Million Genomes Initiative while respecting GDPR residency constraints. |
Research Methodology
The analysis maps sequencing platform providers, clinical diagnostic laboratories, research biobank networks, and pharmaceutical sponsors, each validated through laboratory directors, bioinformatics specialists, hospital procurement managers, and regulatory affairs leads. Primary interviews with these stakeholders combined with secondary validation from EMA companion diagnostic filings, EU MDR conformity assessment databases, hospital procurement records, and health technology assessment body publications. Bottom-up instrument installation counts and top-down reimbursement expenditure estimates were triangulated to derive market sizing.
Assumptions held reimbursement eligibility criteria and EU MDR enforcement timelines fixed across the projection horizon, while technology substitution rates and cross-border data sharing participation were varied under sensitivity scenarios. Segmentation dimensions modeled include application type, end-user institution, sequencing technology, and distribution channel, with additional stratification by national regulatory cluster. CAGRs were derived from exponential growth curve fitting to validated base-year estimates and forward expenditure projections, incorporating EMA companion diagnostic approval trajectories and biobank network expansion plans as industry-specific inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by long-read sequencing platform vendors or cloud-native bioinformatics entrants would shift outcomes beyond modeled ranges. Quarterly review of EMA biomarker qualification procedures, IQWiG reimbursement decisions, and GDPR enforcement actions on cross-border data transfers is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Antisense Oligonucleotides Market
Genomics
Global NGS Sample Preparation Market
Genomics
Alagille Syndrome Market
Genomics
Global Microarray Analysis Market
Genomics
Europe DNA Sequencing Products Market
Genomics
Next Generation Sequencing Market
Genomics
Genetic Testing Market
Genomics
Global Genomics Market
Genomics
DNA Gene Chip Market
Genomics
Asia Pacific Pharmacogenetics Testing in Psychiatry/Depression Market
Genomics
Europe Hereditary Cancer Testing Market
Genomics
Genomic Biomarkers Market
Genomics
Next-Generation Sequencing Library Preparation Market
Genomics
Non Invasive Prenatal Testing (NIPT) Market
Genomics
Gene Sequencing Market
Genomics
Spatial Genomics and Transcriptomics Market