
 Global Artificial Intelligence in Genomics Market | 2026-2036
Global Artificial Intelligence in Genomics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Artificial Intelligence in Genomics Market Foresight
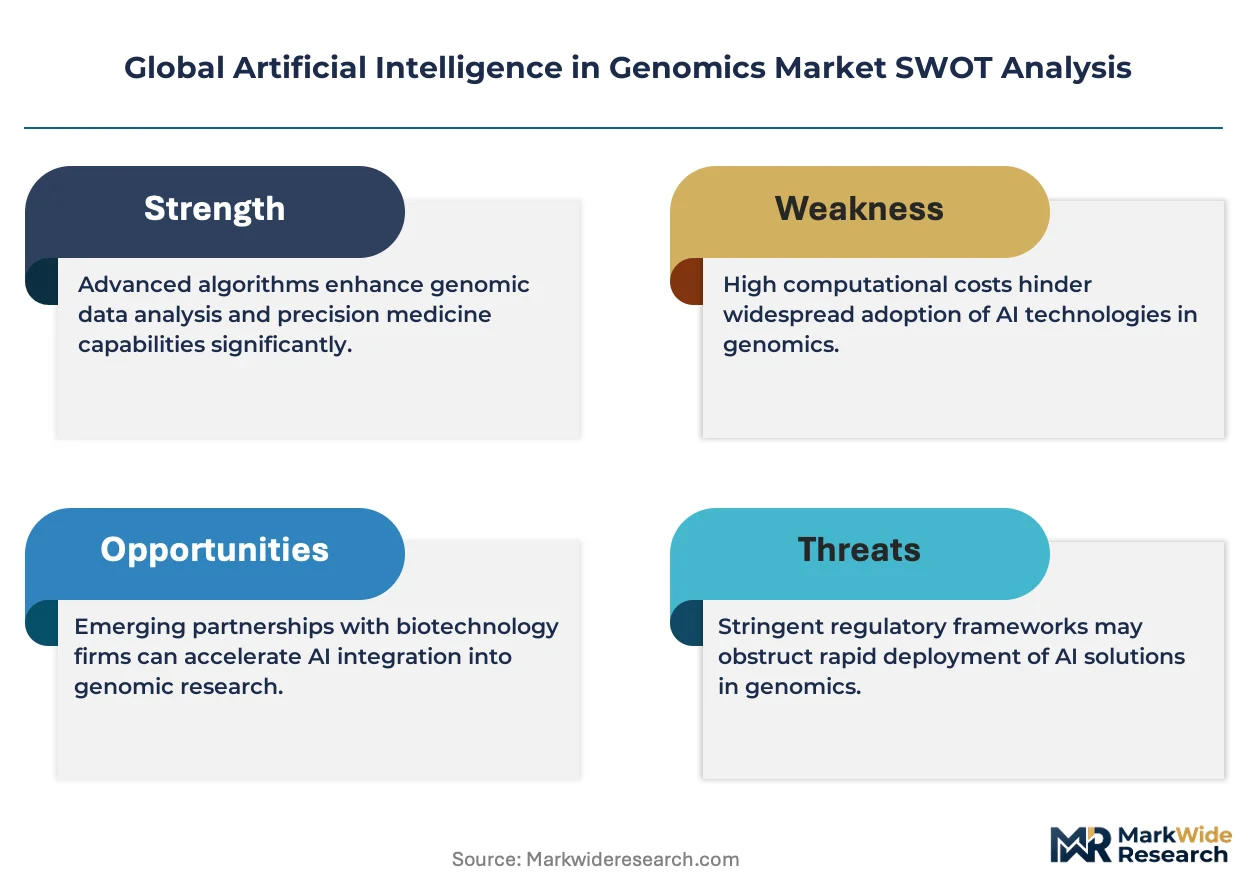
The EU AI Act is recalibrating how genomic AI platforms gain market access across European healthcare systems. Deep Genomics leverages its proprietary AI-driven target discovery engine to anchor early-stage therapeutic pipelines. NVIDIA Corporation dominates GPU-accelerated genomic computing infrastructure, while SOPHiA GENETICS competes through cloud-native variant interpretation networks deployed across diagnostic laboratories.
Artificial intelligence in genomics applies machine learning algorithms, neural architectures, and statistical models to DNA, RNA, and epigenetic datasets, enabling automated variant classification, pathway inference, and therapeutic target identification at throughput scales exceeding manual curation. Cloud-based deployment captures expanding share as research institutes and biotechnology firms prioritize elastic compute for population-scale genomic studies. Predictive modeling and drug discovery within the solution portfolio attract concentrated R&D investment due to pharmaceutical demand for compressed preclinical timelines.
FDA digital health guidance, EMA's qualification opinion pathways for AI biomarkers, and HIPAA data governance requirements collectively shape product validation standards and cross-border data mobility constraints for platform vendors. ISO 13485 and IEC 62304 compliance frameworks further define quality management boundaries for software-as-medical-device genomic tools. Stakeholders must monitor evolving reimbursement codes for AI-augmented molecular diagnostics across national health systems.
Market Dynamics
Foundation model architectures trained on population-scale genomic datasets are compressing target identification timelines from years to months across pharmaceutical R&D pipelines. This computational shift is restructuring competitive advantage away from laboratory scale toward data moats and specialized training corpora.
Growth Catalysts
- NIH All of Us Research Program:The initiative's million-participant genomic dataset provides training foundations for polygenic risk score algorithms. Academic medical centers leverage this resource to validate clinical AI tools.
- GPU-accelerated variant calling:NVIDIA's Clara Parabricks and competing frameworks reduce whole-genome processing from days to hours. Sequencing service providers deploy these toolkits to differentiate turnaround guarantees.
- FDA Pre-Certification for AI/ML:The pathway enables iterative algorithm updates without repeated 510(k) submissions. Diagnostic platform vendors prioritize this regulatory track for competitive positioning.
Market Restraints
- High-performance computing infrastructure costs:Training billion-parameter genomic models requires sustained access to A100/H100 clusters. Mid-tier biotechnology firms face capital constraints for in-house deployment.
- EU AI Act high-risk system classification:Clinical genomic AI applications fall under stringent conformity assessment requirements. Deployment timelines extend 12-18 months for European market entry.
- Interpretable model limitations:Deep neural architectures for variant pathogenicity prediction resist mechanistic explanation. Clinician trust gaps persist against regulatory demands for algorithmic transparency.
Strategic Opportunities
- Multi-omics data fusion:Integrating transcriptomic, proteomic, and metabolomic layers with genomic baselines enables causal pathway inference. Platform vendors with unified data architectures capture premium pricing.
- Saudi Arabia genomic medicine mandate:The national biotechnology strategy prioritizes AI-augmented rare disease diagnosis. International platform providers partner with local health system digitization initiatives.
- Federated learning architectures:Distributed model training across institutional boundaries preserves data sovereignty while pooling statistical power. Privacy-preserving computation unlocks previously inaccessible clinical cohorts.
Industry Challenges
- Computational biology talent scarcity:Hybrid expertise spanning machine learning and molecular genetics commands premium compensation. Recruitment competition intensifies between technology incumbents and emerging biotechnology ventures.
- ISO 13485 quality management implementation:Software-as-medical-device genomic tools require documented design controls and risk management. Early-stage ventures face 18-24 month certification timelines.
- Interoperability with legacy EHR systems:Genomic decision support integration demands HL7 FHIR compliance and custom API development. Health system IT departments prioritize phased rollout over immediate deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Artificial Intelligence in Genomics Market |
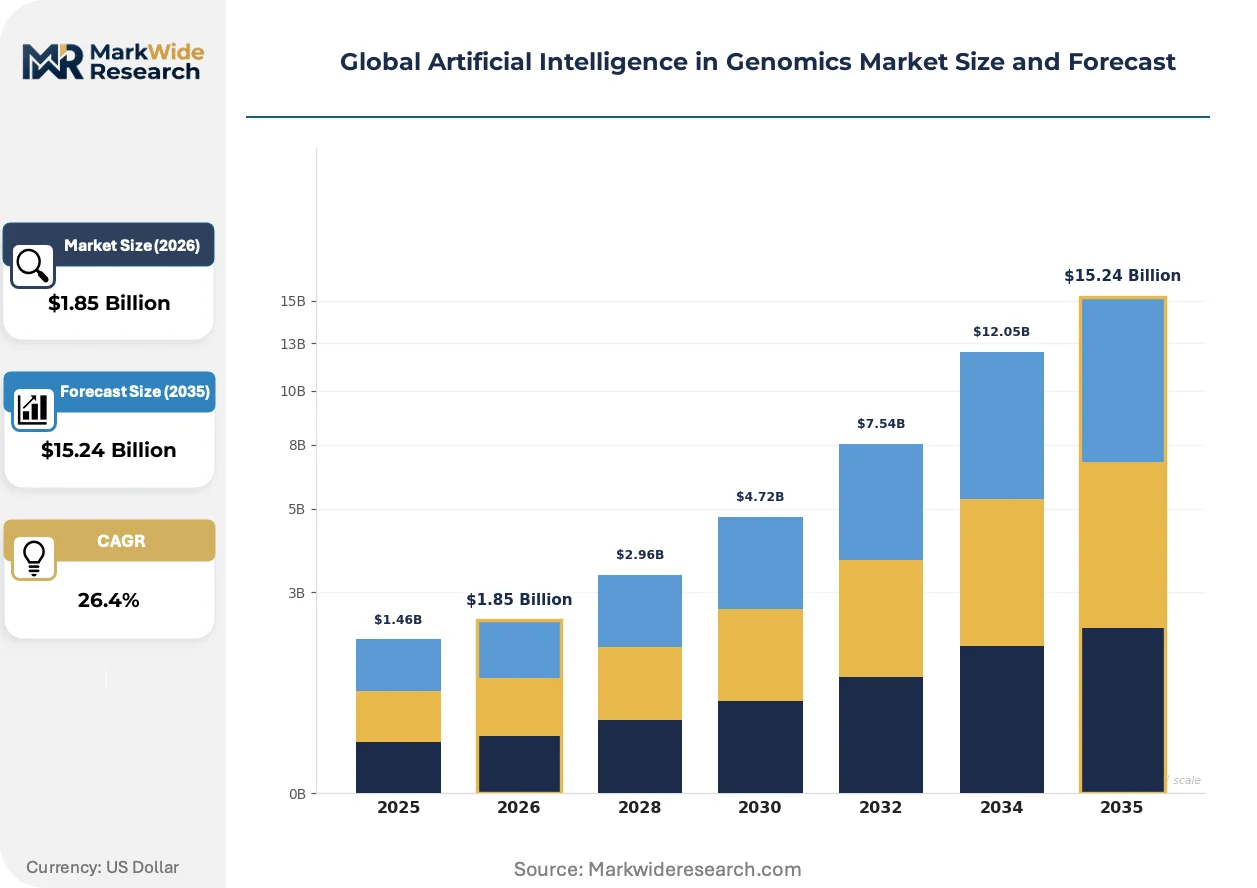
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing Solution/Offering: Genomic Data Analysis, Predictive Modeling, Variant Calling, Drug Discovery, Gene Expression Analysis Application: Precision Medicine, Population Studies, Agrigenomics, Rare Disease Research, Microbial Genomics End User: Research Institutes, Biotechnology Firms, Pharmaceutical Companies, Diagnostic Laboratories, Academic Centers |
| Companies Covered | Deep Genomics, SOPHiA GENETICS, Illumina, Fabric Genomics, Data4Cure, Freenome Holdings, NVIDIA Corporation, IBM, Microsoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Artificial Intelligence in Genomics Market Shifts & Advancements
Transformer architectures originally developed for natural language processing are migrating into nucleotide sequence analysis, enabling attention-based modeling of regulatory element interactions. This architectural convergence is redrawing capability boundaries between generalist AI laboratories and specialized genomics platforms.
Large language models fine-tuned on protein-coding sequences and functional genomics annotations are electrifying therapeutic target prioritization workflows. Biotechnology firms with proprietary CRISPR screening datasets use these models to predict guide RNA efficiency before wet-lab validation. The compression of design-test cycles is reallocating R&D budgets toward computational hypothesis generation.
The EU AI Act's high-risk system requirements are mandating post-market performance monitoring and human oversight protocols for clinical genomic AI. Diagnostic platform vendors must implement continuous accuracy tracking across diverse patient populations. Germany's Federal Institute for Drugs and Medical Devices and France's National Agency for Food, Environmental and Occupational Health Safety are developing coordinated implementation guidance.
Pharmaceutical procurement departments are consolidating molecular diagnostic partnerships under multi-year platform agreements rather than transactional testing contracts. Genomic AI providers respond with outcome-based pricing tied to target validation success rates. This shift is most pronounced in Massachusetts and California, where biotechnology clusters concentrate decision-making authority within centralized sourcing functions.
Global Artificial Intelligence in Genomics Market Segmentation
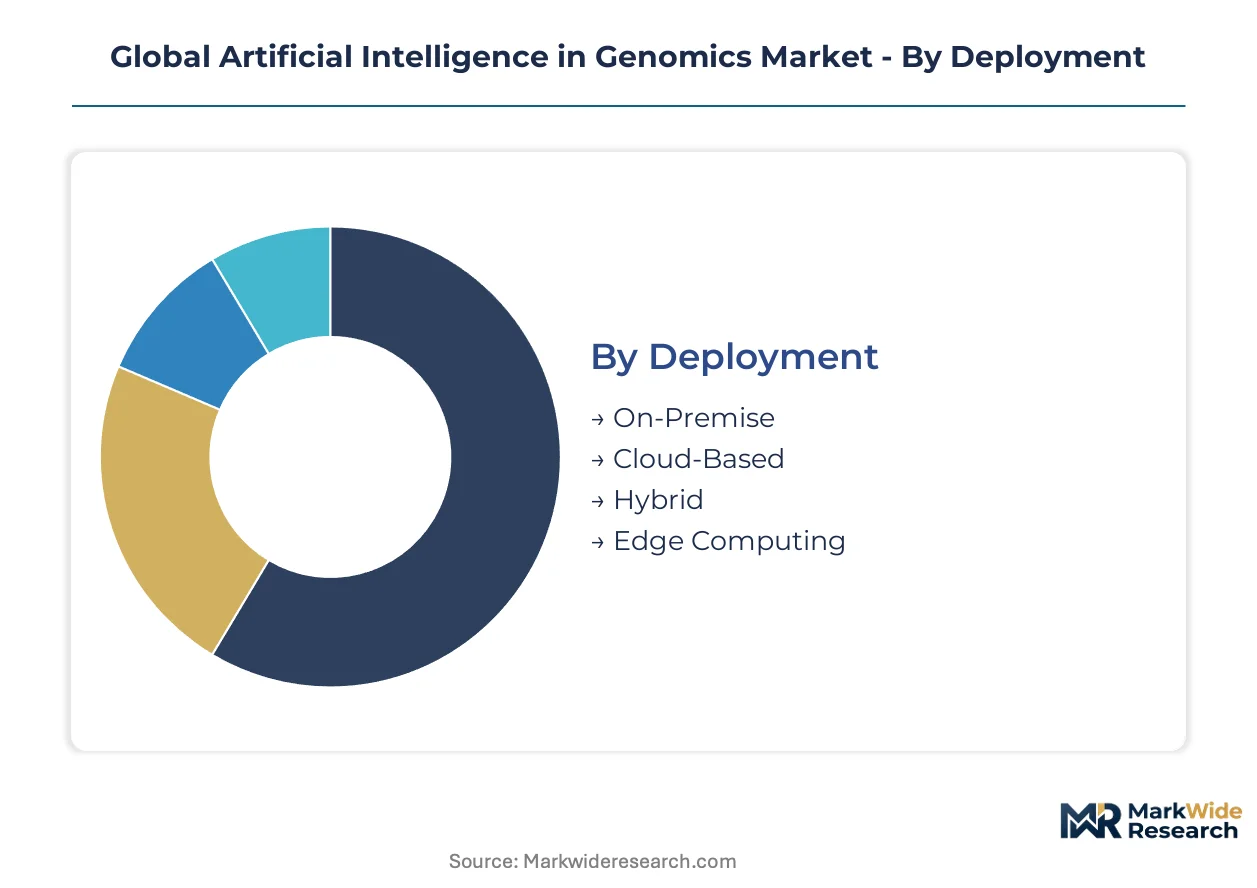
Segmentation in genomic AI reveals how infrastructure choices, solution architectures, and end-user workflows diverge across research and clinical settings. Deployment models determine capital intensity and data sovereignty compliance. Application focus shapes regulatory pathways and reimbursement eligibility.
Deployment:
Pharmaceutical procurement teams weigh total cost of ownership against data control requirements when selecting infrastructure models.
- Cloud-Based:Elastic compute resources enable population-scale genomic studies without capital expenditure. Research institutes in the United States leverage AWS, Google Cloud, and Azure for NIH-funded initiatives requiring burst capacity for polygenic risk score calculations.
- On-Premise:Dedicated GPU clusters within institutional data centers enforce HIPAA compliance and minimize latency for real-time variant interpretation. Academic medical centers with established high-performance computing facilities prefer this model for sensitive patient cohorts.
- Hybrid:Split architectures process de-identified data in cloud environments while retaining identifiable records locally. Biotechnology firms use this approach to satisfy FDA pre-certification data integrity requirements.
- Edge Computing:Distributed processing at sequencing instruments reduces bandwidth costs for high-throughput facilities. Diagnostic laboratories with NovaSeq systems deploy edge nodes for real-time quality control.
Volume sits with Cloud-Based deployments; growth tilts toward Hybrid configurations as compliance complexity increases.
Solution/Offering:
R&D budget allocation follows therapeutic pipeline stage, with early discovery commanding differentiated tooling investments.
- Drug Discovery:AI-driven target identification and lead optimization compress preclinical timelines. Deep Genomics and Recursion Pharmaceuticals anchor proprietary pipelines on these capabilities.
- Predictive Modeling:Polygenic risk algorithms and treatment response classifiers support clinical decision support. Academic centers in Germany and France validate these tools against EMA qualification opinion pathways.
- Genomic Data Analysis:Population-scale variant annotation and pathway enrichment for research consortia.
- Variant Calling:GPU-accelerated germline and somatic mutation detection from sequencing reads.
- Gene Expression Analysis:Transcriptomic quantification and differential expression profiling for functional studies.
Investment concentrates in Drug Discovery; regulatory validation momentum builds fastest around Predictive Modeling.
Application:
Funding source and reimbursement mechanism determine platform commercialization strategy across use cases.
- Precision Medicine:Tumor-normal sequencing and pharmacogenomic dosing guide oncology and cardiology practice. Memorial Sloan Kettering and MD Anderson anchor clinical deployment in the United States.
- Rare Disease Research:Exome and genome sequencing for undiagnosed genetic conditions accelerates diagnostic odyssey resolution. Saudi Arabia's national biotechnology strategy prioritizes AI-augmented rare disease diagnosis.
- Population Studies:Cohort-scale genomic epidemiology for disease architecture discovery.
- Agrigenomics:Crop and livestock breeding optimization through genomic selection.
- Microbial Genomics:Pathogen surveillance and antimicrobial resistance tracking.
Clinical revenue pools deepest in Precision Medicine; public funding expansion favors Rare Disease Research most steeply.
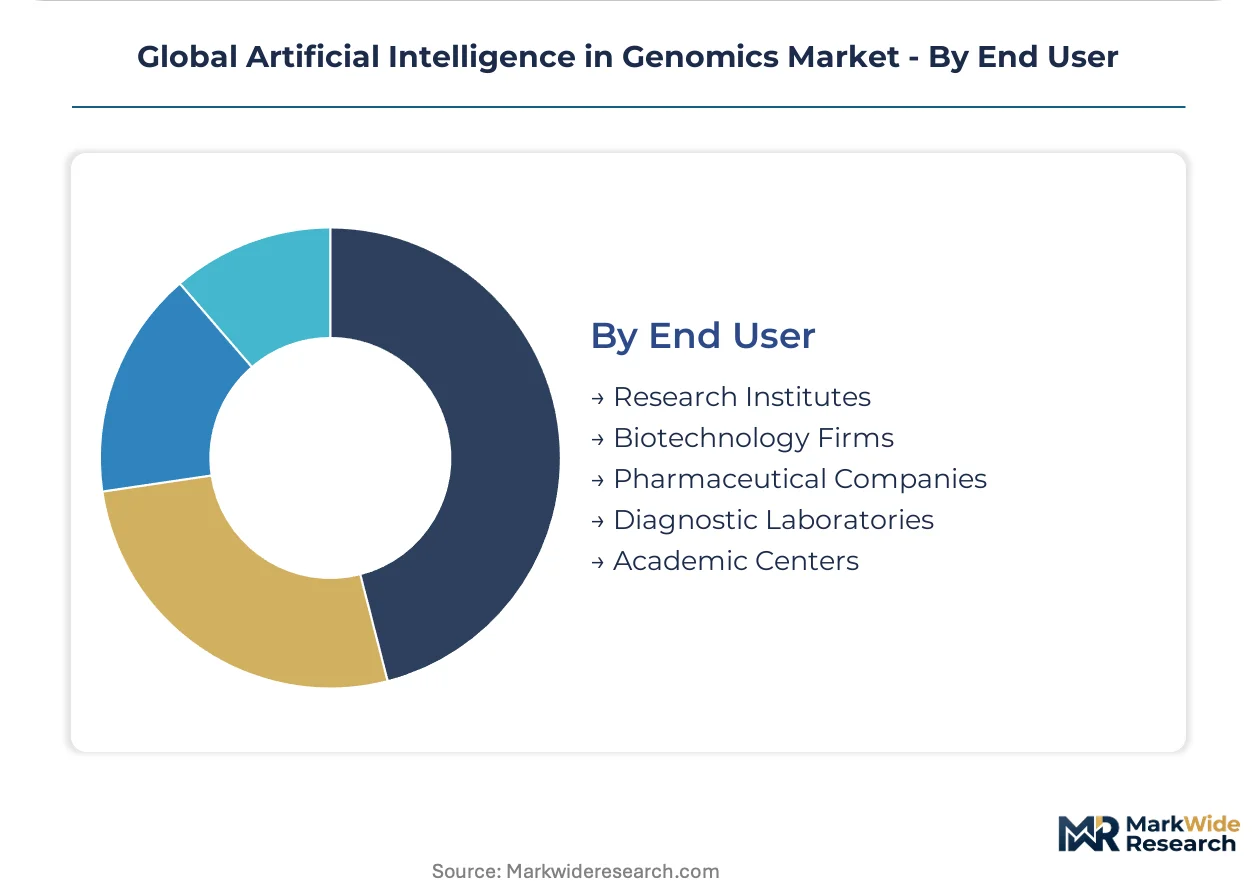
End User:
Procurement sophistication and integration requirements vary sharply across organizational types.
- Pharmaceutical Companies:Enterprise-scale platform agreements with outcome-based pricing tied to target validation success. Roche, Novartis, and Bristol Myers Squibb consolidate vendor relationships under multi-year contracts.
- Research Institutes:Grant-funded access to shared national resources like the NIH All of Us Research Program dataset. The Broad Institute and Sanger Institute operate at terabyte-scale data generation.
- Biotechnology Firms:Venture-backed platform selection prioritizing speed-to-insight over total cost.
- Diagnostic Laboratories:Regulatory-compliant variant interpretation for clinical reporting.
- Academic Centers:Teaching hospital integration of genomic decision support into residency workflows.
Contract value peaks with Pharmaceutical Companies; platform adoption velocity runs highest among Biotechnology Firms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates disproportionate platform revenue while Germany and China scale computational infrastructure fastest. Consumption concentrates in pharmaceutical R&D clusters; production of GPU-accelerated systems tilts toward East Asian semiconductor foundries.
United States
The NIH All of Us Research Program furnishes million-participant genomic datasets for algorithm training. FDA Pre-Certification pathways enable iterative AI/ML updates without repeated 510(k) submissions. Memorial Sloan Kettering and MD Anderson anchor clinical deployment in Greater Boston and Houston, where pharmaceutical procurement teams consolidate multi-year platform agreements.
Germany
Federal Institute for Drugs and Medical Devices coordinates EU AI Act implementation guidance for high-risk clinical genomic systems. Heidelberg and Munich academic medical centers validate predictive modeling tools against EMA qualification opinion pathways. The country's national pharmaceutical regulator extends deployment timelines 12-18 months for conformity assessment completion.
China
NMPA digital health guidance shapes validation standards for AI-augmented molecular diagnostics. Shenzhen and Shanghai biotechnology clusters prioritize elastic compute for population-scale studies. The country's national pharmaceutical regulator accelerates local platform commercialization through streamlined review tracks for software-as-medical-device tools.
Saudi Arabia
National biotechnology strategy mandates AI-augmented rare disease diagnosis across health system digitization initiatives. SFDA alignment with international quality management frameworks enables cross-border data mobility for federated learning architectures. Riyadh and Eastern Province health clusters partner with international platform providers for diagnostic infrastructure deployment.
United Kingdom
Genomics England furnishes population-scale datasets for polygenic risk score algorithm development. MHRA recognition of FDA pre-certification pathways accelerates transatlantic platform commercialization. London and Cambridge research institutes operate at terabyte-scale data generation, anchoring European validation workflows for cloud-native variant interpretation networks.
Global Artificial Intelligence in Genomics Market Competitive Landscape
The competitive structure tilts toward technology incumbents with captive GPU infrastructure and specialized biotechnology ventures with proprietary training corpora. Platform vendors fragment across cloud-native interpretation networks, on-premise diagnostic systems, and pharmaceutical-facing discovery engines. Two strategic archetypes dominate: infrastructure-anchored compute providers and data-moated therapeutic discovery platforms. Competitive moves concentrate on federated learning partnerships and outcome-based pricing tied to target validation success rates.
Within the specialized discovery tier, Deep Genomics and SOPHiA GENETICS exemplify contrasting positioning strategies. Deep Genomics anchors early-stage therapeutic pipelines on proprietary AI-driven target identification engines. SOPHiA GENETICS occupies a position across cloud-native variant interpretation networks deployed through diagnostic laboratory partnerships. NVIDIA Corporation represents the infrastructure-anchored archetype, supplying GPU-accelerated genomic computing frameworks that compress whole-genome processing timelines.
| Leading Market Players |
|---|
| Deep Genomics |
| SOPHiA GENETICS |
| Illumina |
| Fabric Genomics |
| Data4Cure |
| Freenome Holdings |
| NVIDIA Corporation |
| IBM |
| Microsoft |
| Others |
Supply & Pricing Matrix
Performance-grade bifurcation between FDA pre-certified platforms and uncertified research tools manifests in subscription premiums exceeding threefold multiples, with supply chain configurations tracking certification tier through dedicated quality management infrastructure and audit-ready documentation systems.
Pricing Analysis
Margin tightening in cloud-native variant interpretation reflects GPU cluster rental cost pass-through from AWS, Google Cloud, and Azure. Three-tier pricing structure across premium, standard, and economy levels separates FDA pre-certified diagnostic modules from research-grade analytics and uncertified open-source alternatives. Pharmaceutical procurement teams demonstrate lowest price sensitivity given outcome-based contracts tied to target validation success, while academic medical centers face highest budget constraint pressure from grant-funded operating budgets.
Supply Chain Analysis
Dual-sourcing mandates from pharmaceutical quality departments require qualified secondary suppliers for GPU-accelerated computing hardware, with NVIDIA A100/H100 clusters drawing from Taiwan Semiconductor Manufacturing Company foundry output and Samsung alternative qualification programs. Raw material dependencies center on advanced node semiconductors, high-bandwidth memory modules, and specialized cooling systems. Single-source vulnerability concentrates in TSMC's 4nm/5nm capacity allocation for AI training chips. Distribution runs through direct enterprise sales teams for pharmaceutical accounts and channel partners for diagnostic laboratory segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GPU cluster availability constraints prop pricing power for infrastructure-anchored vendors, with A100/H100 supply rationing extending pharmaceutical procurement timelines and compressing buyer negotiation leverage.
For Market Incumbents: Cement data moat advantages through exclusive partnerships with NIH All of Us Research Program and Genomics England cohorts, locking out emerging competitors from population-scale training corpora. Invest in ISO 13485 certification expansion to defend against regulatory upstarts exploiting FDA pre-certification pathway acceleration. Priority lever rests on federated learning network density to institutionalize switching costs across diagnostic laboratory customers. For New Entrants and Emerging Players: Cloud-native deployment routes through AWS Marketplace and Google Cloud Partner Network offer lowest-friction customer acquisition for mid-tier biotechnology firms underserved by enterprise sales teams. White-space concentrates in Saudi Arabia rare disease diagnostic infrastructure and hybrid deployment configurations satisfying EU AI Act data sovereignty requirements. Go-to-market angle emphasizes outcome-based pricing with zero upfront infrastructure commitment. For Investors and Strategic Acquirers: Re-rating potential sits with specialized discovery platforms possessing proprietary CRISPR screening datasets given therapeutic pipeline validation inflections. Long-term viability favors vendors with captive training corpora over pure infrastructure plays facing hyperscaler competition. Signal to watch: FDA pre-certification pathway enrollment velocity as predictor of commercialization timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Partnership | Privacy-preserving model training unlocks previously inaccessible clinical cohorts across institutional boundaries. |
| FDA Pre-Certification Enrollment | Iterative algorithm updates without repeated submissions compress diagnostic platform commercialization timelines. |
| GPU Cluster Capacity Reservation | Guaranteed A100/H100 access insulates pharmaceutical R&D contracts from hyperscaler demand surges. |
| Multi-Omics Data Architecture | Unified transcriptomic and proteomic integration commands premium pricing from pathway inference customers. |
| EU AI Act Conformity Assessment | Early high-risk system classification completion secures 12-18 month first-mover advantage in European markets. |
Research Methodology
Multi-period observation of NIH funding allocation patterns, FDA pre-certification enrollment velocity, and GPU cluster pricing trends anchored the trend analysis, supplemented by interviews with computational biology directors, diagnostic laboratory medical directors, pharmaceutical R&D procurement leads, and cloud infrastructure solution architects. Secondary validation drew from ClinicalTrials.gov genomic AI protocol registrations, FDA 510(k) submission databases, EMA qualification opinion track records, and hyperscaler healthcare vertical revenue disclosures. Bottom-up segmentation modeling triangulated against top-down pharmaceutical R&D budget allocation estimates.
Input-output matrices mapped deployment model adoption rates, solution type R&D investment flows, application area reimbursement code expansions, and end-user procurement sophistication indices across the projection horizon. CAGRs derived from segment-level growth rate reconciliation with aggregate market boundary conditions. Industry-specific forecast inputs incorporated NIH All of Us dataset release schedules and EU AI Act implementation guidance publication timelines.
The model holds under sustained NIH funding commitments and stable GPU supply chain conditions; deviation in semiconductor export restrictions or pharmaceutical R&D budget contraction would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Apolipoprotein Test Market
Genomics
Pharmacogenomics Technology Market
Genomics
Global Whole Genome Sequencing (WGS) Market
Genomics
Cancer-Focused Genetic Testing Services Market
Genomics
Global Hereditary Cancer Testing Market
Genomics
Microarray Scanners Market
Genomics
North America Whole Exome Sequencing Market
Genomics
Molecular Breeding Market
Genomics
Latin America Gene Expression Market
Genomics
Genome Sequencing Market
Genomics
Direct-To-Consumer (DTC) Genetic Testing Market
Genomics
Mitochondrial DNA Market
Genomics
Transcriptomics Technologies Market
Genomics
Latin America Next Generation Sequencing Market
Genomics
Global Gene Expression Market
Genomics
SNP Genotyping Market