
 Targeted Protein Degradation Market | 2026-2036
Targeted Protein Degradation Market Size, Share, and Industry Trends Forecast 2026-2036
Targeted Protein Degradation Market Insights
Project finance partnerships between biotech innovators and large pharmaceutical backers is reconfiguring competitive entry in targeted protein degradation. Arvinas leverages its platform collaborations to sustain clinical-stage momentum across oncology indications. Bristol Myers Squibb anchors its position through deep integration of molecular glue assets into existing immuno-oncology infrastructure. Kymera Therapeutics competes by specializing in tissue-specific E3 ligase programs that differentiate its pipeline from broader PROTAC approaches.
Targeted protein degradation employs heterobifunctional small molecules that hijack cellular ubiquitin-proteasome machinery to eliminate disease-causing proteins, with PROTACs typically spanning 700-1100 Daltons to achieve simultaneous target and E3 ligase engagement. Cancer Therapies commands the largest revenue pool given the concentration of clinical trials in hematologic malignancies and solid tumors, while Molecular Glue platforms attract disproportionate R&D investment due to their simpler chemistry and oral bioavailability advantages. The technology dimension shows CRISPR-enabled target validation accelerating preclinical timelines, though Antibody-Drug Conjugates occupy a parallel track that occasionally competes for the same oncology budgets.
FDA breakthrough therapy designations and EMA PRIME eligibility reshape development economics by compressing regulatory review periods for qualifying degraders. The FDA maintains stringent chemistry, manufacturing, and controls standards for bifunctional molecules, while REACH compliance in Europe governs novel synthetic intermediates used in degraders. Stakeholders must monitor how emerging FDA guidance on protein degradation modalities interacts with existing small-molecule frameworks to anticipate approval pathway clarity.
Market Dynamics
Project finance partnerships between biotech innovators and large pharmaceutical backers are reconfiguring competitive entry in targeted protein degradation, compressing development timelines while concentrating risk capital in platforms with demonstrated E3 ligase engineering capabilities.
Growth Catalysts
- FDA breakthrough therapy designations:These compress regulatory review periods for qualifying degraders, accelerating path-to-market for oncology candidates. The designation triggers intensive agency guidance that reduces protocol amendment cycles.
- CRISPR-enabled target validation:This technology accelerates preclinical timelines by enabling rapid knockout confirmation of protein dependencies. Pharmaceutical discovery teams now integrate CRISPR screening at lead optimization stage.
- Venture funding concentration in United States:Deep capital pools in Boston and San Francisco biotech clusters sustain platform-scale investments that European and Asian ecosystems cannot yet match.
Market Restraints
- Complex chemistry manufacturing:Bifunctional molecules spanning 700-1100 Daltons require specialized synthetic intermediates with limited supplier base, creating input cost volatility and capacity constraints.
- REACH compliance in Europe:Novel synthetic intermediates used in degrader production face extended registration timelines and toxicity testing requirements that delay EU market entry.
- Antibody-Drug Conjugate competition:ADCs occupy parallel oncology budgets with established reimbursement pathways, creating substitution threat for first-in-class degraders in hematologic malignancies.
Strategic Opportunities
- Underserved neurodegenerative applications:Blood-brain barrier penetrant degraders for tau and alpha-synuclein targets remain preclinical white space with limited competitive intensity.
- EMA PRIME eligibility:Accelerated assessment pathways for innovative medicines create regulatory tailwind for European market access, complementing FDA momentum.
- Tissue-specific E3 ligase programs:Convergence of ligase engineering with organ-selective delivery technologies enables differentiated pipelines beyond oncology.
Industry Challenges
- E3 ligase biochemist scarcity:The specialized protein engineering talent required for novel ligase discovery concentrates at a handful of academic centers, constraining platform expansion.
- CMC standardization gaps:FDA maintains stringent chemistry, manufacturing, and controls standards for bifunctional molecules without established ICH guidelines, creating compliance timeline uncertainty.
- Intellectual property thickets:Overlapping patent estates covering PROTAC linker geometries and warhead chemistries generate licensing complexity that delays program initiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Targeted Protein Degradation Market |
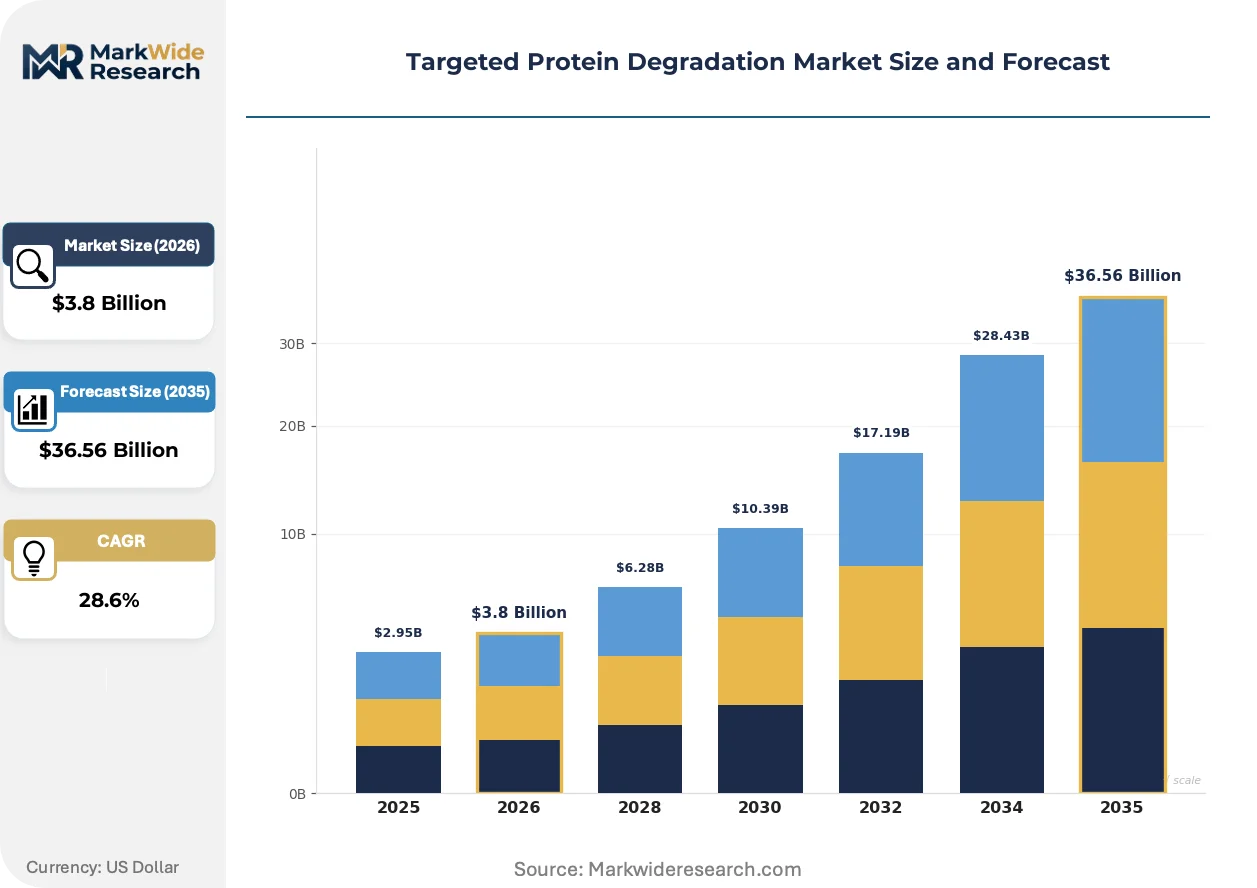
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $36.56 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PROTACs, Molecular Glue, Degraders, Small Molecule Drugs Technology: CRISPR, RNA Interference, Antibody-Drug Conjugates, Synthetic Biology Application: Cancer Therapies, Autoimmune Diseases, Neurological Disorders, Infectious Diseases End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Contract Research Organizations |
| Companies Covered | Arvinas, Bristol Myers Squibb, Kymera Therapeutics, Nurix Therapeutics, C4 Therapeutics, AstraZeneca, BPS Bioscience, LifeSensors, Promega Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Targeted Protein Degradation Market Trends and Innovations
Degrader modality engineering is actively reshaping competitive positioning as platforms differentiate through ligase repertoire depth and tissue-selective delivery capabilities rather than target portfolio breadth alone.
PROTAC molecular design is migrating from conventional cereblon-recruiting architectures toward alternative E3 ligase harnessing, including VHL and IAP-directed systems that expand the druggable target space beyond established oncology dependencies. Mid-stage biotech platforms are adopting these expanded ligase toolkits to differentiate from first-generation competitors. This migration from cereblon-centric approaches is compressing the timeline for target-class expansion into immunology and virology applications.
REACH compliance in Europe governs novel synthetic intermediates used in degrader manufacturing, imposing extended substance registration requirements that reshape supply chain geography toward established chemical producers with regulatory affairs infrastructure. The regulation forces reformulation of intermediate sourcing strategies. Small-molecule CDMOs in Germany and Switzerland are consolidating advantage through pre-registered compound libraries that bypass new substance notification delays.
Pharmaceutical procurement of degrader discovery services is compressing toward integrated platform partnerships rather than fee-for-service target validation. Biotechnology innovators are disintermediating traditional CRO relationships through multi-year collaboration structures with large-cap pharmaceutical partners. This pattern concentrates most visibly in the United States, where venture-backed platforms leverage existing pharmaceutical infrastructure to accelerate IND-enabling studies.
Targeted Protein Degradation Market Segmentation
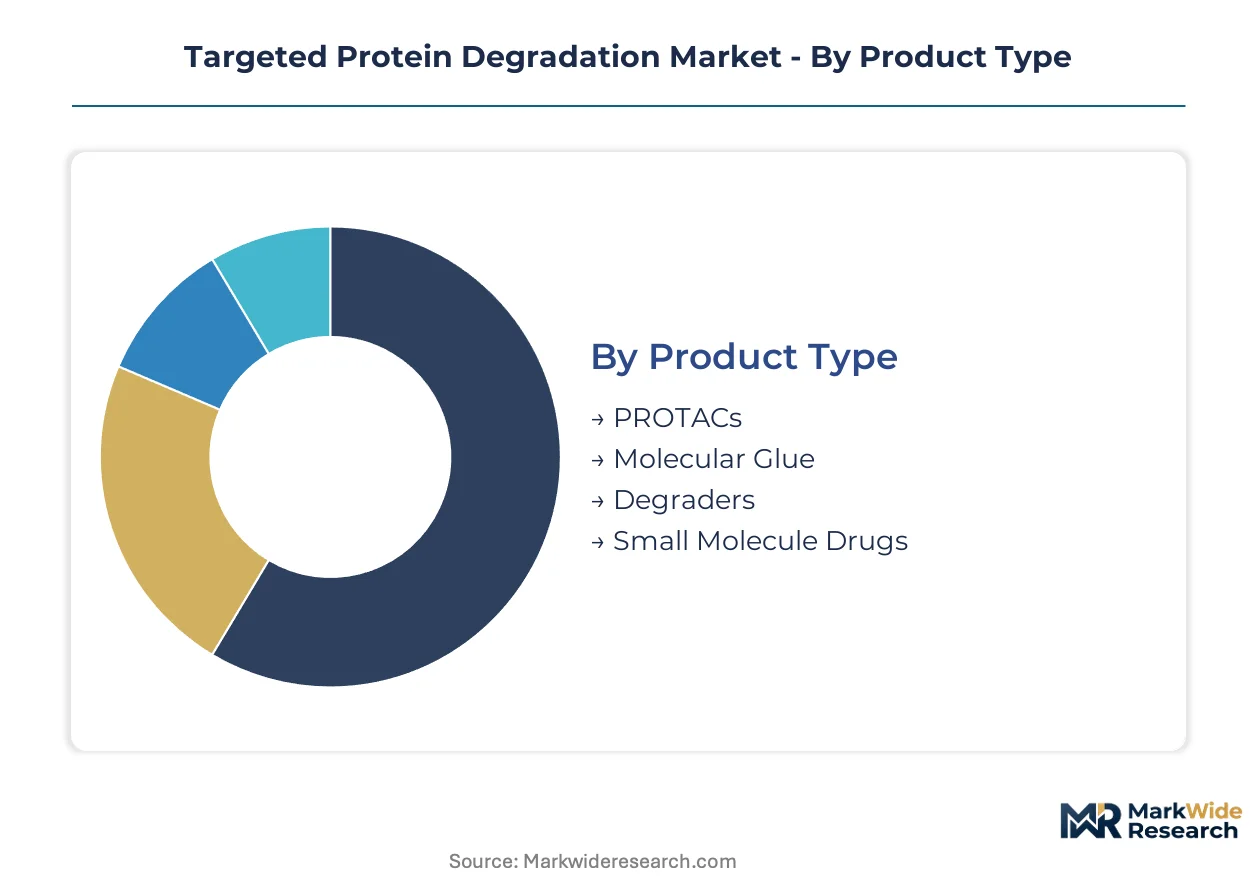
Targeted protein degradation modalities fragment across distinct technical architectures and therapeutic applications, with each segment demanding specialized manufacturing capabilities and regulatory pathways. Understanding these divisions reveals where capital deployment concentrates and which platforms face substitution pressures from competing therapeutic classes.
Product Type:
Mature bifunctional architectures dominate current clinical pipelines, while emerging modalities reshape competitive differentiation through simplified chemistry and expanded target accessibility.
- PROTACs:Heterobifunctional constructs spanning 700-1100 Daltons that simultaneously engage disease targets and E3 ligases through optimized linkers. Demand concentrates in United States oncology programs where venture funding sustains platform-scale investments, though complex synthesis creates manufacturing bottlenecks at CDMOs with limited bifunctional expertise.
- Molecular Glue:Monovalent small molecules that remodel E3 ligase substrate receptors to induce neo-substrate degradation. These compounds attract disproportionate R&D investment from Bristol Myers Squibb and large pharmaceutical partners due to superior oral bioavailability and simpler synthetic routes compared to bifunctional alternatives.
- Degraders:Encompasses emerging modality classes including lysosome-targeting chimeras and autophagy-tethering compounds that operate outside ubiquitin-proteasome pathways.
- Small Molecule Drugs:Traditional enzymatic inhibitors that compete for the same oncology budgets and patient populations, occasionally serving as comparator arms in degrader clinical trials.
PROTACs retain volume leadership; Molecular Glue holds the steepest expansion curve.
Technology:
Cost tier stratification separates capital-intensive platform technologies from accessible research tools, with premium-priced modalities commanding exclusive licensing arrangements.
- CRISPR:Genome editing systems enabling rapid target validation through knockout confirmation of protein dependencies. Pharmaceutical discovery teams integrate CRISPR screening at lead optimization stage, compressing preclinical timelines for degrader candidate selection.
- RNA Interference:Gene silencing mechanisms that operate orthogonally to protein degradation, occasionally competing for the same target validation budgets within biotechnology research programs.
- Antibody-Drug Conjugates:Targeted delivery systems occupying parallel oncology development tracks with established reimbursement pathways, creating direct budget competition for hematologic malignancy indications.
- Synthetic Biology:Engineered biological systems for producing novel E3 ligase variants and ubiquitin pathway components that expand the druggable target space beyond endogenous machinery.
CRISPR dominates current research expenditure; Synthetic Biology is gaining share fastest through ligase engineering applications.
Application:
Customer type concentration varies sharply across therapeutic areas, with pharmaceutical companies driving oncology development while biotechnology firms pioneer neurodegenerative applications.
- Cancer Therapies:Hematologic malignancies and solid tumors command the largest revenue pool given clinical trial concentration and FDA breakthrough therapy designation frequency. Arvinas and Kymera Therapeutics anchor development in this segment through platform collaborations with large pharmaceutical backers.
- Autoimmune Diseases:Immunology applications remain preclinical white space with limited competitive intensity, though tissue-specific E3 ligase programs are beginning to address selective immune cell targeting.
- Neurological Disorders:Blood-brain barrier penetrant degraders for tau and alpha-synuclein targets represent underserved territory with high unmet need and limited existing competitive solutions.
- Infectious Diseases:Viral protein degradation applications exploit host ubiquitin machinery to eliminate pathogen factors, with CRISPR-enabled target validation accelerating preclinical timelines for emerging viral threats.
Cancer Therapies retain volume leadership; Neurological Disorders hold the steepest expansion curve.
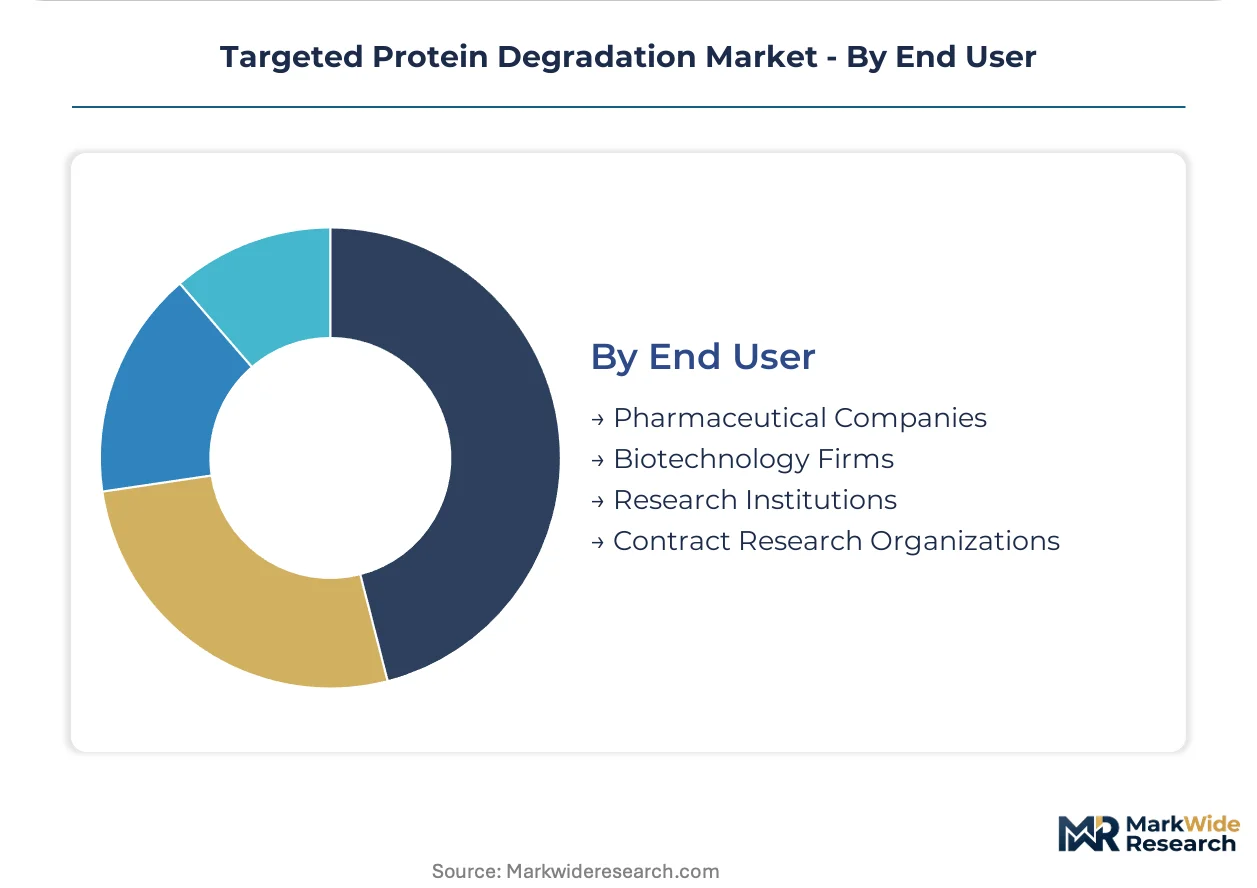
End User:
Geography determines procurement patterns, with United States-based organizations accessing deeper venture funding pools than European or Asian counterparts.
- Pharmaceutical Companies:Large-cap organizations including Bristol Myers Squibb integrate molecular glue assets into existing immuno-oncology infrastructure, driving adoption through internal discovery pipeline expansion.
- Biotechnology Firms:Venture-backed platforms in Boston and San Francisco clusters specialize in tissue-specific E3 ligase programs that differentiate from broader PROTAC approaches.
- Research Institutions:Academic centers concentrate the specialized protein engineering talent required for novel ligase discovery, constraining platform expansion through E3 ligase biochemist scarcity.
- Contract Research Organizations:Traditional fee-for-service relationships are disintermediated as biotechnology innovators pursue multi-year collaboration structures directly with pharmaceutical partners.
Pharmaceutical Companies retain volume leadership; Biotechnology Firms hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The targeted protein degradation trade flows reflect specialized pharmaceutical manufacturing concentration, with the United States exporting platform technologies while importing clinical-grade intermediates from established chemical producers. Germany and Switzerland anchor European supply chains through pre-registered compound libraries. Asian markets are expanding import demand for research tools as domestic biotechnology ecosystems mature.
United States
Venture funding pools in Boston and San Francisco sustain platform-scale investments that European ecosystems cannot yet match. The FDA breakthrough therapy designation program compresses regulatory review periods for qualifying degraders, accelerating path-to-market timelines. Cambridge, Massachusetts hosts the deepest concentration of E3 ligase biochemistry talent, constraining global platform expansion through specialized human capital scarcity.
Germany
Small-molecule CDMOs consolidate advantage through REACH-compliant intermediate libraries that bypass new substance notification delays. The country's national pharmaceutical regulator maintains stringent chemistry, manufacturing, and controls standards for bifunctional molecules without established ICH guidelines. Frankfurt and Basel-adjacent chemical producers in the Rhine-Main region are consolidating contract manufacturing relationships with American biotechnology innovators.
Switzerland
Swissmedic accelerated assessment pathways complement FDA momentum for innovative medicines seeking European market access. Basel-centered pharmaceutical infrastructure integrates molecular glue assets into existing immuno-oncology development frameworks. The Lake Geneva region attracts disproportionate R&D investment due to superior oral bioavailability chemistry capabilities compared to bifunctional alternatives.
United Kingdom
Research institutions concentrate specialized protein engineering talent required for novel ligase discovery, though Brexit-related regulatory divergence creates compliance timeline uncertainty. The Medicines and Healthcare products Regulatory Agency maintains independent chemistry standards that occasionally diverge from EMA frameworks. The Oxford-Cambridge-London golden triangle anchors CRISPR-enabled target validation services that compress preclinical timelines for emerging biotechnology platforms.
Japan
PMDA regulatory pathways for first-in-class degraders face extended review periods compared to breakthrough-designated American counterparts, delaying market entry for domestic patients. METI industrial policy supports synthetic biology investments for engineered E3 ligase variant production. The Kanto region around Tokyo hosts the primary concentration of pharmaceutical procurement relationships with United States-based platform companies.
Targeted Protein Degradation Market Competitive Landscape
On the supply side, the industry is consolidating around platforms with demonstrated E3 ligase engineering capabilities and established pharmaceutical partnerships. The vendor base separates into three strategic archetypes: clinical-stage biotechnology innovators, large-cap pharmaceutical integrators, and specialized research tool providers. Dominant competitive moves include multi-year collaboration structures that disintermediate traditional CRO relationships, and backward integration into captive synthetic intermediate production to bypass supplier capacity constraints.
Within the clinical-stage biotechnology tier, Arvinas and Kymera Therapeutics occupy positions exemplifying platform-scale investment sustainability through pharmaceutical backing. Bristol Myers Squibb anchors the large-cap pharmaceutical integrator archetype. These three entities represent the competitive concentration visible in partnership-driven market development, with each occupying distinct positioning around bifunctional architectures, tissue-specific ligase programs, and molecular glue integration respectively.
| Leading Market Players |
|---|
| Arvinas |
| Bristol Myers Squibb |
| Kymera Therapeutics |
| Nurix Therapeutics |
| C4 Therapeutics |
| AstraZeneca |
| BPS Bioscience |
| LifeSensors |
| Promega Corporation |
| Others |
Pricing and Supply Chain Analysis
The trans-Atlantic pharmaceutical freight corridor connecting Basel and Boston transmits cost volatility from European intermediate suppliers directly into United States CDMO pricing tiers, compressing margins for bifunctional molecule producers while amplifying price differentiation between cereblon-centric and expanded-ligase platform offerings.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the targeted protein degradation market. Price differentiation rests on ligase engineering sophistication and FDA breakthrough designation status, with tissue-specific E3 programs commanding premiums over conventional PROTAC architectures. Cost compression in standard-tier molecular glue manufacturing is intensifying because Bristol Myers Squibb and large pharmaceutical partners are consolidating procurement volumes. Biotechnology firms with preclinical-stage assets exhibit highest price sensitivity, while clinical-stage platforms with demonstrated partnerships show least elasticity.
Supply Chain Analysis
Contract manufacturing concentration among German and Swiss small-molecule CDMOs with REACH-compliant intermediate libraries dominates upstream capacity for bifunctional degrader production. Raw material dependencies center on novel synthetic linkers, cereblon-binding warheads, and VHL-recruiting ligands sourced from specialized chemical producers. Single-source vulnerability in E3 ligase biochemist talent pools constrains platform expansion timelines. Distribution runs through integrated pharmaceutical partnerships rather than traditional fee-for-service CRO relationships, with multi-year collaboration structures disintermediating conventional procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The targeted protein degradation market is entering a cyclical recovery phase as FDA breakthrough therapy designations compress development timelines and reactivate venture deployment into clinical-stage platforms after a funding contraction period.
For Market Incumbents: Insulate platform value through captive synthetic intermediate production in Basel-adjacent chemical corridors and exclusive E3 ligase biochemist employment contracts. Patent estate thickets around PROTAC linker geometries represent the primary substitution threat from emerging molecular glue competitors. Backward integration into novel warhead chemistry capabilities offers defensive leverage against CDMO capacity constraints. For New Entrants and Emerging Players: Establish a beachhead in neurological disorder applications where blood-brain barrier penetrant degraders for tau and alpha-synuclein targets remain preclinical white space with limited competitive intensity. Autoimmune disease tissue-specific E3 ligase programs offer secondary penetration opportunity given lower rival concentration versus oncology. Go-to-market positioning should emphasize CRISPR-enabled target validation partnerships with academic medical centers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platforms with demonstrated ligase repertoire depth beyond cereblon-centric architectures. Long-term viability over the next decade hinges on regulatory approval pathway diversification across FDA, EMA, and Swissmedic jurisdictions. The signal to monitor is EMA PRIME eligibility frequency as an inflection indicator for European market access momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | FDA breakthrough designation compresses regulatory review timelines for qualifying oncology degraders. |
| Manufacturing Scale-Up | REACH-compliant intermediate sourcing from German CDMOs bypasses new substance notification delays. |
| Pipeline Diversification | Tissue-specific E3 ligase programs differentiate from crowded cereblon-recruiting competitor pipelines. |
| Licensing Agreement | Multi-year pharmaceutical partnerships disintermediate traditional fee-for-service CRO relationships. |
| Regulatory Approval Pathway | EMA PRIME eligibility creates accelerated assessment tailwind complementing FDA momentum. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up segmentation modeling triangulated against top-down market sizing across the analysis window.
Calibration against historical FDA approval timelines and venture funding deployment patterns anchored the analytical framework. Segmentation dimensions modeled include degrader modality, E3 ligase target class, therapeutic application, and regional regulatory cluster. CAGRs were derived from slope analysis of investment flow trajectories and clinical trial initiation rates. Forecast inputs incorporated E3 ligase biochemist hiring velocity and CDMO capacity expansion announcements.
Stress conditions across FDA guidance clarity, REACH compliance timeline extensions, and ADC substitution pressure were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory pathway convergence and partnership structure durability. Quarterly review of breakthrough therapy designation grants and EMA PRIME eligibility decisions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Thailand Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Plasma Protease C1-Inhibitor Market
Biopharmaceuticals
Global Bovine Blood Plasma Derivatives Market
Biopharmaceuticals
Combination Antibody Therapy Market
Biopharmaceuticals
Global Actinic Keratosis Drugs Market
Biopharmaceuticals
Bioequivalence Studies Market
Biopharmaceuticals
Large Macrolide Drugs Market
Biopharmaceuticals
Oseltamivir Market
Biopharmaceuticals
Global Insulin Glargine Market
Biopharmaceuticals
RNA Targeting Small Molecule Drug Discovery Market
Biopharmaceuticals
Inactivated Vaccines Market
Biopharmaceuticals
Tamiflu (Oseltamivir Phosphate) Market
Biopharmaceuticals
Linaclotide API Market
Biopharmaceuticals
Bromodomain and Extraterminal Domain (BET) Inhibitors Market
Biopharmaceuticals
Terbinafine Tablet Market
Biopharmaceuticals
Chemotherapy Market