
 Mendelian Disorders Testing Market | 2026-2036
Mendelian Disorders Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Mendelian Disorders Testing Market Outlook
The Mendelian Disorders Testing Market is consolidating around a widening gap between premium molecular diagnostics and commodity screening panels. Quest Diagnostics leverages its national laboratory network to sustain volume leadership in carrier identification programs. PerkinElmer anchors its position through specialized newborn screening platforms that dominate state public health contracts.
Mendelian disorders testing encompasses molecular diagnostic methods that detect pathogenic variants in single genes following Mendelian inheritance patterns, employing technologies such as next-generation sequencing with read depths exceeding 100x for clinical-grade variant calling. The primary purpose is to enable definitive diagnosis, reproductive risk assessment, and therapeutic guidance for conditions such as cystic fibrosis, sickle cell disease, and Huntington disease. Next-generation sequencing now leads the technology dimension by throughput and cost efficiency, while Sanger sequencing retains dominance in confirmatory testing for variant validation. Carrier testing represents the fastest-growing product type segment as expanded panels replace single-gene assays in preconception and prenatal workflows.
The FDA regulates in vitro diagnostic devices and laboratory-developed tests through premarket notification and quality system requirements, while the Centers for Medicare and Medicaid Services governs reimbursement under the Clinical Laboratory Fee Schedule. CLIA certification remains the baseline gateway for diagnostic laboratories seeking to perform high-complexity molecular testing. Stakeholders must monitor evolving coverage determinations for whole-exome sequencing and polygenic risk scores as payers recalibrate benefit structures.
Market Dynamics
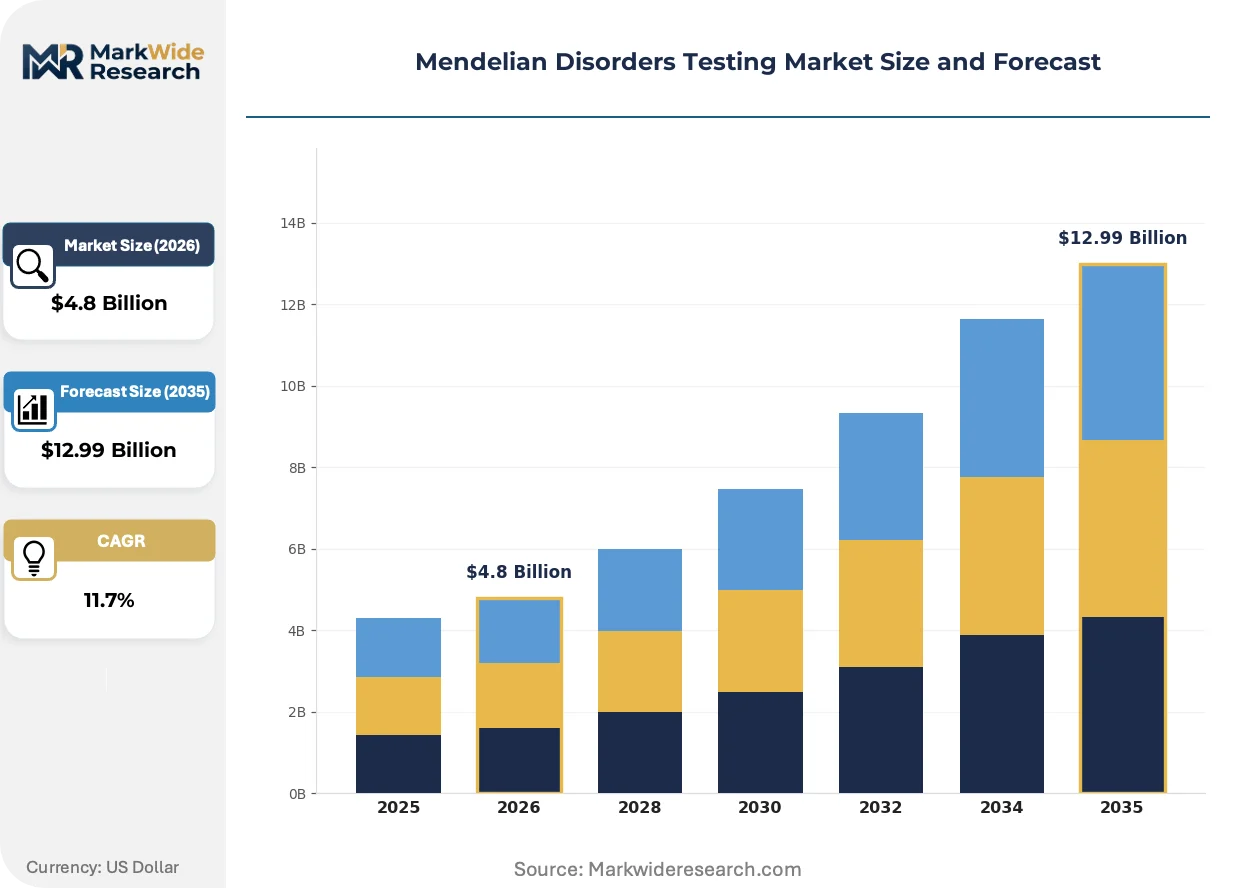
The Mendelian Disorders Testing Market is consolidating around a fundamental tension between high-throughput sequencing economics and the clinical necessity of interpretive depth. Expanded carrier screening panels are compressing per-test revenue while simultaneously broadening addressable patient populations.
Growth Catalysts
- Statutory reimbursement expansion:Germany's statutory health insurance now covers exome sequencing for rare disease diagnosis, removing cost barriers for patient access and accelerating clinical adoption of comprehensive genomic testing workflows.
- Preconception screening protocols:Reproductive medicine clinics are integrating expanded carrier panels into standard preconception counseling, creating systematic demand for multi-gene assays that replace sequential single-gene testing.
- Next-generation sequencing throughput gains:Automated library preparation and cloud-based variant interpretation are reducing turnaround times from weeks to days, enabling diagnostic laboratories to process higher sample volumes without proportional staffing increases.
Market Restraints
- Reimbursement compression under CLFS:The Centers for Medicare and Medicaid Services Clinical Laboratory Fee Schedule imposes pricing ceilings on molecular diagnostic codes, constraining margins for high-complexity testing despite rising operational costs.
- Variant interpretation bottleneck:The scarcity of board-certified clinical laboratory geneticists and molecular pathologists creates processing backlogs, limiting laboratory expansion regardless of instrument capacity.
- Reagent supply concentration:Critical sequencing chemistries and consumables depend on a concentrated vendor base, exposing diagnostic laboratories to input cost volatility and supply continuity risks.
Strategic Opportunities
- Polygenic risk score integration:The convergence of Mendelian variant detection with polygenic risk algorithms creates differentiated product offerings for reproductive health and preventive medicine applications.
- Direct-to-consumer channel development:Telehealth-integrated genetic counseling platforms are emerging as alternative distribution pathways, bypassing traditional physician-mediated ordering for carrier screening.
- Pharmacogenomic expansion:Diagnostic laboratories can leverage existing sequencing infrastructure to capture adjacent demand for drug-gene interaction testing, utilizing CLIA-certified workflows for new revenue streams.
Industry Challenges
- CLIA high-complexity personnel requirements:Recruitment and retention of qualified laboratory directors and technical supervisors constrain operational scaling, particularly in competitive metropolitan labor markets.
- EHR integration complexity:Disparate health record systems and non-standardized genomic data formats create friction in clinical workflow adoption, requiring substantial IT investment for seamless implementation.
- Variant classification standardization:Inconsistent interpretation guidelines across laboratories generate diagnostic discordance, complicating quality assurance and inter-laboratory comparison efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mendelian Disorders Testing Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DNA Sequencing, Genetic Screening, Carrier Testing, Prenatal Testing Technology: Sanger Sequencing, Next-Generation Sequencing, PCR, Microarray Application: Newborn Screening, Diagnostic Testing, Carrier Identification, Research Applications End User: Hospitals, Diagnostic Laboratories, Research Institutions, Genetics Clinics |
| Companies Covered | Quest Diagnostics, PerkinElmer, Celera Group, Bio-Rad Laboratories, Roche Diagnostics, Abbott Laboratories, AutoGenomics, Applied Biosystems, ELITechGroup, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mendelian Disorders Testing Market Strategic Shifts
Long-read sequencing platforms are disrupting established short-read workflows by resolving complex genomic regions previously inaccessible to conventional analysis. This technological transition is reshaping competitive positioning among diagnostic service providers.
Third-generation sequencing systems from Pacific Biosciences and Oxford Nanopore Technologies is overtaking second-generation platforms for structural variant detection and repeat expansion analysis. Clinical laboratories in the United States are adopting these instruments for Huntington disease and fragile X syndrome testing where short-read methods produce ambiguous results. The technology is overtaking established workflows by eliminating orthogonal confirmation requirements and reducing diagnostic odyssey duration for patients with unresolved Mendelian phenotypes.
The European Union's In Vitro Diagnostic Medical Devices Regulation imposes stricter clinical evidence requirements for genetic testing kits, forcing manufacturers to generate prospective performance data. Diagnostic companies are responding by restructuring quality management systems and expanding post-market surveillance capabilities. The regulation most acutely affects laboratories distributing commercial assay kits across member states, driving consolidation toward CE-marked integrated platforms.
Patients are initiating genetic testing through employer-sponsored wellness programs before traditional clinical encounters, shifting the diagnostic entry point from specialist referral to population health screening. This behavioral change is compressing the interval between initial testing and genetic counseling demand, straining workforce capacity. The pattern is most visible in the United States where large self-insured employers contract directly with testing vendors for preconception and pharmacogenomic screening benefits.
Mendelian Disorders Testing Market Segmentation
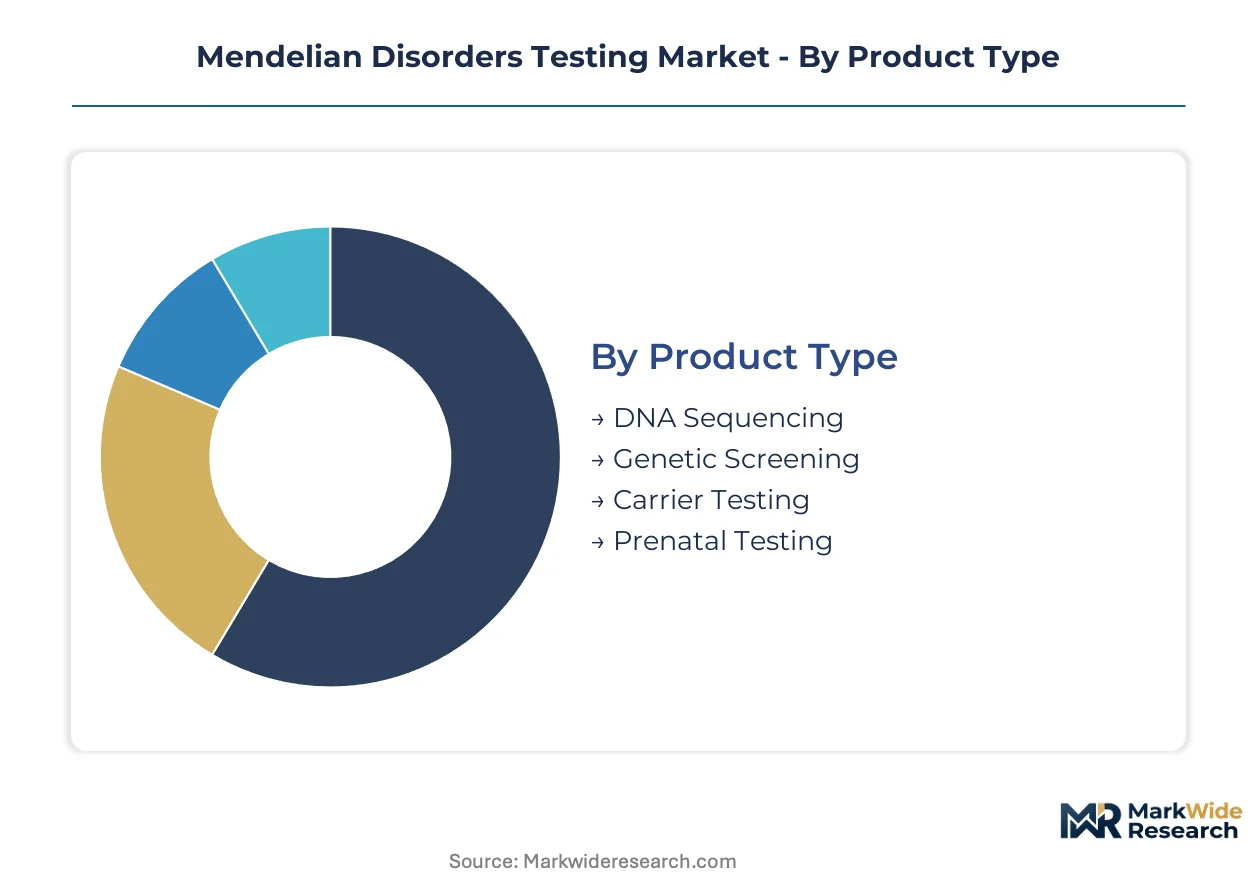
Molecular diagnostic workflows fragment across four intersecting dimensions that determine reimbursement pathways, regulatory burden, and technical infrastructure requirements. Each segmentation axis captures distinct purchasing logic—from high-volume screening contracts to precision diagnostic consultations.
Product Type:
Customization intensity varies sharply across this category, with standardized screening panels competing against bespoke diagnostic sequences for laboratory capital allocation.
- DNA Sequencing:Whole-exome and whole-genome platforms deliver definitive variant identification for unresolved phenotypes. Demand concentrates in academic medical centers pursuing diagnostic odyssey resolution, constrained by prior authorization requirements from US commercial payers.
- Carrier Testing:Expanded panels screening 100-500 genes now dominate preconception workflows in US reproductive medicine clinics. Steepest expansion trajectory as employers directly contract for population-level screening benefits.
- Genetic Screening:State-mandated newborn screening programs operate through centralized public health laboratories with rigid protocol standardization.
- Prenatal Testing:Cell-free DNA analysis for aneuploidy and microdeletion detection flows through maternal-fetal medicine specialists in Germany and the United States.
Most installed capacity flows through Carrier Testing. Expansion is steepest in DNA Sequencing.
Technology:
Cost tiers separate legacy instrumentation from capital-intensive next-generation platforms, with mid-range PCR systems capturing point-of-care niches.
- Next-Generation Sequencing:Short-read platforms from Illumina process thousands of samples weekly in high-complexity CLIA laboratories. US reference laboratories anchor volume leadership through automated library preparation pipelines.
- Sanger Sequencing:Confirmatory testing for variant validation retains indispensable status despite throughput limitations. Demand persists in European Union laboratories navigating IVDR compliance for orthogonal verification requirements.
- PCR:Targeted amplification dominates point-of-care sickle cell screening in sub-Saharan African public health programs.
- Microarray:Comparative genomic hybridization platforms serve copy number variant detection in cytogenetics laboratories with established workflows.
Next-Generation Sequencing commands the largest capital base. PCR maintains the lowest per-test cost position.
Application:
Maturity gradients separate decades-old public health infrastructure from emerging precision medicine categories with evolving evidence standards.
- Diagnostic Testing:Symptomatic patient evaluation for suspected Mendelian conditions requires board-certified clinical laboratory geneticist oversight. German statutory health insurance coverage for exome sequencing removed cost barriers, accelerating clinical adoption.
- Newborn Screening:State public health contracts in the United States specify tandem mass spectrometry and molecular second-tier testing for 35-60 conditions. Procurement concentrates through PerkinElmer and Revvity under multi-year sole-source agreements.
- Carrier Identification:Preconception and prenatal risk assessment expands through telehealth-integrated platforms bypassing traditional specialist referral.
- Research Applications:Undiagnosed disease programs and gene discovery initiatives operate through NIH-funded networks with distinct funding mechanisms from clinical reimbursement.
Newborn Screening absorbs the most public capital. Carrier Identification is climbing the fastest.
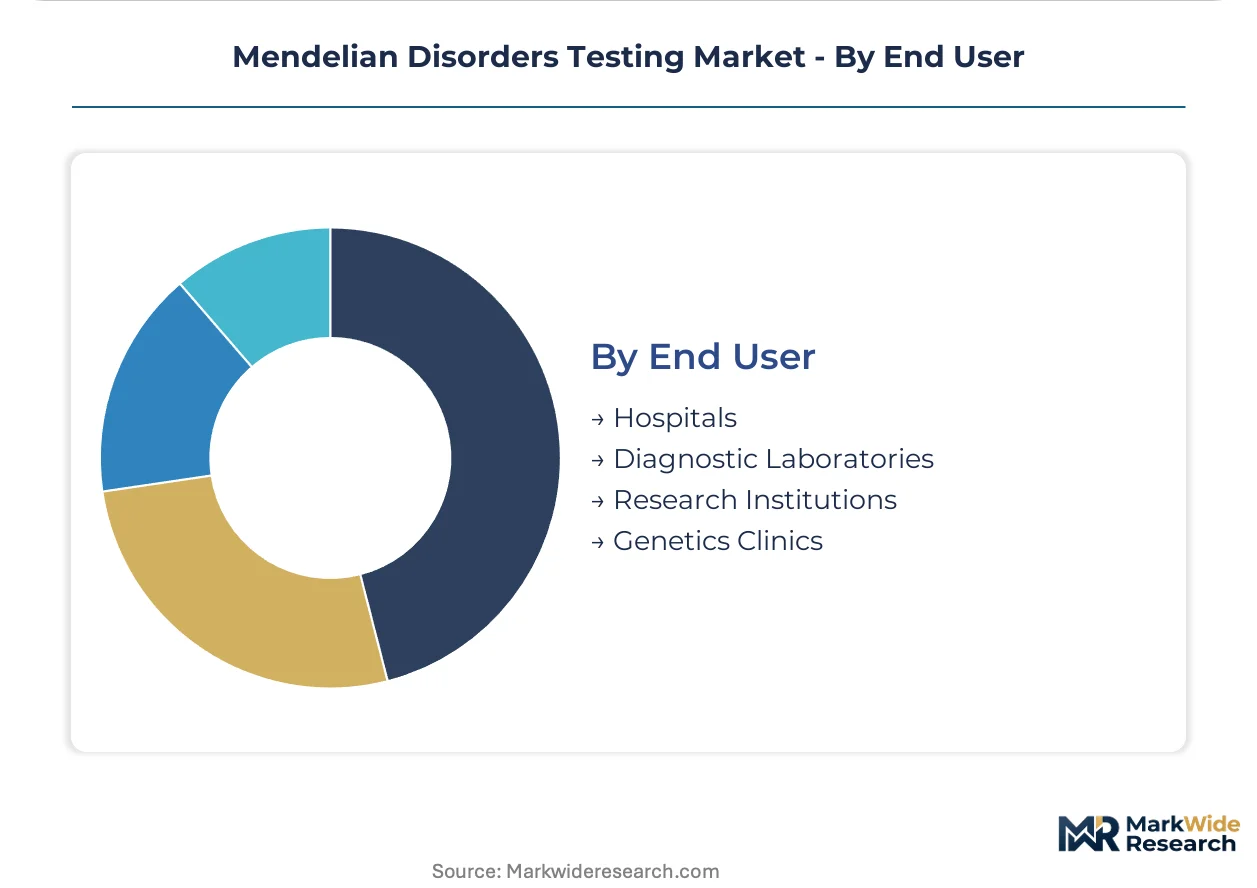
End User:
Customer type determines pricing power, with consolidated health systems extracting volume discounts unavailable to fragmented clinic networks.
- Diagnostic Laboratories:Quest Diagnostics and LabCorp leverage national networks to standardize expanded carrier panels across multiple state jurisdictions. CLIA high-complexity certification requirements create personnel recruitment bottlenecks in competitive metropolitan labor markets.
- Hospitals:Integrated delivery networks in the United States consolidate send-out testing through captive laboratory joint ventures with academic medical centers.
- Genetics Clinics:Specialist-mediated ordering persists for complex prenatal diagnostic consultations requiring genetic counseling integration.
- Research Institutions:NIH-designated undiagnosed disease network sites operate under separate funding streams with distinct procurement timelines.
Diagnostic Laboratories process the highest sample volumes. Genetics Clinics command the highest per-test reimbursement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clinical laboratory geneticists and molecular pathologists cluster in metropolitan academic medical centers across five countries, concentrating diagnostic expertise where sequencing infrastructure and payer density align.
United States
Reproductive medicine clinics in Boston and San Francisco integrate expanded carrier panels into preconception workflows. The FDA oversees laboratory-developed tests through premarket notification pathways, while CMS governs reimbursement under the Clinical Laboratory Fee Schedule. Quest Diagnostics leverages its national network to standardize high-volume carrier screening across multiple state jurisdictions.
Germany
Statutory health insurance coverage for exome sequencing removed cost barriers for rare disease diagnosis. The Federal Joint Committee regulates inclusion of genomic tests in the statutory benefits catalogue. Diagnostic laboratories in Berlin and Munich process comprehensive genomic testing for unresolved Mendelian phenotypes.
United Kingdom
NHS Genomic Medicine Service contracts concentrate sequencing capacity in designated genomic laboratory hubs. NICE evaluates clinical utility and cost-effectiveness for rare disease testing inclusion. The Cambridge and London clusters anchor academic-industry partnerships for variant interpretation software development.
China
Tertiary hospitals in Beijing and Shanghai expand clinical exome sequencing for pediatric genetic disorders. The National Medical Products Administration regulates in vitro diagnostic reagents and sequencing instruments. Domestic sequencing platform manufacturers challenge imported instrument dominance in provincial hospital networks.
Japan
Designated core hospitals for rare and intractable diseases coordinate genetic testing referrals under the Ministry of Health, Labour and Welfare framework. PMDA regulates companion diagnostics and genetic testing devices. The Tokyo and Osaka metropolitan areas concentrate board-certified clinical geneticists and genetic counselors.
Mendelian Disorders Testing Market Competitive Environment
Capital-heavy diagnostic laboratories compete with asset-light technology developers for control of testing workflows and data interpretation layers. The market structure concentrates around national reference laboratories with CLIA-certified infrastructure and specialized platform vendors with proprietary chemistries. Three archetypes dominate: integrated reference networks, newborn screening platform specialists, and sequencing technology licensors. Consolidation proceeds through laboratory network acquisitions and exclusive state public health contracting.
Among integrated reference network operators, Quest Diagnostics exemplifies the scale-driven archetype through national specimen logistics and standardized panel deployment. PerkinElmer occupies a specialized position anchored in state-mandated newborn screening contracts. Within the technology tier, Bio-Rad Laboratories represents the diversified life science tools segment supplying analytical instrumentation and quality controls.
| Leading Market Players |
|---|
| Quest Diagnostics |
| PerkinElmer |
| Celera Group |
| Bio-Rad Laboratories |
| Roche Diagnostics |
| Abbott Laboratories |
| AutoGenomics |
| Applied Biosystems |
| ELITechGroup |
| Others |
Value Chain & Pricing Dynamics
EU IVDR compliance mandates gate qualified supply and premium-tier pricing access, as CE-marked reagent kits command 15-25% price premiums over non-certified alternatives while domestic-content rules in China and India reshape sourcing patterns for instrument manufacturers.
Pricing Analysis
Bundled service contracts covering sequencing, bioinformatics, and clinical interpretation dominate enterprise sales to hospital systems, while unbundled per-test pricing persists in direct-to-consumer carrier screening. Three-tier pricing structure across premium, standard, and economy levels separates academic medical center exome sequencing from commercial laboratory panels and public health newborn screening programs. Cost compression in standard-tier panels is intensifying because automated library preparation is reducing labor intensity without proportional reimbursement gains. Employer-sponsored wellness programs exhibit highest price sensitivity, whereas integrated delivery networks prioritize turnaround time and interpretive depth over per-test cost.
Supply Chain Analysis
China's domestic-content mandates for sequencing instruments are reshaping sourcing, compelling multinational manufacturers to establish local production or cede provincial hospital contracts to domestic competitors. Critical reagent supply concentrates in the United States, Germany, and China, with sequencing chemistries drawing from concentrated vendor bases in San Diego and Munich. Fluorophore-labeled nucleotides, polymerases, and flow cell consumables face single-source vulnerability from Thermo Fisher and Illumina captive production. Distribution runs through CLIA-certified reference laboratories for high-complexity testing, bypassing traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as reproductive medicine clinics shift demand toward expanded carrier panels with genetic counseling integration, favoring laboratories with interpretive depth over commodity testing volume.
For Market Incumbents: To counter long-read sequencing disruption from Pacific Biosciences and Oxford Nanopore, anchor market position through backward integration into proprietary variant interpretation software and captive bioinformatics pipelines. Prioritize CLIA laboratory director recruitment in Boston and San Francisco metropolitan areas where board-certified clinical laboratory geneticist scarcity constrains competitor expansion. Defend state newborn screening contracts through multi-year sole-source agreements with public health departments. For New Entrants and Emerging Players: Telehealth-integrated genetic counseling platforms offer the lowest customer acquisition cost route for carrier screening market entry, bypassing physician-mediated ordering workflows dominated by established reference laboratories. Target employer-sponsored wellness benefits as the most penetrable segment, where large self-insured employers contract directly for preconception screening without prior authorization requirements. Pursue white-label partnerships with reproductive medicine clinics lacking in-house sequencing infrastructure. For Investors and Strategic Acquirers: Roll-up economics work for regional CLIA-certified laboratories because Medicare reimbursement standardization enables margin expansion through centralized bioinformatics and variant interpretation platforms. Five-to-ten year viability hinges on polygenic risk score integration capabilities and pharmacogenomic testing adjacencies. Monitor FDA premarket notification pathways for laboratory-developed tests as the critical inflection signal for regulatory risk recalibration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | IVDR compliance unlocks German statutory health insurance reimbursement for exome sequencing. |
| Hospital System Partnership | Integrated delivery network contracts consolidate send-out testing through captive laboratory joint ventures. |
| Software Companion Development | Cloud-based variant interpretation platforms reduce turnaround times from weeks to days. |
| Reimbursement Strategy | CMS Clinical Laboratory Fee Schedule coverage determinations govern commercial payer adoption patterns. |
| Acquisition of Specialist Firm | Clinical laboratory geneticist talent scarcity makes personnel-heavy acquisitions attractive. |
Study Parameters
Bottom-up diagnostic laboratory capacity modeling reconciled against top-down sequencing instrument installation tracking forms the analytical core. Primary interviews with clinical laboratory directors, genetic counselors, reproductive medicine specialists, and hospital procurement managers combined with secondary validation from FDA 510(k) filings, CMS Clinical Laboratory Fee Schedule determinations, and German Federal Joint Committee benefit catalogue decisions. Triangulation against CLIA-certified laboratory registries and state public health newborn screening program contracts anchored supply-side estimates.
Historical trendline analysis of carrier screening panel adoption, exome sequencing reimbursement decisions, and long-read platform clinical validation studies informed projection assumptions. Segmentation modeling spanned product type, technology platform, application workflow, and end-user channel across the analysis window. CAGRs derived from fitted adoption curves for next-generation sequencing penetration and statutory coverage expansion trajectories. Forecast inputs incorporated German statutory health insurance coverage decisions and US employer wellness program contract growth.
The model assumes a particular technology adoption path; alternative pathways for long-read sequencing would alter the outlook if structural variant detection accuracy accelerates clinical guideline revision. Forecasts reflect assumptions regarding CLIA personnel supply, IVDR implementation timelines, and CMS reimbursement stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Genetic Testing Panels Market
Genomics
Global Digital PCR Market
Genomics
Genotyping Market
Genomics
Transcriptomics Technologies Market
Genomics
Forensic Genomics Market
Genomics
Pharmacogenomics Technology Market
Genomics
Digital Genome Market
Genomics
Whole Genome Amplification Market
Genomics
Prenatal Genetic Testing Market
Genomics
Global Mirna Sequencing and Assay Market
Genomics
Reproductive Genetics Market
Genomics
Animal Genetics Market
Genomics
Molecular Biomarkers for Cancer Detection Market
Genomics
Antisense Oligonucleotides Market
Genomics
Next Generation Genomics Market
Genomics
Middle East and Africa Whole Exome Sequencing Market