
 Genomics Personalized Health Market | 2026-2036
Genomics Personalized Health Market Size, Share, and Industry Trends Forecast 2026-2036
Genomics Personalized Health Market Analysis
The capability gap between high-throughput sequencing infrastructure and point-of-care genomics is collapsing as platform economics shift. Illumina Inc. sustains dominance in clinical-grade sequencing throughput, while Oxford Nanopore Technologies differentiates through portable, real-time analysis for decentralized settings. Thermo Fisher Scientific leverages its integrated reagent-to-instrument portfolio to control laboratory workflows across multiple continents.
Genomics personalized health encompasses the use of individual genetic profiles—derived from DNA sequencing, genotyping, and bioinformatics analysis—to guide preventive care, diagnosis, and therapeutic selection with base-pair resolution. DNA sequencing generates the foundational data layers, while bioinformatics transforms raw reads into clinically actionable variant calls through pipeline-standardized algorithms. Among applications, oncology commands the deepest clinical integration as tumor profiling becomes standard-of-care, whereas rare disorders represent the fastest-expanding addressable population as undiagnosed disease programs scale nationally. Next-generation sequencing leads technology deployment, while CRISPR-based diagnostics emerge as the highest-growth modality for rapid pathogen identification.
FDA oversees premarket authorization and breakthrough device designation for genomic diagnostics, while HIPAA governs the privacy architecture surrounding genetic data exchange in clinical networks. The EU AI Act and GDPR impose additional conformity requirements on automated variant interpretation tools deployed across European healthcare systems. Stakeholders must monitor evolving reimbursement determinations from CMS and parallel agencies as coverage policies increasingly determine which genomic tests achieve routine clinical adoption.
Market Dynamics
Platform consolidation around portable sequencing hardware is collapsing the cost-per-base economics that once confined clinical genomics to centralized reference laboratories. This infrastructure democratization is redistributing analytical capability toward ambulatory and retail health settings.
Growth Catalysts
- FDA Breakthrough Device Designation:Streamlined premarket pathways compress regulatory timelines for companion diagnostics, accelerating tumor profiling adoption in community oncology practices.
- Pharmacogenomic program expansion:Pharmaceutical manufacturers embed genetic stratification into Phase II/III trials, creating pull-through demand for preemptive patient screening.
- Undiagnosed disease networks:National health systems in Australia, Germany, and Canada fund systematic rare disease sequencing, expanding addressable testing volumes beyond oncology.
Market Restraints
- Reagent supply concentration:Three vendors control polymerase and flow-cell manufacturing, creating vulnerability to single-source disruptions.
- GDP compliance friction:Cross-border transfer restrictions on genomic data impede multi-site clinical trials and international biobank collaborations.
- Interpretation bottleneck:Variant classification pipelines require board-certified molecular pathologists, and training program capacity lags instrument deployment.
Strategic Opportunities
- Direct-to-consumer pharmacogenomics:Employer wellness programs and health plans in the United States sponsor preemptive drug-gene testing for polypharmacy populations.
- CRISPR-Dx convergence with mobile health:Handheld nucleic acid detection platforms enable same-day infectious disease genotyping at pharmacy clinics.
- EU AI Act conformity:Automated variant interpretation tools gain competitive differentiation through CE-marked algorithmic transparency documentation.
Industry Challenges
- Bioinformatics workforce scarcity:Pipeline engineering and clinical variant curation require hybrid computational-biological training that academic programs have not scaled.
- EHR integration complexity:Genomic data structures lack standardization across Epic, Cerner, and regional hospital information systems, fragmenting clinical decision support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Genomics Personalized Health Market |
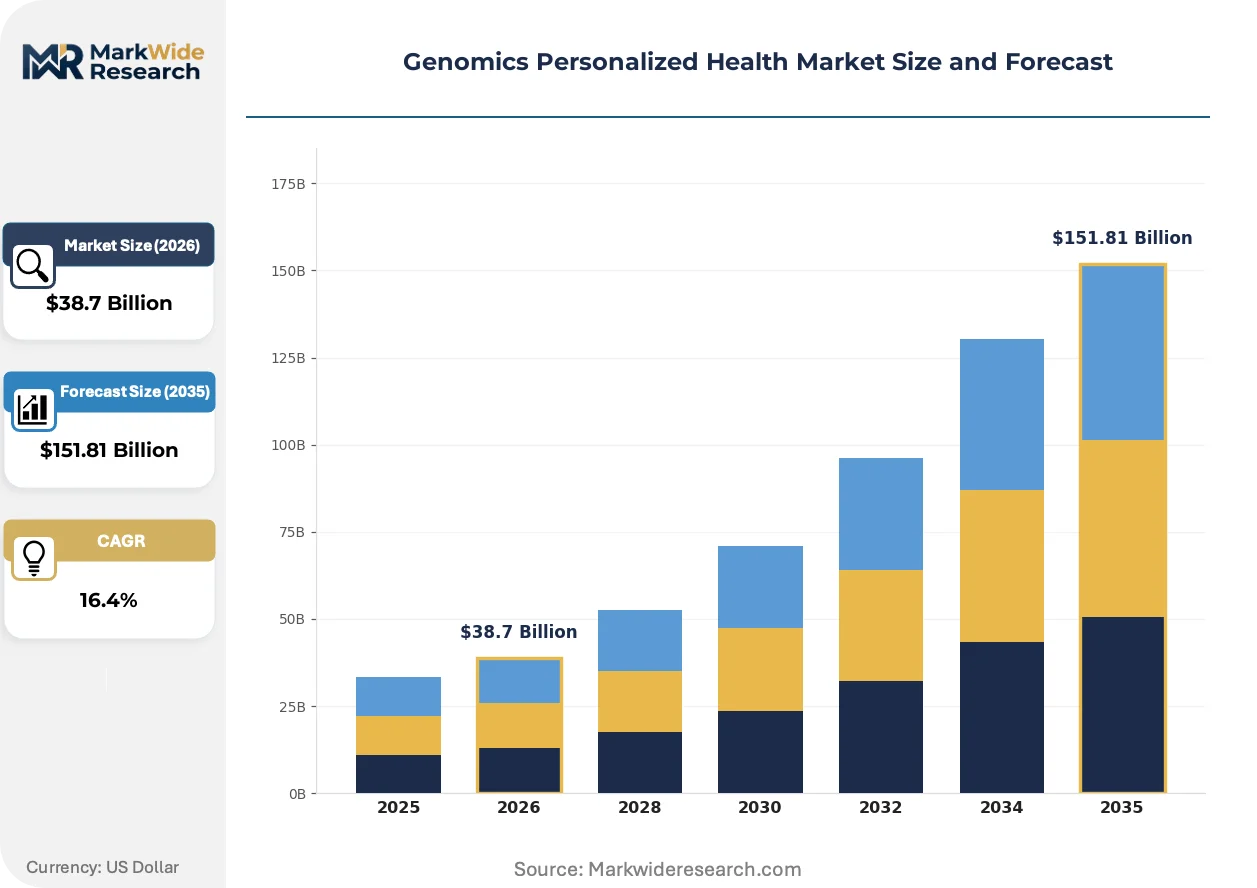
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $151.81 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DNA Sequencing, Genotyping, Gene Editing, Bioinformatics End User: Healthcare Providers, Research Institutions, Pharmaceutical Companies, Diagnostics Labs Application: Oncology, Cardiovascular Disease, Rare Disorders, Infectious Diseases Technology: Next-Generation Sequencing, CRISPR, Microarrays, PCR |
| Companies Covered | Illumina Inc., Thermo Fisher Scientific, Danaher Corporation, F. Hoffmann-La Roche Ltd., Agilent Technologies, QIAGEN, 23andMe, Myriad Genetics, Oxford Nanopore Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Genomics Personalized Health Market Emerging Trajectories
Real-time analysis at the point of collection is eliminating the cold-chain logistics and batch-processing delays that have defined clinical sequencing workflows. This shift compresses diagnostic turnaround from weeks to hours.
Oxford Nanopore's portable sequencing hardware is displacing centralized short-read infrastructure for time-critical applications. Emergency departments and field epidemiology units deploy these devices for same-day pathogen identification and antimicrobial resistance profiling. The technology is displacing overnight courier networks and reference laboratory queues as the binding constraint on clinical decision velocity.
The EU AI Act imposes conformity assessment requirements on automated variant interpretation algorithms deployed in European healthcare networks. Manufacturers must document training data provenance and algorithmic decision logic for notified body review. Oncology decision-support tools face the steepest compliance burden, with several vendors restructuring European distribution to limit liability exposure.
Health system procurement of pharmacogenomic testing is consolidating through national framework agreements and group purchasing organizations. Independent laboratories lose access to hospital contracts as integrated delivery networks mandate in-house or exclusive reference partnerships. This concentration is most pronounced in the United States, where CMS reimbursement determinations increasingly favor health system-affiliated laboratories over independent diagnostic facilities.
Genomics Personalized Health Market Segmentation
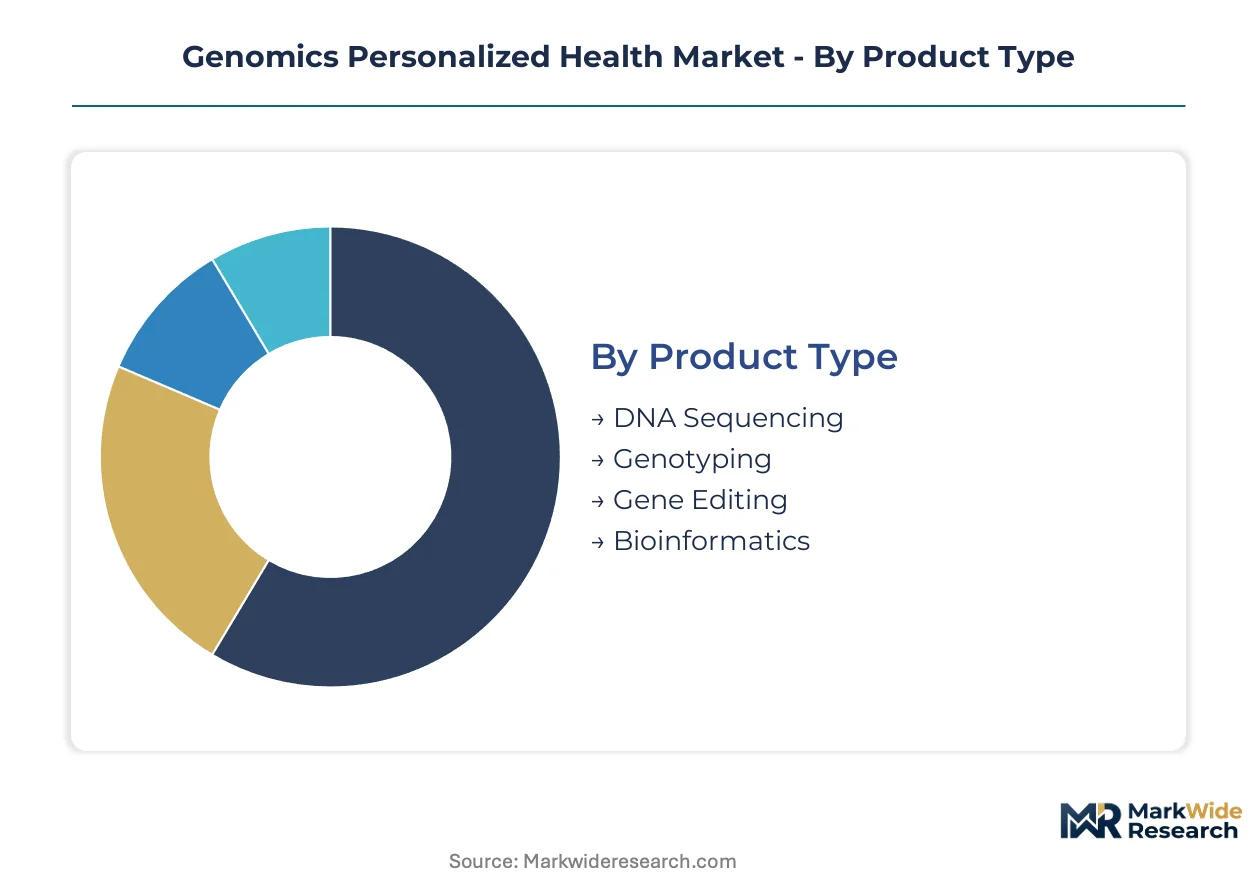
Segmentation reveals where value concentrates across the genomics personalized health value chain. Product architecture, end-user procurement patterns, and technology deployment choices each create distinct margin pools with divergent competitive dynamics.
Product Type:
Margin pools concentrate in instruments and reagents with recurring consumable revenue, while software layers capture value through subscription retention.
- DNA Sequencing:Instruments generate foundational genomic data through short-read and long-read chemistries. Demand clusters in United States hospital systems and academic medical centers where CMS reimbursement for molecular profiling sustains instrument placement velocity. The consumable pull-through model locks in multi-year revenue streams per installed base.
- Bioinformatics:Pipeline software and variant interpretation platforms transform raw sequencing data into clinically actionable reports. Cloud-native deployments in European health systems face EU AI Act conformity costs that favor established vendors with regulatory documentation capabilities.
- Genotyping:Array-based SNP analysis delivers cost-effective population-scale screening for pharmacogenomic applications.
- Gene Editing:CRISPR-based therapeutic development tools and diagnostics reagents serve research and clinical translation workflows.
The dominant share belongs to DNA Sequencing, while Bioinformatics is closing the gap fastest through recurring platform subscriptions.
End User:
Procurement authority determines pricing power, with consolidated health systems extracting volume discounts unavailable to fragmented purchasers.
- Healthcare Providers:Integrated delivery networks in the United States mandate in-house molecular pathology or exclusive reference partnerships, displacing independent laboratories from hospital contracts. Oncology departments drive the deepest test volumes as tumor profiling becomes standard-of-care.
- Pharmaceutical Companies:Manufacturers embed genetic stratification into Phase II/III trials, creating pull-through demand for companion diagnostic co-development. Preemptive patient screening programs expand addressable testing populations beyond treatment settings.
- Research Institutions:Academic medical centers and national genomics initiatives fund undiagnosed disease programs with systematic rare disease sequencing mandates.
- Diagnostics Labs:Independent reference facilities face margin compression as health system consolidation and CMS reimbursement shifts favor affiliated laboratories.
Healthcare Providers command the largest installed base, though Pharmaceutical Companies are expanding contract values fastest through trial-embedded testing programs.
Application:
Clinical integration depth varies sharply across disease areas, with oncology establishing the reference standard other specialties seek to replicate.
- Oncology:Tumor profiling guides therapeutic selection and clinical trial enrollment with established reimbursement pathways. Community oncology practices in the United States adopt FDA breakthrough-designated companion diagnostics as standard workflow.
- Rare Disorders:National health systems in Australia, Germany, and Canada fund systematic sequencing for undiagnosed disease programs. Addressable volumes expand as diagnostic odyssey programs demonstrate cost-effectiveness against prolonged clinical workups.
- Cardiovascular Disease:Polygenic risk scores and pharmacogenomic guidance for anticoagulation therapy gain traction in preventive cardiology settings.
- Infectious Diseases:Pathogen genotyping and antimicrobial resistance profiling deploy in emergency departments and field epidemiology units.
Oncology retains the deepest clinical penetration, while Rare Disorders are gaining share fastest through national funding commitments.
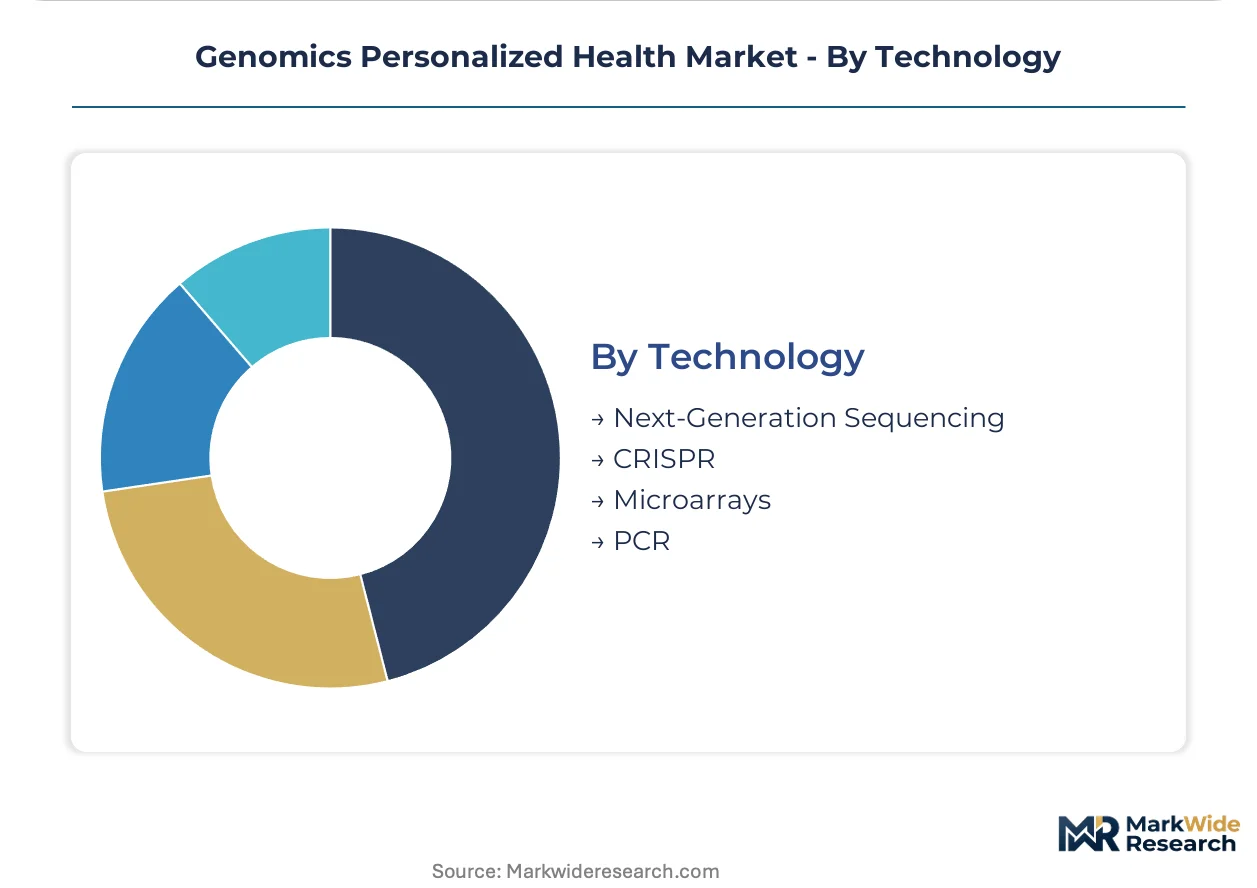
Technology:
Platform economics determine where analytical capability migrates, with throughput-optimized and portability-optimized architectures serving distinct use cases.
- Next-Generation Sequencing:Short-read and emerging long-read platforms dominate clinical-grade throughput requirements. Illumina sustains dominance in centralized reference laboratories while Oxford Nanopore displaces legacy infrastructure for time-critical decentralized applications.
- CRISPR:Diagnostic applications enable rapid nucleic acid detection at point-of-care settings. Handheld platforms compress turnaround from days to hours for infectious disease genotyping in pharmacy clinics and field deployments.
- Microarrays:SNP arrays retain cost advantages for high-volume genotyping in direct-to-consumer and population screening contexts.
- PCR:Quantitative and digital PCR methods serve targeted variant detection with established regulatory pathways and reimbursement codes.
Next-Generation Sequencing holds the broadest installed base, though CRISPR is climbing the fastest as diagnostic applications mature beyond research settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States exports sequencing instruments and bioinformatics platforms while importing specialized reagents from European and Asian suppliers. Germany and China maintain trade surpluses in precision components and consumables. Cross-border data transfer restrictions under GDPR and emerging national biosecurity frameworks are reshaping supply routes.
United States
CMS reimbursement for molecular tumor profiling sustains instrument placement velocity across hospital systems. FDA breakthrough device designation compresses regulatory timelines for companion diagnostics. The Boston-Cambridge corridor and San Francisco Bay Area concentrate venture-funded genomics startups and reference laboratory networks.
Germany
Undiagnosed disease programs funded by the national health system expand rare disease sequencing volumes. The EU AI Act imposes conformity assessment requirements on automated variant interpretation tools deployed in clinical networks. The Munich-Heidelberg-Stuttgart axis anchors pharmaceutical genomics partnerships and academic medical center infrastructure.
China
NMPA streamlined review pathways accelerate domestic sequencing platform approvals while import substitution policies favor local reagent manufacturers. National biosecurity regulations restrict cross-border genomic data transfer from population-scale biobanks. The Yangtze River Delta and Beijing-Tianjin-Hebei corridor concentrate domestic platform developers and clinical testing facilities.
United Kingdom
NHS Genomic Medicine Service mandates standardized tumor profiling across cancer centers, creating procurement concentration. MHRA post-Brexit regulatory autonomy diverges from EU MDR timelines for in-vitro diagnostic certification. The Cambridge-London corridor hosts CRISPR therapeutic developers and bioinformatics platform vendors.
Australia
National undiagnosed disease programs demonstrate cost-effectiveness against prolonged diagnostic odysseys, expanding government-funded testing volumes. TGA convergence with IMDRF standards accelerates approval of FDA-authorized companion diagnostics. Melbourne and Sydney concentrate clinical genomics research institutes and precision oncology trial networks.
Genomics Personalized Health Market Vendor Landscape
Concentration sits with diversified life science conglomerates controlling reagent-to-instrument portfolios. Three vendors dominate polymerase and flow-cell manufacturing, creating single-source vulnerability. Two strategic archetypes prevail: integrated platform vendors capturing recurring consumable revenue and specialized bioinformatics providers securing subscription retention. Competitive moves center on health system exclusive partnerships and preemptive pharmacogenomic screening program sponsorship.
Among platform-integrated conglomerates, Illumina Inc. and Thermo Fisher Scientific anchor the instrument-reagent bundling tier. Oxford Nanopore Technologies occupies a differentiated position in portable real-time sequencing for decentralized deployment. Within the diagnostics-specialist segment, QIAGEN exemplifies the sample-to-insight workflow consolidation archetype.
| Leading Market Players |
|---|
| Illumina Inc. |
| Thermo Fisher Scientific |
| Danaher Corporation |
| F. Hoffmann-La Roche Ltd. |
| Agilent Technologies |
| QIAGEN |
| 23andMe |
| Myriad Genetics |
| Oxford Nanopore Technologies |
| Others |
Supply Flow & Price Mechanics
Long-term consumable supply agreements lock in both reagent access and price visibility for clinical sequencing platforms, binding hospital systems to multi-year procurement commitments that insulate vendors from spot-market volatility while creating switching costs for buyers.
Pricing Analysis
Industrial OEM buyers anchor instrument-reagent bundling as the dominant pricing structure across the genomics personalized health market. Price differentiation rests on throughput tier and FDA breakthrough device certification, with premium placements commanding higher per-run economics. Cost compression in mid-tier sequencers is intensifying because Oxford Nanopore's portable platforms erode Illumina's historical margin cushion. Community oncology practices exhibit the highest price sensitivity, whereas integrated delivery networks leverage volume scale for least-favorable vendor terms.
Supply Chain Analysis
Polymerase and flow-cell manufacturing chokepoints concentrate supply vulnerability across the genomics value chain. Production gravity centers on the United States, Germany, and China for precision optical components, while Singapore and South Korea anchor semiconductor fabrication for signal processing chips. Raw material dependencies include fluorophore-labeled nucleotides, silicon wafer substrates, and synthetic oligonucleotide libraries. Single-source vulnerability pervades CRISPR guide RNA synthesis, where two vendors control gMP-grade manufacturing. Distribution runs through health system group purchasing organizations and national framework agreements that disintermediate independent distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The genomics personalized health market operates as a defensive-moat business where regulatory entrenchment around FDA breakthrough device designation and CMS reimbursement codes creates durable switching costs for incumbent platform vendors.
For Market Incumbents: Fortify consumable pull-through economics by embedding reagent exclusivity into instrument lease structures, directly countering Oxford Nanopore's portable-platform threat. Deepen backward integration into flow-cell polymer manufacturing to neutralize single-source supply risk. Prioritize CE-marked algorithmic transparency documentation under EU AI Act requirements to defend European market access against cloud-native bioinformatics challengers.
For New Entrants and Emerging Players: Interpretation-layer service gaps in variant classification pipelines offer the most penetrable white-space, as board-certified molecular pathologist scarcity constrains incumbent scaling. Target rare disorder diagnostic odyssey programs in Australia and Germany, where national health system funding creates procurement concentration without entrenched vendor relationships. Pursue direct-to-consumer pharmacogenomics partnerships with employer wellness programs as the lowest-friction go-to-market channel.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among bioinformatics platform vendors with health system subscription contracts, offering superior cash-flow quality versus instrument-replacement cyclicality. Five-to-ten-year viability favors automated variant interpretation tools with documented EU AI Act conformity. Signal to watch: CMS reimbursement determinations shifting toward health system-affiliated laboratories, which would accelerate independent diagnostic facility consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Compresses premarket review timelines for companion diagnostics in oncology decision-support. |
| EU AI Act Conformity Pathway | Enables CE-marked deployment of automated variant interpretation across German hospital networks. |
| Health System Exclusive Partnership | Locks out independent reference laboratories through integrated delivery network procurement mandates. |
| Pharmacogenomic Screening Program | Creates preemptive testing demand through employer wellness sponsorships and health plan coverage. |
| Reagent Manufacturing Scale-Up | Reduces single-source vulnerability in polymerase and flow-cell supply for clinical-grade sequencing. |
Methodological Framework
Operator-level perspectives from molecular pathologists, hospital GPO contract managers, pharmaceutical trial operations executives, and diagnostic laboratory directors anchored the qualitative base for this analysis. Primary interview insights triangulated against secondary validation from FDA 510(k) and breakthrough device designation filings, CMS national coverage determinations, EMA scientific advice letters, and ClinicalTrials.gov protocol registries. Bottom-up instrument placement and reagent consumption estimates cross-checked against top-down health system procurement database aggregates.
Sensitivity analysis tested forecast robustness across instrument replacement cycle assumptions, reimbursement policy scenarios, and CRISPR diagnostic adoption curves over the projection horizon. Segmentation modeling incorporated technology platform, application area, end-user procurement authority, and regional regulatory cluster dimensions. CAGRs derived from logistic diffusion curves for platform adoption, adjusted for health system capital expenditure cycles and national sequencing initiative funding commitments.
Forecasts assume regulatory continuity in FDA breakthrough device pathways and EU AI Act implementation timelines; material policy shifts would require re-modeling. Genomic data transfer restrictions under GDPR and emerging national biosecurity frameworks represent specific revision triggers. Practitioners should keep alternative scenarios live as CMS reimbursement determinations and NMPA import substitution policies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
SNP Genotyping Market
Genomics
Genetic Material Market
Genomics
Whole Plasmid Sequencing Market
Genomics
Immunogenetics Market
Genomics
Cancer-Focused Genetic Testing Services Market
Genomics
Global Pharmacogenomics Market
Genomics
NGS-Based RNA-Sequencing Market
Genomics
Restriction Endonucleases Market
Genomics
Europe Gene Synthesis (Research Use) Market
Genomics
Short-Read Sequencing Market
Genomics
Nutrigenomics Testing Market
Genomics
Oligonucleotide Pool Market
Genomics
Microarray Scanners Market
Genomics
Next Generation Molecular Assay Market
Genomics
Cytogenetic Systems Market
Genomics
North America Genetic Testing Market