
 Microbiome Sequencing Market | 2026-2036
Microbiome Sequencing Market Size, Share, and Industry Trends Forecast 2026-2036
Microbiome Sequencing Market Outlook
Modular service bundling is rebalancing procurement patterns across the microbiome sequencing value chain. Illumina leverages its installed base of sequencing instruments to sustain recurring consumable revenue. Thermo Fisher Scientific anchors its position through integrated sample-to-data workflows spanning preparation through analysis. QIAGEN differentiates with automated nucleic acid extraction systems that reduce hands-on time for high-throughput labs.
Microbiome sequencing encompasses the determination of nucleic acid sequences from microbial communities to identify species composition, functional gene content, and metabolic pathways, typically resolving taxa to the genus or species level with read depths exceeding millions per sample. The primary commercial purpose spans human health diagnostics, agricultural yield optimization, and environmental bioremediation monitoring. Next-generation sequencing occupies the dominant technology position due to throughput scalability and declining per-base costs, while bioinformatics services capture expanding margin pools as dataset complexity outpaces in-house analytical capacity. Clinical diagnostics applications are maturing fastest as regulatory pathways clarify, though environmental monitoring retains higher growth velocity from expanding soil and water quality mandates.
FDA oversight of microbiome-based therapeutics as biologics and EMA qualification pathways for microbiome biomarkers are tightening analytical validation standards and shaping demand for compliant sequencing protocols. ISO 17025 accreditation and CLIA certification requirements in the United States are becoming gatekeeping credentials for clinical service providers. Stakeholders must monitor evolving regulatory divergence between jurisdictions to avoid redundant validation investments and maintain cross-border sample processing flexibility.
Market Dynamics
Pharmaceutical sequencing budgets are expanding as FDA biologics guidance and EMA qualification opinions tighten analytical validation standards, forcing service providers to restructure workflows around compliant protocols.
Growth Catalysts
- EMA Qualification Pathways:Streamlined biomarker validation frameworks accelerate clinical adoption of microbiome-based diagnostics across European precision medicine clusters.
- Soil Health Mandates:Agricultural biotechnology firms in Germany deploy sequencing for nitrogen-fixing microbial community optimization under expanding environmental compliance regimes.
- Long-Read Sequencing:Third-generation platforms resolve strain-level taxonomic resolution that short-read technologies cannot achieve, opening new therapeutic target identification pipelines.
Market Restraints
- Reagent Supply Concentration:Nucleic acid extraction chemistries and sequencing consumables depend on concentrated manufacturing in select supply geographies, creating vulnerability to logistics disruptions.
- CLIA Certification Barriers:United States clinical laboratories face 12-18 month validation timelines and substantial documentation burdens before processing reimbursable patient samples.
- Functional Metagenomics Costs:Shotgun sequencing workflows require 5-10x higher per-sample investment than 16S amplicon approaches, limiting penetration in price-sensitive agricultural monitoring segments.
Strategic Opportunities
- China Precision Medicine Initiative:National investment in microbiome-drug interaction research creates demand for ISO 17025-accredited service capacity in Shanghai and Beijing biotech corridors.
- Water Quality Biomonitoring:Regulatory expansion of microbial contamination surveillance in European drinking water infrastructure opens recurring revenue streams for environmental sequencing contracts.
- AI-Augmented Analysis:Machine learning integration with taxonomic classification pipelines compresses bioinformatics turnaround times from weeks to days for high-volume clinical laboratories.
Industry Challenges
- Bioinformatics Talent Scarcity:Shortage of computational biologists proficient in metagenomic assembly and pathway reconstruction limits in-house analytical capacity expansion at mid-size institutions.
- Cross-Border Sample Logistics:Divergent biosafety and data sovereignty requirements between United States, European, and Chinese jurisdictions complicate multi-site clinical trial sequencing workflows.
- Reference Database Gaps:Incomplete genomic representation of uncultured environmental taxa degrades annotation accuracy for soil and marine microbiome applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microbiome Sequencing Market |
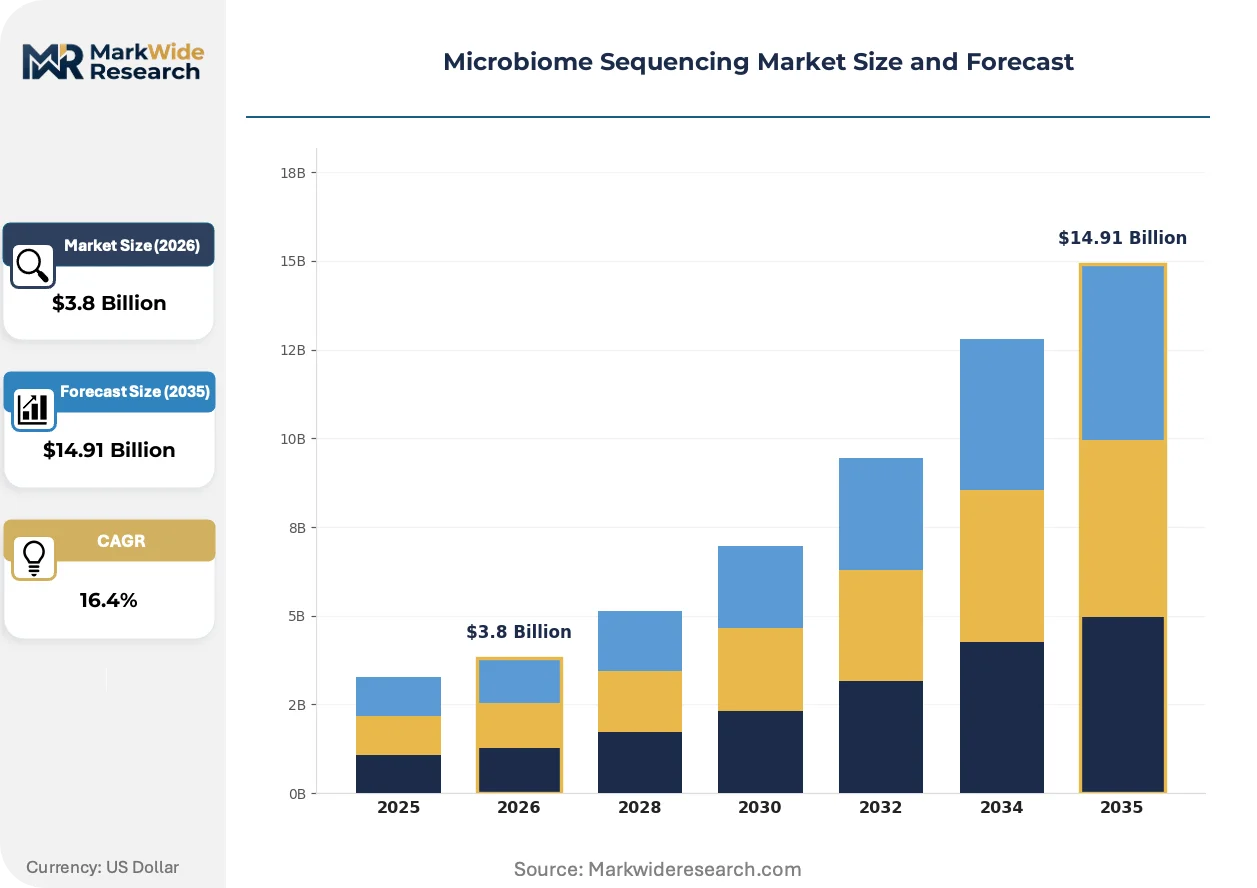
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Clinical Diagnostics, Environmental Monitoring, Agriculture, Drug Development Technology: Next-Generation Sequencing, Sanger Sequencing, Microarray Technology, PCR-based Methods End User: Research Institutes, Pharmaceutical Companies, Biotechnology Firms, Academic Organizations Service Type: Data Analysis, Sample Preparation, Sequencing Services, Bioinformatics |
| Companies Covered | Illumina, Thermo Fisher Scientific, QIAGEN, Zymo Research, Novogene, Oxford Nanopore Technologies, Microbiome Insights, Baseclear, MR DNA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microbiome Sequencing Market Strategic Shifts
Sequencing platforms and analytical workflows are converging around higher resolution, faster turnaround, and tighter regulatory compliance as clinical validation standards crystallize across major jurisdictions.
Third-generation long-read sequencing is overtaking short-read dominance in therapeutic development pipelines. Pacific Biosciences and Oxford Nanopore platforms deliver contiguous microbial genome assemblies that resolve strain-level variation critical for live biotherapeutic product characterization. Pharmaceutical sponsors in the United States and Germany now specify long-read protocols for investigational new drug submissions, compressing the timeline from sample collection to regulatory filing.
FDA guidance classifying microbiome-based therapeutics as biologics under 21 CFR 600-series regulations is tightening quality control documentation requirements. The agency's 2023 enforcement discretion framework for fecal microbiota products has forced developers to demonstrate comparable manufacturing consistency between donor-derived and cultured consortia. Clinical service providers are responding by investing in CLIA-certified, CAP-accredited laboratory information management systems that audit every processing step.
Contract research organizations are unbundling sequencing and analysis services to capture margin from biopharma sponsors lacking in-house bioinformatics infrastructure. United States-based pharmaceutical firms increasingly outsource entire sample-to-insight workflows rather than maintaining captive sequencing capacity. This restructuring concentrates procurement authority with therapeutic developers while fragmenting execution across specialized preparation, sequencing, and analysis vendors.
Microbiome Sequencing Market Segmentation
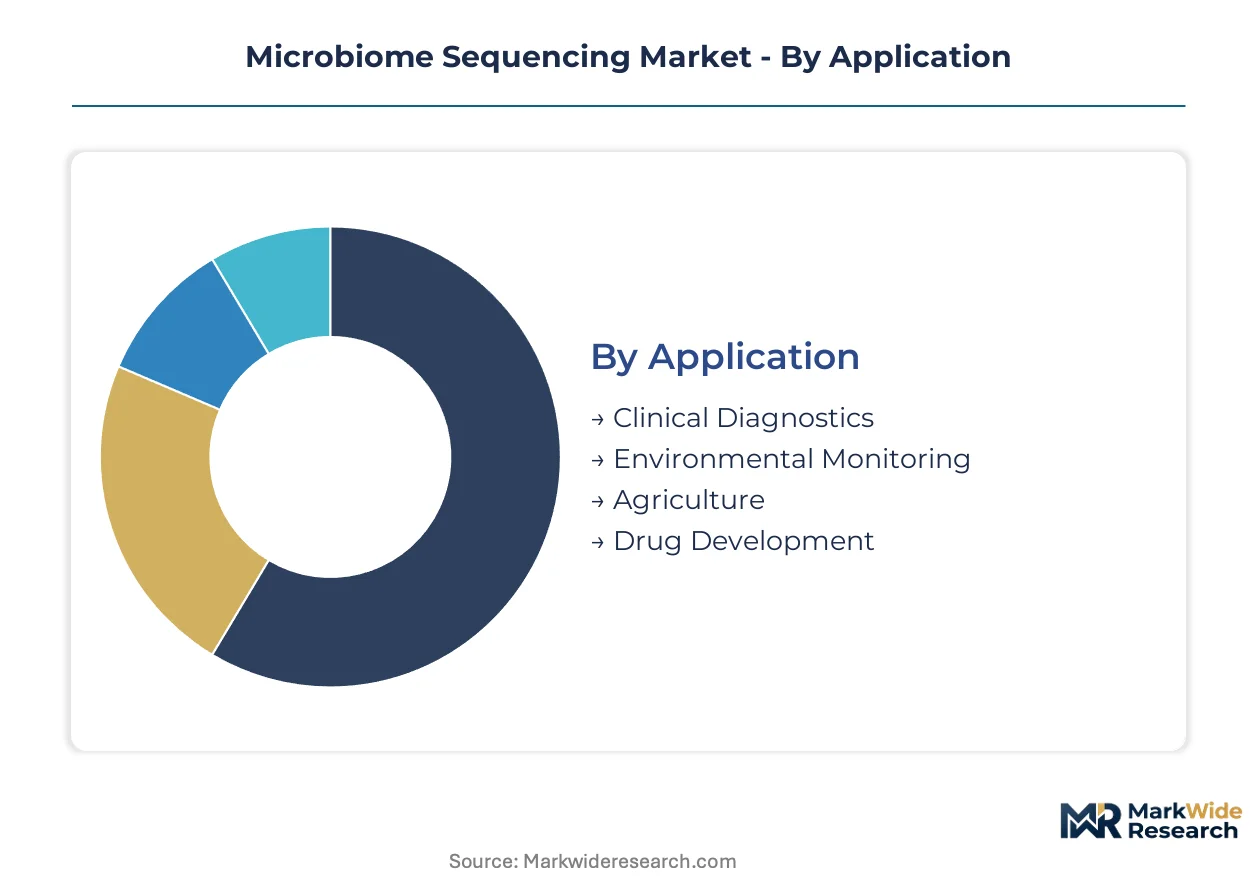
Microbiome sequencing procurement fragments across distinct technical specifications, service models, and end-use requirements. Each segmentation axis shapes vendor selection criteria, pricing structures, and regulatory compliance pathways differently.
Application:
Resolution requirements and regulatory stringency diverge sharply across use cases, with clinical applications demanding validated protocols that environmental work often bypasses.
- Clinical Diagnostics:FDA biologics oversight and CLIA certification requirements enforce rigorous analytical validation for patient-facing microbiome tests. United States hospital laboratories concentrate procurement here as reimbursement codes solidify for gut microbiome dysbiosis screening.
- Environmental Monitoring:Shotgun metagenomics captures uncultured taxa in soil and water quality surveillance. German agricultural biotechnology firms deploy sequencing for nitrogen-fixing community optimization under expanding environmental compliance mandates.
- Agriculture:Crop yield optimization drives demand for rhizosphere microbiome profiling at lower per-sample cost points than clinical applications.
- Drug Development:Live biotherapeutic product characterization requires strain-level resolution that pharmaceutical sponsors now specify for investigational new drug submissions.
Mature deployment sits with Clinical Diagnostics. Newer deployment is concentrated in Environmental Monitoring.
Technology:
Platform selection hinges on read length requirements, throughput scale, and capital availability, with cost-per-base trajectories diverging across generations.
- Next-Generation Sequencing:Illumina short-read platforms dominate commercial throughput with declining per-base economics. United States precision medicine clusters and Chinese biotech corridors anchor installed base expansion for high-volume clinical and agricultural applications.
- Sanger Sequencing:First-generation capillary electrophoresis retains niche utility for targeted validation of taxonomic markers identified through broader surveys.
- Microarray Technology:Hybridization-based detection offers cost advantages for predefined microbial panel screening in resource-constrained settings.
- PCR-based Methods:Quantitative amplification provides rapid turnaround for known pathogen detection without full community characterization.
Established infrastructure concentrates with Next-Generation Sequencing. Emerging therapeutic pipelines are adopting long-read alternatives.
End User:
Procurement authority and in-house capability depth vary substantially across organizational types, fragmenting vendor engagement models.
- Research Institutes:Academic centers with captive bioinformatics infrastructure favor unbundled sequencing services and open-source analytical pipelines.
- Pharmaceutical Companies:Sponsors increasingly outsource entire sample-to-insight workflows rather than maintaining captive sequencing capacity, concentrating procurement authority with therapeutic developers.
- Biotechnology Firms:Mid-size developers lack computational biology bench strength and purchase integrated preparation-through-analysis packages.
- Academic Organizations:Grant-funded laboratories prioritize cost minimization over turnaround speed for exploratory microbiome surveys.
Contract value concentrates with Pharmaceutical Companies. Volume expansion is steepest among Biotechnology Firms.
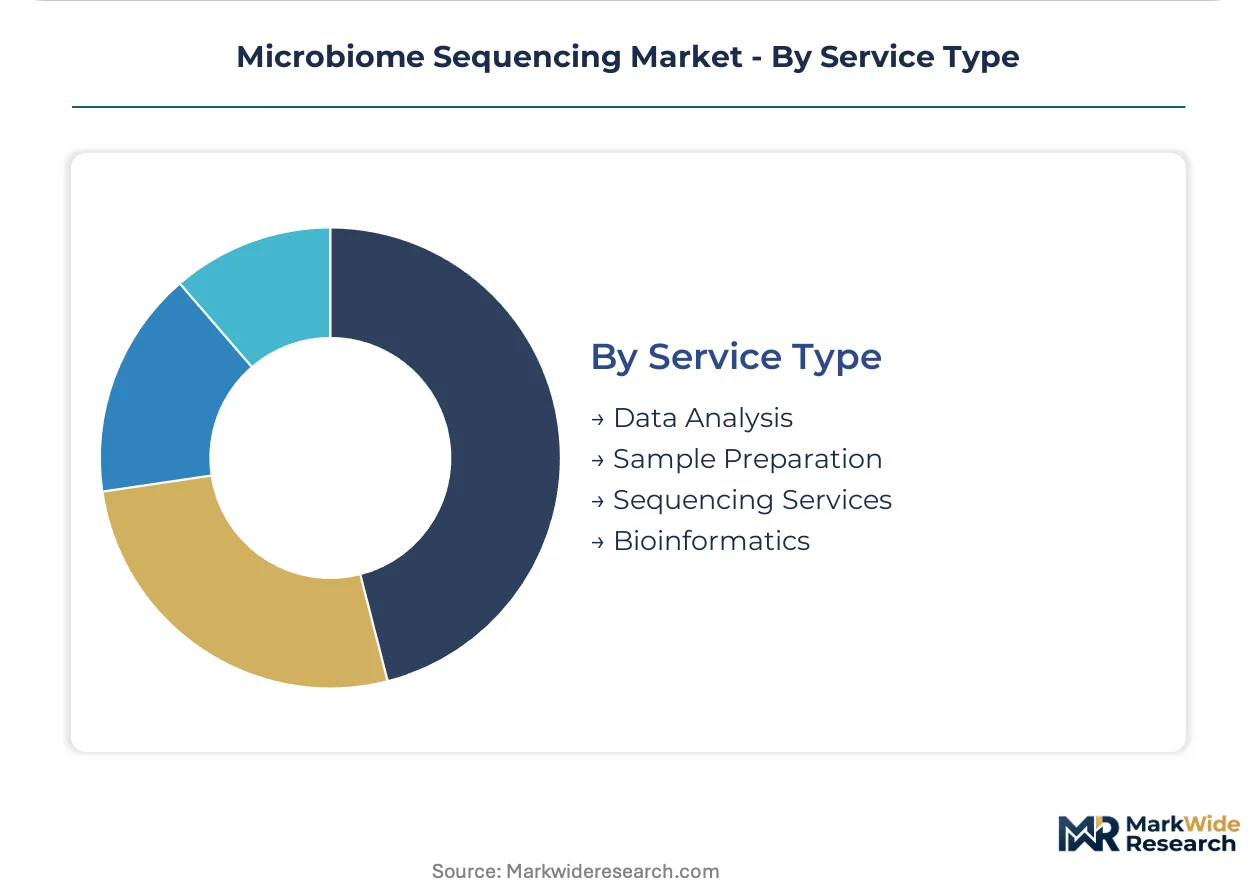
Service Type:
Value capture shifts downstream as dataset complexity outpaces in-house analytical capacity at most institutions.
- Data Analysis:Taxonomic classification and pathway reconstruction command expanding margins as metagenomic assembly expertise scarcity limits insourcing.
- Sample Preparation:Automated nucleic acid extraction systems reduce hands-on time for high-throughput labs, with QIAGEN and similar vendors differentiating on throughput consistency.
- Sequencing Services:Core facilities and commercial providers compete on instrument access and turnaround guarantees for time-sensitive clinical trials.
- Bioinformatics:Machine learning integration with classification pipelines compresses turnaround from weeks to days for high-volume clinical laboratories.
Recurring revenue concentrates with Sequencing Services. Margin expansion is fastest in Data Analysis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of sequencing instruments and consumables concentrates in the United States, Germany, and China, while service demand spreads across precision medicine clusters in all three markets plus emerging agricultural biotechnology centers.
United States
Pharmaceutical sequencing budgets and hospital laboratory expansion drive procurement. FDA biologics guidance under 21 CFR 600-series regulations enforces quality control documentation for microbiome-based therapeutics. The Greater Boston and San Francisco Bay Area biotech corridors anchor live biotherapeutic product development pipelines.
Germany
Agricultural biotechnology firms and environmental monitoring mandates propel sequencing demand for soil microbiome optimization. EMA qualification pathways for microbiome biomarkers streamline clinical validation frameworks. The Rhine-Ruhr and Munich metropolitan regions concentrate nitrogen-fixing microbial community research under expanding environmental compliance regimes.
China
National precision medicine initiatives and microbiome-drug interaction research expand service capacity requirements. The country's national pharmaceutical regulator enforces ISO 17025 accreditation standards for clinical laboratories. Shanghai and Beijing biotech corridors attract investment for ISO-accredited sequencing infrastructure.
United Kingdom
Academic research institutions and contract research organizations sustain demand for unbundled sequencing and bioinformatics services. GDPR data sovereignty requirements complicate cross-border sample processing for multi-site clinical trials. The Cambridge-Oxford-London golden triangle anchors metagenomic assembly expertise and pathway reconstruction capability.
Japan
Pharmaceutical sponsors and food safety regulators adopt microbiome profiling for functional food validation. PMDA oversight of live biotherapeutic products aligns with international biologics standards. The Tokyo-Yokohama and Osaka-Kobe metropolitan areas concentrate gut microbiome dysbiosis screening for aging population diagnostics.
Microbiome Sequencing Market Competitive Environment
The competitive structure tilts toward platform-anchored incumbents with recurring consumable revenue streams. Instrument manufacturers with installed base advantages and integrated workflow providers dominate procurement decisions at high-volume laboratories. Three archetypes prevail: sequencing platform holders, sample-to-data integrators, and specialized bioinformatics service vendors. Capacity expansion through automated extraction systems and strategic partnerships for regulatory-compliant protocol development represent the dominant competitive moves.
Among platform-anchored incumbents, Illumina and Thermo Fisher Scientific exemplify the sequencing instrument and integrated workflow archetypes respectively. Oxford Nanopore Technologies occupies a position representing the long-read sequencing alternative for strain-level resolution applications. These three companies anchor the vendor landscape across clinical diagnostics, pharmaceutical development, and environmental monitoring segments without exhaustive market coverage claims.
| Leading Market Players |
|---|
| Illumina |
| Thermo Fisher Scientific |
| QIAGEN |
| Zymo Research |
| Novogene |
| Oxford Nanopore Technologies |
| Microbiome Insights |
| Baseclear |
| MR DNA |
| Others |
Value Chain & Pricing Dynamics
Sequencing reagent price indices in the United States and Germany cascade through three-tier pricing structures across premium, standard, and economy levels, with CLIA-certified workflows commanding substantial premiums over agricultural monitoring protocols. Pharmaceutical sponsors absorbing these input costs drive consolidation toward integrated sample-to-data vendors capable of volume discounts.
Pricing Analysis
Margin tightening in clinical-grade sequencing reflects FDA biologics documentation burdens and CAP accreditation requirements. Three-tier pricing structure across premium, standard, and economy levels separates CLIA-validated diagnostics from exploratory research services. Agricultural biotechnology buyers exhibit highest price sensitivity, while pharmaceutical developers prioritize turnaround reliability over per-sample economics.
Supply Chain Analysis
Workforce availability constraints in United States, German, and Chinese manufacturing hubs for nucleic acid extraction chemistries concentrate production of sequencing consumables. Supply chains draw from fluoropolymer substrates, fluorescent dye precursors, and high-purity solvents. Single-source vulnerability in semiconductor-grade reagent purification creates exposure to logistics disruptions. Distribution runs through authorized distributor networks and direct procurement channels at high-volume pharmaceutical accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
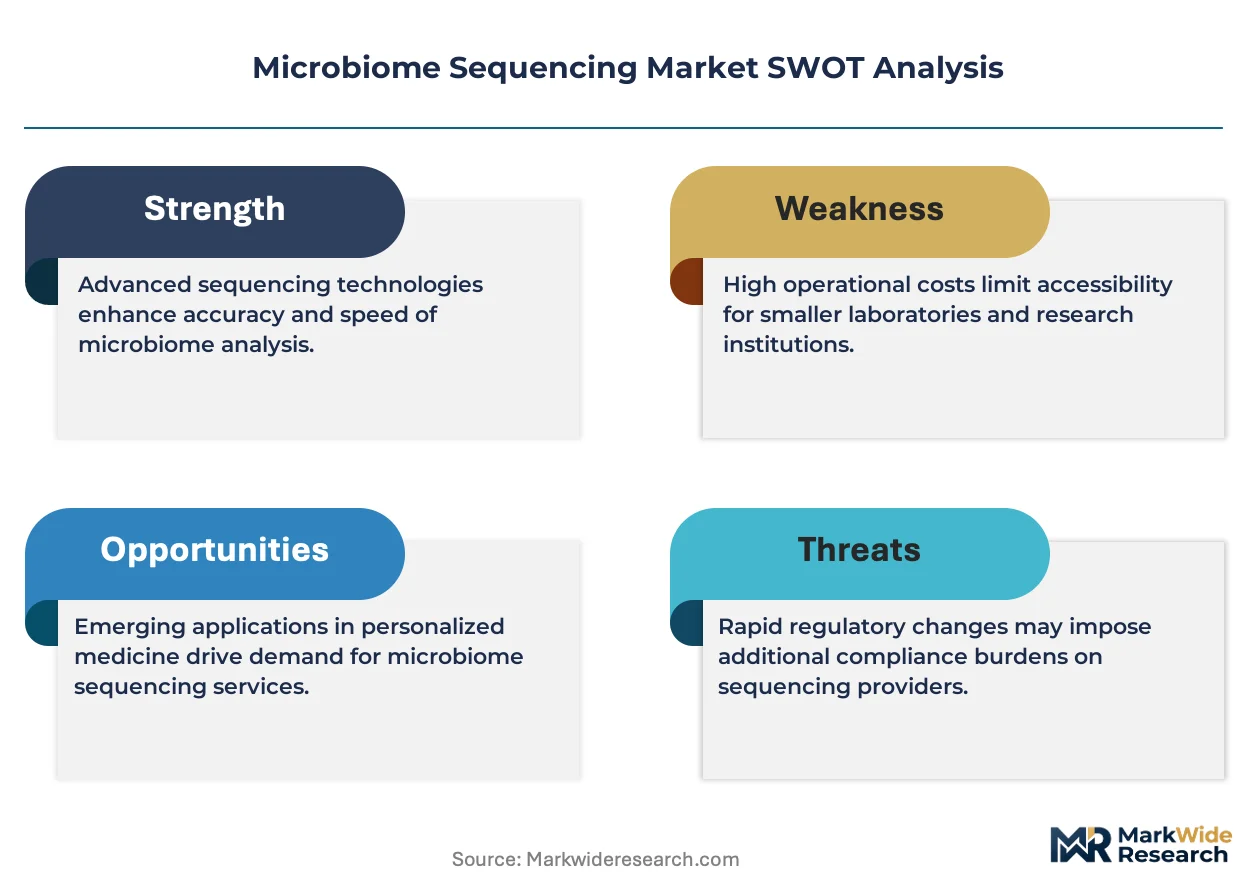
This market functions as a cost-of-compliance story where FDA 21 CFR 600-series biologics guidance erects validation barriers that favor incumbent platform holders with certified laboratory information management systems.
For Market Incumbents: Hedge against long-read sequencing displacement by securing exclusive consumable supply agreements with pharmaceutical sponsors. Anchor recurring revenue through automated nucleic acid extraction system placements at high-throughput clinical laboratories. Prioritize CAP-accredited workflow investments that mid-size competitors cannot replicate within 12-18 month validation timelines. For New Entrants and Emerging Players: Cloud-based bioinformatics platforms offer the lowest capital entry point for agricultural monitoring segments underserved by integrated workflow providers. Target German nitrogen-fixing microbial community optimization contracts where environmental compliance mandates expand faster than established vendor capacity. Deploy AI-augmented taxonomic classification as the primary go-to-market differentiator against legacy analysis pipelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor ISO 17025-accredited service providers in Shanghai and Beijing biotech corridors where national precision medicine initiatives sustain demand regardless of Western capital market volatility. Long-term viability hinges on regulatory compliance infrastructure rather than sequencing hardware ownership. Watch EMA qualification opinion issuance velocity as the inflection indicator for European clinical adoption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Certification Investment | Unlocks reimbursable patient sample processing under United States hospital laboratory expansion programs. |
| Long-Read Sequencing Platform Integration | Resolves strain-level variation for live biotherapeutic product characterization per FDA investigational new drug specifications. |
| AI-Augmented Bioinformatics Development | Compresses taxonomic classification turnaround from weeks to days for high-volume clinical trial sponsors. |
| Automated Extraction System Deployment | Reduces hands-on time at high-throughput laboratories competing on preparation consistency guarantees. |
| Cross-Border Sample Logistics Partnership | Navigates divergent biosafety and data sovereignty requirements between United States, European, and Chinese jurisdictions. |
Study Parameters
Multi-period observation of sequencing instrument placements, consumable shipment volumes, and service contract signings anchored the trend analysis, supplemented by interviews with laboratory directors at CLIA-certified facilities, regulatory affairs specialists at pharmaceutical sponsors, bioinformatics pipeline architects, and procurement managers at agricultural biotechnology firms. Secondary validation drew from FDA 510(k) and biologics license application filings, EMA qualification opinion documents, ClinicalTrials.gov microbiome trial registrations, and ISO 17025 accreditation databases. Bottom-up service provider revenue estimates triangulated against top-down pharmaceutical R&D expenditure allocations.
Segment-weighting across application, technology, end user, and service type dimensions shaped the analytical framework over the projection horizon. CAGRs derived from fitted growth curves incorporating regulatory approval velocity, instrument replacement cycles, and bioinformatics talent supply constraints. Modeled inputs included long-read platform adoption rates in therapeutic pipelines and environmental monitoring mandate expansion trajectories in European agricultural policy.
Inputs from regulatory filing databases and service provider contract disclosures were available through the study window; gaps in private biotechnology firm R&D spending introduce uncertainty bands around pharmaceutical segment projections. Forecasts reflect documented assumptions regarding EMA qualification pathway streamlining and FDA enforcement discretion framework stability. Regulatory divergence acceleration, reagent supply chain disruptions, and reference database completion rates constitute the trigger set warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Global Microarray Analysis Market
Genomics
Single-Cell Omics Market
Genomics
United States Cancer Biomarkers Market
Genomics
Middle East and Africa Whole Exome Sequencing Market
Genomics
Next Generation Sequencing Market
Genomics
Point-Of-Care Genetic Testing Market
Genomics
Global Single-Cell Genome Sequencing Market
Genomics
DNA Methylation Market
Genomics
Rare Disease Genetic Testing Market
Genomics
Global Single Nucleotide Polymorphism (SNP) Genotyping Market
Genomics
Latin America Next Generation Sequencing Market
Genomics
Prenatal Genetic Testing Market
Genomics
Asia-Pacific Whole Exome Sequencing Market
Genomics
Global Blockchain in Genomic Data Management Market
Genomics
Pharmacogenomics Technology Market
Genomics
Dna Polymerase Market