
 Next-Generation Sequencing Library Preparation Market | 2026-2036
Next-Generation Sequencing Library Preparation Market Size, Share, and Industry Trends Forecast 2026-2036
Next-Generation Sequencing Library Preparation Market Intelligence
CE marking under the EU In Vitro Diagnostic Regulation is consolidating the cost-of-entry calculus for commercial library preparation kit suppliers seeking European market access. Illumina, Inc. leverages its installed base of sequencing platforms to sustain captive demand for proprietary prep chemistries. Thermo Fisher Scientific Inc. anchors its position through backward integration into reagent manufacturing and consumables distribution.
Next-generation sequencing library preparation encompasses the enzymatic and mechanical processing of nucleic acids into adapter-ligated, size-selected fragments compatible with high-throughput sequencing platforms, typically requiring input material quantities ranging from picograms to micrograms. This workflow serves as the critical quality-determining step that converts raw biological samples into sequence-ready libraries for genomic analysis across research and clinical settings. DNA library preparation occupies the largest revenue share given its foundational role in whole genome and exome workflows, while automated systems represent the fastest-expanding technology segment as laboratories seek to minimize batch-to-batch variability and operator-dependent errors. Targeted enrichment commands premium positioning in oncology research applications where focused gene panels reduce per-sample sequencing costs.
FDA oversight of laboratory-developed tests, EMA qualification of biomarker assays, and ISO 13485 quality management standards collectively shape product development roadmaps and commercialization timelines for library preparation manufacturers. These frameworks elevate documentation burdens but also create durable competitive moats for vendors with established regulatory affairs capabilities. Stakeholders must monitor evolving premarket review pathways for multi-analyte NGS panels as reimbursement and regulatory convergence determines addressable market boundaries.
Market Dynamics
Automated liquid handling platforms are compressing manual processing bottlenecks in high-throughput clinical laboratories, forcing reagent suppliers to redesign consumables for robotic compatibility rather than benchtop workflows.
Growth Catalysts
- FDA Breakthrough Device Designation:The FDA's accelerated pathway for NGS-based oncology tests compresses premarket review timelines, incentivizing diagnostic developers to expand validated assay menus and pull through library prep kit volumes.
- Targeted Gene Panels:Focused enrichment chemistries for somatic mutation profiling reduce per-sample sequencing costs by 60-80% versus whole-genome approaches, anchoring demand in solid tumor and hematologic malignancy workflows.
- Academic Medical Center Procurement:United States-based AMCs and reference laboratories anchor North American procurement volumes through centralized purchasing consortia and multi-year reagent supply agreements.
Market Restraints
- Input Material Scarcity:Formalin-fixed paraffin-embedded clinical samples frequently yield degraded DNA below picogram thresholds, constraining assay success rates in retrospective oncology studies and archival biobank projects.
- Reagent Supply Concentration:Critical enzymes including transposases and high-fidelity polymerases concentrate among three specialized biochemical suppliers, creating single-source vulnerability for kit manufacturers.
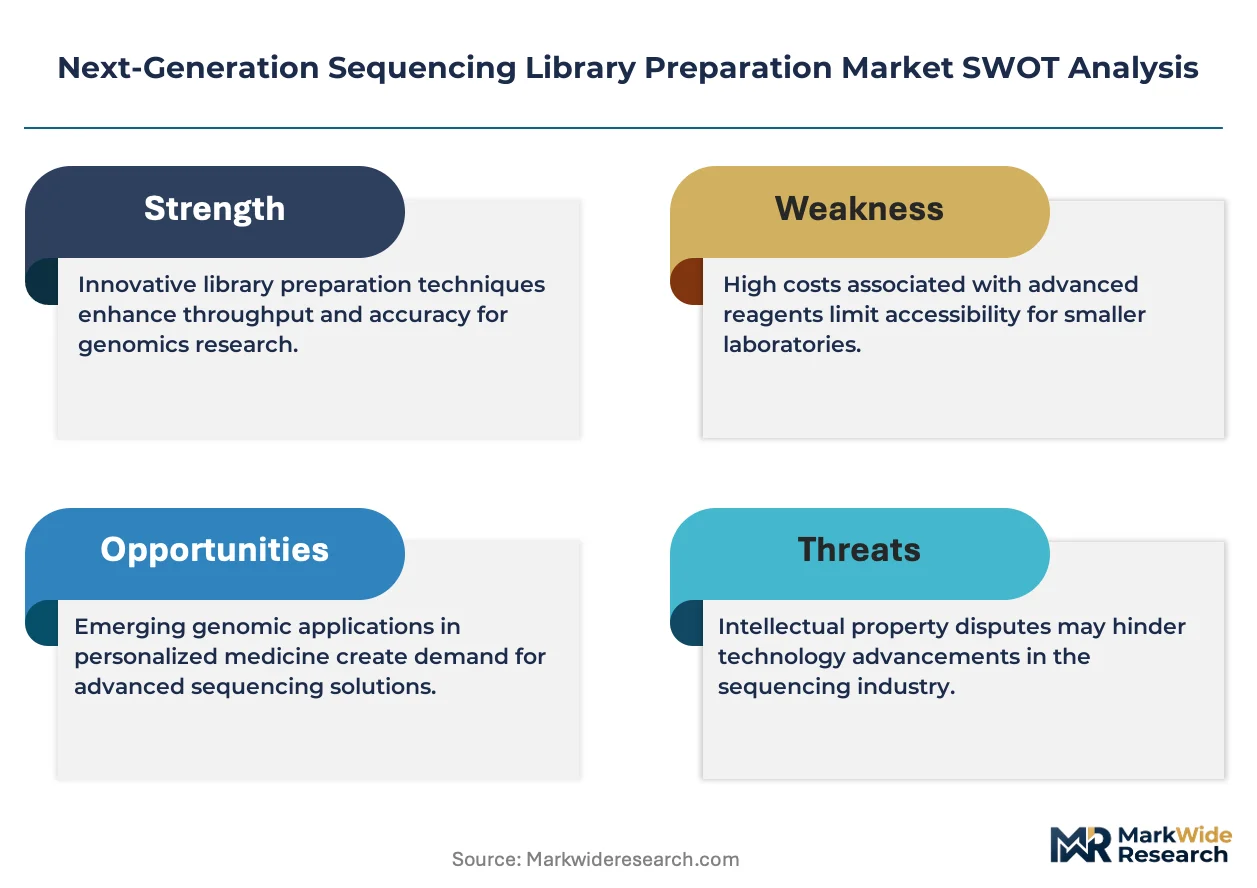
- EU IVDR Transition Costs:CE marking under the EU In Vitro Diagnostic Regulation demands expanded clinical evidence packages and notified body engagement, elevating cost-of-entry for mid-tier kit vendors seeking European market access.
Strategic Opportunities
- Cell-Free DNA Workflows:Liquid biopsy applications for minimal residual disease monitoring and early cancer detection are driving demand for ultra-low-input library prep chemistries optimized for circulating tumor DNA fragmentation patterns.
- Long-Read Sequencing Convergence:Hybrid workflows combining short-read Illumina platforms with Pacific Biosciences or Oxford Nanopore long-read technologies create white space for adapter chemistries compatible with both sequencing modalities.
- India CDSCO Pathway:The Central Drugs Standard Control Organization's streamlined import license framework for research-use-only reagents reduces regulatory friction for kit suppliers targeting India's expanding genomics services sector.
Industry Challenges
- Bioinformatics Integration Complexity:Laboratory information management systems and downstream analysis pipelines require vendor-specific API configurations, extending implementation timelines and elevating total cost of ownership.
- ISO 13485 Certification Burden:Quality management system documentation for clinical-grade kit manufacturing demands dedicated regulatory affairs headcount that mid-sized reagent suppliers struggle to resource.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next-Generation Sequencing Library Preparation Market |
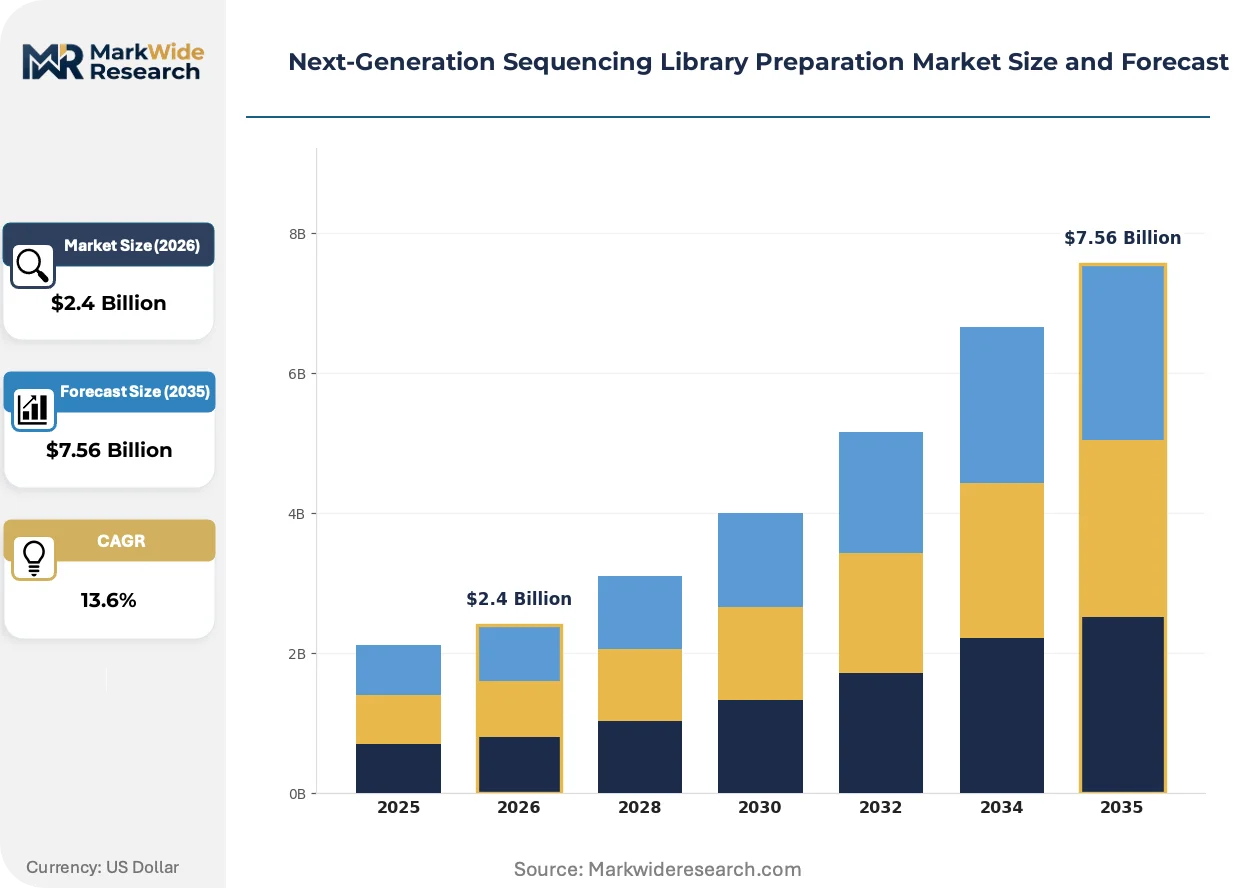
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $7.56 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DNA Library Preparation, RNA Library Preparation, Targeted Enrichment, Whole Genome Sequencing Technology: Automated Systems, Manual Techniques, Reagent Kits, Innovative Platforms End User: Research Institutes, Clinical Laboratories, Pharmaceutical Companies, Academic Entities Application: Oncology Research, Infectious Disease Testing, Genetic Variation Analysis, Personalized Medicine |
| Companies Covered | Illumina, Inc., Thermo Fisher Scientific Inc., Agilent Technologies, Inc., QIAGEN N.V., F. Hoffmann-La Roche AG, Pacific Biosciences of California, Inc., Oxford Nanopore Technologies, New England Biolabs Inc., Revvity, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next-Generation Sequencing Library Preparation Market Strategic Shifts & Innovations
Workflow integration and sample-to-data automation are compressing turnaround times from days to hours, reshaping competitive positioning around hands-free operation and error-rate reduction rather than reagent chemistry alone.
Integrated library preparation workstations from Tecan, Hamilton, and Beckman Coulter are automating nucleic acid extraction, fragmentation, end-repair, adapter ligation, and bead-based cleanup within sealed cartridge formats. Large reference laboratories in the United States and Germany are deploying these platforms for 24-hour turnaround on urgent oncology cases. This automation is compressing labor cost per sample by 70% while reducing batch-to-batch coefficient of variation below 5%.
The EU In Vitro Diagnostic Regulation's 2022 implementation deadline forced kit manufacturers to reclassify research-use-only products and submit technical documentation to notified bodies. Products lacking IVDR certification face market withdrawal, consolidating shelf space among vendors with established regulatory affairs infrastructure. Oncology-focused gene panel suppliers with pre-submitted performance evaluation reports captured first-mover advantage in European hospital procurement.
Consolidated procurement through group purchasing organizations and multi-hospital health systems is displacing decentralized reagent purchasing by individual principal investigators. Academic medical centers in the United States are centralizing sequencing core facility budgets under institutional contracts with preferred vendor tiers. This concentration is visible most acutely in California and Massachusetts, where three health systems control 40% of regional NGS reagent spend.
Next-Generation Sequencing Library Preparation Market Segmentation
Library preparation purchasing decisions split across workflow complexity, sample throughput requirements, and regulatory validation tiers. Each segment category reflects distinct buyer economics: reagent costs dominate high-volume clinical labs, while flexibility governs research institute procurement.
Product Type:
Procurement volumes track directly to sequencing depth requirements and per-sample budget constraints across end-use settings.
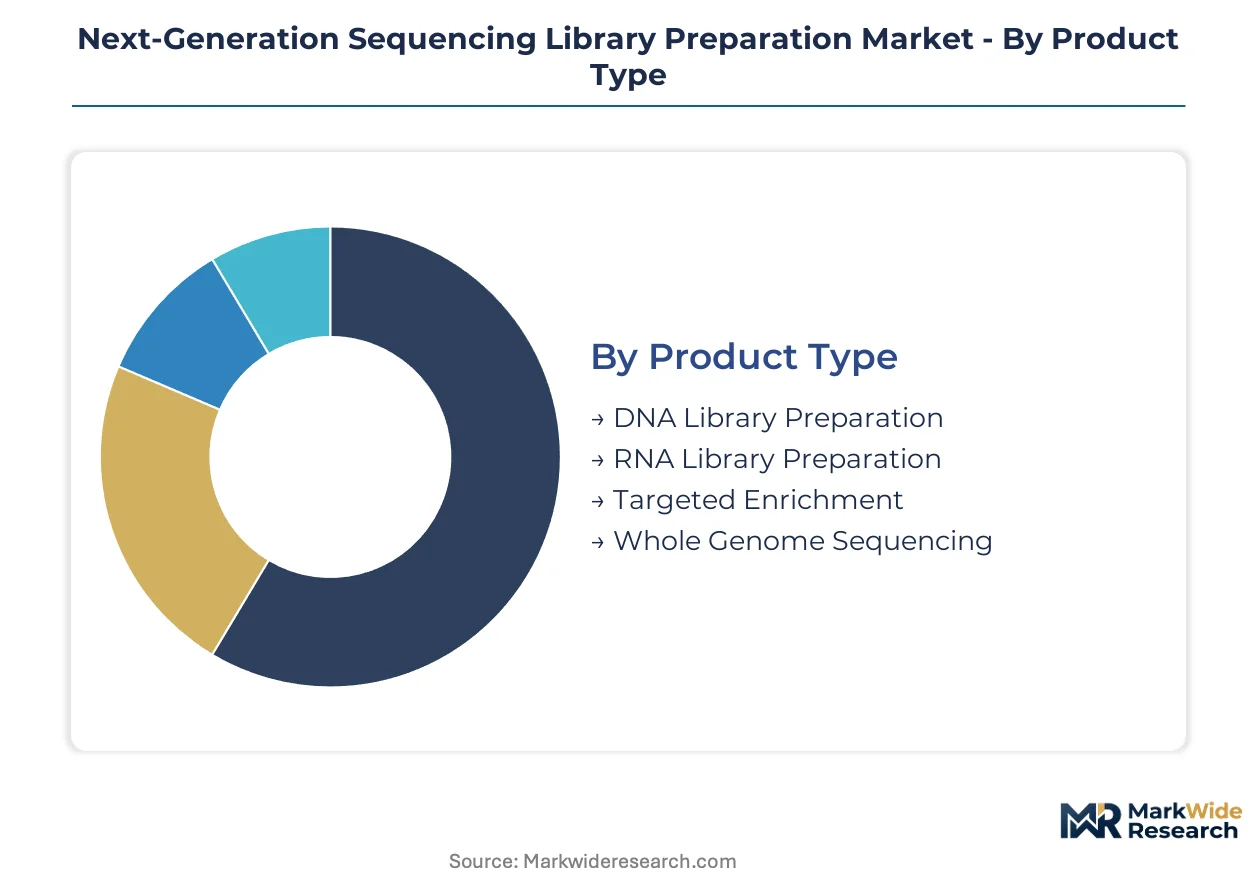
- DNA Library Preparation:Enzymatic fragmentation, end-repair, and adapter ligation workflows convert genomic DNA into sequence-ready molecules. Academic medical centers in the United States anchor procurement through centralized core facility contracts for whole genome and exome projects. Input material flexibility from picogram to microgram scales determines kit selection for FFPE clinical samples.
- Targeted Enrichment:Hybridization capture and amplicon-based chemistries focus sequencing reads on predefined gene panels. Oncology diagnostic developers in Germany and France prioritize these workflows to reduce per-sample sequencing costs in solid tumor profiling. Panel customization services create vendor stickiness through locked-in probe library investments.
- RNA Library Preparation:Reverse transcription and rRNA depletion protocols convert transcriptomic material into cDNA libraries compatible with sequencing platforms. Demand concentrates in infectious disease surveillance programs requiring pathogen gene expression profiling.
- Whole Genome Sequencing:Comprehensive library construction without enrichment steps maximizes genomic coverage for de novo assembly and structural variation detection. Population genomics initiatives and rare disease research programs drive intermittent bulk purchasing.
Volume sits with DNA library preparation; growth tilts toward targeted enrichment.
Technology:
Laboratory staffing costs and error-rate tolerance determine the automation-versus-manual calculus in kit selection.
- Automated Systems:Integrated liquid handling workstations execute nucleic acid extraction through library normalization with minimal operator intervention. Reference laboratories in California and Massachusetts deploy these platforms for 24-hour oncology turnaround requirements. Cartridge-based consumables lock facilities into vendor-specific reagent supply agreements.
- Reagent Kits:Benchtop chemistries for manual or semi-automated processing offer workflow flexibility and lower capital barriers. Research institutes with diverse sample types and irregular throughput favor kit-based approaches for protocol customization.
- Manual Techniques:Column-based purification and multi-step pipetting workflows persist in low-throughput settings and specialized protocols requiring hands-on optimization.
- Innovative Platforms:Transposase-based tagmentation and single-tube reaction chemistries reduce hands-on time and sample loss points. Early adopters in Singapore and Switzerland evaluate these systems for integration with emerging long-read sequencing workflows.
Installed base concentrates in reagent kits; expansion accelerates most quickly in automated systems.
End User:
Budget authority and reimbursement pathways shape purchasing behavior across institutional categories.
- Clinical Laboratories:CAP-accredited and CLIA-certified facilities process patient samples under FDA oversight for diagnostic reporting. United States-based reference laboratories anchor North American volumes through multi-year reagent supply contracts with preferred vendor tiers.
- Research Institutes:Government-funded and independent research centers prioritize protocol flexibility and publication-grade data quality over regulatory documentation. Grant-funded principal investigators in the United Kingdom and Netherlands drive seasonal procurement spikes tied to fiscal year budget releases.
- Pharmaceutical Companies:Companion diagnostic development and clinical trial biomarker programs demand GMP-compliant reagent manufacturing and batch traceability. Oncology pipeline investments by large-cap drug developers pull through validated library prep workflows.
- Academic Entities:University sequencing core facilities balance service breadth against per-sample cost targets through centralized institutional purchasing. Multi-hospital health systems in Texas and Florida consolidate reagent procurement under single vendor agreements.
Transaction volume clusters in clinical laboratories; fastest share gains appear in pharmaceutical company outsourced testing partnerships.
Application:
Reimbursement coding and clinical utility evidence determine addressable market boundaries for each application area.
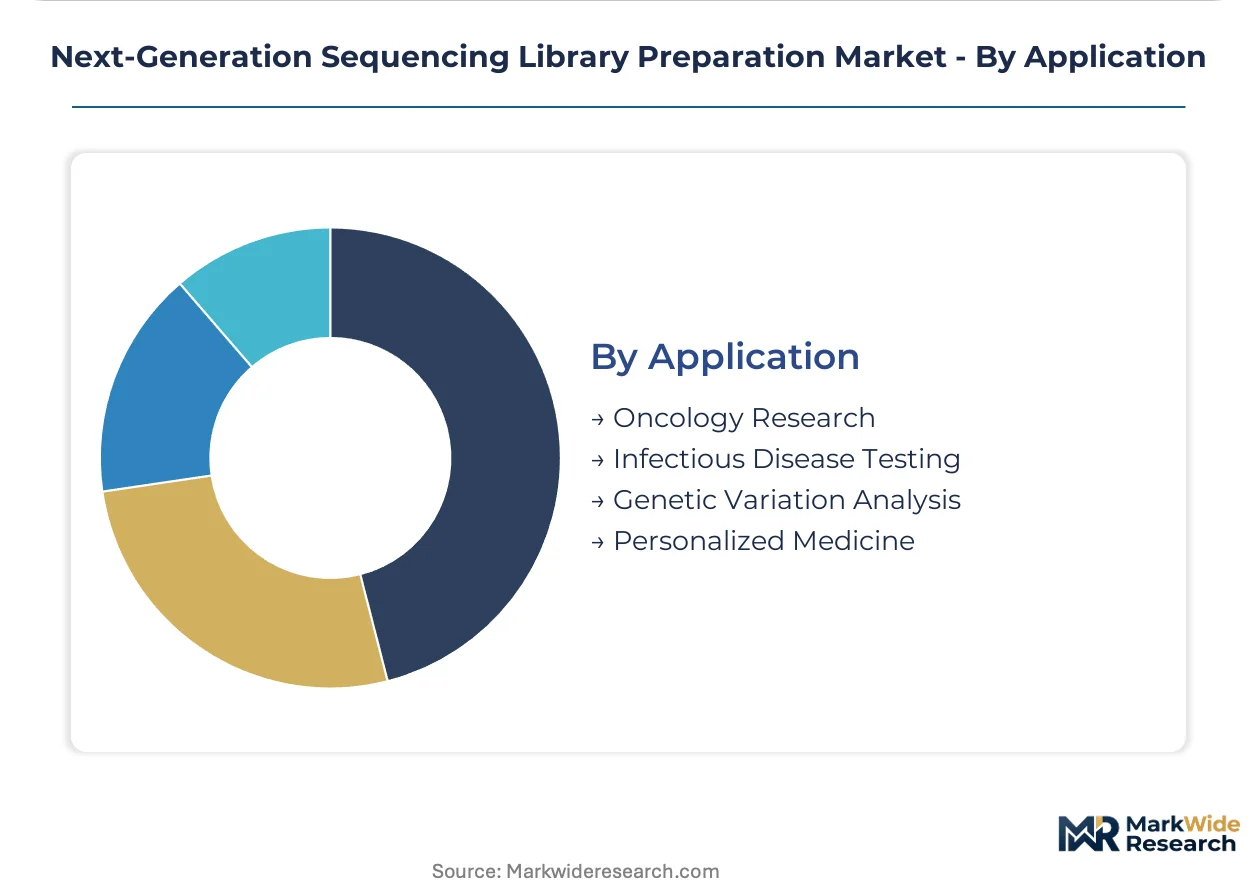
- Oncology Research:Somatic mutation profiling, minimal residual disease monitoring, and circulating tumor DNA analysis dominate NGS library prep consumption. FDA breakthrough device designations for NGS-based oncology tests compress premarket timelines and expand validated assay menus.
- Infectious Disease Testing:Metagenomic sequencing and pathogen whole genome analysis gained traction during pandemic surveillance programs. Public health laboratories in Australia and South Korea maintain strategic reagent stockpiles for outbreak response capabilities.
- Genetic Variation Analysis:Population-scale genomics and rare disease research programs require high-throughput library construction with standardized quality metrics. Biobank initiatives in Sweden and Estonia drive demand for automated processing at scale.
- Personalized Medicine:Pharmacogenomic testing and polygenic risk scoring applications expand beyond research into clinical implementation. Payer coverage decisions for NGS-based therapeutic selection tools remain fragmented across United States commercial insurance plans.
Revenue concentration rests in oncology research; infectious disease testing climbs the fastest as genomic surveillance becomes standard practice.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biotechnology special economic zones in San Diego and Boston concentrate NGS library prep demand through tax-incentive clustering of sequencing core facilities and diagnostic developers. These zones anchor procurement volumes for automated liquid handling platforms and validated reagent kits.
United States
Academic medical centers in California and Massachusetts drive centralized purchasing through multi-hospital health systems controlling 40% of regional reagent spend. FDA breakthrough device designations for oncology tests compress premarket timelines and expand validated assay menus. The San Diego biotechnology corridor hosts sequencing core facilities deploying 24-hour turnaround workflows for urgent cancer cases.
Germany
Reference laboratories in North Rhine-Westphalia and Bavaria anchor European procurement through CAP-accredited facilities processing clinical samples under EMA oversight. The EU In Vitro Diagnostic Regulation's notified body engagement demands expanded clinical evidence packages for CE marking. Heidelberg and Munich clusters concentrate oncology-focused gene panel suppliers with pre-submitted performance evaluation reports.
China
Genomics services sector expansion in Shanghai and Shenzhen pulls through research-use-only reagent imports under streamlined regulatory pathways. The National Medical Products Administration oversees clinical-grade kit manufacturing quality management standards. Yangtze River Delta biotech parks house automated liquid handling platform deployments for population-scale genomics initiatives.
India
Central Drugs Standard Control Organization import license frameworks reduce regulatory friction for research-use-only reagents targeting expanding genomics services. Bangalore and Hyderabad clusters concentrate outsourced testing partnerships and companion diagnostic development programs. Pharmaceutical companies in these cities demand GMP-compliant reagent manufacturing with batch traceability for clinical trial biomarker programs.
Switzerland
Precision medicine research programs in Basel and Zurich drive demand for ultra-low-input library prep chemistries optimized for circulating tumor DNA. Swissmedic oversight aligns with ISO 13485 quality management standards for clinical-grade kit manufacturing. The Basel biotechnology cluster anchors European headquarters for global reagent suppliers seeking regulatory affairs infrastructure.
Next-Generation Sequencing Library Preparation Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Platform-integrated conglomerates leverage installed sequencing hardware bases to sustain captive demand for proprietary chemistries. Reagent-focused specialists compete on input material flexibility and protocol customization for irregular-throughput research settings. The dominant competitive moves are backward integration into enzyme manufacturing and multi-year reagent supply agreements with academic medical center consortia.
Among platform-integrated conglomerates, Illumina, Inc. and Thermo Fisher Scientific Inc. exemplify archetypes that anchor market structure through distinct strategic positions. Illumina represents the sequencing-platform-captive model where hardware installed bases drive pull-through chemistry demand. Thermo Fisher exemplifies backward integration into reagent manufacturing and consumables distribution networks. QIAGEN N.V. occupies a position bridging sample preparation expertise with clinical-grade regulatory documentation capabilities.
| Leading Market Players |
|---|
| Illumina, Inc. |
| Thermo Fisher Scientific Inc. |
| Agilent Technologies, Inc. |
| QIAGEN N.V. |
| F. Hoffmann-La Roche AG |
| Pacific Biosciences of California, Inc. |
| Oxford Nanopore Technologies |
| New England Biolabs Inc. |
| Revvity, Inc. |
| Others |
Cost & Logistics Intelligence
ISO 13485 certification requirements gate qualified supply access and premium-tier pricing for clinical-grade library preparation kits, compressing margins for uncertified manufacturers while rewarding vendors with established quality management infrastructure. This regulatory filter concentrates pricing power among backward-integrated enzyme suppliers and platform-integrated conglomerates that can absorb documentation burdens.
Pricing Analysis
Short lead-time premiums command pricing tiers in automated liquid handling consumables, with cartridge-based reagent supply agreements locking facilities into vendor-specific contracts at standard rates. Three-tier pricing structure across premium, standard, and economy levels separates IVDR-certified clinical kits from research-use-only chemistries and bulk unvalidated reagents. Price differentiation hinges on regulatory documentation depth and input material flexibility for FFPE samples. Pricing pressure stems from group purchasing organization consolidation in United States academic medical centers, with reference laboratories showing lowest price sensitivity due to reimbursement-anchored budgets.
Supply Chain Analysis
Reverse logistics for temperature-sensitive enzyme shipments and expired reagent returns flow through specialized cold-chain distributors serving clinical laboratories in Germany and the United States. Manufacturing concentration centers on Singapore, Switzerland, and the United States for high-fidelity polymerases and transposases, with kit assembly distributed across regional hubs. Raw material dependencies include recombinant enzymes, magnetic bead suspensions, and synthetic adapter oligonucleotides. Single-source vulnerability for transposase biochemistry creates supply chain risk. Distribution runs through direct sales forces for automated platforms and distributor networks for benchtop reagent kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around regulatory compliance capabilities, with EU IVDR transition costs and FDA breakthrough device pathways forcing mid-tier kit vendors toward acquisition or exit.
For Market Incumbents: Acquire specialized enzyme manufacturing assets to secure captive supply of transposases and high-fidelity polymerases against single-source concentration risk. Defend installed base positions through multi-year reagent supply agreements with academic medical center consortia in California and Massachusetts, while investing in IVDR performance evaluation documentation to capture European hospital procurement shelf space before smaller competitors achieve certification. For New Entrants and Emerging Players: Sequencing core facility outsourcing partnerships in India's Bangalore and Hyderabad clusters offer the most penetrable entry point, with CDSCO's streamlined import license framework reducing regulatory friction for research-use-only reagent positioning. Target liquid biopsy workflows for minimal residual disease monitoring, where ultra-low-input chemistry demand outpaces established vendor supply. Pursue co-development agreements with long-read sequencing platform developers for hybrid adapter compatibility. For Investors and Strategic Acquirers: FDA breakthrough device designation announcements for NGS-based oncology tests are the leading indicator that library prep kit volumes will accelerate through diagnostic developer pull-through. Five-to-ten year viability favors platform-integrated conglomerates with sequencing hardware installed bases and regulatory affairs infrastructure over pure-play reagent specialists. Monitor CE marking submission timelines under EU IVDR for early signals of European market access consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Enzyme Manufacturing | Captive supply of transposases eliminates single-source vulnerability for kit manufacturers. |
| IVDR Performance Evaluation Submission | CE marking under EU regulation captures European hospital procurement shelf space. |
| Multi-Year Reagent Supply Agreements | Academic medical center consortia in California and Massachusetts lock in predictable volumes. |
| Hybrid Adapter Chemistry Development | Compatibility with both short-read Illumina and long-read Pacific Biosciences platforms opens white space. |
| Liquid Biopsy Workflow Optimization | Ultra-low-input chemistries for circulating tumor DNA address minimal residual disease monitoring demand. |
Research Approach
Multi-period observation of FDA breakthrough device designations, EU IVDR certification timelines, and academic medical center procurement patterns anchored the trend analysis, supplemented by interviews with sequencing core facility directors, diagnostic development executives, regulatory affairs leads at kit manufacturers, and hospital procurement managers. Secondary validation drew from FDA 510(k) filings, EMA qualification procedure documentation, ClinicalTrials.gov NGS assay registrations, and GPO contract databases. Bottom-up reagent volume modeling triangulated against top-down platform installed base estimates.
Segment-weighting across product type, technology tier, end-user category, and application area structured the analytical framework, with growth rates derived from elasticity modeling against sequencing platform deployment curves and reimbursement pathway expansion. Inputs included laboratory staffing cost indices, automation adoption curves in reference laboratories, and regulatory documentation burden estimates for IVDR transition.
Caveats apply where FDA premarket review pathway revisions, EU IVDR notified body capacity constraints, or novel sequencing platform disruptions could materially shift the outlook. Practitioners should monitor CE marking approval velocities and liquid biopsy reimbursement coding decisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Global Hereditary Cancer Testing Market
Genomics
Global NGS Sample Preparation Market
Genomics
Global Genotyping Assay Market
Genomics
UAE Genetic Testing Market
Genomics
Microarray Biochips Market
Genomics
Short-Read Sequencing Market
Genomics
Transcriptomics Technologies Market
Genomics
Next Generation Genomics Market
Genomics
Whole Genome Amplification Market
Genomics
Genetic Testing Service Market
Genomics
Mendelian Disorders Testing Market
Genomics
China Genetic Testing Market
Genomics
NGS-Based RNA-Sequencing Market
Genomics
Predisposition Biomarkers Market
Genomics
Global Metagenomic Sequencing Market
Genomics
Global Microbiome Sequencing Services Market