
 Europe Digital PCR Market | 2026-2036
Europe Digital PCR Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Digital PCR Market Analytics
Aftermarket service revenue from instrument calibration and assay validation is rewriting profit allocation across the Europe digital PCR landscape. Thermo Fisher Scientific leverages its installed base of QuantStudio systems to capture recurring consumables demand. Bio-Rad Laboratories anchors its position through droplet digital PCR specialization in oncology and cell therapy quality control. QIAGEN N.V. competes via integrated sample-to-insight workflows that reduce laboratory turnaround times.
Digital PCR quantifies nucleic acid targets through absolute molecule counting without standard curves, achieving sensitivity below 0.1% mutant allele frequency for liquid biopsy applications. The technology partitions individual DNA or RNA molecules into thousands of micro-reactions, then applies Poisson statistics to calculate original target concentration. Reagents and consumables dominate value capture given their recurring purchase rhythm against capital-intensive instrument placements. Clinical diagnostics applications expand fastest under IVDR compliance pressure, while research laboratories sustain steady demand for gene expression and copy number variation studies.
The European Medicines Agency (EMA) and notified bodies under the IVDR framework enforce stricter clinical evidence requirements for companion diagnostic claims, elevating barriers for unvalidated platforms. REACH and RoHS directives constrain fluorophore and plastic consumable sourcing, pushing vendors toward sustainable reagent reformulation. Stakeholders must monitor IVDR transition timelines and notified body capacity constraints to avoid supply disruptions for critical oncology assays.
Market Dynamics
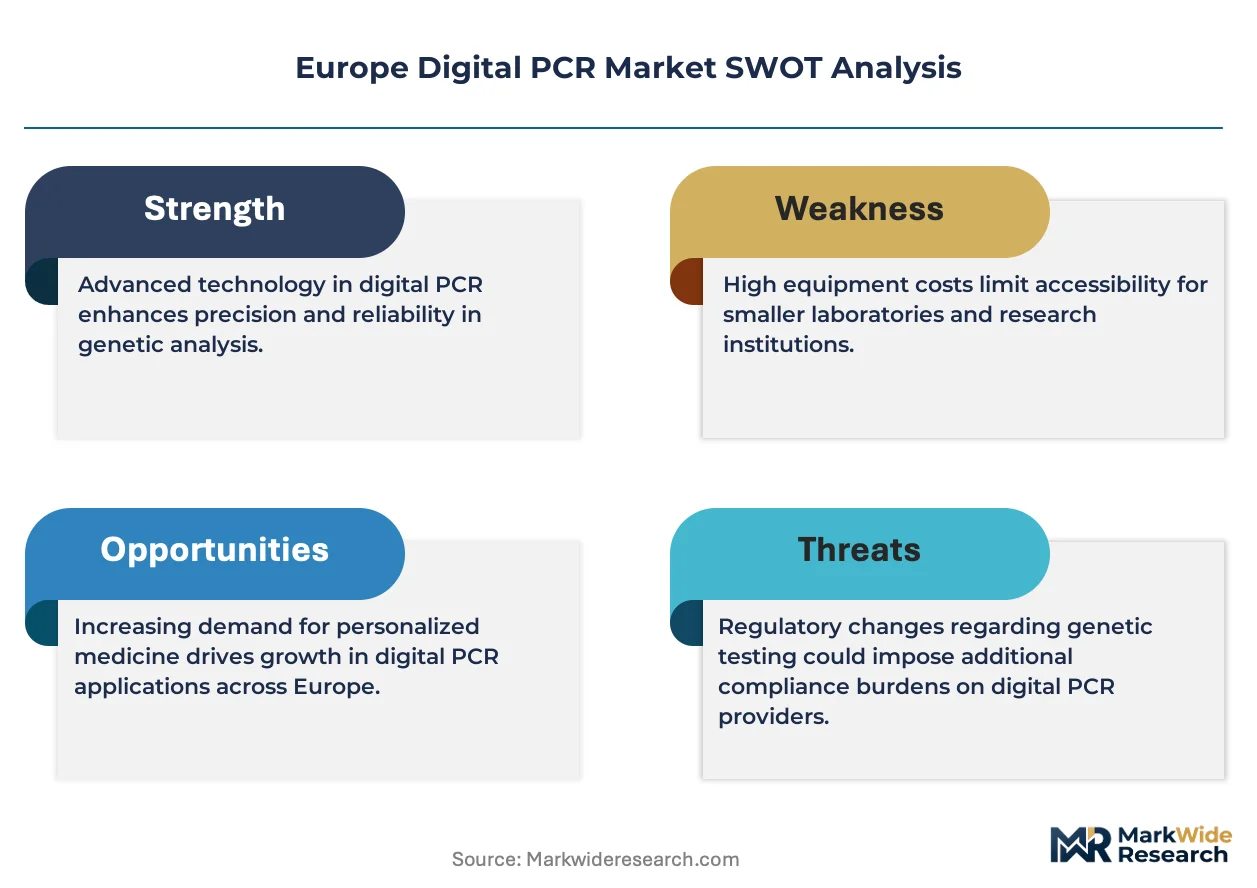
The EU In Vitro Diagnostic Regulation (IVDR) rollout compresses certification timelines while elevating clinical evidence requirements, forcing molecular diagnostics vendors to restructure quality management systems and notified body engagement strategies.
Growth Catalysts
- IVDR Compliance Pressure:The European Medicines Agency mandates stricter performance validation for companion diagnostics, compelling hospitals and reference laboratories to upgrade from quantitative PCR to digital PCR platforms that deliver absolute quantification without standard curves.
- Liquid Biopsy Workflows:Oncology departments across Germany, France, and the United Kingdom deploy digital PCR for circulating tumor DNA detection at mutant allele frequencies below 0.1%, driving instrument placements and recurring consumables demand.
- Cell Therapy Manufacturing:Gene therapy developers adopt droplet digital PCR for vector copy number quantification and residual DNA detection, creating sustained pull from contract development and manufacturing organizations.
Market Restraints
- Fluorophore Supply Concentration:REACH and RoHS directives constrain fluorophore and plastic consumable sourcing from Asian chemical suppliers, pushing vendors toward sustainable reagent reformulation with uncertain performance equivalence.
- Notified Body Bottleneck:IVDR transition timelines collide with limited notified body capacity, extending certification delays for new assay launches and freezing competitive pipeline expansion.
- High Instrument Capital Intensity:Digital PCR platforms require capital commitments exceeding quantitative PCR systems by threefold, restricting adoption in underfunded regional hospital networks and academic core facilities.
Strategic Opportunities
- Central and Eastern Europe Penetration:Poland, Hungary, and the Czech Republic exhibit underdeveloped molecular diagnostics infrastructure where liquid biopsy and precision oncology programs remain nascent, offering first-mover positioning for platform vendors.
- EU Green Deal Alignment:Sustainable reagent packaging and reduced plastic consumable formats qualify for public procurement preferences in France and Germany, creating differentiation for environmentally certified product lines.
- Artificial Intelligence Integration:Machine learning algorithms for droplet classification and data interpretation are virtualizing manual analysis steps, enabling laboratory staff reduction and throughput scaling in high-volume reference laboratories.
Industry Challenges
- Bioinformatics Talent Scarcity:Digital PCR data interpretation requires specialized expertise in Poisson statistics and quality control algorithm validation, creating recruitment bottlenecks in European clinical laboratories.
- Legacy System Integration:Hospital laboratory information management systems lack native digital PCR connectivity, forcing middleware development and custom validation efforts that extend deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Digital PCR Market |
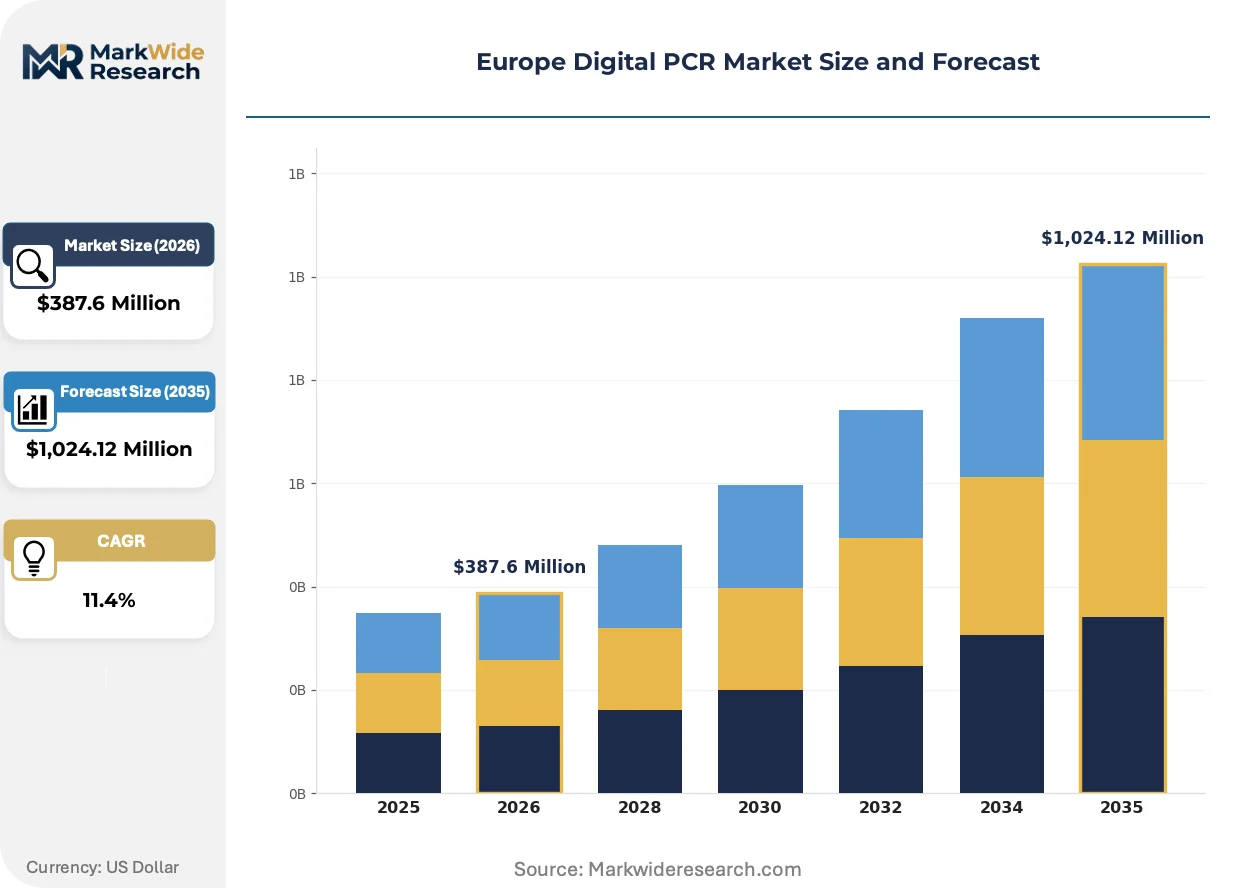
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Software, Accessories Application: Clinical Diagnostics, Research, Biotechnology, Environmental Testing End User: Hospitals, Academic Institutions, Research Laboratories, Contract Research Organizations Technology: Microfluidics, Nanotechnology, Bioinformatics, Digital Imaging |
| Companies Covered | QIAGEN N.V., Thermo Fisher Scientific, F. Hoffmann-La Roche, Bio-Rad Laboratories, Merck KGaA, Stilla Technologies, Agilent Technologies, Abbott Laboratories, Becton Dickinson, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Digital PCR Market Evolving Landscape
Digital PCR instrumentation is virtualizing through cloud-based analysis platforms and artificial intelligence-assisted droplet classification, compressing the boundary between hardware performance and software-enabled workflow efficiency.
Next-generation digital PCR systems partition nucleic acid samples into twenty-thousand-plus micro-reactions using nanofluidic chips rather than traditional emulsion droplets. Clinical laboratories in Germany and France adopt these platforms for minimal residual disease monitoring in hematological malignancies. The technology is virtualizing the role of specialized technicians by automating threshold setting and quality control flagging that previously demanded expert manual review.
The IVDR framework enforces Unique Device Identification (UDI) and post-market surveillance requirements that exceed the Medical Device Directive (MDD) scope. Manufacturers must maintain technical documentation and performance data across the entire product lifecycle, elevating compliance costs. Oncology companion diagnostic developers face the steepest adaptation burden, as EMA now requires parallel drug-diagnostic approval evidence that delays platform launches.
Consolidated purchasing through centralized hospital procurement consortia is displacing decentralized laboratory buying authority across France, Italy, and Spain. National tender frameworks now bundle instrument, reagent, and service contracts into multi-year agreements that favor vendors with broad installed bases. This concentration is most visible in the United Kingdom, where NHS Supply Chain coordinates molecular diagnostics acquisition for over two hundred hospital trusts, compressing price negotiation leverage for specialized regional suppliers.
Europe Digital PCR Market Segmentation
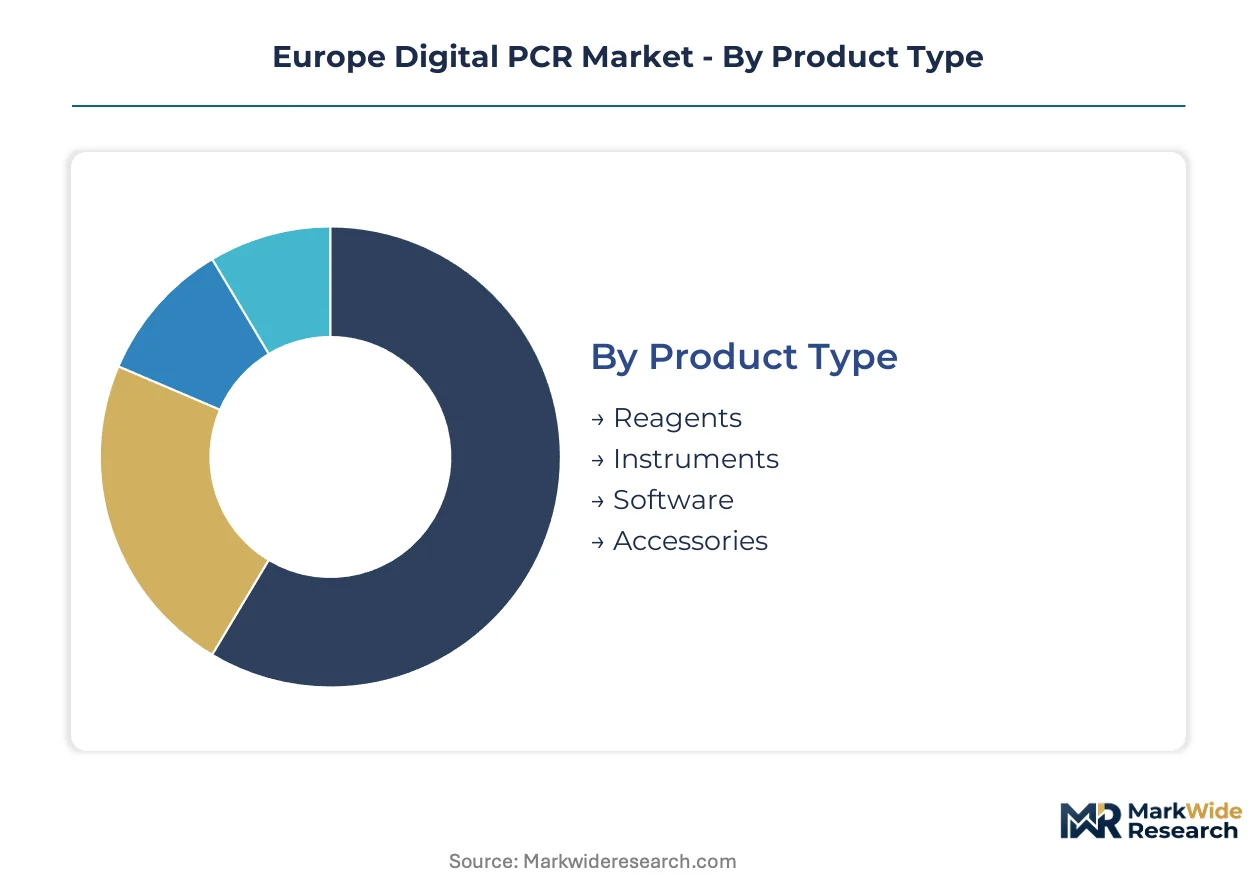
Digital PCR segmentation in Europe reflects divergent procurement patterns across clinical diagnostics and research environments. Reagent recurring revenue models, IVDR compliance pathways, and liquid biopsy workflow integration each reshape how vendors prioritize product development and geographic deployment.
Product Type:
The use-case spectrum spans single-run consumables through decade-scale capital equipment, with profit pools concentrating in recurring purchase categories rather than instrument placements.
- Reagents:Enzyme master mixes, fluorescent probes, and droplet generation oils constitute the recurring revenue backbone of digital PCR economics. German reference laboratories and French hospital networks drive bulk purchasing agreements under national tender frameworks, with IVDR performance validation requirements elevating barriers for unproven formulations.
- Instruments:Thermal cyclers, droplet generators, and fluorescence readers represent capital commitments exceeding quantitative PCR platforms by substantial multiples. United Kingdom NHS Supply Chain consolidates procurement for over two hundred hospital trusts, compressing price negotiation leverage and favoring vendors with established service infrastructure.
- Software:Cloud-based analysis platforms and AI-assisted droplet classification tools virtualize manual interpretation steps. REACH compliance constraints shape data localization requirements for European deployments.
- Accessories:Cartridge consumables, sealing films, and quality control reference materials complete workflow integration. RoHS directives constrain fluorophore sourcing from Asian chemical suppliers.
Established volume favors Reagents; emerging adoption favors Software.
Application:
Cost tier stratification separates regulated clinical claims from exploratory research budgets, with reimbursement pathways determining viable price points.
- Clinical Diagnostics:Oncology companion diagnostics and minimal residual disease monitoring command premium pricing under EMA parallel approval requirements. Liquid biopsy workflows for circulating tumor DNA detection at sub-0.1% mutant allele frequency concentrate demand in German and French precision oncology programs.
- Research:Gene expression quantification and copy number variation studies sustain steady instrument utilization in academic core facilities. United Kingdom Research and Innovation funding cycles shape replacement timelines for aging quantitative PCR infrastructure.
- Biotechnology:Cell therapy developers deploy droplet digital PCR for vector copy number quantification and residual DNA detection. Contract development and manufacturing organizations in Belgium and the Netherlands create sustained pull for validated assay formats.
- Environmental Testing:Pathogen detection in water and food safety applications employs digital PCR for absolute quantification without standard curve dependencies. Regulatory surveillance programs in Italy and Spain expand method validation requirements.
Clinical Diagnostics commands the steepest compliance investment; Biotechnology offers the most predictable volume expansion trajectory.
End User:
Customer type determines procurement authority concentration, with centralized purchasing displacing decentralized laboratory autonomy across Southern Europe.
- Hospitals:Integrated health systems in France and Germany bundle instrument, reagent, and service contracts into multi-year agreements. IVDR transition timelines collide with limited notified body capacity, freezing competitive pipeline expansion for new platform launches.
- Academic Institutions:Core facility shared-resource models spread capital costs across multiple principal investigator groups. Polish and Hungarian molecular diagnostics infrastructure remains underdeveloped relative to Western European benchmarks.
- Research Laboratories:Biotechnology company R&D operations and independent research institutes prioritize throughput scalability and automation compatibility. Bioinformatics talent scarcity creates recruitment bottlenecks for Poisson statistics expertise.
- Contract Research Organizations:Central and Eastern European CROs exploit cost arbitrage for cell therapy quality control and assay validation services. EU Green Deal procurement preferences favor environmentally certified product lines in public tenders.
Hospitals dominate current purchasing volume; Contract Research Organizations are climbing the fastest as manufacturing outsourcing accelerates.
Technology:
Maturity gradients separate established partitioning methods from emerging integration layers, with nanofluidic chip platforms displacing traditional emulsion droplet systems.
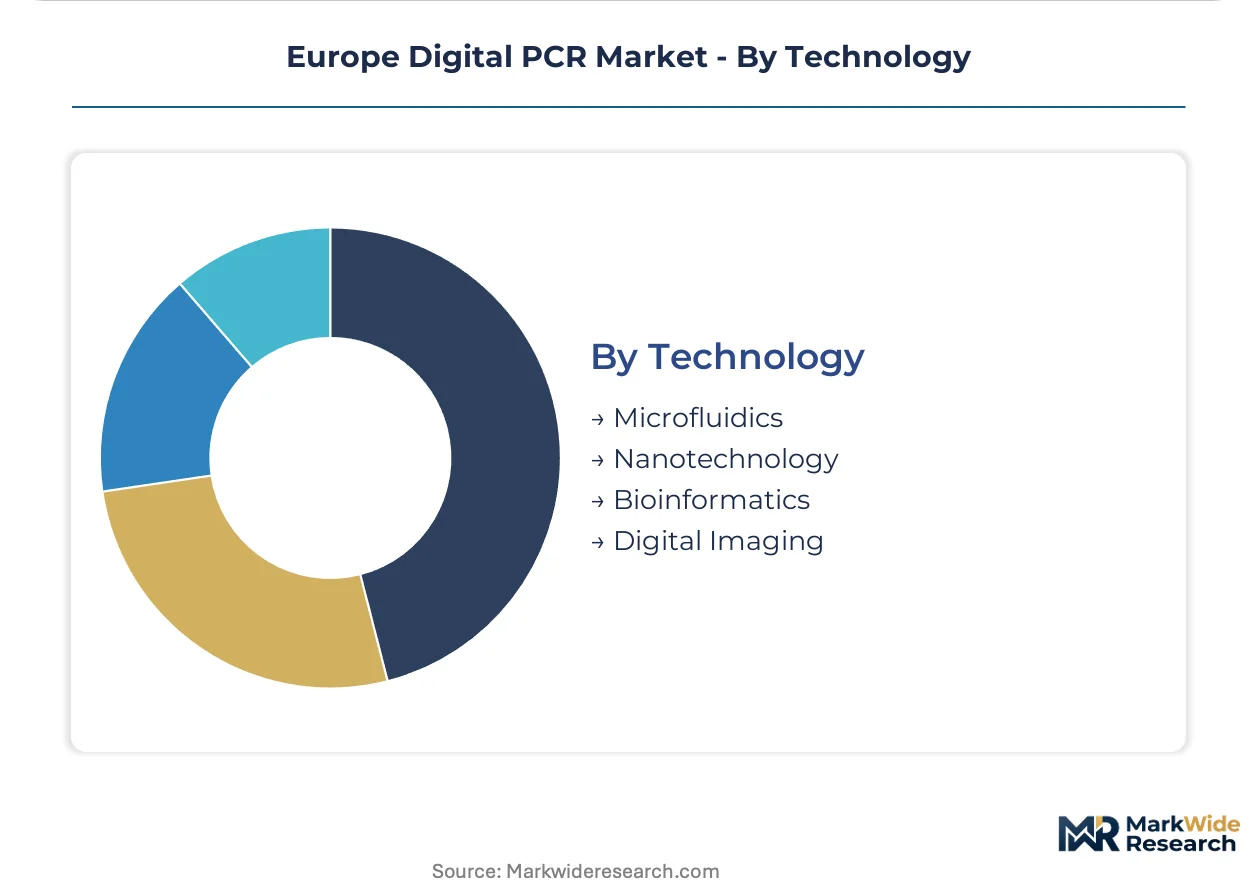
- Microfluidics:Nanofluidic chip architectures partition samples into twenty-thousand-plus micro-reactions with superior precision. German and French clinical laboratories adopt these platforms for hematological malignancy monitoring, automating threshold setting that previously demanded expert manual review.
- Nanotechnology:Surface chemistry engineering and droplet stabilization materials enable smaller reaction volumes and reduced reagent consumption. REACH chemical registration requirements constrain fluorophore reformulation timelines.
- Bioinformatics:Machine learning algorithms for droplet classification compress analysis turnaround times. Legacy laboratory information management systems lack native connectivity, forcing middleware development.
- Digital Imaging:High-resolution fluorescence detection and multi-channel spectral unmixing expand multiplexing capabilities. Reduced plastic consumable formats qualify for sustainable procurement preferences.
Microfluidics anchors near-term placements; Bioinformatics is gaining share fastest as workflow virtualization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys digital PCR predominantly for hematological malignancy monitoring, while France concentrates demand in centralized hospital procurement frameworks; the United Kingdom channels adoption through NHS Supply Chain consolidation, and Central European markets exhibit infrastructure gaps that reshape go-to-market economics.
Germany
Precision oncology programs and cell therapy manufacturing anchor demand in Bavaria and North Rhine-Westphalia. EMA parallel approval requirements for companion diagnostics elevate compliance investment for platform vendors. Berlin-Brandenburg clusters host reference laboratories adopting nanofluidic chip systems for minimal residual disease workflows.
France
Centralized hospital procurement consortia bundle instrument, reagent, and service contracts into multi-year agreements. EU Green Deal procurement preferences favor environmentally certified reagent packaging in public tenders. The Île-de-France region concentrates liquid biopsy adoption within integrated health systems.
United Kingdom
NHS Supply Chain coordinates molecular diagnostics acquisition for over two hundred hospital trusts, compressing price negotiation leverage. IVDR transition timelines collide with limited notified body capacity, freezing competitive pipeline expansion. Greater London anchors demand for circulating tumor DNA detection at sub-0.1% mutant allele frequency.
Netherlands
Contract development and manufacturing organizations in the Randstad region create sustained pull for vector copy number quantification and residual DNA detection. REACH chemical registration requirements constrain fluorophore reformulation timelines. Eindhoven-based biotechnology clusters adopt droplet digital PCR for gene therapy quality control.
Poland
Underdeveloped molecular diagnostics infrastructure offers first-mover positioning for platform vendors establishing liquid biopsy programs. Academic core facilities in Warsaw and Kraków sustain steady instrument utilization for gene expression studies. EU structural funds accelerate laboratory modernization in regional hospital networks.
Europe Digital PCR Market Competitive Landscape
Capability concentration sits with specialized droplet digital PCR developers; scale advantage sits with diversified life science conglomerates. The vendor base stratifies across three tiers: integrated sample-to-insight workflow providers, standalone instrument specialists, and consumables-focused reagent suppliers. Strategic moves center on IVDR compliance infrastructure investment and aftermarket service network expansion to capture recurring revenue.
Among diversified conglomerates, Thermo Fisher Scientific and QIAGEN N.V. occupy positions emphasizing installed base leverage and integrated workflow architectures. Bio-Rad Laboratories exemplifies the specialization tier through droplet digital PCR focus. These three anchors represent distinct competitive archetypes: scale-driven platform consolidation, sample-to-insight integration, and technology-specific depth.
| Leading Market Players |
|---|
| QIAGEN N.V. |
| Thermo Fisher Scientific |
| F. Hoffmann-La Roche |
| Bio-Rad Laboratories |
| Merck KGaA |
| Stilla Technologies |
| Agilent Technologies |
| Abbott Laboratories |
| Becton Dickinson |
| Others |
Value Network & Pricing Analysis
The Rhine-Main chemical cluster in Germany anchors fluorophore and polymer consumable production for digital PCR workflows, with capacity constraints under REACH registration timelines translating directly into reagent pricing power for validated suppliers.
Pricing Analysis
Long-term offtake contracts dominate hospital and reference laboratory procurement across France and Germany, with multi-year instrument-reagent-service bundles compressing spot-market participation. Price differentiation hinges on IVDR certification tier and after-sales service bundling, with notified body-validated assays commanding substantial premiums over research-use-only alternatives. Cost compression in the mid-tier instrument segment is intensifying because NHS Supply Chain consolidation aggregates purchasing power across United Kingdom hospital trusts. Academic core facilities exhibit the highest price sensitivity due to grant-funded capital cycles, while cell therapy CDMOs prioritize assay validation certainty over unit cost.
Supply Chain Analysis
Contract manufacturing for digital PCR consumables concentrates in Germany, the Netherlands, and Switzerland, with specialized polymer injection molding and surface chemistry functionalization feeding cartridge production. Raw material dependencies span fluorophores from specialized chemical suppliers, high-purity plastics, and enzyme master mix components. Single-source vulnerability in notified body capacity creates certification bottlenecks that freeze competitive pipeline expansion. Distribution runs through centralized hospital procurement consortia in France and Italy, displacing decentralized laboratory buying authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe digital PCR market represents high-growth disruption as IVDR compliance mandates absolute quantification platforms for companion diagnostics, with EMA parallel approval requirements creating irreversible technology substitution pressure.
For Market Incumbents: Insulate installed base positions through captive reagent supply agreements and accelerated IVDR validation pipelines for oncology assay menus. The notified body bottleneck threatens competitive pipeline expansion for unvalidated platforms; vertical integration into fluorophore formulation under REACH compliance reduces third-party chemical dependency. For New Entrants and Emerging Players: Build out Central and Eastern European presence where molecular diagnostics infrastructure remains underdeveloped relative to Western benchmarks. Poland and Hungary offer first-mover positioning for liquid biopsy program establishment; partner with academic core facilities to anchor reference laboratory adoption before national tender consolidation advances. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized droplet digital PCR developers with IVDR-compliant assay portfolios over diversified platform conglomerates. The five-to-ten year viability window rewards acquisition targets possessing notified body relationships and sustainable reagent packaging certifications; monitor EMA companion diagnostic approval velocity as inflection signal for platform demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Compliance Infrastructure Investment | Notified body engagement and technical documentation capabilities determine market access under EMA enforcement timelines. |
| Sustainable Reagent Reformulation | EU Green Deal procurement preferences in France and Germany favor environmentally certified packaging formats. |
| Aftermarket Service Network Expansion | Instrument calibration and assay validation contracts capture recurring revenue beyond capital placement cycles. |
| AI-Assisted Droplet Classification Development | Machine learning algorithms for data interpretation reduce laboratory staffing requirements and accelerate turnaround. |
| Central and Eastern European Market Entry | Underdeveloped molecular diagnostics infrastructure in Poland and Hungary offers first-mover positioning for platform vendors. |
Research Methodology
The analysis maps reagent formulations, instrument platforms, software analysis tools, and service contracts, each validated through laboratory directors, procurement managers at hospital networks, regulatory affairs specialists, and CDMO quality control leads. Primary interviews with these stakeholders combined with secondary validation against EMA guidance documents, IVDR technical documentation requirements, notified body capacity reports, and EU structural fund disbursement records established segment boundaries. Bottom-up instrument placement counts and top-down molecular diagnostics market sizing provided triangulation checks.
The assumption-set held IVDR transition timelines and notified body capacity constraints within observed patterns while varying cell therapy manufacturing growth and precision oncology program expansion across scenarios. Segmentation dimensions modeled include product type, application area, end-user category, and technology platform, with regional regulatory cluster as an additional cross-cutting variable. CAGRs derived from instrument replacement cycles, consumables pull-through rates, and service contract renewal patterns across the projection horizon, incorporating liquid biopsy adoption curves and cell therapy manufacturing capacity buildouts as industry-specific demand drivers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by specialized nanofluidic chip developers or consolidated purchasing consortiums would shift outcomes beyond modeled ranges. Quarterly review of EMA companion diagnostic approval velocity, notified body capacity expansion announcements, and EU structural fund laboratory modernization disbursements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Predisposition Biomarkers Market
Genomics
Mrna Sequencing Market
Genomics
Global Nucleic Acid Labeling Market
Genomics
Plant Genomics Market
Genomics
SNP Genotyping Market
Genomics
Global Clinical Oncology Next Generation Sequencing Market
Genomics
Global Metagenomic Sequencing Market
Genomics
Immunogenetics Market
Genomics
Single-Cell Omics Market
Genomics
Whole Plasmid Sequencing Market
Genomics
Europe Epigenetics Market
Genomics
Restriction Endonucleases Market
Genomics
Next-Generation Sequencing for Non-Invasive Prenatal Testing Market
Genomics
Molecular Biomarkers for Cancer Detection Market
Genomics
Genetic Testing Market
Genomics
Global Nutrigenomics Market