
 Spatial Genomics and Transcriptomics Market | 2026-2036
Spatial Genomics and Transcriptomics Market Size, Share, and Industry Trends Forecast 2026-2036
Spatial Genomics and Transcriptomics Market Intelligence
The traditional divide between computational biologists and wet-lab molecular biologists is collapsing due to the data-intensive nature of spatial platforms. This shift requires a new generation of scientists skilled in both areas. In this environment, 10x Genomics leverages its strong position in single-cell analysis to offer integrated spatial solutions. Akoya Biosciences differentiates with its high-plex protein and RNA imaging platforms for tissue analysis. Meanwhile, NanoString Technologies competes with its digital spatial profiling systems for biomarker discovery.
Spatial genomics and transcriptomics refers to a class of methods that measure gene activity and its location within the native tissue architecture. These techniques provide a cellular or subcellular map of gene expression, preserving the spatial context lost in bulk sequencing methods. Its primary purpose is to elucidate complex biological processes, such as tumor microenvironments or neural circuits. Analysis of the market shows instruments and reagents constitute the largest product type segments. Within applications, cancer research and neuroscience studies represent the areas with the highest investment and publication volume.
The regulatory environment is shaped by agencies governing clinical research and diagnostics. The US FDA's framework for companion diagnostics and the EU's Medical Device Regulation (MDR) for instruments influence the path to clinical translation. These regulations mandate stringent validation for any spatial technology intended for patient diagnosis or treatment selection. Stakeholder decisions will center on selecting platforms that offer a clear pathway from basic research to clinically validated applications.
Market Dynamics
The convergence of high-throughput sequencing with advanced imaging is the central force shaping the market. This integration generates massive, multi-modal datasets, compelling a unification of computational and wet-lab skill sets and driving demand for platforms with integrated analysis software.
Growth Catalysts
- Advancing Imaging Modalities:The development of high-plex and super-resolution imaging technologies allows for unprecedented detail in mapping gene and protein expression, accelerating discovery in complex fields like neuroscience and immunology.
- Translational Cancer Research:Intense investment in understanding the tumor microenvironment to develop next-generation immunotherapies and targeted treatments provides a significant demand stream for spatial analysis platforms.
- Government Research Funding:Increased public funding for precision medicine and genomics, such as initiatives from the National Institutes of Health (NIH) in the US, directly supports academic adoption of spatial technologies.
Market Restraints
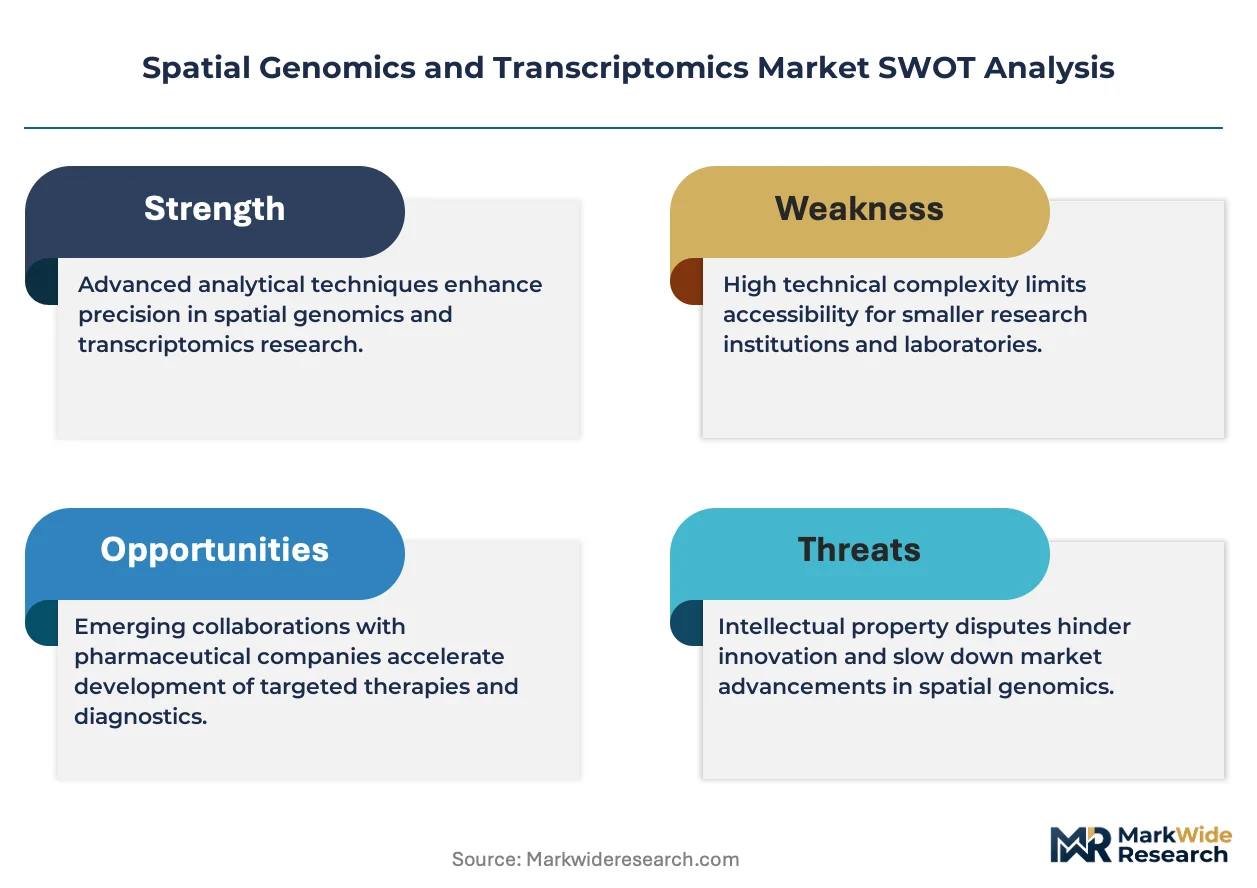
- High Capital and Operational Costs:The substantial upfront investment for spatial analysis instruments, combined with high per-sample reagent costs, limits adoption to well-funded research institutions and large biopharmaceutical companies.
- Data Analysis Bottlenecks:The immense size and complexity of spatial omics datasets require significant computational infrastructure and specialized bioinformatics expertise, which remains a widespread technical hurdle for many organizations.
- Stringent Regulatory Pathways:The path to clinical application is constrained by rigorous validation requirements from bodies like the US FDA for companion diagnostics and the EU's MDR for instruments, slowing translation from research to diagnostics.
Strategic Opportunities
- Expansion into Clinical Diagnostics:Developing validated spatial biomarker panels for patient stratification in oncology and other diseases offers a significant value-creation opportunity beyond the research-use-only market.
- Multi-Omic Integration:The convergence of spatial transcriptomics with proteomics and metabolomics on single platforms creates an opportunity to provide a more holistic biological understanding, commanding premium value.
- Pharmacotoxicology Applications:Applying spatial technologies in preclinical safety and toxicology studies to visualize drug-induced tissue damage at a cellular level presents a new application area within pharmaceutical development.
Industry Challenges
- Bioinformatics Talent Scarcity:A persistent shortage of scientists possessing the dual expertise required for sophisticated spatial data analysis and experimental biology impedes the effective utilization of generated data.
- Lack of Methodological Standardization:The absence of standardized protocols for data processing, quality control, and analysis across different commercial platforms hinders the ability to compare and integrate results from different studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spatial Genomics and Transcriptomics Market |
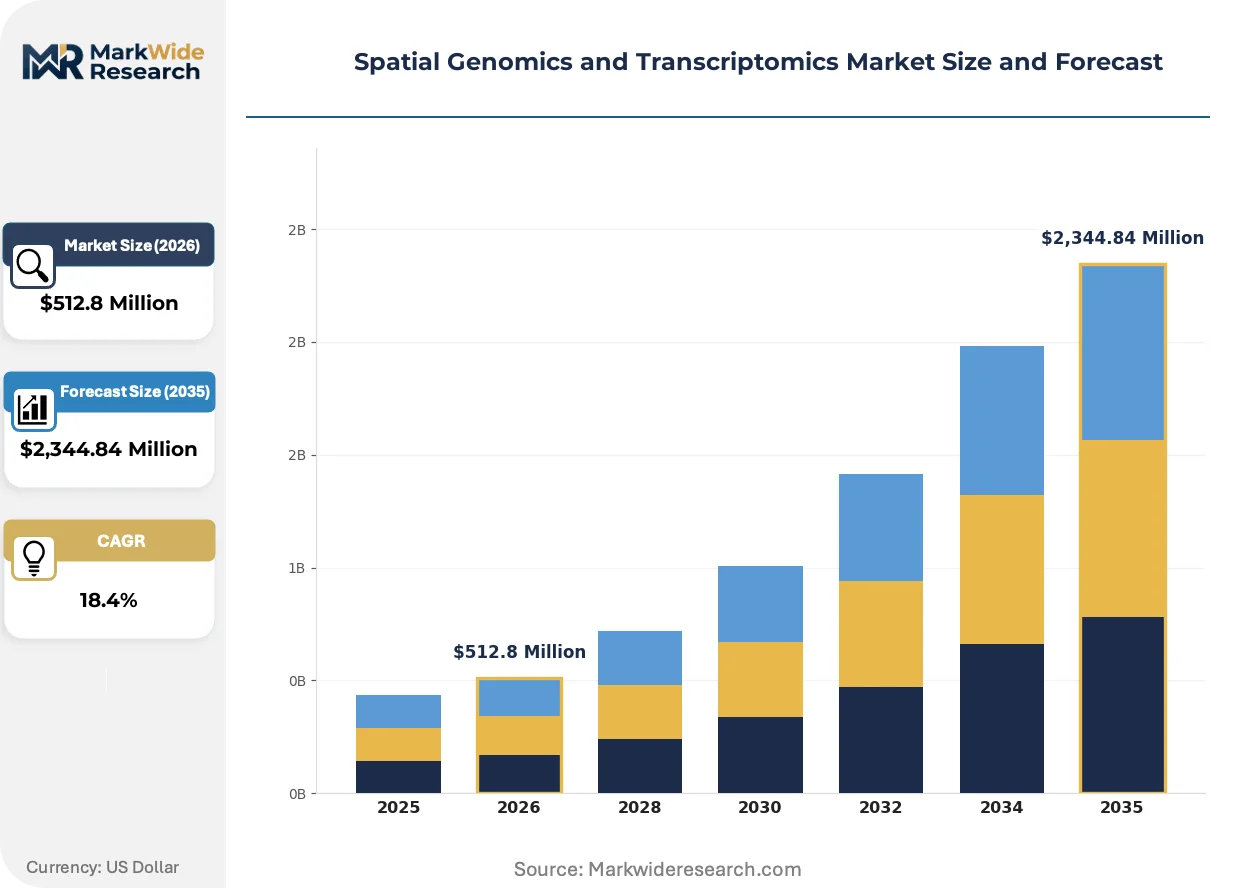
| Market Size in 2026 | $512.8 Million |
| Market Size in 2035 | $2,344.84 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: In situ Hybridization, Spatial Transcriptomics Sequencing, Multiplexed Error-Robust FISH, Nanostring, Imaging Mass Cytometry, Slide-seq Product Type: Reagents, Instruments, Software Platforms, Consumables, Assay Kits, Services Application: Cancer Research, Neuroscience Studies, Immunology Analysis, Drug Discovery, Plant Genomics, Developmental Biology End User: Academic Research Institutes, Biotechnology Firms, Pharmaceutical Companies, Contract Research Organizations, Diagnostics Laboratories, Government Research Centers |
| Companies Covered | 10x Genomics, Bruker (Bruker Spatial Biology), NanoString Technologies, Bio-Techne, Illumina, Akoya Biosciences, Dovetail Genomics, Standard BioTools, Vizgen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spatial Genomics and Transcriptomics Market Strategic Shifts & Innovations
The market's evolution is defined by a push towards higher throughput, greater multiplexing capabilities, and the integration of multi-omic data layers. This technological maturation is happening alongside the development of clearer regulatory frameworks for clinical translation.
Advanced *in situ* sequencing methods provide the ability to directly sequence RNA within morphologically preserved tissue, offering high resolution and specificity. Pharmaceutical research teams are adopting these techniques in preclinical studies to precisely map drug effects and identify potential toxicity signatures. This direct-readout capability is supplanting older, lower-plex methods like traditional fluorescence *in situ* hybridization (FISH) in complex tissue analysis.
The European Union's Medical Device Regulation (MDR) establishes a more rigorous legal framework for instruments and software intended for diagnostic use. This regulation heightens the requirements for clinical evidence, risk management, and post-market surveillance for manufacturers. Consequently, companies targeting the European clinical market must now allocate significant resources to generating validation data and maintaining extensive technical documentation.
A distinct shift in user behavior sees many research labs favoring access to spatial technologies through contract research organizations (CROs) and core facilities. This service-based model allows institutions to bypass the high capital expenditure and specialized expertise required for in-house operation. The trend is particularly visible within academic research clusters in the United States and Germany where budget cycles often favor operational expenses over large capital outlays.
Spatial Genomics and Transcriptomics Market Segmentation
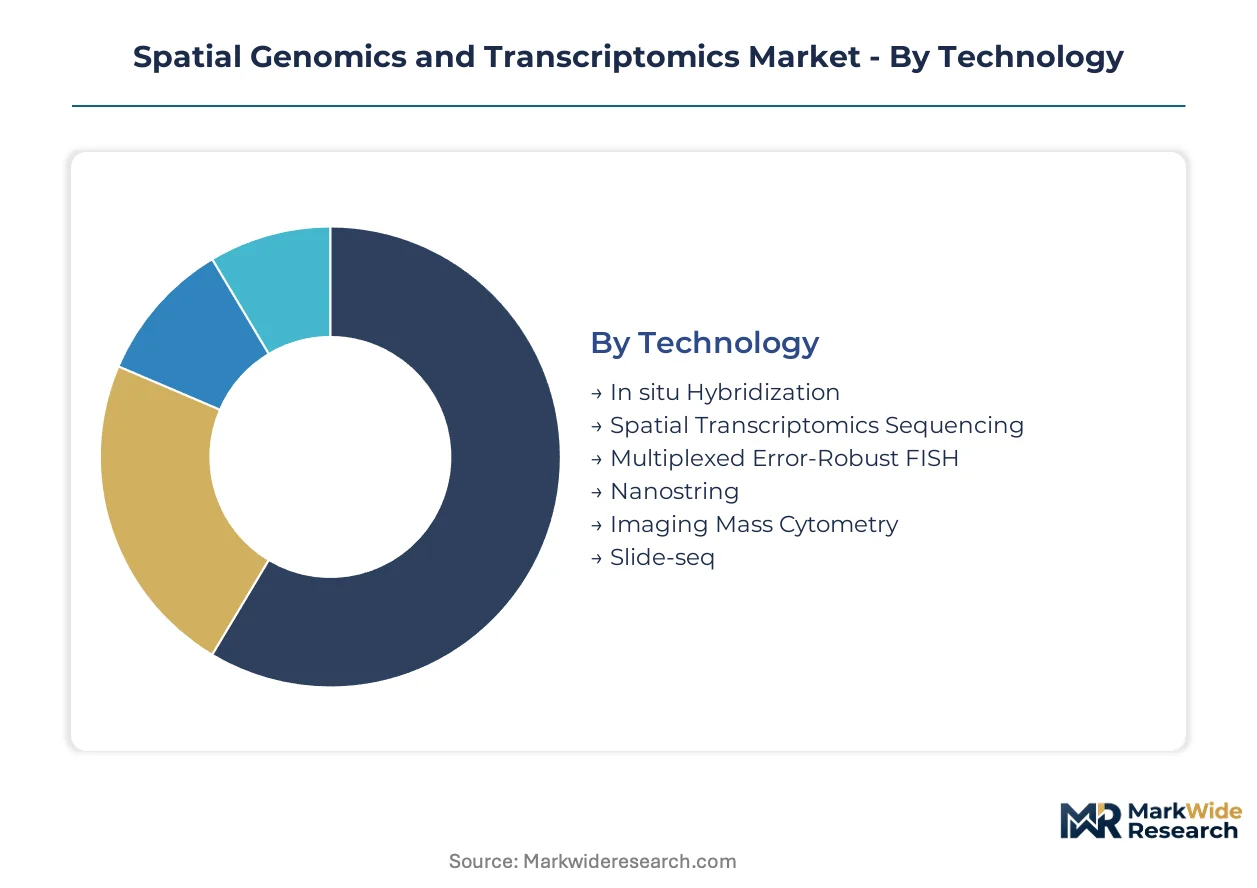
The spatial genomics and transcriptomics market categorizes distinct technological approaches and end-user applications. Understanding these segments is crucial for stakeholders to identify areas of concentrated investment and emerging opportunities. This segmentation highlights where innovation is driving new capabilities and where established methods maintain their utility.
Technology:
Regulatory considerations often differentiate spatial technologies based on their potential for clinical translation and data validation. This distinction influences adoption patterns across research and diagnostic settings.
- In situ Hybridization:This foundational technique employs labeled probes to detect specific RNA or DNA sequences directly within tissue sections. Demand concentrates in academic research for initial gene localization studies, driven by its relatively lower cost for targeted analysis.
- Spatial Transcriptomics Sequencing:High-throughput sequencing methods capture and map RNA expression profiles across tissue sections, providing comprehensive genomic data with spatial context. Biopharmaceutical companies adopt this for drug target identification, compelled by the need for multi-gene analysis in complex disease models.
- Multiplexed Error-Robust FISH:This advanced method uses combinatorial labeling and error-robust encoding to visualize numerous RNA targets simultaneously at subcellular resolution. Academic centers use this for detailed cell-type specific analysis.
- Nanostring:Digital spatial profiling systems offer highly multiplexed protein and RNA detection from spatially defined regions of interest. Translational research relies on this for biomarker discovery.
- Imaging Mass Cytometry:This technique combines flow cytometry principles with mass spectrometry to analyze multiple protein markers in tissue sections. Immunology studies employ this for deep immune cell phenotyping.
- Slide-seq:A bead-based spatial transcriptomics method provides genome-wide expression data at near single-cell resolution across tissue. Neuroscience researchers use this to map gene expression in brain regions.
Established volume favors In situ Hybridization; emerging adoption favors Spatial Transcriptomics Sequencing.
Product Type:
The cost structure of spatial genomics and transcriptomics solutions varies significantly, impacting accessibility and operational budgets for different research entities. Initial capital outlay versus recurring operational expenses shapes procurement decisions.
- Reagents:These consumable chemical and biological components, including antibodies, probes, and enzymes, are essential for executing spatial experiments. Pharmaceutical companies represent a major demand driver for high-quality, validated reagents due to their continuous experimental throughput and stringent quality control requirements.
- Instruments:Specialized hardware systems, such as automated imagers, sequencers, and liquid handlers, enable the capture and analysis of spatial data. Academic research institutes represent a significant segment for instrument adoption, driven by government funding for cutting-edge research infrastructure.
- Software Platforms:These computational tools are critical for data processing, visualization, and advanced bioinformatics analysis of complex spatial datasets. Biotechnology firms rely on integrated software for efficient data interpretation.
- Consumables:Items like slides, microfluidic chips, and reaction vessels are single-use components necessary for each experiment. Contract research organizations drive demand for cost-effective consumables.
- Assay Kits:Pre-packaged and optimized sets of reagents and protocols streamline specific spatial genomics applications. Diagnostics laboratories utilize these for standardized testing.
- Services:External providers offer spatial omics experiments, data analysis, and consulting to organizations lacking in-house capabilities. Small biotechnology firms frequently outsource these specialized services.
The steepest expansion trajectory is for Services, while Reagents maintain stable, high-volume demand.
Application:
The primary focus of research and development efforts within specific disease areas drives the application landscape for spatial technologies. The complexity of biological questions dictates the type of spatial method employed.
- Cancer Research:Studies investigating tumor microenvironments, immunotherapy response, and precision oncology leverage spatial methods to map cellular interactions and gene expression within solid tumors. This application receives substantial investment from biopharmaceutical companies seeking new therapeutic targets and biomarkers.
- Neuroscience Studies:Research into brain disorders, neural circuits, and cellular heterogeneity within the central nervous system benefits from high-resolution spatial mapping of gene activity. Academic institutions in the United States and Germany drive demand for these complex analyses, supported by significant public funding.
- Immunology Analysis:Understanding immune cell localization and activation within tissues is critical for autoimmune diseases and infectious disease research. Biotechnology firms utilize spatial platforms for this purpose.
- Drug Discovery:Identifying drug targets, assessing drug efficacy, and understanding mechanisms of action benefit from spatially resolved molecular insights. Pharmaceutical companies integrate these techniques into their preclinical pipelines.
- Plant Genomics:Investigating gene expression patterns in plant tissues to understand development, stress responses, and crop improvement. Government research centers use spatial tools for agricultural science.
- Developmental Biology:Mapping gene expression during embryonic development and tissue formation provides insights into fundamental biological processes. Academic research institutes apply these methods for basic scientific discovery.
Investment volume is highest in Cancer Research; emerging applications show promise in Plant Genomics.
End User:
Different customer types possess distinct resource allocations, research objectives, and regulatory requirements, influencing their adoption patterns for spatial genomics and transcriptomics. These user groups dictate the market's demand profile.
- Academic Research Institutes:Universities and non-profit research centers conduct fundamental scientific discovery, often acting as early adopters of new technologies. These institutions, particularly in the United States, drive significant demand for spatial platforms, supported by government grants from entities like the NIH.
- Biotechnology Firms:Innovative companies focus on developing and commercializing new biological products and technologies, often bridging basic research with clinical applications. These firms, concentrated in clusters like Boston and San Francisco, invest in spatial tools for novel biomarker identification and therapeutic development.
- Pharmaceutical Companies:Large corporations engaged in drug discovery, development, and manufacturing utilize spatial technologies for target validation, preclinical testing, and patient stratification. Global pharmaceutical giants integrate these platforms into their extensive R&D pipelines.
- Contract Research Organizations:These service providers offer specialized research support to pharmaceutical, biotechnology, and academic clients, often providing access to advanced spatial platforms without significant capital outlay. CROs facilitate broader access to spatial technologies for smaller entities.
- Diagnostics Laboratories:Clinical laboratories aim to translate spatial biomarkers into diagnostic tests for disease detection, prognosis, and treatment selection. These labs focus on validated, high-throughput systems.
- Government Research Centers:Publicly funded institutions conduct research on public health, defense, and foundational science, contributing to technology adoption and method development. Centers in China and Germany are increasing their spatial omics capabilities.
The largest volume of foundational research originates from Academic Research Institutes; the commercialization momentum gathers with Biotechnology Firms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US FDA's regulatory framework for companion diagnostics significantly influences the clinical translation of spatial genomics and transcriptomics technologies within the United States. This regulatory environment, coupled with substantial public and private investment, shapes regional adoption patterns. Global demand concentrations for these advanced platforms are observed in key research and biopharma hubs across multiple countries.
United States
Drug discovery and translational research drive significant demand for spatial platforms in the United States. The National Institutes of Health (NIH) provides extensive government funding for precision medicine and genomics initiatives. Academic and biopharma research clusters in Boston and San Francisco accelerate technology adoption and innovation.
Germany
Academic research institutes and neuroscience studies fuel the demand for spatial technologies in Germany. The EU's Medical Device Regulation (MDR) sets stringent validation requirements for instruments intended for clinical use. Research clusters in Munich and Berlin actively integrate spatial omics into complex biological investigations.
China
Increasing spatial omics capabilities within government research centers and biopharmaceutical companies propel market expansion in China. The National Medical Products Administration (NMPA) oversees the approval of medical devices and diagnostics, impacting market access. Major cities like Beijing and Shanghai are developing as significant hubs for genomics research.
Japan
Pharmaceutical research teams and academic institutions contribute to the growing adoption of spatial technologies in Japan. The Pharmaceuticals and Medical Devices Agency (PMDA) regulates medical devices, influencing the path to clinical application. Tokyo and Kyoto host prominent academic and industry research institutions focused on advanced biological insights.
United Kingdom
Precision medicine initiatives and oncology research represent strong demand drivers for spatial genomics in the United Kingdom. The Medicines and Healthcare products Regulatory Agency (MHRA) provides regulatory guidance for medical devices, including diagnostic instruments. Cambridge and London maintain vibrant biotech ecosystems, fostering innovation and application of these platforms.
Spatial Genomics and Transcriptomics Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the spatial genomics and transcriptomics market. The market structure exhibits a tiered landscape, with established life science tool providers alongside specialized technology innovators. Strategic partnerships and portfolio diversification represent dominant competitive moves among market participants.
Among technology innovators, 10x Genomics leverages its strong position in single-cell analysis to offer integrated spatial solutions. NanoString Technologies competes with its digital spatial profiling systems for biomarker discovery, occupying a distinct niche. Akoya Biosciences differentiates its offerings with high-plex protein and RNA imaging platforms for tissue analysis, demonstrating specialization in advanced imaging.
| Leading Market Players |
|---|
| 10x Genomics |
| Bruker (Bruker Spatial Biology) |
| NanoString Technologies |
| Bio-Techne |
| Illumina |
| Akoya Biosciences |
| Dovetail Genomics |
| Standard BioTools |
| Vizgen |
| Others |
Cost & Logistics Intelligence
Capacity reservation agreements for high-throughput instruments, alongside long-term supply contracts for specialized reagents, lock in both supply access and price visibility for major research institutions and pharmaceutical companies.
Pricing Analysis
Geographic price-spreads for spatial genomics instruments reflect regional market maturity and installation base. Per-sample reagent pricing dominates the operational cost structure for most users, while software platforms often utilize subscription-based licensing. Price differentiation stems from the level of validation for assay kits and the volume scale of reagent procurement. Cost compression in research-use-only instruments stems from increasing competition and technological advancements. Academic research institutes often exhibit the highest price sensitivity due to grant-based funding cycles, unlike large pharmaceutical companies.
Supply Chain Analysis
The United States and Germany anchor the manufacturing of specialized spatial genomics instruments and high-purity biochemical reagents. The supply chain draws from critical dependencies on specialized optics, microfluidic chips, and DNA/RNA sequencing consumables. Single-source vulnerability for niche components or highly specialized probes presents a structural supply chain risk. Downstream distribution primarily involves direct sales channels for instruments and specialized distributors for reagents and consumables to research and clinical laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market's expansion is constrained by a persistent scarcity of scientists proficient in both computational biology and wet-lab molecular techniques, creating a critical skill gap. This dual expertise is essential for effectively leveraging complex spatial omics data.
For Market Incumbents: Secure leadership by investing heavily in integrated software solutions that simplify data analysis and interpretation. Form strategic partnerships with contract research organizations to offer service-based access, mitigating high capital costs for smaller labs. This defends against emerging entrants offering simplified platforms and addresses the bioinformatics talent scarcity by providing managed solutions. Prioritize R&D in AI and machine learning algorithms for automated data processing.
For New Entrants and Emerging Players: Anchor in niche application areas with unmet needs, such as pharmacotoxicology or highly specific multi-omic integration platforms. The most penetrable segment remains small biotechnology firms and academic core facilities seeking accessible, user-friendly spatial tools. Offer specialized, cloud-based data analysis software as a service to circumvent the high upfront instrument costs and internal bioinformatics expertise requirements for these groups.
For Investors and Strategic Acquirers: Capital is best deployed toward companies with proprietary high-plex imaging technologies or advanced, integrated bioinformatics platforms that address data analysis bottlenecks. Long-term viability over the next decade hinges on platforms offering clear pathways to clinical validation and regulatory approval. Watch for regulatory approvals of spatial companion diagnostics by agencies like the US FDA as a key inflection indicator for market maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-driven analysis software | This enhances data interpretation for complex spatial omics datasets, addressing bioinformatics talent scarcity. |
| Expand into clinical diagnostics | This unlocks significant value beyond research-use-only markets, targeting patient stratification in oncology. |
| Form CRO partnerships | This broadens technology access for institutions lacking capital and specialized in-house expertise. |
| Invest in multi-omic integration | This provides a more holistic biological understanding, commanding premium value in drug discovery. |
| Standardize data protocols | This facilitates data comparability and integration across different platforms, accelerating collaborative research. |
Research Approach
The analysis maps spatial transcriptomics sequencing, multiplexed error-robust FISH, and imaging mass cytometry as key technological sub-sectors, each validated through extensive primary interviews with R&D directors, lab managers, and bioinformatics specialists. This primary research was triangulated with secondary data from academic publications, biopharmaceutical company reports, and government funding announcements. The study employed both bottom-up and top-down approaches to ensure comprehensive market sizing and validation.
Outputs were validated against external benchmarks and industry reports to ensure consistency across the analysis window. The analytical framework modeled market segmentation across technology, product type, application (focusing on cancer research and neuroscience), end-user (academic research institutes, pharmaceutical companies), and regional adoption patterns. Compound annual growth rates were derived from historical growth trends, projected technological advancements, and anticipated regulatory changes. Key industry-specific forecast inputs included NIH funding levels and US FDA regulatory timelines for companion diagnostics.
Material uncertainties — including unforeseen regulatory changes, major technological breakthroughs, or significant shifts in public research funding — sit outside the modeled envelope. Forecasts reflect assumptions regarding current market dynamics and technological trajectories. Recalibration cycles align with material shifts in named drivers like high capital costs and data analysis bottlenecks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Global Metagenomic Sequencing Market
Genomics
Restriction Endonucleases Market
Genomics
Microbiome Sequencing Outsourcing Services Market
Genomics
Genetic Testing Service Market
Genomics
NGS Automation Market
Genomics
Sequencing Electrophoresis Systems Market
Genomics
Next Generation Genomics Market
Genomics
Next-Generation Sequencing Data Analysis Market
Genomics
Global Genotyping Assay Market
Genomics
Genomic Biomarkers Market
Genomics
Latin America Gene Expression Market
Genomics
North America Genetic Testing Market
Genomics
Global Nutrigenomics Market
Genomics
Genomics and Transcriptomics Market
Genomics
Global Nucleic Acid Labeling Market
Genomics
Global Molecular Cytogenetics Market