
 Asia-Pacific Genetic Testing Market | 2026-2036
Asia-Pacific Genetic Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Genetic Testing Market Analysis
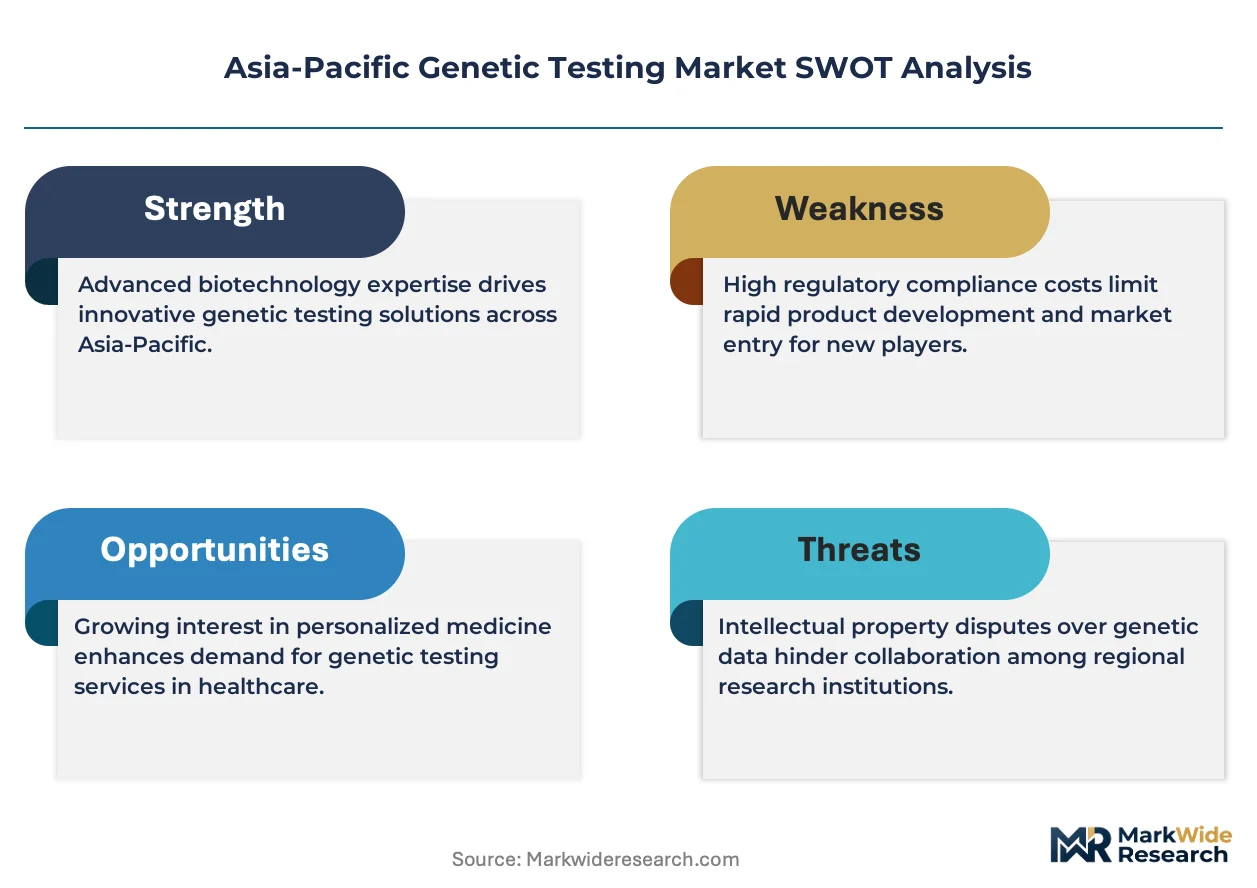
ISO 15189 accreditation for clinical laboratories is rotating the competitive landscape, filtering out smaller operators that lack quality management systems. BGI Genomics leverages its Shenzhen-based sequencing campuses to anchor production scale across East Asia. Illumina sustains technology leadership in next generation sequencing instrument platforms, while MGI Tech competes aggressively on domestic Chinese government procurement tenders.
Genetic testing encompasses molecular diagnostic procedures that analyze DNA, RNA, chromosomes, or proteins to detect heritable disease risk, pathogenic mutations, or pharmacogenomic profiles, typically requiring specimen extraction, nucleic acid amplification, and bioinformatic interpretation against reference databases. Its primary commercial purpose is enabling clinicians to stratify patient treatment pathways or confirm congenital disorder diagnoses. Carrier screening and prenatal testing command established reimbursement channels, whereas predictive testing for adult-onset conditions captures expanding out-of-pocket spend from health-conscious consumers. Next generation sequencing dominates laboratory throughput for oncology panels and rare disease exomes, while polymerase chain reaction retains cost advantages for targeted infectious disease assays in resource-constrained settings.
China's NMPA implements risk-based classification for in vitro diagnostic reagents, compelling manufacturers to submit clinical evidence for novel gene panels before hospital listing. India's CDSCO and Japan's PMDA maintain divergent approval timelines that fragment product launch synchronization across the region. Australia's TGA operates a parallel conformity assessment pathway that accelerates market entry for CE-IVD certified devices. Stakeholders must monitor how ASEAN harmonization initiatives reshape regulatory equivalence agreements and distributor qualification requirements.
Market Dynamics
China's NMPA risk-based reclassification of in vitro diagnostic reagents is compressing hospital listing timelines and forcing manufacturers to front-load clinical evidence generation before commercial rollout.
Growth Catalysts
- Oncology panel expansion:Tertiary hospitals across China are scaling molecular diagnostic programs for tumor profiling. Pathology departments in Shanghai and Suzhou industrial parks anchor sequencing infrastructure deployment.
- CDSCO medical device rule revision:India's tightened premarket scrutiny for high-risk genetic tests is professionalizing quality standards and filtering substandard imports from distributor networks.
- Carrier screening reimbursement channels:Established payment pathways for prenatal and newborn testing in Australia and Japan are stabilizing revenue predictability for clinical laboratories.
Market Restraints
- Reagent import dependency:Polymerase chain reaction master mixes and sequencing flow cells concentrate in US and European supply chains, exposing margins to currency volatility and shipping disruptions.
- PMDA-NMPA timeline divergence:Japan's pharmaceutical regulator maintains extended review cycles for novel gene panels compared to China's NMPA, fragmenting product launch synchronization across Northeast Asia.
- Bioinformatic talent scarcity:Variant interpretation pipelines require specialized computational biologists, a skill set concentrated in Bangalore, Singapore, and Sydney with limited mobility.
Strategic Opportunities
- ASEAN harmonization initiatives:Emerging regulatory equivalence frameworks across Southeast Asia promise streamlined distributor qualification for manufacturers already holding TGA or CE-IVD certification.
- Pharmacogenomic out-of-pocket spend:Health-conscious consumers in South Korea and urban China are self-funding predictive testing for adult-onset conditions outside reimbursement schemes.
- Point-of-care convergence:Isothermal amplification technologies are merging with smartphone-based readout platforms to enable decentralized infectious disease screening in Indonesia and Philippines rural clinics.
Industry Challenges
- ISO 15189 accreditation timelines:Clinical laboratories in India and Vietnam face 18-24 month quality management system implementation cycles before qualifying for tertiary hospital contracts.
- Legacy LIS integration:Hospital information system interoperability gaps between next-generation sequencing platforms and existing laboratory information systems delay report turnaround times.
- Variant database fragmentation:East Asian population-specific allele frequency references remain incomplete compared to European ancestry datasets, complicating pathogenicity classification for Chinese and Japanese patients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Genetic Testing Market |
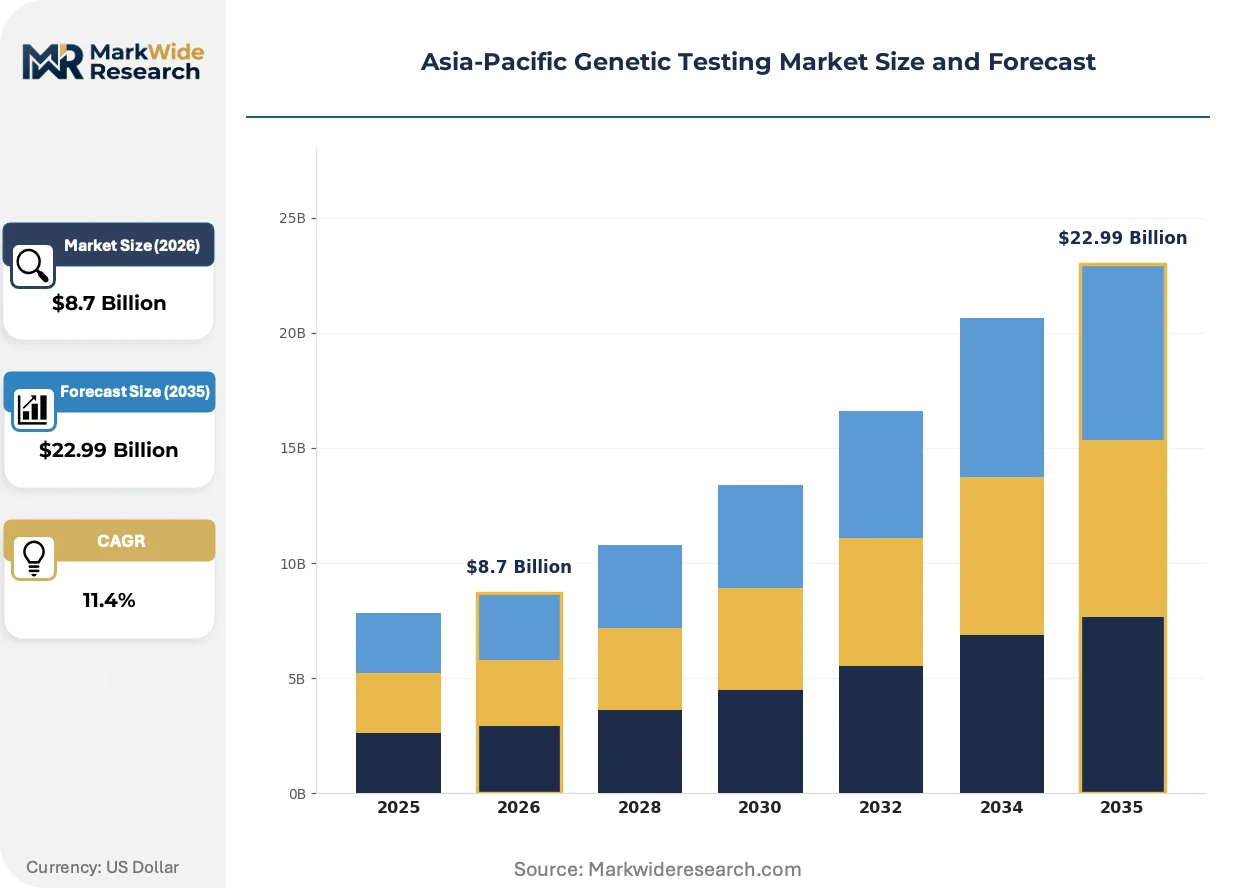
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carrier Screening, Prenatal Testing, Newborn Screening, Predictive Testing Testing Method: Next Generation Sequencing, Sanger Sequencing, Microarray Analysis, Polymerase Chain Reaction End User: Hospitals, Laboratories, Research Institutions, Home Care Settings Application: Oncology, Infectious Diseases, Cardiovascular Disorders, Rare Diseases |
| Companies Covered | BGI Genomics, Illumina, Thermo Fisher Scientific, Abbott Laboratories, Bio-Rad Laboratories, Myriad Genetics, MGI Tech, QIAGEN, Agilent Technologies, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Genetic Testing Market Emerging Trajectories
Portable nucleic acid detection platforms are compressing the distance between specimen collection and analytical interpretation, collapsing traditional hub-and-spoke laboratory logistics across archipelagic and mountainous geographies.
CRISPR-based diagnostic chemistry is miniaturizing into cartridge formats suitable for district-level clinics. Community health centers in Vietnam and Philippines are piloting these systems for tuberculosis and dengue screening. The format shift is reducing cold-chain dependencies and enabling same-day treatment initiation protocols.
China's NMPA implemented clinical evidence requirements for novel gene panels in 2021, compelling manufacturers to submit prospective validation studies before hospital listing approval. Domestic sequencing firms have responded by building captive biobanks and retrospective cohort access agreements. The regulatory friction most affects oncology companion diagnostic developers targeting simultaneous US FDA and China NMPA submissions.
Direct-to-consumer genetic testing platforms are bypassing traditional physician gatekeeping in South Korea and Australia. Subscription-based wellness reporting is displacing one-off ancestry tests as the primary customer acquisition channel. This channel rotation concentrates marketing spend on social media influencer partnerships rather than clinician education programs.
Asia-Pacific Genetic Testing Market Segmentation
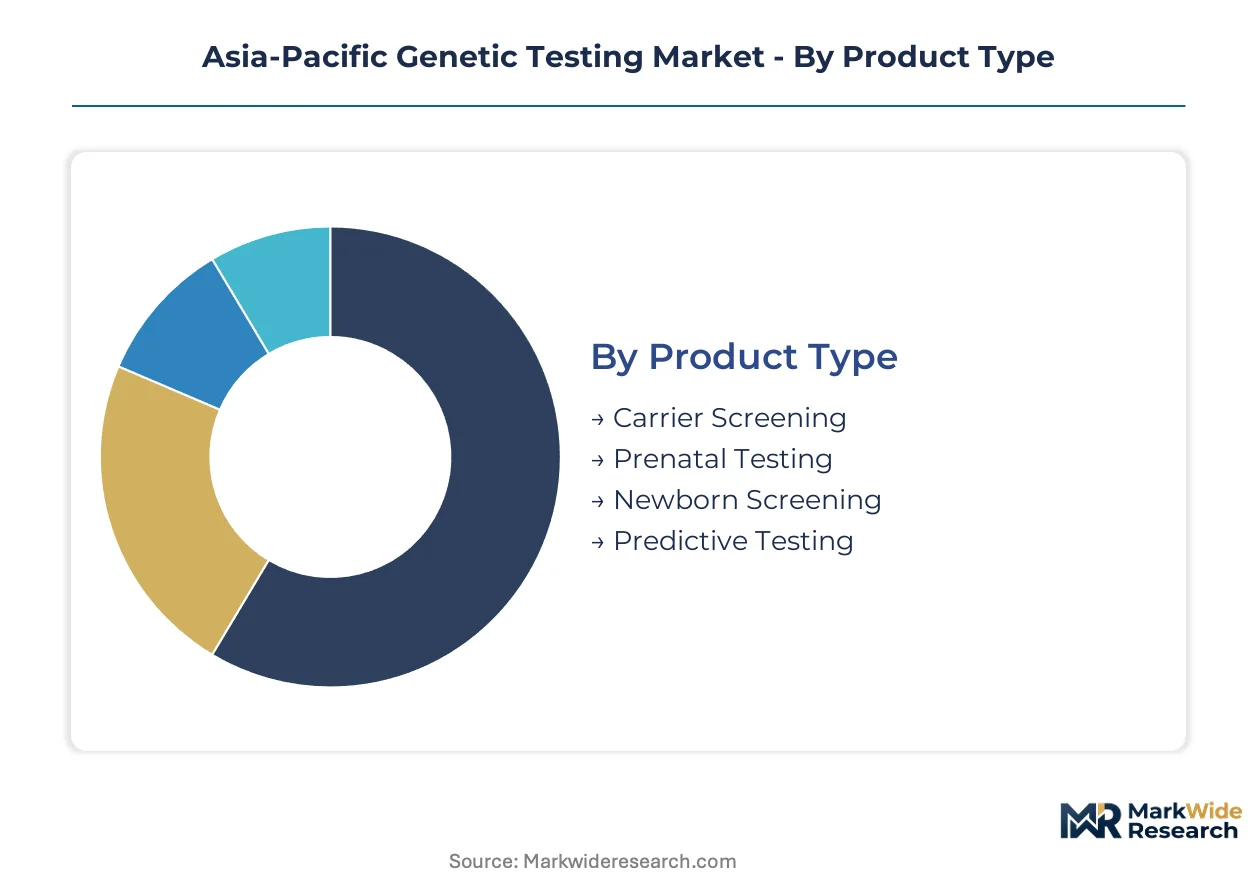
Genetic testing segments in Asia-Pacific diverge sharply by channel economics. Reimbursement pathways favor hospital-based oncology and prenatal workflows, while out-of-pocket spend concentrates in direct-to-consumer predictive and pharmacogenomic offerings.
Product Type:
Carrier screening and prenatal testing flow through obstetrics departments with established insurance coverage, whereas predictive testing channels increasingly bypass clinical gatekeepers via wellness platforms.
- Carrier Screening:Preconception and prenatal mutation detection for autosomal recessive disorders. Australia's Medicare and Japan's statutory health insurance stabilize hospital laboratory revenue, though India's fragmented private payer landscape forces cash-pay concentration in urban fertility centers.
- Predictive Testing:Adult-onset condition risk stratification for hereditary cancer and neurodegenerative syndromes. South Korean and Chinese consumers self-fund through digital health platforms, displacing traditional physician-referral volumes in Seoul and Shanghai metropolitan markets.
- Prenatal Testing:Non-invasive fetal aneuploidy screening dominates tertiary hospital obstetrics units across China's Yangtze River Delta.
- Newborn Screening:State-mandated metabolic and hearing panels anchor public health programs in Australia and Japan.
By volume, prenatal testing leads. By growth pace, predictive testing is gaining share fastest.
Testing Method:
Cost tiers separate centralized high-throughput platforms from distributed point-of-care formats, with capital intensity determining laboratory versus clinic deployment patterns.
- Next Generation Sequencing:Massively parallel readout of millions of DNA fragments enables comprehensive oncology panels and rare disease exomes. Shanghai and Suzhou industrial parks host the region's densest sequencing infrastructure, serving tertiary hospital pathology departments with 48-hour tumor profiling turnaround.
- Polymerase Chain Reaction:Targeted amplification of specific genomic loci retains cost advantages for infectious disease surveillance. Indonesian and Philippine rural clinics deploy isothermal PCR variants with smartphone readouts, circumventing cold-chain logistics for tuberculosis and dengue protocols.
- Sanger Sequencing:First-generation capillary electrophoresis remains the gold standard for single-gene confirmation in research contexts.
- Microarray Analysis:Comparative genomic hybridization platforms support copy number variation detection in developmental disorder diagnostics.
Next generation sequencing commands the highest absolute spend. Polymerase chain reaction shows the steepest expansion trajectory in point-of-care infectious disease applications.
End User:
Customer type dictates regulatory stringency and procurement scale, with tertiary hospitals representing the most concentrated revenue pool.
- Hospitals:Tertiary oncology and obstetrics departments in China, Japan, and Australia represent the largest concentrated demand for companion diagnostics and prenatal screening. NMPA and TGA accreditation requirements filter supplier qualification to ISO 15189-compliant laboratories.
- Home Care Settings:Direct-to-consumer saliva collection kits bypass clinical infrastructure in South Korea and Australia, with subscription wellness reporting displacing one-off ancestry products.
- Laboratories:Independent reference labs in Bangalore and Singapore specialize in bioinformatic interpretation for complex variant classification.
- Research Institutions:Academic medical centers in Tokyo and Sydney drive early adoption of CRISPR-based diagnostic chemistries.
Hospitals generate the dominant revenue share. Home care settings are climbing the fastest as digital distribution erodes traditional channel control.
Application:
Margin structures vary by clinical urgency and reimbursement depth, with oncology commanding premium pricing and infectious disease competing on throughput.
- Oncology:Tumor profiling and hereditary cancer risk assessment anchor molecular diagnostic program expansion across Chinese tertiary hospitals. Companion diagnostic development requires synchronized NMPA and FDA submission strategies, compressing timelines for domestic sequencing firms building captive biobanks.
- Infectious Diseases:Tuberculosis and dengue screening in Vietnam and Philippines community health centers pilot CRISPR-based cartridge formats, reducing cold-chain dependency and enabling same-day treatment initiation.
- Cardiovascular Disorders:Pharmacogenomic-guided antiplatelet and statin selection gains traction in South Korean cardiology practices.
- Rare Diseases:Exome sequencing for pediatric undiagnosed disorders concentrates in Sydney and Singapore reference laboratories.
Oncology leads by revenue concentration. Infectious disease applications are expanding most quickly in decentralized Southeast Asian deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NMPA risk-based reclassification of in vitro diagnostic reagents is compressing hospital listing timelines across the region, while India's CDSCO tightened premarket scrutiny filters substandard imports from distributor networks.
China
Oncology departments in tertiary hospitals are expanding molecular diagnostic programs for tumor profiling. NMPA clinical evidence requirements compel manufacturers to submit prospective validation studies before hospital listing approval. Sequencing infrastructure clusters around Shanghai and Suzhou industrial parks, serving pathology departments with 48-hour turnaround protocols.
India
CDSCO revised medical device rules now classify high-risk genetic tests under stricter premarket scrutiny. The regulatory shift professionalizes quality standards while filtering smaller operators lacking ISO 15189 accreditation. Bangalore hosts specialized bioinformatic interpretation hubs for complex variant classification.
Japan
PMDA maintains extended review cycles for novel gene panels compared to China's NMPA, fragmenting product launch synchronization across Northeast Asia. Statutory health insurance stabilizes revenue predictability for hospital-based prenatal and newborn screening programs. Tokyo academic medical centers drive early adoption of CRISPR-based diagnostic chemistries.
Australia
Medicare reimbursement channels anchor established payment pathways for carrier screening and prenatal testing. TGA operates a parallel conformity assessment pathway that accelerates market entry for CE-IVD certified devices. Sydney reference laboratories concentrate exome sequencing capacity for pediatric undiagnosed disorders.
South Korea
Health-conscious consumers in urban centers self-fund predictive testing for adult-onset conditions outside reimbursement schemes. MFDS regulatory frameworks support pharmacogenomic-guided antiplatelet and statin selection in cardiology practices. Seoul metropolitan markets see direct-to-consumer platforms displacing traditional physician-referral volumes.
Asia-Pacific Genetic Testing Market Vendor Landscape
Player mix skews toward integrated sequencing platform providers and specialized bioinformatic service laboratories. Market structure concentrates around instrument manufacturers with captive reagent supply chains and independent reference labs with variant interpretation expertise. Two strategic archetypes dominate: vertically integrated sequencing campus operators and distributed point-of-care diagnostic developers. Competitive moves center on biobank construction for clinical evidence generation and smartphone-based readout platform partnerships for decentralized deployment.
Among China-based sequencing specialists, BGI Genomics and MGI Tech occupy positions within the integrated platform tier, leveraging Shenzhen-based production scale for government procurement tenders. Illumina represents the multinational instrument incumbent, sustaining technology leadership in next-generation sequencing platforms across hospital pathology departments. These three anchors exemplify the competitive tension between domestic champions and global technology leaders in regional market development.
| Leading Market Players |
|---|
| BGI Genomics |
| Illumina |
| Thermo Fisher Scientific |
| Abbott Laboratories |
| Bio-Rad Laboratories |
| Myriad Genetics |
| MGI Tech |
| QIAGEN |
| Agilent Technologies |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day lead times for sequencing flow cells and polymerase chain reaction master mixes concentrate procurement leverage with US and European suppliers, compressing margins for Asia-Pacific laboratories while amplifying pricing power at the source.
Pricing Analysis
Certification level creates the primary spread across Asia-Pacific genetic testing services. ISO 15189-accredited laboratories in Shanghai and Sydney command premium positioning against non-accredited operators in Vietnam and Indonesia. Three-tier pricing structure across premium, standard, and economy levels separates tertiary hospital oncology contracts from fertility center cash-pay and rural clinic point-of-care screening. Price differentiation hinges on bioinformatic interpretation depth and turnaround commitment. Pricing pressure stems from government procurement tender compression in China, where domestic sequencing firms compete aggressively on reagent bundling. Hospital pathology departments show lowest price sensitivity given reimbursement anchoring, while direct-to-consumer wellness platforms face acute elasticity as subscription fatigue sets in.
Supply Chain Analysis
Inventory concentration for next-generation sequencing instruments and flow cells rests on California, Massachusetts, and Shenzhen manufacturing nodes, with secondary dependencies on German optical component suppliers. Raw material inputs draw from rare earth processing facilities in Inner Mongolia, fluorinated polymers from Japanese chemical specialists, and synthetic oligonucleotides from South Korean contract manufacturers. Single-source vulnerability concentrates in Illumina-patterned flow cell architectures, where patent-protected surface chemistry limits qualified second sourcing. Distribution runs through hospital GPO contracts in Australia and Japan, direct government procurement in China, and fragmented distributor networks across Southeast Asian archipelagos.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent sequencing platform providers face substitution pressure from CRISPR-based diagnostic chemistries miniaturizing into cartridge formats suitable for district-level deployment outside traditional laboratory infrastructure.
For Market Incumbents: Shield installed base positions by deepening captive biobank construction for NMPA clinical evidence requirements and securing exclusive pathology department partnerships across China's Yangtze River Delta industrial corridor. Backward integration into oligonucleotide synthesis reduces exposure to South Korean contract manufacturer concentration.
For New Entrants and Emerging Players: Lead with pharmacogenomic interpretation services targeting South Korean cardiology practices and urban Chinese wellness platforms, where reimbursement gaps create self-fund white space. Direct-to-consumer subscription models bypass hospital procurement friction entirely.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational diagnostic conglomerates seeking to divest non-core regional reference laboratory assets in Bangalore and Singapore. Long-term viability centers on bioinformatic talent density and variant database completeness for East Asian populations. Watch ASEAN regulatory harmonization progress as inflection signal for distributor qualification cost compression.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 15189 Accreditation Investment | Qualifies laboratories for tertiary hospital contracts in China, Japan, and Australia. |
| Captive Biobank Construction | Accelerates NMPA clinical evidence generation for novel oncology gene panels. |
| Smartphone Readout Platform Partnership | Enables decentralized tuberculosis and dengue screening in Philippine rural clinics. |
| Pharmacogenomic Subscription Launch | Captures out-of-pocket spend from health-conscious consumers in Seoul and Shanghai. |
| ASEAN Distributor Qualification Streamlining | Reduces market entry friction for TGA-certified device manufacturers. |
Methodological Framework
Two parallel data streams informed the analysis: structured interviews with sequencing platform manufacturers, hospital pathology directors, CDSCO regulatory consultants, and bioinformatic service laboratory executives; and secondary validation against NMPA device filings, TGA conformity assessment registers, hospital procurement databases, and GPO contract repositories. Bottom-up triangulation cross-checked instrument installation counts and reagent consumption patterns against top-down market sizing from tertiary hospital molecular diagnostic program expansion rates.
Across the analysis window, the forecasting framework modeled volume and value trajectories by product type, testing method, end user, and application, with additional segmentation by regulatory approval pathway. CAGRs derived from instrument replacement cycles, reagent per-test economics, and reimbursement channel maturation. Key inputs included NMPA hospital listing timeline compression effects and CDSCO premarket scrutiny implementation pace.
The analysis sits within stated boundaries; outcomes outside sustained government procurement tender volumes or accelerated ASEAN harmonization timelines would require recalibration. Forecasts reflect documented assumptions regarding sequencing infrastructure deployment rates and bioinformatic talent pool expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Next Generation Sequencing Market
Genomics
Latin America Gene Expression Market
Genomics
Global Pharmacogenomics Market
Genomics
US Direct-To-Consumer Genetic Testing Market
Genomics
Animal Genetics Market
Genomics
North America Genetic Testing Market
Genomics
Global NGS Sample Preparation Market
Genomics
Global Microarray Analysis Market
Genomics
Direct-To-Consumer (DTC) Genetic Testing Market
Genomics
Apolipoprotein Test Market
Genomics
Whole Genome Amplification Market
Genomics
Global Microbiome Sequencing Services Market
Genomics
DNA Gene Chip Market
Genomics
Global Long Read Sequencing Market
Genomics
Genomics and Transcriptomics Market
Genomics
Global Gene Expression Market