
 Two-Wheeler Motorcycle Market | 2026-2036
Two-Wheeler Motorcycle Market Size, Share, and Industry Trends Forecast 2026-2036
Two-Wheeler Motorcycle Market Analysis
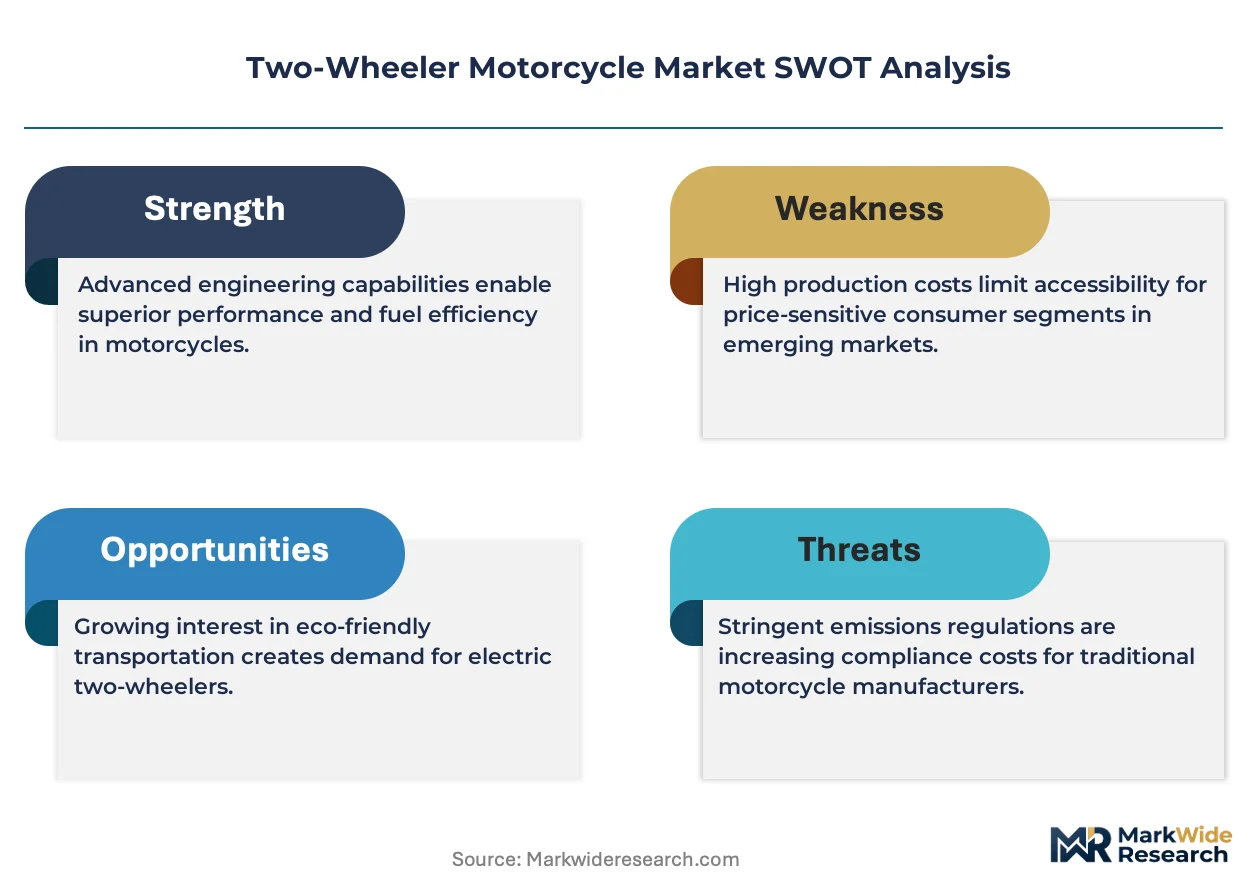
Europe's F-Gas Regulation is repositioning refrigerant and thermal management standards that indirectly affect motorcycle component sourcing. Honda Motor leverages its integrated powertrain ecosystem to sustain cost advantages across multiple displacement categories. Yamaha Motor anchors its competitive stance through motorsport-derived technology transfer. Bajaj Auto dominates value-engineered segments in price-sensitive emerging markets through manufacturing scale.
A two-wheeler motorcycle is a single-track motorized vehicle with engine capacities ranging from 50cc to over 1000cc, utilizing tubular steel or aluminum frames, chain or belt final drive, and hydraulic disc or drum braking systems, designed primarily for individual transportation, commercial delivery, and recreational mobility. Standard motorcycles occupy the highest volume tier globally due to utilitarian commuting demand, while electric powertrains represent the fastest-expanding fuel type as battery energy density improves and charging infrastructure proliferates. Sportbike configurations concentrate margin pools in developed markets where enthusiast spending on performance specifications remains durable.
The EPA enforces tailpipe emission thresholds through Tier 3 standards that constrain internal combustion engine architectures, while India's BIS mandates Bharat Stage VI compliance that elevates fuel injection and catalytic converter requirements. The EU Green Deal accelerates decarbonization timelines that OEMs must address through electrification roadmaps. Stakeholders must calibrate platform investments against divergent regulatory stringency across their priority markets.
Market Dynamics
Electrification roadmaps and Bharat Stage VI-equivalent emission mandates are compressing internal combustion engine development cycles while battery energy density improvements accelerate platform redesign investments across all displacement categories.
Growth Catalysts
- Urban first-mile mobility concentration:Southeast Asian megacities including Jakarta, Bangkok, and Ho Chi Minh City rely on two-wheelers for dense corridor transit where four-wheeled alternatives face congestion penalties.
- Battery chemistry advancement:Lithium iron phosphate and solid-state cell architectures are extending electric motorcycle range thresholds toward parity with 125cc-150cc gasoline equivalents.
- India's PLI scheme:The production-linked incentive framework for automotive manufacturing is repositioning component sourcing incentives toward domestic battery pack and power electronics assembly.
Market Restraints
- Raw material cost volatility:Lithium carbonate and neodymium price swings destabilize electric powertrain cost structures before scale economies mature.
- Charging infrastructure gaps:Grid reliability constraints in tier-2 and tier-3 Indian cities limit electric motorcycle penetration outside metropolitan charging corridors.
- Technical limitation in cold climates:Battery thermal management performance degradation below 5°C restricts electric two-wheeler viability in northern Chinese and European winter markets.
Strategic Opportunities
- Last-mile delivery electrification:E-commerce logistics fleets in Indonesia and Vietnam are converting gasoline scooter pools to swappable-battery electric configurations.
- EU Green Deal tailwind:The 2035 internal combustion engine phase-out deadline creates regulatory certainty for zero-emission motorcycle platform investments.
- Subscription ownership models:Battery-as-a-service and pay-per-use financing structures are emerging in Indian and Brazilian urban markets to reduce upfront electric acquisition barriers.
Industry Challenges
- Power electronics talent scarcity:Motor controller firmware and battery management system engineering expertise concentrates in automotive and consumer electronics sectors, creating recruitment competition.
- Homologation timeline compression:Simultaneous Bharat Stage VI, Euro 5, and EPA Tier 3 certification cycles strain validation laboratory capacity and engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Two-Wheeler Motorcycle Market |
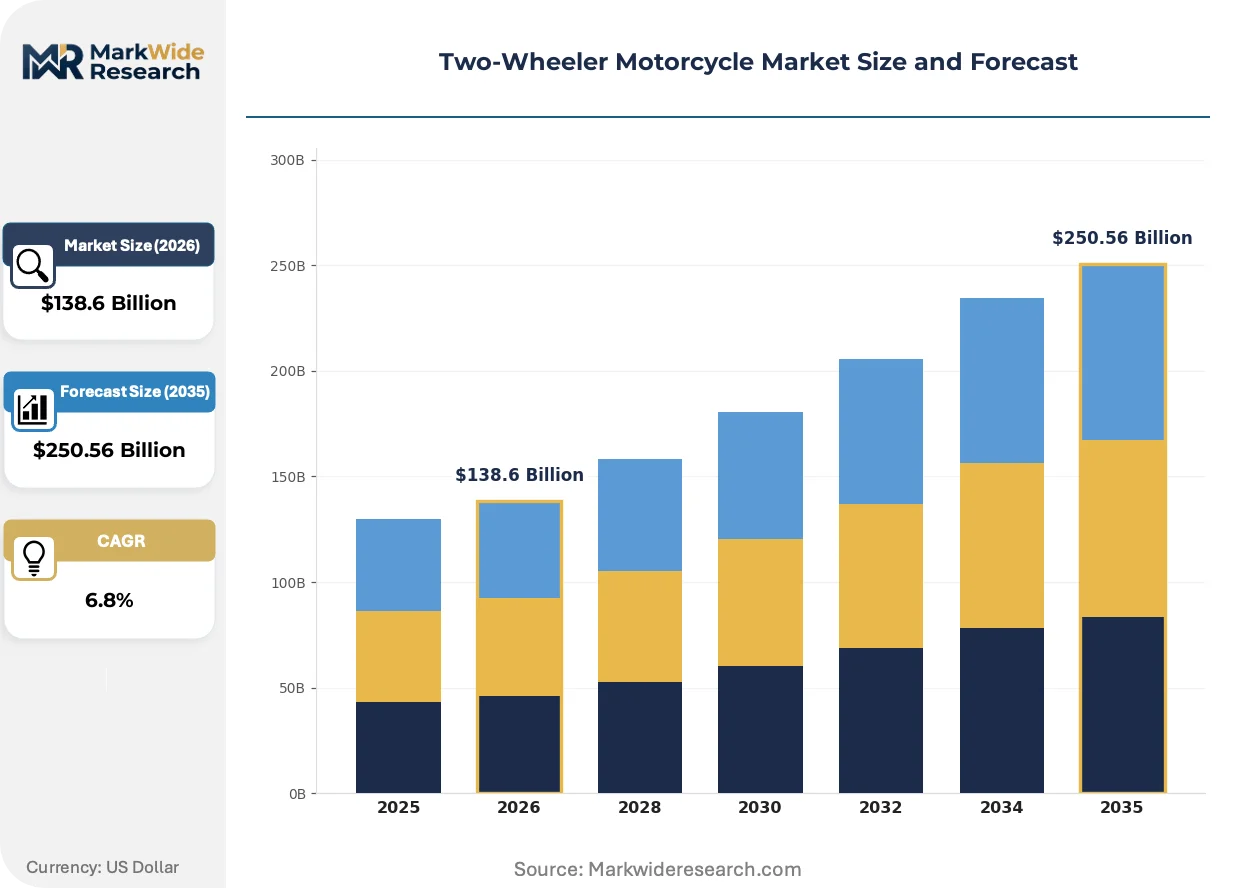
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $250.56 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Cruiser, Sportbike, Touring Consumer Segment: Beginner, Experienced, Commuter, Enthusiast Engine Capacity: 100cc-200cc, 201cc-400cc, 401cc-600cc, 601cc-1000cc Fuel Type: Petrol, Electric, Diesel, Hybrid |
| Companies Covered | TVS Motors, Haojue, Honda Motor, CFMOTO, Lifan, Yamaha Motor, Suzuki Motor, Kawasaki Heavy Industries, Bajaj Auto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Two-Wheeler Motorcycle Market Emerging Trajectories
Powertrain electrification is fragmenting traditional displacement-based segmentation while connectivity integration and subscription service unbundling redefine ownership economics across emerging and developed markets.
Silicon carbide MOSFETs in motor inverters are overtaking silicon IGBTs in mid-to-high power electric motorcycles due to switching efficiency gains and thermal density advantages. Premium and performance-oriented manufacturers in Germany, Japan, and South Korea are adopting 800V architectures faster than mass-market segments. This semiconductor transition is compressing cooling system mass and enabling faster charging protocols that reshape platform packaging constraints.
The EU F-Gas Regulation is tightening refrigerant and thermal management substance approvals that indirectly constrain motorcycle air conditioning and battery cooling system sourcing. Component suppliers must reformulate heat transfer fluids and validate alternative chemistries under accelerated timelines. Sport-touring and luxury electric segments face the steepest compliance requalification burdens as thermal management complexity increases with battery capacity.
Fleet procurement departments at delivery and ride-hailing operators are consolidating vendor relationships around total-cost-of-ownership metrics rather than sticker price. Direct manufacturer-to-fleet contracts are displacing traditional dealer network intermediation in Indonesian and Brazilian urban logistics markets. This channel compression is most visible in São Paulo and Jakarta where consolidated fleet operators command multi-thousand-unit annual volumes.
Two-Wheeler Motorcycle Market Segmentation
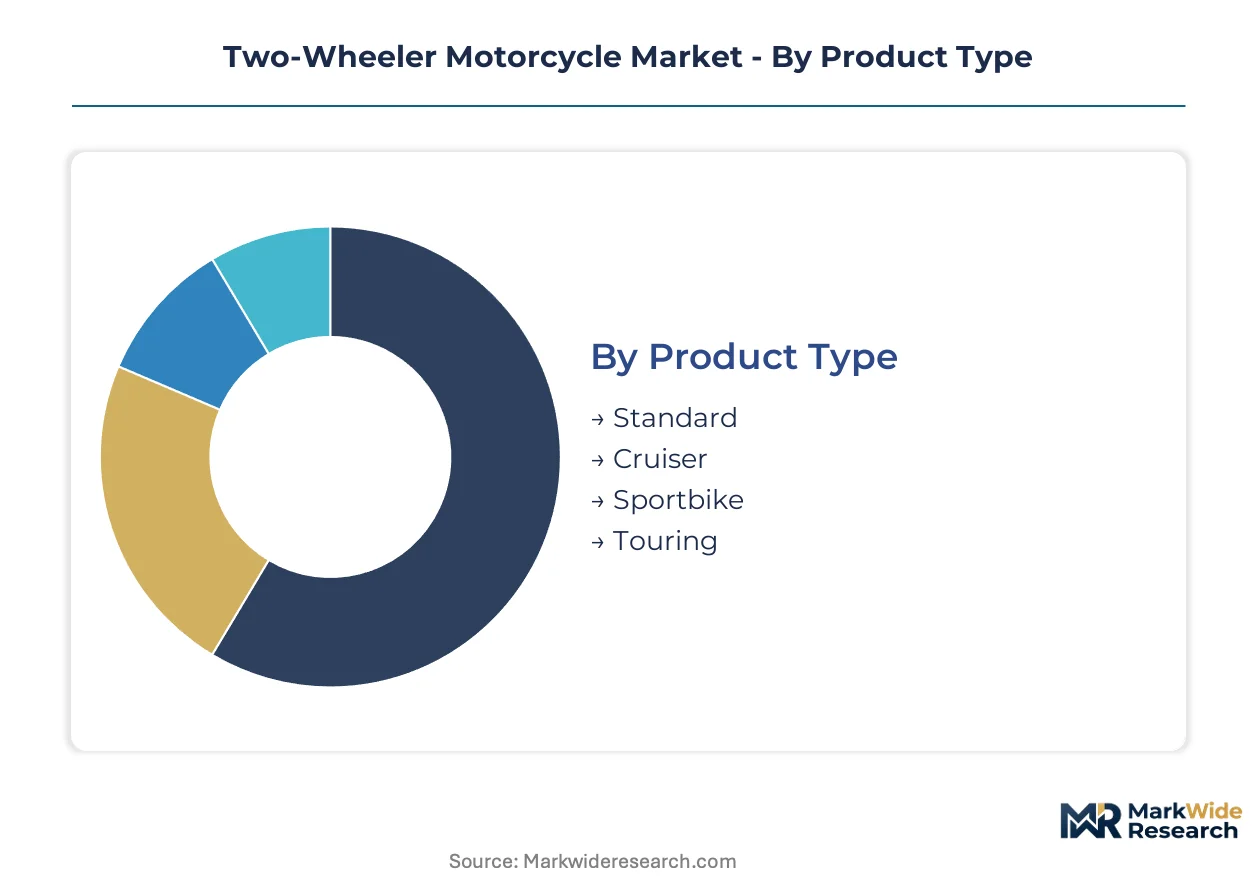
Two-wheeler motorcycle segmentation reflects divergent mobility economics across emerging and developed economies. Product configuration, rider expertise, displacement needs, and powertrain preferences each create distinct margin structures and investment priorities for manufacturers.
Product Type:
Price sensitivity and usage intensity separate buyers across these four configurations.
- Standard:Upright ergonomics, mid-range displacement, and minimal bodywork define this utilitarian format. Demand clusters in Indian and Indonesian urban corridors where fuel efficiency and low maintenance costs dominate purchase calculus.
- Sportbike:Full fairings, aggressive rider triangles, and high-revving engines characterize performance-oriented machines. Enthusiast spending in Germany, Japan, and Italy sustains premium pricing despite regulatory pressure on internal combustion powertrains.
- Cruiser:Low-slung chassis, V-twin engines, and relaxed ergonomics target recreational riders in North American markets.
- Touring:Wind protection, luggage capacity, and comfort amenities serve long-distance riders in European and Australian markets.
Volume sits with Standard; growth tilts toward Sportbike as electrification enables new performance architectures.
Consumer Segment:
Risk tolerance and replacement frequency determine service expectations and brand loyalty patterns.
- Commuter:Daily reliance on two-wheelers for income-generating activities creates extreme price elasticity and durability demands. Southeast Asian megacities including Jakarta, Bangkok, and Ho Chi Minh City concentrate this segment's global volume.
- Enthusiast:Discretionary spending on specifications, customization, and brand heritage supports margin-rich transactions. Japanese and Italian manufacturers cultivate this cohort through motorsport association and limited-edition releases.
- Beginner:Licensing restrictions and insurance costs constrain displacement choices in European and Australian markets.
- Experienced:Accumulated riding hours translate to precise feature preferences and reduced dealer dependence.
The Commuter segment anchors absolute volume; Enthusiast spending climbs fastest as electrification creates new performance categories.
Engine Capacity:
Taxation brackets, licensing tiers, and fuel cost exposure segment demand across displacement bands.
- 100cc-200cc:Single-cylinder air-cooled architectures minimize production cost and maintenance complexity. Indian and Vietnamese domestic manufacturers dominate this bracket through localized supply chains and distribution density.
- 201cc-400cc:Liquid cooling, fuel injection, and multi-valve heads enable highway capability without premium taxation. Indonesian and Brazilian middle-class expansion drives replacement demand from 125cc upgrades.
- 401cc-600cc:Parallel-twin and inline-triple configurations balance performance and insurance accessibility in European markets.
- 601cc-1000cc:Multi-cylinder premium segments face steepest electrification disruption as torque-rich electric motors challenge displacement-based performance hierarchies.
100cc-200cc commands production volume; 201cc-400cc expands most quickly as emerging economy incomes mature.
Fuel Type:
Energy infrastructure availability and total cost of ownership calculations reshape powertrain preferences.
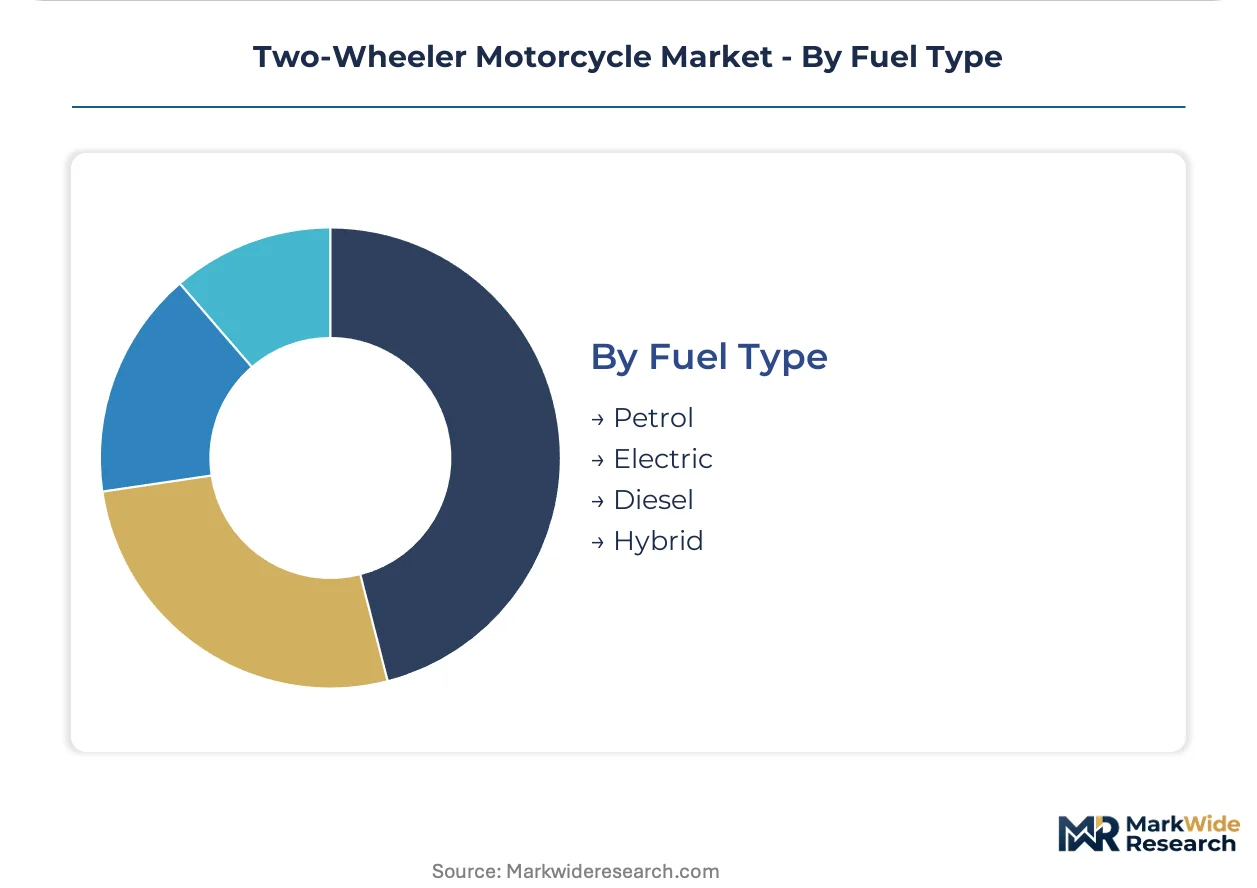
- Petrol:Established refining infrastructure and three-minute refueling sustain incumbent dominance across Southeast Asian and African markets. Bharat Stage VI and Euro 5 compliance costs erode margin at entry price points.
- Electric:Battery swapping networks in Indonesian and Vietnamese logistics fleets demonstrate commercial viability before consumer adoption. Solid-state chemistry improvements promise range parity with 150cc gasoline equivalents.
- Diesel:Torque density and fuel efficiency serve commercial three-wheeler derivatives in Indian agricultural and freight applications.
- Hybrid:Range-extender architectures address charging infrastructure gaps in Brazilian and Mexican urban markets.
Petrol retains volume leadership; Electric gains share fastest as battery-as-a-service financing reduces acquisition barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Tamil Nadu and Gujarat concentrate two-wheeler manufacturing capacity through India's PLI scheme incentives. These zones anchor component sourcing for domestic consumption and export markets across Southeast Asia and Africa.
India
Urban commuter density in Delhi-NCR and Mumbai drives replacement demand for 100cc-150cc motorcycles. BIS mandates Bharat Stage VI compliance that elevates fuel injection and catalytic converter requirements across all displacement categories. The Chennai-Bengaluru industrial corridor concentrates electric powertrain assembly investments as OEMs localize battery pack production.
Indonesia
Jakarta's megacity congestion sustains two-wheeler dominance for first-mile mobility across 30 million daily trips. The national government's battery swapping infrastructure program targets logistics fleet electrification in Greater Jakarta. Bekasi and Karawang manufacturing clusters host Japanese OEM joint ventures serving ASEAN export markets.
Vietnam
Ho Chi Minh City and Hanoi account for 60 percent of national two-wheeler registrations amid rapid urbanization. The Ministry of Transport's electric vehicle roadmap mandates 100 percent electric motorcycle sales by 2040. VinFast's Haiphong facility exemplifies vertical manufacturing integration from cells to finished vehicles.
Thailand
Bangkok's metropolitan expansion sustains premium 150cc-300cc displacement growth among middle-income households. Board of Investment tax incentives attract EV powertrain investments to the Eastern Economic Corridor. Rayong province hosts concentrated Japanese OEM capacity serving domestic and export demand.
Brazil
São Paulo's ride-hailing and delivery fleet operators consolidate procurement around total-cost-of-ownership metrics. ANVISA and environmental agency regulations shape emission compliance timelines for flex-fuel and electric platforms. Manaus Free Trade Zone incentives sustain assembly operations for northern and northeastern regional distribution.
Two-Wheeler Motorcycle Market Vendor Landscape
Japanese producers anchor the premium-engineering tier; Indian and Chinese specialists hold volume-driven positions in price-sensitive emerging markets. The vendor base organizes around three strategic archetypes: integrated powertrain ecosystem operators, value-engineered mass-market manufacturers, and motorsport-heritage performance brands. Capacity expansion and battery platform partnerships constitute the dominant competitive moves as electrification roadmaps compress development cycles.
Among integrated Japanese manufacturers, Honda Motor and Yamaha Motor exemplify ecosystem control across multiple displacement categories. Bajaj Auto occupies a position within the value-engineered archetype, leveraging manufacturing scale for emerging market penetration. These three anchors represent divergent strategic postures—ecosystem breadth, motorsport-derived technology transfer, and cost-optimized production density—each calibrated to distinct regional demand profiles and regulatory stringency levels.
| Leading Market Players |
|---|
| TVS Motors |
| Haojue |
| Honda Motor |
| CFMOTO |
| Lifan |
| Yamaha Motor |
| Suzuki Motor |
| Kawasaki Heavy Industries |
| Bajaj Auto |
| Others |
Supply Flow & Price Mechanics
Silicon carbide MOSFET adoption in motor inverters simultaneously compresses cooling system costs and concentrates semiconductor sourcing among Japanese and South Korean foundries, reshaping tier-1 supplier pricing power across displacement categories.
Pricing Analysis
Short lead-time premiums for power electronics and battery management systems separate contract manufacturers from spot-market purchasers in tier-2 Indian and Indonesian cities. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under Bharat Stage VI and Euro 5 compliance tiers. Cost compression in entry-level petrol segments intensifies because fuel injection and catalytic converter mandates erode margin pools at sub-$1,500 price points. Fleet procurement departments in São Paulo and Jakarta exhibit lowest price sensitivity due to total-cost-of-ownership consolidation, while individual commuters in Vietnamese tier-3 cities demonstrate highest elasticity.
Supply Chain Analysis
Reverse-logistics flows for battery pack refurbishment and motor controller remanufacturing are emerging in Indonesian and Vietnamese swapping networks, creating secondary component channels that compete with OEM spare parts pricing. Manufacturing concentration rests on China for lithium-ion cells, India for stamped steel frames and casting components, and Japan for precision powertrain machining. Lithium carbonate, neodymium permanent magnets, and silicon carbide wafers anchor raw material dependencies. Single-source vulnerability concentrates in Chinese cathode active material supply. Distribution runs through consolidated fleet operators in São Paulo and Jakarta alongside traditional dealer networks in Indian tier-2 cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where battery cell production and power electronics assembly constitute the decisive upstream levers separating margin leaders from assemblers.
For Market Incumbents: Anchor ecosystem control through captive battery pack assembly in Tamil Nadu special economic zones and in-house motor controller firmware development. Electrification roadmaps compress development cycles, threatening engineering bandwidth advantages. Certification investment in simultaneous Bharat Stage VI, Euro 5, and EPA Tier 3 homologation creates defensive moats against emerging Chinese entrants. For New Entrants and Emerging Players: Direct-to-fleet digital sales channels in Indonesian and Brazilian urban logistics markets bypass entrenched dealer networks with lowest penetration costs. Last-mile delivery electrification in Jakarta and Ho Chi Minh City represents the most penetrable white-space, where gasoline scooter replacement demand concentrates in consolidated procurement departments. Battery-as-a-service financing partnerships with ride-hailing platforms reduce customer acquisition friction versus traditional retail distribution. For Investors and Strategic Acquirers: Exit pathways concentrate in platform standardization plays and battery supply agreements with ASEAN logistics fleets. Long-term viability hinges on power electronics engineering talent density and charging infrastructure deployment velocity. Acquisition targets should demonstrate backward integration into cell assembly or swapping network operations. Solid-state chemistry breakthrough announcements from Japanese and South Korean materials suppliers signal the critical inflection indicator for electric range parity.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term cell offtake contracts with Chinese and South Korean suppliers secure cost visibility for Indian OEM electrification roadmaps. |
| Platform Standardization | Shared 800V architectures across multiple displacement categories amortize R&D investment for Japanese integrated manufacturers. |
| Backward Integration | In-house lithium iron phosphate cell production in Gujarat special economic zones captures PLI scheme incentives for domestic assembly. |
| Swapping Network Partnership | Indonesian government infrastructure programs create regulatory certainty for logistics fleet electrification in Greater Jakarta. |
| Power Electronics Acquisition | Motor controller firmware specialists in automotive and consumer electronics sectors address talent scarcity constraining platform development. |
Methodological Framework
Multi-period observation of battery energy density improvements, charging infrastructure deployment, and fleet electrification conversion rates anchored the trend analysis, supplemented by interviews with OEM platform engineers, Tier 1 supplier procurement leads, battery swapping network operators, and logistics fleet procurement managers. Secondary validation drew from vehicle production databases, IHS Markit registration data, BIS and EPA regulatory filings, and ASEAN trade statistics. Bottom-up segment sizing triangulated against top-down macroeconomic demand projections.
Input-output matrices mapped powertrain cost structures across displacement categories and fuel types, with segmentation dimensions spanning product configuration, consumer risk tolerance, engine capacity bands, and propulsion architecture. CAGRs were derived from regression analysis of historical adoption curves applied to regulatory phase-out timelines and infrastructure investment trajectories. Forecast inputs incorporated battery chemistry advancement curves and thermal management performance degradation factors in cold-climate markets.
The model holds under stable lithium carbonate pricing and continued PLI scheme disbursement; deviation in raw material cost volatility or grid reliability constraints would shift electric penetration trajectories. Forecasts reflect documented assumptions regarding swapping network deployment velocity and solid-state chemistry commercialization timelines. Practitioners should monitor neodymium price movements and Japanese materials supplier R&D disclosures for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Cruiser Bikes Market
Bikes and Motorcycles
Vietnam Bike-Sharing Market
Bikes and Motorcycles
Europe Motorcycle Airbag Market
Bikes and Motorcycles
Two-Wheeler Services Market
Bikes and Motorcycles
Netherlands E-Bike Market
Bikes and Motorcycles
Bicycle Crank Motor Market
Bikes and Motorcycles
Brazil E-Bike Market
Bikes and Motorcycles
Asia-Pacific Two-Wheeler Taxi Market
Bikes and Motorcycles
Bicycle Mechanical Disc Brake Market
Bikes and Motorcycles
Motorsports Motorcycle Market
Bikes and Motorcycles
Motorsport Components Market
Bikes and Motorcycles
Asia-Pacific Motorcycle Market
Bikes and Motorcycles
Cargo Bicycles Market
Bikes and Motorcycles
Fixed Gear Bikes Market
Bikes and Motorcycles
Bicycle Brake Lever Market
Bikes and Motorcycles
Motorcycle Transmission Control Unit Market