
 Electric Two-Wheeler Market | 2026-2036
Electric Two-Wheeler Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Two-Wheeler Market Analysis
Chinese battery pack producers is broadening export capacity for Southeast Asian assembly plants. Yadea Group Holdings leverages its integrated motor and controller manufacturing to dominate price-sensitive scooter segments across Indonesia and the Philippines. Gogoro Limited anchors its position through proprietary battery swap infrastructure that locks in urban fleet operators across Taipei and Singapore. Hero Electric Vehicles sustains rural distribution depth that national competitors struggle to replicate in India's tier-three towns.
Electric two-wheelers encompass battery-powered motorized vehicles with two inline wheels, typically incorporating hub-mounted or mid-drive motors rated between 250 watts and 11 kilowatts, with lithium-ion battery packs enabling ranges from 40 to 150 kilometers per charge. These vehicles serve urban mobility and commercial logistics applications where operating cost reduction and emissions compliance replace fossil-fuel alternatives. The battery type dimension shows lithium-ion chemistry capturing margin pools from lead acid as energy density requirements tighten, while solid-state prototypes attract premium motorcycle development budgets. Electric scooters occupy the highest volume tier across Asian megacities, whereas electric motorcycles command premium positioning among adventure enthusiasts seeking torque performance parity with internal combustion engines.
The EPA tailpipe standards and NHTSA safety classifications in the United States shape product homologation requirements for imported electric motorcycles, while India's BIS certification and PLI scheme localize battery supply chains through domestic cell manufacturing mandates. The EU Green Deal's transport decarbonization targets coupled with REACH substance restrictions on battery materials force European importers to redesign pack compositions and trace mineral sourcing. Stakeholders must monitor how swap-versus-charge infrastructure bets by national regulators determine which business models achieve network-effect lock-in across dense urban markets.
Market Dynamics
Battery chemistry migration from lead-acid to lithium-ion is compressing total cost of ownership curves while forcing supply chain reconfiguration across cell manufacturing and thermal management systems.
Growth Catalysts
- FAME II subsidy scheme:India's production-linked incentive structure reduces upfront vehicle acquisition costs for commercial fleet operators, accelerating replacement cycles for last-mile delivery vehicles in tier-two and tier-three urban centers.
- Swap infrastructure mandates:Singapore's Land Transport Authority licensing framework for battery exchange stations creates regulated network density requirements that lock in operational advantages for early-mover fleet service providers.
- Lithium iron phosphate chemistries:Improved thermal stability and cycle life characteristics enable higher utilization rates in tropical climates where ambient temperatures degrade conventional lithium-ion performance.
Market Restraints
- Cobalt and nickel price volatility:Cathode material cost swings compress margin structures for mid-range scooter producers who lack long-term offtake agreements with integrated mining operators.
- Charging infrastructure gap:Residential building electrical capacity constraints in dense Vietnamese and Indonesian urban housing stock limit overnight charging penetration among individual owner-operators.
- Homologation timeline friction:India's BIS certification requirements for battery pack safety testing extend product launch cycles by four to six months versus unregulated import pathways.
Strategic Opportunities
- Philippine archipelago logistics:Island-hopping commercial delivery routes favor modular battery systems that eliminate range anxiety across disconnected charging networks.
- EU Green Deal border adjustments:Carbon intensity documentation requirements for imported two-wheelers create competitive openings for producers with verified renewable-powered cell manufacturing.
- Telematics-embedded financing:Usage-based asset financing models leverage real-time vehicle performance data to underwrite credit for thin-file borrowers in Indonesia's informal economy.
Industry Challenges
- Battery thermal management expertise:Shortage of engineers with cell-level electrochemistry and pack integration experience delays product development cycles for regional assembly operations.
- Swap-charge standardization deadlock:Competing proprietary connector protocols across Gogoro, Yadea, and emerging entrants fragment infrastructure investment and strand capital in non-interoperable assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Two-Wheeler Market |
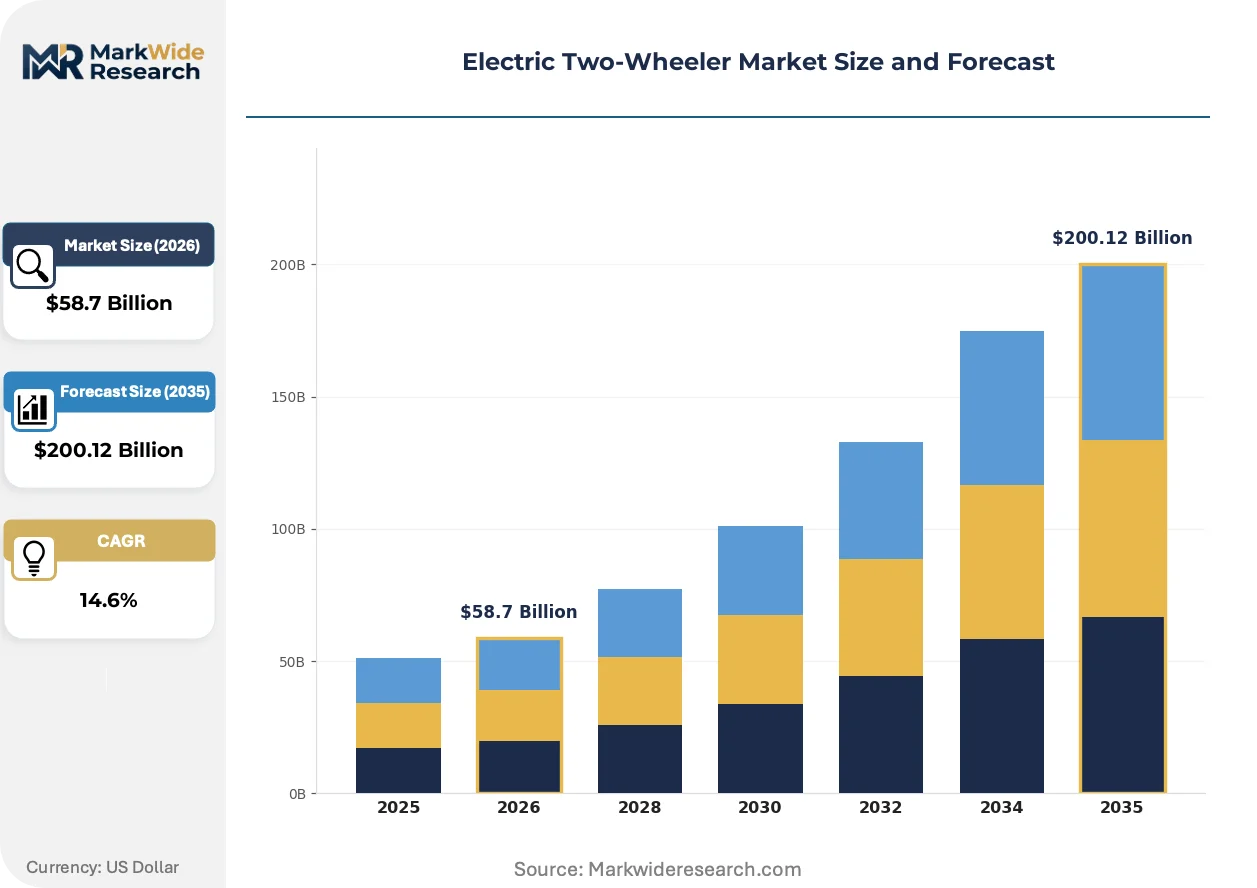
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $200.12 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Scooters, Electric Motorcycles, E-bikes, Mopeds Battery Type: Lithium-ion, Lead Acid, Nickel-Metal Hydride, Solid State End User: Commuters, Delivery Services, Rental Services, Adventure Enthusiasts Distribution Channel: Online Retail, Dealerships, Direct Sales, Service Centers |
| Companies Covered | Yamaha Motor Company, Yadea Group Holdings, Gogoro Limited, Niu Technologies, Hero Electric Vehicles, Jiangsu Xinri E-Vehicle, Ola Electric Mobility, Bajaj Auto, Ather Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Two-Wheeler Market Emerging Trajectories
Power electronics miniaturization and silicon carbide inverter adoption are reshaping motor efficiency benchmarks while enabling platform architectures that span multiple vehicle classes without fundamental redesign.
Silicon carbide MOSFETs in motor controllers handle higher switching frequencies with reduced thermal losses than conventional IGBT architectures. Tier-one suppliers in Taiwan and South Korea are qualifying these components for 11-kilowatt peak power outputs in premium motorcycle segments. This semiconductor transition is decentralizing thermal management system design by enabling air-cooled solutions that previously required liquid cooling loops and their associated plumbing complexity.
REACH substance restrictions on nickel, cobalt, and manganese compounds in battery materials force European importers to redesign cathode compositions and establish traceable mineral sourcing documentation. The EU Battery Regulation's carbon footprint declaration requirements extend compliance obligations upstream to cell manufacturing energy inputs. Premium motorcycle exporters to Germany and France are responding by securing power purchase agreements with renewable generators to document supply chain decarbonization.
Fleet operators in Bangkok and Jakarta are unbundling vehicle acquisition from energy service contracts, shifting from capital expenditure ownership to per-kilometer operational leasing structures. This preference compression eliminates traditional dealer margin capture and redirects commercial relationships toward direct manufacturer-fleet procurement channels. The shift is most visible in food delivery and grocery logistics verticals where utilization rates exceed 200 kilometers daily and downtime sensitivity maximizes swap infrastructure dependency.
Electric Two-Wheeler Market Segmentation
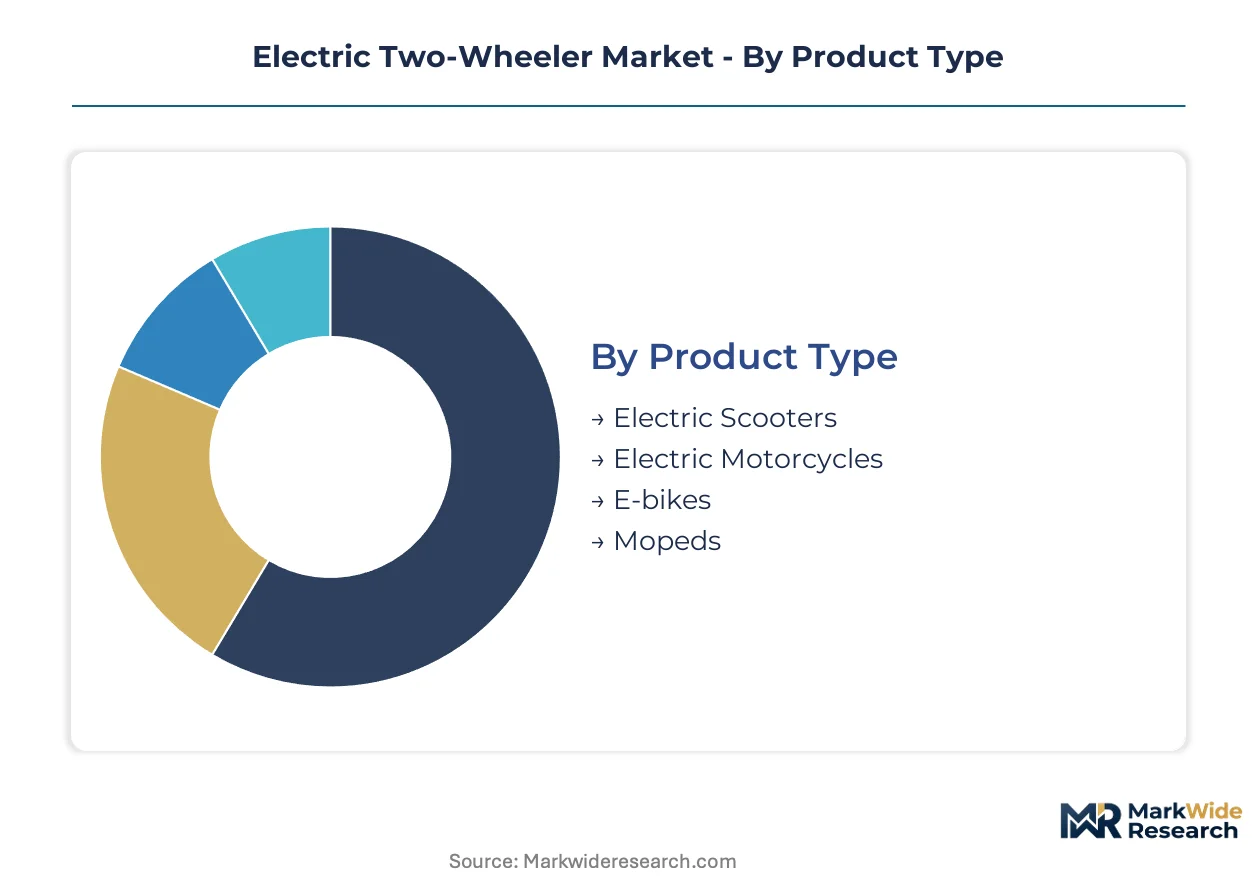
Segmentation in electric two-wheelers separates volume-driven urban mobility from premium performance categories. Battery chemistry and distribution channel choices determine margin capture and geographic expansion feasibility for manufacturers.
Product Type:
Volume concentrates in entry-level scooters while premium motorcycles command higher per-unit economics.
- Electric Scooters:Hub-mounted motors rated 250W–4kW power lightweight chassis designs optimized for dense Asian megacity traffic. Demand clusters in Vietnam's urban corridors and Indonesia's tier-two cities where air quality mandates accelerate fleet replacement cycles.
- Electric Motorcycles:Mid-drive configurations delivering 5kW–11kW peak outputs target torque parity with 150cc internal combustion engines. Adventure enthusiasts in Thailand and premium commuters in Singapore drive adoption where swap infrastructure eliminates range constraints.
- E-bikes:Pedal-assist systems with 250W–750W motors serve last-mile connectivity in European regulatory environments.
- Mopeds:Step-through frames with sub-2kW motors dominate Philippine commercial delivery fleets.
Today's leader: Electric Scooters. Tomorrow's challenger: Electric Motorcycles.
Battery Type:
Chemistry selection tracks climate exposure and utilization intensity across fleet versus consumer applications.
- Lithium-ion:NMC and LFP cathode formulations enable 40–150 kilometer ranges with 1,000+ cycle lifespans. Tropical fleet operators in Bangkok and Jakarta favor LFP variants for thermal stability in ambient temperatures exceeding 35°C.
- Lead Acid:Legacy chemistry persists in India's price-sensitive rural markets where upfront cost sensitivity outweighs total cost of ownership calculations.
- Nickel-Metal Hydride:Niche applications in hybrid two-wheeler prototypes with limited commercial deployment.
- Solid State:Prototype cells with ceramic electrolytes target premium motorcycle segments requiring 300+ kilometer ranges.
Current installed base: Lead Acid. Steepest expansion trajectory: Lithium-ion.
End User:
Commercial utilization rates exceed consumer ownership by 3–5x, reshaping product durability specifications.
- Commuters:Daily 20–40 kilometer trip distances prioritize charging convenience and theft-resistant battery locking mechanisms in Vietnamese and Indonesian residential contexts.
- Delivery Services:Food and grocery logistics operators in Singapore and Taipei achieve 200+ kilometer daily utilization through battery swap subscriptions that eliminate downtime.
- Rental Services:Micro-mobility platforms in Manila and Ho Chi Minh City demand ruggedized chassis with telematics integration for asset tracking.
- Adventure Enthusiasts:Torque-focused riders in Thailand's touring corridors seek DC fast-charging compatibility for intercity routes.
Revenue concentration: Delivery Services. Emerging volume: Commuters.
Distribution Channel:
Fleet procurement bypasses traditional retail margin structures through direct manufacturer relationships.
- Online Retail:Configurator-driven sales with home delivery expand penetration in India's tier-three towns where physical dealership presence remains thin.
- Dealerships:Service-integrated networks in Indonesia and the Philippines provide maintenance capacity for lead-acid battery replacement and brake servicing.
- Direct Sales:Manufacturer-fleet contracts dominate Singapore's commercial leasing market with per-kilometer operational structures.
- Service Centers:Swap station operators in Taipei double as maintenance hubs for Gogoro's subscription-based ecosystem.
Dominant channel: Dealerships. Fastest-growing: Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's subsidy architecture accelerates fleet electrification faster than Vietnam's regulatory mandates, yet both markets reveal how policy design shapes adoption velocity across motorcycle-dependent economies.
India
Commercial fleet operators in tier-two and tier-three urban centers drive replacement cycles for last-mile delivery vehicles. The FAME II subsidy scheme reduces upfront acquisition costs through production-linked incentive structures. Maharashtra and Gujarat host battery assembly operations where domestic cell manufacturing mandates localize supply chains.
Vietnam
Motorcycle-dependent cities face escalating air quality mandates that accelerate moped electrification in Ho Chi Minh City and Hanoi corridors. The country's national transport regulator imposes emissions compliance deadlines that compress fleet replacement timelines. Northern industrial zones concentrate motor and controller manufacturing for regional export.
Indonesia
Island-hopping commercial delivery routes favor modular battery systems that eliminate range anxiety across disconnected charging networks. The central government's electric vehicle roadmap sets domestic production targets that attract Chinese battery pack investment. Jababeka and MM2100 industrial estates outside Jakarta host Southeast Asian assembly plants.
Singapore
Urban fleet operators achieve 200+ kilometer daily utilization through battery swap subscriptions that eliminate downtime sensitivity. The Land Transport Authority licensing framework for battery exchange stations creates regulated network density requirements. Commercial leasing structures dominate direct manufacturer-fleet procurement channels.
Thailand
Adventure enthusiasts in touring corridors seek DC fast-charging compatibility for intercity routes where torque parity with internal combustion engines matters. The national industrial policy board coordinates with METI-aligned standards for regional harmonization. Eastern Economic Corridor provinces concentrate premium motorcycle development and power electronics manufacturing.
Electric Two-Wheeler Market Vendor Landscape
Chinese producers anchor one tier; Taiwan and India specialists hold differentiated positions through infrastructure and distribution depth. The vendor base spans integrated motor manufacturers, battery swap operators, and rural distribution networks. Three archetypes dominate: scale-driven exporters, swap-infrastructure lock-in players, and tier-three distribution specialists. Capacity expansion and direct fleet procurement partnerships represent the dominant competitive moves.
Within the swap-infrastructure tier, Gogoro Limited exemplifies network-effect positioning through proprietary battery exchange ecosystems. Among Chinese scale producers, Yadea Group Holdings occupies a position representing integrated manufacturing advantages across price-sensitive segments. Hero Electric Vehicles anchors the rural distribution archetype in India's tier-three towns where national competitors struggle to replicate service depth.
| Leading Market Players |
|---|
| Yamaha Motor Company |
| Yadea Group Holdings |
| Gogoro Limited |
| Niu Technologies |
| Hero Electric Vehicles |
| Jiangsu Xinri E-Vehicle |
| Ola Electric Mobility |
| Bajaj Auto |
| Ather Energy |
| Others |
Supply Flow & Price Mechanics
EU Green Deal carbon footprint declarations gate both qualified supply and premium-tier pricing access for electric two-wheeler exporters, forcing manufacturers to document renewable energy inputs or forfeit positioning in Germany and France. This regulatory filter compresses margin structures for producers lacking verified power purchase agreements while rewarding integrated cell manufacturers with pricing power in high-compliance markets.
Pricing Analysis
Capacity additions in China's Jiangsu and Guangdong provinces are reshaping price floors for lithium-ion battery packs across Southeast Asian assembly operations. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling, with BIS-certified packs commanding premiums in India. Cost compression in economy-tier scooters is intensifying because lead-acid replacement cycles compress as LFP chemistries achieve cost parity. Commercial fleet operators in Singapore and Taipei exhibit lowest price sensitivity due to swap-subscription dependency, while individual owner-operators in Vietnamese residential corridors face highest upfront cost barriers.
Supply Chain Analysis
Freight cost volatility between Chinese cell manufacturing hubs and Indonesian assembly plants is forcing inventory positioning shifts across the ASEAN trade corridor. Supply concentrates in China for cathode materials, Taiwan for power electronics, and South Korea for silicon carbide components. The network draws from lithium carbonate sourced through Australian and Chilean offtake agreements, nickel laterite from Indonesian processing facilities, and refined cobalt via DRC-Zambia logistics routes. Single-source vulnerability in Gogoro-proprietary battery swap connectors strands infrastructure capital in non-interoperable assets. Distribution runs through direct manufacturer-fleet contracts in Singapore's commercial leasing market and dealership-integrated service networks in India's tier-three towns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric two-wheeler markets present margin-expansion potential as silicon carbide inverter adoption drives motor efficiency gains and swap-infrastructure lock-in secures recurring revenue streams. LFP chemistry cost-down curves and fleet utilization premiums justify premium-tier positioning for integrated producers.
For Market Incumbents: To counter swap-charge standardization deadlock, Yadea and Gogoro should deepen backward integration into cell manufacturing to secure thermal management expertise and accelerate BIS certification timelines for Indian market access. Prioritize proprietary connector protocol alliances that prevent infrastructure asset stranding. For New Entrants and Emerging Players: Begin with Philippine archipelago logistics white-space where modular battery systems eliminate range anxiety across disconnected island networks. Target Indonesia's informal economy telematics-embedded financing segment where usage-based asset models underwrite thin-file borrowers. Pursue direct manufacturer-fleet procurement channels to bypass traditional dealer margin capture. For Investors and Strategic Acquirers: Roll-up economics work for rural distribution specialists because Hero Electric's tier-three service depth demonstrates replicable asset-light expansion models across India's secondary cities. Five-to-ten-year viability hinges on swap infrastructure network-effect lock-in achieving critical density. Monitor Land Transport Authority licensing framework decisions as inflection indicator for regulated network density requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Swap Infrastructure Partnership | Gogoro's Taipei licensing framework creates regulated network density moats for fleet operators. |
| LFP Chemistry Transition | Thermal stability in Bangkok's 35°C ambient enables higher utilization rates for commercial fleets. |
| Silicon Carbide Inverter Adoption | Taiwan and South Korean suppliers qualify components for 11kW premium motorcycle segments. |
| Direct Fleet Procurement Channel | Singapore's per-kilometer leasing structures eliminate dealer margin capture for manufacturers. |
| BIS Certification Investment | India's battery pack safety testing mandates extend launch cycles without domestic compliance. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM platform engineers, Tier 1 supplier procurement leads, commercial fleet operators in Bangkok and Jakarta, battery swap station operators, and Land Transport Authority regulatory planners. Secondary validation drew from SEC filings of listed manufacturers, BIS certification registries, EU Battery Regulation carbon footprint documentation, and vehicle production databases. Bottom-up cell manufacturing capacity estimates triangulated against top-down fleet replacement projections across the analysis window.
Segment-weighting approaches modeled product type differentiation between hub-mounted scooter configurations and mid-drive motorcycle architectures, battery chemistry migration from lead-acid to LFP and solid-state prototypes, and distribution channel shifts from dealership networks to direct sales. CAGRs derived from utilization intensity differentials between commercial fleet and consumer ownership patterns, with inputs including FAME II subsidy phase-out trajectories and REACH substance restriction compliance timelines.
Caveats apply where cobalt and nickel price volatility, swap-charge standardization deadlock, or residential electrical capacity constraints in Vietnamese urban housing could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Global Solar Powered Car Market
Electric Vehicles
Folding E-Scooter Market
Electric Vehicles
Asia Pacific Electric Three-Wheelers Market
Electric Vehicles
Global Electric Vehicles Market
Electric Vehicles
Spain Solar E-Bike Market
Electric Vehicles
Australia Electric Vehicle Market
Electric Vehicles
Canada Solar E-Bike Market
Electric Vehicles
Oman EV Market
Electric Vehicles
North America Automotive Battery Thermal Management System Market
Electric Vehicles
Global Electric All Wheel Drive (AWD) Market
Electric Vehicles
E-Bike Accessories Market
Electric Vehicles
Belgium Solar E-Bike Market
Electric Vehicles
Electric Vehicle (EV) Ball Bearings Market
Electric Vehicles
Electric Vehicle Battery Cases Market
Electric Vehicles
Italy Hybrid Electric Vehicle Battery Market
Electric Vehicles
Solar Golf Cart Market