
 Asia-Pacific Motorcycle Market | 2026-2036
Asia-Pacific Motorcycle Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Motorcycle Market Analytics
Commercial delivery fleets are reorganizing procurement priorities across Southeast Asia, shifting volume toward fuel-efficient two-wheelers with lower total cost of ownership. Honda Motor anchors regional production through extensive Thai and Indonesian manufacturing bases. Hero MotoCorp dominates the sub-150cc commuter segment through deep distribution in India's tier-two cities. Yamaha Motor extends its competitive position via advanced liquid-cooled engine platforms for premium urban buyers.
A motorcycle is a two-wheeled motorized vehicle powered by an internal combustion or electric powertrain, typically featuring a tubular steel or aluminum frame, telescopic front forks, and chain or belt final drive, engineered primarily for individual or dual-rider transportation across varied road conditions. Scooter configurations lead volume across Asian megacities due to step-through convenience and under-seat storage utility, while sport bikes capture margin concentration among enthusiast segments in Australia and Japan. The 126cc to 250cc engine capacity band sustains the broadest addressable demand, bridging commuting utility with occasional highway capability across Indonesia, Vietnam, and the Philippines.
India's BIS emission standards, Thailand's Industrial Standards Institute certification requirements, and Vietnam's QCVN technical regulations collectively elevate compliance costs for imported powertrain components. These frameworks compress margins for non-integrated assemblers while rewarding manufacturers with captive engine production. Stakeholders must monitor electrification subsidy trajectories across Jakarta, Bangkok, and Delhi to anticipate platform investment timing.
Market Dynamics
Commercial delivery fleets across Southeast Asia are reorganizing procurement priorities toward fuel-efficient two-wheelers with lower total cost of ownership, compressing replacement cycles and elevating lifecycle cost analysis over upfront sticker price in vendor selection criteria.
Growth Catalysts
- ASEAN Euro-equivalent emission standards:Progressive tightening of tailpipe regulations in Indonesia, Vietnam, and Thailand accelerates fleet turnover toward cleaner combustion platforms and early electrification trials.
- Urban corridor congestion:Jakarta, Bangkok, and Ho Chi Minh City face severe last-mile delivery bottlenecks where motorcycles maintain throughput advantages over four-wheeled alternatives.
- 126cc–250cc engine band:This capacity segment bridges commuting utility with occasional highway capability, capturing broad demand across Indonesian archipelago logistics and Vietnamese manufacturing belt transport.
Market Restraints
- Steel and aluminum input volatility:Tubular frame and swingarm raw material costs fluctuate with regional commodity markets, squeezing margin for non-integrated assemblers lacking captive metalworking.
- Thai and Indonesian production concentration:Regional supply chains cluster manufacturing in flood-prone industrial zones near Bangkok and Jakarta, exposing output to climate-related disruption.
- Lithium-ion cell import dependency:Electric motorcycle battery packs rely predominantly on Chinese cell suppliers, creating geopolitical exposure and currency risk for ASEAN assemblers.
Strategic Opportunities
- Philippine archipelago logistics:Underpenetrated inter-island commercial fleet segments present white space for durable 150cc–200cc utility motorcycles with enhanced corrosion resistance.
- Delhi and Jakarta electrification subsidies:Municipal incentive programs for electric two-wheelers create regulatory tailwinds for battery-swapping platform investments.
- Digital fleet management integration:Convergence of telematics hardware and route-optimization software enables subscription-based mobility services for gig economy delivery contractors.
Industry Challenges
- Powertrain calibration expertise:Shortage of engineers skilled in fuel injection mapping for tropical humidity and altitude variation complicates localized product development.
- BIS and QCVN certification timelines:India's Bureau of Indian Standards and Vietnam's technical regulations impose extended homologation periods that delay new model launches.
- Legacy dealer network digitization:Traditional tier-two city distribution requires costly CRM and inventory system upgrades to support fleet customer account management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Motorcycle Market |
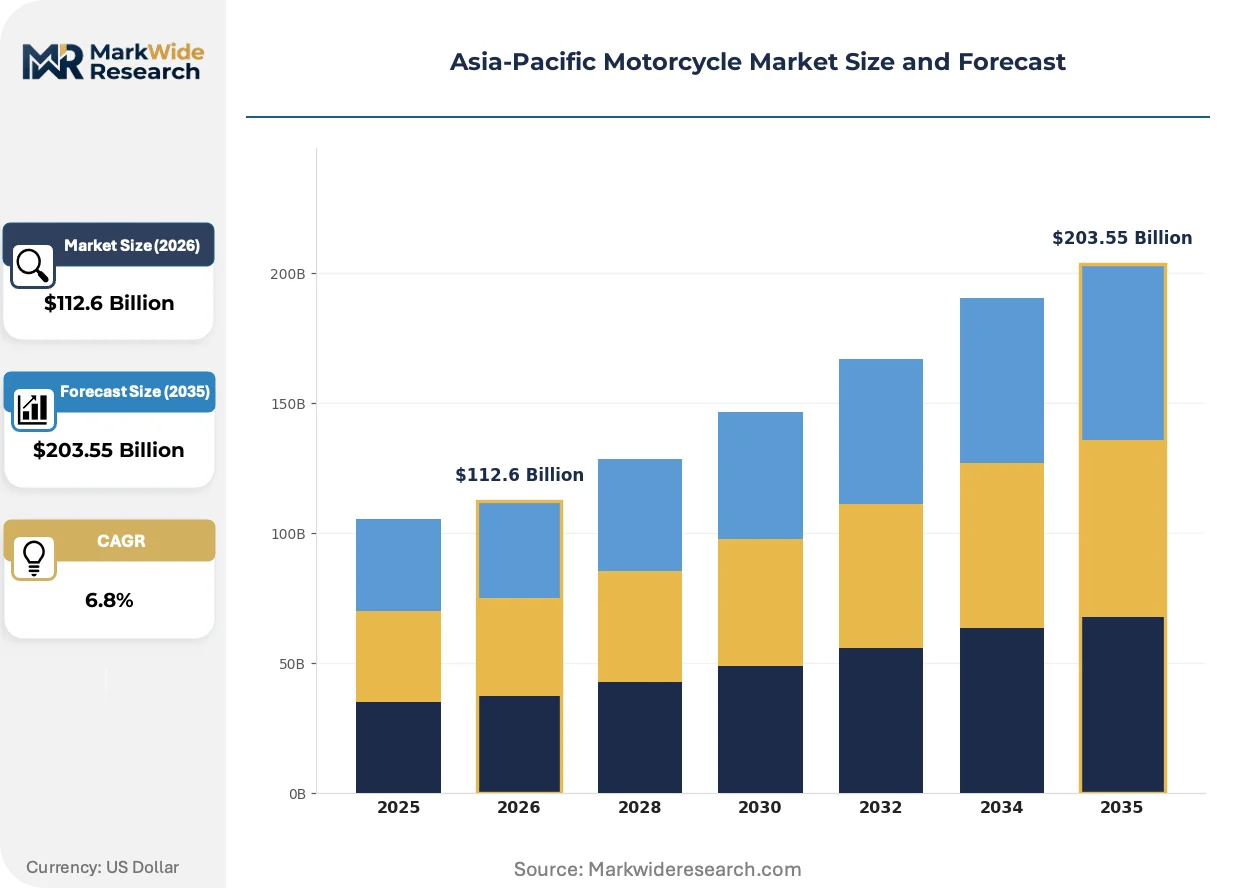
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $203.55 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sport Bikes, Cruiser Bikes, Touring Bikes, Scooter Engine Capacity: Up to 125cc, 126cc to 250cc, 251cc to 500cc, Above 500cc Usage Type: Commuting, Recreational, Racing, Delivery Customer Segment: First-Time Buyers, Enthusiasts, Commercial Users, Casual Riders |
| Companies Covered | KTM, Haojue, Honda Motor, Ducati, Kawasaki Heavy Industries, Yamaha Motor, BMW Motorrad, Hero MotoCorp, Suzuki Motor, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Motorcycle Market Evolving Landscape
Powertrain electrification and connected vehicle architectures are actively reshaping competitive positioning across the Asia-Pacific motorcycle landscape, compressing development cycles and elevating software competency alongside mechanical engineering.
Silicon carbide MOSFET power electronics are supplanting traditional IGBT modules in premium electric motorcycle motor controllers. Indonesian and Vietnamese fleet operators are piloting these platforms for thermal efficiency gains in stop-start urban delivery duty cycles. This semiconductor transition is enabling higher power density in compact battery pack configurations, reducing vehicle weight and extending range without cell chemistry breakthroughs.
India's BIS emission norms are tightening particulate matter and hydrocarbon limits for sub-150cc engines, forcing carburetor-to-fuel-injection conversions across the commuter segment. The regulatory pressure compresses margin for price-sensitive manufacturers while rewarding suppliers with in-house injection system development. Hero MotoCorp and TVS Motor are responding with localized ECU calibration facilities in Tamil Nadu and Karnataka.
Delivery platform aggregators are consolidating motorcycle procurement through direct manufacturer partnerships, bypassing traditional dealer networks. Grab, Gojek, and Shopee Xpress are negotiating volume-based fleet pricing and integrated maintenance contracts. This channel disintermediation is most visible in Jakarta and Bangkok, where platform-affiliated riders now represent the dominant commercial demand segment.
Asia-Pacific Motorcycle Market Segmentation
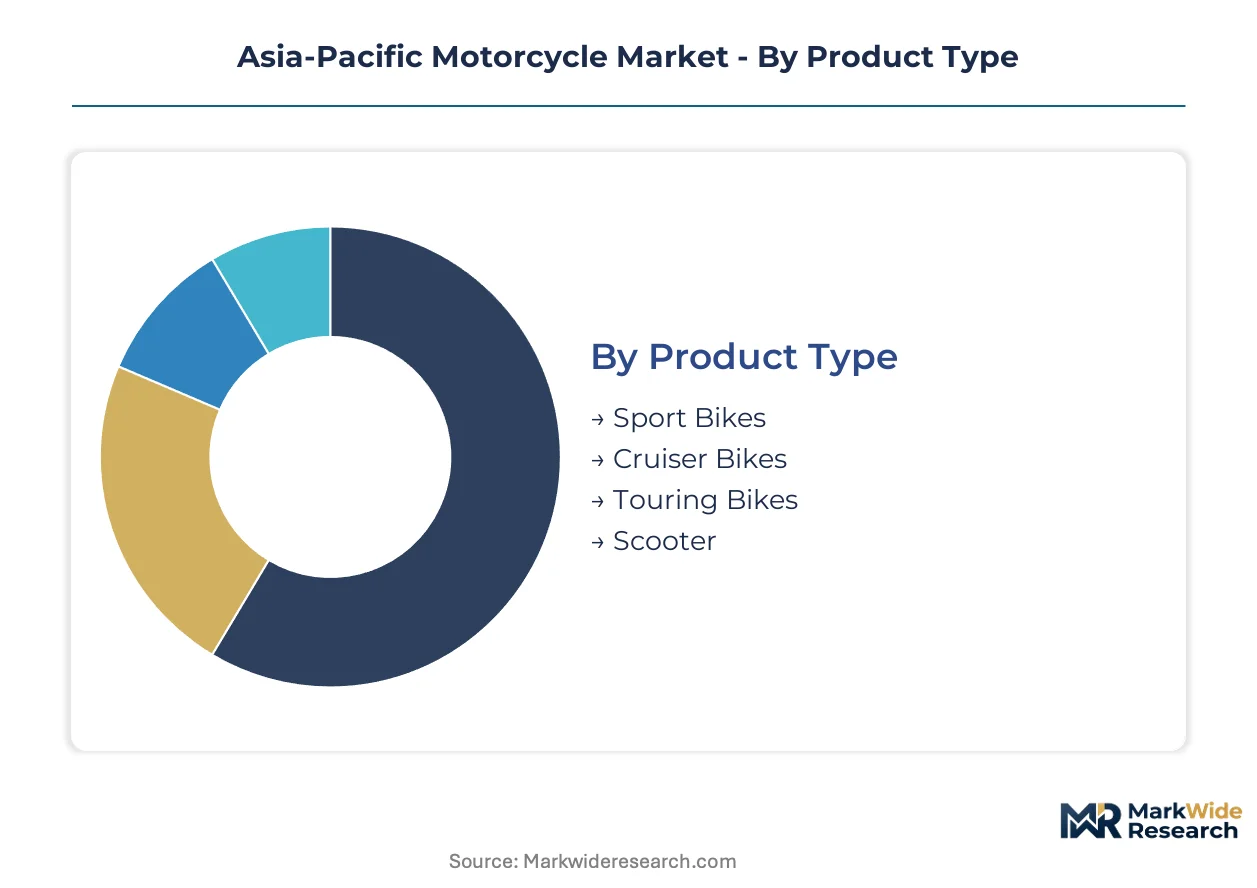
Segmentation across the Asia-Pacific motorcycle market reveals distinct channel strategies. Product type and engine capacity determine whether units flow through dealer networks, direct fleet contracts, or platform-aggregator partnerships. Understanding these pathways exposes margin concentration and procurement leverage points.
Product Type:
Channel distribution varies sharply by motorcycle configuration. Scooters dominate urban retail through traditional dealers, while sport bikes concentrate in premium showrooms and direct-to-enthusiast digital channels.
- Scooter:Step-through architecture with under-seat storage and automatic transmission. Demand concentrates in Jakarta, Bangkok, and Ho Chi Minh City where delivery fleets and commuters prioritize maneuverability in dense traffic. Municipal electrification subsidies are accelerating battery-swapping pilot programs for this segment.
- Sport Bikes:Performance-oriented machines with aerodynamic fairings and high-revving engines. Australian and Japanese enthusiasts drive margin concentration through specialty retailers and track-day event networks. Liquid-cooled engine platforms differentiate competitive positioning.
- Cruiser Bikes:Low-slung seating position with torque-focused V-twin engines. Niche appeal among urban professionals in Singapore and Sydney seeking weekend recreational use.
- Touring Bikes:Long-distance machines with wind protection and luggage capacity. Limited volume concentrates among affluent riders in Japan and Australia's coastal highway corridors.
Scooter dominates installed base across Southeast Asian megacities. Sport bike is where expansion concentrates among premium urban buyers.
Engine Capacity:
Cost tier stratification aligns engine displacement with customer purchasing power and regulatory treatment. Sub-150cc segments face tightening BIS and ASEAN emission standards, while larger displacements encounter luxury taxation in select markets.
- 126cc to 250cc:Single-cylinder or parallel-twin configurations balancing fuel efficiency with highway capability. Indonesian archipelago logistics and Vietnamese manufacturing belt transport drive fleet procurement. This band bridges commuter utility and occasional intercity travel.
- Up to 125cc:Air-cooled single-cylinder engines with carburetor or basic fuel injection. India's tier-two cities and Philippine provincial towns generate volume through price-sensitive first-time buyers. BIS emission norms are forcing costly injection system upgrades.
- 251cc to 500cc:Twin-cylinder platforms targeting enthusiast and premium commuter segments. Moderate growth in Thailand and Malaysia among riders upgrading from entry-level machines.
- Above 500cc:Multi-cylinder performance engines with advanced electronics. Australia and Japan sustain demand through discretionary recreational purchases and touring applications.
Up to 125cc dominates installed base across South Asian price-sensitive markets. 126cc to 250cc is where expansion concentrates as fleet operators prioritize total cost of ownership.
Usage Type:
Application-specific requirements reshape product specifications and distribution relationships. Commercial delivery platforms are disintermediating traditional dealer networks through direct manufacturer partnerships.
- Delivery:Ruggedized frames with enhanced corrosion resistance and high-cycle durability. Grab, Gojek, and Shopee Xpress negotiate volume-based fleet pricing with integrated maintenance contracts. Stop-start urban duty cycles favor fuel injection and emerging electric platforms.
- Commuting:Reliability-focused specifications with low maintenance intervals. Indonesian and Vietnamese urban corridors generate sustained replacement demand as emission standards accelerate fleet turnover.
- Recreational:Styling and comfort prioritization over pure utility. Weekend riders in Australia's coastal regions and Japan's mountain roads sustain premium pricing.
- Racing:Track-focused machines with specialized suspension and braking systems. Extremely limited volume concentrated among dedicated enthusiast communities and organized competition circuits.
Commuting dominates installed base across the region's urban workforce. Delivery is where expansion concentrates as platform economies reshape procurement channels.
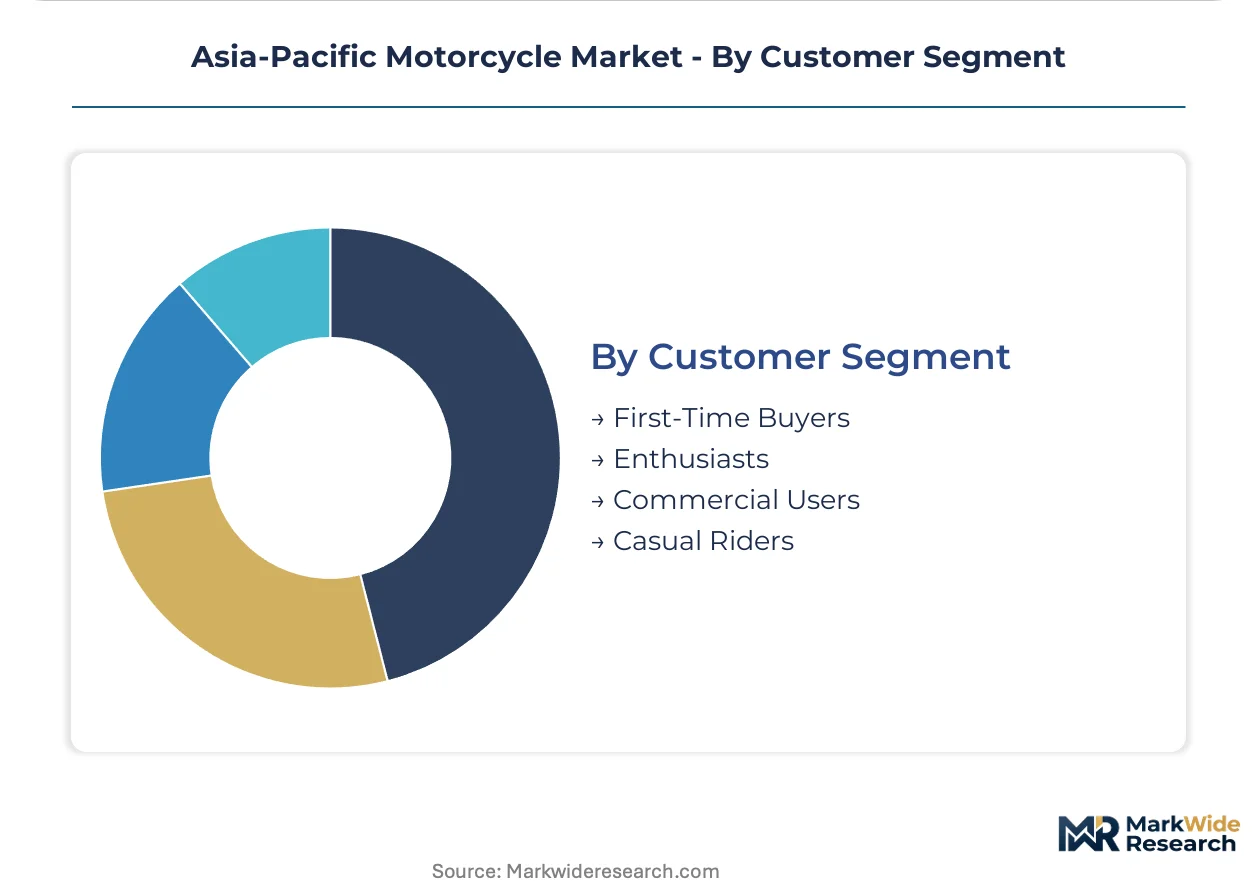
Customer Segment:
Buyer maturity and purchase frequency determine marketing investment and loyalty program design. First-time buyers require financing partnerships, while commercial users demand total cost of ownership analytics.
- Commercial Users:Fleet operators and gig economy contractors with high utilization rates. Direct manufacturer relationships bypass dealer markups and enable customized service intervals. Telematics integration supports route optimization and asset tracking.
- First-Time Buyers:Price-sensitive entrants prioritizing affordability and operating simplicity. India's rural and semi-urban markets generate volume through two-wheeler financing schemes and trade-in programs.
- Enthusiasts:Performance-oriented purchasers with brand loyalty and upgrade cycles. Australian and Japanese markets sustain premium pricing through limited editions and racing heritage marketing.
- Casual Riders:Discretionary users with intermittent utilization and extended replacement cycles. Secondary market transactions outpace new purchases in this segment.
First-time buyers dominate installed base across emerging market expansion. Commercial users is where expansion concentrates as delivery platforms consolidate procurement volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial delivery contractors and first-time commuters dominate purchasing across Asia-Pacific, with fleet operators in Jakarta, Bangkok, and Ho Chi Minh City driving volume concentration toward fuel-efficient utility machines.
Indonesia
Jakarta's delivery platforms generate sustained demand for 125cc–150cc scooters with automatic transmission. The country's Ministry of Industry enforces Euro 4-equivalent emission standards that accelerate carburetor phase-out. Manufacturing clusters in Bekasi and Karawang host assembly operations for regional export.
India
Tier-two cities across Maharashtra and Gujarat generate replacement demand as BIS emission norms tighten particulate limits for sub-150cc engines. Hero MotoCorp and TVS Motor operate localized ECU calibration facilities in Tamil Nadu. The Delhi-NCR corridor experiments with electric two-wheeler subsidies and battery-swapping infrastructure.
Vietnam
Ho Chi Minh City's manufacturing belt sustains fleet procurement of 150cc utility motorcycles for inter-factory logistics. QCVN technical regulations extend homologation timelines for imported powertrain components. Industrial zones in Binh Duong and Dong Nai concentrate assembly capacity for domestic and Cambodian markets.
Thailand
Bangkok's congestion charges favor motorcycle throughput for last-mile delivery. The Industrial Standards Institute certifies fuel injection systems and emission control devices for ASEAN distribution. Rayong and Chonburi host Honda and Yamaha production bases serving Australian and Japanese export demand.
Philippines
Inter-island logistics operators seek corrosion-resistant 150cc–200cc machines for archipelago commercial routes. The Department of Trade and Industry enforces safety and emission labeling requirements. Cebu and Davao manufacturing zones supply Visayas and Mindanao distribution networks.
Asia-Pacific Motorcycle Market Competitive Landscape
Player mix skews toward integrated Japanese manufacturers with captive engine production and established ASEAN assembly networks. Market structure concentrates around three to four dominant assemblers controlling distribution through tier-two city dealer networks. Strategic archetypes include full-line producers with combustion and electric portfolios, regional specialists serving single-country demand, and premium importers targeting enthusiast segments. Competitive moves center on backward integration into fuel injection systems and direct fleet partnerships bypassing traditional retail channels.
Among Japanese full-line producers, Honda Motor and Yamaha Motor anchor regional manufacturing through Thai and Indonesian assembly bases. Hero MotoCorp occupies a position within the India-focused commuter tier, exemplifying localized product development for price-sensitive markets. These three entities represent distinct strategic postures: transnational scale with ASEAN export orientation, premium urban positioning through liquid-cooled platforms, and deep distribution penetration in South Asian tier-two cities.
| Leading Market Players |
|---|
| KTM |
| Haojue |
| Honda Motor |
| Ducati |
| Kawasaki Heavy Industries |
| Yamaha Motor |
| BMW Motorrad |
| Hero MotoCorp |
| Suzuki Motor |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Thai and Indonesian assembly plants shapes regional price floors for fuel-injected commuter motorcycles, concentrating supply-side leverage among manufacturers with captive engine production while compressing margins for non-integrated assemblers dependent on imported powertrain components.
Pricing Analysis
Cost-plus contracts with steel and aluminum indexation dominate procurement between ASEAN assemblers and tubular frame suppliers. Three-tier pricing structure across premium liquid-cooled, standard air-cooled injection, and economy carbureted tiers reflects BIS and QCVN certification compliance costs. Pricing pressure stems from lithium-ion cell import dependency and currency exposure to Chinese suppliers. First-time buyers in Indian tier-two cities exhibit highest price sensitivity, while Australian enthusiasts accept premium positioning for track-capable sport bikes.
Supply Chain Analysis
Strait of Malacca transit underwrites just-in-time delivery schedules for Japanese OEMs sourcing semiconductors from Taiwan, South Korea, and Japan. Regional production draws from Chinese lithium-ion cells, Indian steel tubing, and Thai aluminum casting. Single-source vulnerability concentrates in battery cell supply, with geopolitical friction threatening ASEAN electrification timelines. Distribution runs through tier-two city dealer networks for retail sales, while direct manufacturer partnerships serve Grab, Gojek, and Shopee Xpress fleet procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-aggregator procurement consolidation fragments traditional dealer channels, creating white-space opportunities for specialists targeting underpenetrated archipelago logistics and electrification infrastructure.
For Market Incumbents: Fortify backward integration into fuel injection ECU calibration to defend against BIS particulate tightening and emerging electric platform competition. Prioritize captive engine production in Tamil Nadu and Karnataka facilities to compress homologation timelines and reduce imported component exposure. For New Entrants and Emerging Players: BIS fast-track certification for sub-150cc fuel-injected commuters offers entry into India's replacement cycle acceleration. Target Philippine inter-island commercial fleets with corrosion-resistant 150cc–200cc utility specifications. Pursue direct fleet partnerships bypassing established dealer networks to capture Grab and Shopee Xpress volume. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among telematics-integrated fleet management providers serving platform-affiliated delivery contractors. Long-term viability hinges on electrification subsidy durability across Jakarta, Bangkok, and Delhi. Monitor battery-swapping infrastructure deployment rates as inflection indicator for platform economics.| Strategic Initiative | Industry Significance |
|---|---|
| Fuel Injection System Localization | BIS particulate compliance in Tamil Nadu compresses competitor response timelines. |
| Battery-Swapping Platform Investment | Jakarta and Delhi subsidy trajectories determine electric motorcycle adoption velocity. |
| Direct Fleet Partnership Formation | Grab and Gojek volume consolidation disintermediates traditional dealer markups. |
| Corrosion-Resistant Frame Development | Philippine archipelago logistics demand outpaces standard commuter specifications. |
| Telematics Hardware Integration | Route-optimization subscriptions monetize gig economy contractor utilization data. |
Research Methodology
Desk research of ASEAN trade statistics, BIS certification registries, and OEM production disclosures preceded structured interviews with fleet procurement managers at delivery platforms, plant directors at Thai and Indonesian assembly facilities, fuel injection calibration engineers, and tier-two city dealer network operators. Primary fieldwork validated secondary findings against commercial utilization patterns and regulatory implementation timelines. Bottom-up unit economics triangulated with top-down production capacity assessments.
Variance decomposition across engine capacity bands, product type configurations, and usage applications shaped the analytical framework over the projection horizon. Modeled segmentation spanned propulsion architecture, customer segment maturity, and regional regulatory cluster intensity. CAGRs derived from replacement cycle compression rates and fleet turnover acceleration under Euro-equivalent emission standards. Forecast inputs incorporated platform-aggregator procurement volume shifts and electrification subsidy trajectory assumptions.
Decision-makers should treat outputs as directional under stable lithium-ion cell supply and sustained ASEAN emission enforcement; material deviation would warrant model refresh. Forecasts reflect base-case assumptions regarding BIS implementation timelines and platform fleet consolidation. Practitioners should keep alternative scenarios live as Indonesian and Vietnamese subsidy durability and Chinese cell export policy evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Motorbike Riding Gear Market
Bikes and Motorcycles
Trike Market
Bikes and Motorcycles
Bike Taxi Market
Bikes and Motorcycles
Two-Wheeler Market
Bikes and Motorcycles
Malaysia Bicycle Market
Bikes and Motorcycles
Motorcycle Lighting Market
Bikes and Motorcycles
United States E-Bike Market
Bikes and Motorcycles
Japan Motorcycle ADAS Market
Bikes and Motorcycles
Motorcycle Chain Market
Bikes and Motorcycles
Bike Fenders Market
Bikes and Motorcycles
Europe E-Cargo Bike Market
Bikes and Motorcycles
Africa Two-Wheeler Market
Bikes and Motorcycles
Cargo Bicycles Market
Bikes and Motorcycles
Italy E-Bike Market
Bikes and Motorcycles
Motorcycle Accessories Market
Bikes and Motorcycles
Child Bike Seats Market