
 Motorsport Components Market | 2026-2036
Motorsport Components Market Size, Share, and Industry Trends Forecast 2026-2036
Motorsport Components Market Analysis
Market Context
The capability gap between capital-intensive OEM-affiliated suppliers and independent component specialists is redrawing competitive boundaries in motorsport components. Pirelli leverages its exclusive tire supply contracts with Formula 1 to sustain decades of compound development leadership. Brembo anchors its position through vertical integration into carbon-ceramic brake disc manufacturing, while ZF Friedrichshafen competes across transmission and chassis systems with extensive motorsport engineering operations.
Technical Definition and Segment Structure
Motorsport components encompass precision-engineered subsystems designed for extreme thermal, mechanical, and aerodynamic loads, with brake discs routinely operating above 1,000°C and suspension arms machined to tolerances within 0.02 millimeters. These parts serve the primary purpose of maximizing vehicle performance, driver safety, and regulatory compliance within formula racing, touring car, endurance, and rally disciplines. Engine and brake system segments command substantial margin pools due to their critical performance differentiation and frequent replacement cycles, while 3D printing within manufacturing processes represents the fastest-growing fabrication method as teams prototype complex geometries with reduced lead times. CNC machining dominates current production volume across aluminum and carbon fiber materials, though composite-intensive applications are expanding fastest in monocoque and aerodynamic component fabrication.
Regulatory Framework
FIA technical regulations, EU REACH chemical compliance for carbon fiber resins, and EPA emissions standards for racing engines collectively shape product specifications and market access conditions across major motorsport jurisdictions. FIA cost-cap provisions now extend to power unit and transmission suppliers, forcing component pricing transparency that alters procurement negotiations between race teams and vendors. Stakeholders must monitor evolving sustainability mandates from the EU Green Deal and emerging battery-electric formula series regulations to anticipate material and powertrain investment requirements.
Market Dynamics
Carbon fiber composite manufacturing is fragmenting supplier hierarchies as smaller engineering houses acquire automated fiber placement systems previously exclusive to aerospace tier-1s, compressing development cycles from months to weeks for monocoque and aerodynamic components.
Growth Catalysts
- EU Green Deal sustainability mandates:Battery-electric formula series regulations are accelerating demand for lightweight chassis architectures and thermal management systems across endurance and touring car disciplines.
- Additive manufacturing adoption:Metal 3D printing is enabling rapid prototyping of titanium suspension geometries that CNC machining cannot economically produce at prototype volumes.
- Germany-Italy-Japan engineering clusters:Concentrated motorsport R&D infrastructure in Stuttgart, Maranello, and Sakura is pulling component procurement toward co-located supplier networks.
Market Restraints
- Carbon fiber precursor cost volatility:Polyacrylonitrile feedstock prices fluctuate with oil markets, squeezing margin pools for composite-intensive brake disc and monocoque suppliers.
- REACH compliance burden:ECHA restrictions on epoxy resin chemistries are forcing reformulation of established pre-preg systems, extending qualification timelines for European suppliers.
- Single-source aerodynamic supply risk:Wind tunnel and CFD expertise concentrates among three UK-based engineering consultancies, creating procurement bottlenecks for independent race teams.
Strategic Opportunities
- Saudi Arabia motorsport infrastructure investment:Qiddiya circuit development and regional F1 expansion are creating demand for localized component warehousing and rapid-response fabrication services.
- Hydrogen combustion powertrains:FIA feasibility studies for hydrogen-fueled endurance racing are opening development contracts for high-pressure fuel system and injection component specialists.
- Direct team-to-manufacturer digital procurement:B2B platforms are disintermediating traditional motorsport distributors, enabling smaller teams to specify custom brake pad compounds with 48-hour turnaround.
Industry Challenges
- Composite technician scarcity:Automated fiber placement and autoclave operation skills concentrate among aerospace-trained labor pools, forcing motorsport suppliers to compete for talent with defense contractors.
- FIA cost-cap audit complexity:Component pricing transparency requirements are forcing suppliers to restructure intercompany transfer pricing, extending contract negotiation cycles with power unit and transmission vendors.
- Legacy CAD-CAM system integration:Established teams operate proprietary design databases that resist interoperability with supplier PLM platforms, complicating collaborative development of suspension kinematics packages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorsport Components Market |
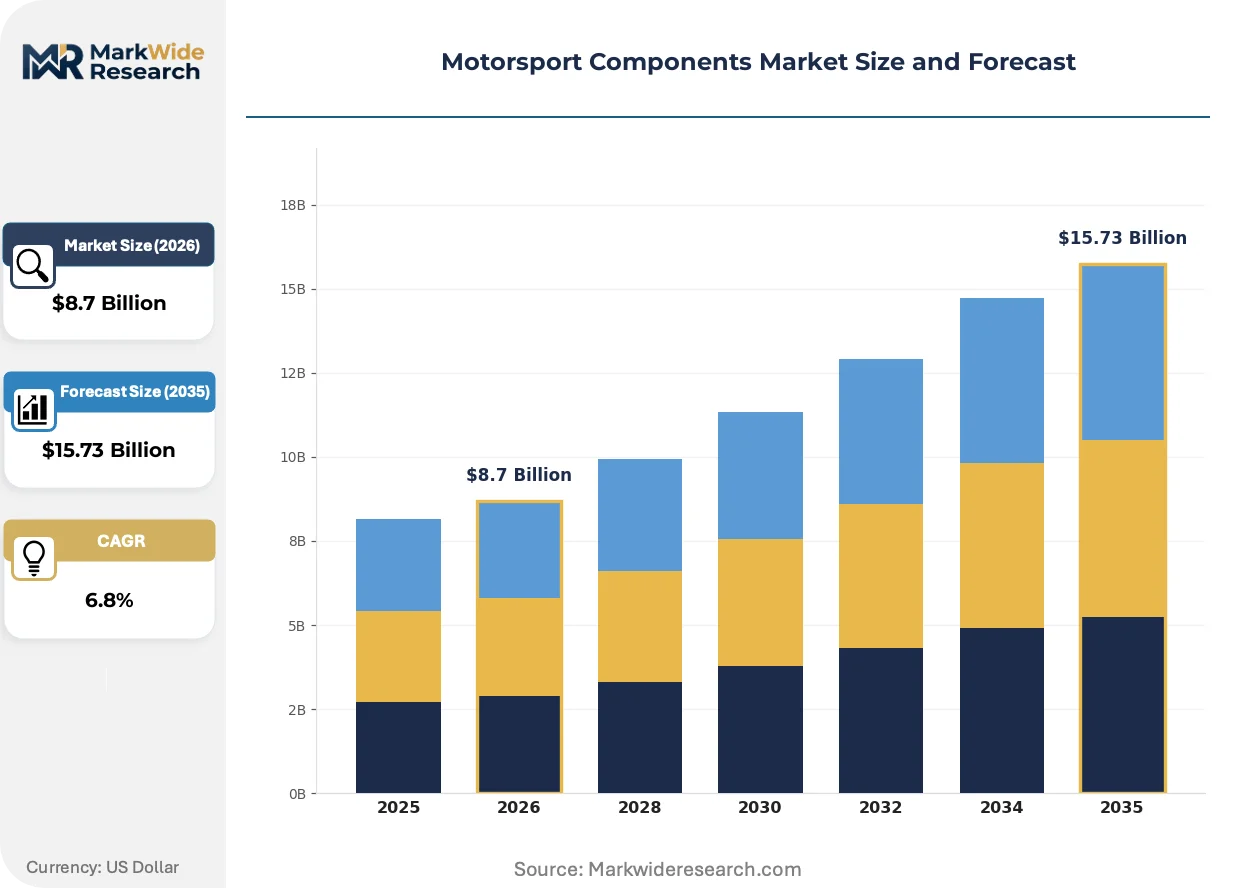
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Suspension, Brake System, Engine, Transmission Manufacturing Process: CNC Machining, Forging, Injection Molding, 3D Printing End User: OEMs, Aftermarket Providers, Race Teams, Enthusiasts Material: Aluminum, Carbon Fiber, Steel, Composite |
| Companies Covered | Pirelli, Mercedes, ZF Friedrichschafen, Brembo, Toyota Motor Corporation, Bosch, Ferrari, SKF, Magneti Marelli, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorsport Components Market Emerging Trajectories
Digital thread integration across design, simulation, and production is collapsing traditional stage-gate development, while regulatory pressure on material sustainability and powertrain electrification is redirecting R&D investment toward novel fabrication chemistries and thermal management architectures.
Generative design algorithms paired with topology optimization are fragmenting traditional component design workflows. Formula 1 and WEC teams now deploy AI-driven lattice structures for suspension wishbones and brake caliper housings, reducing mass while maintaining stiffness. Engineering departments that previously relied on iterative manual CAD are compressing concept-to-prototype timelines by sixty percent, enabling more aggressive geometric experimentation within fixed development budgets.
REACH chemical compliance for carbon fiber resins is forcing material substitutions across European supply chains. ECHA restrictions on bisphenol-A derivatives and specific amine hardeners are compelling pre-preg manufacturers to qualify bio-based epoxy alternatives, extending qualification protocols for monocoque and aerodynamic components. Suppliers serving FIA-homologated series are responding by establishing dual-source material qualifications to prevent single-chemistry supply disruptions during regulatory transition periods.
Team procurement departments are consolidating vendor relationships around full-subsystem suppliers capable of integrated brake-transmission-chassis packages. Independent race teams that previously sourced discrete components from specialist manufacturers are now awarding multi-year contracts to engineering houses offering design-through-manufacturing responsibility. This concentration is most visible in Germany's Baden-Württemberg region, where ZF Friedrichshafen and Bosch Motorsport are capturing expanded scope from customer racing programs seeking reduced interface complexity.
Motorsport Components Market Segmentation
Motorsport component procurement patterns diverge sharply across technical specifications, fabrication methods, and customer types. Understanding these fault lines exposes where suppliers capture premium pricing versus where commoditization pressures concentrate.
Component Type:
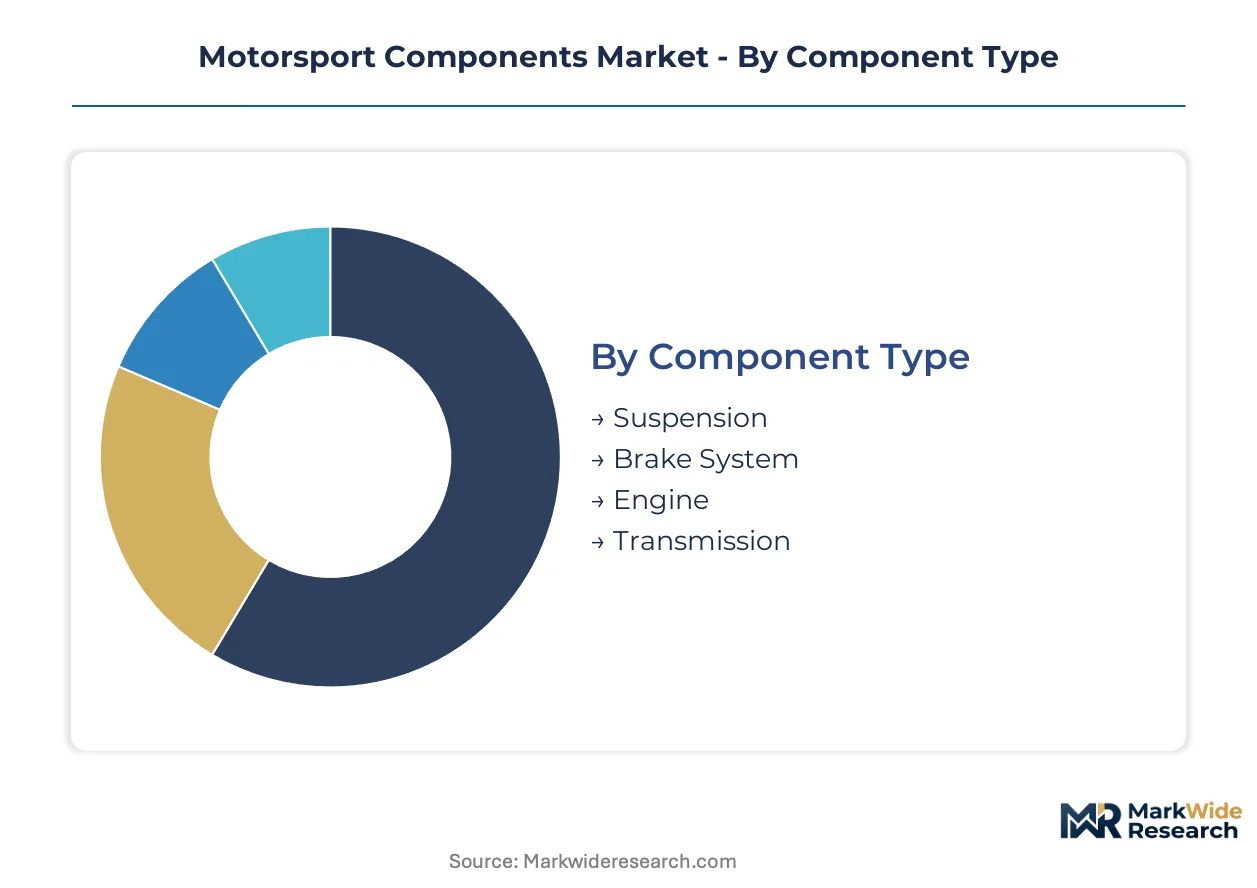
Brake systems and engine subsystems command the deepest margin pools due to thermal performance differentiation and regulatory homologation complexity, while suspension and transmission segments face more transparent pricing from standardized architectures.
- Brake System:Carbon-ceramic discs and multi-piston calipers operate above 1,000°C during deceleration events. Demand clusters with Formula 1 and WEC teams in Germany and Italy as these organizations prioritize thermal management under FIA cost-cap scrutiny.
- Engine:Power unit assemblies encompass turbochargers, energy recovery systems, and internal combustion blocks machined to extreme tolerances. Procurement concentrates among OEM-affiliated suppliers in Japan and Germany where hybrid powertrain development absorbs the largest R&D allocations.
- Suspension:Wishbones, dampers, and steering racks fabricated from aluminum and carbon fiber composites.
- Transmission:Sequential gearboxes and differential housings serving touring car and rally disciplines.
The dominant share belongs to Engine, while Brake System is closing the gap fastest.
Manufacturing Process:
Volume concentration currently favors subtractive methods, though additive fabrication is rewriting lead-time economics for prototype-intensive development programs.
- CNC Machining:Subtractive manufacturing of aluminum suspension brackets and steel transmission cases dominates current production volume. Maranello and Stuttgart engineering clusters maintain the densest concentrations of five-axis machining centers serving FIA-homologated series.
- 3D Printing:Laser powder bed fusion of titanium brake caliper housings and inconel exhaust manifolds collapses prototyping cycles from weeks to days. Adoption is climbing the fastest among independent race teams lacking captive tooling investments.
- Forging:Closed-die forming of aluminum and steel components for high-stress suspension and drivetrain applications.
- Injection Molding:Polymer fabrication for aerodynamic ducts, cooling scoops, and interior trim in customer racing categories.
CNC Machining retains the largest installed base, yet 3D Printing is expanding most quickly as teams compress design iteration timelines.
End User:
Procurement authority fragments across vertically integrated manufacturers, distributed service networks, and direct team relationships with divergent technical specification depth.
- OEMs:Manufacturer-affiliated motorsport divisions such as Mercedes-AMG and Ferrari Corse Clienti specify integrated subsystem packages. These organizations leverage captive engineering resources to dictate component architectures across customer racing programs.
- Race Teams:Independent constructors from Formula 2, WEC, and GT categories source discrete components or full suspension-brake-transmission modules. Procurement in this segment is shifting toward digital platforms that disintermediate traditional distributors.
- Aftermarket Providers:Specialized retailers and service centers supplying replacement parts and upgrade kits to amateur competitors.
- Enthusiasts:Individual owners of track-day vehicles and historic racing cars purchasing consumable brake pads and suspension bushings.
OEMs control the steepest expenditure per vehicle, though Race Teams are gaining procurement sophistication fastest through direct manufacturer relationships.
Material:
Performance requirements and regulatory compliance are fragmenting material selection across thermal load, mass reduction, and chemical safety dimensions.
- Carbon Fiber:Pre-preg composites fabricated into monocoque structures, aerodynamic surfaces, and high-temperature brake ducts. ECHA restrictions on epoxy resin chemistries under REACH are forcing European suppliers to qualify bio-based alternatives, extending qualification timelines.
- Aluminum:7075 and 6061 alloys machined into suspension wishbones and gearbox casings balance strength-to-weight with machinability. Stuttgart and Sakura engineering clusters anchor demand for precision-forged and CNC-finished aluminum components.
- Steel:High-strength alloys for transmission gears, driveshafts, and impact-absorbing structural elements.
- Composite:Glass fiber and natural fiber hybrids for non-structural body panels and interior components.
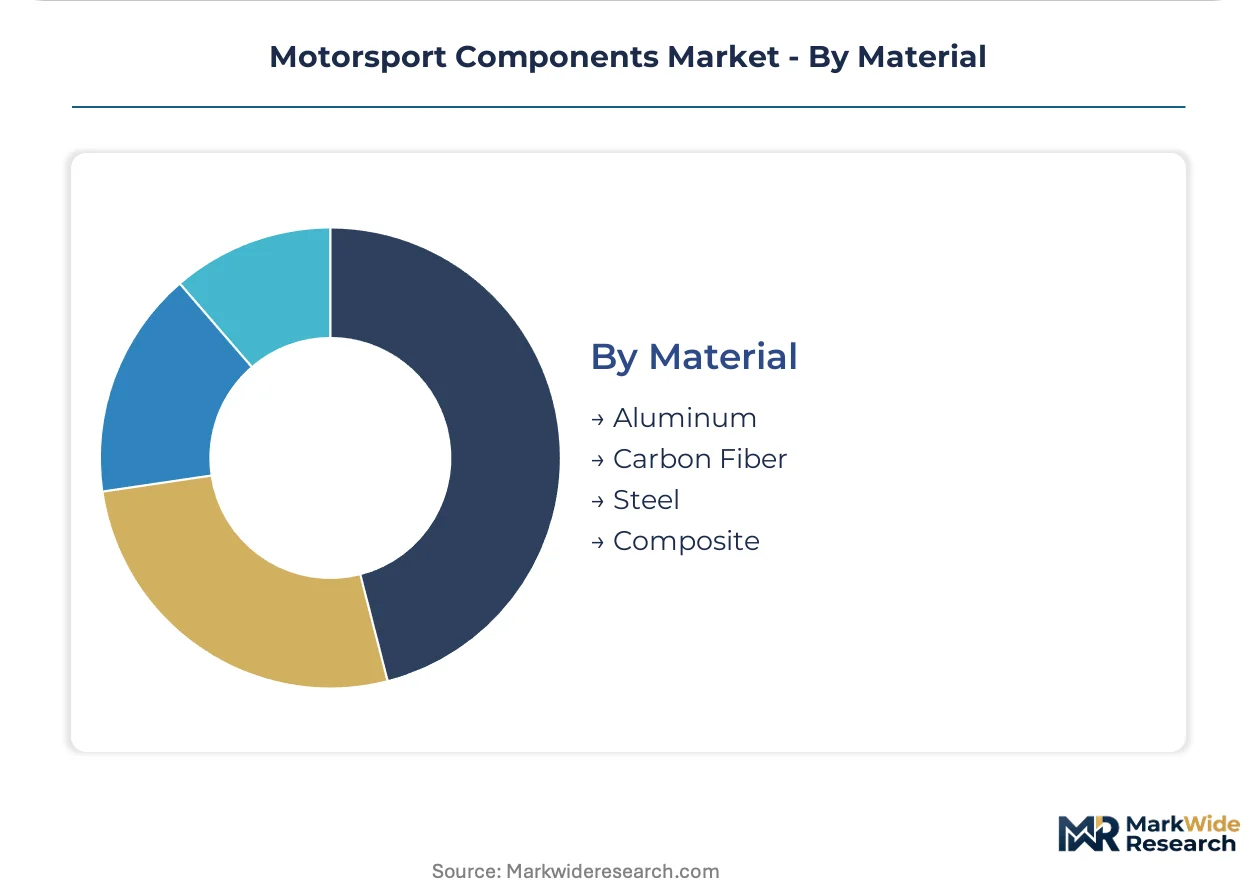
Carbon Fiber holds the premium positioning, while Aluminum maintains the broadest application footprint across price-accessible categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement elasticity varies sharply across motorsport jurisdictions. German and Italian buyers absorb premium pricing for FIA-homologated brake and powertrain systems, while Saudi Arabian and Chinese entrants prioritize rapid-response logistics over technical specification depth.
Germany
Formula 1 power unit development and endurance racing programs drive sustained demand for precision-engineered transmission and chassis subsystems. The EU Green Deal accelerates investment in battery-electric formula architectures, forcing Stuttgart-area suppliers to requalify lightweight material portfolios. Baden-Württemberg engineering clusters concentrate five-axis machining capacity and automated fiber placement systems serving OEM-affiliated motorsport divisions.
Italy
Maranello and Modena-based constructors anchor carbon-ceramic brake disc procurement and composite monocoque fabrication for FIA-sanctioned series. REACH compliance deadlines from ECHA are compelling pre-preg manufacturers to reformulate epoxy resin chemistries, extending qualification timelines for European suppliers. Emilia-Romagna's dense supplier networks maintain captive tooling investments for rapid design iteration cycles.
Japan
Hybrid powertrain R&D absorption by Toyota and Honda motorsport programs sustains demand for energy recovery system components and high-temperature alloys. METI industrial policy supports carbon fiber precursor development to reduce polyacrylonitrile import dependency. Sakura and Toyota City engineering bases concentrate turbocharger and energy storage system manufacturing for WEC and Super Formula categories.
United Kingdom
Silverstone and Milton Keynes motorsport valleys host wind tunnel and CFD expertise concentrated among engineering consultancies serving independent race teams. FIA cost-cap audit requirements are forcing component suppliers to restructure transfer pricing documentation. Oxfordshire and Northamptonshire clusters specialize in suspension kinematics packages and rapid prototyping services for Formula 2 and GT championships.
Saudi Arabia
Qiddiya circuit development and regional F1 calendar expansion are creating demand for localized component warehousing and 48-hour fabrication turnaround capabilities. The Saudi national motorsport regulator is establishing vehicle homologation frameworks aligned with FIA technical standards. Riyadh and Jeddah logistics hubs are attracting brake pad and suspension specialist distributors seeking proximity to Middle Eastern customer racing programs.
Motorsport Components Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier that competes on fabrication speed and regulatory compliance depth. The upper tier captures multi-year subsystem contracts through design-through-manufacturing responsibility, while specialists win discrete component orders from independent teams lacking captive engineering resources. Three archetypes dominate: OEM-affiliated divisions leveraging captive R&D, independent precision fabricators with automated fiber placement capacity, and tire suppliers holding exclusive series contracts. Competitive moves concentrate on backward integration into carbon-ceramic production and strategic partnerships for hydrogen powertrain development.
Among the integrated tier, Pirelli exemplifies the exclusive supply contract archetype that locks in compound development leadership across decades of Formula 1 participation. Brembo anchors the brake system specialist position through in-house production of carbon-ceramic disc manufacturing capabilities. ZF Friedrichshafen occupies the full-subsystem supplier role, competing across transmission and chassis systems with extensive motorsport engineering operations that capture expanded scope from customer racing programs.
| Leading Market Players |
|---|
| Pirelli |
| Mercedes |
| ZF Friedrichschafen |
| Brembo |
| Toyota Motor Corporation |
| Bosch |
| Ferrari |
| SKF |
| Magneti Marelli |
| Others |
Supply Flow & Price Mechanics
Five-axis machining center utilization rates above eighty percent in Stuttgart and Maranello engineering clusters compress fixed cost absorption across brake disc and suspension component production, establishing price floors that smaller independent fabricators cannot match without captive aerospace contracts.
Pricing Analysis
After-sales consumable revenue from brake pad compounds and replacement carbon-ceramic discs drives lifetime customer value beyond initial system procurement. Three-tier pricing structure across premium, standard, and economy levels stratifies by FIA homologation grade and thermal performance certification. Pricing pressure stems from FIA cost-cap audit requirements forcing component pricing transparency in power unit and transmission negotiations. Independent race teams exhibit highest price sensitivity due to fixed championship budgets, while OEM-affiliated motorsport divisions absorb premium positioning for integrated subsystem packages.
Supply Chain Analysis
Just-in-time inventory strategies dominate brake system and suspension procurement for Formula 1 and WEC teams operating on compressed race-calendar development cycles, though strategic stockpiling of polyacrylonitrile carbon fiber precursor mitigates oil-market price volatility. Supply concentrates in Germany, Italy, and Japan where automated fiber placement capacity and five-axis machining clusters serve FIA-homologated series. Raw material dependencies encompass polyacrylonitrile feedstock, aerospace-grade aluminum alloys, and titanium powder for additive manufacturing. Single-source vulnerability concentrates in UK-based wind tunnel and CFD engineering consultancies serving aerodynamic development. Distribution runs through direct team-to-manufacturer digital platforms disintermediating traditional motorsport distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery-electric powertrain substitution threatens traditional brake thermal management and internal combustion component demand, forcing incumbents to defend positioning through electrification-adjacent capabilities.
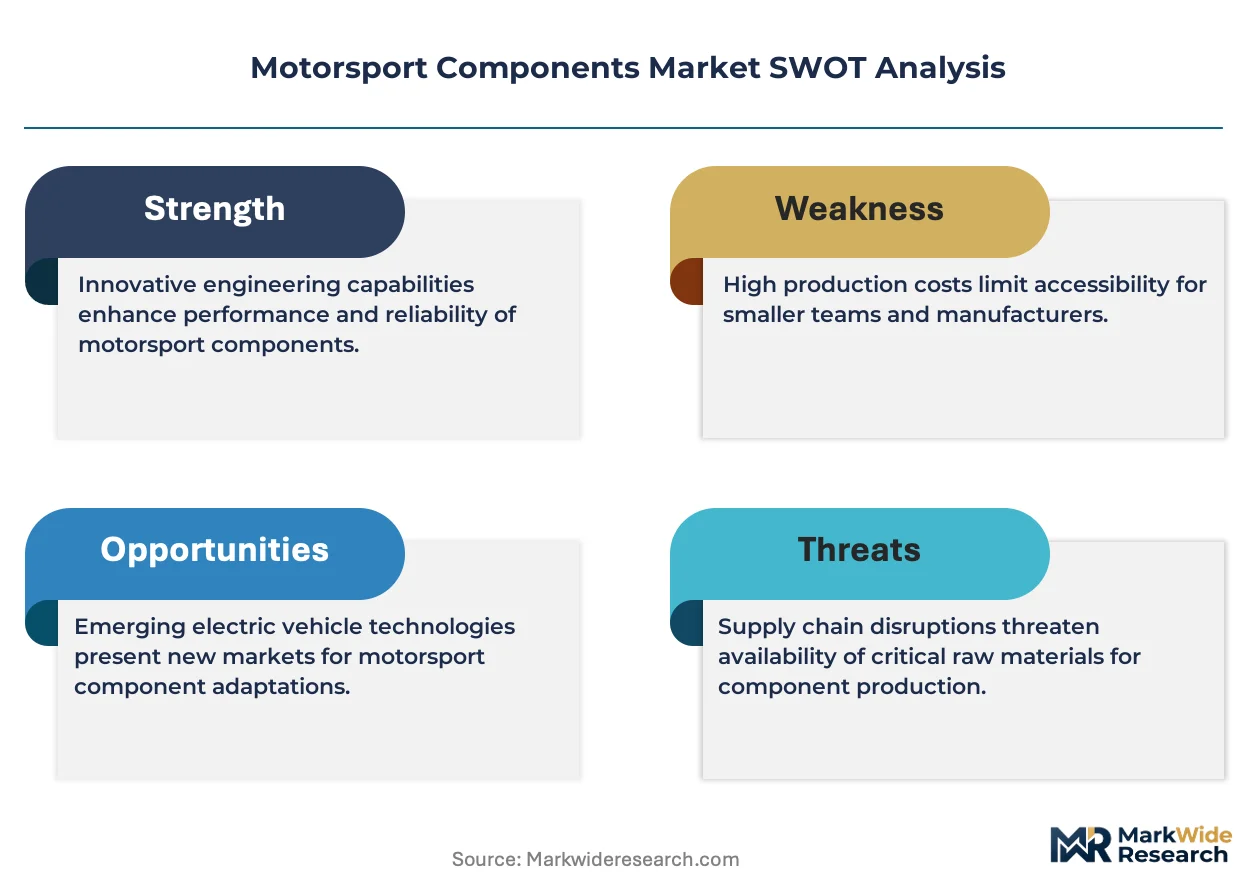
For Market Incumbents: Compound defensive positioning by acquiring automated fiber placement capacity to capture composite-intensive monocoque contracts from aerospace talent pools, and anchor multi-year integrated brake-transmission-chassis packages before customer racing programs consolidate vendor relationships. FIA cost-cap pricing transparency demands upstream control over carbon-ceramic disc manufacturing to preserve margin pools. For New Entrants and Emerging Players: Rapid-response fabrication services for Saudi Arabian Qiddiya circuit development represent the most penetrable service-layer gap, where localized 48-hour brake pad compound turnaround eludes established European suppliers. Target hydrogen combustion fuel system development contracts as FIA feasibility studies progress, leveraging direct digital procurement platforms to bypass traditional distributor networks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision fabricators with captive automated fiber placement systems and dual-source REACH-compliant resin qualifications. Five-to-ten year viability hinges on electrification-transition exposure balance. Acquisition targets should demonstrate qualified bio-based epoxy alternatives and thermal management system capabilities for battery-electric architectures. The signal to watch is FIA hydrogen endurance racing regulation finalization accelerating high-pressure fuel system development contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon-Ceramic Production | In-house disc manufacturing preserves margin pools under FIA cost-cap pricing transparency mandates. |
| Dual-Source REACH-Compliant Resin Qualification | Bio-based epoxy alternatives prevent supply disruption during ECHA regulatory transition periods. |
| Automated Fiber Placement Capacity Acquisition | Aerospace-derived fabrication systems compress monocoque development cycles from months to weeks. |
| Hydrogen Fuel System Development Partnership | FIA feasibility studies for endurance racing open high-pressure injection component contracts. |
| Direct Digital Procurement Platform Launch | B2B disintermediation enables 48-hour custom brake compound turnaround for independent teams. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FIA technical regulations, ECHA REACH compliance databases, and customs trade data covering carbon fiber precursor and aerospace alloy movements. Primary interviews encompassed brake system procurement directors at Formula 1 constructors, composite engineering leads at Maranello-area monocoque fabricators, and powertrain sourcing managers at Stuttgart OEM motorsport divisions. Secondary validation drew from FIA cost-cap audit disclosures, ECHA substance restriction notifications, and METI industrial policy documentation. Bottom-up component demand modeling triangulated against top-down motorsport championship expenditure analysis.
Segmentation dimensions modeled encompass component type, manufacturing process, end-user archetype, and material composition across the projection horizon. Engine and brake system segments received distinct thermal load and replacement cycle assumptions. Geographic clustering applied engineering hub concentration indices for Stuttgart, Maranello, and Sakura. CAGR derivation incorporated polyacrylonitrile price elasticity and FIA regulatory compliance cost trajectories. Industry-specific inputs included FIA homologation timeline data and REACH reformulation qualification protocols.
Forecasts assume regulatory continuity in EU REACH chemical compliance and FIA cost-cap enforcement regimes; material policy shifts would require re-modeling. Carbon fiber precursor cost volatility and hydrogen combustion regulation uncertainty constitute primary revision triggers. Practitioners should keep alternative scenarios live as battery-electric formula series technical standards and Saudi Arabian homologation frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
LAMEA Motorcycle ADAS Market
Bikes and Motorcycles
Folding Bikes Market
Bikes and Motorcycles
Two-Wheeler Market
Bikes and Motorcycles
Folding Bicycle Market
Bikes and Motorcycles
Emission Control Catalyst for Motorcycle Market
Bikes and Motorcycles
Two Wheeler Seats Market
Bikes and Motorcycles
Smart Electric Bikes Market
Bikes and Motorcycles
Motorsports Motorcycle Market
Bikes and Motorcycles
Vietnam Bike-Sharing Market
Bikes and Motorcycles
Bicycle Gear Shifter Market
Bikes and Motorcycles
Bike Taxi Market
Bikes and Motorcycles
Fixed Gear Bikes Market
Bikes and Motorcycles
Bike Fenders Market
Bikes and Motorcycles
Three Wheeled Motorcycle Market
Bikes and Motorcycles
South Africa Two-Wheeler Market
Bikes and Motorcycles
Motorbike Carburetor Market