
 Netherlands E-Bike Market | 2026-2036
Netherlands E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands E-Bike Market Foresight
Aftermarket service revenue is tilting from independent repair shops toward manufacturer-certified networks. Royal Dutch Gazelle leverages its established dealer infrastructure to capture recurring maintenance contracts. VanMoof sustains direct-to-consumer service models that integrate diagnostics through proprietary software platforms.
An e-bike combines a conventional bicycle frame with an electric motor delivering pedal assistance up to 25 km/h under EU type-approval rules, powered by rechargeable battery packs typically mounted on the downtube or rear rack. City E-Bikes dominate unit sales among Dutch commuters seeking weather-protected frame designs and integrated lighting systems. Cargo E-Bikes represent the fastest-expanding category as delivery services replace diesel vans in urban cores. Lithium-Ion battery configurations anchor the technology mix due to superior energy density and declining cell costs.
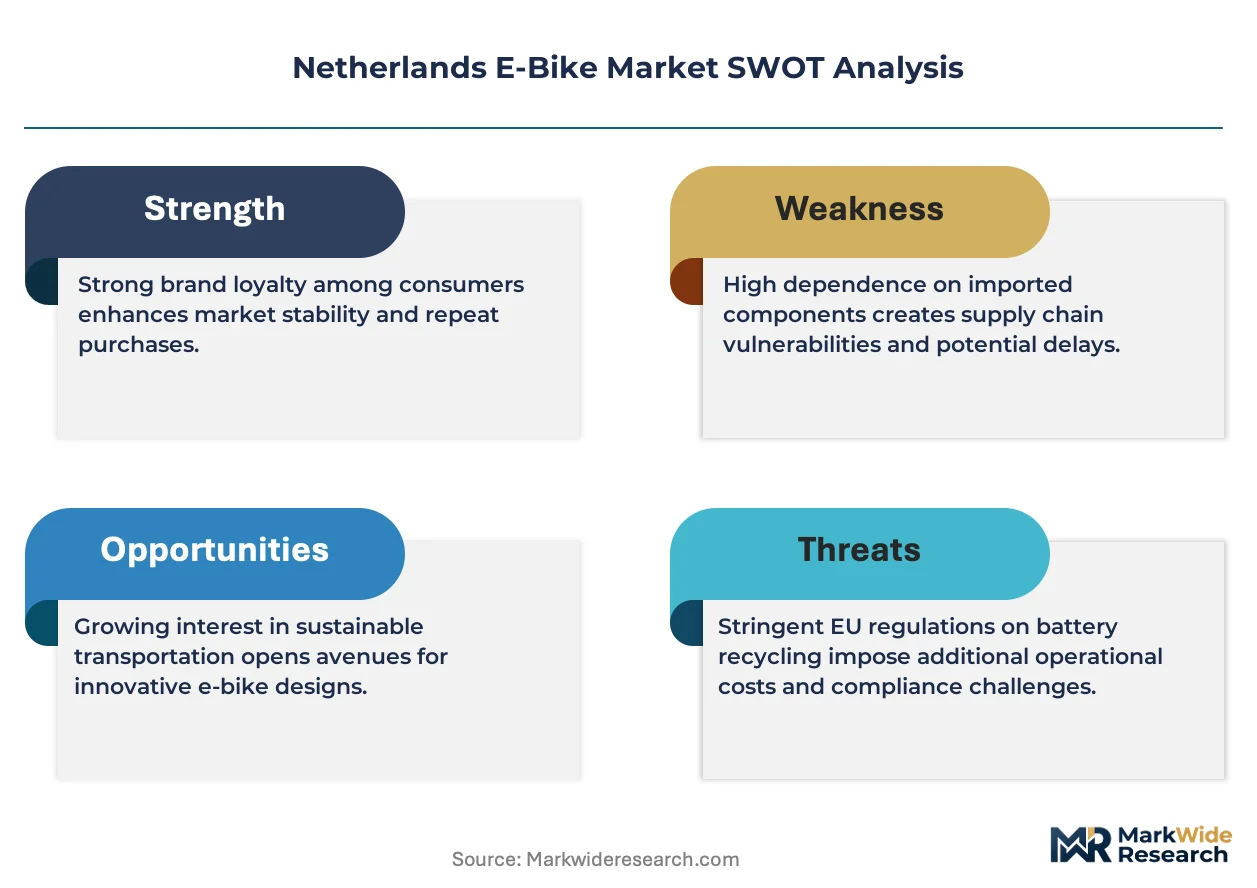
The Dutch Vehicle Authority (RDW) enforces strict type-approval standards that limit motor output and mandate speed governors, while the Ministry of Infrastructure and Water Management oversees cycling infrastructure investments that expand lane networks. Stakeholders must monitor potential adjustments to EU battery passport requirements that could reshape supply chain disclosure obligations for Dutch importers and assemblers.
Market Dynamics
The Netherlands E-Bike Market pivots on infrastructure density cycling infrastructure investments by the Ministry of Infrastructure and Water Management that convert car lanes into protected corridors, accelerating modal shift velocity beyond subsidy effects alone.
Growth Catalysts
- RDW Type-Approval Framework:Strict motor-output limits and speed-governor mandates create product standardization that reduces consumer confusion and accelerates purchase decisions.
- Last-Mile Logistics:Delivery services operating throughout the Randstad metropolitan cluster are replacing diesel van fleets with cargo e-bike configurations to circumvent congestion charges and access restrictions.
- Lithium-Ion Cell Chemistry:Superior energy density and declining cell costs are compressing battery pack pricing, enabling manufacturers to spec larger capacities without frame redesign.
Market Restraints
- Raw Material Concentration:Cathode precursor processing and rare-earth magnet supply chains concentrate in China, exposing Dutch assemblers to export quota volatility and freight cost spikes.
- Technical Ceiling:EU type-approval rules cap pedal assistance at 25 km/h, preventing product differentiation on performance and compressing margin expansion for speed-oriented variants.
- Substitution Pressure:Micromobility alternatives including electric mopeds and shared e-scooters compete for the same urban commuter wallet and parking infrastructure.
Strategic Opportunities
- Battery Passport Compliance:Pending EU battery passport requirements create first-mover advantages for Dutch importers who pre-position supply chain disclosure systems ahead of mandatory phase-in.
- Service Revenue Capture:Diagnostics-integrated software platforms enable subscription-based maintenance models that shift economics from one-time hardware sales toward recurring revenue streams.
- Rotterdam-Utrecht Corridor:Underpenetrated secondary cities within the Randstad present whitespace for cargo e-bike deployment as logistics networks extend beyond Amsterdam saturation.
Industry Challenges
- Diagnostic Technician Shortage:Proprietary software platforms require specialized training that outpaces vocational education output, creating service bottlenecks for direct-to-consumer brands.
- Certification Timeline Compression:RDW type-approval procedures for new motor variants extend development cycles, delaying product launches against faster-moving unregulated markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands E-Bike Market |
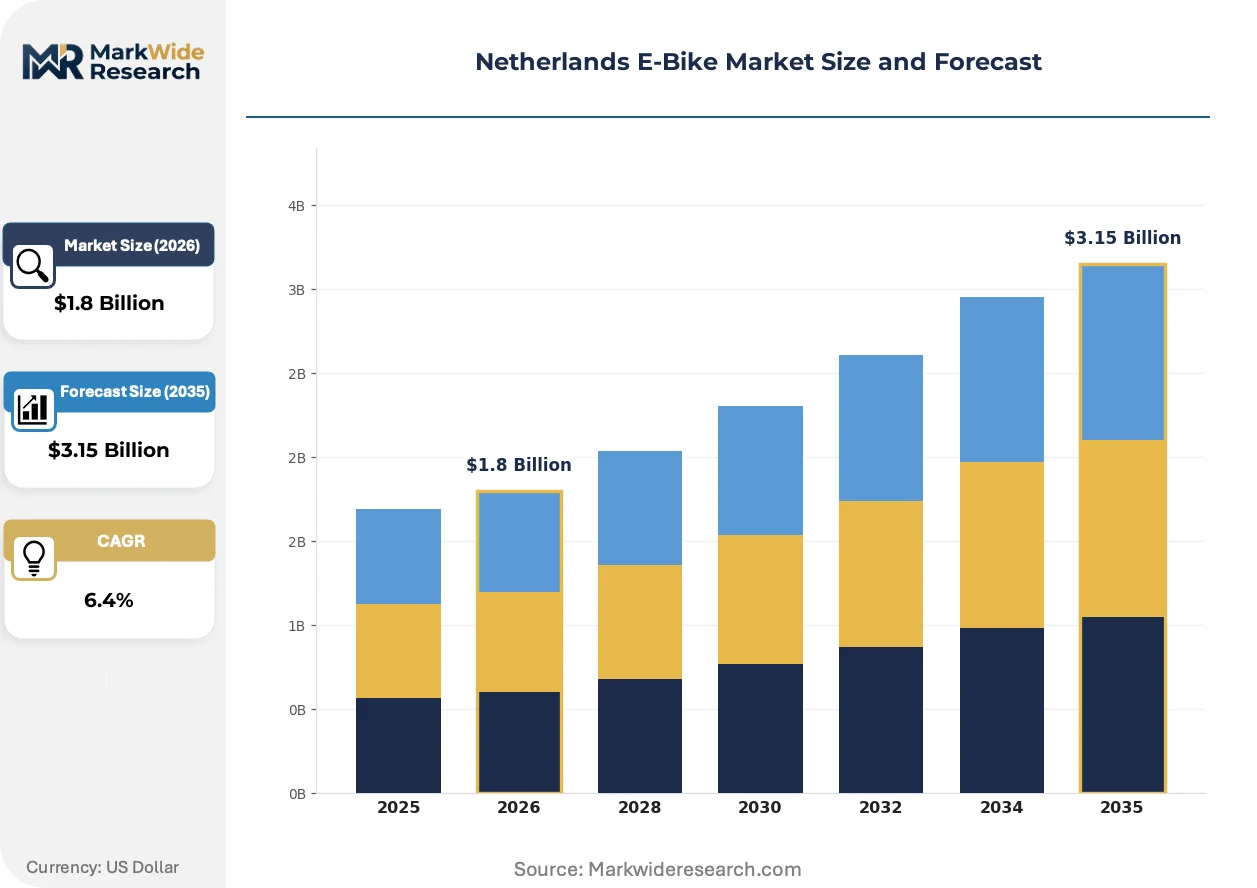
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: City E-Bikes, Mountain E-Bikes, Folding E-Bikes, Cargo E-Bikes Battery Type: Lithium-Ion, Nickel-Metal Hydride, Lead Acid, Lithium Polymer Speed: Standard, High-Speed, Low-Speed, Boost Mode End User: Commuters, Recreational Riders, Delivery Services, Tourists |
| Companies Covered | Trek Bicycle Corporation, VanMoof, Accell Group, Urban Arrow, Swapfiets, Pon Holdings B.V., Royal Dutch Gazelle, Yamaha Motor Co., Ltd., Giant Manufacturing Co. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands E-Bike Market Shifts & Advancements
Software-defined functionality is digitizing the mechanical core of Dutch e-bike manufacturing, compressing the traditional hardware-service boundary and enabling predictive maintenance models that alter ownership economics.
Integrated motor controllers with over-the-air firmware capability are digitizing power delivery mapping and theft-recovery systems. Urban commuters in Amsterdam and Rotterdam are adopting these configurations at replacement-cycle velocity. This capability is digitizing the aftermarket, enabling remote diagnostics that reduce dealer visit frequency and compress warranty claim resolution times.
EU battery passport requirements are reshaping supply chain disclosure obligations for Dutch importers and assemblers. Cell-level traceability mandates will force upstream contracting revisions with Asian cell manufacturers. Cargo e-bike categories with larger battery packs face disproportionate compliance burden and are accelerating supplier qualification programs.
Fleet procurement by logistics operators is consolidating buyer power and unbundling after-sales service from hardware acquisition. Delivery services operating throughout the Randstad are negotiating direct maintenance contracts with manufacturer-certified networks, bypassing traditional retail channels. This concentration is most visible in Rotterdam's port-adjacent distribution zones where diesel van displacement timelines are most aggressive.
Netherlands E-Bike Market Segmentation
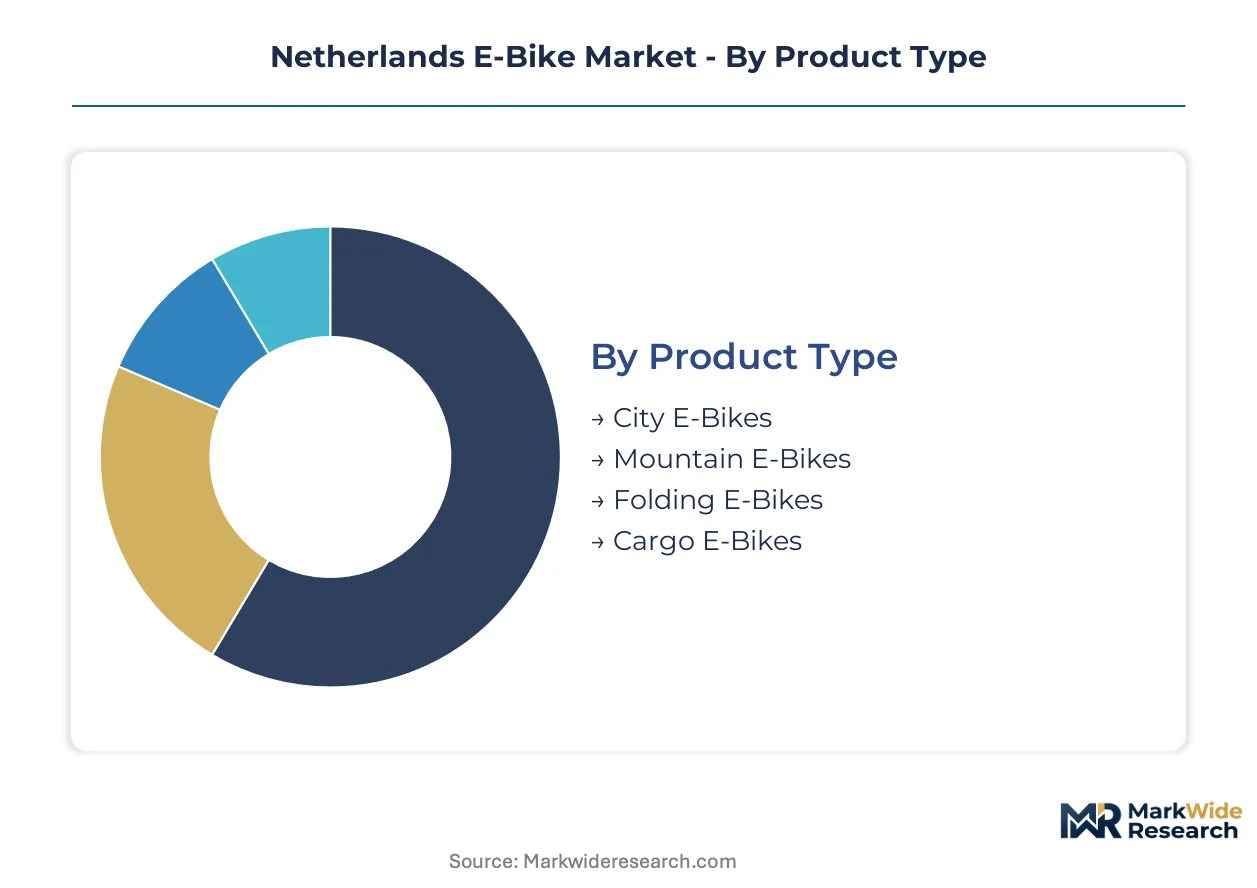
Segmentation in the Dutch e-bike market reveals how infrastructure investment and regulatory frameworks concentrate demand into distinct product configurations. Understanding these partitions clarifies where battery technology investments and service network expansion deliver maximum returns.
Product Type:
Application context determines frame geometry, motor placement, and load-bearing specifications across Dutch cycling infrastructure.
- City E-Bikes:Weather-protected frame designs with integrated lighting and fender systems dominate Amsterdam and Rotterdam commuter corridors. RDW type-approval compliance ensures standardized motor output that simplifies purchase decisions for daily transport users navigating protected lane networks.
- Cargo E-Bikes:Extended wheelbases and reinforced frames accommodate commercial loads up to 250kg, displacing diesel vans in Randstad last-mile logistics. Rotterdam port-adjacent distribution zones drive fleet procurement concentration as congestion charges tighten.
- Mountain E-Bikes:Off-road suspension geometries and torque-optimized mid-drive motors serve recreational trail networks in Limburg and Veluwe regions.
- Folding E-Bikes:Hinge-frame designs with reduced wheel diameters address multimodal commuters combining cycling with NS rail services.
City E-Bikes commands the established base. The steepest expansion runs through Cargo E-Bikes.
Battery Type:
Energy density and cell chemistry tradeoffs shape total cost of ownership across Dutch replacement cycles.
- Lithium-Ion:Cylindrical or prismatic cells delivering 500-700Wh capacities anchor manufacturer specifications. Declining cell costs enable larger pack configurations without frame redesign, supporting the extended range requirements of Randstad metropolitan commuters.
- Lithium Polymer:Pouch-cell architectures permit irregular form factors that integrate into step-through frame designs popular among older Dutch demographics. Higher discharge rates support cargo applications with frequent stop-start patterns.
- Nickel-Metal Hydride:Legacy chemistry persists in budget-tier replacements for early-generation e-bike fleets.
- Lead Acid:Sealed absorbent glass mat configurations occupy minimal aftermarket niches for low-speed utility applications.
Lithium-Ion retains volume leadership. The chemistry gaining share fastest is Lithium Polymer.
Speed:
Motor controller programming and regulatory compliance boundaries segment performance tiers.
- Standard:25 km/h pedal assistance cutoff per EU type-approval rules covers the vast majority of Dutch road-legal sales. RDW enforcement ensures product standardization that reduces consumer confusion and accelerates replacement-cycle velocity.
- High-Speed:45 km/h speed pedelec variants require license plate registration and helmet compliance, constraining adoption to exurban commuters with longer distances.
- Low-Speed:15 km/h governors serve specialized mobility-aid applications and youth-accessible configurations.
- Boost Mode:Temporary override functions for hill starts and loaded cargo acceleration operate within instantaneous power limits rather than sustained speed thresholds.
Standard speed classifications dominate unit economics. The most constrained trajectory belongs to High-Speed.
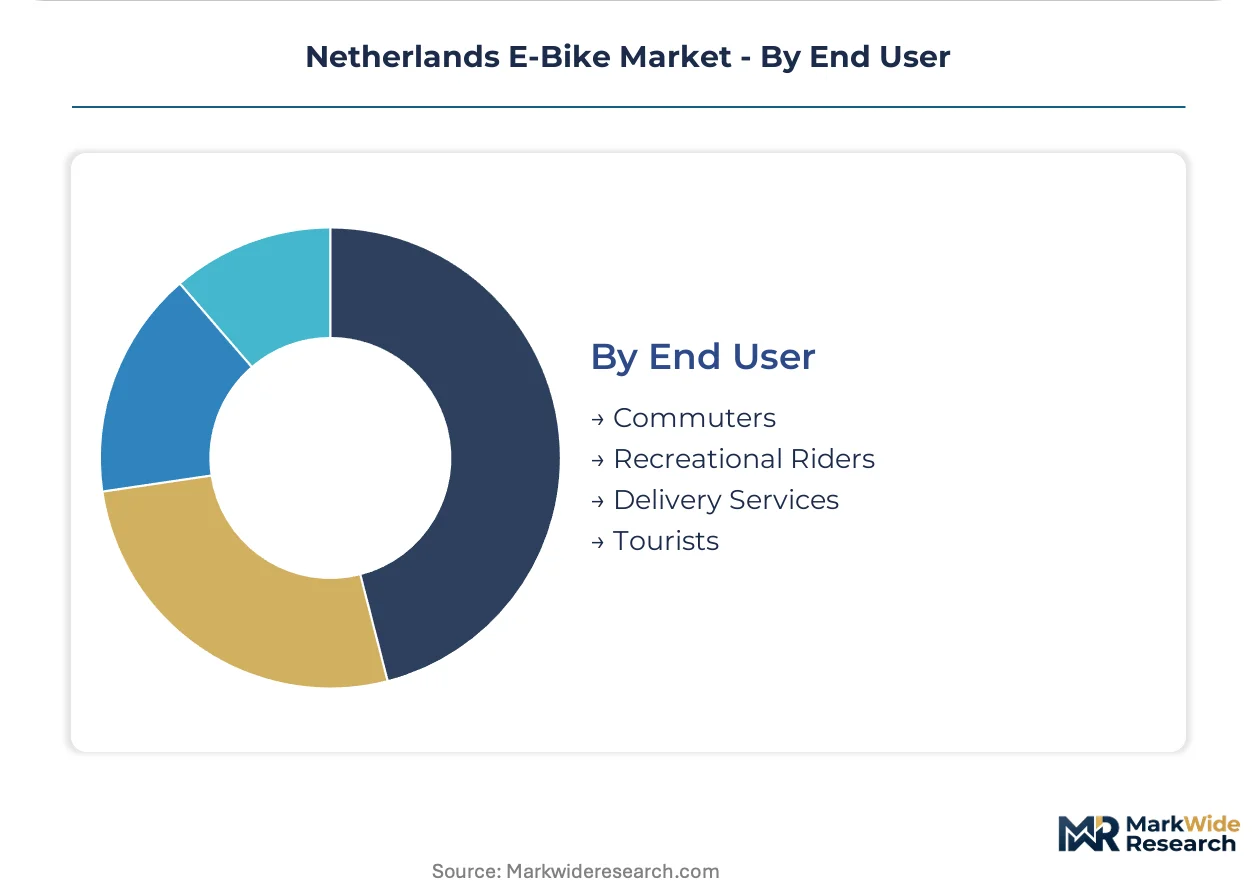
End User:
Customer type determines service interval frequency, warranty claim patterns, and software feature prioritization.
- Commuters:Daily transport users in Amsterdam, Rotterdam, Utrecht, and The Hague generate recurring aftermarket revenue through wear-component replacement and battery degradation management. Predictive maintenance subscriptions concentrate in this cohort.
- Delivery Services:Fleet operators throughout the Randstad negotiate direct maintenance contracts with manufacturer-certified networks, bypassing retail channels and consolidating buyer power.
- Recreational Riders:Weekend and holiday cyclists in coastal and forested regions drive seasonal demand spikes and premium accessory attachment.
- Tourists:Short-term rental users in canal districts and bulb-field routes generate high-utilization fleet turnover with compressed service intervals.
Commuters anchor recurring revenue streams. The most aggressive volume expansion is occurring in Delivery Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component manufacturing clusters in Taiwan and China supply the majority of Dutch e-bike battery cells and motor systems, creating geographic dependency that shapes assembler procurement strategies and inventory positioning across the Randstad.
Randstad Metropolitan Cluster
Amsterdam, Rotterdam, The Hague, and Utrecht generate the densest commuter demand in Europe, with protected cycling corridors converting former car lanes into high-velocity transport arteries. The Ministry of Infrastructure and Water Management directs infrastructure investment toward this corridor, accelerating modal shift beyond subsidy effects. Rotterdam port-adjacent distribution zones drive cargo e-bike fleet procurement as congestion charges tighten diesel van access.
Brabant Province
Eindhoven's high-tech manufacturing ecosystem supplies embedded systems and power electronics to domestic e-bike assemblers. The Brainport development agency coordinates R&D consortia between technical universities and mobility hardware firms. Tilburg and Breda logistics hubs extend cargo e-bike deployment into secondary distribution networks underserved by Amsterdam-centric operators.
Northern Netherlands
Groningen and Friesland maintain the Netherlands' highest per-capita cycling rates, sustaining replacement-cycle demand for city e-bikes among aging rural demographics. Provincial governments administer purchase subsidies that supplement national schemes for low-income households. Leeuwarden's cargo bike manufacturers serve agricultural supply chains and island ferry connections across the Wadden Sea.
Germany
North Rhine-Westphalia's industrial base supplies precision-machined motor housings and forged aluminum frames to Dutch assemblers across the open border. KBA type-approval alignment with RDW standards enables cross-border product certification efficiency. Düsseldorf and Cologne metropolitan cyclists generate parallel demand that Dutch retailers serve through integrated Rhine-Ruhr distribution networks.
Belgium
Flanders' cycling infrastructure investments mirror Dutch corridor development, creating contiguous lowland cycling territory from Zeeland to Brussels. Antwerp's port logistics operators pilot cargo e-bike integration with barge and rail intermodal terminals. Flemish mobility subsidies and RDW-equivalent type-approval frameworks enable Dutch manufacturers to scale across the Benelux without product reconfiguration.
Netherlands E-Bike Market Competitive Landscape
Heritage bicycle manufacturers and direct-to-consumer technology entrants split the market into distinct competitive spheres with divergent channel economics. Royal Dutch Gazelle leverages century-old dealer networks to capture service-contract revenue, while VanMoof sustains vertically integrated retail and diagnostics platforms that bypass traditional distribution. Consolidation pressure operates through fleet procurement concentration among Randstad logistics operators, unbundling aftermarket service from hardware acquisition. Capacity expansion and software-defined functionality represent the dominant competitive vectors, compressing hardware margins while opening subscription revenue streams.
Within the heritage manufacturer tier, Royal Dutch Gazelle and Trek Bicycle Corporation anchor established positions through dealer infrastructure and multi-brand portfolio breadth. VanMoof occupies the direct-to-consumer technology vector with integrated software-hardware platforms that enable remote diagnostics and predictive maintenance subscriptions. Pon Holdings B.V. exemplifies holding-company consolidation, assembling multiple Dutch and Belgian cycling brands under unified procurement and distribution coordination.
| Leading Market Players |
|---|
| Trek Bicycle Corporation |
| VanMoof |
| Accell Group |
| Urban Arrow |
| Swapfiets |
| Pon Holdings B.V. |
| Royal Dutch Gazelle |
| Yamaha Motor Co., Ltd. |
| Giant Manufacturing Co. Ltd. |
| Others |
Supply & Pricing Matrix
Overcapacity in Taiwanese motor-controller foundries is compressing component pricing and enabling Dutch assemblers to negotiate volume discounts without binding long-term commitments. This utilization slack feeds directly into hardware margin expansion while simultaneously pressuring suppliers to extend payment terms to maintain load factors.
Pricing Analysis
After-sales service contracts and predictive maintenance subscriptions now drive lifetime value economics for Dutch e-bike manufacturers. Three-tier pricing structure across premium, standard, and economy levels segments buyers by software integration depth and warranty extension length. Cost compression in economy-tier hardware is intensifying because Chinese cell manufacturers are absorbing freight spikes to defend market share. Fleet procurement managers at Randstad logistics operators exhibit the highest price sensitivity, while individual commuters purchasing through dealer networks show lowest elasticity due to financing bundling.
Supply Chain Analysis
Extended payment terms from Chinese cathode precursor suppliers are becoming standard practice as they compete for Dutch assembler allocation amid regional overcapacity. Taiwan, China, and South Korea anchor the component supply base for lithium-ion cells, rare-earth magnets, and motor controllers. Battery-grade lithium carbonate and neodymium-dysprosium magnet alloys constitute critical input dependencies. Single-source vulnerability concentrates in high-nickel cathode chemistries where qualified supplier pools remain narrow. Distribution runs through manufacturer-certified service networks that are displacing independent repair shops for warranty-covered transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Netherlands e-bike market sits in early-cycle expansion as cargo fleet procurement accelerates diesel van displacement across Randstad logistics networks. Subsidy scheme extensions and infrastructure lane conversions provide durable tailwinds for penetration gains.
For Market Incumbents: Harden dealer network exclusivity clauses to preempt direct-to-consumer brands from capturing service revenue in Rotterdam-Amsterdam corridors. Accelerate backward integration into battery pack assembly to reduce exposure to Chinese cell pricing volatility. Certification investment in RDW type-approval for proprietary motor variants creates switching costs against emerging Asian entrants.
For New Entrants and Emerging Players: Secondary cities in the Northern Netherlands present whitespace for cargo e-bike deployment where logistics networks remain underserved by Amsterdam-centric operators. Target agricultural supply chains in Friesland and Groningen where diesel van access restrictions are tightening. A subscription-first go-to-market angle with predictive maintenance bundles bypasses capital-intensive dealer infrastructure requirements.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-defined e-bike platforms as diagnostics capabilities shift economics toward recurring revenue. Five-to-ten-year viability favors assemblers with captive battery supply agreements and certified service network density. Acquisition targets should demonstrate RDW type-approval track records and fleet procurement relationships. The signal to watch is consolidation velocity among Randstad logistics operators as buyer power concentrates.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Passport Compliance Investment | Pre-positions Dutch importers ahead of mandatory EU supply chain disclosure phase-in. |
| Service Network Certification Expansion | Captures recurring maintenance contracts from fleet operators bypassing retail channels. |
| Software-Defined Vehicle Platform Launch | Enables over-the-air firmware updates and predictive diagnostics for commuter subscriptions. |
| Cargo E-Bike Capacity Buildout | Addresses Rotterdam port-adjacent diesel van displacement demand from logistics operators. |
| Secondary City Distribution Partnership | Extends reach into underpenetrated Brabant and Northern Netherlands corridors. |
Research Methodology
Initial hypotheses were tested against primary input from e-bike fleet procurement managers, RDW type-approval officials, dealer network operators, and lithium-ion cell procurement leads and refined through secondary validation. Customs trade data, Ministry of Infrastructure cycling investment disclosures, RDW registration databases, and EU regulatory filings anchored the quantitative foundation. Bottom-up unit shipment modeling triangulated against top-down value estimates across the analysis window.
Demand-supply-balance framing structured the forecast architecture, with segmentation across product type, battery chemistry, speed classification, and end-user category modeled throughout the projection horizon. CAGRs were derived from replacement-cycle velocity analysis and infrastructure investment correlation. Battery degradation curves and fleet utilization rates informed installed-base revenue projections.
Practitioners should monitor subsidy scheme adjustments, EU battery passport implementation timelines, and raw material export quota shifts for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Denmark E-Bike Market
Bikes and Motorcycles
Vietnam Bike-Sharing Market
Bikes and Motorcycles
Motorbike Riding Gear Market
Bikes and Motorcycles
Bike Taxi Market
Bikes and Motorcycles
Two-Wheeler Services Market
Bikes and Motorcycles
Europe Motorcycle Market
Bikes and Motorcycles
Europe E Bike Market
Bikes and Motorcycles
Two-Wheeler Motorcycle Market
Bikes and Motorcycles
Flying Bikes Market
Bikes and Motorcycles
300cc Motorcycle Market
Bikes and Motorcycles
Motorcycle Headlight Market
Bikes and Motorcycles
Motorcycle Fairings Market
Bikes and Motorcycles
South America Two-Wheeler Market
Bikes and Motorcycles
Europe Motorcycle Airbag Market
Bikes and Motorcycles
Motorcycle Accessories Market
Bikes and Motorcycles
Two Wheeler Suspension System Market