

Bicycle Brake Lever Market Size, Share, and Industry Trends Forecast 2026-2036
Bicycle Brake Lever Market Insights
Modular brake-and-shifter integration is consolidating buyer choice around unified cockpit systems rather than standalone levers. Shimano leverages its Di2 electronic ecosystem to anchor premium road and mountain bike specifications. SRAM competes through wireless AXS platforms that eliminate hydraulic hose routing complexity. Tektro Technology Corporation sustains volume leadership in OEM supply contracts for mid-range hybrid and commuter bicycles across Asian manufacturing hubs.
A bicycle brake lever translates rider finger force into caliper clamping pressure through mechanical cable pull or hydraulic fluid displacement, typically requiring 20-30mm lever blade travel and 80-120N maximum operating force to achieve controlled deceleration. Its primary commercial purpose is enabling safe speed modulation across diverse terrain and traffic conditions while meeting ergonomic and fatigue-resistance standards. Hydraulic levers dominate premium mountain and road segments where heat dissipation and modulation precision command margin premiums, while mechanical levers retain cost-sensitive positions in entry-level and developing-market bicycles. Carbon fiber lever blades concentrate in professional cyclist and high-end custom build channels where gram reduction justifies material cost multiples over aluminum alloy.
The EU Machinery Directive and ISO 4210 frame safety testing requirements compel manufacturers to validate lever fatigue resistance under standardized protocols, while the US Consumer Product Safety Commission monitors recall thresholds for mechanical failure incidents. Germany's KBA-equivalent national safety regulator and Japan's JIS standards body further shape product certification requirements for export-market access. Stakeholders must monitor evolving e-bike motor cutoff integration mandates and regional repairability regulations that could redefine lever electronics architecture and aftermarket replacement protocols.
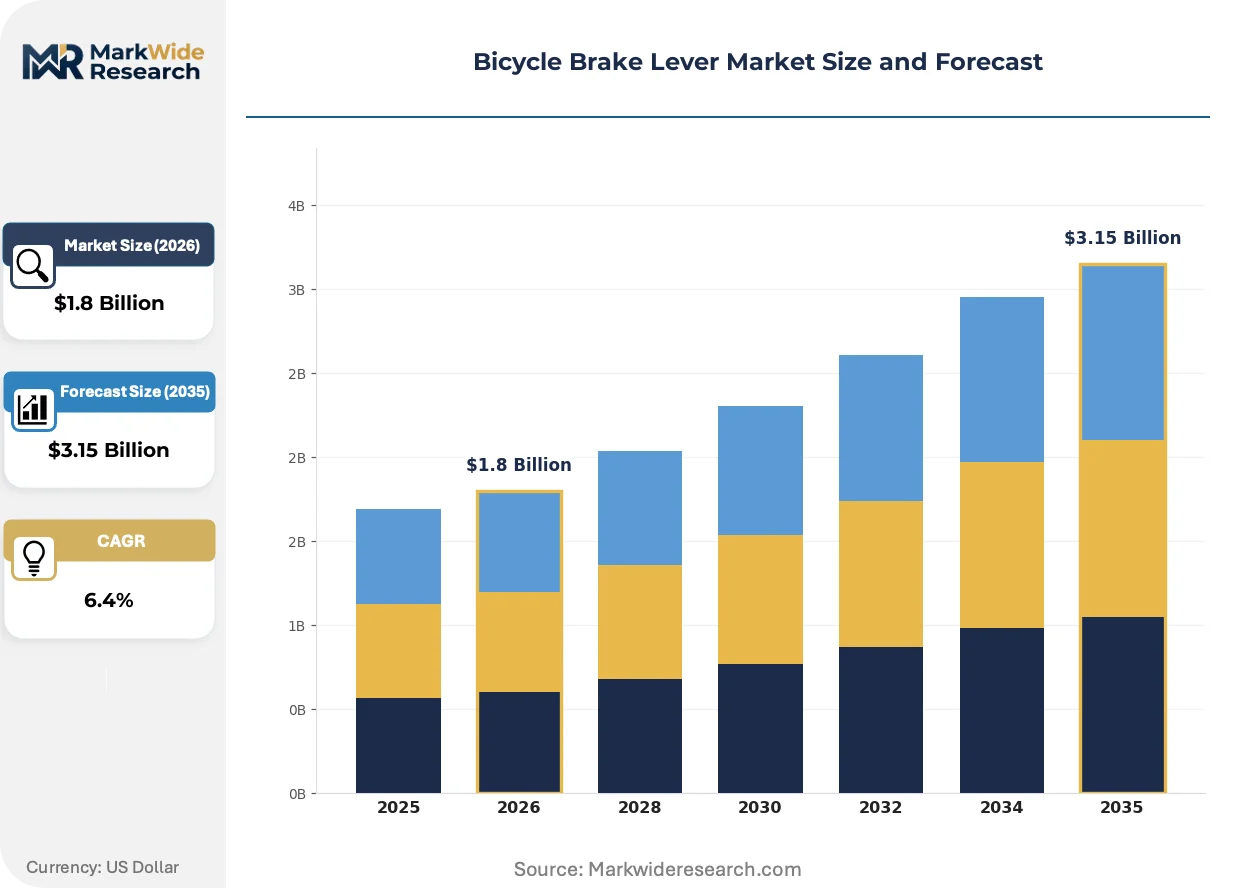
Market Dynamics
E-bike motor cutoff integration mandates are compressing development cycles and forcing lever architecture redesigns across OEM supply chains. Hydraulic system suppliers must now embed position sensors and CAN-bus interfaces that communicate with Bosch, Brose, and Shimano motor controllers.
Growth Catalysts
- EU Machinery Directive compliance:Mandatory fatigue-testing protocols under ISO 4210 are accelerating replacement demand as older lever designs fail recertification.
- Urban cycling infrastructure:Germany's federal transport investment programs are expanding protected lane networks and elevating bicycle component procurement volumes.
- Carbon fiber blade adoption:Professional racing teams and custom builders are specifying gram-reduced lever materials that command manufacturing premiums.
Market Restraints
- Aluminum alloy price volatility:Lever housing and blade material costs fluctuate with LME pricing, compressing margin buffers for mid-tier suppliers.
- Taiwanese supply concentration:Precision CNC machining capacity for hydraulic master cylinder bodies clusters in Taichung, creating single-source vulnerability.
- Mechanical cable redundancy:Entry-level bicycles retain pull-cable systems that limit hydraulic upgrade attach rates in price-sensitive segments.
Strategic Opportunities
- Indian e-mobility expansion:FAME-II subsidy extensions and state-level EV policies are stimulating e-bike assembly growth that requires integrated brake-motor systems.
- Right-to-repair mandates:EU and US state-level repairability regulations are opening aftermarket lever electronics replacement protocols.
- Wireless shifting convergence:Bluetooth-enabled brake levers that synchronize with electronic drivetrains are creating unified cockpit upgrade cycles.
Industry Challenges
- Hydraulic fluid compatibility certification:Mineral oil and DOT formulations require distinct seal materials, complicating inventory management.
- E-bike sensor calibration:Motor cutoff timing tolerances demand precision assembly skills that strain technician training pipelines.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bicycle Brake Lever Market Trends and Innovations
Brake lever architecture is fragmenting into specialized configurations that serve distinct riding disciplines and regulatory environments. Component suppliers must now engineer parallel product lines rather than universal platforms.
Integrated brake-and-shifter units are consolidating cockpit real estate and simplifying cable routing for frame manufacturers. Road and gravel bike OEMs are specifying these unified systems at accelerating rates. This convergence is modularizing supplier relationships as frame designers specify complete cockpit ecosystems rather than discrete components.
REACH substance restrictions and EU battery regulations are forcing material substitutions in lever electronics and hydraulic fluids. Seal manufacturers are reformulating compounds to eliminate restricted phthalates and heavy-metal catalysts. E-bike lever suppliers serving European export markets are absorbing extended compliance timelines and third-party testing costs.
Direct-to-consumer bicycle brands are compressing traditional distributor tiers and demanding configurable lever specifications at reduced minimum order quantities. Canyon, YT Industries, and comparable digital-native sellers are forcing component suppliers to unbundle legacy volume commitments. This channel disintermediation is most pronounced in Germany and the Netherlands where online bicycle sales penetration exceeds conventional retail in premium segments.
Bicycle Brake Lever Market Segmentation
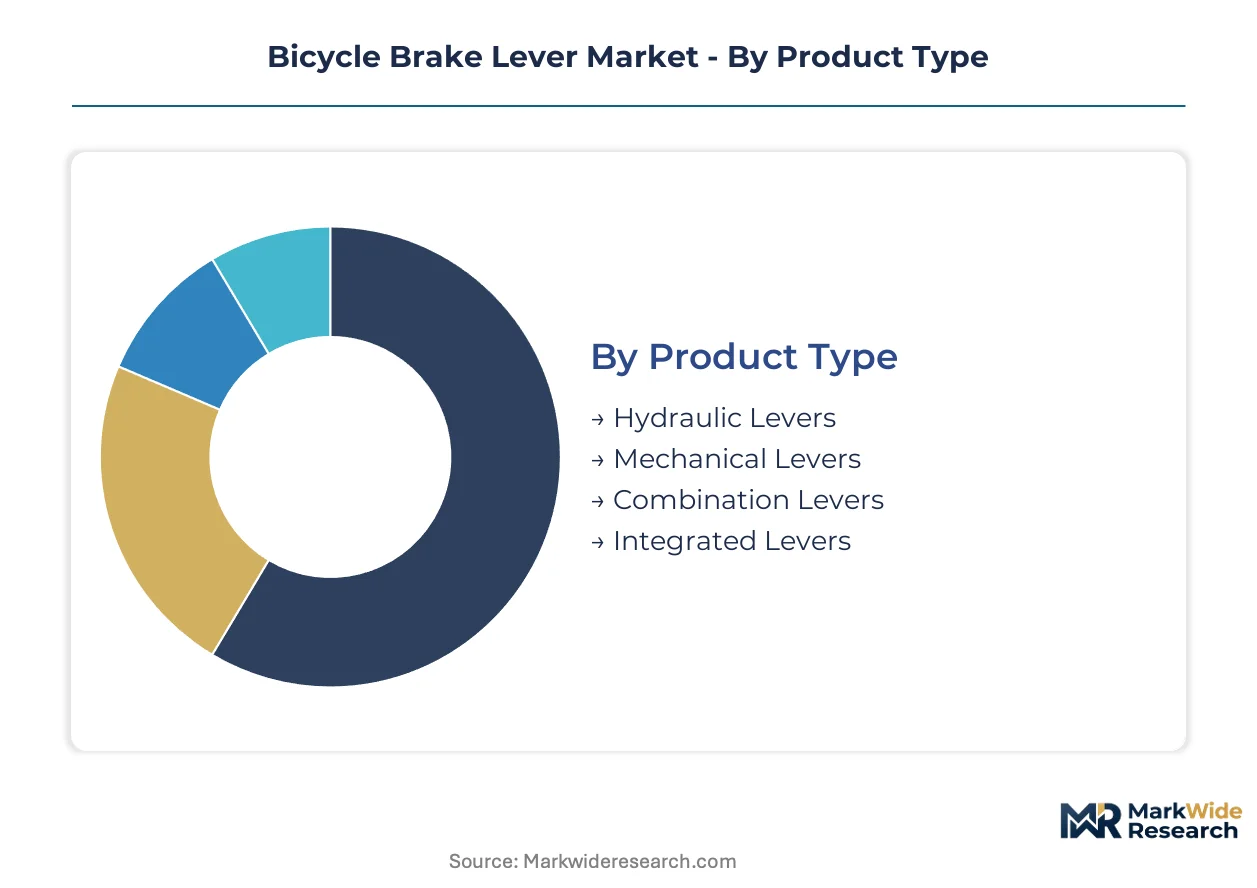
Brake lever segmentation reflects divergent engineering requirements across riding disciplines and price tiers. Component suppliers must maintain parallel production lines serving hydraulic precision systems alongside cost-optimized mechanical alternatives. Material selection and integration complexity further stratify procurement patterns among OEM and aftermarket channels.
Product Type:
Hydraulic master cylinder manufacturing concentrates in Taiwanese CNC machining clusters, creating supply bottlenecks for premium system assembly.
- Hydraulic Levers:These systems displace mineral oil or DOT fluid through sealed master cylinders to achieve precise modulation and superior heat dissipation. Demand concentrates in Germany's premium mountain bike OEM sector, where enduro and downhill specifications require fade-resistant performance under sustained braking loads.
- Mechanical Levers:Cable-pull architectures translate finger force through Bowden cables to actuate rim or disc calipers. India's expanding FAME-II-subsidized e-bike assembly lines specify these systems for cost-sensitive urban mobility platforms where hydraulic maintenance infrastructure remains limited.
- Combination Levers:Hybrid designs accommodate both cable and hydraulic actuation within unified housings for model-year flexibility.
- Integrated Levers:Combined brake-and-shifter units consolidate cockpit controls for simplified cable routing.
Today's leader: Hydraulic Levers. Tomorrow's challenger: Integrated Levers.
Material:
Raw material cost tiers create distinct margin architectures across supplier portfolios.
- Aluminum Alloy:Extruded and forged 6061-T6 or 7075-T6 alloys deliver optimal strength-to-weight ratios for mid-tier and OEM-volume production. LME price volatility directly compresses margin buffers for housing and blade manufacturers serving Asian assembly hubs.
- Carbon Fiber:Pre-preg layup or forged composite lever blades achieve 30-40% mass reduction versus aluminum equivalents. Professional racing teams and German custom builders specify these materials where gram reduction justifies manufacturing premiums.
- Steel:Stamped housings and pivot hardware serve entry-level replacement markets.
- Composite Plastic:Glass-reinforced nylon components reduce unit costs for children's bicycle and rental fleet specifications.
- Titanium:Grade 5 alloy hardware targets ultra-premium custom builds with corrosion-resistant pivots and mounting bolts.
Aluminum Alloy commands current volume leadership. Carbon Fiber is gaining share fastest among performance-tier suppliers.
Application:
Frame geometry and braking duty cycles dictate divergent lever specification requirements across bicycle categories.
- Mountain Bicycles:Long-travel suspension designs and steep descent profiles demand high-leverage ratios and reservoir-equipped master cylinders for thermal management. German enduro and trail bike OEMs specify four-piston hydraulic systems with tool-free reach adjustment.
- Road Bicycles:Drop-bar ergonomics require compact hood-integrated levers with minimal aerodynamic penalty. Integrated electronic shifting compatibility now dominates premium road specifications.
- BMX Bikes:U-brake and linear-pull cable systems prevail in dirt and park disciplines.
- Touring Bicycles:Mechanical cable redundancy appeals to long-distance riders prioritizing field serviceability.
- Folding Bicycles:Compact handlebar clearances necessitate shortened lever blades and reduced sweep angles.
Mountain Bicycles anchor current procurement volumes. Road Bicycles present the steepest expansion trajectory through electronic integration mandates.
End User:
Channel structure and technical sophistication separate replacement demand from factory-fit specification authority.
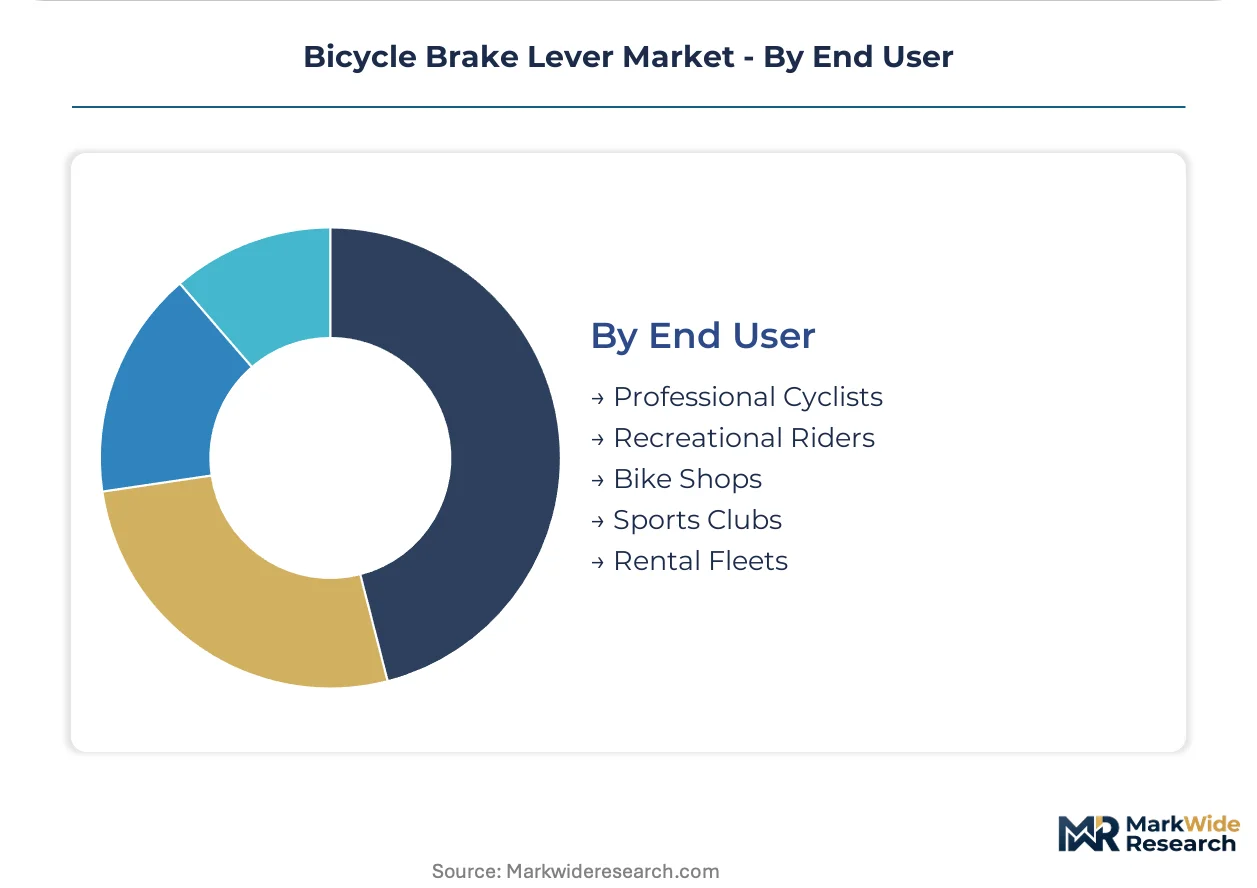
- Professional Cyclists:UCI-registered teams and elite amateur racers demand gram-optimized components with sponsored-equipment homologation. German WorldTour and ProTeam programs leverage specification influence to secure early-access prototype systems.
- Recreational Riders:Weekend enthusiasts and fitness cyclists drive aftermarket upgrade demand through direct-to-consumer channels. Canyon and YT Industries' digital-native sales models compress traditional distributor tiers for this segment.
- Bike Shops:Independent retailers and service centers stock replacement levers for crash damage and wear-item turnover.
- Sports Clubs:Collegiate and amateur racing programs procure volume-discounted team equipment.
- Rental Fleets:Municipal bike-share and tourism operators prioritize durability and vandal resistance over performance metrics.
Professional Cyclists set specification standards. Recreational Riders represent the deepest volume pool for aftermarket conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial cycling heritage traces to early 20th-century component manufacturing in the Ruhr Valley, establishing engineering protocols that persist in contemporary brake lever certification standards.
Germany
Federal transport investment programs and premium bicycle OEM clusters in Baden-Württemberg sustain above-average component procurement volumes. The KBA-equivalent national safety regulator enforces ISO 4210 fatigue-testing protocols that compel lever redesign cycles. Stuttgart and Friedrichshafen host engineering centers where hydraulic system suppliers validate motor cutoff integration with Bosch and Brose controllers.
United States
Direct-to-consumer digital-native brands and mountain bike recreation infrastructure drive aftermarket upgrade demand. The Consumer Product Safety Commission monitors recall thresholds for mechanical failure incidents, shaping liability exposure calculations. Colorado's Front Range and California's Bay Area concentrate product development talent for electronic shifting convergence.
Taiwan
Precision CNC machining capacity for hydraulic master cylinder bodies clusters in Taichung, creating single-source vulnerability for global supply chains. The Bureau of Standards, Metrology and Inspection aligns domestic certification with ISO frameworks for export-market access. Kaohsiung manufacturing hubs supply mid-range OEM contracts for Asian and North American assembly operations.
India
FAME-II subsidy extensions and state-level EV policies stimulate e-bike assembly growth requiring integrated brake-motor systems. The Bureau of Indian Standards develops domestic safety protocols parallel to European directives. Tamil Nadu and Maharashtra production corridors attract component suppliers serving cost-sensitive urban mobility platforms.
Japan
Professional racing team specifications and custom builder channels sustain demand for gram-reduced carbon fiber lever materials. The Japanese Industrial Standards body shapes product certification requirements for export-market access. Osaka and Nagoya industrial zones maintain captive supply relationships with domestic bicycle OEMs.
Bicycle Brake Lever Market Competitive Landscape
Premium-margin players sit above commodity-margin players across electronic integration and material specification tiers. The vendor base stratifies into three distinct layers: ecosystem-anchored conglomerates controlling proprietary communication protocols, specialized hydraulic system houses serving racing and gravity disciplines, and volume-oriented fabricators capturing mid-range OEM contracts. Consolidation pressures concentrate around electronic shifting convergence and motor cutoff mandate compliance. Capacity expansion in Taiwanese CNC clusters and strategic partnerships for sensor calibration technology represent dominant competitive vectors.
Within the ecosystem-anchored tier, Shimano, SRAM, and Tektro Technology Corporation exemplify divergent strategic positioning. Shimano represents the vertically integrated conglomerate archetype with captive electronic protocol control. SRAM occupies the wireless disruption position, eliminating traditional routing complexity through proprietary communication standards. Tektro Technology Corporation anchors the volume-fabricator archetype, sustaining OEM supply relationships through scale economics rather than premium specification capture.
| Leading Market Players |
|---|
| Shimano |
| SRAM |
| Tektro Technology Corporation |
| Magura |
| Campagnolo |
| Hayes Performance Systems |
| TRP Cycling Components |
| FSA |
| Hope Technology |
| Others |
Pricing and Supply Chain Analysis
Integrated brake-motor cutoff electronics are simultaneously elevating R&D amortization costs and concentrating procurement leverage among e-bike OEMs with Bosch, Brose, and Shimano motor controller certification requirements. This dual pressure is reshaping margin architectures across hydraulic system suppliers and mechanical lever fabricators alike.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Di2-compatible electronic levers from mid-range hydraulic systems and entry-level cable-pull alternatives. Price differentiation hinges on ISO 4210 fatigue-testing certification tier and volume scale commitments from frame manufacturers. Pricing pressure stems from aluminum alloy LME volatility compressing mid-tier supplier buffers. OEM procurement teams at Asian assembly hubs exhibit highest price sensitivity, while German custom builders show lowest elasticity for gram-reduced carbon fiber specifications.
Supply Chain Analysis
Refurbishment flows for crash-damaged levers remain underdeveloped, creating aftermarket voids that independent bike shops fill with new-unit replacements. Precision CNC machining capacity draws from Taiwan, Germany, and Japan for hydraulic master cylinder bodies. Raw material dependencies rest on 6061-T6 aluminum extrusions, carbon fiber pre-preg, and mineral oil seal compounds. Single-source vulnerability clusters in Taichung machining capacity. Distribution runs through OEM direct contracts, aftermarket distributors, and direct-to-consumer digital channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bicycle brake lever market functions as a stable compounder, with e-bike motor cutoff mandates embedding recurring redesign cycles that sustain engineering service revenues across supplier tiers.
For Market Incumbents: Extend proprietary electronic protocol control through deeper integration with Bosch and Shimano motor controller ecosystems. Fortify Taichung CNC capacity relationships through equity partnerships or long-term offtake guarantees to defend against single-source disruption. Prioritize REACH-compliant seal compound R&D to preempt regulatory displacement. For New Entrants and Emerging Players: Direct-to-consumer digital-native channels offer the most penetrable route for wireless lever systems that bypass incumbent hydraulic hose routing complexity. Target Indian FAME-II-subsidized e-bike assemblers with cost-optimized integrated brake-motor cutoff designs. Pursue white-label partnerships with Canyon-class digital sellers seeking configurable cockpit specifications at reduced minimum order quantities. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized hydraulic system houses serving racing and gravity disciplines, where technical differentiation sustains margin premiums despite smaller revenue bases. Long-term viability centers on sensor calibration capability and CAN-bus interface IP. Monitor EU right-to-repair mandate implementation timelines as inflection signals for aftermarket electronics replacement protocol demand.| Strategic Initiative | Industry Significance |
|---|---|
| E-Bike Motor Cutoff Certification | Validates lever electronics compatibility with Bosch, Brose, and Shimano controllers for OEM fitment. |
| Taiwan CNC Capacity Partnership | Secures precision master cylinder machining throughput amid single-source supply concentration. |
| REACH-Compliant Seal Reformulation | Eliminates restricted phthalates and heavy-metal catalysts for European export market access. |
| Wireless Shifting Convergence | Enables Bluetooth-enabled brake levers that synchronize with electronic drivetrain ecosystems. |
| Direct-to-Consumer Channel Entry | Captures aftermarket upgrade demand from Canyon and YT Industries digital-native customer bases. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with brake system engineering directors, OEM procurement managers, independent bike shop owners, and regulatory compliance officers with secondary validation against ISO 4210 certification databases, EU Machinery Directive implementation records, and customs trade flow data. Bottom-up supplier revenue aggregation and top-down OEM fitment rate estimates were triangulated for convergence.
Comparable-period anchoring linked projection assumptions to historical e-bike penetration curves and hydraulic lever adoption trajectories across the analysis window. The forecast framework modeled product type, material specification, application discipline, and end-user channel dimensions. CAGRs were derived from segment-level growth rate reconciliation against macro bicycle production forecasts and motor cutoff mandate implementation schedules.
The model assumes a particular technology adoption path; alternative pathways for wireless electronic shifting convergence would alter the outlook. Forecasts reflect assumptions about EU right-to-repair enforcement intensity and Taiwanese supply chain stability. Practitioners should monitor FAME-II subsidy renewal decisions and aluminum LME price volatility for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.