
 Fixed Gear Bikes Market | 2026-2036
Fixed Gear Bikes Market Size, Share, and Industry Trends Forecast 2026-2036
Fixed Gear Bikes Market Insights
Market Context
Aftermarket component customization is fragmenting across dedicated fixie workshops, direct-to-consumer online retailers, and boutique frame builders. State Bicycle Company leverages vertical integration to control wheelset and crankset sourcing. FabricBike specializes in entry-level steel frames for European urban commuters. Cannondale anchors premium positioning through aluminum track frames with race-proven geometry.
Technical Definition and Segment Structure
Fixed gear bicycles employ a drivetrain with no freewheel mechanism, meaning crank rotation directly corresponds to rear wheel motion at a fixed gear ratio typically ranging from 2.3:1 to 3.0:1. These machines demand continuous pedal engagement, making them favored for cadence training, track racing, and low-maintenance urban commuting where mechanical simplicity reduces failure points. Aluminum frames dominate volume production due to favorable stiffness-to-weight ratios and weldability at scale, while carbon fiber commands the racing tier where gram reduction justifies cost premiums. Urban usage applications generate the broadest addressable base as congestion-charged city centers incentivize minimal-maintenance personal transit, whereas track racing sustains elite-tier pricing power through Olympic and World Championship visibility.
Regulatory Framework and Outlook
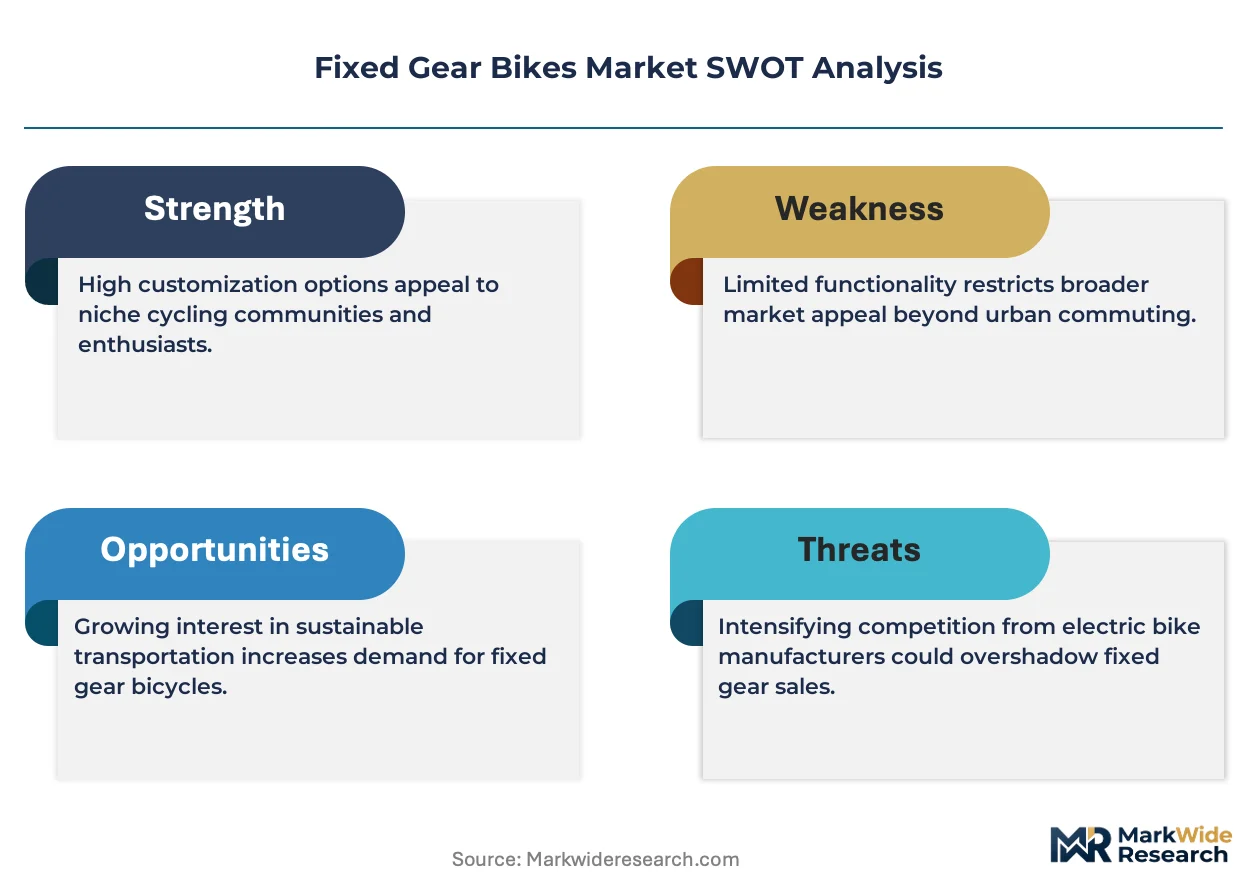
The Consumer Product Safety Commission mandates bicycle braking performance standards that fixed-gear models must satisfy through front calipers or coaster-compatible configurations. Japan's Ministry of Economy, Trade and Industry enforces JIS frame integrity protocols that export-oriented manufacturers target for quality signaling. European Union CE marking under the Machinery Directive governs component interoperability and safety documentation for cross-border distribution. Stakeholders must monitor evolving e-bike subsidy eligibility rules that could either cannibalize or complement fixed-gear demand in municipal mobility programs.
Market Dynamics
Chromoly steel and 4130 alloy tubing innovations are compressing frame weight differentials between entry-level and premium fixed-gear segments, forcing aluminum incumbents to defend positioning through geometry refinement rather than material exclusivity.
Growth Catalysts
- Last-mile delivery fleet conversion:Urban courier services in Japan, Italy, and the United States are standardizing fixed-gear configurations for mechanical reliability and theft deterrence in dense metropolitan zones.
- CE marking harmonization:European Union Machinery Directive alignment is reducing cross-border compliance costs for component manufacturers serving multiple member-state markets.
- Track racing visibility:Olympic and World Championship cycling disciplines sustain elite-tier pricing power and aspirational demand transfer into urban commuter segments.
Market Restraints
- Input cost volatility:Chromoly steel tubing prices fluctuate with scrap metal commodity cycles, squeezing margin buffers for mid-tier frame builders.
- Substitution threat:Municipal e-bike subsidy programs in European and Japanese cities divert commuter budgets toward electrified alternatives with lower physical exertion requirements.
- Regulatory friction:Consumer Product Safety Commission braking performance mandates add front caliper costs to fixed-gear builds that track purists consider unnecessary.
Strategic Opportunities
- Direct-to-consumer channel expansion:Online retailers bypass traditional bike shop markups to capture price-sensitive urban commuters in underserved secondary Italian and Japanese cities.
- Boutique frame builder collaboration:Limited-run collaborations between established component brands and artisan builders create scarcity premiums in collector markets.
- Workshop education programming:Fixie-specific maintenance clinics build recurring revenue streams and brand loyalty among mechanically inclined urban riders.
Industry Challenges
- Skilled welder scarcity:Chromoly and 4130 alloy frame production requires TIG welding expertise that vocational programs have deprioritized in favor of automated manufacturing tracks.
- Component interoperability standardization:Proprietary bottom bracket and hub dimensions fragment aftermarket upgrade paths, frustrating consumer expectations of modular customization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fixed Gear Bikes Market |
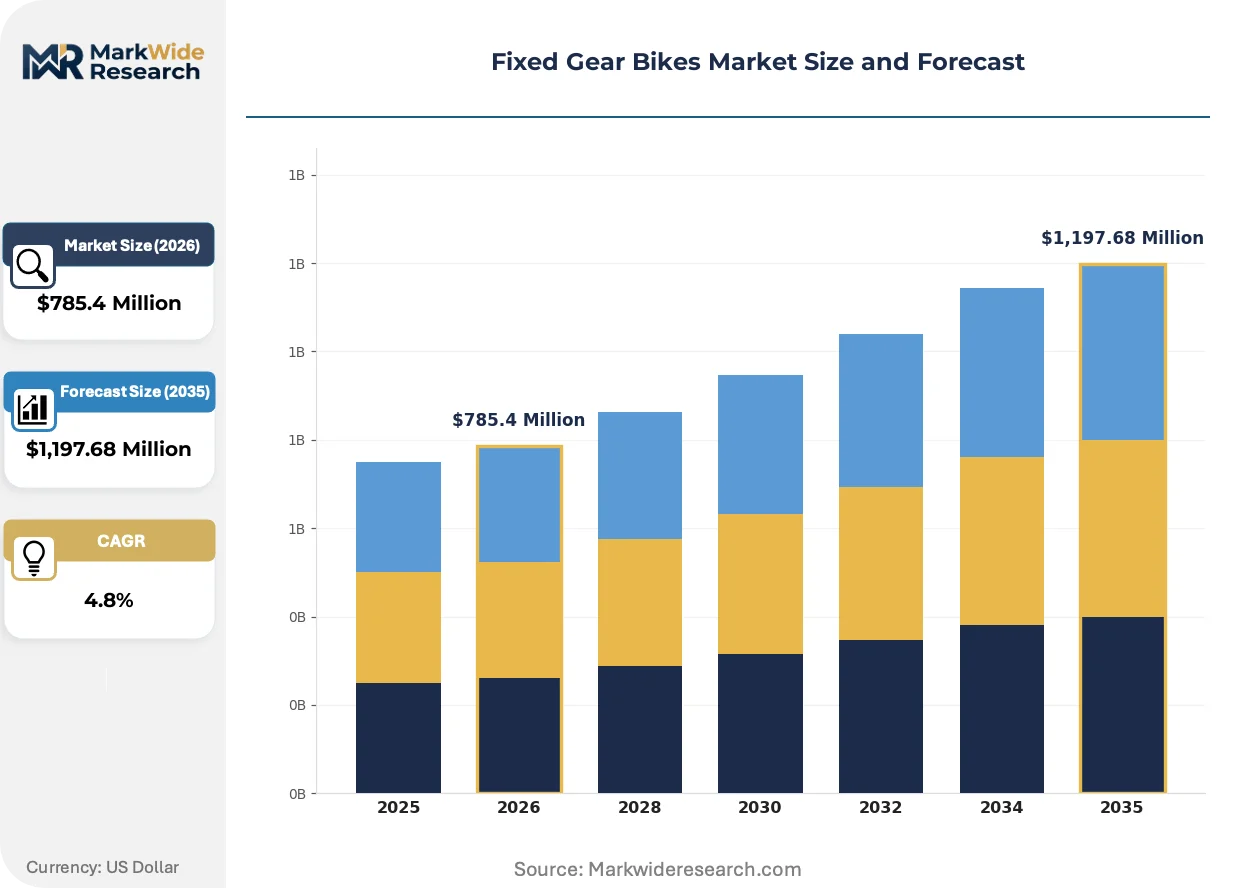
| Market Size in 2026 | $785.4 Million |
| Market Size in 2035 | $1,197.68 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Bike Type: Track, Urban, Single-Speed, Freestyle Material: Aluminum, Steel, Carbon Fiber, Titanium Age Group: Adults, Teens, Kids, Seniors Usage: Commuting, Racing, Leisure, Fitness |
| Companies Covered | Cannondale, Ribble, Specialized, State Bicycle Company, FabricBike, Giant, Condor, Brooklyn Bicycle Company, Trek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fixed Gear Bikes Market Trends and Innovations
Fixed-gear product development is bifurcating between hyper-specialized track equipment and urban utility configurations, with material science and regulatory compliance driving divergence in engineering priorities.
Tubing manufacturers are deploying butted chromoly and heat-treated 4130 alloys to achieve aluminum-comparable weights without ride-quality penalties. Boutique builders in Japan and Italy are adopting these specifications for premium urban frames. The shift is rendering obsolete the traditional aluminum-versus-steel dichotomy that previously segmented price tiers by material alone.
European Union Machinery Directive enforcement is tightening documentation requirements for component interoperability and safety traceability. Manufacturers targeting cross-border distribution must now maintain technical files beyond previous self-certification norms. Track racing equipment faces the steepest compliance burden due to minimal safety redundancy in stripped-down configurations.
Urban commuters are consolidating purchases through dedicated fixie workshops that bundle frame, wheelset, and drivetrain selection with fit services. This channel shift compresses the traditional bike shop intermediary layer that stocked generalized inventory. The pattern is most pronounced in Japanese and Italian metropolitan cores where fixed-gear cycling culture intersects with established fabrication expertise.
Fixed Gear Bikes Market Segmentation
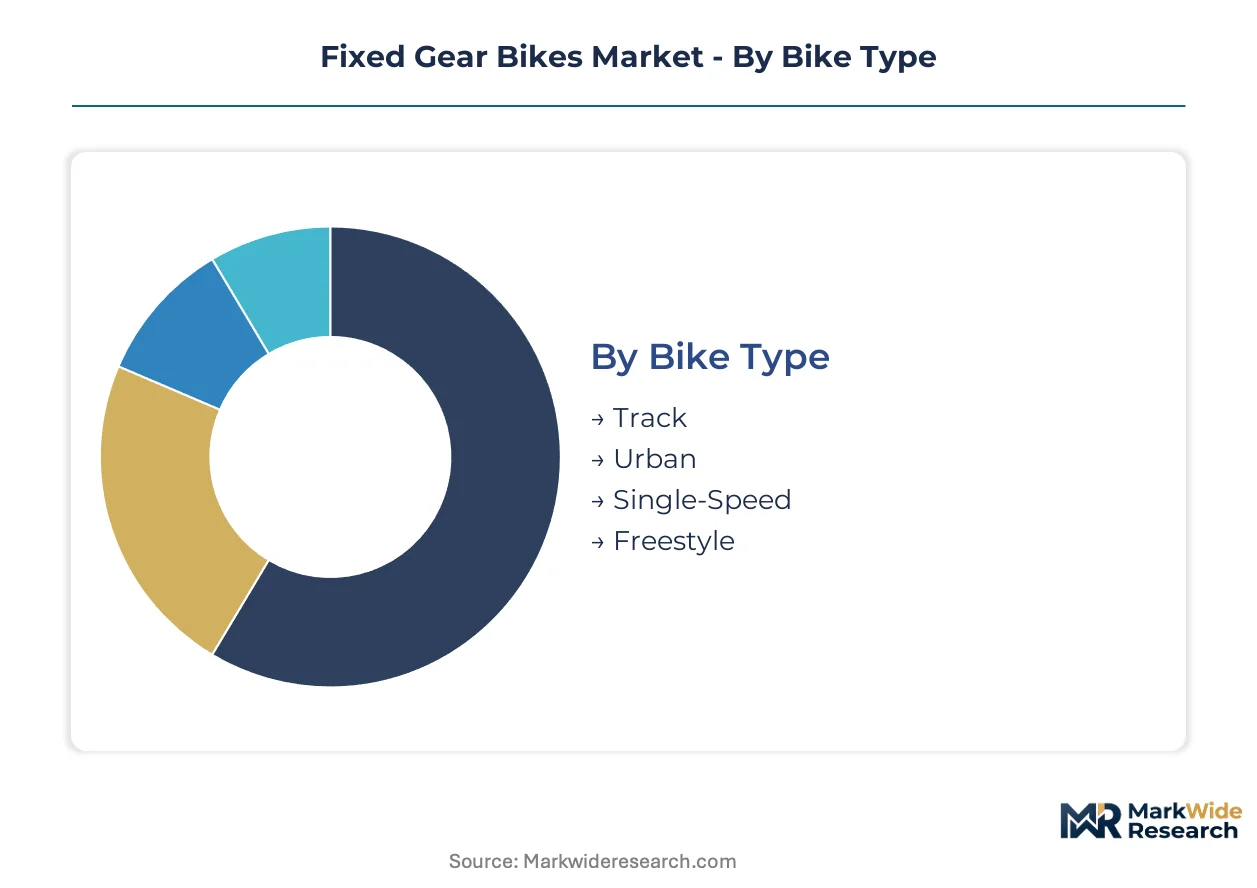
Fixed-gear bicycle segmentation reflects divergent engineering priorities between closed-circuit track performance and open-road urban utility. Material selection and frame geometry must align with distinct biomechanical demands across racing disciplines, commuter durability requirements, and recreational accessibility thresholds.
Bike Type:
The use-case spectrum spans Olympic velodrome specifications through street-level freestyle configurations, each demanding incompatible frame geometries and component tolerances.
- Track:Ultra-stiff aluminum or carbon fiber frames with aggressive 75-degree head tube angles maximize power transfer on banked wooden surfaces. Olympic and World Championship visibility sustains elite-tier pricing power in Japan, Italy, and the United States where velodrome infrastructure concentrates.
- Urban:Chromoly steel and 4130 alloy tubing dominate for impact resistance against curbs and potholes in dense metropolitan zones. Last-mile delivery fleets in Tokyo, Milan, and New York City standardize these configurations for mechanical reliability and theft deterrence.
- Single-Speed:Freewheel-compatible frames with flip-flop rear hubs accommodate riders transitioning between fixed and coasting modes. Entry-level positioning attracts price-sensitive commuters in European and Japanese secondary cities.
- Freestyle:Reinforced steel frames with compact geometries withstand repeated impact from tricks and stairs. Fixed-gear trick riding culture concentrates in Brooklyn, London, and Tokyo street riding communities.
Established volume favors Urban; emerging adoption favors Track.
Material:
Cost tier stratification once separated aluminum entry-level from steel premium, but tubing innovations are collapsing these distinctions.
- Aluminum:6061-T6 and 7005 alloys deliver favorable stiffness-to-weight ratios at volume production scale. Cannondale and State Bicycle Company anchor positioning through race-proven geometry and vertical integration into wheelset sourcing.
- Steel:Butted chromoly and heat-treated 4130 alloys achieve aluminum-comparable weights without ride-quality penalties. Boutique builders in Osaka and Milan adopt these specifications for premium urban frames that command scarcity premiums.
- Carbon Fiber:Monocoque construction dominates UCI-sanctioned track events where gram reduction justifies cost premiums. Limited production runs restrict availability to sponsored athletes and collector markets.
- Titanium:Seamless 3Al-2.5V tubing offers corrosion resistance and fatigue life for all-weather commuters in coastal Japanese and Italian cities. Fabrication complexity limits output to artisan frame builders.
Procurement is shifting toward steel as tubing manufacturers compress weight differentials; carbon fiber retains pricing power in racing tiers only.
Age Group:
Customer type segmentation maps biomechanical development stages against frame size availability and control skill requirements.
- Adults:Full size run availability from 48cm through 62cm frames accommodates inseam ranges across global anthropometric variation. Metropolitan courier employment and club racing participation drive replacement cycles.
- Teens:650c wheel platforms and scaled crank arm lengths bridge growth spurts without premature obsolescence. Japanese and Italian school commuting culture sustains dedicated product lines.
- Kids:24-inch and smaller wheel formats with reduced gear ratios prevent knee strain during developmental years. Limited distribution through specialty retailers constrains volume.
- Seniors:Step-through frame geometries and lower bottom bracket heights address flexibility limitations. Fixed-gear demand remains minimal given balance and joint stress concerns.
Adults generate absolute volume; Teens represent the steepest expansion trajectory as urban cycling culture transmits across generations.
Usage:
Application segmentation distinguishes between utility-driven mileage accumulation and discretionary recreational expenditure.
- Commuting:Rack and fender compatibility, sealed bearing hubs, and puncture-resistant tires prioritize reliability over weight reduction. Congestion charging in London, Milan, and Tokyo metropolitan centers incentivizes modal shift from automotive transport.
- Racing:UCI compliance mandates for track width, weight minimums, and handlebar restrictions constrain design freedom. Olympic qualification events and World Championship calendars create predictable equipment replacement windows.
- Leisure:Aesthetic customization through colored wheelsets, brooks leather saddles, and vintage-inspired frames dominates purchasing criteria. Social media visibility drives component selection over functional specifications.
- Fitness:Fixed-gear training improves pedaling efficiency and cadence discipline for road cyclists during base-building periods. Indoor smart trainer compatibility expands year-round utility.
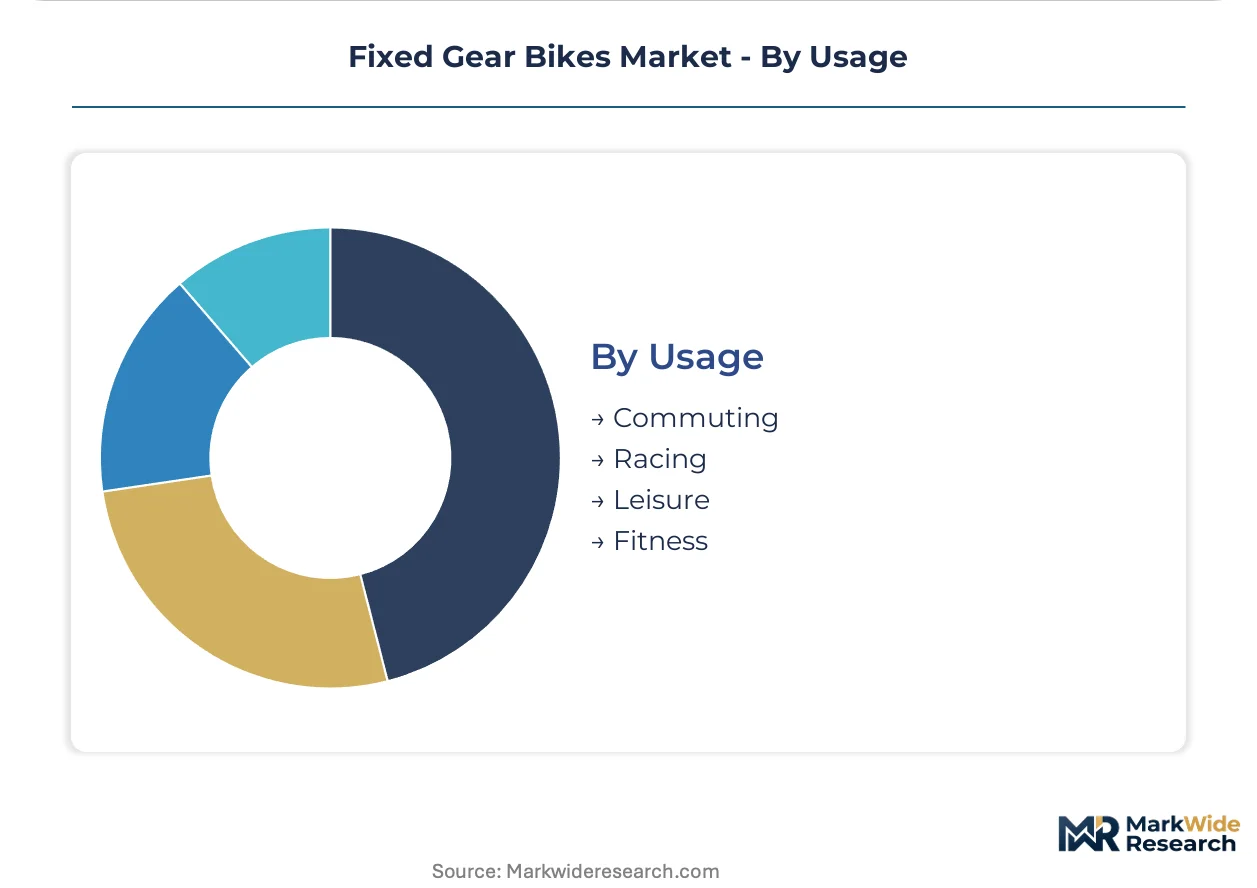
Commuting commands installed base; Fitness applications are gaining share fastest as structured training methodologies penetrate amateur cycling populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fixed-gear consumption patterns diverge sharply by geography: Japan and Italy treat these machines as precision urban instruments, while the United States bifurcates between messenger-workhorse utility and boutique collector culture.
United States
Last-mile delivery fleets in New York City and San Francisco have standardized fixed-gear configurations for mechanical reliability and theft deterrence. The Consumer Product Safety Commission mandates front caliper braking systems that add cost but satisfy urban safety requirements. Brooklyn's fabrication cluster supports artisan frame builders serving the freestyle and commuter segments.
Japan
Keirin racing culture sustains domestic demand for track-certified frames, while Tokyo's congestion-charged center pushes courier employment toward fixed-gear adoption. The Ministry of Economy, Trade and Industry enforces JIS frame integrity protocols that export-oriented manufacturers target for quality signaling. Osaka's steel tubing specialists supply boutique builders across the Kansai region.
Italy
Milan's dense metropolitan core and established cycling infrastructure generate sustained commuter demand for chromoly steel urban configurations. European Union CE marking under the Machinery Directive governs component interoperability for cross-border distribution. The Veneto and Lombardy regions host artisan frame builders serving premium collector markets.
United Kingdom
London's congestion charging and cycle superhighway investments have expanded fixed-gear commuting among financial district workers. The UK's Trading Standards office enforces bicycle safety regulations aligned with EU Machinery Directive principles. Manchester and Bristol fabrication workshops serve growing regional demand outside the capital.
Germany
Berlin's flat topography and extensive bike lane network support fixed-gear adoption among young professionals, though e-bike subsidies create substitution pressure. The Kraftfahrt-Bundesamt regulates bicycle safety standards for domestic market access. Hamburg and Munich host specialized retailers bridging track racing and urban utility segments.
Fixed Gear Bikes Market Competitive Landscape
Capability concentration sits with boutique frame builders and specialized component manufacturers; scale advantage sits with vertically integrated mass-market producers. The vendor base spans three tiers: artisan builders commanding scarcity premiums, mid-market specialists balancing quality and accessibility, and volume producers optimizing aluminum fabrication at scale. Dominant competitive moves include backward integration into wheelset and crankset sourcing, plus direct-to-consumer channel expansion that bypasses traditional bike shop intermediaries.
Among North American specialists, State Bicycle Company and Brooklyn Bicycle Company exemplify the mid-market tier that balances urban utility specifications with accessible price positioning. European positioning is anchored by FabricBike, a Spanish limited company specializing in entry-level steel frames for continental commuters. These three entities represent distinct geographic anchoring strategies while occupying overlapping competitive space between artisan scarcity and mass-market scale.
| Leading Market Players |
|---|
| Cannondale |
| Ribble |
| Specialized |
| State Bicycle Company |
| FabricBike |
| Giant |
| Condor |
| Brooklyn Bicycle Company |
| Trek |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese aluminum frame fabrication is compressing margin buffers for mid-tier producers and forcing pricing discipline across Japanese and Italian supply bases. Utilization rates below 70% in Yangtze River Delta extrusion facilities are triggering aggressive spot-market discounting that reverberates through chromoly steel and 4130 alloy tubing segments.
Pricing Analysis
Project-based contracting dominates premium track frames and limited-run collaborations, while spot purchasing governs volume aluminum commuter production. Price differentiation hinges on JIS certification tier and geographic delivery cost to congestion-charged metropolitan cores. Cost compression in entry-level steel is intensifying because FabricBike and similar European specialists are optimizing 4130 alloy sourcing at scale. Fleet procurement teams at Tokyo and New York courier services exhibit highest price sensitivity; collector markets for Osaka and Milan boutique builds show least.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for Taiwanese hub manufacturers supplying wheelset assemblies to mid-market assemblers. Raw material sourcing draws from Chinese aluminum smelters, Japanese chromoly specialists, and Italian 4130 tubing mills. Single-source vulnerability concentrates in Osaka-area heat-treatment facilities serving premium urban frame builders. Distribution runs through direct-to-consumer online retailers and dedicated fixie workshops that bypass traditional bike shop intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as urban courier fleet standardization and boutique collector demand create divergent premium tiers. Last-mile delivery mechanization and freestyle culture expansion are generating addressable niches for differentiated positioning.
For Market Incumbents: Entrench through backward integration into wheelset and crankset sourcing that State Bicycle Company has demonstrated. Secure JIS frame integrity certification to defend against European CE-marked competitors. Channel control via dedicated fixie workshops builds recurring maintenance revenue and locks in replacement cycles.
For New Entrants and Emerging Players: Secondary Japanese and Italian cities outside Tokyo and Milan represent underpenetrated urban commuter demand. Direct-to-consumer online retail with bundled fit services bypasses established bike shop networks. Target chromoly steel configurations where aluminum incumbents have ceded positioning.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across direct-to-consumer assembly operations as modular component ecosystems mature. Boutique frame builders with established Osaka or Milan fabrication relationships offer acquisition profiles with scarcity premium capture. Monitor e-bike subsidy program expansion in European and Japanese municipalities as demand substitution signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wheelset Sourcing | State Bicycle Company's captive supply of hubs and rims compresses cost structures for mid-market positioning. |
| JIS Certification Investment | Japanese Ministry of Economy, Trade and Industry protocols signal quality for export-oriented manufacturers targeting premium tiers. |
| Direct-to-Consumer Channel Expansion | Online retailers capture price-sensitive commuters in underserved secondary Italian and Japanese metropolitan zones. |
| Boutique Frame Builder Collaboration | Limited-run partnerships between component brands and artisan builders create scarcity premiums in collector markets. |
| Workshop Education Programming | Fixie-specific maintenance clinics build recurring revenue streams and brand loyalty among mechanically inclined urban riders. |
Research Methodology
The analysis maps track racing, urban commuter, freestyle, and single-speed segments, each validated through frame builders, component manufacturers, courier fleet managers, and specialty retailers. Primary interviews with workshop owners, tubing mill procurement leads, and velodrome equipment coordinators combined with secondary validation from UCI technical regulations, JIS standards documentation, and EU Machinery Directive filings. Bottom-up unit economics from frame fabrication cost structures and top-down market sizing from metropolitan cycling mode-share data provide triangulation.
Assumptions held fixed include regulatory stability for braking performance mandates and continued congestion charging in analyzed metropolitan cores; variables tested include e-bike subsidy expansion rates and chromoly steel commodity cycles. Segmentation dimensions span bike type, frame material, age group, and usage application across the projection horizon. CAGRs derive from installed base replacement cycles and fleet conversion trajectories. Forecast inputs incorporate Keirin racing equipment refresh calendars and last-mile delivery employment growth in Tokyo, Milan, and New York.
Practitioners should monitor municipal e-bike subsidy rule changes and chromoly steel scrap metal volatility for early signals of demand substitution or input cost disruption. Forecasts reflect documented assumptions; macroeconomic contraction, regulatory braking mandate relaxation, or carbon fiber cost breakthrough would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Automotive Bicycle Rack Market
Bikes and Motorcycles
Motorsports Motorcycle Market
Bikes and Motorcycles
Cargo Bike Market
Bikes and Motorcycles
Spain E-Bike Market
Bikes and Motorcycles
Motorcycle Airbag Market
Bikes and Motorcycles
Sweden E-Bike Market
Bikes and Motorcycles
Two Wheeler Handlebars Market
Bikes and Motorcycles
Flying Bikes Market
Bikes and Motorcycles
Bicycle Crank Motor Market
Bikes and Motorcycles
US Fuel Cell Bikes Market
Bikes and Motorcycles
Carbon Fiber Bicycle Market
Bikes and Motorcycles
Ride on Bikes Market
Bikes and Motorcycles
Mountain Bike Suspension Market
Bikes and Motorcycles
Two Wheeler Fenders Market
Bikes and Motorcycles
Motorcycle Fairings Market
Bikes and Motorcycles
Bike Hub Market