
 Asia-Pacific Two-Wheeler Taxi Market | 2026-2036
Asia-Pacific Two-Wheeler Taxi Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Two-Wheeler Taxi Market Outlook
Asset-light leasing frameworks for driver-owned electric two-wheelers is rewriting competitive entry barriers across Southeast Asian corridors. GOJEK Ltd. leverages its super-app ecosystem to sustain rider retention through bundled financial services. Rapido Ltd. anchors its position in Indian tier-2 cities through hyperlocal fleet density and vernacular-language interfaces. Pathao Ltd. competes by dominating Bangladesh's dense urban corridors where four-wheeler penetration remains minimal.
The Asia-Pacific two-wheeler taxi comprises on-demand motorcycle and scooter-based passenger transport services, typically deploying vehicles with engine displacements under 150cc or electric equivalents rated for 25-45 kmph urban cruising speeds, designed to navigate narrow arterial roads and high-congestion zones where four-wheeler throughput collapses. Ride-hailing platforms occupy the structural center of value capture, while shared-ride configurations represent the fastest-growing service tier as unit economics improve through passenger-pooling algorithms. E-bike segments within the vehicle-type classification are drawing disproportionate capital allocation as battery-swapping infrastructure spreads across Indonesian and Vietnamese urban clusters.
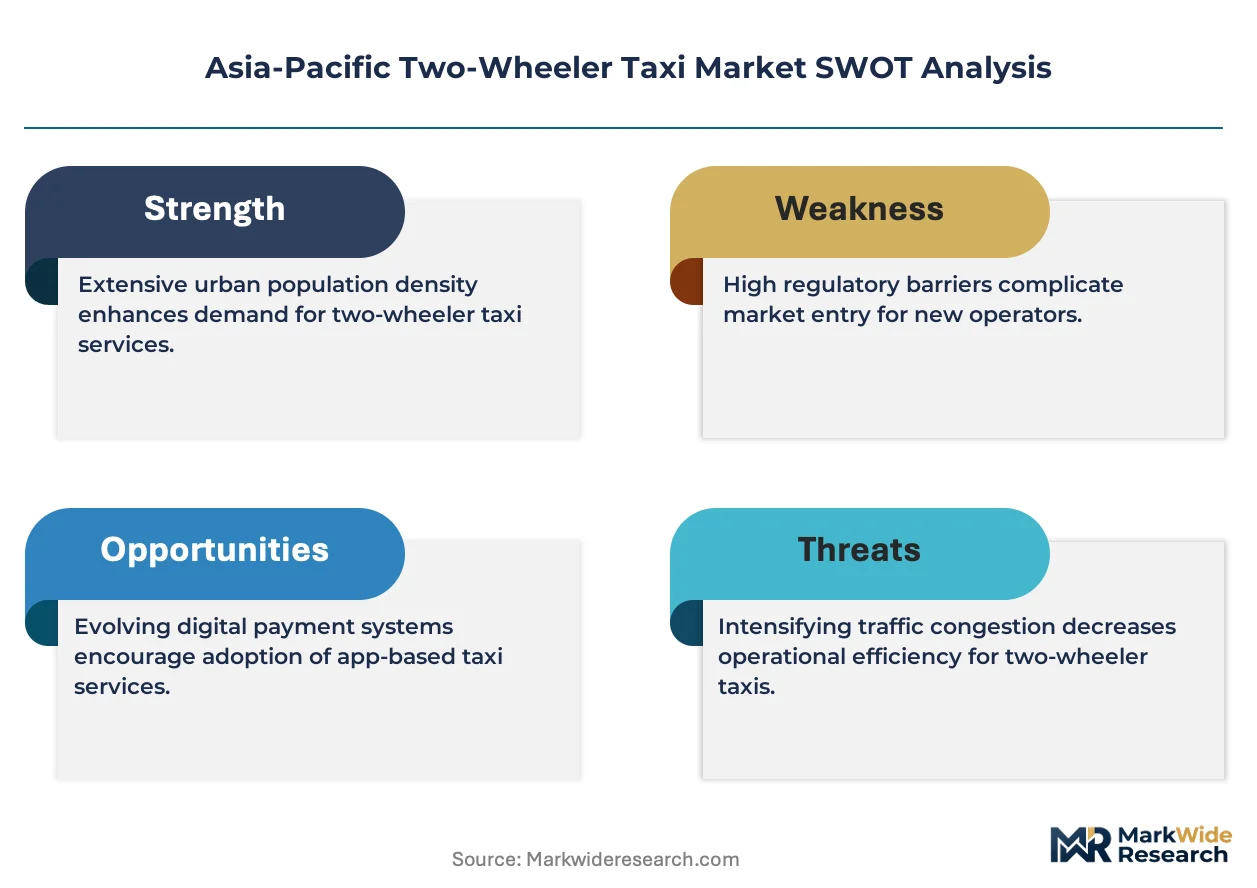
Indonesia's Ministry of Transportation collaborates with the country's central bank to enforce digital-payment interoperability standards that lock out cash-only operators, while India's BIS certification requirements for electric two-wheeler batteries reshape fleet procurement specifications. Vietnam's MIC mandates GPS-tracking and rider-identity verification protocols that raise compliance costs for unorganized traditional taxi segments. Stakeholders must monitor which regulatory jurisdiction first mandates comprehensive commercial-insurance coverage for gig-platform riders, as this single policy shift would compress margins across asset-light business models and force consolidation toward balance-sheet-heavy fleet ownership.
Market Dynamics
Fleet electrification mandates across Indian states and Indonesia's digital-payment interoperability standards are compressing operating margins for cash-dependent operators while accelerating capital deployment into battery-swapping infrastructure.
Growth Catalysts
- India's PLI scheme for electric vehicle manufacturing:State transport departments in Maharashtra, Karnataka, and Tamil Nadu are mandating progressive electrification targets for commercial two-wheeler fleets, creating procurement pull for domestic OEMs.
- Daily commuter density in Jakarta, Ho Chi Minh City, and Dhaka:Motorcycle penetration exceeding household car ownership in these corridors generates structural demand for on-demand mobility that four-wheelers cannot physically fulfill.
- Battery-swapping networks:Standardized swap stations across Indonesian and Vietnamese urban clusters are eliminating range anxiety and enabling 24-hour fleet utilization rates previously impossible with plug-in charging.
Market Restraints
- Lithium-ion cell import dependence:Southeast Asian operators rely on Chinese and South Korean cell suppliers, exposing fleet procurement to currency volatility and shipping cost spikes.
- Vietnam's GPS-tracking and rider-identity verification protocols:MIC mandates raise compliance costs for unorganized traditional taxi segments, limiting competitive pressure on organized platforms.
- Four-wheeler ride-hailing substitution:Ola and Grab's car services capture premium corridor demand in Indian and Indonesian metro centers during off-peak hours.
Strategic Opportunities
- Bangladesh's dense urban corridors:Dhaka and Chittagong maintain minimal four-wheeler penetration, creating white space for two-wheeler platforms to establish category dominance before infrastructure catches up.
- Shared-ride configurations:Passenger-pooling algorithms improve unit economics on identical routes, enabling platform expansion into price-sensitive Indian tier-3 cities.
- Indonesia's central bank digital-payment interoperability:BI standards lock out cash-only competitors, creating regulatory moats for platforms with integrated e-wallet infrastructure.
Industry Challenges
- Commercial-insurance coverage gaps:No Asia-Pacific jurisdiction currently mandates comprehensive gig-platform rider insurance, leaving platforms exposed to liability spikes from single incidents.
- BIS certification timelines for electric two-wheeler batteries:Indian fleet procurement faces 4-6 month approval cycles that delay fleet refresh schedules and strand capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Two-Wheeler Taxi Market |
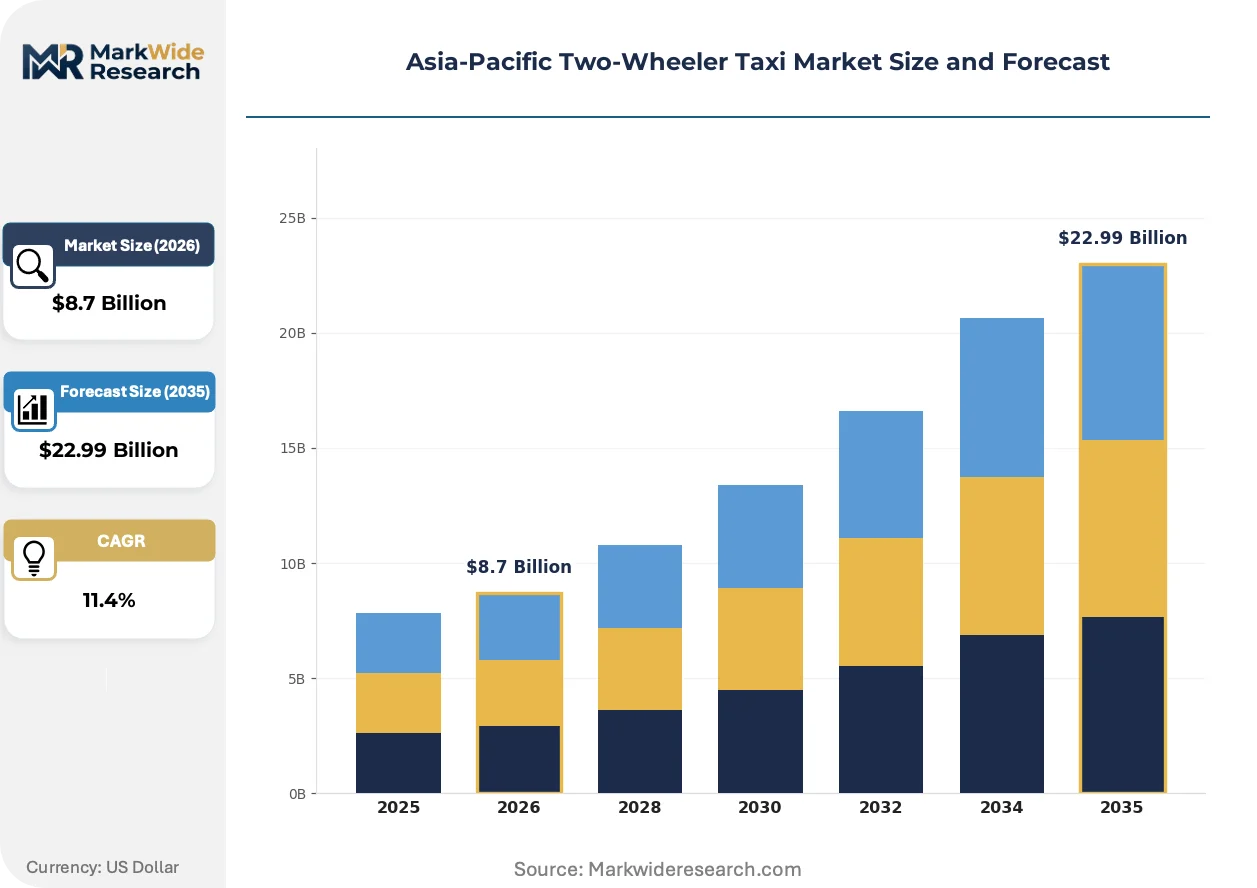
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Ride-Hailing, Traditional Taxi, Shared Ride, Premium Service End User: Daily Commuters, Tourists, Delivery Services, Students Vehicle Type: Scooter, Motorcycle, E-Bike, Moped Payment Model: Cash, Mobile Wallets, Credit/Debit Cards, Subscription |
| Companies Covered | Uber Technologies Inc., Grab Holdings Inc., GOJEK Ltd., ANI Technologies Pvt. Ltd., Rapido Ltd., Pathao Ltd., Bolt Technology OU, Mopedo, Roppen Transportation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Two-Wheeler Taxi Market Strategic Shifts
Three distinct forces are restructuring value capture in Asia-Pacific two-wheeler mobility: fleet virtualization through software-defined operations, regulatory compression of informal competition, and behavioral shifts toward bundled service consumption.
Telematics-integrated fleet management platforms are virtualizing dispatch and asset utilization across Indonesian and Vietnamese operator networks. GOJEK and Grab deploy real-time demand prediction algorithms that reposition idle riders before requests materialize. This virtualization is collapsing the traditional street-hail advantage of unorganized motorcycle taxis by intercepting demand digitally before physical proximity matters.
India's BIS certification requirements for electric two-wheeler batteries are reshaping procurement specifications for fleet operators. The standards disqualify uncertified imports and favor domestic cell-pack integrators with testing laboratory relationships. Maharashtra-based fleet aggregators are responding by consolidating orders through OEMs with pre-approved battery configurations, compressing supplier diversity.
Commuter preferences in Jakarta and Ho Chi Minh City are gravitating toward super-app bundled services that combine ride-hailing with food delivery and digital payments. This convergence rewards platforms with multi-service infrastructure and disadvantages single-vertical operators. The shift is most visible among Indonesian daily commuters under 35, where wallet retention metrics now exceed ride frequency as the primary loyalty indicator.
Asia-Pacific Two-Wheeler Taxi Market Segmentation
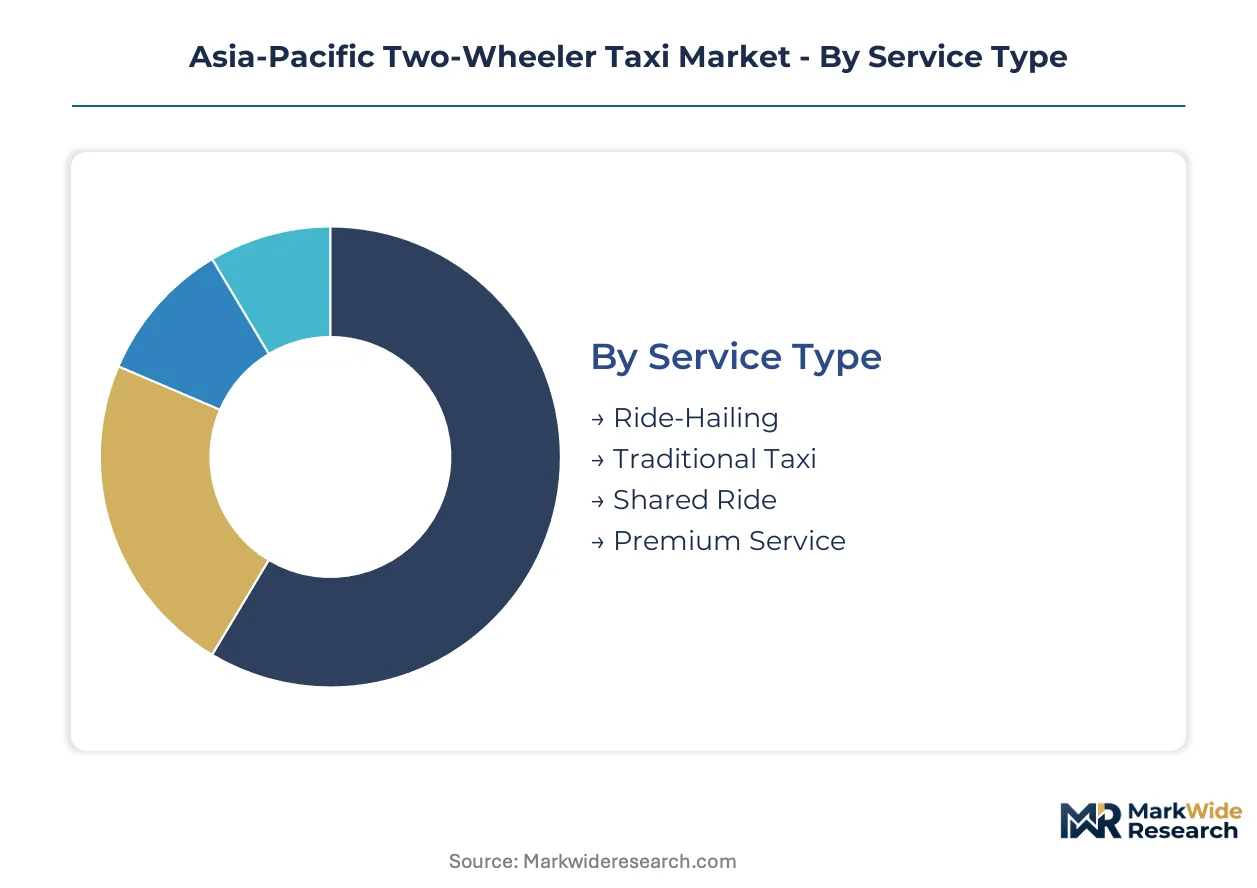
Asia-Pacific two-wheeler taxi operators configure service portfolios around four intersecting dimensions: how rides are summoned, who consumes them, what vehicle delivers the trip, and how payment settles. These axes determine capital intensity, regulatory exposure, and margin structure across Indonesian, Indian, and Vietnamese corridors.
Service Type:
Application architecture separates platforms by how demand interfaces with supply—whether through algorithmic matching, street-hail legacy, pooled capacity, or premium guarantees.
- Ride-Hailing:App-based dispatch platforms dominate Jakarta, Bangalore, and Ho Chi Minh City corridors. Real-time GPS positioning and dynamic pricing algorithms compress wait times below three minutes in dense urban clusters.
- Shared Ride:Passenger-pooling configurations improve unit economics on identical routes. Vietnamese operators deploy this tier aggressively in price-sensitive corridors where per-kilometer rates must undercut solo rides by 40% to capture volume.
- Traditional Taxi:Street-hail motorcycle taxis persist in Bangladeshi and Indonesian secondary cities where smartphone penetration lags. These segments face compression from BI-mandated digital-payment interoperability standards.
- Premium Service:Guaranteed vehicle quality and trained riders target airport corridors and business districts. Indian platforms restrict this tier to 150cc+ motorcycles or electric equivalents with certified battery configurations.
Ride-hailing holds installed capacity. Shared Ride is rotating up the share rankings.
End User:
Customer type determines frequency patterns, price elasticity, and loyalty mechanics across metropolitan mobility networks.
- Daily Commuters:Recurring morning-evening corridor trips generate 70%+ of platform volume in Jakarta and Dhaka. Subscription payment models and route-locking features retain this cohort against competitor poaching.
- Delivery Services:Restaurant and parcel platforms outsource last-mile fulfillment to two-wheeler taxi networks. Indonesian super-apps bundle driver supply across passenger and cargo demand to flatten idle-time curves.
- Tourists:Short-stay visitors favor prepaid package rides and English-language interfaces. Vietnamese operators concentrate this segment in Ho Chi Minh City and Hanoi historic districts.
- Students:Campus-to-transit-hub corridors in Indian tier-2 cities drive off-peak utilization. Price-sensitive demand forces platforms into shared-ride configurations with 15-minute departure windows.
Daily Commuters anchor revenue stability. Delivery Services is climbing the fastest as e-commerce penetration deepens.
Vehicle Type:
Powertrain and form factor selection shapes regulatory compliance, battery-swapping compatibility, and driver acquisition economics.
- E-Bike:Electric two-wheelers with 25-45 kmph urban cruising speeds dominate Indonesian fleet refresh programs. Battery-swapping infrastructure from Gogoro and domestic providers eliminates range anxiety for 24-hour utilization.
- Motorcycle:110-150cc internal combustion engines retain cost advantages in Indian tier-3 cities where charging infrastructure remains sparse. BIS certification timelines for battery imports delay electrification in these corridors.
- Scooter:Step-through designs with under-seat storage suit shared-ride configurations and short-haul delivery. Vietnamese manufacturers optimize frame geometry for passenger-plus-cargo loads.
- Moped:Low-displacement 50cc variants serve student and elderly demographics with restricted license classes. These segments contract as platforms mandate higher vehicle specifications for insurance coverage.
Motorcycle holds legacy fleet mass. E-Bike is gaining share fastest on electrification mandates and swapping network expansion.
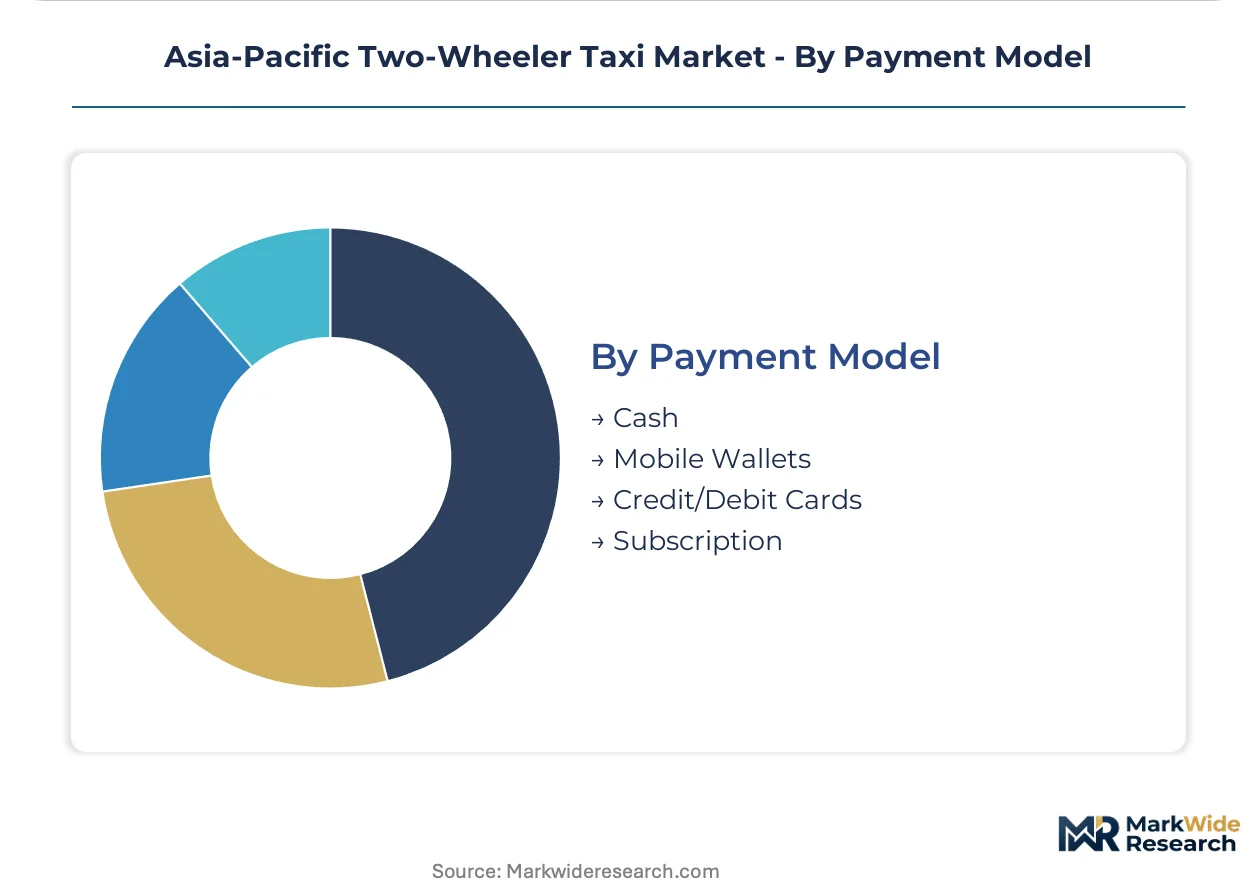
Payment Model:
Settlement infrastructure determines customer acquisition friction, driver cash-handling risk, and regulatory compliance exposure.
- Mobile Wallets:Integrated e-wallet retention exceeds ride frequency as the primary loyalty metric among Indonesian commuters under 35. BI interoperability standards lock out cash-only competitors.
- Cash:Street-hail transactions persist where smartphone penetration lags or bank account access remains limited. Indian demonetization history and Indonesian central bank mandates compress this segment's viable geography.
- Credit/Debit Cards:Card-linked rewards target premium service tiers and tourist segments. Foreign-issued cards require additional verification layers that increase checkout abandonment.
- Subscription:Fixed-fee unlimited ride packages lock in daily commuter loyalty. Platforms in Bangalore and Jakarta experiment with employer-subsidized corporate subscriptions to secure base-load demand.
Mobile Wallets commands transaction volume leadership. Subscription is ascending the adoption curve as platforms seek predictable revenue streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in electric two-wheeler components reshape fleet procurement economics across Asia-Pacific corridors. Vietnamese operators source battery cells from regional suppliers while Indian platforms face BIS certification delays on imported lithium-ion packs. Metropolitan density gradients determine where two-wheeler taxis outcompete four-wheeler alternatives.
Indonesia
Jakarta's motorcycle penetration exceeds household car ownership by multiples, generating structural demand for on-demand two-wheeler mobility. Bank Indonesia enforces digital-payment interoperability standards that exclude cash-only operators from formal corridors. Surabaya and Bandung clusters concentrate battery-swapping infrastructure deployment from Gogoro and domestic providers, enabling 24-hour fleet utilization rates.
India
Maharashtra, Karnataka, and Tamil Nadu transport departments mandate progressive fleet electrification targets for commercial two-wheeler operators. The PLI scheme for electric vehicle manufacturing accelerates domestic OEM procurement pull and compresses import dependence. Bangalore and Delhi-NCR corridors anchor platform volume through daily commuter density and hyperlocal fleet deployment strategies.
Vietnam
Ho Chi Minh City and Hanoi historic districts generate concentrated demand from tourists and daily commuters navigating high-congestion zones. The Ministry of Information and Communications mandates GPS-tracking and rider-identity verification protocols that raise compliance costs for unorganized traditional taxi segments. Domestic manufacturers optimize scooter frame geometry for passenger-plus-cargo loads in shared-ride configurations.
Bangladesh
Dhaka and Chittagong maintain minimal four-wheeler penetration, creating white space for two-wheeler platforms to establish category dominance. The dense urban corridor structure favors motorcycle taxis over car-based alternatives on narrow arterial roads. Platform operators deploy vernacular-language interfaces to capture price-sensitive commuter segments before infrastructure modernization accelerates.
Thailand
Bangkok's congestion-prone corridors sustain demand for motorcycle taxi services despite expanding mass transit infrastructure. The country's central bank promotes digital wallet adoption that aligns with platform payment integration strategies. Chiang Mai and Phuket clusters serve tourist segments through prepaid package rides and English-language interface deployment.
Asia-Pacific Two-Wheeler Taxi Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in battery-swapping infrastructure and telematics hardware. The vendor structure concentrates around super-app ecosystems that bundle ride-hailing with financial services and delivery logistics. Three archetypes dominate: asset-light aggregators leasing driver-owned vehicles, balance-sheet-heavy fleet operators controlling vehicle inventory, and infrastructure providers deploying standardized swap stations. Competitive moves center on geographic densification in tier-2 cities and backward integration into battery certification workflows.
Among Asia-Pacific-based platform operators, GOJEK Ltd., Rapido Ltd., and Pathao Ltd. exemplify distinct regional archetypes. GOJEK represents the super-app integrator model with bundled service ecosystems spanning Indonesia's metropolitan corridors. Rapido occupies a position in Indian tier-2 city densification with hyperlocal deployment strategies. Pathao anchors Bangladesh's dense urban corridor specialization where four-wheeler penetration remains minimal and motorcycle taxis dominate mobility infrastructure.
| Leading Market Players |
|---|
| Uber Technologies Inc. |
| Grab Holdings Inc. |
| GOJEK Ltd. |
| ANI Technologies Pvt. Ltd. |
| Rapido Ltd. |
| Pathao Ltd. |
| Bolt Technology OU |
| Mopedo |
| Roppen Transportation |
| Others |
Value Chain & Pricing Dynamics
The Malacca Strait container corridor feeds lithium-ion cell shipments from Chinese and South Korean suppliers into Indonesian and Vietnamese battery-swapping networks, concentrating procurement leverage among fleet operators with multi-year OEM contracts while fragmenting price-setting power for cash-dependent street-hail competitors locked out of BI-mandated digital payment corridors.
Pricing Analysis
Fleet operators and delivery platforms anchor pricing structure around subscription-based driver leasing and per-trip revenue-sharing models. Price differentiation hinges on battery certification tier under BIS and MIC protocols and geographic density of swap station coverage. Cost compression in unorganized street-hail segments intensifies because central bank digital mandates exclude cash-only riders from formal corridors. Student commuters in Indian tier-3 cities exhibit highest price sensitivity; premium airport corridors in Jakarta and Bangkok show lowest elasticity.
Supply Chain Analysis
Domestic battery pack integrators in Indonesia, Vietnam, and India hold final assembly capacity while cell production concentrates in China and South Korea. Raw material dependencies span lithium carbonate, nickel sulfate, and copper busbar feedstock. Single-source vulnerability runs through Chinese cathode precursor suppliers subject to export licensing volatility. Distribution runs through OEM-direct fleet procurement and third-party leasing aggregators serving driver-owned vehicle segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific two-wheeler taxi market is recovering from pandemic-induced driver attrition and fuel price volatility, with electrification mandates and super-app bundling serving as the cyclical engine normalizing fleet utilization rates across metropolitan corridors.
For Market Incumbents: Entrench category dominance through backward integration into BIS-certified battery procurement workflows and exclusive swap station partnerships with domestic energy providers. The threat of four-wheeler ride-hailing substitution during off-peak hours demands hyperlocal fleet density in tier-2 corridors where car penetration remains minimal. Channel control through employer-subsidized corporate subscriptions locks in base-load commuter demand against competitor poaching. For New Entrants and Emerging Players: Establish a beachhead in Bangladesh's Dhaka-Chittagong corridor where four-wheeler infrastructure gaps and minimal organized platform presence create white space for category capture. The most penetrable segment comprises vernacular-language daily commuters priced out of premium super-app ecosystems. A go-to-market angle anchored in driver-owned electric two-wheeler leasing with embedded insurance coverage bypasses balance-sheet-heavy fleet capital requirements. For Investors and Strategic Acquirers: Carve-out targets emerge from regional logistics conglomerates seeking to divest non-core mobility assets amid electrification capital intensity. Long-term viability hinges on regulatory jurisdictions mandating comprehensive commercial insurance for gig-platform riders, compressing asset-light models toward fleet ownership consolidation. The signal to watch is BI or RBI movement toward interoperability standards that privilege integrated e-wallet infrastructure over cash-dependent competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Domestic OEM partnerships with Gogoro and local swap providers secure 24-hour fleet utilization in Indonesian corridors. |
| Platform Integration | Super-app bundling of ride-hailing with food delivery and digital payments retains Indonesian commuters under 35. |
| Geographic Expansion | Tier-2 city densification in India captures student and daily commuter segments before four-wheeler infrastructure matures. |
| Regulatory Certification Investment | BIS battery approval workflows accelerate fleet refresh schedules and compress procurement delays for Maharashtra operators. |
| Strategic Partnership | Employer-subsidized corporate subscriptions in Bangalore and Jakarta lock in predictable base-load revenue streams. |
Study Parameters
Cross-validation between fleet operator procurement data and central bank payment system disclosures anchors the qualitative findings on digital mandate enforcement. Primary interviews with platform operations directors, state transport department officials, battery OEM procurement leads, and driver cooperative representatives combined with secondary validation from BI interoperability circulars, BIS certification registries, MIC technical standards, and customs import records. Bottom-up trip-volume modeling and top-down metropolitan mobility demand estimation triangulate market sizing.
Calibration against historical fleet electrification trajectories in Maharashtra and Jakarta refines projection parameters across the analysis window. Segmentation dimensions span service architecture, commuter type, powertrain configuration, and settlement infrastructure, with regional regulatory cluster as an additional modeled layer. CAGRs derive from slope-consistent growth patterning rather than endpoint anchoring. Forecast inputs incorporate battery-swapping network deployment schedules and PLI scheme utilization rates.
Stress conditions across lithium carbonate price volatility, currency fluctuation in cell import corridors, and regulatory acceleration of insurance mandates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on infrastructure buildout pacing and subsidy continuity. Quarterly review of swap station deployment metrics and state-level electrification compliance rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
China E-Bike Market
Bikes and Motorcycles
Saudi Arabia Motorcycle ADAS Market
Bikes and Motorcycles
Maxi Scooter Market
Bikes and Motorcycles
South America Two-Wheeler Market
Bikes and Motorcycles
E-Cargo Bike Market
Bikes and Motorcycles
Bike Fenders Market
Bikes and Motorcycles
Electric Cargo Bikes Market
Bikes and Motorcycles
Motorcycle Headlight Bracket Market
Bikes and Motorcycles
Carbon Fiber Bicycle Market
Bikes and Motorcycles
Motorcycle Exhaust Mounting Brackets Market
Bikes and Motorcycles
Motorcycle Boot Market
Bikes and Motorcycles
Motorcycle Accessories Market
Bikes and Motorcycles
Motorcycle Headlight Market
Bikes and Motorcycles
Global Motorcycle Airbag System Market
Bikes and Motorcycles
Austria E-Bike Market
Bikes and Motorcycles
Motorcycle Suspension System Market