
 Bicycle Crank Motor Market | 2026-2036
Bicycle Crank Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Bicycle Crank Motor Market Analysis
Commuter and delivery-service buyer archetypes is redrawing demand patterns away from pure recreational purchasers. Bosch eBike Systems leverages in-house sensor integration and German manufacturing scale to dominate European OEM supply chains. Shimano anchors its position through proprietary drivetrain compatibility that locks in replacement-part revenue. Bafang competes aggressively on cost-engineered mid-drive platforms for Asian and North American price-sensitive brands.
A bicycle crank motor integrates an electric motor into the bottom-bracket or crankset assembly, delivering torque directly through the drivetrain at 250–750 W nominal outputs for pedal-assist or throttle-controlled propulsion. Brushless DC technology leads unit volume due to thermal efficiency and regenerative-capable controller compatibility, while geared architectures capture margin in high-torque cargo and mountain-bike applications where low-speed climbing performance commands premium pricing. Mid-drive systems concentrate value pools because frame-integrated placement optimizes weight distribution and enables multi-gear torque multiplication.
Germany's KBA, the EU's REACH chemical-compliance framework, and the US NHTSA e-bike classification rules collectively shape motor-output limits, battery-transport safety, and product-liability exposure across export markets. The EU's F-Gas Regulation and emerging battery-passport requirements are adding compliance layers that favor vertically integrated manufacturers with in-house certification teams. Stakeholders must monitor how torque-sensor precision standards and software-defined motor-mapping capabilities reshape supplier qualification criteria.
Market Dynamics
The bicycle crank motor market is being fundamentally restructured by the electrification of urban freight logistics, where fleet operators now specify torque-dense mid-drive systems as standard equipment for cargo-bike procurement tenders.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of fluorinated refrigerants is accelerating investment in thermally efficient motor architectures that reduce cooling-system dependency.
- Last-mile delivery electrification:Urban logistics operators in the Netherlands and Germany are mandating crank-motor cargo bikes for congestion-zone access permits.
- Brushless DC thermal efficiency:Improved heat-dissipation profiles enable sustained high-torque output without derating, expanding mountain-bike and heavy-cargo applications.
Market Restraints
- Neodymium magnet cost volatility:Rare-earth price swings compress margins on high-performance permanent-magnet motor variants.
- German KBA certification backlog:StVZO compliance testing queues extend product launch timelines for EU-market entrants.
- Hub-motor substitution in Asian price segments:Cost-engineered direct-drive alternatives capture entry-level urban commuter volume in China and India.
Strategic Opportunities
- US NHTSA e-bike classification clarity:Three-tier regulatory framework is creating distinct product positioning tiers for Class 1-3 motor mapping.
- Battery-passport integration:EU emerging requirements favor manufacturers with in-house cell traceability and second-life logistics capabilities.
- Sensor-fusion convergence:Integration of torque, cadence, and inertial measurement enables predictive power delivery for safety-critical cargo applications.
Industry Challenges
- Embedded software certification:Functional-safety validation for motor-control algorithms under ISO 13849 is extending development cycles.
- Multi-gear drivetrain compatibility:Proprietary interface standards between crank motors and transmission systems fragment aftermarket service ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bicycle Crank Motor Market |
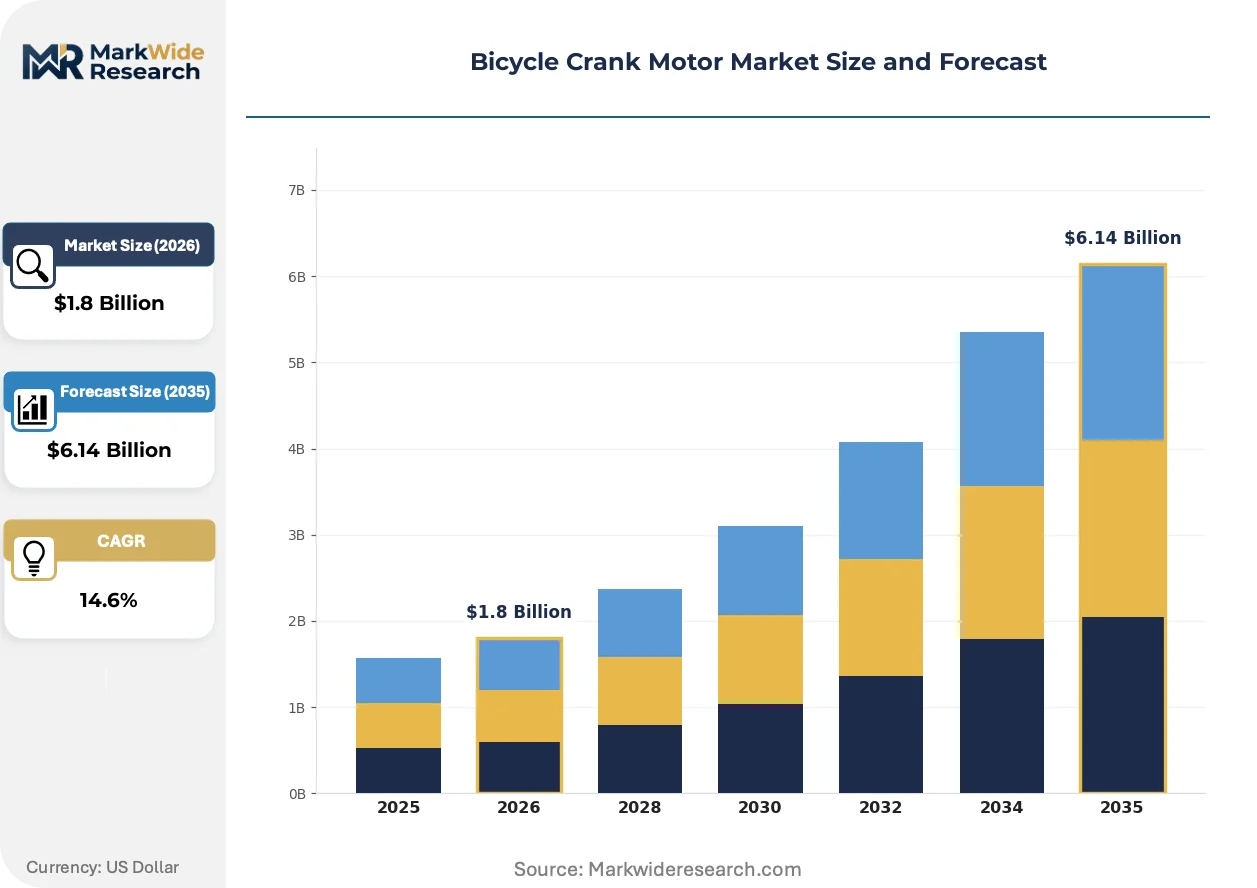
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mid-Drive, Hub Motor, Crankset, Bottom Bracket End User: Recreational Riders, Commuters, Delivery Services, Enthusiasts Technology: Brushless DC, Geared, Direct Drive, Regenerative Application: Mountain Biking, Road Cycling, Urban Commuting, Cargo Transport |
| Companies Covered | Bosch eBike Systems, Shimano, Bafang, Brose, Yamaha, Panasonic, TQ Systems, BionX International, MAHLE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bicycle Crank Motor Market Emerging Trajectories
Active torque-sensor architectures and software-defined motor mapping are displacing passive cadence-based systems as the primary competitive differentiator across premium and fleet segments.
Brushless DC motor technology is bifurcating into two distinct optimization paths: high-speed compact variants for lightweight urban commuters and high-torque geared architectures for cargo and all-terrain applications. Fleet procurement teams now specify thermal continuous-rating thresholds rather than peak-output figures in technical tenders. This specification shift is compressing market share for ungeared direct-drive alternatives that cannot sustain rated torque under load.
The EU's battery-passport requirements and REACH chemical-compliance frameworks are mandating granular material traceability from raw-source to end-of-life recycling. Manufacturers must now document conflict-mineral status and carbon-intensity metrics for magnet supply chains. Mid-drive system suppliers with captive rare-earth sourcing or long-term offtake agreements are securing preferential qualification status with German and Dutch OEMs.
Commercial fleet operators are consolidating procurement through direct manufacturer relationships rather than traditional bike-shop distribution channels. Large-scale urban logistics contracts now specify multi-year service-level agreements inclusive of predictive maintenance telemetry. This channel compression is most advanced in Copenhagen and Amsterdam, where municipal cargo-bike subsidy programs require integrated telematics reporting for compliance verification.
Bicycle Crank Motor Market Segmentation
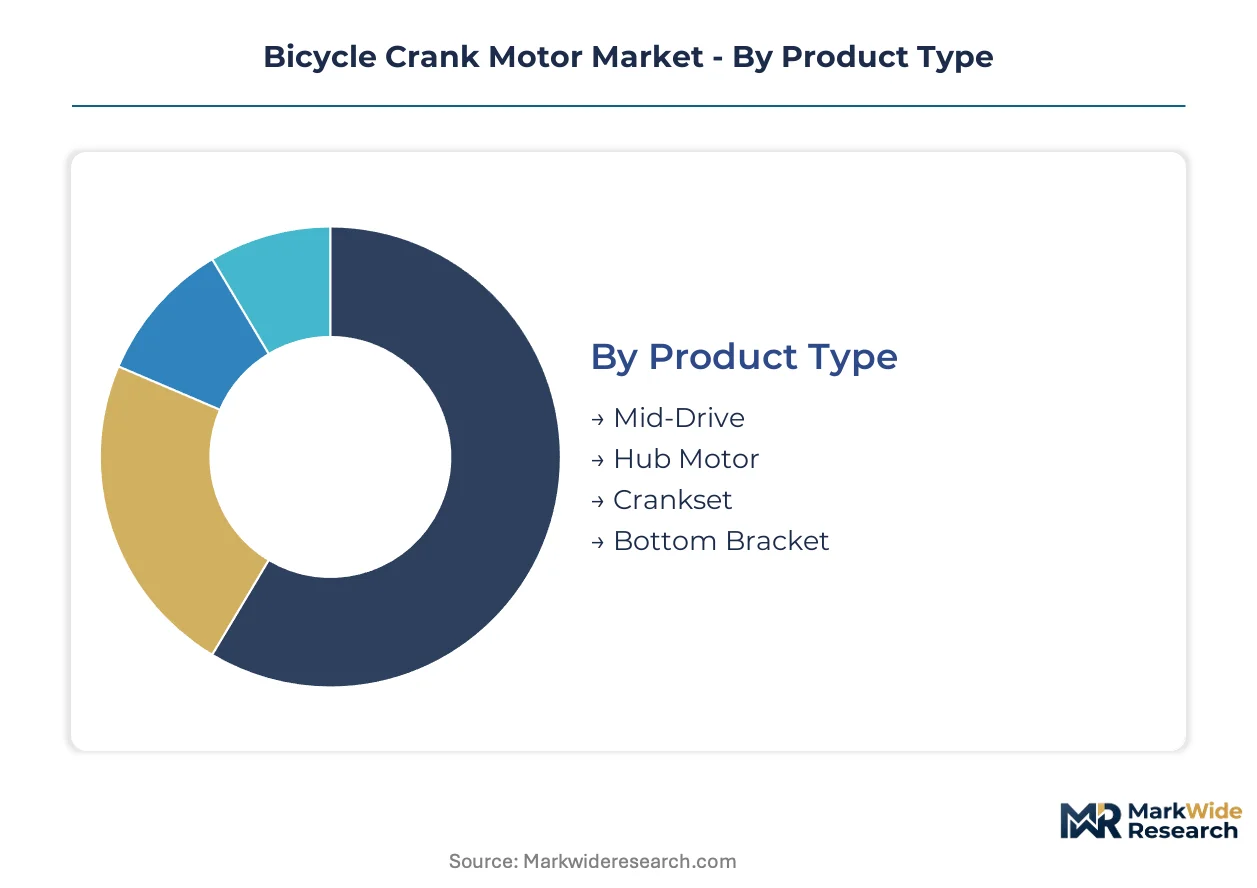
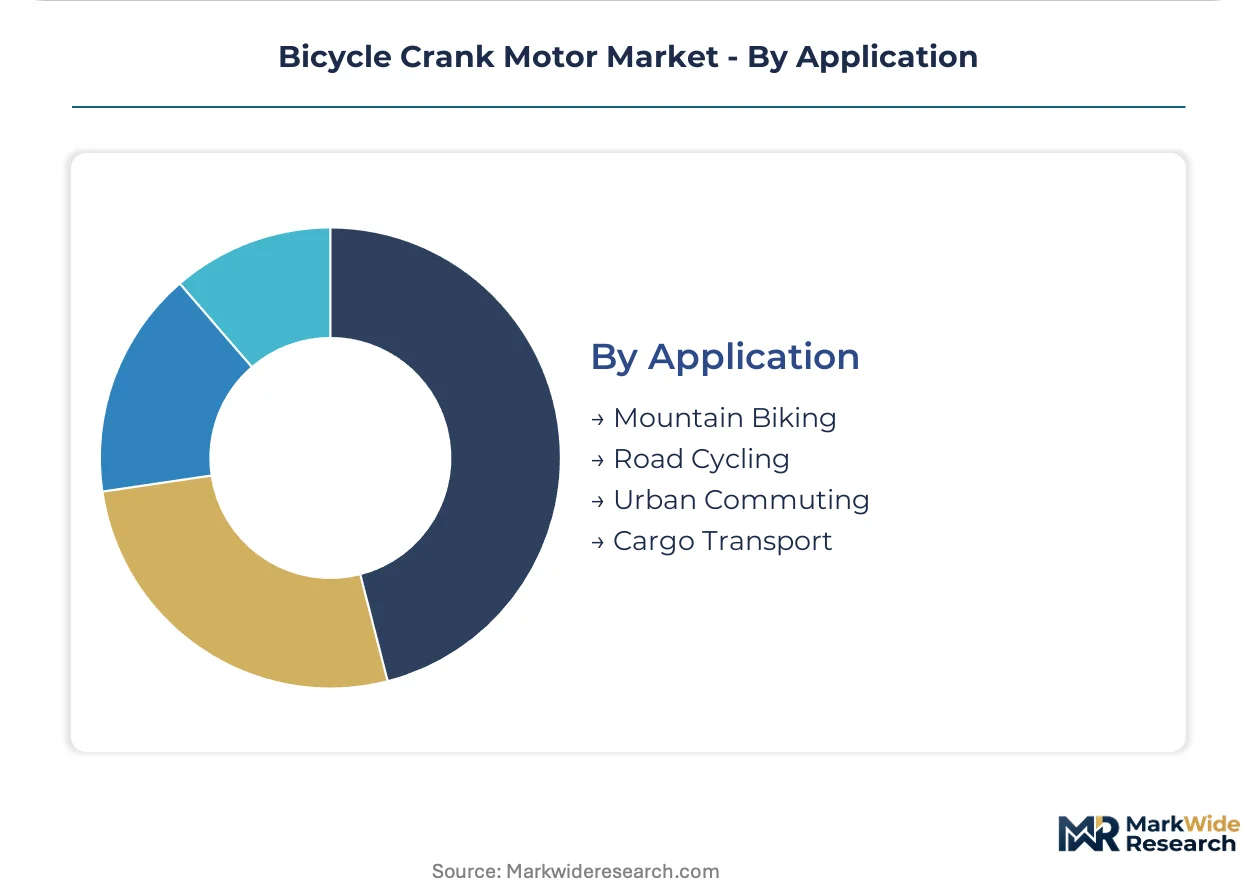
Crank motor segmentation reveals how torque density, thermal management, and drivetrain integration create divergent value pools across mobility applications. Fleet procurement specifications now override consumer preference as the primary demand shaper.
Product Type:
Hub motor substitution pressure concentrates most intensely on entry-level crankset variants, while mid-drive architectures defend position through frame-integrated weight distribution advantages.
- Mid-Drive:Frame-integrated placement at the bottom bracket enables multi-gear torque multiplication and optimized center-of-gravity positioning. Dutch and German cargo-bike fleet tenders now specify mid-drive systems as mandatory for urban access permits, locking out hub alternatives in commercial procurement.
- Hub Motor:Wheel-mounted direct-drive architectures compete on manufacturing simplicity and service accessibility. Cost-engineered variants capture price-sensitive urban commuter volume in Asian markets where regulatory output limits reduce the performance gap with crank-based systems.
- Crankset:Modular motor units replace traditional chainring assemblies for aftermarket retrofit applications. Enthusiast segments in North America drive demand for plug-and-play electrification kits compatible with legacy bicycle frames.
- Bottom Bracket:Compact motor housings integrate directly into the pedal spindle interface for minimalist frame designs. Premium urban commuter OEMs in Copenhagen specify these units for aesthetic integration with step-through frame geometries.
Mid-Drive anchors the volume base while Bottom Bracket gains share at the steepest rate as frame designers prioritize clean integration.
End User:
Cost tier stratification separates fleet procurement teams with multi-year service agreements from individual purchasers optimizing upfront acquisition expense.
- Recreational Riders:Weekend cyclists prioritize lightweight systems with minimal visual intrusion. European markets show concentration in Germany and Austria where rail-and-ride tourism infrastructure supports pedal-assist mountain bike rentals.
- Commuters:Daily urban travelers demand reliability-focused mid-drive platforms with sealed enclosures against road spray. Netherlands cycling infrastructure density creates the highest per-capita penetration globally for this segment.
- Delivery Services:Last-mile logistics operators specify thermal continuous-rating thresholds and predictive maintenance telemetry. Amsterdam and Copenhagen municipal subsidy programs mandate integrated telematics reporting for cargo-bike fleet compliance.
- Enthusiasts:Performance-oriented buyers seek high-torque geared architectures for technical trail riding. Mountain bike segments in Colorado and British Columbia drive specification for low-speed climbing capability.
Commuters represent the largest installed base while Delivery Services expand most quickly as urban freight electrification accelerates.
Technology:
Supply concentration around rare-earth magnet sourcing and controller firmware capabilities determines which architectures achieve cost-competitive scale.
- Brushless DC:Permanent-magnet synchronous designs dominate unit volume through thermal efficiency and regenerative controller compatibility. REACH chemical-compliance frameworks now mandate conflict-mineral documentation for magnet supply chains, favoring manufacturers with captive rare-earth offtake agreements.
- Geared:Planetary reduction stages multiply torque output for high-load cargo and all-terrain applications. German KBA certification requirements for sustained output ratings compress market share for ungeared alternatives in EU commercial fleets.
- Direct Drive:Gearless hub configurations reduce mechanical complexity for price-sensitive urban markets. Indian and Chinese commuter segments accept weight penalties in exchange for manufacturing cost advantages.
- Regenerative:Energy-recovery controller algorithms extend range in stop-and-go urban environments. EU battery-passport traceability requirements favor integrated motor-battery systems with second-life logistics capabilities.
Brushless DC maintains volume leadership while Geared systems climb fastest as cargo-bike specifications tighten.
Application:
Geography-driven regulatory divergence creates distinct product positioning tiers, with mountain and cargo segments commanding premium pricing through specialized thermal and torque requirements.
- Mountain Biking:Technical terrain demands high-torque geared architectures with impact-resistant housings. Colorado and British Columbia trail networks drive specification for sustained climbing output without thermal derating.
- Road Cycling:Weight minimization priorities favor compact mid-drive units with carbon fiber integration. Italian and Swiss racing-bike heritage brands specify sub-3kg complete systems for competitive segments.
- Urban Commuting:Stop-and-go traffic patterns optimize for responsive torque-sensor mapping and all-weather sealing. Copenhagen and Amsterdam infrastructure investments create concentrated demand for step-through compatible crank systems.
- Cargo Transport:Heavy-load logistics mandate continuous thermal ratings and multi-year service agreements. German StVZO regulations and Dutch subsidy programs collectively shape procurement specifications for commercial fleet operators.
Urban Commuting holds the largest addressable base while Cargo Transport demonstrates the steepest expansion trajectory as last-mile delivery electrifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine rail freight corridor underwrites Germany's dominance in European crank motor manufacturing, connecting Stuttgart engineering clusters to Rotterdam port logistics.
Germany
Stuttgart and Munich engineering belts concentrate mid-drive R&D for cargo-bike fleet specifications. KBA StVZO certification queues extend product launch timelines, favoring incumbent manufacturers with dedicated compliance teams. North Rhine-Westphalia's Ruhr Valley hosts final assembly operations serving Dutch and Belgian procurement tenders.
Netherlands
Amsterdam and Utrecht municipal subsidy programs mandate integrated telematics for cargo-bike fleet compliance. Dense cycling infrastructure creates premium uptake corridors for high-torque crank systems. Eindhoven's high-tech manufacturing cluster supplies sensor components to German motor integrators.
United States
Colorado and British Columbia trail networks drive specification for sustained climbing output without thermal derating. NHTSA's three-tier e-bike classification framework creates distinct product positioning tiers for Class 1-3 motor mapping. Pacific Northwest urban commuters favor sealed mid-drive platforms for year-round weather exposure.
China
Zhejiang and Jiangsu provinces host cost-engineered mid-drive fabrication for Asian and North American price-sensitive brands. Hub-motor substitution pressure concentrates in entry-level urban commuter segments. Shenzhen controller electronics clusters supply firmware capabilities to domestic motor manufacturers.
Japan
Kansai precision manufacturing traditions anchor torque-sensor component supply for premium European OEMs. METI industrial standards influence reliability benchmarks adopted across Asian export markets. Nagoya automotive supplier networks transfer quality-system expertise to e-mobility component production.
Bicycle Crank Motor Market Vendor Landscape
Concentration sits with integrated drivetrain specialists who control sensor-to-motor firmware stacks. Three-tier structure separates premium German engineering houses, Japanese precision component suppliers, and Chinese cost-optimized fabricators. Strategic archetypes include captive rare-earth magnet offtake holders, proprietary drivetrain compatibility gatekeepers, and fleet-telemetry service bundlers. Dominant competitive moves span backward integration into magnet supply chains and predictive maintenance software licensing.
Among German engineering houses, Bosch eBike Systems and Brose exemplify the premium-tier archetype through in-house manufacturing scale and sensor integration depth. Shimano occupies a position as the proprietary drivetrain anchor, leveraging replacement-part revenue lock-in. Bafang represents the cost-engineered mid-drive fabricator competing aggressively on manufacturing efficiency for price-sensitive brand procurement.
| Leading Market Players |
|---|
| Bosch eBike Systems |
| Shimano |
| Bafang |
| Brose |
| Yamaha |
| Panasonic |
| TQ Systems |
| BionX International |
| MAHLE |
| Others |
Supply Flow & Price Mechanics
Stuttgart engineering cluster scale economies concentrate mid-drive motor manufacturing in Germany's industrial belt, compressing unit costs for KBA-certified suppliers while anchoring price floors through regulatory compliance overhead. Dutch cargo-bike fleet tenders now specify thermal continuous-rating thresholds that filter out cost-engineered alternatives, creating volume-discount leverage for qualified incumbents.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Bosch and Brose sensor-integrated platforms from Shimano drivetrain-locked systems and Bafang cost-engineered variants. Price differentiation hinges on KBA StVZO certification grade and after-sales telemetry bundling. Cost compression in economy tiers intensifies because hub-motor substitution erodes entry-level crankset demand. Delivery service fleets show lowest price sensitivity while Asian commuter brands exhibit highest.
Supply Chain Analysis
Rare-earth magnet processing in China, Japan, and Malaysia underwrites permanent-motor supply security for premium European manufacturers. Controller firmware development draws from Shenzhen electronics clusters and Stuttgart embedded-systems houses. Single-source vulnerability concentrates in neodymium offtake agreements. Distribution runs through direct OEM supply contracts for fleet procurement and bike-shop networks for aftermarket retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as cargo-bike fleet specifications diverge from recreational consumer preferences, creating distinct qualification tiers that reward specialized positioning over broad portfolio coverage.
For Market Incumbents: Compound sensor-fusion capabilities through torque-cadence-inertial measurement integration to defend against hub-motor substitution in price-sensitive segments. Deepen captive rare-earth offtake agreements to secure magnet supply chain resilience against commodity volatility. Prioritize ISO 13849 functional-safety certification investment to extend KBA compliance lead times for challengers. For New Entrants and Emerging Players: KBA fast-track certification services in North Rhine-Westphalia offer regulatory arbitrage for mid-drive specialists targeting Dutch municipal subsidy programs. White-space concentrates in aftermarket crankset retrofit kits for North American enthusiast segments where legacy frame compatibility commands premium positioning. Go-to-market should emphasize plug-and-play installation protocols bypassing dealer network dependence. For Investors and Strategic Acquirers: Fleet-telemetry service bundlers with predictive maintenance software represent the most defensible acquisition archetype as urban logistics operators consolidate procurement through direct manufacturer relationships. Long-term viability centers on embedded software recurring revenue models displacing transactional hardware sales. Monitor German KBA queue length as inflection indicator for incumbent pricing power erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Fusion Platform Development | Integration of torque, cadence, and IMU data enables predictive power delivery for Amsterdam cargo-bike compliance mandates. |
| Rare-Earth Magnet Backward Integration | Captive neodymium sourcing secures preferential qualification status with Dutch and German OEM procurement teams. |
| Battery-Passport System Integration | EU emerging traceability requirements favor manufacturers with in-house cell documentation and second-life logistics capabilities. |
| Fleet Telematics Service Licensing | Predictive maintenance software bundling captures multi-year service agreements from Copenhagen municipal subsidy programs. |
| ISO 13849 Functional-Safety Certification | Motor-control algorithm validation extends development cycles but locks out unqualified competitors from commercial procurement. |
Methodological Framework
Operator-level perspectives from fleet procurement managers, OEM platform engineers, aftermarket service technicians, and regulatory compliance officers anchored the qualitative base. Secondary validation drew from KBA type-approval filings, EU REACH chemical-compliance registries, StVZO technical documentation, and NHTSA e-bike classification guidance. Bottom-up unit shipment estimates triangulated against top-down value pools across the analysis window.
Sensitivity analysis tested forecast outputs against neodymium price volatility scenarios, KBA certification timeline variations, and hub-motor substitution elasticity in Asian price segments. Segmentation modeling spanned motor architecture, end-user archetype, drivetrain integration depth, and regional regulatory framework. CAGRs derived from logistic diffusion curves fitted to fleet electrification adoption patterns and municipal subsidy program expansion trajectories.
Underlying assumptions cover sustained EU F-Gas Regulation enforcement, stable rare-earth supply chain throughput, and NHTSA classification framework continuity, with deviation risk concentrated in trade policy shifts affecting magnet sourcing. Practitioners should keep alternative scenarios live as battery-passport implementation timelines and torque-sensor precision standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Folding Bikes Market
Bikes and Motorcycles
Europe E Bike Market
Bikes and Motorcycles
Ride on Bikes Market
Bikes and Motorcycles
Vietnam Bike-Sharing Market
Bikes and Motorcycles
LAMEA Motorcycle ADAS Market
Bikes and Motorcycles
Europe Motorcycle Market
Bikes and Motorcycles
South America Two-Wheeler Market
Bikes and Motorcycles
Motorbike Carburetor Market
Bikes and Motorcycles
Motorcycle Chain Market
Bikes and Motorcycles
Fuel Cell Bikes Market
Bikes and Motorcycles
Motorcycle Advanced Rider Assistance System Market
Bikes and Motorcycles
Maxi Scooter Market
Bikes and Motorcycles
North America Bicycle Market
Bikes and Motorcycles
Folding Bicycle Market
Bikes and Motorcycles
Europe E-Cargo Bike Market
Bikes and Motorcycles
Two-Wheeler Services Market