
 China Coal Market | 2026-2036
China Coal Market Size, Share, and Industry Trends Forecast 2026-2036
China Coal Market Analysis
Shanxi Province's thermal coal output is hardening as the national base-load power fleet requires steady feedstock through the energy transition. China Shenhua Energy Company Limited leverages its integrated rail-port-mine network to sustain delivered cost advantages across coastal demand centers. Shaanxi Coal Industry Company Limited anchors supply security for the central China grid through its Yulin field operations. Yanzhou Coal Mining Company Limited competes on deep-gas management expertise in its Shandong underground complexes.
Coal is a combustible sedimentary rock with carbon content ranging from 50% to 90% by weight, formed from compressed peat through geological heat and pressure over millions of years, and serves as the primary fossil fuel for electricity generation and metallurgical reduction. Thermal coal dominates volume flows to power plants, while metallurgical coal commands premium pricing for blast furnace coke production in steelmaking. Quality grade stratification is widening as MEE rules push low-sulfur grades toward scarcity pricing and high-sulfur output into stranded cost positions.
MEE emissions standards, GB quality benchmarks, and the national dual carbon framework together dictate washing investment schedules and mine closure timelines across the Chinese coal sector. SAMR pricing oversight and provincial resource tax regimes further shape inter-provincial arbitrage and export competitiveness. Stakeholders must track the pace of ultra-supercritical plant retrofits and carbon capture pilots to judge how long base-load coal retains dispatch priority against renewables and nuclear.
Market Dynamics
Beijing's dual carbon framework is compressing mine lifecycles while forcing simultaneous investment in washing upgrades and carbon capture pilots, creating a capital squeeze that favors state-backed operators with integrated rail-port networks over fragmented county-level mines.
Growth Catalysts
- Ultra-supercritical retrofits:State Grid Corporation is mandating efficiency upgrades across coastal power fleets, preserving thermal coal dispatch priority against intermittent renewables through higher heat rates and lower coal intensity per megawatt-hour.
- MEE emissions standards:Tightening sulfur and particulate limits are accelerating consolidation toward Shanxi and Inner Mongolia mines with pre-existing washing infrastructure, shuttering high-sulfur operations in smaller provinces.
- Central China grid expansion:Henan and Hubei provincial utilities are expanding base-load capacity to replace decommissioned hydro during drought cycles, anchoring thermal coal offtake from Shaanxi's Yulin field.
Market Restraints
- Capital intensity of carbon capture:Post-combustion amine scrubbing and oxy-fuel retrofits require capital deployment that exceeds private mining balance sheet capacity, forcing reliance on state policy bank lending windows.
- Inner Mongolia supply concentration:Overreliance on Ordos Basin open-cast operations exposes coastal demand centers to rail bottleneck risks during Mongolian border disruptions or Qinhuangdao port maintenance cycles.
- Blast furnace hydrogen substitution:Baowu Steel and HBIS Group are piloting direct reduced iron with hydrogen feedstock, threatening long-term metallurgical coal pricing power in premium coking segments.
Strategic Opportunities
- Carbon capture utilization and storage hubs:Sinopec and China Energy are developing saline aquifer injection partnerships in Ordos Basin, creating revenue streams from enhanced oil recovery credits and carbon offset monetization.
- Coal-to-chemicals pivot:Coal-to-olefins and coal-to-ethanol pathways are absorbing stranded high-sulfur output rejected by power utilities, with Ningxia and Xinjiang pilot plants securing chemical sector offtake contracts.
- Intelligent mining mandates:MIIT's smart mine certification program is subsidizing 5G-enabled autonomous haulage and remote monitoring deployments, lowering labor intensity in deep Shandong underground complexes.
Industry Challenges
- Geotechnical engineering scarcity:Deep gas management expertise for multi-seam Shandong operations is concentrated among retiring state-owned enterprise engineers, constraining safe production expansion at Yanzhou's Jining mines.
- Washing capacity mismatch:GB quality benchmarks for low-sulfur thermal coal are outpacing installed preparation plant throughput, forcing raw coal blending that degrades boiler efficiency and accelerates plant maintenance cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Coal Market |
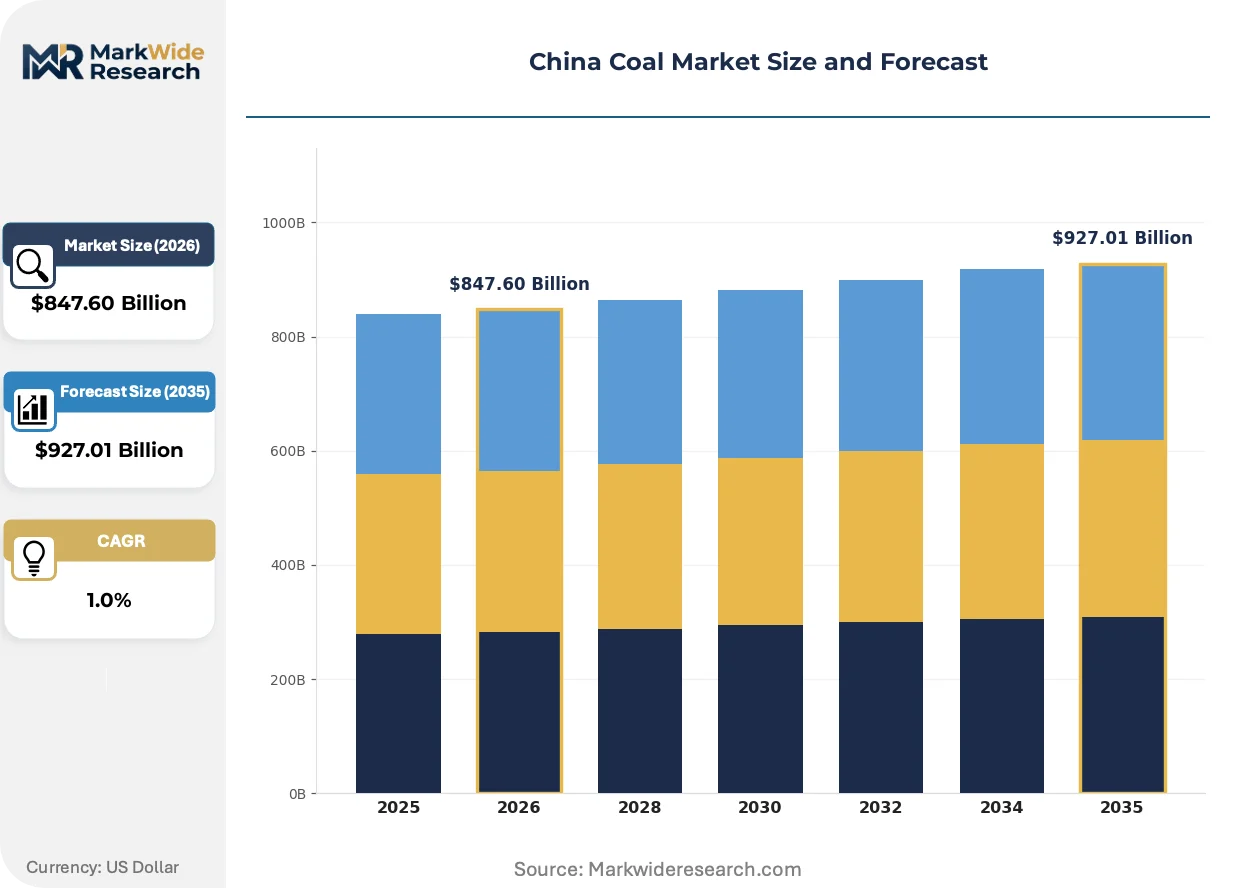
| Market Size in 2026 | $847.60 Billion |
| Market Size in 2035 | $927.01 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
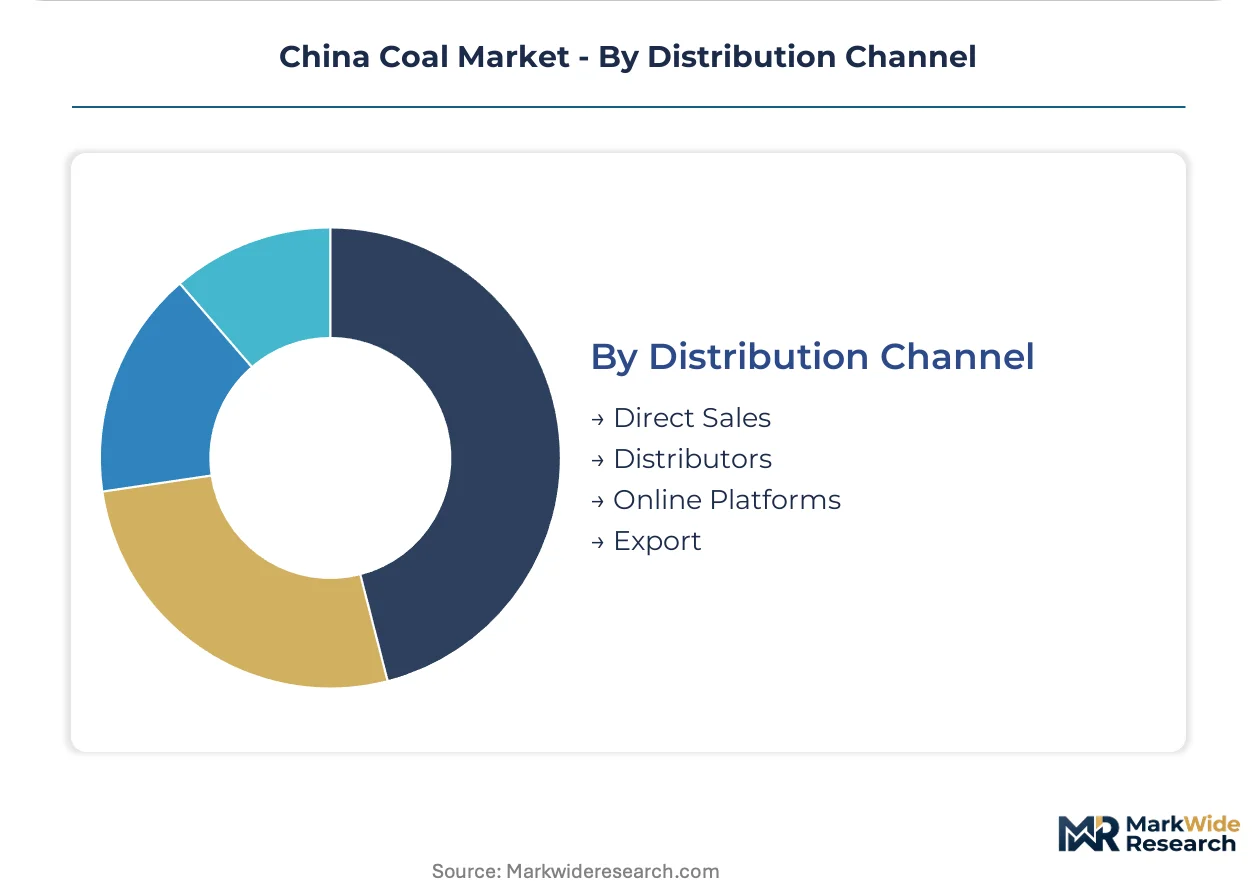
| Segmentation | Product Type: Thermal Coal, Metallurgical Coal, Coking Coal, Anthracite End User: Power Generation, Steel Production, Cement Manufacturing, Industrial Heating Quality Grade: Low-Sulfur, High-Sulfur, High-Heat, Medium-Quality Distribution Channel: Direct Sales, Distributors, Online Platforms, Export |
| Companies Covered | China Shenhua Energy Company Limited, China Coal Energy Company Limited, Shaanxi Coal Industry Company Limited, Yanzhou Coal Mining Company Limited, China Power International Development Limited, Huadian Power International Corporation Limited, Jinneng Holding Shanxi Coal Industry Co., Ltd., China Coal Xinji Energy Co Ltd., Anhui Hengyuan Coal Industry and Electricity Power Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Coal Market Emerging Trajectories
Carbon capture pilot deployment and intelligent mining automation are absorbing capital and engineering talent, while provincial resource tax reforms are reshaping inter-provincial arbitrage patterns and mine closure timelines.
Post-combustion amine scrubbing systems are absorbing stranded capital from deferred mine expansions, with China Energy and Sinopec installing 100,000-tonne annual capture pilots at Guohua Taishan and Jingbian power stations. State Grid's coastal utilities are prioritizing retrofitted units for dispatch merit order, compressing margins for unwashed high-sulfur supply. The technology is absorbing engineering procurement construction capacity that would otherwise flow toward greenfield mine development, extending replacement investment timelines.
MEE's 2023 revision to ambient air quality standards tightened sulfur dioxide emission limits for power sector stacks, forcing washing investment or fuel switching across northern China grids. Industrial consequence includes accelerated closure of mines lacking flue gas desulfurization compatibility, with Hebei and Shandong provincial environmental bureaus denying operating permits to high-ash producers. Shanxi mines with integrated 50-million-tonne washing plants are capturing displaced volume, while Shaanxi operators are upgrading Yulin preparation capacity to maintain grid supply contracts.
Long-term offtake contracting is displacing spot market procurement for coastal power utilities, with State Grid and China Huaneng Group negotiating five-year fixed-volume agreements indexed to Qinhuangdao port prices. Procurement departments are rejecting quarterly tender cycles in favor of direct mine relationships that guarantee washed coal quality consistency. This pattern is most visible in Jiangsu and Zhejiang provincial grids, where sulfur content penalties in contract terms now exceed spot market price volatility exposure.
China Coal Market Segmentation

Product differentiation across the China coal market determines washing investment requirements, emissions compliance costs, and dispatch priority in power sector procurement. Quality grade stratification and end-use specification now dictate mine viability under tightening MEE standards.
Product Type:
Standardization dominates thermal coal specifications for power sector procurement, while metallurgical grades require customized washing protocols to meet blast furnace chemistry requirements.
- Thermal Coal:Carbon content ranges from 50% to 70% with calorific values between 4,500 and 6,000 kcal/kg. State Grid Corporation procurement concentrates in Shanxi and Inner Mongolia deposits that feed ultra-supercritical retrofits along the coastal grid.
- Metallurgical Coal:Low-ash coking varieties command premium pricing through volatile matter control and coke strength indices. Baowu Steel and HBIS Group offtake from Shanxi Xishan mines anchors this segment despite hydrogen substitution pilots.
- Coking Coal:Blend optimization for blast furnace permeability requires precise sulfur and phosphorus limits. Domestic supply concentrates in Shanxi and Shandong provinces with integrated preparation plants.
- Anthracite:High-carbon low-volatile fuel serves industrial heating and specialized metallurgical applications in Henan and Guizhou provinces.
Most installed capacity flows through thermal coal. Expansion is steepest in metallurgical coal as steel sector quality requirements tighten.
End User:
Volume concentration versus margin capture splits this category between base-load power procurement and premium industrial applications.
- Power Generation:Ultra-supercritical retrofits in Jiangsu and Zhejiang provinces absorb the majority of washed low-sulfur supply. State Grid five-year offtake contracts now specify sulfur content penalties exceeding spot price volatility exposure.
- Steel Production:Blast furnace coke demand from Baowu and HBIS operations requires precise volatile matter control. Shaanxi and Shanxi mines with integrated washing infrastructure capture this premium segment.
- Cement Manufacturing:Medium-heat coal specifications for rotary kiln operations tolerate higher ash content than power sector requirements.
- Industrial Heating:Distributed boiler operations in northern China provinces face MEE emissions standard pressure driving fuel switching or washing upgrades.
Power generation absorbs the largest volume share. Steel production commands the highest quality premiums and steepest specification escalation.
Quality Grade:
Regulatory compression is forcing binary outcomes between compliance-ready low-sulfur supply and stranded high-sulfur output.
- Low-Sulfur:Sulfur content below 0.8% meets MEE 2023 ambient air quality standards without flue gas desulfurization retrofit. Shanxi mines with 50-million-tonne washing plants dominate supply to coastal utilities.
- High-Sulfur:Output above 1.5% sulfur faces operating permit denials from Hebei and Shandong environmental bureaus. Stranded volumes pivot toward coal-to-chemicals pathways in Ningxia and Xinjiang.
- High-Heat:Calorific values exceeding 5,500 kcal/kg reduce coal intensity per megawatt-hour for ultra-supercritical units.
- Medium-Quality:Blended feedstock for industrial heating applications tolerates moderate sulfur and ash content.
Low-sulfur grades dominate installed washing capacity. High-heat specifications are climbing fastest as efficiency standards tighten.
Distribution Channel:
Integration depth versus market access determines channel selection across state-backed and county-level operators.
- Direct Sales:China Shenhua Energy leverages captive rail-port-mine networks to deliver cost advantages across coastal demand centers. Long-term contracting displaces spot procurement for major utilities.
- Distributors:County-level mines without logistics integration rely on provincial trading companies for Qinhuangdao port access.
- Online Platforms:Provincial coal exchanges in Shanxi and Shaanxi facilitate price discovery for medium-volume industrial offtake.
- Export:Limited volume flows through Mongolian border corridors and Qinhuangdao port terminals subject to SAMR pricing oversight.
Direct sales channel the largest volume flows. Online platforms are expanding most quickly as procurement departments seek price transparency alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance arbitrage is redistributing coal output across Chinese provinces as MEE emissions standards tighten unevenly, with washing infrastructure availability determining which regions retain operating permits and which face accelerated mine closures.
Shanxi Province
Ultra-supercritical retrofit demand from coastal utilities anchors thermal coal offtake from the Xishan and Datong fields. Provincial environmental bureaus enforce GB quality benchmarks that favor integrated 50-million-tonne washing plants. Taiyuan-Jinzhong industrial clusters concentrate coking coal preparation capacity serving Baowu Steel contracts.
Inner Mongolia
Ordos Basin open-cast operations supply base-load feedstock to State Grid Corporation's northern China grids. Dual carbon framework timelines compress mine lifecycles while subsidizing carbon capture pilot deployment. Hohhot-Baotou logistics corridors face rail bottleneck exposure during Qinhuangdao port maintenance cycles.
Shaanxi Province
Yulin field thermal coal secures five-year offtake contracts with Henan and Hubei provincial utilities replacing drought-depleted hydro capacity. SAMR pricing oversight shapes long-term contracting terms indexed to Qinhuangdao benchmarks. Xi'an-based preparation plant upgrades maintain grid supply security amid MEE sulfur limit tightening.
Shandong Province
Deep underground multi-seam operations at Jining mines compete on gas management expertise for metallurgical coal premiums. Provincial environmental permit denials strand high-sulfur output lacking flue gas desulfurization compatibility. Jinan-Qingdao industrial zones absorb washed coking coal for local blast furnace operations.
Hebei Province
Tangshan steel cluster demand for low-ash coking coal drives procurement from Shanxi and Shandong suppliers with integrated rail access. MEE 2023 ambient air quality standards deny operating permits to high-ash producers lacking washing infrastructure. Provincial resource tax reforms compress margins for county-level mines without captive logistics networks.
China Coal Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue coal-to-chemicals conversion and carbon capture service partnerships. State-backed operators with integrated rail-port-mine networks dominate volume flows, while county-level mines without logistics integration face consolidation pressure. Three archetypes define competitive positioning: vertically integrated energy conglomerates, provincial resource holding groups, and specialized deep-gas management operators. Capacity expansion and long-term offtake contracting represent the dominant competitive moves, displacing spot market procurement.
Within the integrated energy conglomerate tier, China Shenhua Energy Company Limited and China Coal Energy Company Limited anchor supply security through captive logistics networks. Shaanxi Coal Industry Company Limited occupies a position exemplifying provincial resource holding group consolidation. These entities represent the capital deployment capacity required for MEE-compliant washing upgrades and ultra-supercritical retrofit feedstock contracts.
| Leading Market Players |
|---|
| China Shenhua Energy Company Limited |
| China Coal Energy Company Limited |
| Shaanxi Coal Industry Company Limited |
| Yanzhou Coal Mining Company Limited |
| China Power International Development Limited |
| Huadian Power International Corporation Limited |
| Jinneng Holding Shanxi Coal Industry Co., Ltd. |
| China Coal Xinji Energy Co Ltd. |
| Anhui Hengyuan Coal Industry and Electricity Power Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
State Grid Corporation and China Huaneng Group procurement concentration anchors long-term offtake contracting indexed to Qinhuangdao port benchmarks, compressing spot market liquidity and elevating sulfur-content penalties above price volatility exposure.
Pricing Analysis
Direct sales channel margins absorb rail-port-mine integration premiums, with distributor markups stranded where county-level mines lack captive logistics. Price differentiation hinges on GB quality certification tier and washing infrastructure depth, with low-sulfur grades commanding scarcity premiums as MEE standards tighten. Cost compression runs through high-sulfur output rejected by coastal utilities, forcing stranded volumes toward coal-to-chemicals conversion. County-level mines without preparation plant access exhibit highest price sensitivity, while integrated state-backed operators capture margin stability through five-year volume commitments.
Supply Chain Analysis
Rail freight costs from Ordos Basin to Qinhuangdao port terminals shape delivered cost arbitrage across northern China demand centers. Supply concentrates in Shanxi, Inner Mongolia, and Shaanxi provinces, with raw coal flows drawing from deep-gas managed underground complexes and open-cast operations. Single-source vulnerability concentrates in Qinhuangdao port maintenance cycles and Mongolian border corridor disruptions. Distribution runs through provincial trading companies for unwashed output and captive rail networks for integrated majors.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Beijing's dual carbon framework operates as a regulatory compounder, with MEE emissions standards tightening across the analysis window to force washing investment and carbon capture deployment.
For Market Incumbents: Deepen backward integration into rail-port infrastructure to sustain delivered cost advantages against county-level competitors. Accelerate preparation plant upgrades in Shanxi and Shaanxi to capture displaced volume from Hebei and Shandong permit denials. Hydrogen substitution pilots at Baowu Steel threaten metallurgical coal pricing power; diversify into carbon capture service partnerships to offset stranded asset risk.
For New Entrants and Emerging Players: The premium-economy price-point gap in washed low-sulfur thermal coal offers white-space entry through coal-to-chemicals conversion partnerships in Ningxia and Xinjiang. Target stranded high-sulfur output rejected by power utilities, securing chemical sector offtake contracts for coal-to-olefins pathways. Pursue MIIT smart mine certification to access 5G-enabled automation subsidies and lower labor intensity benchmarks.
For Investors and Strategic Acquirers: State-backed energy conglomerates are the most active acquirer in this space, consolidating county-level mines lacking MEE compliance infrastructure. Long-term viability hinges on washing capacity depth and carbon capture pilot deployment timelines. Watch the pace of ultra-supercritical retrofit completion as the inflection signal for base-load coal dispatch priority against renewables and nuclear.
| Strategic Initiative | Industry Significance |
|---|---|
| Washing Capacity Expansion | Shanxi and Shaanxi operators capture displaced volume from Hebei permit denials. |
| Carbon Capture Pilot Deployment | Sinopec and China Energy partnerships in Ordos Basin create enhanced oil recovery revenue streams. |
| Long-term Offtake Contracting | State Grid five-year agreements indexed to Qinhuangdao benchmarks displace spot procurement. |
| Intelligent Mining Certification | MIIT subsidies for 5G-enabled autonomous haulage lower labor intensity in deep Shandong complexes. |
| Coal-to-Chemicals Pivot | Ningxia and Xinjiang pilot plants absorb stranded high-sulfur output rejected by power utilities. |
Methodological Framework
Coverage spans Shanxi, Inner Mongolia, Shaanxi, Shandong, and Hebei provinces, with primary inputs from each region's mine operators, State Grid procurement officers, and provincial environmental bureau officials. Secondary validation draws from SAMR pricing oversight disclosures, MEE emissions standard revisions, and China Energy carbon capture pilot announcements. Bottom-up volume modeling triangulates against top-down provincial production statistics from national energy administration sources.
Granularity extends to product type, quality grade, and end-use segments across the projection horizon, with washing capacity utilization and carbon capture deployment timelines as coal-specific forecast inputs. CAGRs derive from fitted growth curves applied to base-year market sizing, cross-referenced against dual carbon policy milestone schedules and ultra-supercritical retrofit completion rates.
Caveats apply where MEE enforcement intensity or hydrogen substitution acceleration could materially shift the outlook for metallurgical coal demand. Stakeholders should weight assumptions against their own operating context and provincial resource tax exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Methane Market
Fuels
Fuel Oxygenate Market
Fuels
Fuel Quality Testing Market
Fuels
Aerospace Aviation Fuels Market
Fuels
Synthetic Natural Gas (SNG) Market
Fuels
Hydrogen Cylinder Market
Fuels
Global Industrial Burner Market
Fuels
Europe Aviation Fuel Market
Fuels
Brazil LNG Market
Fuels
Briquette Market
Fuels
Europe Renewable Aviation Fuel Market
Fuels
CNG Dispenser Market
Fuels
Coal Trading Market
Fuels
Global Methane Hydrate Market
Fuels
South Africa Bunker Fuel Market
Fuels
Heavy Fuel Oil Market