
 Coal Trading Market | 2026-2036
Coal Trading Market Size, Share, and Industry Trends Forecast 2026-2036
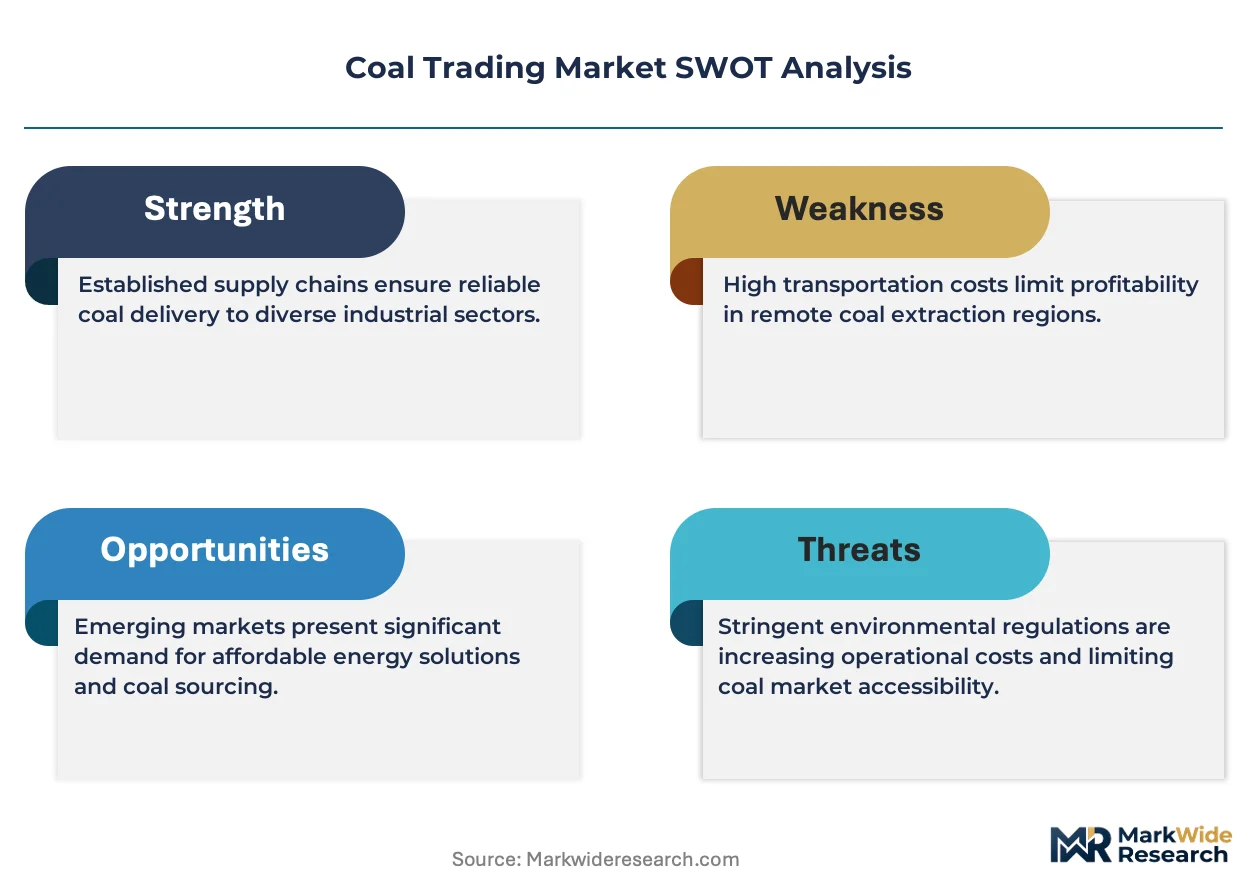
Coal Trading Market Analysis
Australian thermal coal exporters is rebalancing supply commitments across Asian buyer portfolios as Indonesian miners expand seaborne output. Glencore Plc leverages integrated mining-to-shipping assets across Colombian and South African basins. Trafigura Group Pte Ltd anchors physical trading liquidity through term offtake agreements with Indian power generators. Vitol Holding B.V. competes aggressively in Atlantic basin arbitrage, moving cargoes between European and Asian pricing hubs.
Coal trading encompasses the commercial exchange of solid fossil fuels graded by calorific value, ash content, and sulphur concentration for combustion or metallurgical reduction. Thermal coal with calorific values above 5,500 kcal/kg serves baseload power generation, while coking coal with low volatile matter and specific swelling indices feeds blast furnace ironmaking. Metallurgical coal commands premium pricing in bilateral contract structures due to stringent quality thresholds and limited substitute availability. Exchange-traded volumes in thermal grades are expanding as utilities seek price transparency, though over-the-counter transactions still dominate coking coal procurement for steel manufacturers.
Indonesia's MEMR, India's CEA, and China's NMPA each enforce divergent sulphur and ash thresholds that fragment tradable coal specifications across basins. These regulatory disparities force traders to maintain quality-blending infrastructure at multiple discharge ports. Stakeholders must monitor evolving carbon border adjustments and emerging emissions accounting standards that threaten to reclassify certain coal grades as non-compliant mid-contract.
Market Dynamics
Quality fragmentation across Indonesian, Australian, and Russian export corridors is forcing traders to maintain parallel blending infrastructure at multiple discharge ports. China's NMPA-aligned sulphur caps and India's CEA ash thresholds now diverge sufficiently that single-origin cargoes rarely clear both markets without intermediate processing.
Growth Catalysts
- Blast furnace expansion:Indian steel manufacturers are scaling metallurgical coal procurement as domestic blast furnace capacity adds new demand corridors for Australian and US coking coal grades.
- CEA emission compliance:India's Central Electricity Authority mandates are tightening sulphur and ash thresholds for imported thermal coal, creating structured demand for low-impurity Indonesian and Australian supply.
- Seaborne logistics:Indonesian export corridor investments in Kalimantan loading terminals are expanding vessel loading rates and reducing demurrage exposure for East Asian power utilities.
Market Restraints
- Input cost volatility:Bunker fuel price swings and Panama Canal transit constraints are compressing arbitrage margins on Atlantic-to-Pacific coal movements.
- Supply concentration risk:Indonesian thermal coal production concentrates in South Kalimantan and East Kalimantan basins, exposing buyers to simultaneous weather-related loading disruptions.
- Regulatory friction:China's NMPA environmental standards are tightening mid-contract, forcing traders to absorb quality-downgrade penalties or divert non-compliant cargoes.
Strategic Opportunities
- Underpenetrated corridors:Mozambique's Tete basin metallurgical coal offers coking coal diversification for Indian and Southeast Asian blast furnace operators seeking Australian supply alternatives.
- Carbon border positioning:The EU Carbon Border Adjustment Mechanism creates early-mover advantage for traders building certified low-emission coal blending and methane monitoring capabilities.
- Technology convergence:Blockchain-based cargo documentation and automated sampling systems are converging to reduce documentary fraud and quality disputes in CIF transactions.
Industry Challenges
- Blending infrastructure capex:Quality-divergent regulations across China, India, and Southeast Asia require capital deployment at multiple discharge ports for sulphur and ash adjustment.
- Certification timeline compression:Emerging emissions accounting standards from ISO and national regulators are shortening the window for mid-contract cargo reclassification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coal Trading Market |
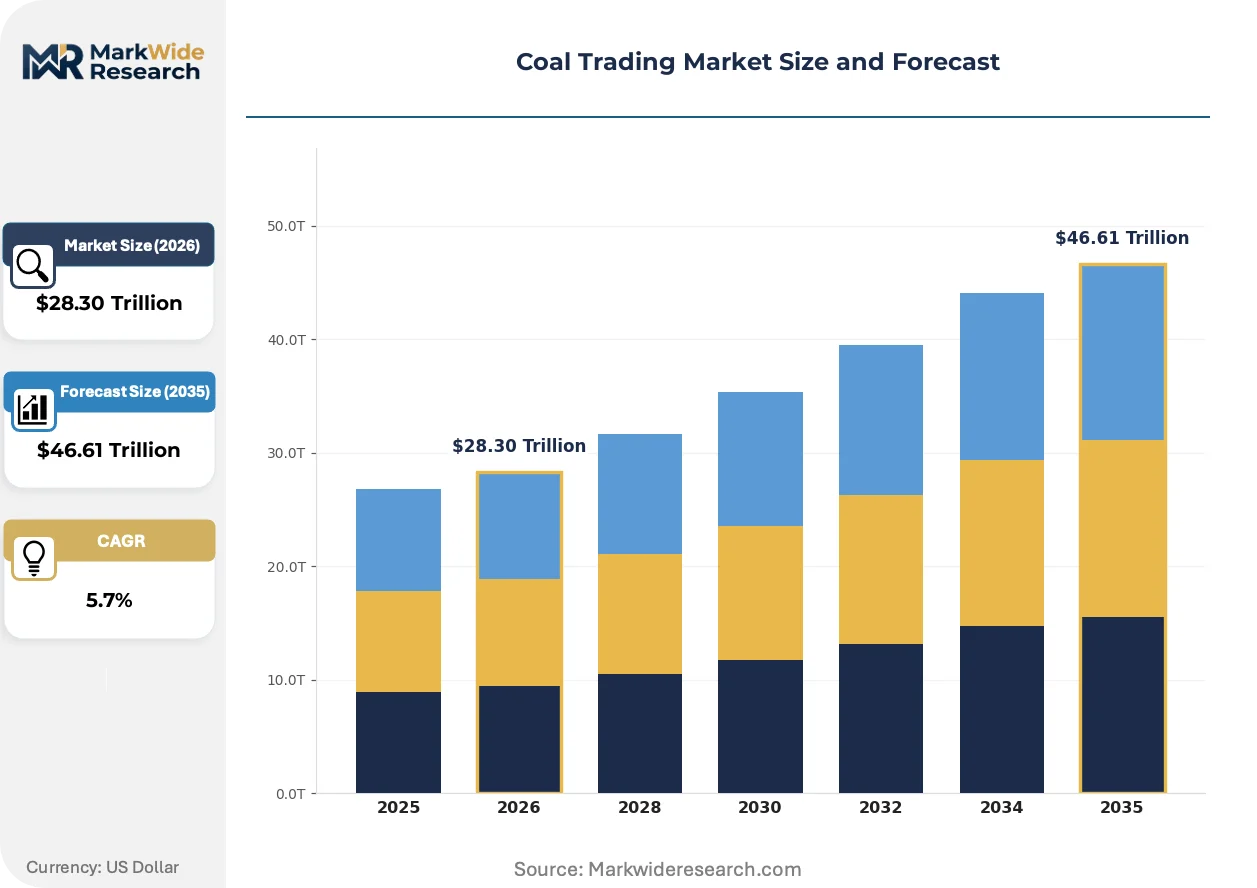
| Market Size in 2026 | $28.30 Trillion |
| Market Size in 2035 | $46.61 Trillion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Coal, Coking Coal, Anthracite, Metallurgical Coal End User: Power Plants, Steel Manufacturers, Cement Producers, Industrial Utilities Trading Platform: Exchange-Traded, Over-the-Counter, Bilateral Contracts, Spot Market Quality Grade: High Calorific Value, Low Calorific Value, Sulphur Content, Ash Content |
| Companies Covered | Trafigura Group Pte Ltd, Glencore Plc, Mercuria Energy Group, Vitol Holding B.V, Mitsubishi Corporation RtM Japan Ltd, China Shenhua Energy Company Limited, Gunvor Group, ICBC Standard Bank, COALTRA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coal Trading Market Emerging Trajectories
Digital infrastructure and regulatory precision are compressing settlement cycles and redefining tradable coal specifications. Physical traders now compete on data transparency and quality verification speed as much as on freight optimization.
Automated sampling and analysis systems are expanding into discharge port operations, replacing manual grab-sampling with continuous on-belt analysers. Indian power utilities at Mundra and Hazira are adopting these systems to accelerate customs clearance and reduce stockpile detention. This compression of quality verification is expanding into contract structures that tie pricing to real-time calorific value rather than declared specifications.
China's NMPA is tightening sulphur and mercury thresholds for thermal coal imports, forcing traders to pre-screen cargoes at load ports. The industrial consequence is a bifurcation between compliant and non-compliant supply pools, with Australian and Russian exporters capturing premium placement in Chinese procurement. Steel-grade coking coal faces parallel pressure as China's MIIT mandates lower volatile matter ceilings for blast furnace injection coal.
Indian power generators are consolidating procurement through term offtake agreements with embedded price collars, displacing spot-market exposure for baseload supply. State-owned generation companies in Gujarat and Maharashtra are leading this consolidation, locking in Indonesian supply through five-year contracts with annual reopener clauses. This contractual shift is most visible in the western coastal belt, where import dependency exceeds domestic rail-delivered supply.
Coal Trading Market Segmentation
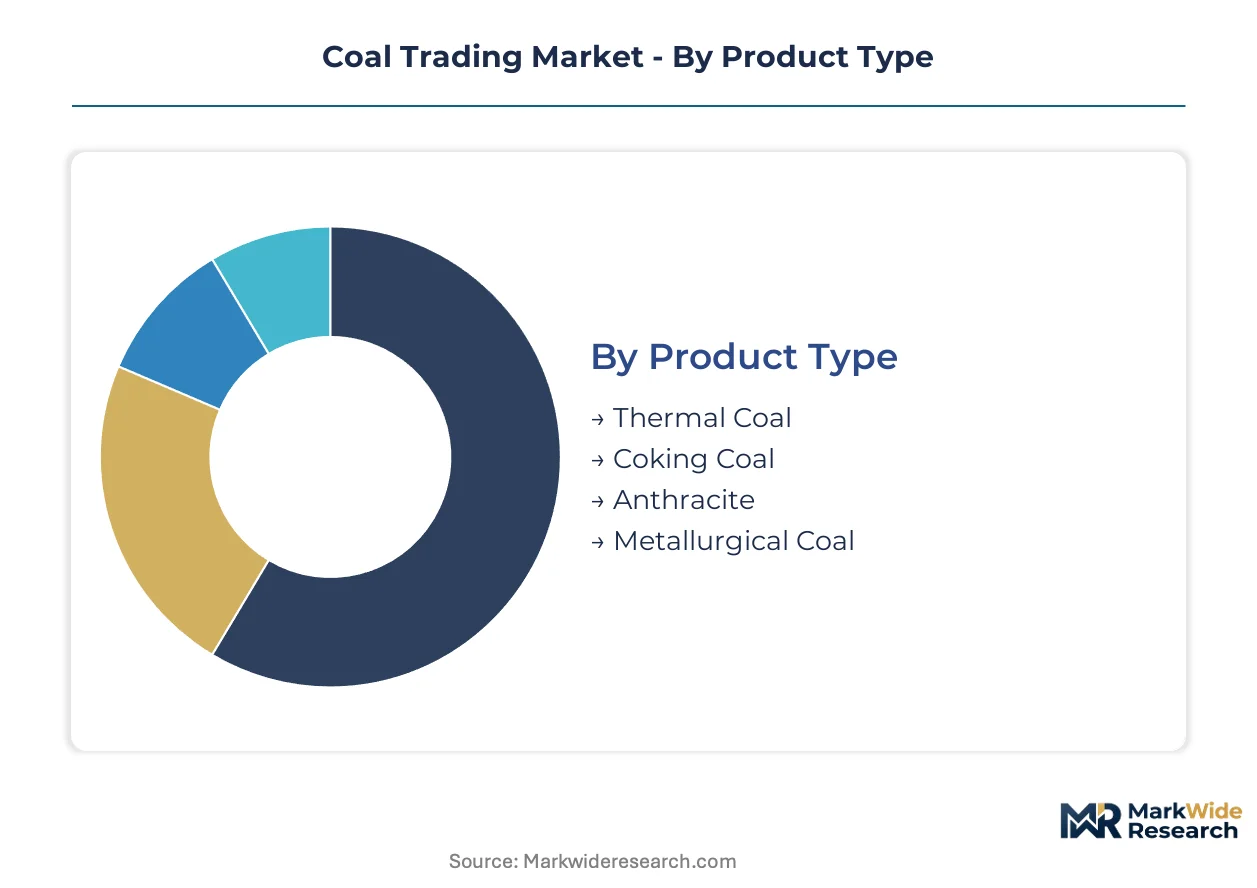
Coal trading segmentation reflects divergent capital requirements across mining, logistics, and quality-certification infrastructure. Traders must match segment-specific investment profiles to buyer procurement structures in fragmented regulatory environments.
Product Type:
Thermal coal extraction and export terminal development demands the heaviest upfront capital deployment, with dedicated loading infrastructure and stockpile management systems.
- Thermal Coal:Graded by calorific value above 5,500 kcal/kg for baseload power generation. Demand concentrates in Indonesian export corridors serving East Asian utilities, driven by CEA-mandated emission thresholds in India that filter out high-ash alternatives.
- Coking Coal:Metallurgical-grade material with low volatile matter and specific swelling indices for blast furnace ironmaking. Procurement is intensifying among Indian steel manufacturers expanding blast furnace capacity, constrained by limited Australian and US supply substitution.
- Anthracite:High-carbon, low-volatile smokeless coal for residential heating and specialized industrial applications. China's NMPA sulphur caps restrict import eligibility to premium grades.
- Metallurgical Coal:Premium-priced bilateral contract structures dominate due to stringent quality thresholds and scarce substitute availability for steel-grade reduction processes.
Most installed capacity flows through Thermal Coal. Expansion is steepest in Coking Coal.
End User:
Procurement scale and contract duration vary sharply across buyer categories, with power generators locking in term supply while industrial users retain spot-market flexibility.
- Power Plants:Baseload generators in Gujarat and Maharashtra consolidate procurement through five-year term offtake agreements with embedded price collars. State-owned companies displace spot exposure for Indonesian supply through annual reopener clauses.
- Steel Manufacturers:Blast furnace operators in India scale metallurgical coal procurement as domestic capacity expands, sourcing Australian and US coking coal grades through quality-specific bilateral structures.
- Cement Producers:Clinker kilns consume mid-calorific thermal grades with moderate ash tolerance, procuring through diversified spot and short-term contract mixes.
- Industrial Utilities:Process heat users in chemical and manufacturing sectors source lower-grade thermal coal with flexible quality specifications.
Contract volume concentrates with Power Plants. Procurement reform is accelerating fastest among Steel Manufacturers.
Trading Platform:
Platform selection determines counterparty risk exposure, price transparency, and settlement velocity for physical cargo movements.
- Exchange-Traded:Standardized thermal grade contracts on regional commodity exchanges provide price discovery for utilities seeking benchmark transparency. Volumes are expanding as Indonesian and Australian exporters seek reduced bilateral negotiation overhead.
- Over-the-Counter:Bilateral negotiations dominate coking coal procurement for steel manufacturers, with customized quality specifications and delivery terms. Trafigura Group Pte Ltd anchors liquidity through term offtake agreements with Indian power generators in this channel.
- Bilateral Contracts:Long-term supply agreements with quality-adjustment clauses and force majeure provisions structure relationships between Indonesian miners and East Asian utilities.
- Spot Market:Short-term cargo purchases for supply disruption coverage and arbitrage opportunities, compressed by bunker fuel volatility and Panama Canal transit constraints.
Transaction volume flows predominantly through Bilateral Contracts. Platform migration is most pronounced toward Exchange-Traded structures.
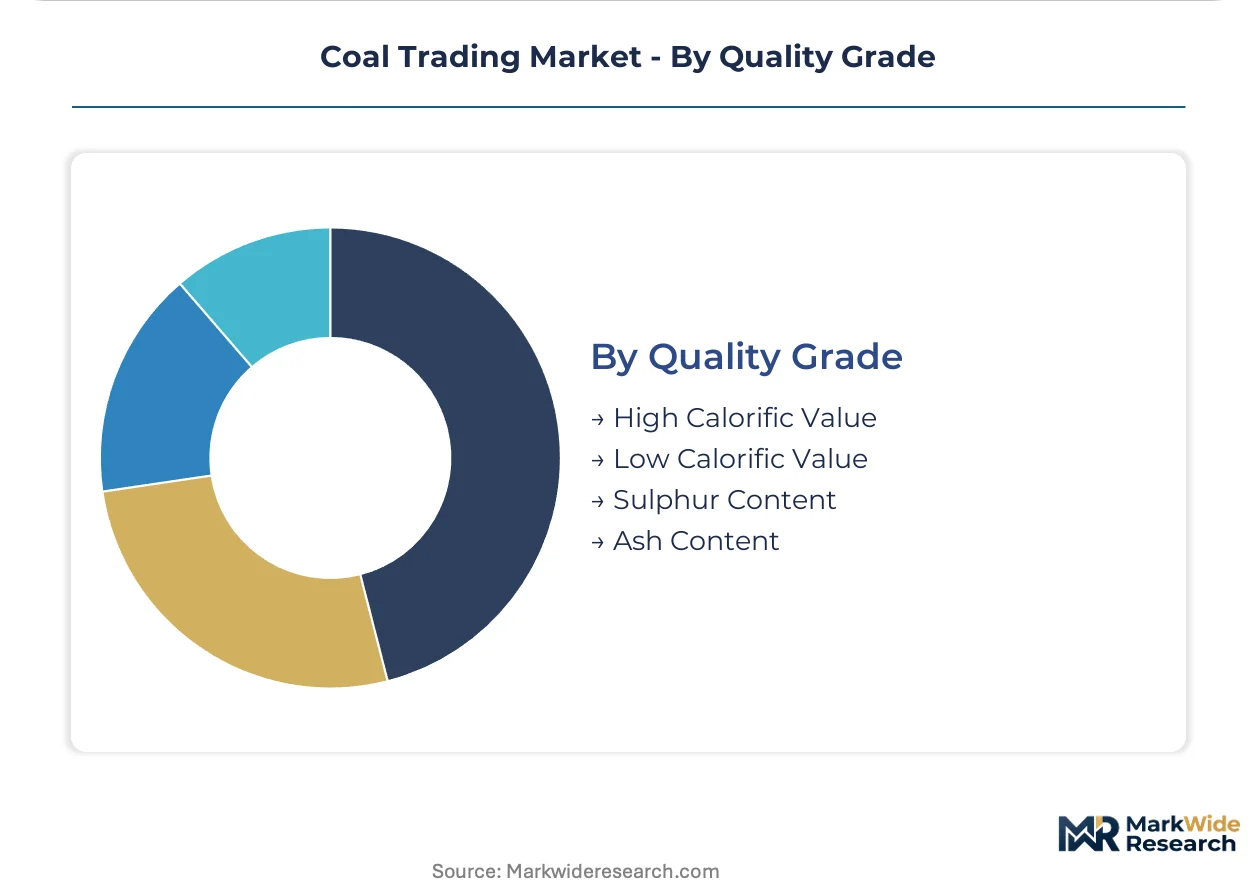
Quality Grade:
Regulatory divergence across import jurisdictions fragments tradable specifications and forces parallel blending infrastructure investment.
- High Calorific Value:Coal exceeding 5,500 kcal/kg commands premium placement in Chinese procurement under NMPA-aligned environmental standards. Australian exporters capture structured demand from compliant supply pools.
- Low Calorific Value:Sub-5,000 kcal/kg grades serve price-sensitive Southeast Asian utilities with less stringent emission mandates, sourced primarily from Indonesian Kalimantan basins.
- Sulphur Content:Sulphur thresholds determine Chinese import eligibility, with pre-screening now required at load ports. Traders absorb quality-downgrade penalties or divert non-compliant cargoes to alternative markets.
- Ash Content:India's CEA mandates tightening ash thresholds for imported thermal coal, creating filtered demand for low-impurity Indonesian and Australian supply.
Certification complexity concentrates in Sulphur Content compliance. Specification tightening is advancing fastest on Ash Content thresholds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's NMPA-aligned sulphur caps diverge sharply from India's CEA ash mandates, fragmenting tradable specifications and forcing traders to maintain parallel blending infrastructure at discharge ports across both markets.
China
Blast furnace operators and coastal power utilities drive thermal coal procurement through state-owned trading arms. NMPA environmental standards tighten mid-contract sulphur and mercury thresholds, forcing pre-screening at Australian and Indonesian load ports. Qingdao and Rizhao terminals concentrate quality-verification infrastructure for compliant supply pools.
India
Steel manufacturers scale metallurgical coal procurement as domestic blast furnace capacity expands. CEA emission mandates tighten sulphur and ash thresholds for imported thermal coal, filtering demand toward low-impurity Indonesian and Australian grades. Mundra and Hazira ports deploy automated sampling systems to accelerate customs clearance for Gujarat and Maharashtra generators.
Indonesia
Kalimantan basin miners expand seaborne output through MEMR-regulated export corridors serving East Asian power utilities. MEMR production licensing and royalty structures shape cost competitiveness for sub-5,000 kcal/kg grades. South Kalimantan and East Kalimantan loading terminals reduce demurrage exposure through expanded vessel loading rates.
Australia
Newcastle and Gladstone exporters capture premium placement in Chinese procurement under NMPA-compliant high-calorific specifications. Queensland coking coal producers supply Indian blast furnace expansion through bilateral contract structures with quality-adjustment clauses. Port infrastructure investments target reduced loading turnaround for capesize vessels.
South Africa
Richards Bay Coal Terminal operators rebalance supply commitments between Atlantic and Indian Ocean buyers as bunker fuel volatility compresses arbitrage margins. Domestic rail constraints and Transnet port capacity limit export expansion despite European utility demand. Glencore-anchored mining assets supply blended grades for sulphur-sensitive jurisdictions.
Coal Trading Market Vendor Landscape
Indonesian producers anchor the volume-driven tier; Australian and US specialists hold premium-grade positioning through quality-differentiated contract structures. The vendor base concentrates around integrated mining-to-shipping conglomerates, independent physical traders, and state-linked procurement arms. Three archetypes dominate: basin-integrated miners with captive terminal access, arbitrage-focused traders with freight optimization capabilities, and utility-aligned offtake specialists with term contract portfolios. Competitive moves center on quality-blending infrastructure deployment at discharge ports and carbon-border certification capability building.
Within the integrated conglomerate tier, Glencore Plc and Trafigura Group Pte Ltd exemplify asset-heavy positioning across Colombian, South African, and Australian basins. Vitol Holding B.V. occupies the arbitrage-specialist vector, moving cargoes between European and Asian pricing hubs. These three entities represent divergent capital deployment strategies—captive mining assets versus freight-optimized trading books versus term-liquidity provision—each extracting margin from different points in the physical supply chain.
| Leading Market Players |
|---|
| Trafigura Group Pte Ltd |
| Glencore Plc |
| Mercuria Energy Group |
| Vitol Holding B.V |
| Mitsubishi Corporation RtM Japan Ltd |
| China Shenhua Energy Company Limited |
| Gunvor Group |
| ICBC Standard Bank |
| COALTRA |
| Others |
Supply Flow & Price Mechanics
Automated sampling systems at discharge ports are compressing quality verification cycles and simultaneously raising capital thresholds for market participation while concentrating procurement power among utilities with integrated infrastructure. This technological shift tightens margins for traders lacking real-time calorific value verification capabilities while rewarding basin-integrated miners with captive terminal access.
Pricing Analysis
Capacity additions in Indonesian Kalimantan basins are reshaping price floors for sub-5,000 kcal/kg thermal grades serving Southeast Asian utilities. Three-tier pricing structure across premium Australian high-calorific, standard Indonesian mid-grade, and economy Russian low-ash tiers reflects quality-adjustment clauses and NMPA sulphur compliance premiums. Pricing pressure stems from bunker fuel volatility compressing Atlantic-to-Pacific arbitrage margins. Cement producers and industrial utilities exhibit highest price sensitivity; Indian steel manufacturers show lowest sensitivity due to limited coking coal substitute availability.
Supply Chain Analysis
Regional distribution centers at Mundra, Hazira, Qingdao, and Rizhao form hub-and-spoke patterns for quality-blending and customs clearance acceleration. Geographic supply concentrates in Indonesia, Australia, and Russia for thermal grades; Australia and the United States for metallurgical grades. Raw material dependencies include diesel for mine haulage, explosives for overburden removal, and marine fuel for vessel propulsion. Single-source vulnerability runs through Indonesian South Kalimantan and East Kalimantan basins exposed to simultaneous weather disruptions. Distribution runs through term offtake agreements with annual reopener clauses dominating downstream structure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where India's CEA emission mandates and China's NMPA environmental standards continuously tighten quality thresholds and fragment tradable specifications.
For Market Incumbents: Lock in discharge port blending infrastructure at Mundra, Hazira, Qingdao, and Rizhao to preempt quality-downgrade penalties from mid-contract regulatory tightening. Anchor term offtake agreements with Indian state-owned generators through five-year contracts with embedded price collars. Absorb margin pressure from bunker fuel volatility by securing capesize vessel charters on multi-year fixtures. For New Entrants and Emerging Players: India's CEA emission mandates open a window for low-ash Indonesian and Australian supply specialists to capture filtered demand from Gujarat and Maharashtra generators. Target Mozambique's Tete basin metallurgical coal corridors as the most penetrable geography for Australian coking coal substitution. Pursue carbon border certification capabilities as the go-to-market angle for EU-bound supply positioning. For Investors and Strategic Acquirers: Valuations sit cheapest among independent physical traders lacking integrated mining assets but holding freight optimization capabilities and term contract liquidity. Long-term viability hinges on regulatory adaptation speed across multiple jurisdictions. Acquire basin-integrated miners with captive terminal access and NMPA-compliant quality pools. Watch for EU Carbon Border Adjustment Mechanism implementation pace as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Quality-Blending Infrastructure Deployment | CEA and NMPA divergence forces parallel capital deployment at multiple discharge ports. |
| Carbon Border Certification Program | EU CBAM creates early-mover advantage for certified low-emission coal and methane monitoring. |
| Automated Sampling System Integration | Indian utilities at Mundra and Hazira adopt continuous on-belt analysers to compress settlement cycles. |
| Term Offtake Agreement Expansion | Trafigura anchors liquidity through five-year contracts with annual reopener clauses for baseload supply. |
| Alternative Basin Supply Diversification | Mozambique's Tete basin offers metallurgical coal diversification for Indian blast furnace operators. |
Methodological Framework
Multiple input streams — physical cargo movement data, regulatory filing analysis, and freight rate benchmarks — were reconciled through bottom-up and top-down triangulation. Primary interviews with coal trading desk heads, utility procurement officers, and port terminal operators were validated against secondary sources including customs trade databases, MEMR production licensing records, and CEA emission compliance filings. Cross-reference with bunker fuel price indices and vessel charter rate assessments anchored cost structure assumptions.
Data-stream reconciliation across product type, end user, trading platform, and quality grade dimensions generated volume and value outputs across the projection horizon. CAGRs were derived from segment-level growth trajectory modeling incorporating blast furnace capacity expansion timelines, MEMR export corridor investments, and NMPA threshold tightening schedules. Forecast inputs included Indonesian Kalimantan loading terminal capacity additions and Indian state-owned generator procurement consolidation patterns.
Revisions become necessary when regulatory threshold tightening accelerates beyond modeled schedules, bunker fuel price volatility exceeds historical bands, or carbon border mechanisms expand coverage faster than anticipated. Forecasts reflect documented assumptions on quality grade fragmentation and infrastructure deployment timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
North America Aviation Fuel Market
Fuels
Waste-Derived Pyrolysis Oil Market
Fuels
Refuse Derived Fuel Market
Fuels
India Liquified Petroleum Gas (LPG) Market
Fuels
Marine Fuel Filter Market
Fuels
Brazil Bunker Fuel Market
Fuels
LPG Cylinder Manufacturing Market
Fuels
Fuel Quality Testing Market
Fuels
CNG Dispenser Market
Fuels
South Africa Bunker Fuel Market
Fuels
India Bunker Fuel Market
Fuels
Asia-Pacific Bunker Fuel Market
Fuels
Asia-Pacific Commercial Aircraft Aviation Fuel Market
Fuels
Germany Bunker Fuel Market
Fuels
Gas to Liquid (GTL) Market
Fuels
Global Gas Cylinder Market