
 India Coal Market | 2026-2036
India Coal Market Size, Share, and Industry Trends Forecast 2026-2036
India Coal Market Outlook
Long-term fuel supply agreements bundled with dedicated railway corridors is repositioning procurement economics for large buyers. Coal India Limited leverages its monopoly over domestic reserves to sustain volume commitments to state grids. NTPC Ltd anchors its generation portfolio with captive coal linkages and pithead stations. Jindal Steel & Power Ltd competes through integrated mining-to-steel operations that reduce logistics exposure.
India coal encompasses combustible sedimentary rock with carbon content ranging from lignite at 25-35% to anthracite exceeding 90%, extracted through underground bord-and-pillar or opencast mechanized methods for thermal and metallurgical applications. Bituminous grades dominate power generation feedstock due to higher calorific value and established washery infrastructure. Steel production applications command premium pricing through coking coal blends, while carbon capture represents an emerging application segment where policy incentives are building project pipelines.
Ministry of Coal allocation frameworks, CEA technical standards for thermal efficiency, and MoEFCC environmental clearances collectively shape mine approvals, plant dispatch priorities, and emission compliance costs. BIS quality norms for coal grading affect contract pricing and import substitution calculations. Stakeholders must monitor auction dynamics for commercial mining blocks and the pace of renewable dispatch obligations that alter baseload coal economics.
Market Dynamics
Long-term fuel supply agreements bundled with dedicated railway corridors are repositioning procurement economics for large buyers. Coal India Limited leverages its monopoly over domestic reserves to sustain volume commitments to state grids.
Growth Catalysts
- CEA Technical Standards:The Central Electricity Authority mandates higher thermal efficiency benchmarks, compelling power utilities to source beneficiated coal and upgrade combustion systems.
- Jharkhand-Odisha-Chhattisgarh Clustering:Captive mining blocks and pithead power stations concentrate demand in these eastern states, reducing logistics costs and enabling direct mine-to-plant conveyor systems.
- Coal Beneficiation Mandates:Ministry of Environment emission norms require washed coal for plants beyond 500 kilometers from mines, expanding washery capacity and improving combustion quality.
Market Restraints
- Domestic Supply Concentration:Coal India Limited controls over 80 percent of domestic production, creating single-source dependency and limiting price negotiation leverage for buyers.
- Import Substitution Calculations:BIS quality norms for coal grading create friction between domestic washery output and seaborne coking coal specifications required by integrated steel plants.
- Renewable Dispatch Obligations:State-level renewable purchase obligations compress baseload coal plant utilization rates, stranding generation assets in Maharashtra and Gujarat.
Strategic Opportunities
- Carbon Capture Project Pipelines:Policy incentives under the National Clean Energy Fund are building demonstration projects at NTPC's Vindhyachal and Ramagundam stations.
- Commercial Mining Auctions:Ministry of Coal allocation frameworks now permit private commercial mining without end-use restrictions, opening stranded blocks in Odisha to merchant power producers.
- Metallurgical Coal Blends:Steel production applications command premium pricing, creating white space for domestic coking coal washeries to displace Australian imports at coastal mills.
Industry Challenges
- Environmental Clearance Timelines:MoEFCC forest clearance procedures for opencast expansions in Chhattisgarh routinely extend 24-36 months, delaying project commissioning.
- Railway Rake Availability:Dedicated freight corridor capacity constraints force thermal plants in Uttar Pradesh and Madhya Pradesh to maintain costly coal inventory buffers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Coal Market |
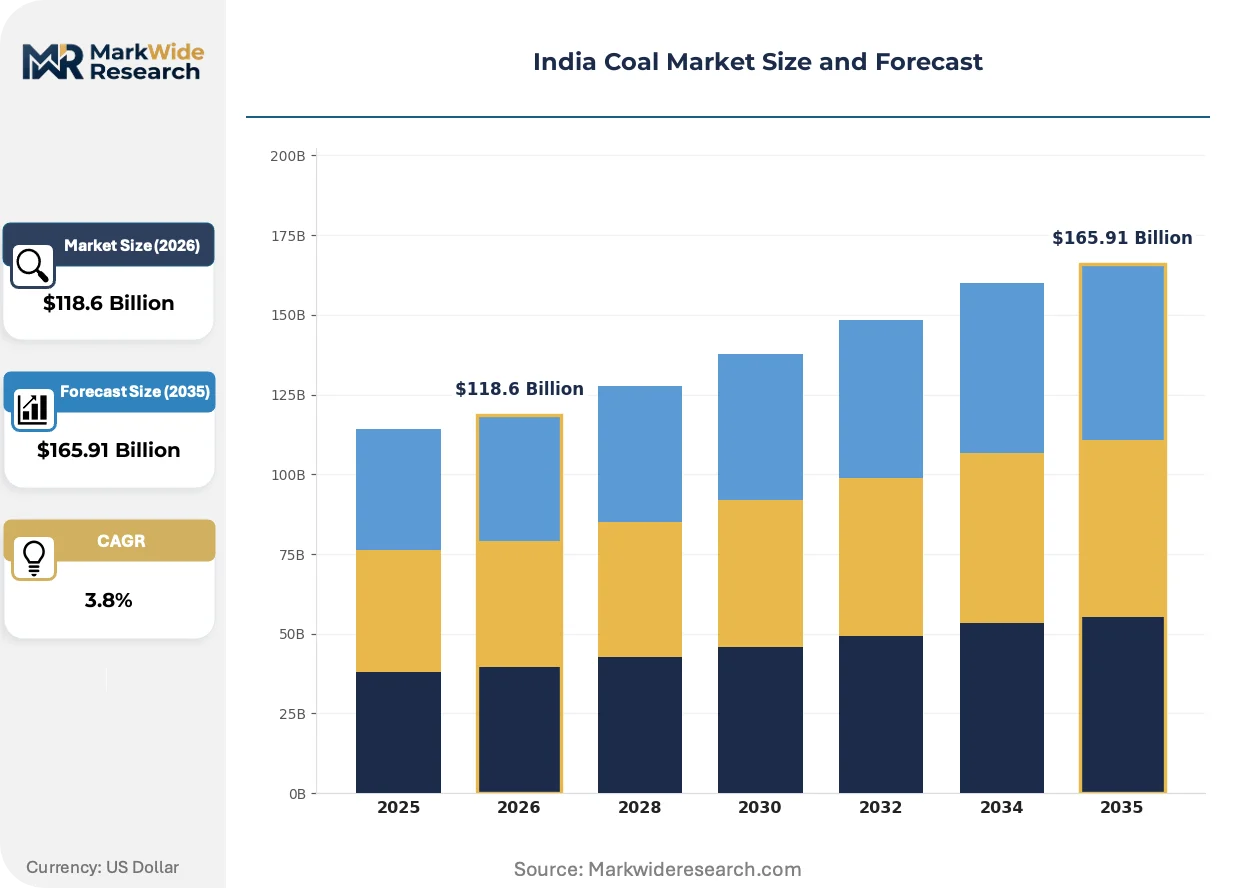
| Market Size in 2026 | $118.6 Billion |
| Market Size in 2035 | $165.91 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anthracite, Bituminous, Sub-bituminous, Lignite End User: Power Generation, Cement Manufacturing, Steel Production, Chemical Industry Delivery Mode: Rail Transport, Road Transport, Barging, Conveyor System Application: Electricity Generation, Char Production, Industrial Heating, Carbon Capture |
| Companies Covered | Coal India Limited, Singareni Collieries Company Limited, NTPC Ltd, NLC India Ltd, JSW Energy Limited, Adani Power Ltd, Jindal Steel & Power Ltd, Bharat Coking Coal Limited, NMDC Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Coal Market Strategic Shifts
Automation and emission control technologies are reshaping extraction and combustion economics across the value chain. Digital monitoring systems now track ash content and calorific value in real time.
Flue-gas desulfurization retrofitting is electrifying compliance strategies for aging supercritical units. NTPC and state gencos in Tamil Nadu and Andhra Pradesh are installing limestone-gypsum systems to meet SOx norms. This capital deployment is compressing the operational life of sub-500 MW plants that cannot justify scrubber economics.
MoEFCC tightened particulate matter emission standards for thermal power plants in 2015, with full compliance deadlines extended through 2022. The regulation forced installation of electrostatic precipitator upgrades and low-NOx burners. Plants in the National Capital Region faced the strictest enforcement, driving early retirement of Dadri and Badarpur units.
Buyers are consolidating procurement through centralized fuel management platforms rather than bilateral negotiations with individual subsidiaries. State discoms in Rajasthan and Punjab now aggregate demand through joint tendering mechanisms, displacing the fragmented linkage allocation system. This concentration is most visible among coastal utilities with dual-fuel flexibility.
India Coal Market Segmentation
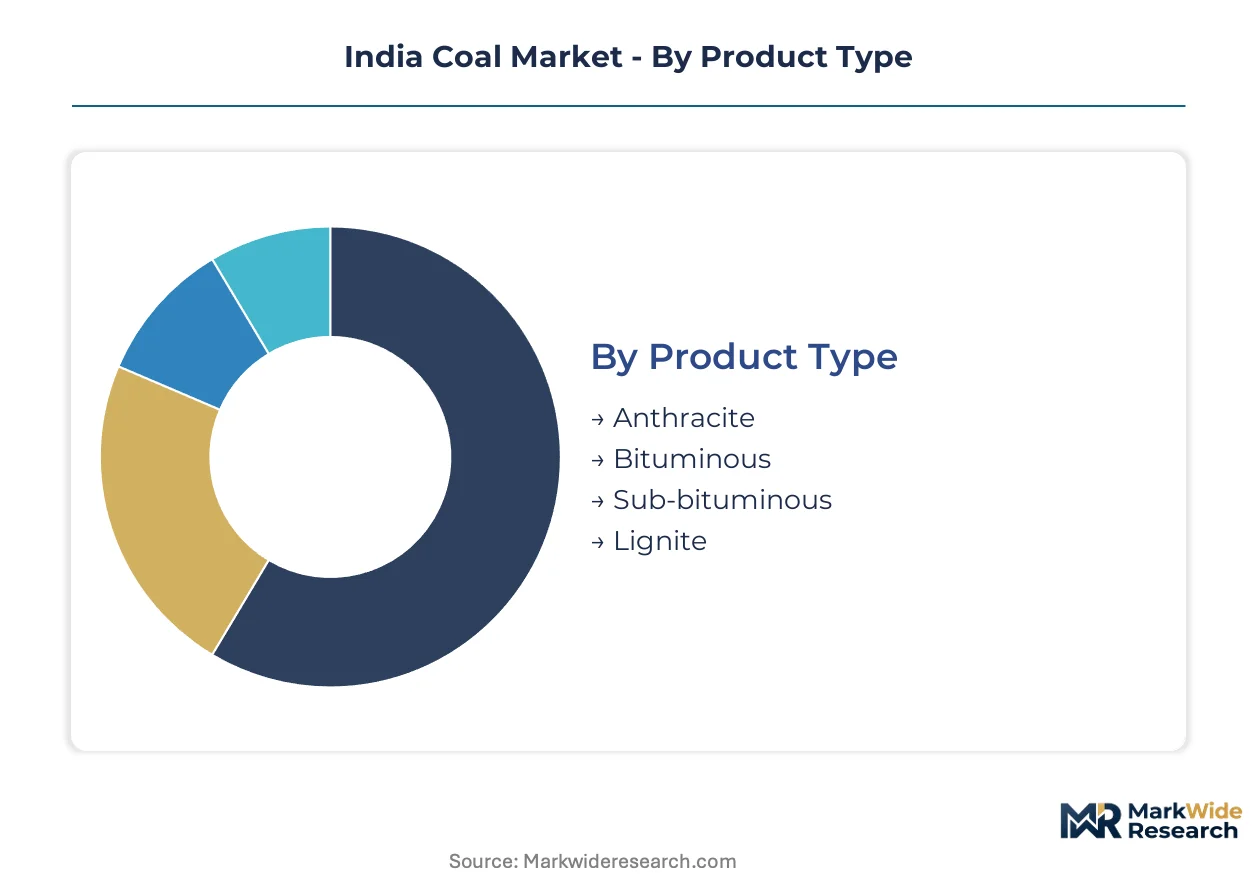
India's coal market segments reflect the geological diversity of eastern reserves and the logistical imperatives of moving bulk fuel across congested rail networks. Understanding these divisions reveals where beneficiation investments, transport infrastructure, and emission compliance costs concentrate.
Product Type:
Supply concentration in Jharkhand, Odisha, and Chhattisgarh determines which grades reach which buyers through dedicated washery corridors.
- Bituminous:Carbon content ranges 45-86% with calorific values of 24-35 MJ/kg, making it the preferred feedstock for NTPC's supercritical units. Demand clusters at pithead stations in Singrauli and Korba where mine-mouth plants eliminate rail freight exposure.
- Lignite:Moisture-heavy deposits at 25-35% carbon content power Tamil Nadu's Neyveli Lignite Corporation complex. Lower energy density confines its economic radius to 100-kilometer plant radii, limiting inter-state trade.
- Anthracite:Premium carbon grades exceeding 90% content serve metallurgical applications requiring controlled combustion.
- Sub-bituminous:Intermediate grades bridge power and industrial heating segments with moderate beneficiation requirements.
Today's leader: Bituminous. Tomorrow's challenger: Lignite as coastal ultra-supercritical plants experiment with imported blending ratios.
End User:
Customer scale determines contract structures, with central public sector undertakings locking in 25-year fuel supply agreements while smaller buyers face spot market volatility.
- Power Generation:State gencos and NTPC absorb over 75% of domestic offtake through linkage allocations and captive mine dedications. Central Electricity Authority dispatch protocols prioritize these plants, though renewable purchase obligations now compress their plant load factors.
- Steel Production:Integrated mills at Jamshedpur, Bhilai, and Rourkela command premium coking coal blends with strict ash and phosphorus specifications. Domestic washery output rarely meets these standards, forcing coastal mills to maintain Australian import pipelines.
- Cement Manufacturing:Kiln operators in Rajasthan and Madhya Pradesh source mid-grade bituminous through e-auction windows, exposing them to price spikes during monsoon transport disruptions.
- Chemical Industry:Fertilizer and synthetic fuel plants require consistent quality for gasification processes, sourcing through long-term import contracts.
Steel Production captures the highest per-tonne margins. Power Generation faces the steepest cost compression from renewable alternatives.
Delivery Mode:
Transport economics dictate procurement boundaries, with rail-served plants commanding 300-kilogram-per-kilometre cost advantages over road-dependent competitors.
- Rail Transport:Dedicated freight corridors on the Eastern DFC route move 100-tonne rakes from Jharia and Talcher fields to Uttar Pradesh and Delhi-NCR plants. Coal India Limited's Fuel Management System tracks rake positioning, though monsoon flooding of the Damodar basin routinely disrupts schedules.
- Conveyor System:Pithead stations at Korba, Sipat, and Ramagundam deploy direct mine-to-bunker conveyors eliminating intermediate handling. These systems operate at 4,000 tonnes per hour through dedicated merry-go-round circuits.
- Road Transport:Last-mile connectivity for small industrial consumers and emergency plant restocking during rail embargoes.
- Barging:Coastal movement from Paradip and Dhamra ports to Tamil Nadu and Gujarat generators, competing with Indonesian import pricing.
Rail Transport dominates volume throughput. Conveyor System offers the lowest landed cost where geography permits.
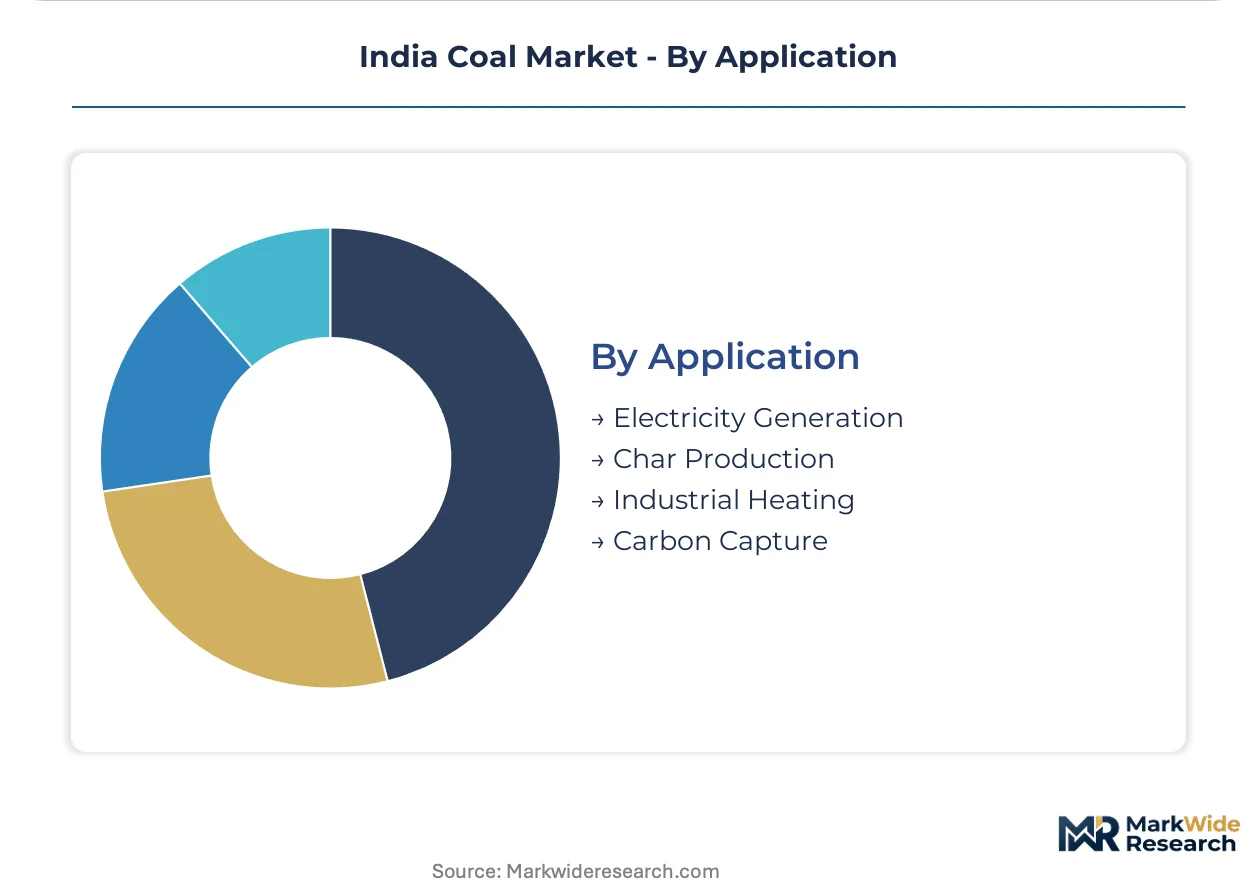
Application:
End-use specifications drive beneficiation intensity, with electricity generation tolerating higher ash content than metallurgical or chemical processes.
- Electricity Generation:Pulverized fuel combustion in subcritical and supercritical boilers consumes 80% of domestic production. Ministry of Environment mandates require washed coal for plants beyond 500 kilometers from mines, expanding washery capacity at Piparwar and Kargali.
- Carbon Capture:Pilot projects at NTPC Vindhyachal and Ramagundam test amine-based post-combustion capture on 500 MW units. National Clean Energy Fund subsidies cover capital costs, though energy penalty economics remain unproven at scale.
- Industrial Heating:Brick kilns, sponge iron units, and textile processing in Punjab and Haryana source run-of-mine coal through informal channels, evading quality standards and emission monitoring.
- Char Production:Metallurgical coke ovens and activated carbon facilities require low-volatile bituminous grades with controlled coking properties.
Electricity Generation anchors current demand. Carbon Capture represents the steepest expansion trajectory if policy incentives deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coal mining in India traces its organized origins to the Raniganj coalfield discoveries in 1774, with systematic exploitation accelerating under British colonial administration and post-independence nationalization creating the modern sector structure.
Jharkhand
Jharia and Bokaro fields host the nation's deepest underground workings and densest concentration of coking coal reserves. The CEA mandates beneficiated coal for plants beyond 500 kilometers from mines, driving washery investments at Kargali and Pootkee. Dhanbad-Ranchi corridor operations feed steel mills at Jamshedpur through dedicated conveyor networks.
Odisha
Talcher and Ib Valley deposits anchor power generation capacity exceeding 20,000 MW at pithead locations. Ministry of Coal commercial mining auctions opened Mahanadi coalfield blocks to private operators without end-use restrictions. Paradip port movements compete with Indonesian imports for coastal Tamil Nadu and Gujarat buyers.
Chhattisgarh
Korba-Surguja belt contains India's largest opencast reserves with seam thicknesses supporting mechanized extraction at 15 million tonnes per annum per mine. MoEFCC forest clearance timelines routinely extend 24-36 months for expansion projects. Korba Super Thermal Power Station exemplifies mine-mouth generation eliminating rail freight exposure.
Madhya Pradesh
Singrauli coalfield straddles the Uttar Pradesh border with NTPC's Vindhyachal complex representing Asia's largest thermal station. Railway rake availability constraints force plants to maintain costly inventory buffers during monsoon disruptions. Amine-based carbon capture pilots at Vindhyachal test post-combustion capture economics with National Clean Energy Fund support.
Tamil Nadu
Neyveli Lignite Corporation operates the nation's only integrated lignite mining and power generation complex. Lower energy density confines economic supply radius to 100-kilometer plant radii, limiting inter-state trade. Flue-gas desulfurization retrofits at aging units address MoEFCC SOx compliance deadlines.
India Coal Market Competitive Environment
Premium-margin players sit above commodity-margin players across beneficiation intensity and captive mine access. The sector exhibits tiered consolidation with a dominant public sector incumbent controlling over 80 percent of domestic production, mid-tier integrated steel operators with backward mining linkages, and emerging private commercial miners. Three archetypes define competitive positioning: state-backed volume leaders with railway corridor commitments, integrated steel-power conglomerates with pithead assets, and merchant power developers securing auctioned blocks. Capacity expansion through opencast mechanization and strategic partnerships for washery infrastructure represent the dominant competitive moves.
Within the state-backed tier, Coal India Limited anchors volume commitments through its monopoly over domestic reserves and Fuel Management System coordination. NTPC Ltd exemplifies the integrated generator archetype with captive linkages and supercritical plant portfolios. Jindal Steel & Power Ltd occupies a position within the steel-integrated segment, representing backward integration from mining through metallurgical processing.
| Leading Market Players |
|---|
| Coal India Limited |
| Singareni Collieries Company Limited |
| NTPC Ltd |
| NLC India Ltd |
| JSW Energy Limited |
| Adani Power Ltd |
| Jindal Steel & Power Ltd |
| Bharat Coking Coal Limited |
| NMDC Ltd |
| Others |
Value Chain & Pricing Dynamics
Captive mining-to-plant integration anchors both supply security and pricing power for India's largest coal consumers, pitting Coal India Limited's monopoly position against private commercial miners seeking volume footholds. This structural arrangement concentrates procurement leverage among pithead power stations while forcing distant buyers into costlier rail-dependent supply chains.
Pricing Analysis
Long-term fuel supply agreements bundled with railway corridor commitments dominate commercial arrangements, with price differentiation driven by calorific value grades and distance from mine mouth. Premium-mid-economy pricing differentiation separates metallurgical coking coal blends from run-of-mine thermal grades, with steel mills absorbing the steepest premiums. Cost compression in power generation feedstock is intensifying because renewable dispatch obligations erode baseload plant utilization. State gencos with captive linkages exhibit lowest price sensitivity; small cement and brick kiln operators buying through e-auction windows face highest volatility exposure.
Supply Chain Analysis
Single-source vulnerability sits with Coal India Limited's control over more than four-fifths of domestic production, creating dependency concentration that limits buyer negotiation leverage. Geographic supply concentration clusters in Jharkhand, Odisha, and Chhattisgarh, where seam thickness and mechanized extraction capacity feed national demand. Raw material dependencies center on diesel for opencast equipment fleets, explosives for blasting operations, and steel for conveyor infrastructure. Railway rake availability constraints present the dominant structural risk, particularly during monsoon flooding of the Damodar basin. Distribution runs through dedicated freight corridors on the Eastern DFC route, with last-mile road transport serving small industrial consumers outside rail-served catchments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
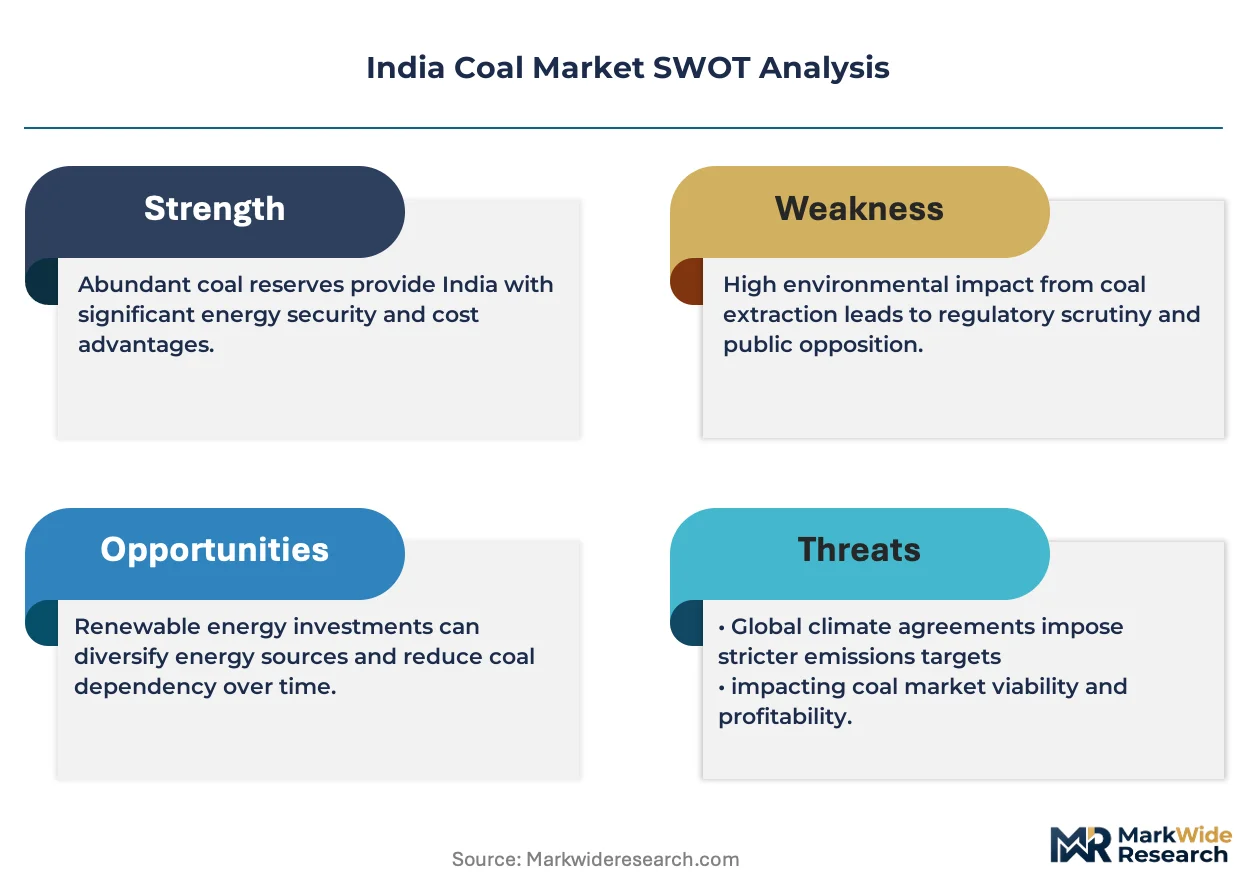
India's coal market functions as a geographic-arbitrage play between eastern pithead stations with negligible logistics costs and western generators facing 500-plus kilometer rail hauls that trigger beneficiation mandates and inflate landed fuel expenses.
For Market Incumbents: Acquire stranded commercial mining blocks in Odisha's Mahanadi coalfield to secure volume buffers against Coal India Limited allocation uncertainties. Cement captive washery infrastructure in Jharkhand and Chhattisgarh to meet Ministry of Environment emission norms for distant plants. Renewable dispatch obligations threaten baseload utilization; backward integration into mine ownership preserves margin structure.
For New Entrants and Emerging Players: Launch via commercial mining auctions targeting merchant power producers without end-use restrictions, exploiting policy openings in previously captive-only blocks. Odisha's Talcher-Ib Valley corridor offers the most penetrable geography, with existing rail spurs and port connectivity reducing greenfield infrastructure requirements. Position around carbon capture demonstration eligibility under National Clean Energy Fund subsidies.
For Investors and Strategic Acquirers: Roll-up economics work for mid-tier private miners with auctioned block portfolios because Coal India Limited's production plateau creates supply gap windows for commercial entrants. Five-to-ten year viability hinges on regulatory enforcement consistency for environmental clearances and railway capacity expansion pacing. Monitor Ministry of Coal auction clearance timelines as the inflection signal for block availability velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Washery Capacity Expansion | Meets CEA beneficiation mandates for plants beyond 500 kilometers from mines. |
| Carbon Capture Pilot Deployment | Secures National Clean Energy Fund subsidies at NTPC's Vindhyachal complex. |
| Dedicated Freight Corridor Access | Reduces rail freight exposure for Uttar Pradesh and Delhi-NCR generators. |
| Commercial Mining Block Acquisition | Exploits Ministry of Coal auctions without end-use restrictions in Odisha. |
| Pithead Power Station Development | Eliminates logistics costs through direct mine-to-plant conveyor systems. |
Study Parameters
Multiple input streams — primary interviews with fuel supply specialists, utility planning officers, and EPC contractors; secondary reconciliation of CEA dispatch data, Ministry of Coal auction records, and Eastern Railway freight statistics; and customs trade flows — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations captured procurement economics, washery utilization rates, and emission compliance cost structures across state gencos and independent power producers.
Historical production volumes were cross-referenced against panel input from mining engineers and grid operators to build the analytical framework. Segmentation dimensions modeled include coal grade tier, end-use application, delivery mode, and state-level regulatory cluster. CAGRs were derived from trend extrapolation adjusted for policy intervention timing, with forecast inputs incorporating renewable purchase obligation enforcement trajectories and railway capacity expansion schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged MoEFCC forest clearance delays or accelerated renewable substitution in Maharashtra and Gujarat. Forecasts reflect documented assumptions about auction block allocation velocity and emission norm enforcement consistency. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Emulsified Fuel Market
Fuels
Diesel Fuel Water Separator Market
Fuels
Chafing Fuel Market
Fuels
Asia-Pacific Bunker Fuel Market
Fuels
Commercial Aircraft Aviation Fuel Market
Fuels
Hydrogen Tube Trailer Market
Fuels
Palm Methyl Ester Market
Fuels
Global Gas Cylinder Market
Fuels
Multifuel Gas Turbine Market
Fuels
India LNG Market
Fuels
Canada Bunker Fuel Market
Fuels
Asia-Pacific Coal Market
Fuels
Global Charcoal Market
Fuels
United States LNG Bunkering Market
Fuels
Collapsible Fuel Tank Market
Fuels
Hybrid Propellants Market