
 LNG Filling Station Market | 2026-2036
LNG Filling Station Market Size, Share, and Industry Trends Forecast 2026-2036
LNG Filling Station Market Intelligence
Modular station design is rebalancing buyer choice toward scalable, redeployable configurations that reduce upfront capital exposure. Shell leverages its integrated fuel retail network to anchor large-scale public station rollouts across multiple continents. Cryostar specializes in cryogenic pump and vaporizer technology, sustaining its position in high-throughput dispensing systems. Kunlun Energy competes through pipeline-connected station clusters that dominate China's inland corridor markets.
An LNG filling station is a fixed or mobile facility engineered to store liquefied natural gas at cryogenic temperatures near minus 162 degrees Celsius and transfer it via vacuum-insulated lines into vehicle or vessel tanks. These installations serve the primary commercial purpose of displacing diesel and heavy fuel oil in transport and industrial applications where energy density and refueling speed matter. Public service stations capture the broadest addressable base among service types, while mobile configurations represent the fastest-expanding segment for remote mining and construction logistics. Within technology categories, dispensing equipment commands concentrated margin pools as precision metering and safety interlocks become more sophisticated.
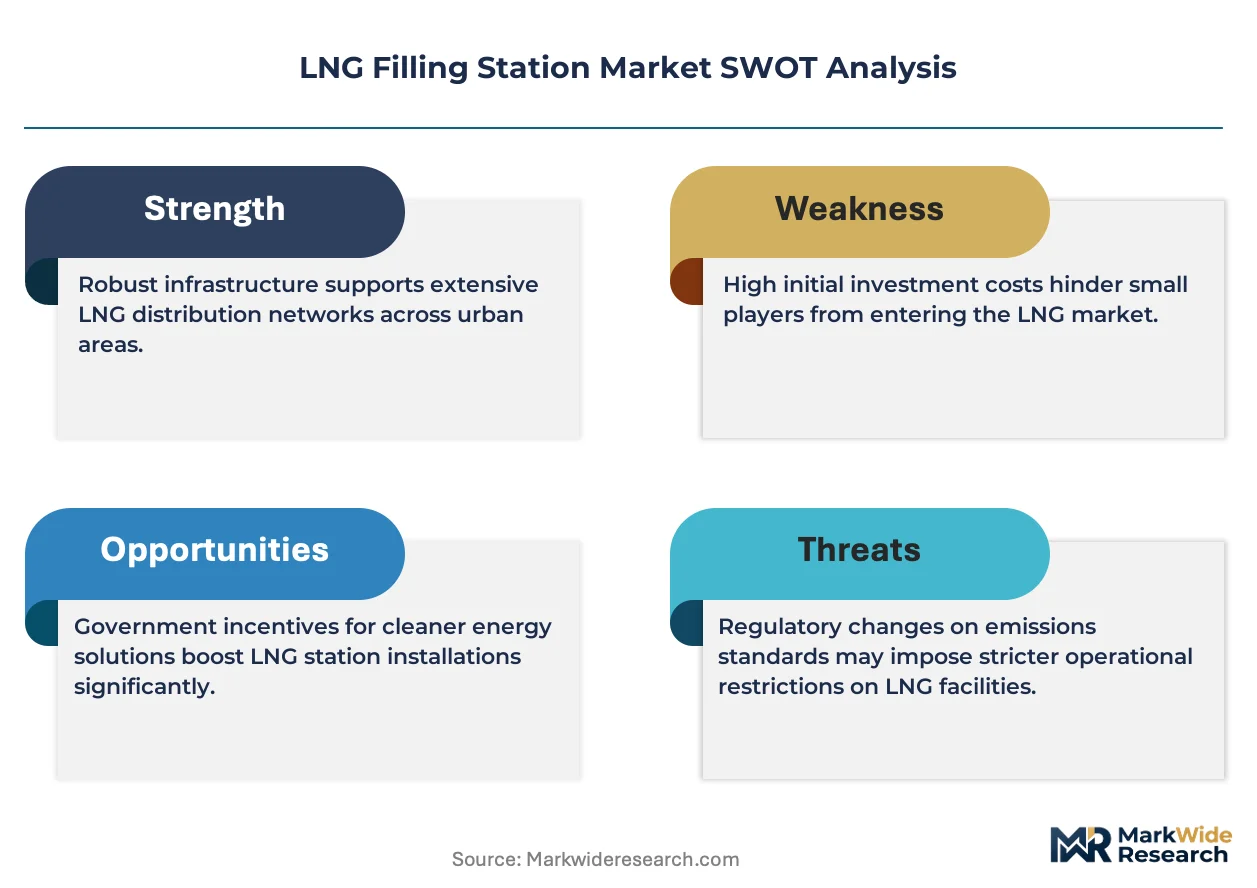
The EPA regulates LNG station emissions and storage vessel standards in the United States, while the EU Green Deal and F-Gas Regulation constrain methane leakage thresholds across European installations. China's MEE enforces dual carbon compliance timelines that directly condition permitting for new station construction. Stakeholders must monitor how tightening methane intensity benchmarks reshape equipment procurement criteria and site certification requirements across jurisdictions.
Market Dynamics
Modular station architecture is compressing deployment timelines and redistributing capital risk across fleet operators and infrastructure developers. This shift from fixed-site construction toward containerized, redeployable systems is altering how capacity scales with demand volatility in long-haul corridors.
Growth Catalysts
- EU Green Deal methane thresholds:The F-Gas Regulation and tightening CO2 standards for heavy-duty transport are mandating fuel-switching timelines that directly accelerate LNG station permitting in German and Dutch freight corridors.
- Port logistics electrification:Coastal China's intermodal container terminals are integrating LNG bunkering and truck refueling into unified fueling hubs, concentrating demand density along the Yangtze River Delta.
- Cryogenic pump efficiency gains:Advances in submersible pump design are cutting boil-off losses during high-throughput dispensing, improving station economics for 24-hour fleet operations.
Market Restraints
- Specialized steel input costs:Vacuum-insulated piping and double-walled storage vessels require nickel-alloy grades whose price volatility constrains station fabrication budgets.
- Limited cryogenic technician pools:The shallow labor market for certified cryogenic system installers extends commissioning timelines and inflates construction labor costs across North American projects.
- Pipeline connectivity gaps:Inland station clusters lacking direct pipeline feed must rely on trucked LNG deliveries, injecting supply reliability risk and transport cost premiums.
Strategic Opportunities
- India's freight corridor densification:The Delhi-Mumbai Industrial Corridor presents undeveloped station spacing that favors early-mover infrastructure anchoring ahead of dedicated LNG trucking lanes.
- Remote mining logistics:Mobile station configurations are penetrating Australian iron ore and Chilean copper operations where diesel resupply involves prohibitive overland distances.
- IMO 2023 marine fuel standards:The International Maritime Organization's carbon intensity regulations are pushing container lines toward LNG dual-fuel vessels, creating demand for port-side bunkering stations at transshipment hubs.
Industry Challenges
- Cryogenic safety certification complexity:Station operators must navigate overlapping pressure vessel codes and hazardous location electrical classifications that vary between China's GB standards and EU ATEX directives.
- Legacy diesel maintenance infrastructure:Fleet workshops require retooling for cryogenic fuel system diagnostics, creating transition friction for mixed-fuel operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LNG Filling Station Market |
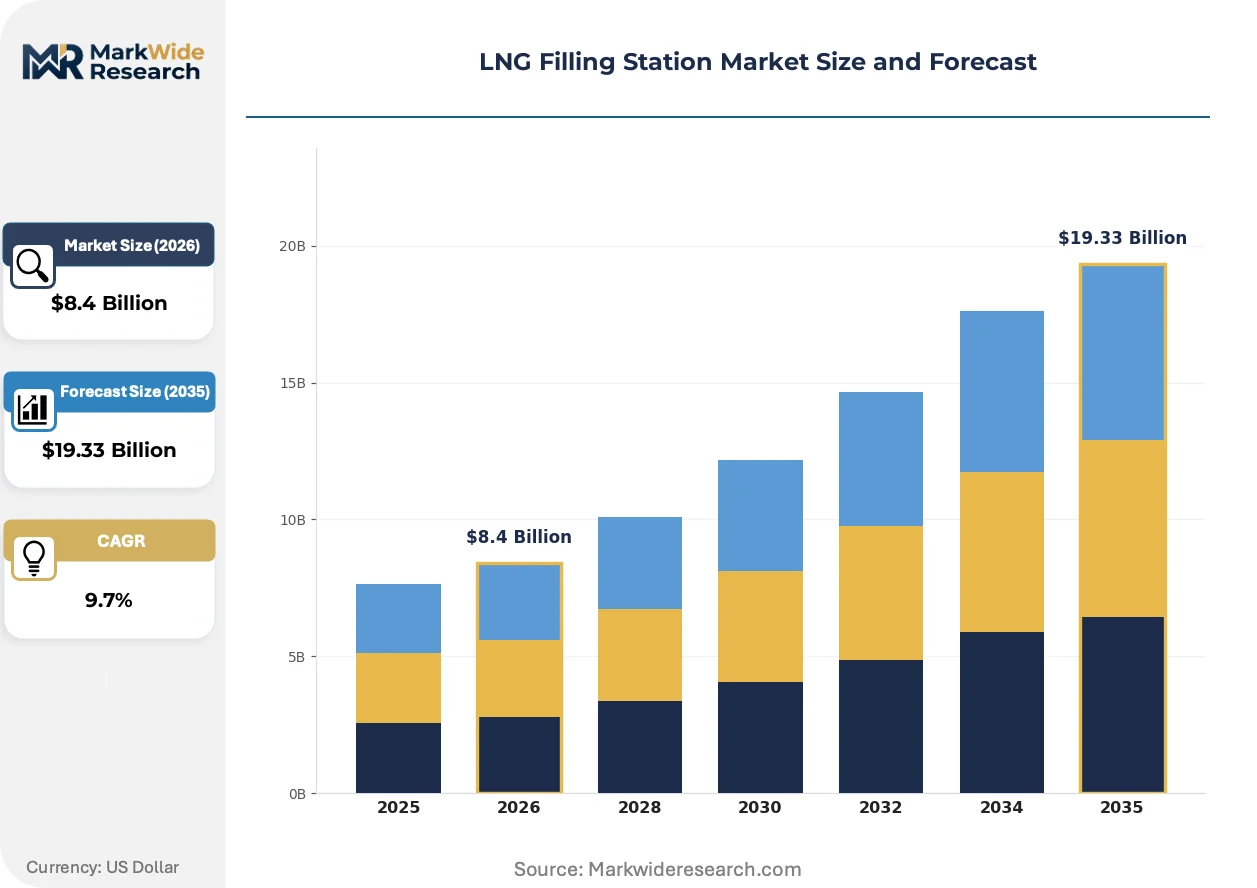
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $19.33 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Public, Private, Hybrid, Mobile Technology: Pump System, Pressure Vessels, Dispensing Equipment, Safety Mechanisms Application: Heavy-Duty Vehicles, Marine Transport, Industrial Uses, Power Generation End User: Logistics Companies, Fleet Operators, Municipalities, Energy Providers |
| Companies Covered | Guanghui, Cryostar, Kunlun Energy, FortisBC, Engie, CNOOC, Sinopec, Shell, ENN Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LNG Filling Station Market Strategic Shifts & Innovations
Dispensing precision and digital integration are converging to redefine station operational models. Equipment vendors are embedding sensor networks and predictive maintenance protocols that compress downtime and extend asset life cycles.
Submerged cryogenic pumps with magnetic bearing drives are electrifying high-flow dispensing architecture. These systems eliminate dynamic seals and reduce maintenance intervals. European port operators are retrofitting existing stations with this technology to handle 80-tonne truck volumes. The shift is electrifying competitive differentiation around throughput reliability rather than fuel price alone.
China's MEE is enforcing dual carbon compliance timelines that condition construction permits on methane leak detection and vapor recovery mandates. Industrial consequence includes mandatory infrared monitoring systems and sealed loading arms. Inland corridor projects face the steepest compliance ramps, with developers accelerating procurement of certified equipment to meet 2025 permitting windows.
Fleet procurement is consolidating around long-term fueling contracts with guaranteed throughput commitments. Large trucking operators are bypassing spot-market refueling in favor of dedicated lane access and fixed pricing structures. This behavioral pivot is most visible in Germany's Rhine-Alpine corridor, where major logistics groups are underwriting station construction in exchange offtake guarantees.
LNG Filling Station Market Segmentation
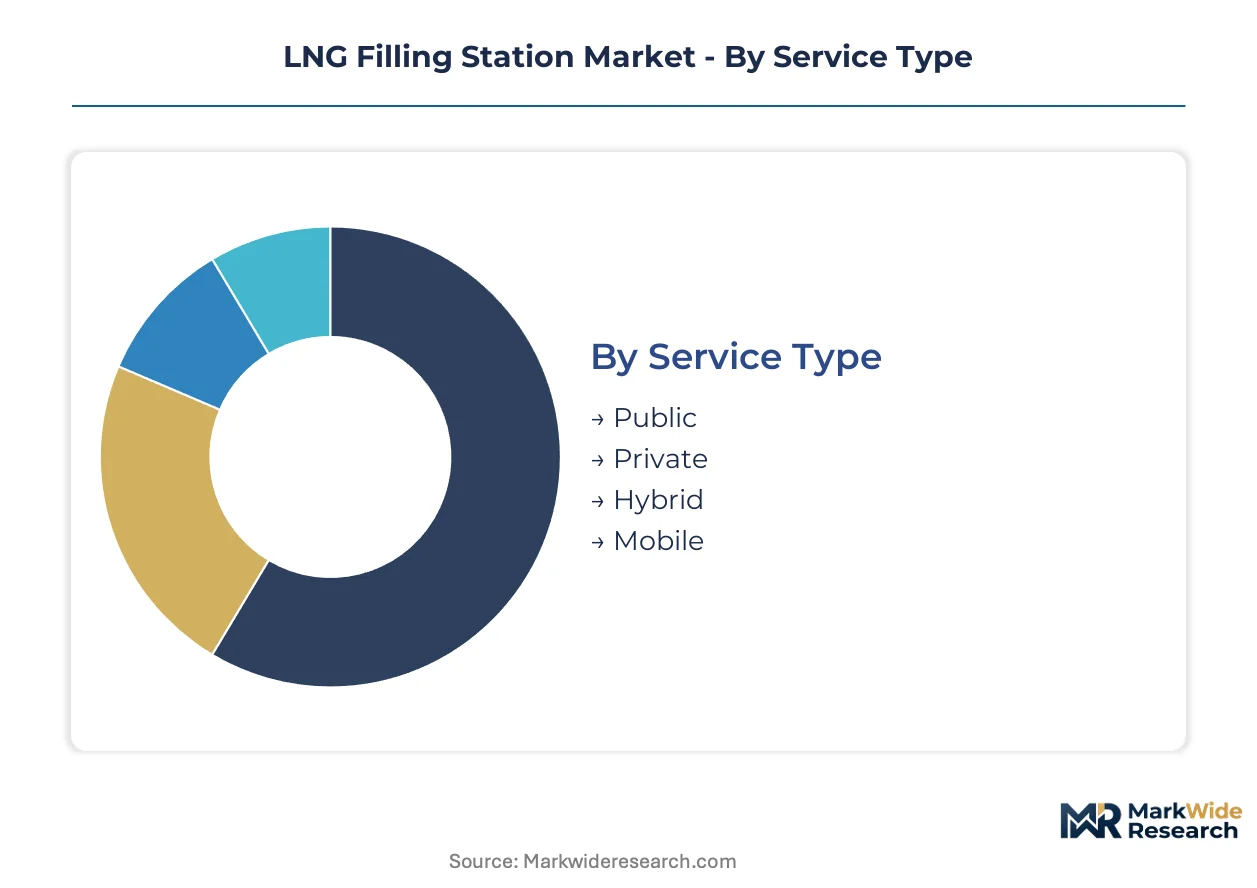
Segmentation in LNG filling stations reveals how infrastructure investment aligns with fleet operational models and regulatory pressure points. Service configuration and technology choices determine capital recovery timelines, while application focus shapes site location economics.
Service Type:
Standalone public stations operate independently of fleet ownership, while embedded private and hybrid configurations integrate directly into captive logistics networks.
- Public:Open-access facilities serve mixed fleets along high-volume freight corridors. Germany's Rhine-Alpine logistics clusters concentrate demand where EU Green Deal methane thresholds accelerate diesel displacement.
- Private:Captive stations serve single-fleet operations with guaranteed throughput. Mining and port terminal operators in coastal China deploy these to lock in fuel cost predictability under dual carbon compliance timelines.
- Hybrid:Dual-access models blend dedicated fleet lanes with third-party sales. These configurations dominate intermodal hubs where logistics companies seek capacity utilization beyond contracted volumes.
- Mobile:Containerized, redeployable units serve remote construction and extraction sites. Australian iron ore corridors and Chilean copper belts adopt these where permanent infrastructure economics fail.
Public stations lead volumes today; mobile configurations are gaining share fastest.
Technology:
Cost tiers separate precision-engineered subsystems from standardized containment hardware, with margin concentration in flow-control and monitoring layers.
- Pump System:Submersible cryogenic pumps with magnetic bearing drives eliminate dynamic seals and cut maintenance intervals. European port operators retrofit existing stations with this technology to handle 80-tonne truck volumes.
- Pressure Vessels:Double-walled vacuum-insulated storage tanks maintain minus 162 degrees Celsius with minimal boil-off. Nickel-alloy grade requirements tie fabrication costs to commodity volatility.
- Dispensing Equipment:Precision metering systems with sealed loading arms and infrared leak detection meet China's MEE vapor recovery mandates. These command concentrated margin pools as safety interlocks grow more sophisticated.
- Safety Mechanisms:Pressure relief systems, emergency shutdown protocols, and hazardous location electrical classifications vary between China's GB standards and EU ATEX directives, complicating cross-border equipment sourcing.
Dispensing equipment leads volumes today; pump systems are climbing the fastest.
Application:
Volume scale differentiates mass-transit corridors from niche industrial installations, with throughput density determining station economic viability.
- Heavy-Duty Vehicles:Long-haul trucking along dedicated freight lanes drives the bulk of station deployment. The Delhi-Mumbai Industrial Corridor presents undeveloped spacing that favors early-mover infrastructure anchoring.
- Marine Transport:Port-side bunkering serves LNG dual-fuel container vessels under IMO 2023 carbon intensity regulations. Transshipment hubs in the Yangtze River Delta integrate these into unified fueling facilities.
- Industrial Uses:Cryogenic nitrogen and process heat applications in manufacturing clusters create secondary demand streams. These installations often colocate with power generation assets.
- Power Generation:Peaking plants and grid stabilization units in pipeline-connected regions use LNG as a cleaner alternative to diesel backup. Station sizing here follows electricity demand curves rather than transport schedules.
Heavy-duty vehicles lead volumes today; marine transport is expanding most quickly.
End User:
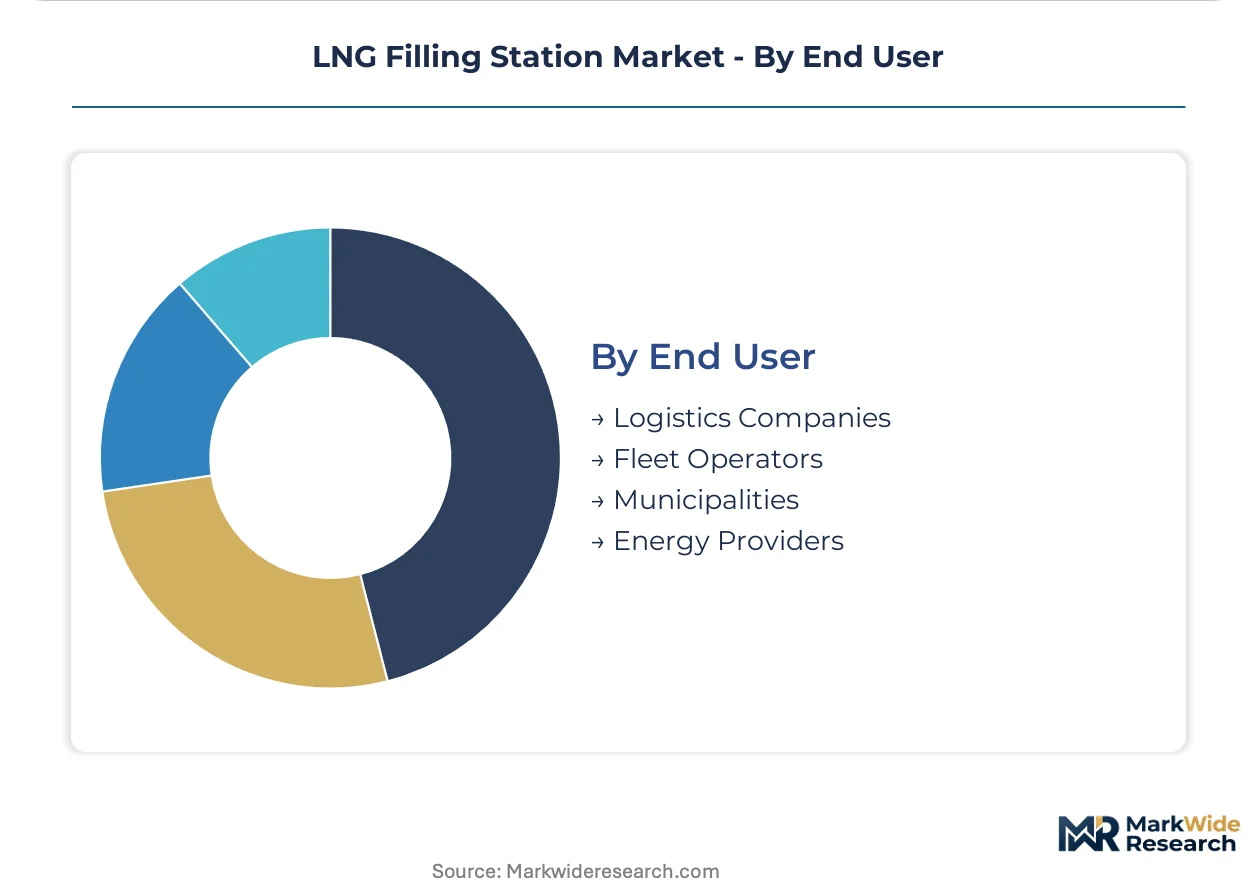
Customer type shapes contract structure, with fleet operators seeking throughput guarantees while municipalities prioritize public access and emissions accounting.
- Logistics Companies:Large trucking operators underwrite station construction in exchange for dedicated lane access and fixed pricing. Germany's major logistics groups have pioneered this model along priority corridors.
- Fleet Operators:Mixed-fuel operators face retooling friction as workshops adapt to cryogenic fuel system diagnostics. These stakeholders drive demand for phased infrastructure transition support.
- Municipalities:Urban transit agencies and waste collection fleets deploy stations to meet local air quality targets. Procurement emphasizes public accessibility and transparent emissions reporting.
- Energy Providers:Integrated fuel retailers leverage existing retail networks for large-scale public rollouts. Shell anchors multi-continent deployment through this channel advantage.
Logistics companies lead volumes today; energy providers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The LNG filling station industry traces its commercial roots to European port logistics networks, where early marine bunkering infrastructure established technical templates later adapted for heavy-duty road transport across multiple continents.
China
Coastal port logistics and intermodal corridors along the Yangtze River Delta concentrate station deployment density. The MEE enforces dual carbon compliance timelines that condition construction permits on methane leak detection and vapor recovery mandates. Inland corridor projects in Sichuan-Chongqing face accelerated procurement deadlines to meet 2025 permitting windows.
Germany
The Rhine-Alpine freight corridor anchors European LNG trucking adoption, with logistics groups underwriting station construction through long-term offtake guarantees. The EU Green Deal and F-Gas Regulation mandate fuel-switching timelines that accelerate station permitting. Major logistics clusters in North Rhine-Westphalia concentrate hybrid-access facilities serving mixed fleet operations.
United States
Long-haul trucking corridors in Texas and California drive demand for public-access stations along interstate freight routes. The EPA regulates emissions and storage vessel standards, constraining equipment procurement criteria. The Permian Basin and Gulf Coast petrochemical clusters support pipeline-connected station economics with reliable feedstock supply.
India
The Delhi-Mumbai Industrial Corridor presents undeveloped station spacing that favors early-mover infrastructure anchoring ahead of dedicated LNG trucking lanes. The Ministry of Road Transport and Highways promotes alternative fuel corridors through policy incentives. Gujarat and Maharashtra industrial belts concentrate pilot deployments near manufacturing and port zones.
Australia
Remote mining operations in Western Australia's Pilbara region adopt mobile station configurations where diesel resupply involves prohibitive overland distances. The country's national energy regulator oversees pressure vessel certification standards. Queensland coal and iron ore logistics networks drive demand for redeployable cryogenic fueling systems.
LNG Filling Station Market Key Industry Players
The competitive structure tilts toward integrated energy conglomerates with captive fuel retail networks and specialized cryogenic equipment fabricators. Tier-one positions cluster around firms combining upstream LNG sourcing with downstream station ownership. Two dominant strategic archetypes define the field: pipeline-connected infrastructure developers leveraging feedstock integration, and precision equipment specialists capturing margin pools in dispensing and storage subsystems. Competitive moves concentrate on corridor anchoring through long-term fleet contracts and modular system standardization to compress deployment timelines.
Among state-affiliated Chinese energy groups, Guanghui, CNOOC, and Sinopec occupy positions reflecting vertical integration from import terminals through retail station networks. These entities exemplify the pipeline-connected archetype dominating inland corridor markets through captive supply chains and permit access advantages under national dual carbon policy frameworks.
| Leading Market Players |
|---|
| Guanghui |
| Cryostar |
| Kunlun Energy |
| FortisBC |
| Engie |
| CNOOC |
| Sinopec |
| Shell |
| ENN Energy |
| Others |
Cost & Logistics Intelligence
Submersible cryogenic pump electrification is compressing maintenance intervals while concentrating procurement power among European and Chinese equipment fabricators. This technology transition simultaneously raises upfront capital requirements and locks buyers into specialized vendor relationships.
Pricing Analysis
Long-term offtake contracting with throughput guarantees dominates procurement structures across Germany's Rhine-Alpine corridor and China's Yangtze River Delta. Price differentiation hinges on certification tier—EU ATEX versus China's GB standards—and volume scale commitments from fleet operators. Pricing pressure stems from nickel-alloy grade volatility affecting vacuum-insulated vessel fabrication. Logistics companies underwritten by fueling contracts show lowest price sensitivity; spot-market fleet operators exhibit highest.
Supply Chain Analysis
Certification gating fragments equipment sourcing between EU ATEX and China's GB standards, forcing dual qualification tracks for multinational vendors. Manufacturing concentrates in Germany, China, and the United States. Supply chains draw from nickel-alloy steel grades, cryogenic pump subassemblies, and precision metering systems. Single-source vulnerability runs through submersible pump magnetic bearing technology. Distribution runs through integrated energy retailers and specialized cryogenic fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in dispensing equipment layers where precision metering and vapor recovery systems command premium positioning. Submersible pump efficiency gains and modular deployment methods compress lifecycle costs for early adopters.
For Market Incumbents: Cement corridor dominance through pipeline-connected station clusters along China's inland Sichuan-Chongqing corridor and Germany's North Rhine-Westphalia logistics hubs. Secure captive LNG feedstock agreements to defend against emerging bio-LNG substitutes. Invest in GB-ATEX dual certification to capture cross-border procurement demand. For New Entrants and Emerging Players: Launch via mobile station configurations targeting Australia's Pilbara iron ore operations and Chilean copper belts where permanent infrastructure economics fail. India's Delhi-Mumbai Industrial Corridor presents undeveloped station spacing with favorable policy tailwinds. Prioritize redeployable system standardization to compress deployment timelines. For Investors and Strategic Acquirers: Valuations sit cheapest among cryogenic equipment specialists lacking integrated fuel retail networks. Long-term viability favors firms combining upstream LNG sourcing with downstream station ownership. Watch for inflection in IMO marine bunkering demand at Yangtze River Delta transshipment hubs.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Station Standardization | Compresses deployment timelines for Australia's remote mining logistics corridors. |
| Dual Certification Investment | Unlocks cross-border procurement from EU ATEX and China's GB standards regimes. |
| Pipeline-Connected Cluster Buildout | Captures inland corridor markets through captive feedstock under China's MEE permitting. |
| Long-Term Offtake Contracting | Secures guaranteed throughput from Germany's major logistics groups. |
| Submersible Pump Retrofit Programs | Captures margin pools in European port operator 80-tonne truck volume upgrades. |
Research Approach
Coverage spans China, Germany, the United States, India, and Australia, with primary inputs from each market cluster. The approach combines interviews with cryogenic equipment procurement managers, fleet operations directors, LNG terminal developers, and regulatory compliance officers alongside secondary validation. Sources include EPA emissions filings, EU F-Gas Regulation documentation, China's MEE permitting records, and customs trade data for nickel-alloy steel imports. Bottom-up station deployment tallies triangulate against top-down fuel demand models.
Rate-of-change decomposition separates volume growth from price trajectory across the projection horizon. Segmentation dimensions include service configuration, technology subsystem, application category, and end-user contract structure. CAGRs derive from corridor-level deployment timelines and fleet conversion rates. Industry-specific inputs incorporate IMO marine fuel standards compliance deadlines and China's dual carbon permitting windows.
Several conditions sit outside the modeled scope, including bio-LNG technology disruption and hydrogen fuel cell substitution timelines. Forecasts reflect assumptions about regulatory enforcement continuity and nickel-alloy price stabilization. A model refresh is warranted upon material change in EU Green Deal methane threshold implementation or China's MEE vapor recovery mandate acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Charcoal Briquette Market
Fuels
India Petrol Station Market
Fuels
Gas Feed System Market
Fuels
China LNG Bunkering Market
Fuels
Global Gas Cylinder Market
Fuels
Global Gas Treatment Market
Fuels
Australia Coal Market
Fuels
India Retail Fuel Market
Fuels
Coal Gasification Market
Fuels
Brazil LNG Market
Fuels
Anthracite Coal Mining Market
Fuels
Turbine Drip Oil Market
Fuels
Oil & Gas Lubricants Market
Fuels
South America Defense Aircraft Aviation Fuel Market
Fuels
Coal Trading Market
Fuels
No.4 Fuel Oil Market