
 Electric Fuel Heater Market | 2026-2036
Electric Fuel Heater Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Fuel Heater Market Analysis
Commercial fleet electrification is expanding faster than residential adoption, pulling electric fuel heater demand toward heavy-duty logistics and cold-chain transport. Bosch leverages its automotive thermal management heritage to anchor European OEM supply relationships. Chromalox specializes in industrial-grade immersion configurations for off-highway and marine applications. Phillips & Temro Industries dominates North American aftermarket channels with extensive distributor coverage.
An electric fuel heater converts electrical energy into thermal energy to raise fuel temperature, typically employing resistance elements rated between 500W and 5kW to ensure proper viscosity and combustion efficiency in diesel, biodiesel, or synthetic fuel systems. Tankless configurations lead commercial vehicle installations where space constraints and rapid heat-up cycles matter most, while immersion types retain margin pools in stationary industrial tanks requiring sustained temperature maintenance. Induction technology segments are gaining share in high-precision applications where uniform heating and reduced element degradation justify premium positioning over conventional resistance methods.
EPA emission standards and NHTSA fuel economy mandates in the US compel OEMs to integrate electric fuel heaters into thermal management architectures for compliance. ECE R10 electromagnetic compatibility regulations govern heater electronics access to European automotive markets, while China's GB standards for vehicle electrical safety shape export qualification requirements for component suppliers. Stakeholders must monitor how battery-electric and hydrogen fuel cell powertrains redefine thermal load profiles and heater integration points across emerging commercial vehicle platforms.
Market Dynamics
Fleet electrification programs are compressing development cycles for thermal management subsystems as cold-chain logistics operators demand cold-weather reliability guarantees from OEMs.
Growth Catalysts
- EPA Phase 3 standards:NHTSA fuel economy mandates compel commercial vehicle manufacturers to integrate electric fuel heaters into thermal architectures for compliance with greenhouse gas reduction timelines.
- Cold-chain logistics:Refrigerated transport fleets operating across Minnesota, Wisconsin, and Michigan corridors require guaranteed fuel flow at sub-zero temperatures, creating pull-through demand for high-wattage heater configurations.
- Induction heating:Uniform thermal distribution and reduced element degradation in precision applications justify premium positioning over conventional resistance methods in high-cycle industrial settings.
Market Restraints
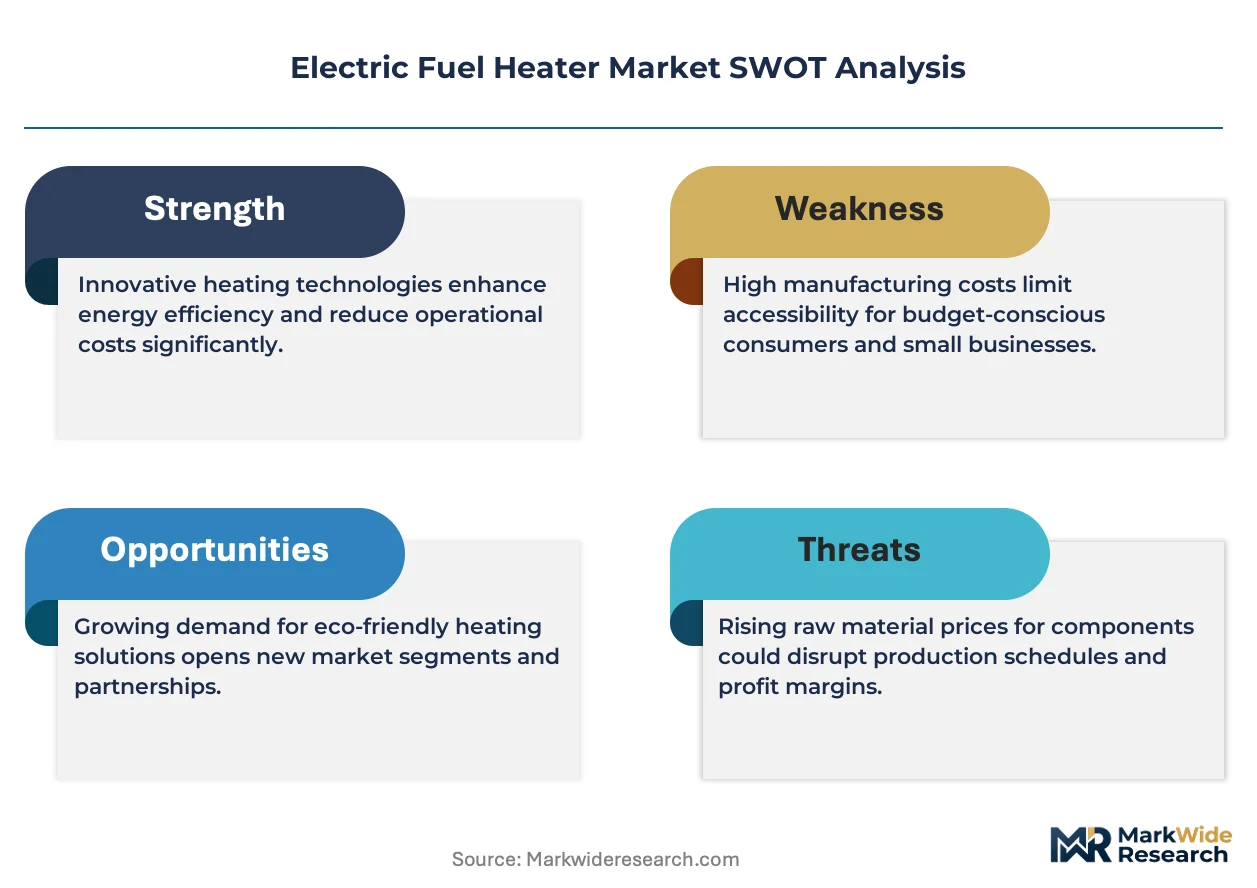
- Copper and nickel price volatility:Resistance element manufacturing faces input cost pressure from commodity swings, squeezing margin pools for mid-tier suppliers without long-term supply agreements.
- Single-source magnetics:Induction heater core components concentrate among East Asian wound-component specialists, exposing European and North American assemblers to geographic supply risk.
- Battery thermal substitution:Solid-state battery architectures with wider operating temperature ranges threaten to displace auxiliary fuel heating in certain commercial vehicle segments.
Strategic Opportunities
- Norway and Finland:Arctic corridor freight operators remain underpenetrated by incumbent suppliers, offering first-mover positioning for heater systems rated below -40°C operational thresholds.
- Hydrogen fuel cell integration:Cryogenic hydrogen storage systems require precision thermal management at fueling interfaces, opening adjacent application space beyond conventional diesel architectures.
- ECE R10 certification pathways:Electromagnetic compliance pre-qualification for European automotive markets creates barrier-to-entry advantages for suppliers with established testing relationships.
Industry Challenges
- Thermal systems engineering talent:Cross-disciplinary expertise spanning electrical heating, fluid dynamics, and vehicle integration remains scarce, elongating product development timelines.
- Legacy CAN bus integration:Retrofit installations into existing fleet management systems require protocol bridging and firmware customization, complicating aftermarket deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Fuel Heater Market |
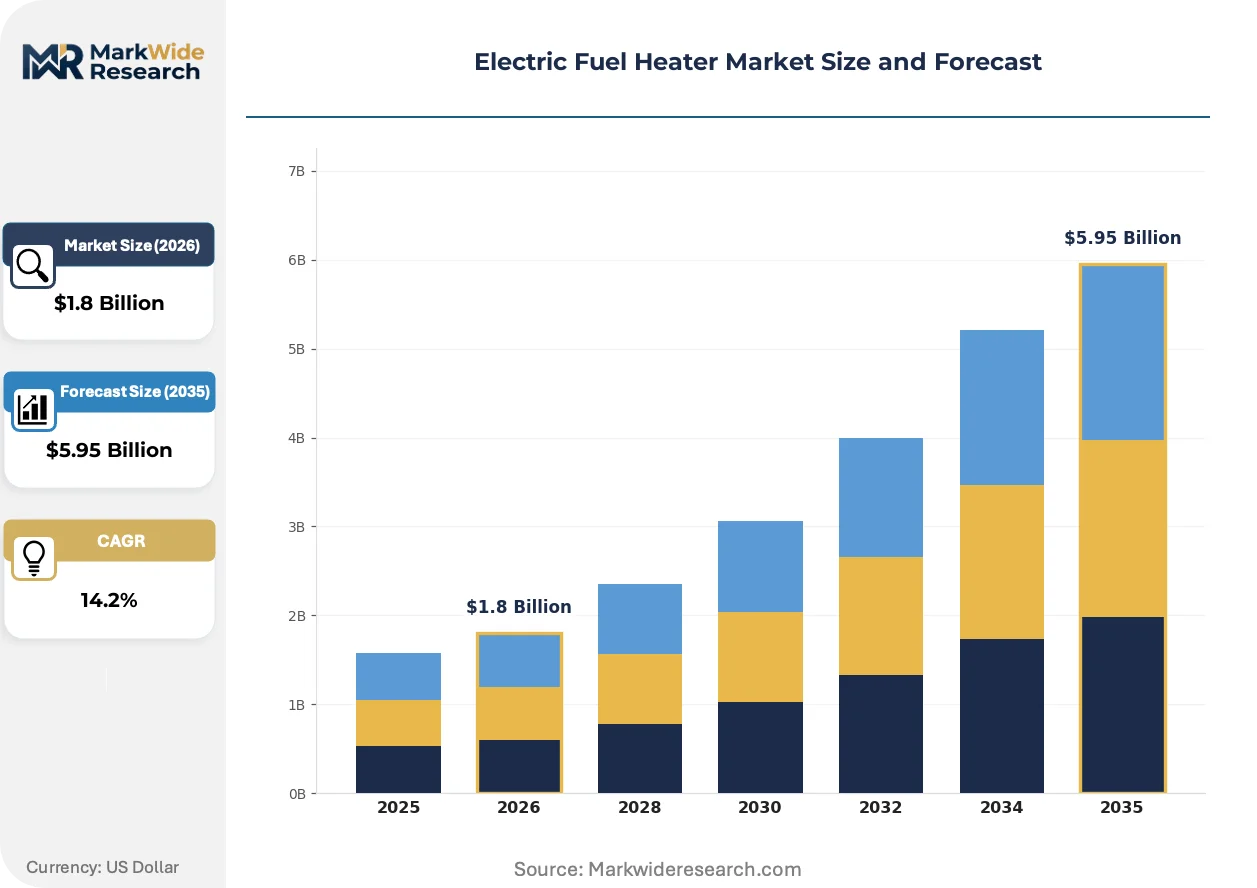
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tankless, Immersion, Indirect, Direct Application: Commercial, Residential, Industrial, Automotive Technology: Resistance, Infrared, Induction, Radiant End User: Households, Factories, Workshops, Fleet Operators |
| Companies Covered | Phillips & Temro Industries, Chromalox, Watlow, Warren Electric Corporation, Mahle GmbH, Gaumer Process, GE Power Systems, Wattco, Bosch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Fuel Heater Market Emerging Trajectories
Heater subsystem architectures are pivoting toward modular, software-defined thermal control as OEMs consolidate supplier bases and demand configurable performance profiles across vehicle platforms.
Solid-state power switching is rewriting thermal response characteristics in commercial vehicle fuel heaters. Silicon carbide MOSFETs replace mechanical relays in 2-5kW resistance elements, enabling millisecond-level duty cycle control. Cold-chain fleet operators in Alberta and Saskatchewan are specifying these configurations for precise viscosity management during temperature transitions, compressing competitive differentiation around semiconductor sourcing rather than mechanical engineering alone.
REACH substance restrictions on hexavalent chromium coatings are forcing redesigns of corrosion-resistant heater housings for European market access. Surface treatment suppliers are accelerating plasma electrolytic oxidation alternatives. Tankless configuration manufacturers serving German and French OEM channels face the steepest compliance timelines, with qualification cycles extending 18-24 months for new coating chemistries.
Specifying behavior among municipal bus procurement departments is pivoting toward lifecycle cost guarantees rather than upfront equipment pricing. Danish and Swedish transit authorities now require 10-year thermal performance warranties with predictive maintenance telemetry. Channel relationships are restructuring around systems integrators capable of underwriting long-term service obligations, displacing traditional component distributor models in Nordic public transport segments.
Electric Fuel Heater Market Segmentation
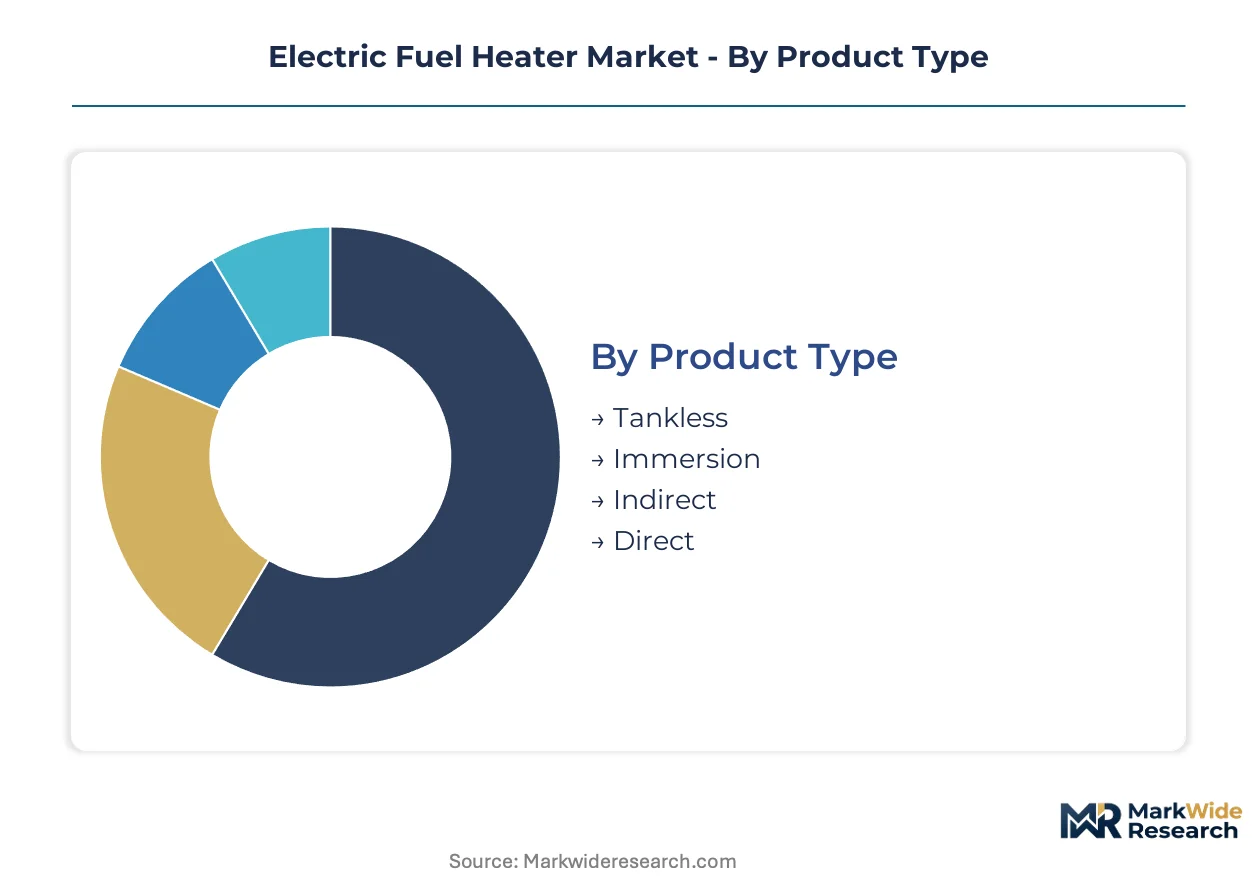
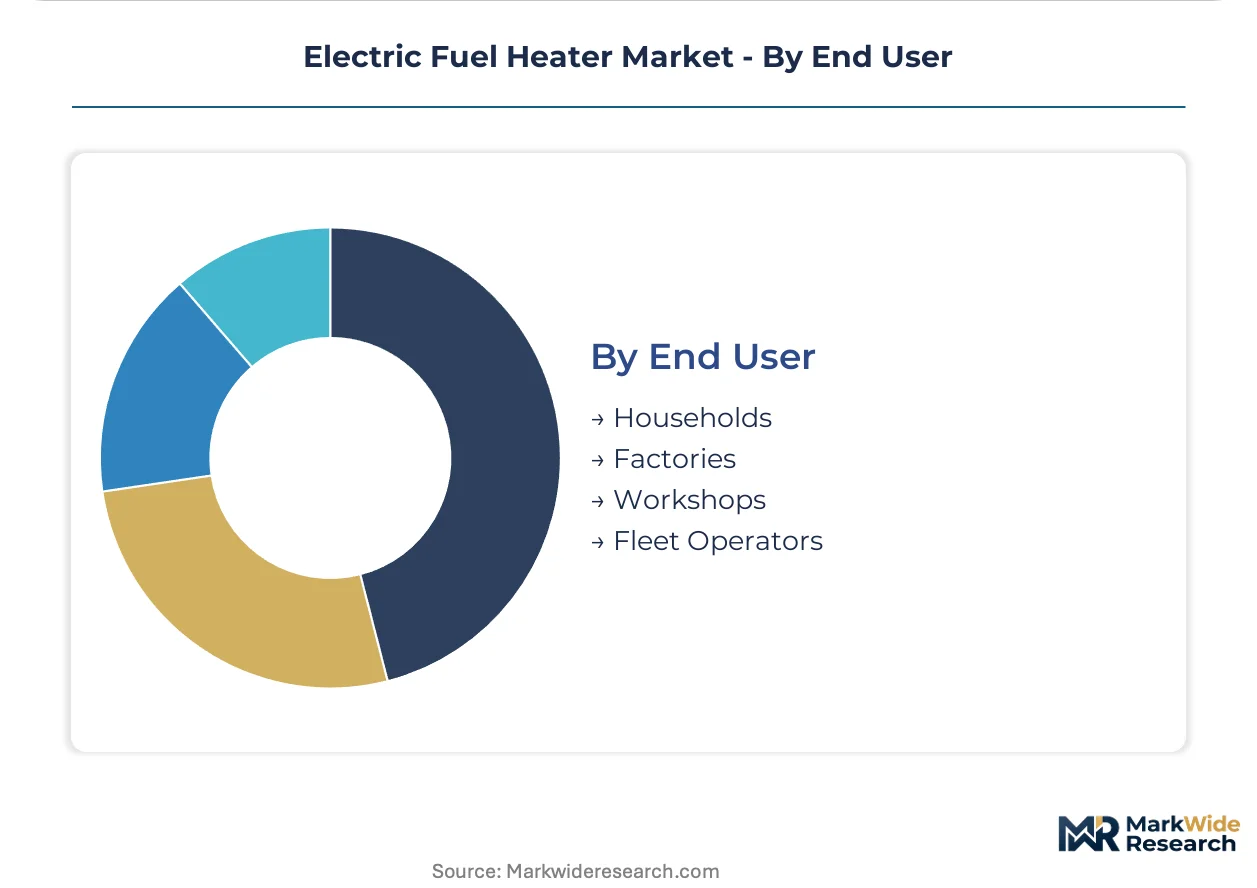
Electric fuel heater architectures fragment across thermal delivery mechanisms, installation constraints, and duty cycle profiles. Segmentation reveals how cold-chain logistics, industrial process heating, and fleet electrification create divergent specification requirements across resistance, induction, and infrared technology platforms.
Product Type:
Thermal delivery architecture determines footprint, response time, and integration complexity across vehicle and stationary applications.
- Tankless:Compact flow-through designs eliminate reservoir thermal mass, enabling sub-30-second heat-up cycles critical for Minnesota and Wisconsin cold-chain fleets. Space-constrained commercial vehicle engine bays favor these configurations where rapid viscosity restoration prevents fuel gelling at sub-zero temperatures.
- Immersion:Submerged resistance elements deliver sustained temperature maintenance in stationary biodiesel storage tanks and marine fuel bunkers. Industrial-grade Chromalox configurations dominate off-highway mining equipment and Arctic marine applications requiring continuous duty cycles below -40°C.
- Indirect:Heat exchanger architectures isolate combustion circuits from fuel streams, serving dual-fuel gensets and hybrid thermal systems where cross-contamination risks disqualify direct contact methods.
- Direct:Resistance elements contact fuel directly for maximum thermal transfer efficiency, occupying cost-sensitive aftermarket retrofits and legacy fleet upgrades across Upper Midwest corridors.
Tankless leads on scale; immersion leads on momentum.
Application:
End-use thermal load profiles dictate wattage specifications, control system complexity, and service interval requirements.
- Commercial:Refrigerated transport fleets operating Alberta-Saskatchewan corridors specify 3-5kW silicon carbide switched systems for precise viscosity management during temperature transitions. Lifecycle cost guarantees now dominate procurement criteria over upfront equipment pricing.
- Industrial:Process heating for biodiesel refinement and synthetic fuel synthesis demands sustained 24/7 operation, favoring immersion configurations with predictive maintenance telemetry.
- Automotive:OEM integration into electric commercial vehicle thermal management architectures responds to EPA Phase 3 greenhouse gas compliance timelines.
- Residential:Standby generators and home heating oil systems occupy smaller addressable pools with less stringent cold-weather performance guarantees.
Commercial leads on scale; automotive leads on momentum.
Technology:
Energy conversion mechanism determines efficiency curves, element longevity, and electromagnetic compatibility qualification pathways.
- Resistance:Nickel-chromium alloy elements dominate installed base with mature supply chains, though copper and nickel price volatility squeezes margin pools for mid-tier assemblers lacking long-term supply agreements.
- Induction:Eddy current heating eliminates element degradation, justifying premium positioning in high-cycle industrial settings. Core magnetics concentrate among East Asian wound-component specialists, exposing European and North American integrators to geographic supply risk.
- Infrared:Radiant energy transfer serves specialized surface heating applications where direct fuel contact poses safety constraints.
- Radiant:Distributed thermal patterns suit large-volume fuel conditioning in marine and stationary storage contexts.
Resistance leads on scale; induction leads on momentum.
End User:
Procurement authority and technical specification capability vary sharply across fragmented demand clusters.
- Fleet Operators:Cold-chain logistics companies with Minnesota, Wisconsin, and Michigan route density command volume pricing leverage and demand 10-year thermal performance warranties with predictive maintenance telemetry.
- Factories:Process industry operators specify industrial-grade immersion systems for biodiesel and synthetic fuel conditioning with continuous duty requirements.
- Workshops:Independent service facilities drive aftermarket retrofit demand for direct-contact resistance heaters in legacy diesel fleets.
- Households:Residential standby generator owners represent price-sensitive, specification-light demand with minimal cold-weather performance guarantees.
Fleet operators lead on scale; factories lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where electric fuel heater production concentrates, as compliance cost gaps between jurisdictions incentivize supplier migration toward markets with streamlined certification pathways and concentrated fleet operator demand.
United States
EPA Phase 3 greenhouse gas standards and NHTSA fuel economy mandates compel commercial vehicle OEMs to integrate electric fuel heaters into thermal management architectures. Cold-chain logistics operators across Minnesota, Wisconsin, and Michigan corridors drive specification intensity for sub-zero rated systems. The Upper Midwest cluster around Minneapolis-St. Paul anchors fleet electrification program deployment.
Germany
ECE R10 electromagnetic compatibility regulations govern heater electronics access to European automotive markets, creating barrier-to-entry advantages for pre-qualified suppliers. REACH substance restrictions on hexavalent chromium coatings force housing redesigns with plasma electrolytic oxidation alternatives. Stuttgart and Munich automotive engineering centers concentrate OEM thermal systems integration activity.
China
GB standards for vehicle electrical safety shape export qualification requirements for component suppliers targeting domestic and overseas markets. Dual carbon goals accelerate commercial fleet electrification timelines, pulling demand toward heavy-duty logistics applications. Yangtze River Delta manufacturing clusters around Shanghai supply wound-component magnetics for induction heater cores.
Norway
Arctic corridor freight operators remain underpenetrated by incumbent suppliers, offering first-mover positioning for systems rated below -40°C operational thresholds. Norwegian and Finnish transit authorities now require 10-year thermal performance warranties with predictive maintenance telemetry. Oslo and Tromsø municipal procurement departments are pivoting specification behavior toward lifecycle cost guarantees.
Canada
Alberta and Saskatchewan cold-chain fleet operators specify silicon carbide switched systems for precise viscosity management during temperature transitions. Federal emissions alignment with US EPA standards creates harmonized compliance pathways for cross-border supplier qualification. Edmonton and Calgary logistics hubs concentrate refrigerated transport fleet electrification investment.
Electric Fuel Heater Market Vendor Landscape
Capacity expansion dominates the current landscape as suppliers race to meet compressed development cycles for thermal management subsystems. The vendor base organizes around three strategic tiers: diversified industrial conglomerates with automotive heritage, specialized thermal engineering firms with industrial process expertise, and regional aftermarket distributors with extensive service networks. Geographic expansion and technology licensing represent the two most active competitive vectors, with European and North American assemblers seeking to reduce exposure to East Asian magnetics concentration.
Among diversified industrial conglomerates, Bosch and Mahle GmbH exemplify the automotive-heritage archetype with established OEM supply relationships. Chromalox occupies a position within the specialized industrial tier, reflecting deep expertise in immersion configurations for off-highway and marine applications. Phillips & Temro Industries anchors the regional distribution archetype, sitting within North American aftermarket channels where extensive distributor coverage creates defensive positioning against direct OEM encroachment.
| Leading Market Players |
|---|
| Phillips & Temro Industries |
| Chromalox |
| Watlow |
| Warren Electric Corporation |
| Mahle GmbH |
| Gaumer Process |
| GE Power Systems |
| Wattco |
| Bosch |
| Others |
Supply Flow & Price Mechanics
Cold-chain fleet operators with concentrated procurement authority in Minnesota, Wisconsin, and Michigan corridors command volume pricing leverage that compresses margin pools for mid-tier suppliers lacking long-term service bundling capabilities. These buyers negotiate lifecycle cost guarantees rather than transactional equipment pricing, reshaping how heater manufacturers structure revenue recognition across 10-year thermal performance warranties.
Pricing Analysis
Distributor margins absorb the steepest compression as direct OEM relationships displace aftermarket channel intermediaries in fleet electrification programs. Three-tier pricing structure across premium, standard, and economy levels separates silicon carbide switched systems from conventional resistance configurations from unbranded retrofit kits. Pricing pressure stems from copper and nickel commodity volatility squeezing resistance element manufacturing. Fleet operators demonstrate lowest price sensitivity where predictive maintenance telemetry bundles into procurement specifications.
Supply Chain Analysis
Workforce scarcity for wound-component magnetics specialists in Yangtze River Delta clusters constrains induction heater core production expansion. Manufacturing concentrates in China, Germany, and Mexico with component sourcing anchored in East Asian semiconductor fabrication for silicon carbide MOSFETs. Raw material dependencies span nickel-chromium alloys, copper busbar stock, and electromagnetic steel laminations. Single-source vulnerability for precision magnetics exposes European and North American assemblers to geographic concentration risk. Distribution runs through systems integrators capable of underwriting long-term service obligations rather than traditional component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards suppliers who arbitrage certification cost differentials between ECE R10 pre-qualification pathways in Europe and streamlined EPA compliance timelines in the US, capturing margin premiums where regulatory barriers delay competitor entry.
For Market Incumbents: Deploy certification pre-qualification investments to lock in barrier-to-entry advantages before REACH coating chemistry deadlines force housing redesigns. Secure long-term nickel and copper supply agreements to insulate margin pools from commodity volatility. Solid-state battery thermal substitution threatens displacement in certain commercial vehicle segments; counter by deepening software-defined thermal control capabilities that extend relevance across emerging powertrain architectures. For New Entrants and Emerging Players: Fleet operator procurement departments in Arctic corridor freight operations represent the most penetrable entry point, as Norwegian and Finnish transit authorities remain under-served by incumbent suppliers. Target hydrogen fuel cell integration applications where cryogenic storage thermal management requirements create adjacent demand beyond conventional diesel architectures. Establish direct relationships with municipal bus procurement departments specifying lifecycle cost guarantees to bypass established distributor networks. For Investors and Strategic Acquirers: Diversified industrial conglomerates with automotive thermal management heritage are the most active acquirer in this space, seeking to consolidate supplier bases as OEMs compress development cycles. Acquisition target archetypes include specialized induction heater engineering firms with established East Asian magnetics sourcing relationships and ECE R10 testing capabilities. Watch solid-state battery commercialization timelines as the critical inflection signal for auxiliary fuel heating displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| ECE R10 Certification Pre-Qualification | Creates 18-24 month barrier-to-entry advantages for European automotive market access. |
| Silicon Carbide MOSFET Integration | Enables millisecond-level duty cycle control for Alberta-Saskatchewan cold-chain fleet specifications. |
| Plasma Electrolytic Oxidation Coating Transition | Substitutes hexavalent chromium to maintain REACH compliance for German and French OEM channels. |
| Predictive Maintenance Telemetry Development | Satisfies Danish and Swedish transit authority requirements for 10-year thermal performance warranties. |
| Arctic Corridor Geographic Expansion | Captures first-mover positioning in Norway and Finland for systems rated below -40°C operational thresholds. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with fleet procurement directors, OEM thermal systems engineers, aftermarket distributor principals, and coating chemistry suppliers. Secondary validation draws from EPA Phase 3 regulatory filings, ECE R10 electromagnetic compatibility test records, REACH substance restriction updates, and customs trade data for nickel-chromium alloy imports. Bottom-up demand modeling triangulates against top-down OEM production forecasts across the analysis window.
Granularity-level modeling disaggregates volume and value outputs by thermal delivery mechanism, installation configuration, energy conversion technology, and end-use thermal load profile. CAGRs derive from segment-specific adoption curves weighted by regulatory compliance timeline acceleration in the US and Europe. Forecast inputs incorporate fleet electrification program deployment schedules, solid-state battery commercialization trajectory assumptions, and hydrogen fuel cell platform thermal architecture specifications.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to battery-electric powertrain thermal load profile redefinitions and copper-nickel commodity price volatility. Forecasts reflect documented assumptions regarding EPA Phase 3 implementation pacing and ECE R10 testing capacity expansion. Material deviation in solid-state battery operating temperature range claims or REACH substance restriction enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Caribbean Islands Bunker Fuel Market
Fuels
Global Steam Coal Market
Fuels
Hydrogen Tube Trailer Market
Fuels
Fuel Analyzer Market
Fuels
North America Commercial Aircraft Aviation Fuel Market
Fuels
Brazil Bunker Fuel Market
Fuels
Smart Gas Market
Fuels
White Coal Market
Fuels
Underground Coal Gasification Market
Fuels
Fuel Conditioning System Market
Fuels
Iso-Octane Market
Fuels
Gasoline Market
Fuels
Europe Bunker Fuel Market
Fuels
LPG Gas Cylinder Market
Fuels
Middle-East and Africa Commercial Aircraft Aviation Fuel Market
Fuels
Coal Intelligent Dry Separators Market