
 Tuberculosis Vaccine Treatment Market | 2026-2036
Tuberculosis Vaccine Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Tuberculosis Vaccine Treatment Market Analytics
Community health organizations are collapsing the historical hospital-centric procurement model for tuberculosis vaccines. Merck & Co. anchors North American supply through sustained manufacturing scale for BCG production. Serum Institute of India dominates volume economics across South Asia and Africa through extensive channel control. GlaxoSmithKline positions its recombinant vaccine pipeline through specialized R&D partnerships with WHO and philanthropic funders.
Tuberculosis vaccine treatment encompasses immunological interventions designed to prevent or therapeutically manage Mycobacterium tuberculosis infection, typically formulated with attenuated live bacilli, recombinant proteins, or subunit antigens combined with novel adjuvants to stimulate cell-mediated immunity. These products serve public health systems, national immunization programs, and therapeutic protocols aimed at reducing active disease burden and latent infection progression. Recombinant vaccines capture expanding investment as developers pursue improved efficacy beyond BCG's variable protection, particularly for adolescent and adult populations. Intradermal delivery retains structural dominance due to established administration infrastructure, though intramuscular formats gain traction where healthcare worker training permits. Latent tuberculosis infection therapy areas attract accelerating clinical focus as health systems prioritize prevention over reactive treatment.
WHO prequalification programs shape market access for tuberculosis vaccines across low-income procurement channels, while FDA and EMA pathways govern commercialization in higher-regulated jurisdictions. India's CDSCO and national immunization technical advisory groups influence tender structures and domestic manufacturing requirements for suppliers like Serum Institute of India. National regulators in China and South Africa increasingly mandate local bridging studies, fragmenting approval timelines. Stakeholders must monitor evolving WHO policy recommendations on booster schedules and novel vaccine substitution, as these will determine procurement volumes and manufacturing commitments before formal guidance crystallizes.
Market Dynamics
BCG manufacturing concentration in India and South Africa is creating supply-side bottlenecks that constrain procurement flexibility for national immunization programs across sub-Saharan Africa and Southeast Asia. This geographic lock-in forces buyers into long-term tender commitments with limited supplier diversification.
Growth Catalysts
- WHO prequalification acceleration:Streamlined assessment pathways for novel TB vaccines are compressing market entry timelines for developers targeting low-income country procurement. This regulatory mechanism expands addressable populations beyond legacy BCG coverage.
- India's Universal Immunization Programme:Government tender volumes for BCG and pipeline candidates are scaling manufacturing capacity at domestic facilities. Serum Institute of India and Bharat Biotech anchor this demand pull through multi-year supply agreements.
- Novel adjuvant platforms:Matrix-M and AS01 formulations are enabling subunit vaccines to achieve cell-mediated immunity responses previously requiring live-attenuated constructs. These technologies broaden the addressable therapeutic window to latent infection populations.
Market Restraints
- BCG strain supply concentration:Denmark-derived 1331 substrain production centers on a single European facility and Serum Institute of India, creating single-source vulnerability for WHO prequalified supply.
- Cold chain infrastructure gaps:Last-mile distribution in the Democratic Republic of Congo, Nigeria, and Indonesia limits effective vaccine coverage despite procurement commitments.
- Regulatory bridging study mandates:China's NMPA and South Africa's SAHPRA increasingly require local immunogenicity data, fragmenting approval timelines and duplicating clinical expenditure.
Strategic Opportunities
- Adolescent and adult booster segments:BCG's waning protection after childhood creates unmet need in 15-35 year cohorts across high-burden countries. Developers with T-cell targeted candidates can capture this whitespace.
- Therapeutic vaccine protocols:Adjunct immunotherapy for multidrug-resistant TB is gaining protocol inclusion in India's RNTCP guidelines. This application expands beyond prophylaxis into treatment-supportive indications.
- Intradermal microarray patches:Dissolving microneedle delivery systems are eliminating cold chain requirements and healthcare worker training barriers. This technology convergence opens community-based administration models.
Industry Challenges
- Good Manufacturing Practice remediation:Legacy BCG facilities require continuous facility upgrades to meet evolving WHO prequalification standards for environmental monitoring and contamination control.
- Latent infection biomarker validation:Lack of standardized correlates of protection complicates Phase III trial design and regulatory endpoint negotiation with FDA and EMA.
- Skilled fill-finish technician scarcity:Aseptic processing expertise for live-attenuated vaccines concentrates in Copenhagen and Pune manufacturing clusters, constraining geographic expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tuberculosis Vaccine Treatment Market |
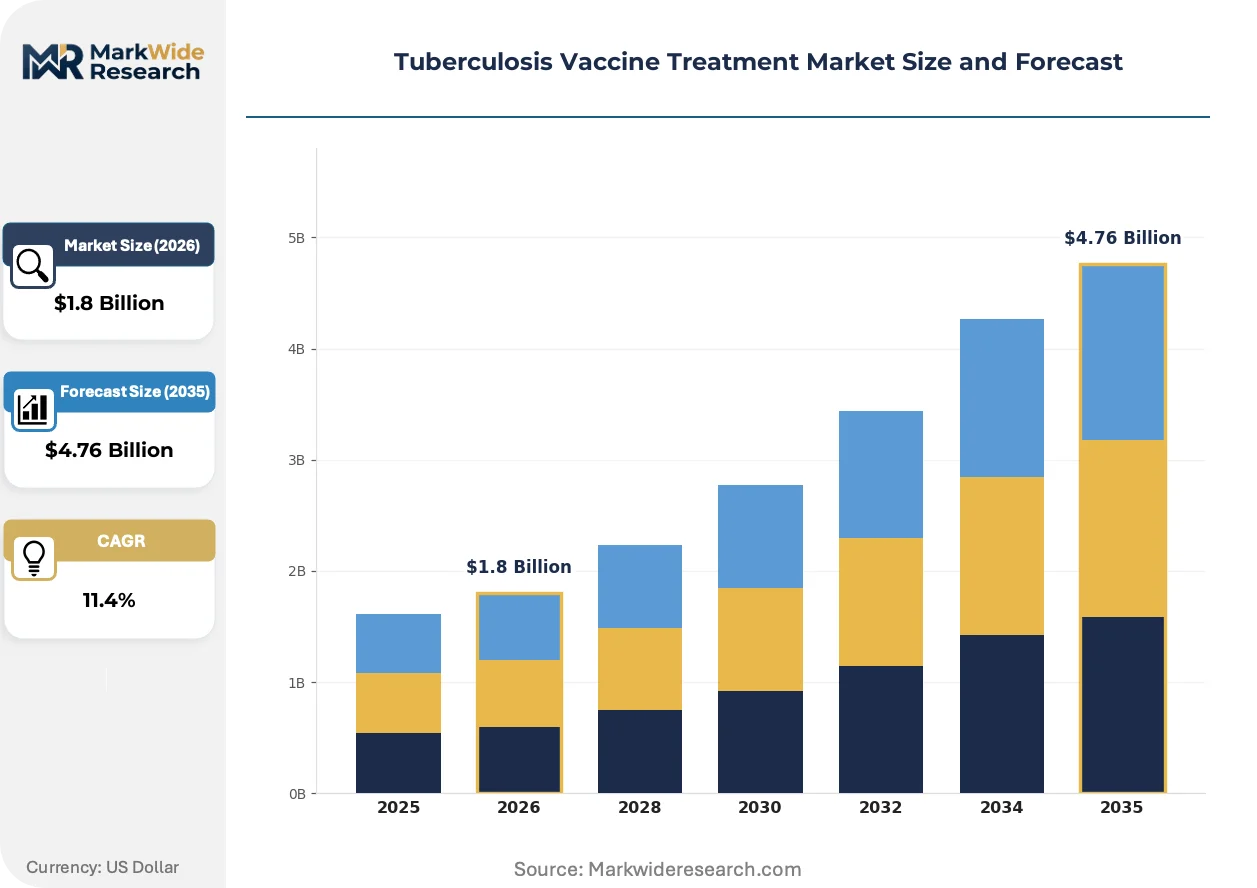
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: BCG, Recombinant Vaccines, Subunit Vaccines, Live Attenuated Vaccines Therapy Area: Active Tuberculosis, Latent Tuberculosis Infection, Preventive Vaccination, Booster Vaccination Delivery Mode: Intramuscular, Intradermal, Oral, Subcutaneous End User: Hospitals, Clinics, Research Institutions, Community Health Organizations |
| Companies Covered | GlaxoSmithKline, Sanofi, Merck & Co., Pfizer, Serum Institute of India, Bavarian Nordic, AstraZeneca, Japan BCG Laboratory, Biofabri, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tuberculosis Vaccine Treatment Market Evolving Landscape
Recombinant subunit platforms are displacing live-attenuated dominance in tuberculosis vaccine development pipelines, driven by improved safety profiles for immunocompromised populations and manufacturing scalability advantages.
AS01-adjuvanted fusion protein constructs are displacing alum-based formulations in Phase II/III candidates. GlaxoSmithKline's M72/AS01E candidate has demonstrated sustained efficacy in latent infection populations, prompting adoption interest from PEPFAR and national TB programs in Kenya and Vietnam. This adjuvant shift is compressing development timelines for candidates previously dependent on live-vector delivery complexity.
EMA's adaptive pathway designation for tuberculosis vaccines is accelerating conditional approval frameworks for products targeting unmet medical need in multidrug-resistant settings. The industrial consequence is compressed Phase IIb-to-approval timelines for developers with robust immunogenicity biomarkers. Subunit vaccine developers targeting European markets are restructuring clinical programs to leverage this mechanism, prioritizing surrogate endpoint validation over traditional prevention-of-disease trials.
Community health worker administration is displacing facility-based immunization for BCG birth-dose delivery in Ethiopia, Bangladesh, and Pakistan. This channel shift reduces dropout between birth and first contact with formal health systems. Ministries of health are integrating this model into national immunization strategies, with procurement contracts now specifying field-stable presentation requirements and simplified logistics training modules.
Tuberculosis Vaccine Treatment Market Segmentation
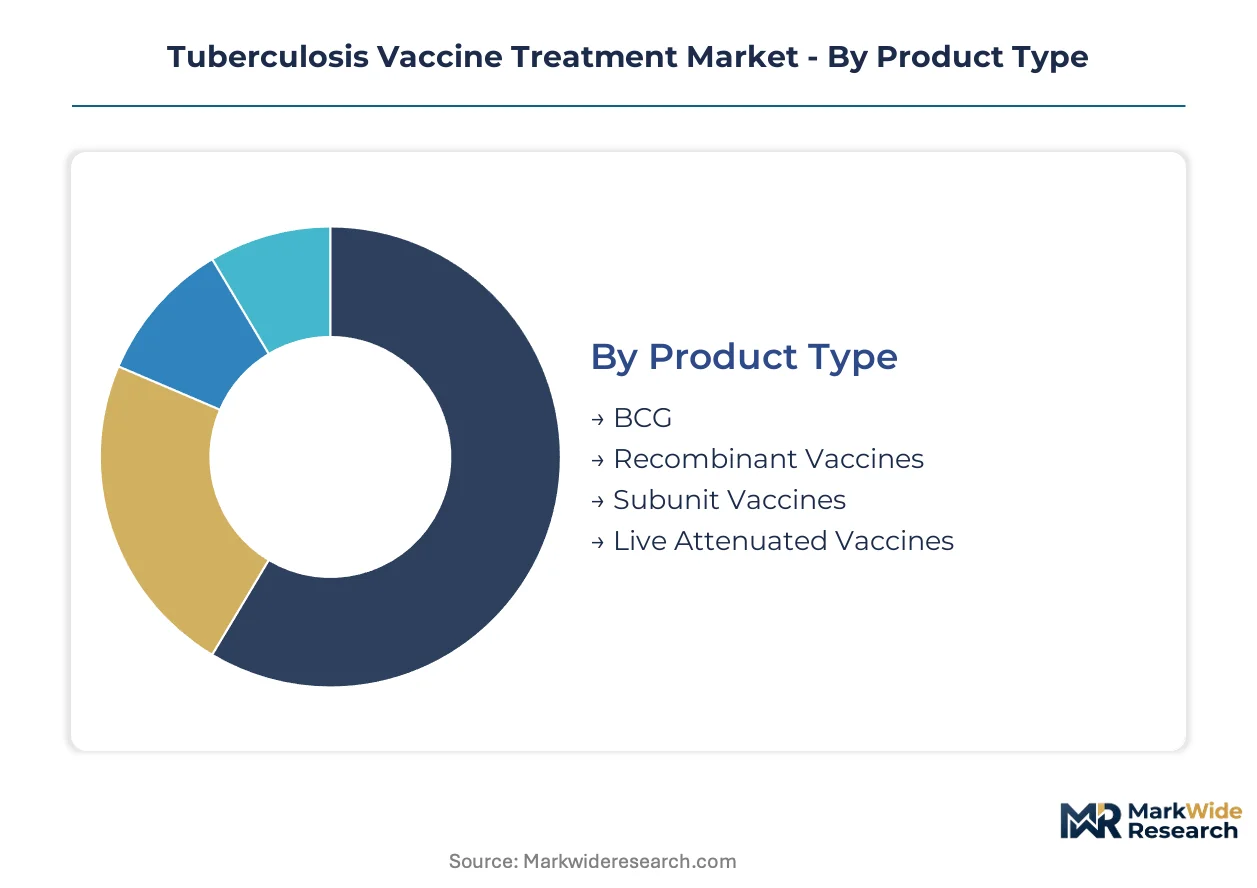
Segmentation in tuberculosis vaccines reveals how procurement power, clinical application, and delivery infrastructure allocate value across the value chain. Product type and therapy area divisions expose where legacy BCG dominance faces displacement pressure from novel platforms.
Product Type:
Recombinant and subunit platforms are exerting substitution pressure on live-attenuated formats, particularly where immunocompromised safety and manufacturing scalability matter.
- BCG:The attenuated live Mycobacterium bovis strain remains the foundation of national immunization programs. Demand concentrates in India's Universal Immunization Programme and African procurement tenders, constrained by single-source manufacturing vulnerability for the Denmark 1331 substrain.
- Recombinant Vaccines:Engineered protein or vector-based constructs target improved efficacy beyond BCG's variable protection. Developers like GlaxoSmithKline pursue adolescent and adult populations through WHO and philanthropic partnerships, with AS01-adjuvanted candidates gaining protocol interest.
- Subunit Vaccines:Purified antigen formulations combined with novel adjuvants enable cell-mediated immunity without live-vector risks. Matrix-M platforms are broadening the therapeutic window to latent infection populations previously excluded from live-attenuated protocols.
- Live Attenuated Vaccines:Modified mycobacterial strains beyond classical BCG seek enhanced durability of protection. Development concentrates in specialized R&D consortia targeting multidrug-resistant TB settings.
BCG anchors the volume base while recombinant vaccines gain share at the steepest rate.
Therapy Area:
Cost tier stratification separates prophylactic mass vaccination from targeted therapeutic protocols requiring higher per-dose investment and specialized administration.
- Active Tuberculosis:Therapeutic adjunct immunization for drug-resistant cases is gaining inclusion in India's RNTCP guidelines. This application commands premium pricing but serves limited patient volumes compared to preventive programs.
- Latent Tuberculosis Infection:Prevention of progression from latent to active disease represents the largest addressable expansion opportunity. M72/AS01E candidates have demonstrated sustained efficacy in this population, prompting PEPFAR and Vietnam national program adoption interest.
- Preventive Vaccination:Birth-dose BCG administration through community health worker models in Ethiopia, Bangladesh, and Pakistan is reducing dropout between birth and formal health system contact. Procurement contracts now specify field-stable presentation requirements.
- Booster Vaccination:Adolescent and adult revaccination addresses BCG's waning childhood protection in high-burden countries. T-cell targeted candidates capture this whitespace where national technical advisory groups revise schedule recommendations.
Preventive vaccination dominates procurement volumes while latent infection therapy climbs the fastest.
Delivery Mode:
Volume concentration favors established intradermal infrastructure, though alternative routes gain traction where healthcare worker training and cold chain limitations apply.
- Intradermal:The standard BCG administration route leverages existing birth-dose infrastructure across South Asia and sub-Saharan Africa. Community health worker programs in Pakistan and Bangladesh have validated field deployment feasibility without facility-based requirements.
- Intramuscular:Recombinant subunit candidates increasingly favor this route where adjuvant formulations permit simpler logistics. Training requirements limit penetration in lowest-resource settings despite manufacturing advantages.
- Oral:Mucosal delivery platforms remain developmental, targeting elimination of needle requirements and cold chain dependence. No WHO-prequalified products currently serve this route.
- Subcutaneous:Alternative to intradermal for specific adjuvanted formulations requiring deeper tissue deposition. Limited commercial presence outside research protocols.
Intradermal delivery maintains volume leadership while intramuscular formats expand most quickly among novel candidates.
End User:
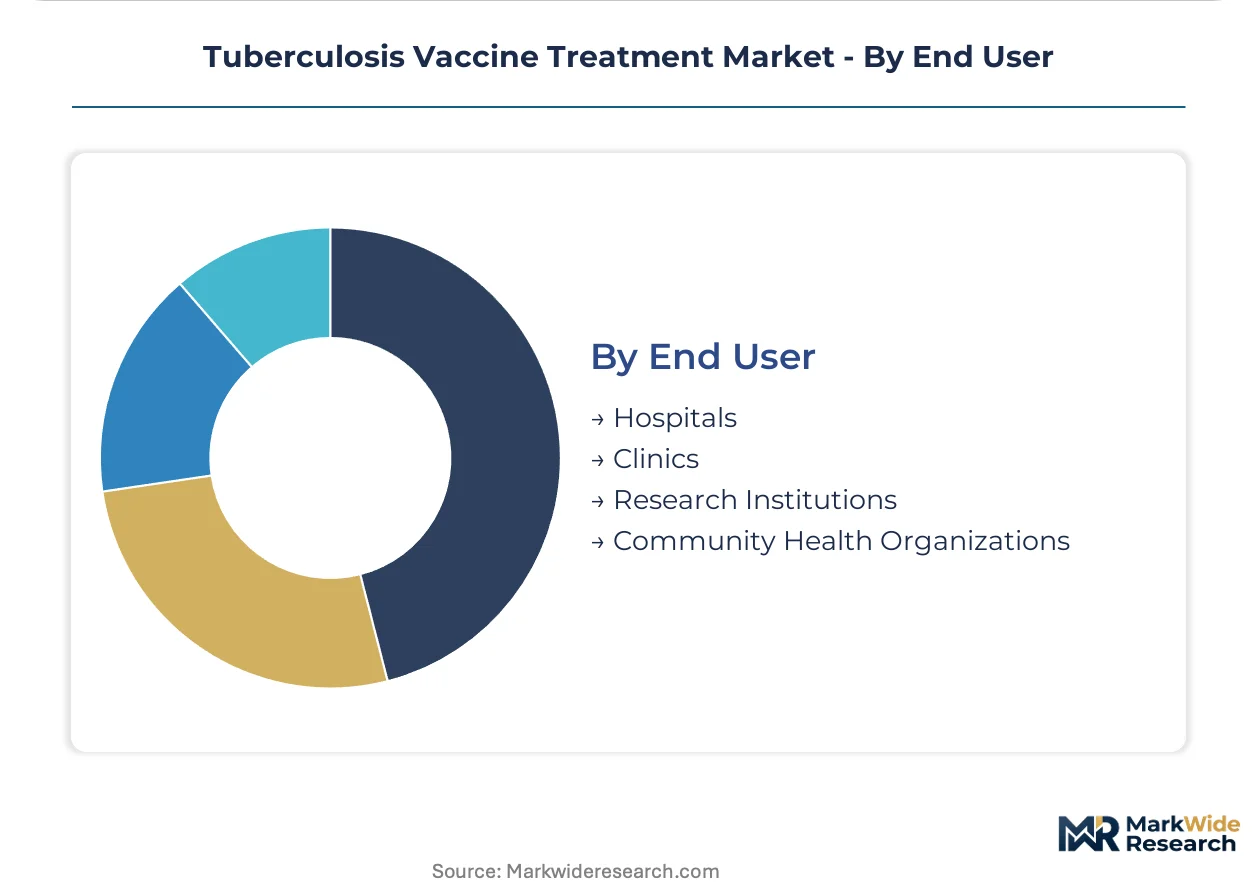
Customer type fragmentation reflects the collapse of hospital-centric procurement toward community-based and research-channel segmentation.
- Hospitals:Tertiary facilities manage complex multidrug-resistant TB cases requiring therapeutic vaccine protocols. Concentrated in urban India, South Africa, and China where specialist infrastructure exists.
- Clinics:Primary health centers anchor BCG birth-dose delivery in formal health systems. India's sub-center network and Nigeria's primary care facilities represent volume concentration points.
- Research Institutions:Clinical trial sites and product development partnerships drive pipeline candidate evaluation. WHO collaborating centers in Kenya, Vietnam, and South Africa host Phase IIb/III studies.
- Community Health Organizations:Non-governmental implementers are displacing facility-based models for birth-dose coverage in Ethiopia, Bangladesh, and Pakistan. Procurement specifications now integrate simplified logistics training modules.
Clinics anchor the volume base while community health organizations gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Copenhagen-Pune manufacturing corridor anchors global BCG supply through specialized aseptic processing infrastructure connecting Denmark's legacy facilities to India's Serum Institute production campus.
India
Universal Immunization Programme tenders drive procurement volumes exceeding 25 million annual BCG doses. CDSCO mandates local bridging studies for novel adjuvanted candidates entering Phase III evaluation. Pune's Serum Institute campus concentrates Denmark 1331 substrain production alongside recombinant vaccine fill-finish capacity expansion.
South Africa
SAHPRA's immunogenicity data requirements fragment approval timelines for subunit candidates targeting adolescent boosters. Johannesburg-Pretoria corridor hosts WHO collaborating centers conducting Phase IIb efficacy trials. Biofabri's local partnerships anchor therapeutic vaccine development for multidrug-resistant TB protocols.
United States
FDA's breakthrough therapy designation pathway accelerates review for candidates addressing latent infection progression in immunocompromised populations. Merck & Co.'s West Point facility sustains BCG production for domestic multidrug-resistant TB therapeutic protocols. Baltimore-Washington research corridor concentrates NIH-funded adjuvant platform development.
China
NMPA's local clinical trial mandates compel developers to establish domestic Phase III sites for recombinant candidates. Shanghai-Beijing corridor hosts state-owned vaccine manufacturers scaling BCG production for national immunization expansion. Chengdu's biotechnology cluster specializes in novel vector platform construction for next-generation candidates.
United Kingdom
EMA's adaptive pathway designation compresses conditional approval timelines for products targeting unmet medical need. London-Oxford-Cambridge golden triangle concentrates GlaxoSmithKline's M72/AS01E development program and associated T-cell immunology research. Oxford's Jenner Institute anchors viral vector platform innovation for tuberculosis vaccine delivery.
Tuberculosis Vaccine Treatment Market Competitive Landscape
Concentration sits with legacy BCG manufacturers and recombinant platform developers, creating a bifurcated structure where volume economics and innovation premiums occupy separate competitive spaces. Two strategic archetypes dominate: established live-attenuated producers leveraging WHO prequalification status and subunit specialists pursuing adolescent-adult segments through novel adjuvant partnerships. Capacity expansion at Pune and Copenhagen facilities represents the primary competitive move, while technology licensing agreements for Matrix-M and AS01 formulations constitute the secondary vector.
Among European-headquartered pharmaceutical conglomerates, GlaxoSmithKline exemplifies the recombinant adjuvant archetype through its AS01 platform positioning. Merck & Co. occupies the established BCG manufacturing tier with sustained North American supply commitment. Serum Institute of India represents the volume-anchored domestic producer archetype, controlling South Asian and African procurement channels through government tender relationships.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| Sanofi |
| Merck & Co. |
| Pfizer |
| Serum Institute of India |
| Bavarian Nordic |
| AstraZeneca |
| Japan BCG Laboratory |
| Biofabri |
| Others |
Value Network & Pricing Analysis
Multi-year tender commitments with Serum Institute of India and Copenhagen facilities lock procurement access and price visibility for national immunization programs, compressing supplier flexibility while anchoring cost predictability across WHO prequalified channels.
Pricing Analysis
Volume-discount tiering structures separate UNICEF consolidated tenders from bilateral government negotiations and spot procurement for emergency stockpiles. Price differentiation rests on cold chain certification grade and volume scale, with Gavi-eligible countries accessing lowest tiers through pooled purchasing. Cost compression in live-attenuated segments is intensifying as legacy BCG facilities require continuous GMP remediation investments. National immunization programs in sub-Saharan Africa demonstrate highest price sensitivity, while therapeutic vaccine protocols for multidrug-resistant TB in tertiary hospitals tolerate premium positioning.
Supply Chain Analysis
Inventory lead times for Denmark 1331 substrain concentrate extend manufacturing cycles, forcing buyers into forward-commitment structures that amplify single-source vulnerability. Supply concentrates in India and Denmark, with fill-finish capacity expansion at Pune facilities drawing from Copenhagen bulk supply. Raw material dependencies include mycobacterial seed stocks, specialized culture media, and novel adjuvant formulations from GlaxoSmithKline's AS01 platform. Single-source vulnerability for WHO-prequalified BCG supply represents the dominant structural risk. Distribution runs through UNICEF's Vaccine Independence Initiative and direct government tenders to national cold chain networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating through UNICEF and Gavi pooled procurement mechanisms, fragmenting bilateral negotiation leverage and compressing margin capture for suppliers outside prequalified channels.
For Market Incumbents: Consolidate manufacturing scale through capacity addition at Pune and Copenhagen facilities to defend against recombinant subunit substitution pressure. Secure backward integration into novel adjuvant supply through licensing agreements with Matrix-M and AS01 platform holders, reducing dependency on external formulation partnerships. For New Entrants and Emerging Players: Community health worker training and field-stable presentation gaps in Ethiopia, Bangladesh, and Pakistan offer white-space entry points where incumbents under-serve last-mile delivery requirements. Target latent tuberculosis infection therapy segments through intradermal microarray patch development, leveraging simplified logistics as the primary go-to-market angle against cold chain-dependent competitors. For Investors and Strategic Acquirers: Adjuvant platform specialists with WHO prequalification pathways and T-cell immunology capabilities represent the priority acquisition archetype for portfolio exposure to next-generation vaccine substitution. Monitor WHO policy recommendation timing on booster schedules and novel vaccine substitution as the critical inflection signal for manufacturing commitment cycles and procurement volume shifts.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway Advancement | Streamlined assessment compresses market entry timelines for developers targeting low-income country procurement through UNICEF channels. |
| Novel Adjuvant Platform Licensing | AS01 and Matrix-M partnerships enable subunit vaccines to achieve cell-mediated immunity responses without live-vector manufacturing complexity. |
| Community Health Worker Training Program | Field deployment capabilities in Pakistan and Bangladesh reduce dropout between birth and formal health system contact. |
| Cold Chain Infrastructure Partnership | Last-mile distribution investments in Democratic Republic of Congo and Nigeria expand effective coverage beyond procurement commitments. |
| Latent Infection Biomarker Validation | Standardized correlates of protection streamline Phase III trial design and regulatory endpoint negotiation with FDA and EMA. |
Research Methodology
Desk research of WHO prequalification databases, national immunization program tender records, and clinical trial registries preceded structured interviews with vaccine development executives, regulatory affairs leads at CDSCO and SAHPRA, national procurement managers, and cold chain logistics specialists. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and Gavi disbursement reports. Bottom-up demand modeling across product type, therapy area, delivery mode, and end user segments was triangulated against top-down macroeconomic indicators.
Variance decomposition across the projection horizon isolates volume drivers from price effects and mix shifts. Segmentation dimensions modeled include product type, therapy area, delivery mode, end user, and regional regulatory cluster. CAGRs were derived from trend extrapolation of procurement volumes, adjusted for policy recommendation timing and manufacturing capacity constraints. Forecast inputs incorporate WHO prequalification pipeline status, national immunization schedule revisions, and adjuvant platform licensing activity.
Forecasts assume regulatory continuity in WHO prequalification pathways, FDA breakthrough therapy designations, and EMA adaptive frameworks; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Mitochondrial-Based Therapeutics Market
Pharmaceuticals
Global Pharmaceutical Contract Manufacturing Market
Pharmaceuticals
OTC Dry Eye Drops Market
Pharmaceuticals
Blood Market
Pharmaceuticals
Europe Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Europe Sodium-Dependent Glucose Cotransporter 2 Market
Pharmaceuticals
Global Gout Therapeutics Market
Pharmaceuticals
Teriflunomide Market
Pharmaceuticals
High Potency API Contract Manufacturing Market
Pharmaceuticals
Asia-Pacific Contraceptive Drugs and Devices Market
Pharmaceuticals
Asia-Pacific Over-The-Counter (OTC) Drugs Market
Pharmaceuticals
Anti Obesity Prescription Drugs Market
Pharmaceuticals
Nucleic Acid Therapeutics Contract Development and Manufacturing Organization Market
Pharmaceuticals
Leflunomide Market
Pharmaceuticals
Global Cytotoxic Drugs Market
Pharmaceuticals
Global Postpartum Depression Drugs Market