
 Teriflunomide Market | 2026-2036
Teriflunomide Market Size, Share, and Industry Trends Forecast 2026-2036
Teriflunomide Market Analytics
Project finance structures and royalty-backed lending arrangements are reshaping which generic manufacturers can fund bioequivalence studies for teriflunomide copies. Sanofi leverages its originator infrastructure to sustain brand loyalty in European markets where healthcare systems reference-price generics aggressively. Glenmark Pharmaceuticals anchors its competitive position through vertical integration into active pharmaceutical ingredient production for immunomodulators. Teva Pharmaceutical Industries Ltd. competes by controlling distribution relationships with large outpatient pharmacy chains across North America.
Teriflunomide is a small-molecule immunomodulatory agent, specifically the active metabolite of leflunomide, functioning as a dihydroorotate dehydrogenase inhibitor that disrupts pyrimidine synthesis in rapidly dividing lymphocytes to reduce autoimmune-mediated neural inflammation. Its primary commercial purpose centers on long-term oral maintenance therapy for relapsing-remitting multiple sclerosis, offering a once-daily tablet alternative to injectable or infusion-based disease-modifying therapies. Tablet formulations dominate volume due to established manufacturing scalability and patient familiarity, while extended-release formats represent a developing margin pool as patent cliffs encourage differentiation. Hospitals remain the largest therapeutic area channel for initial prescription and monitoring, though homecare settings are gaining share as oral administration reduces infusion center dependency.
The FDA's bioequivalence standards for teriflunomide generics, alongside EMA's requirements for immunomodulatory risk management plans, shape both product development timelines and post-market surveillance obligations for manufacturers. India's CDSCO imposes additional pharmacovigilance mandates on imported immunomodulators that filter which multinational suppliers secure marketing authorization. Stakeholders must monitor how evolving FDA guidance on complex generic immunomodulators alters the economic viability of ANDA filings versus novel formulation investments.
Market Dynamics
Oral immunomodulators are displacing infusion-based multiple sclerosis therapies as healthcare systems prioritize outpatient cost containment and patient convenience, compressing hospital pharmacy margins while expanding retail and homecare channel influence.
Growth Catalysts
- Medicare reimbursement policy:US Medicare reimbursement structures favor oral disease-modifying therapies over infusion-based alternatives, redirecting patient volume toward teriflunomide prescriptions and reducing total cost of care for relapsing-remitting multiple sclerosis.
- EMA risk management frameworks:European Medicines Agency requirements for immunomodulatory safety monitoring have standardized post-market surveillance protocols, reducing regulatory uncertainty for manufacturers expanding teriflunomide portfolios across EU member states.
- German neurology clinic expansion:Outpatient neurology clinics in Germany are scaling oral immunomodulator prescribing capacity, creating concentrated demand nodes that reward manufacturers with established hospital-to-homecare transition protocols.
Market Restraints
- Active pharmaceutical ingredient concentration:Teriflunomide API production concentrates among a limited set of Indian and Chinese contract manufacturers, exposing generic developers to supply disruption risks and input cost volatility.
- FDA complex generic bioequivalence standards:The FDA's immunomodulator bioequivalence requirements for ANDA filings extend development timelines and elevate clinical study costs, filtering out undercapitalized generic entrants.
- Injectable DMT residual preference:Neurologists in some markets retain preference for natalizumab and ocrelizumab infusions in high-activity relapsing multiple sclerosis, limiting teriflunomide's addressable patient pool to moderate-severity cases.
Strategic Opportunities
- Extended-release formulation development:Patent cliff pressures are incentivizing investments in modified-release teriflunomide formats that differentiate on dosing convenience and capture premium pricing in markets with aggressive generic reference pricing.
- Homecare monitoring infrastructure:Remote patient monitoring platforms for hepatic enzyme surveillance and teratogenic risk management enable direct-to-patient distribution models that bypass traditional hospital pharmacy gatekeepers.
- India CDSCO import authorization pathways:India's Central Drugs Standard Control Organization pharmacovigilance mandates for imported immunomodulators create first-mover advantages for multinational suppliers that establish local safety databases and distribution partnerships.
Industry Challenges
- Specialized pharmacovigilance workforce scarcity:Teriflunomide's teratogenicity risk and hepatic monitoring requirements demand rare combinations of immunology expertise and regulatory reporting capability, constraining manufacturer scaling.
- Legacy distribution contract renegotiation:Originators' long-term exclusive agreements with outpatient pharmacy chains create friction for generic entrants seeking shelf placement and formulary access in North American markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Teriflunomide Market |
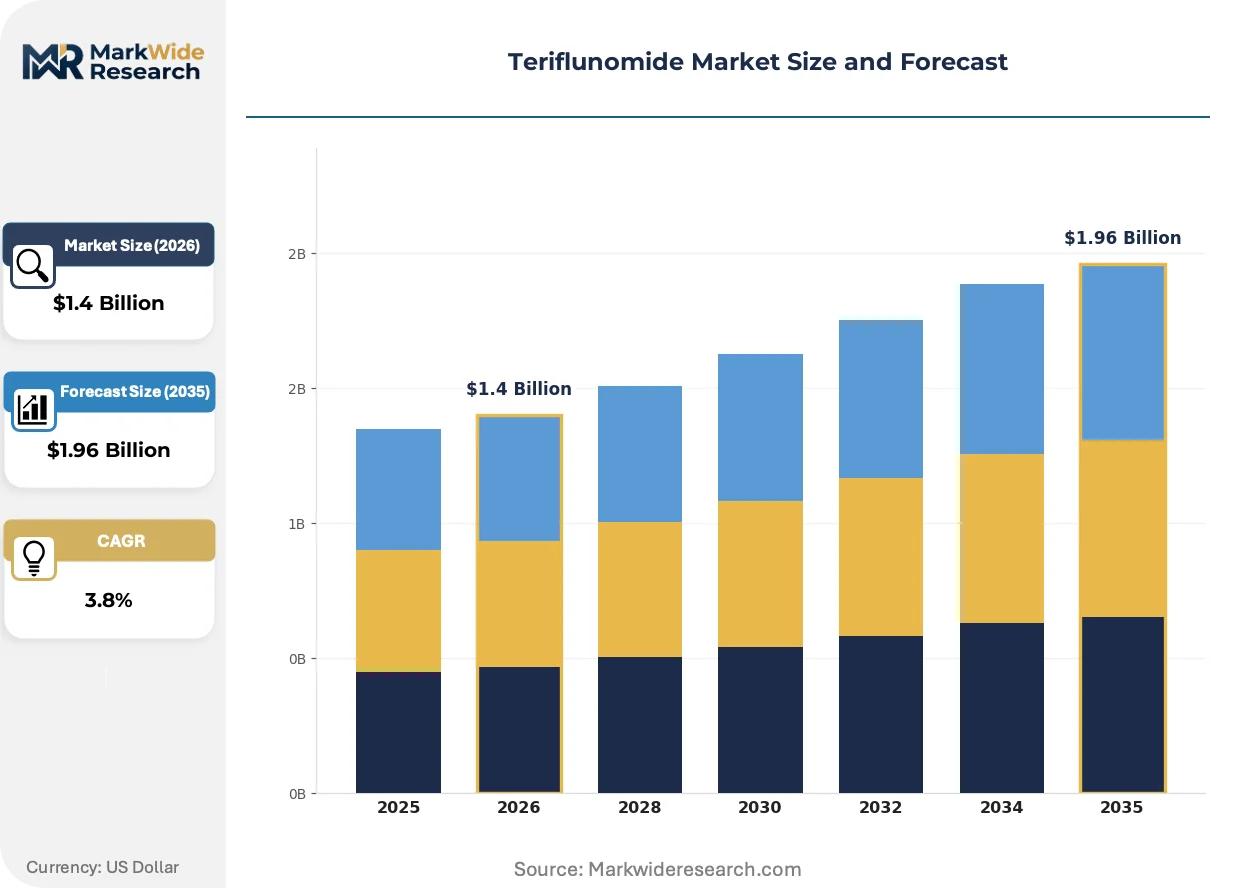
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $1.96 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Formulation Type: Tablet, Injectable, Oral Suspension, Extended Release Therapeutic Area: Multiple Sclerosis, Autoimmune Disorders, Neurology, Oncology End User: Hospitals, Outpatient Clinics, Homecare, Pharmacies Distribution Channel: Direct Sales, Wholesalers, Online Pharmacies, Retail Pharmacies |
| Companies Covered | Sanofi, Genzyme Corporation, Amneal Pharmaceuticals NY LC, Glenmark Pharmaceuticals, MSN Laboratories Private Limited, Alembic Pharmaceuticals, Natco, Teva Pharmaceutical Industries Ltd., Midas Pharma GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Teriflunomide Market Evolving Landscape
Digital therapeutics integration and formulation science advances are compressing traditional multiple sclerosis care pathways, enabling remote patient management while creating new competitive differentiation vectors beyond molecular equivalence.
Continuous manufacturing platforms for small-molecule immunomodulators are virtualizing batch production economics. Contract development and manufacturing organizations serving the teriflunomide supply chain are adopting modular flow chemistry systems that reduce solvent waste and compress cycle times. European generic manufacturers with captive API-to-tablet integration are capturing margin pools that batch-dependent competitors cannot access.
The FDA's streamlined ANDA review pathway for complex generics is compressing approval timelines for teriflunomide copies with differentiated delivery mechanisms. This regulatory efficiency is accelerating manufacturer entry into markets where patent cliffs have already eroded originator exclusivity. US-based generic developers with established immunomodulatory portfolios are prioritizing filings that leverage this pathway over novel formulation investments.
Hospital pharmacy procurement committees are unbundling disease-modifying therapy selection from infusion center economics, creating direct evaluation of oral versus injectable total cost of ownership. Neurology departments in US academic medical centers are piloting value-based formulary tiers that weight patient adherence metrics alongside drug acquisition costs. This behavioral shift concentrates volume with manufacturers offering comprehensive patient support programs rather than molecule-only supply.
Teriflunomide Market Segmentation
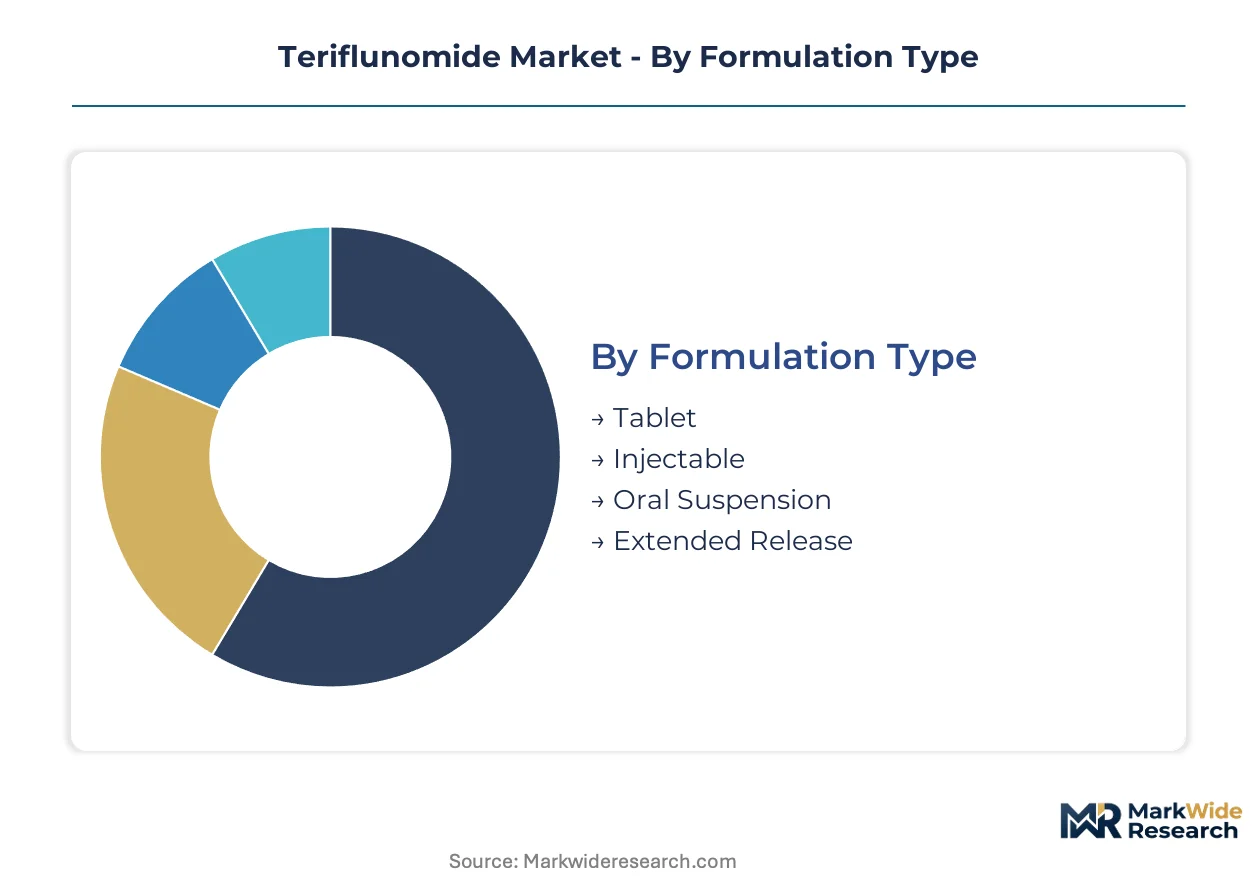
Teriflunomide's market structure fragments across formulation science, clinical application, and care delivery settings. Each segmentation axis reveals distinct margin pools, regulatory burdens, and competitive dynamics that determine manufacturer positioning.
Formulation Type:
After-sales service intensity varies sharply across formulation categories, with extended-release and injectable formats demanding specialized pharmacovigilance support that tablet generics rarely require.
- Tablet:Standard immediate-release tablets contain teriflunomide as the sole active pharmaceutical ingredient in 7mg and 14mg strengths. Hospital pharmacy procurement committees in the United States concentrate volume here due to established bioequivalence pathways and Medicare reimbursement familiarity. The segment rewards manufacturers with vertically integrated active pharmaceutical ingredient production.
- Extended Release:Modified-release matrices employ hydroxypropyl methylcellulose or ethylcellulose coatings to flatten plasma concentration curves. Neurology clinics in Germany are expanding prescriptions for this format as patent cliffs encourage differentiation beyond molecular equivalence. Development timelines extend due to FDA bioequivalence complexity.
- Injectable:Parenteral formulations serve acute exacerbation protocols and patients with severe gastrointestinal intolerance. Compounding pharmacies control regional supply.
- Oral Suspension:Liquid alternatives address dysphagia populations and pediatric off-label use. Specialist homecare distributors manage cold-chain requirements.
By volume, tablet leads. By growth pace, extended release is ahead.
Therapeutic Area:
Cost tier stratification separates high-acuity hospital administration from maintenance therapy economics, with oncology applications commanding premium pricing despite smaller patient pools.
- Multiple Sclerosis:Relapsing-remitting multiple sclerosis represents the approved indication, with once-daily oral dosing displacing interferon injections. Medicare reimbursement policies in the United States favor this therapeutic positioning over infusion-based disease-modifying therapies. Patient adherence metrics determine formulary tier placement.
- Autoimmune Disorders:Off-label use in rheumatoid arthritis and psoriatic arthritis leverages teriflunomide's dihydroorotate dehydrogenase mechanism. Outpatient rheumatology clinics in France are piloting protocols under ANSM risk management frameworks. Prescribing concentration follows leflunomide failure pathways.
- Neurology:Broader neuroinflammatory applications beyond multiple sclerosis remain investigational. Academic medical centers control trial enrollment.
- Oncology:Antiproliferative effects against hematologic malignancies are under clinical evaluation. Compassionate use programs filter access.
Multiple sclerosis dominates prescription volume. Autoimmune disorders are climbing the fastest.
End User:
Customer type segmentation tracks the migration from institutional purchasing toward direct-to-patient models, with homecare settings demanding integrated monitoring infrastructure.
- Hospitals:Academic medical centers and community hospital systems manage initial diagnosis, hepatic enzyme baseline establishment, and teratogenic risk counseling. Pharmacy procurement committees in US academic medical centers are unbundling disease-modifying therapy selection from infusion center economics. Formulary decisions weight total cost of ownership against patient adherence data.
- Homecare:Direct-to-patient distribution models bypass traditional hospital pharmacy gatekeepers through remote hepatic enzyme surveillance platforms. Neurology clinics in Germany are scaling hospital-to-homecare transition protocols. Regulatory compliance depends on specialized pharmacovigilance workforce availability.
- Outpatient Clinics:Neurology and rheumatology practices handle maintenance prescribing and monitoring. Reimbursement parity varies by state.
- Pharmacies:Retail and specialty pharmacy chains manage refill logistics and patient assistance programs. Exclusive distribution agreements create entry barriers.
Hospitals retain the largest share. Homecare shows the steepest expansion trajectory.
Distribution Channel:
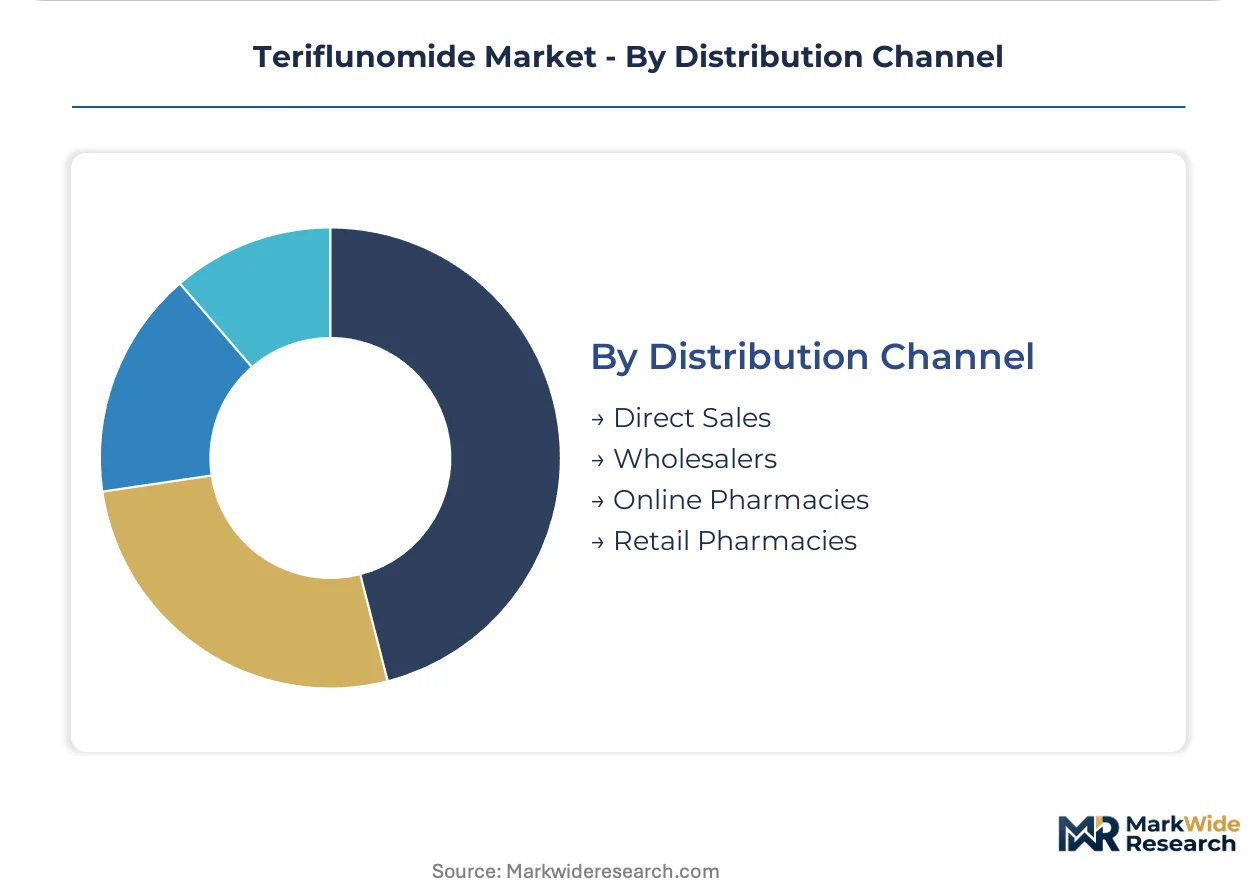
Supply concentration among wholesale distributors shapes price realization, with direct sales models capturing margin in concentrated metropolitan markets.
- Wholesalers:McKesson, AmerisourceBergen, and Cardinal Health control hospital and retail pharmacy supply chains across North America. Generic manufacturers compete for formulary placement through these intermediaries. Contract terms determine shelf access and inventory carrying costs.
- Direct Sales:Manufacturer-to-institution contracts serve large hospital systems and integrated delivery networks with volume commitments. Sanofi leverages originator infrastructure to sustain brand loyalty in European markets with aggressive generic reference pricing. Account management intensity correlates with contract value.
- Retail Pharmacies:CVS, Walgreens, and independent chains manage patient-facing dispensing and copay assistance. Formulary tiers vary by payer.
- Online Pharmacies:Mail-order and digital platforms serve chronic maintenance populations with 90-day supply protocols. Legitimacy verification requirements filter entrants.
Wholesalers move the most volume. Direct sales channels are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany exceeds that in India by a substantial margin, reflecting divergent reimbursement architectures and generic penetration rates. Healthcare systems in Western Europe reference-price aggressively while preserving originator loyalty through risk management protocols. Emerging markets impose pharmacovigilance burdens that filter multinational participation.
United States
Medicare reimbursement structures favor oral disease-modifying therapies over infusion-based alternatives, redirecting patient volume toward teriflunomide prescriptions. The FDA's streamlined ANDA review pathway for complex generics accelerates manufacturer entry into markets where patent cliffs have eroded exclusivity. Neurology departments in academic medical centers across Massachusetts and California pilot value-based formulary tiers weighting adherence metrics.
Germany
Outpatient neurology clinics scale oral immunomodulator prescribing capacity, creating concentrated demand nodes for hospital-to-homecare transition protocols. EMA risk management frameworks standardize post-market surveillance protocols, reducing regulatory uncertainty for portfolio expansion. The Rhine-Ruhr metropolitan cluster hosts specialized pharmacovigilance workforce pools serving immunomodulatory manufacturers.
India
Domestic API production concentrates among contract manufacturers in Gujarat and Maharashtra, exposing generic developers to input cost volatility. CDSCO import authorization pathways impose additional pharmacovigilance mandates that filter which multinational suppliers secure marketing authorization. Hyderabad's pharmaceutical corridor anchors active pharmaceutical ingredient supply for immunomodulators.
France
Outpatient rheumatology clinics pilot teriflunomide protocols for autoimmune disorders under ANSM risk management frameworks. Reimbursement parity varies by region, with Île-de-France concentrating prescribing authority in academic hospital systems. The Paris-Saclay cluster supports clinical trial enrollment for neuroinflammatory applications beyond multiple sclerosis.
United Kingdom
NICE technology appraisals weight total cost of ownership against patient adherence data in formulary decisions. The MHRA's post-Brexit regulatory autonomy enables accelerated approval pathways for bioequivalent immunomodulators. London's hospital pharmacy procurement committees unbundle disease-modifying therapy selection from infusion center economics.
Teriflunomide Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in active pharmaceutical ingredient supply. The teriflunomide market exhibits moderate consolidation among originator-maintained brand franchises and vertically integrated generic challengers. Three archetypes dominate: multinational originators with hospital pharmacy relationships, Indian API-to-tablet integrators, and North American distribution-focused generics. Competitive moves concentrate on backward integration into immunomodulator API production and exclusive outpatient pharmacy chain agreements.
Among originator-heritage players, Sanofi and Genzyme Corporation exemplify the platform-integrator archetype through sustained European brand loyalty. Teva Pharmaceutical Industries Ltd. and Glenmark Pharmaceuticals occupy positions reflecting divergent geographic emphases—Teva through North American distribution relationships, Glenmark through captive API supply. These three companies represent the competitive spectrum from originator defense to generic scale.
| Leading Market Players |
|---|
| Sanofi |
| Genzyme Corporation |
| Amneal Pharmaceuticals NY LC |
| Glenmark Pharmaceuticals |
| MSN Laboratories Private Limited |
| Alembic Pharmaceuticals |
| Natco |
| Teva Pharmaceutical Industries Ltd. |
| Midas Pharma GmbH |
| Others |
Value Network & Pricing Analysis
Single-source API dependency on Indian and Chinese contract manufacturers determines both the three-tier pricing structure across premium, standard, and economy levels and the geographic clustering of downstream tablet production. Hospital pharmacy procurement committees in the United States exploit this concentration to extract volume discounts, while European reference pricing systems compress originator premiums.
Pricing Analysis
Hospital pharmacy procurement committees anchor contract-based long-term offtake pricing for teriflunomide tablets, with price differentiation driven by FDA bioequivalence certification tier and captive API production status. Cost compression in the standard tier is intensifying because ANDA filings from vertically integrated Indian manufacturers are expanding supply. Retail pharmacy chains exhibit the highest price sensitivity due to thin dispensing margins, while academic medical centers with integrated delivery networks demonstrate the least.
Supply Chain Analysis
Export-control scrutiny on pharmaceutical manufacturing equipment limits capacity expansion in regulated markets, forcing generic developers to source from established API producers in India, China, and Italy. Teriflunomide production draws from leflunomide feedstock, hydroxypropyl methylcellulose coatings, and specialized dihydroorotate dehydrogenase inhibitor synthesis capabilities. Single-source vulnerability concentrates in Gujarat-based API manufacturers, with distribution running through McKesson, AmerisourceBergen, and Cardinal Health to hospital and retail endpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as oral immunomodulators displace infusion therapies, creating distinct niches for extended-release formulations, homecare monitoring platforms, and regional API-to-tablet integrators.
For Market Incumbents: Build regulatory data moats through comprehensive hepatic enzyme surveillance databases that exceed EMA risk management framework minimums. Sanofi and Genzyme Corporation should deepen backward integration into leflunomide feedstock production to secure margin against Indian API volatility. Exclusive distribution agreements with CVS and Walgreens create channel control that filters generic shelf access.
For New Entrants and Emerging Players: Pursue extended-release formulation development as the most penetrable segment, where FDA bioequivalence complexity filters out undercapitalized competitors. Target German outpatient neurology clinics scaling hospital-to-homecare transition protocols. A go-to-market angle centered on remote patient monitoring platforms for hepatic enzyme surveillance bypasses traditional hospital pharmacy gatekeepers.
For Investors and Strategic Acquirers: FDA streamlined ANDA review pathway expansion reshapes the acquisition landscape by compressing approval timelines for differentiated delivery mechanisms. Five-to-ten year viability favors vertically integrated manufacturers with captive API supply and established pharmacovigilance infrastructure. Target acquisition archetypes include Indian API-to-tablet integrators with CDSCO import authorization experience. The signal to watch is evolving FDA guidance on complex generic immunomodulators altering economic viability of ANDA filings.
| Strategic Initiative | Industry Significance |
|---|---|
| Extended-Release Formulation Development | Modified-release matrices employing hydroxypropyl methylcellulose coatings capture premium pricing in reference-priced European markets. |
| Backward Integration into API Production | Glenmark Pharmaceuticals anchors competitive position through captive supply of leflunomide-derived teriflunomide active pharmaceutical ingredient. |
| Homecare Monitoring Infrastructure | Remote hepatic enzyme surveillance platforms enable direct-to-patient distribution bypassing hospital pharmacy procurement committees. |
| EMA Risk Management Database Investment | Comprehensive post-market surveillance protocols exceed minimum requirements and sustain originator brand loyalty in Germany. |
| Exclusive Pharmacy Chain Agreements | Teva Pharmaceutical Industries controls shelf placement through distribution relationships with large outpatient pharmacy chains across North America. |
Research Methodology
Cross-validation between formulary director interviews and FDA ANDA filing databases anchors the qualitative findings in this study. Primary fieldwork engaged drug development executives at generic manufacturers, regulatory affairs leads navigating EMA immunomodulatory frameworks, hospital procurement managers at US academic medical centers, and payer access specialists at Medicare Advantage plans. Secondary validation sourced FDA bioequivalence study submissions, EMA risk management plan templates, ClinicalTrials.gov teriflunomide protocol registrations, and CMS Medicare Part D formulary tier placement data. Bottom-up prescription volume modeling triangulates against top-down market sizing across the analysis window.
Calibration against historical generic entry patterns and patent cliff erosion rates shapes the projection framework. Segmentation dimensions include formulation type, therapeutic area application, end-user setting, and regional regulatory cluster. CAGRs derive from regression analysis of oral immunomodulator displacement trends and Medicare reimbursement policy trajectories. Forecast inputs incorporate CDSCO import authorization timeline assumptions and German neurology clinic expansion rates.
Sensitivities concentrate around FDA guidance revisions on complex generic immunomodulators and API supply disruption in Gujarat manufacturing corridors. Forecasts reflect documented assumptions regarding EMA risk management framework stability and Medicare oral therapy preference durability. Material shifts in FDA bioequivalence standards or Indian pharmaceutical export policy would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Saudi Arabia Insulin Drugs and Delivery Devices Market
Pharmaceuticals
Azathioprine API Market
Pharmaceuticals
Nasal Vaccines Market
Pharmaceuticals
Global Sterile Injectable Drugs Market
Pharmaceuticals
Global Exocrine Pancreatic Insufficiency (EPI) Market
Pharmaceuticals
Global Atherosclerosis Drugs Market
Pharmaceuticals
Viscosupplementation Market
Pharmaceuticals
Hepatitis B Treatment Market
Pharmaceuticals
Focal Segmental Glomerulosclerosis (FSGS) Therapeutics Market
Pharmaceuticals
Sodium Aescinate Market
Pharmaceuticals
Tramadol Drug Market
Pharmaceuticals
Global Nizatidine Market
Pharmaceuticals
Etoricoxib Market
Pharmaceuticals
Cefdinir API Market
Pharmaceuticals
Global Heparin Sodium Market
Pharmaceuticals
Hydroxycarbamide Market