
 Europe Obsessive-Compulsive Disorder (OCD) Drugs Market | 2026-2036
Europe Obsessive-Compulsive Disorder (OCD) Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Obsessive-Compulsive Disorder (OCD) Drugs Market Foresight
Outcome-based purchasing agreements between national health services and pharmaceutical suppliers is rewriting competitive dynamics for mid-tier manufacturers. H. Lundbeck AS leverages its Nordic heritage to sustain dominance in serotonin reuptake inhibitor development. Eli Lilly and Co. anchors its position through deep specialization in psychiatric drug portfolios. Pfizer Inc. competes by extending manufacturing scale across continental European distribution networks.
Obsessive-Compulsive Disorder drugs comprise psychotropic compounds—primarily selective serotonin reuptake inhibitors, serotonin-norepinephrine reuptake inhibitors, and adjunctive antipsychotics—formulated to modulate cortico-striato-thalamo-cortical circuit dysfunction and reduce compulsive behavioral patterns. These agents serve the primary commercial purpose of reducing Yale-Brown Obsessive Compulsive Scale symptom severity in diagnosed patients. Among product type segments, SSRIs occupy the mature revenue base while antipsychotic adjuncts represent the fastest-growing margin pool due to treatment-resistant OCD protocols. Delivery mode segmentation shows oral formulations commanding volume leadership, though injectable long-acting depot preparations are gaining traction in hospital and rehabilitation center settings where adherence monitoring drives formulary decisions.
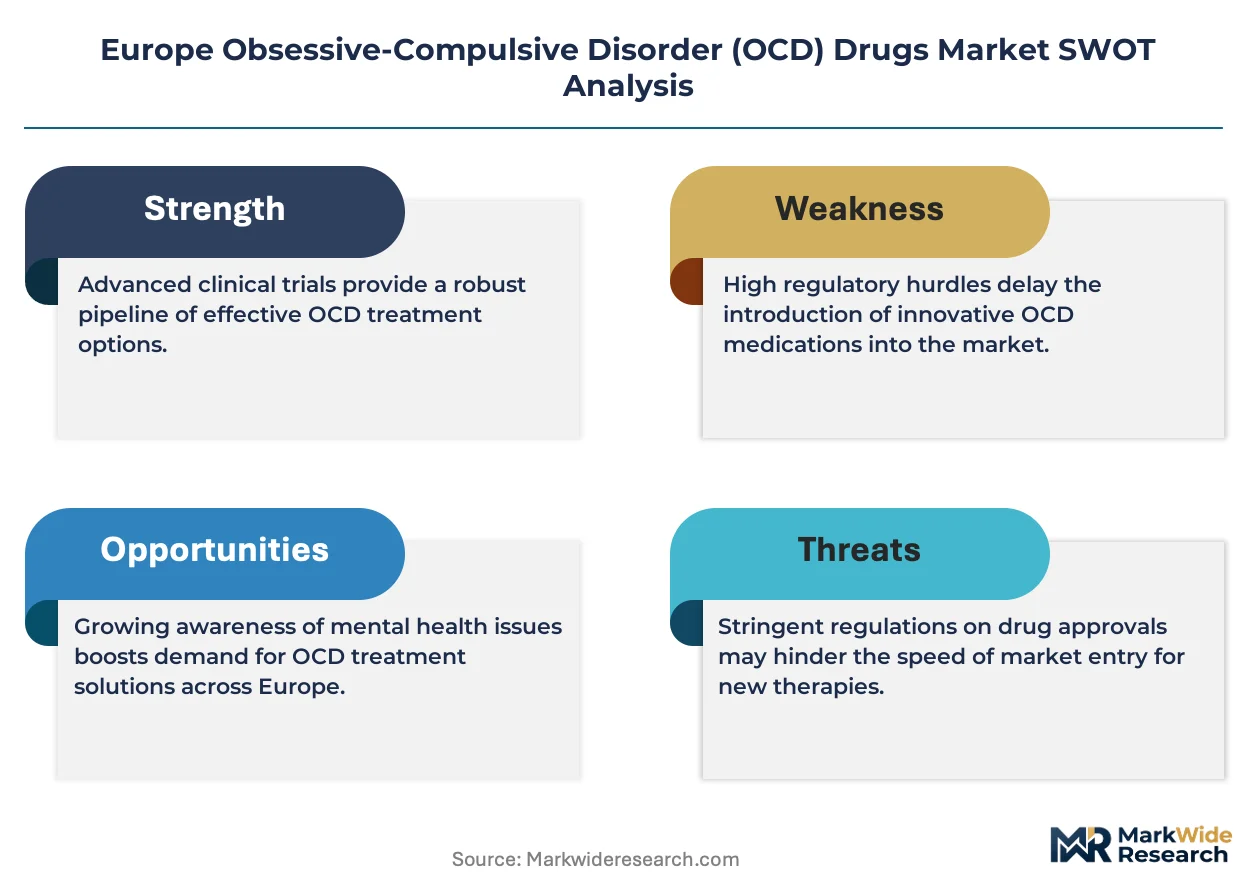
EMA centralized marketing authorization procedures and the EU Clinical Trials Regulation shape product entry timelines, while national reimbursement boards in France, Germany, and Italy determine commercial access at the member-state level. The EU AI Act introduces emerging compliance obligations for algorithmic diagnostic tools that increasingly guide OCD drug prescribing. Stakeholders must monitor how real-world evidence requirements under evolving EMA pharmacovigilance frameworks reshape post-market study investments.
Market Dynamics
Outcome-based purchasing agreements between national health services and pharmaceutical suppliers are rewriting competitive dynamics for mid-tier manufacturers across European psychiatric care markets.
Growth Catalysts
- EMA Centralized Marketing Authorization:Streamlined approval pathways accelerate product entry timelines across member states, reducing fragmentation in regulatory compliance investments.
- Hospital-Based Psychiatric Units:Institutional investment in specialized OCD treatment protocols drives formulary expansion for serotonin reuptake inhibitors and adjunctive antipsychotics.
- Algorithmic Diagnostic Tools:AI-guided prescribing systems under the EU AI Act create demand pull for drugs with robust real-world evidence portfolios.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Dependency on Asian API suppliers exposes European formulators to supply chain disruptions and import tariff volatility.
- Reimbursement Fragmentation:Divergent national health technology assessment criteria across France, Germany, and Italy delay commercial access despite EMA approval.
- Generic Erosion in SSRIs:Patent expiration on first-line serotonin reuptake inhibitors compresses margins in the mature volume segment.
Strategic Opportunities
- Treatment-Resistant Protocols:Antipsychotic adjunct therapies for refractory OCD cases command premium pricing in German and Nordic specialized clinics.
- Long-Acting Injectable Formulations:Depot preparations address adherence monitoring requirements in hospital and rehabilitation center settings.
- Real-World Evidence Mandates:Evolving EMA pharmacovigilance frameworks reward manufacturers with robust post-market study infrastructure.
Industry Challenges
- Specialized Psychiatry Talent Scarcity:Shortage of obsessive-compulsive disorder specialists limits prescriber education and protocol adoption rates.
- Cross-Border Data Harmonization:Inconsistent electronic health record standards impede multi-national clinical trial recruitment and outcomes tracking.
- Legacy Manufacturing Retrofit Costs:EU Medical Device Regulation compliance demands capital-intensive upgrades to sterile injectable production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Obsessive-Compulsive Disorder (OCD) Drugs Market |
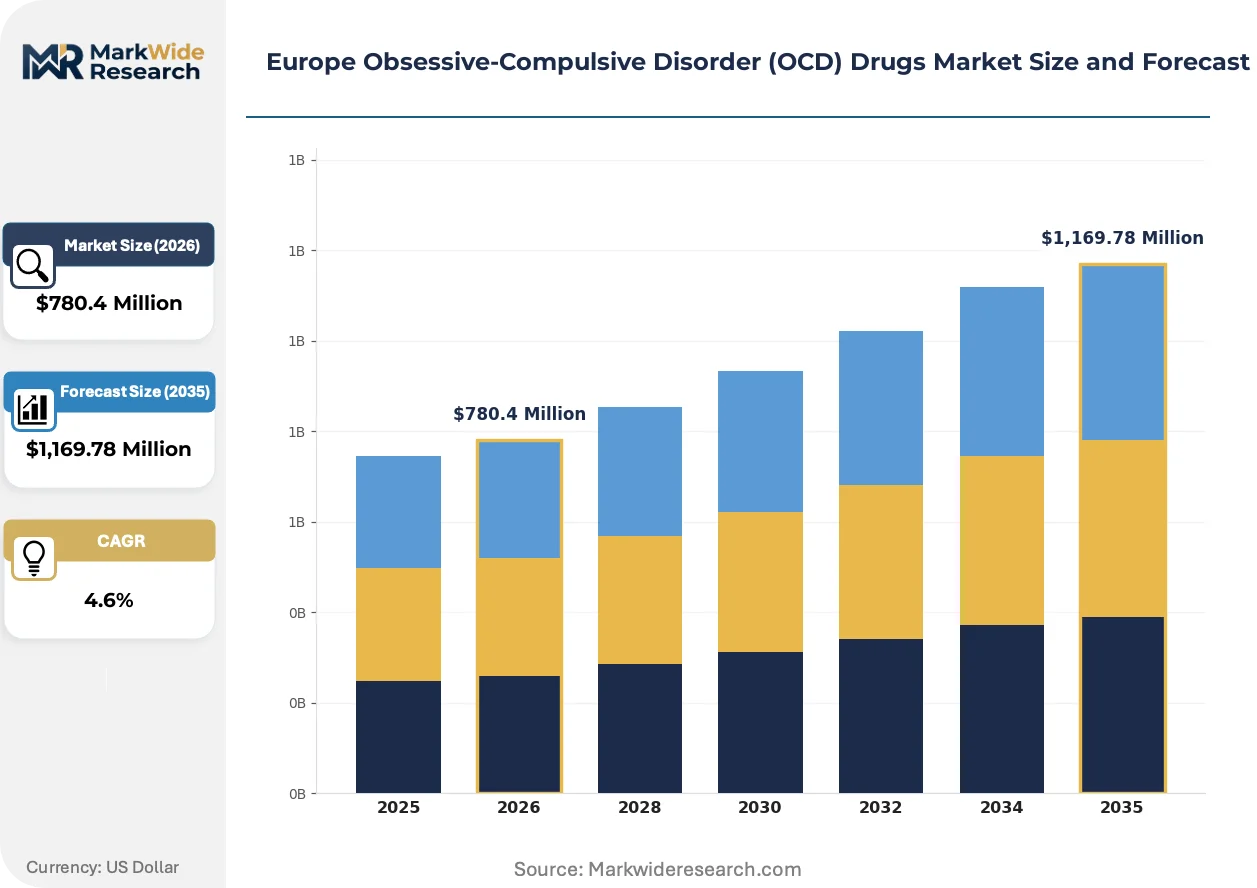
| Market Size in 2026 | $780.4 Million |
| Market Size in 2035 | $1,169.78 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SSRIs, SNRIs, TCAs, Antipsychotics Delivery Mode: Oral, Injectable, Transdermal, Inhalation End User: Hospitals, Clinics, Homecare, Rehabilitation Centers Treatment Approach: Cognitive Behavioral Therapy, Pharmacotherapy, Combination Therapy, Support Groups |
| Companies Covered | GlaxoSmithKline Plc, H. Lundbeck AS, Eli Lilly and Co., Pfizer Inc., Novartis AG, Johnson & Johnson, Otsuka Pharmaceutical, Takeda, Alembic Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Obsessive-Compulsive Disorder (OCD) Drugs Market Shifts & Advancements
Digital biomarker integration and precision dosing algorithms are redefining how European prescribers match patients to pharmacological interventions, shifting competitive advantage toward data-rich portfolios.
Pharmacogenomic testing is migrating from academic medical centers to community psychiatric practice, enabling clinicians to predict SSRI metabolism rates before initiating therapy. Dutch and Belgian hospital networks now mandate CYP2D6 screening for treatment-resistant cases. This capability is compressing the trial-and-error phase of drug selection and shortening time-to-response metrics in hospital formulary evaluations.
The EU AI Act introduces mandatory conformity assessments for algorithmic diagnostic tools that guide OCD drug prescribing, requiring manufacturers to document training data provenance and performance benchmarks across demographic subgroups. German regulators at the Federal Institute for Drugs and Medical Devices have issued draft guidance on AI-enabled dosing support systems. Psychiatric software vendors are responding by restructuring product development pipelines to segregate EU-compliant modules from other geographic configurations.
Centralized procurement consortia in France and Italy are consolidating purchasing power for psychotropic medications, displacing fragmented hospital-level negotiations with multi-year framework agreements tied to outcome metrics. Manufacturers now compete on real-world effectiveness data rather than traditional clinical trial endpoints. This concentration is most visible in Lombardy and Île-de-France, where regional health authorities have established dedicated OCD treatment procurement categories.
Europe Obsessive-Compulsive Disorder (OCD) Drugs Market Segmentation
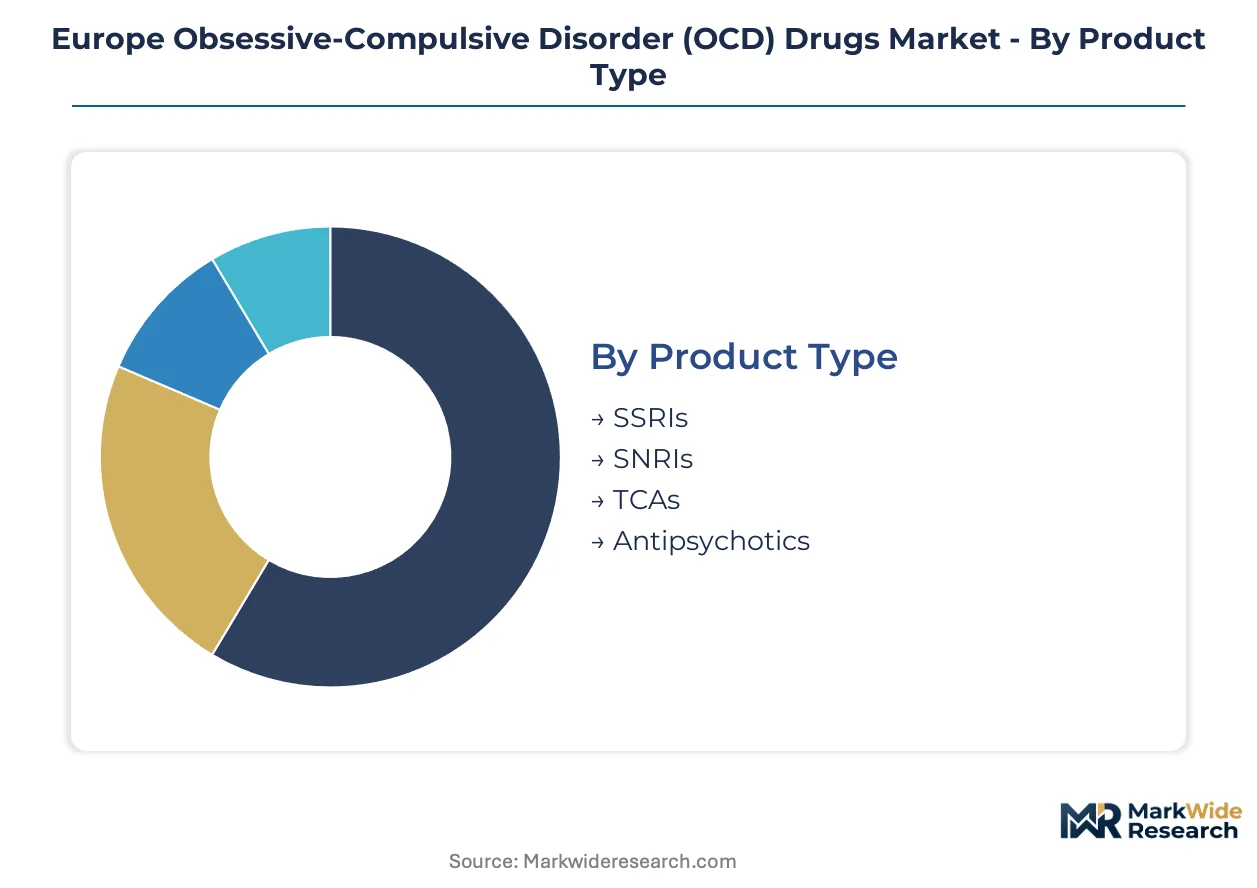
Pharmaceutical procurement patterns across European psychiatric care vary sharply by segment maturity. Treatment protocols in German and Nordic hospital networks prioritize adherence-optimized formulations over cost-minimized alternatives.
Product Type:
Cycle times diverge dramatically across this category, with mature serotonin reuptake inhibitors turning formulary slots slowly while antipsychotic adjuncts refresh prescribing protocols quarterly in treatment-resistant centers.
- SSRIs:First-line selective serotonin reuptake inhibitors including fluoxetine, sertraline, and fluvoxamine modulate synaptic serotonin availability through SERT inhibition. Demand concentrates in French and Italian community mental health centers where primary care physicians manage uncomplicated OCD presentations. Generic erosion compresses margins but sustains volume leadership.
- Antipsychotics:Atypical antipsychotic adjuncts such as aripiprazole and risperidone augment SSRI response in refractory cases through dopamine D2 and serotonin 5-HT2A receptor antagonism. German specialized anxiety disorder clinics anchor regional prescribing volumes for this segment. Premium pricing reflects restricted prescribing rights and hospital formulary gatekeeping.
- SNRIs:Dual serotonin-norepinephrine reuptake inhibitors extend therapeutic options for patients with comorbid depression or chronic pain presentations.
- TCAs:Tricyclic antidepressants including clomipramine retain niche utilization in treatment-resistant protocols despite inferior tolerability profiles.
SSRIs dominate installed base. Antipsychotics are where expansion concentrates.
Delivery Mode:
Cost tiering separates commodity oral tablets from premium injectable depots, with reimbursement bandwidth determining access stratification across national health systems.
- Oral:Immediate-release and extended-release tablets and capsules constitute the foundational administration route. Volume concentrates in Italian and Spanish outpatient settings where pharmacy benefit structures favor self-administered regimens. Convenience and reversibility sustain prescriber preference despite adherence variability.
- Injectable:Long-acting depot formulations including intramuscular and subcutaneous preparations enable sustained plasma levels over weeks to months. Nordic hospital psychiatric units and Dutch rehabilitation centers drive adoption through mandatory adherence monitoring protocols. EMA's centralized marketing authorization streamlines cross-border formulary harmonization for these specialized presentations.
- Transdermal:Patch-based delivery systems offer alternative absorption kinetics for patients with gastrointestinal intolerance or swallowing difficulties.
- Inhalation:Aerosolized and intranasal formulations remain investigational for psychiatric indications with limited commercial penetration.
Oral formulations command volume leadership. Injectable preparations are gaining share fastest in institutional settings.
End User:
Customer type segmentation maps directly to prescriber specialization depth, with hospital-based psychiatrists managing complex polypharmacy while primary care handles maintenance phases.
- Hospitals:Tertiary psychiatric units and university medical centers manage acute exacerbations and treatment-resistant cases. German university hospitals in Munich and Heidelberg anchor specialized OCD treatment protocols. EMA pharmacovigilance frameworks mandate intensive adverse event reporting from these high-acuity settings.
- Rehabilitation Centers:Residential and day-treatment facilities provide structured environments for behavioral intervention integration. Belgian and Dutch mental health institutes prioritize long-acting injectable adoption through supervised administration protocols. Outcome-based purchasing agreements increasingly tie reimbursement to symptom severity reduction metrics.
- Clinics:Outpatient psychiatric practices and community mental health centers manage stable patients in maintenance therapy.
- Homecare:Home-based nursing and telemedicine services support medication adherence for geographically isolated or mobility-limited patients.
Hospitals dominate installed base. Rehabilitation centers are where expansion concentrates.
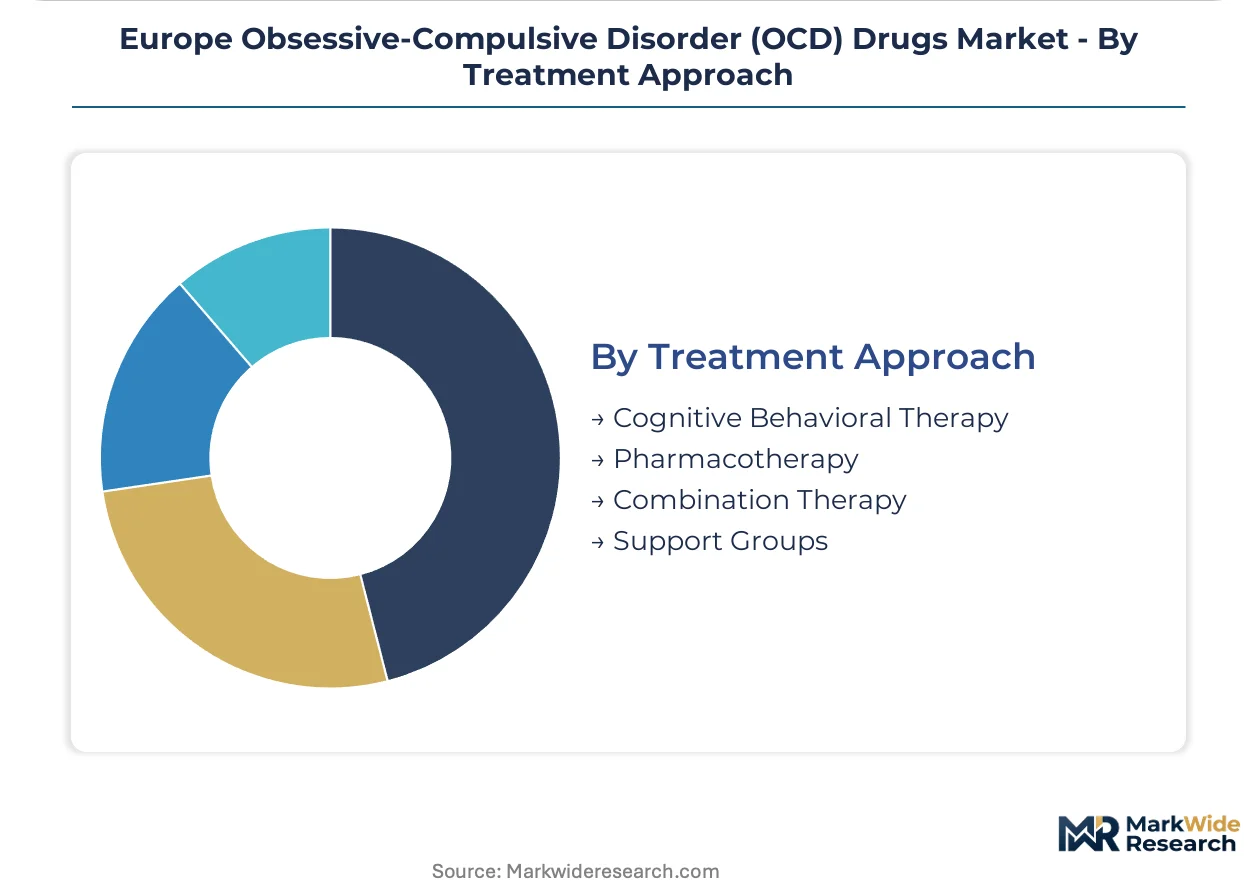
Treatment Approach:
Maturity gradients separate established pharmacotherapy from emerging combination protocols, with reimbursement codes lagging clinical innovation by several approval cycles.
- Pharmacotherapy:Drug monotherapy and polypharmacy regimens targeting cortico-striato-thalamo-cortical circuit dysfunction. French and German prescribing guidelines emphasize SSRI optimization before adjunctive antipsychotic introduction. Real-world evidence requirements under evolving EMA frameworks reshape post-market study investments.
- Combination Therapy:Integrated pharmacological and psychosocial interventions maximize response rates in severe presentations. Specialized anxiety disorder clinics in Hamburg and Amsterdam anchor regional adoption. The EU AI Act introduces compliance obligations for algorithmic tools guiding treatment selection.
- Cognitive Behavioral Therapy:Exposure and response prevention protocols delivered without concurrent medication in mild to moderate cases.
- Support Groups:Peer-led and professionally facilitated group interventions provide adjunctive psychosocial support.
Pharmacotherapy dominates installed base. Combination therapy is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA's centralized marketing authorization procedures and outcome-based purchasing agreements between national health services are accelerating formulary harmonization across member states while tightening quality benchmarks for psychotropic compounds.
Germany
Specialized anxiety disorder clinics in Munich and Heidelberg drive regional prescribing volumes for treatment-resistant OCD protocols. The Federal Institute for Drugs and Medical Devices issued draft guidance on AI-enabled dosing support systems under the EU AI Act. Bavarian university hospitals anchor post-market study investments mandated by evolving EMA pharmacovigilance frameworks.
France
Primary care physicians manage uncomplicated OCD presentations through community mental health centers concentrated in Île-de-France. ANSM and CNIL coordinate oversight of algorithmic diagnostic tools under the EU AI Act conformity assessments. Centralized procurement consortia in Île-de-France have established dedicated OCD treatment procurement categories tied to outcome metrics.
Netherlands
Dutch hospital networks mandate CYP2D6 pharmacogenomic screening for treatment-resistant cases, compressing trial-and-error phases in drug selection. The Dutch Health and Youth Care Inspectorate enforces adherence monitoring protocols that favor long-acting injectable adoption. Mental health institutes in Amsterdam prioritize supervised administration regimens through structured rehabilitation environments.
Italy
Outpatient pharmacy benefit structures in Lombardy favor self-administered oral regimens for maintenance therapy phases. Regional health authorities in Lombardy consolidated purchasing power through multi-year framework agreements displacing fragmented hospital negotiations. Milan-based psychiatric units manage stable patients through community-based adherence support systems.
United Kingdom
London and Southeast England tertiary units integrate exposure and response prevention protocols with pharmacotherapy for severe presentations. NICE guidelines shape formulary decisions for serotonin reuptake inhibitor optimization before adjunctive antipsychotic introduction. Greater Manchester and Birmingham rehabilitation centers pilot real-world evidence collection infrastructure under post-Brexit regulatory alignment discussions.
Europe Obsessive-Compulsive Disorder (OCD) Drugs Market Competitive Landscape
On the supply side, the industry is consolidating around manufacturers with robust real-world evidence portfolios and established relationships with centralized procurement consortia. Mid-tier formulators face margin compression from generic erosion in SSRIs and API supply chain volatility. Three strategic archetypes dominate: Nordic heritage specialists in serotonin reuptake inhibitor development, diversified pharmaceutical conglomerates leveraging continental distribution scale, and Japanese-origin innovators with psychiatric drug specialization. Competitive intensity centers on M&A activity targeting pharmacogenomic testing capabilities and strategic partnerships with algorithmic diagnostic vendors.
Within the Nordic heritage tier, H. Lundbeck AS exemplifies sustained dominance through deep specialization in psychiatric drug portfolios. Eli Lilly and Co. occupies a position among diversified conglomerates with concentrated expertise in CNS therapeutics. Pfizer Inc. anchors the scale-driven segment through continental European manufacturing and distribution network extension. Novartis AG and Johnson & Johnson sit within the diversified pharmaceutical archetype, representing portfolio breadth across neuropsychiatric indications. Otsuka Pharmaceutical and Takeda exemplify Japanese-origin innovators with psychiatric specialization heritage.
| Leading Market Players |
|---|
| GlaxoSmithKline Plc |
| H. Lundbeck AS |
| Eli Lilly and Co. |
| Pfizer Inc. |
| Novartis AG |
| Johnson & Johnson |
| Otsuka Pharmaceutical |
| Takeda |
| Alembic Ltd. |
| Others |
Supply & Pricing Matrix
Active pharmaceutical ingredient manufacturing concentrates in India and China, concentrating margin capture upstream while European formulators compete on finished-dose specialization and regulatory compliance value-adds. This asymmetry shapes how pricing power distributes across the serotonin reuptake inhibitor value chain, with API cost volatility transmitting directly into formulation economics.
Pricing Analysis
EMA marketing authorization tier creates the primary spread between premium patented antipsychotic adjuncts and commodity SSRI generics. Three-tier pricing structure across originator brands, authorized generics, and pure commodity substitutes segments buyer access by prescriber specialization depth. Cost compression in first-line oral tablets is intensifying because German and French centralized procurement consortia consolidate purchasing volume. Primary care physicians in Italian community mental health centers exhibit highest price sensitivity, while German university hospital formulary committees prioritize clinical outcomes over acquisition cost.
Supply Chain Analysis
Upstream feedstock for psychotropic compounds draws from Indian API manufacturers and Chinese intermediate chemical suppliers, with European formulators dependent on maritime logistics through Rotterdam and Hamburg ports. Key inputs include serotonin precursor chemicals, dopamine antagonist active moieties, and specialized excipients for extended-release matrices. Single-source vulnerability in CYP2D6 pharmacogenomic testing reagents creates bottlenecks for Dutch and Belgian precision dosing protocols. Distribution runs through national wholesale pharmaceutical networks with cold-chain requirements for injectable depot formulations, anchored by regional distribution centers in Munich, Paris, and Milan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generic SSRI commoditization and digital therapeutic substitutes for mild OCD presentations threaten incumbent revenue pools, forcing defensive repositioning toward treatment-resistant protocols and adherence-optimized delivery systems.
For Market Incumbents: Entrench dominance in antipsychotic adjunct therapies through backward integration into specialized API manufacturing and exclusive supply agreements with German anxiety disorder clinics. Patent cliff exposure on first-line serotonin reuptake inhibitors demands accelerated real-world evidence generation to defend reimbursement positioning against biosimilar entrants. EMA pharmacovigilance framework investments anchor long-term formulary security. For New Entrants and Emerging Players: Build out pharmacogenomic testing service capabilities as a Trojan horse for drug co-development partnerships with Dutch and Belgian hospital networks. Long-acting injectable formulations for rehabilitation center channels represent the most penetrable white-space segment, given adherence monitoring tailwinds and limited established competition. Position through outcome-based contracting models that align pricing with Yale-Brown Obsessive Compulsive Scale symptom reduction metrics. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier formulators with established EMA centralized marketing authorization track records and relationships with French and Italian centralized procurement consortia. The five-to-ten year viability window favors platforms combining psychiatric drug portfolios with algorithmic diagnostic tool development capabilities under EU AI Act compliance frameworks. Watch for inflection signals in rehabilitation center long-acting injectable adoption rates as a proxy for adherence protocol standardization momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacogenomic Testing Integration | Dutch hospital networks now mandate CYP2D6 screening, compressing trial-and-error prescribing phases and shortening time-to-response metrics. |
| Long-Acting Injectable Development | Nordic psychiatric units and Dutch rehabilitation centers drive depot formulation adoption through mandatory adherence monitoring protocols. |
| Real-World Evidence Infrastructure | Evolving EMA pharmacovigilance frameworks reward manufacturers with robust post-market study capabilities and formulary security. |
| AI-Enabled Dosing Systems | German BfArM draft guidance under the EU AI Act creates compliance barriers that favor established psychiatric software vendors. |
| Centralized Procurement Alignment | Lombardy and Île-de-France regional health authorities consolidate purchasing power through multi-year framework agreements tied to outcome metrics. |
Research Methodology
The analysis maps serotonin reuptake inhibitors, antipsychotic adjuncts, and pharmacogenomic testing services, each validated through formulary directors at German university hospitals, regulatory affairs leads at EMA centralized procedure sponsors, and hospital procurement managers in French centralized consortia. Secondary validation draws from EMA marketing authorization databases, ClinicalTrials.gov OCD protocol registrations, and national health technology assessment publications from HAS and IQWiG. Bottom-up prescription volume modeling triangulates against top-down national health expenditure aggregates for psychotropic medications.
Assumptions held fixed include EMA regulatory framework continuity, EU AI Act implementation timelines, and current reimbursement bandwidth across French, German, and Italian national health systems. Variables stress-tested include API import tariff trajectories, pharmacogenomic testing penetration rates, and long-acting injectable adoption curves across Nordic and Benelux institutional settings. Segmentation dimensions span product type, delivery mode, end-user facility type, and treatment approach protocol. CAGRs derive from regression analysis of historical prescription volume trends against demographic OCD prevalence projections and formulary expansion elasticity estimates.
Stress conditions across generic erosion velocity, centralized procurement consolidation pace, and pharmacogenomic screening reimbursement policy were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions, with specific revision risk from EU Medical Device Regulation compliance cost escalations and cross-border data harmonization failures impeding multi-national clinical trial recruitment. Cross-checking against IQVIA prescription audit data and national health accounts psychotropic expenditure benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Roflumilast API Market
Pharmaceuticals
Japan Pharmaceutical 3PL Market
Pharmaceuticals
Cefdinir API Market
Pharmaceuticals
Global Immunomodulators Market
Pharmaceuticals
Cervical Cancer Vaccine Market
Pharmaceuticals
Asia-Pacific Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Fusion Inhibitors Market
Pharmaceuticals
Nikethamide Injection Market
Pharmaceuticals
Europe Oral Anti-Diabetic Drug Market
Pharmaceuticals
Global Hemostasis and Tissue Sealing Agents Market
Pharmaceuticals
Ceftriaxone Sodium (API) Market
Pharmaceuticals
Anti-Arrhythmic Drugs Market
Pharmaceuticals
Asia-Pacific Over-The-Counter (OTC) Drugs Market
Pharmaceuticals
Indonesia Oral Anti-Diabetic Drug Market
Pharmaceuticals
Italy Healthcare Market
Pharmaceuticals
Plasma-Derived Protein Therapies Market