
 Global Postpartum Depression Drugs Market | 2026-2036
Global Postpartum Depression Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Postpartum Depression Drugs Market Foresight
Prescription volume in hospital outpatient settings is tilting toward infusion-based therapies that command premium reimbursement. Sage Therapeutics leverages its FDA-approved brexanolone platform to anchor the intravenous segment. Eli Lilly and Company sustains competitive pressure through its established antidepressant portfolio and psychiatric sales infrastructure.
Postpartum depression drugs comprise pharmaceutical agents targeting the biochemical dysregulation following childbirth, including allosteric modulators of GABA-A receptors and selective monoamine reuptake inhibitors formulated for lactation-compatible pharmacokinetics. These compounds restore neurotransmitter balance in women experiencing depressive episodes within twelve months of delivery. The drug type dimension shows antidepressants occupying the largest volume share while hormonal therapies represent the fastest-expanding margin pool. Intravenous administration routes capture premium pricing due to supervised clinical administration requirements, whereas oral formulations dominate total prescription counts through primary care channels.
The FDA maintains accelerated approval pathways for novel neurosteroid therapies, while the EMA evaluates centralized marketing authorizations under its psychiatric medicines framework. WHO inclusion of maternal mental health in essential service packages shapes national procurement priorities across multiple jurisdictions. Stakeholders must monitor how CMS reimbursement decisions for at-home subcutaneous formulations reshape site-of-care economics and prescriber behavior.
Market Dynamics
The FDA's accelerated approval pathway for neurosteroid therapies is compressing development timelines and redrawing competitive boundaries between intravenous and oral formulation developers. This regulatory mechanism is forcing incumbent antidepressant manufacturers to recalibrate clinical trial strategies and reimbursement positioning.
Growth Catalysts
- WHO Essential Service Inclusion:The World Health Organization's integration of maternal mental health into essential service packages is elevating national procurement priorities across multiple jurisdictions. Government health ministries are channeling budget allocations toward postpartum depression screening and treatment infrastructure.
- Neuroactive Steroid Platform Expansion:Allosteric modulation of GABA-A receptors is creating a mechanistically distinct therapeutic class with differentiated pharmacokinetic profiles. Hospital outpatient departments are expanding infusion capacity to accommodate supervised administration requirements.
- United States Reimbursement Infrastructure:CMS coverage determinations for novel postpartum depression therapies are establishing precedent for commercial payer adoption. Specialist access networks in metropolitan clusters are concentrating prescription volume toward reimbursed therapeutic categories.
Market Restraints
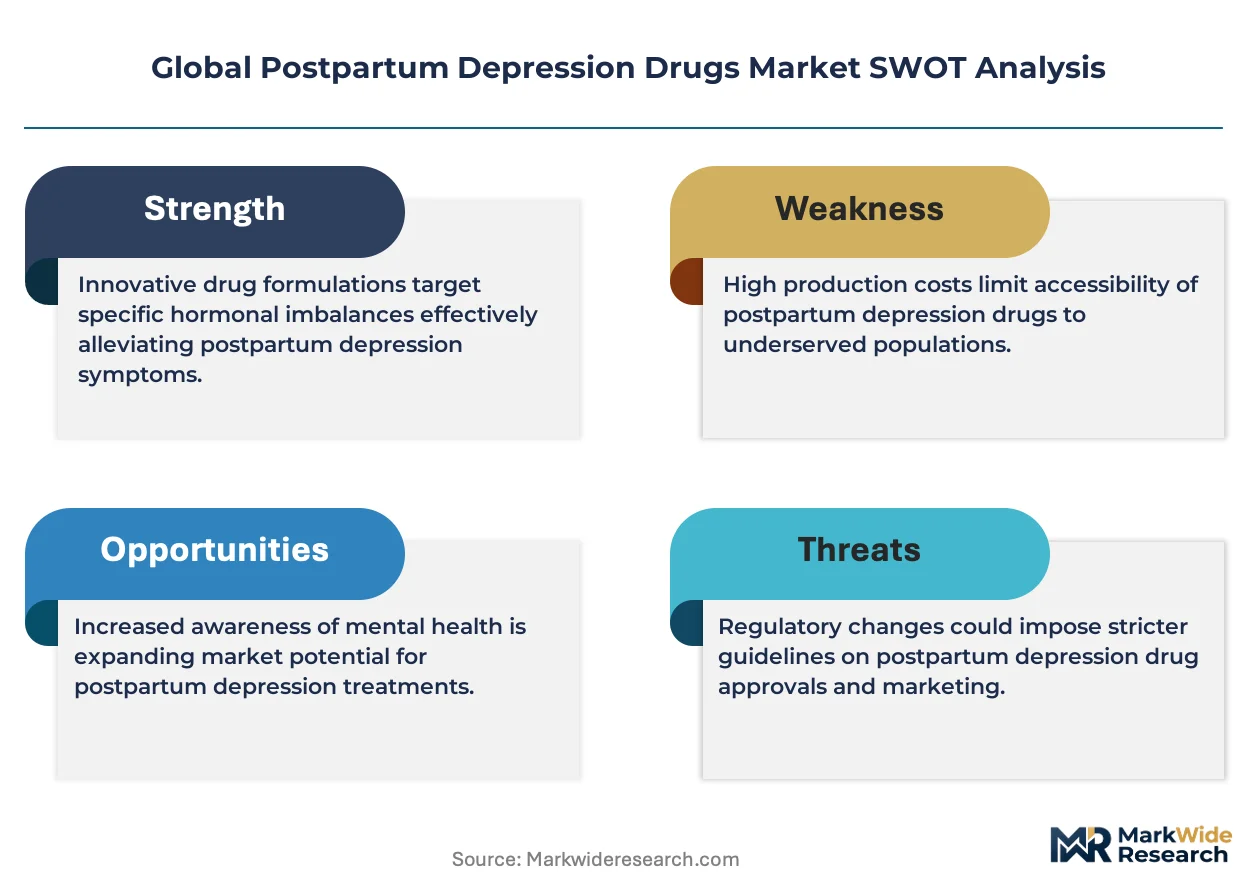
- Intravenous Administration Cost Structure:Supervised clinical administration requirements for neurosteroid infusions impose facility fees and nursing labor costs that compress patient access. Hospital outpatient departments face capacity constraints that limit throughput scaling.
- Active Pharmaceutical Ingredient Concentration:Synthetic neurosteroid precursor supply chains concentrate among specialized contract manufacturers with limited redundancy. Single-source dependencies for GABA-A modulator intermediates create vulnerability to batch failure or quality excursions.
- Lactation Pharmacokinetic Uncertainty:Breast milk transfer data gaps for novel neuroactive steroids generate prescriber hesitation and liability exposure. The FDA's pregnancy and lactation labeling requirements impose extended post-marketing study obligations that extend regulatory risk windows.
Strategic Opportunities
- Subcutaneous Formulation Development:At-home administration routes that bypass infusion center dependency would unlock geographic penetration into rural and underserved metropolitan zones. CMS reimbursement decisions for self-administered neurosteroid delivery systems are reshaping site-of-care economics.
- Primary Care Channel Integration:Oral antidepressant formulations with lactation-compatible profiles are migrating from psychiatric specialty to obstetric and family medicine prescribing. This channel expansion broadens addressable prescriber pools beyond maternal-fetal medicine specialists.
- European Centralized Authorization Pathway:The EMA's psychiatric medicines framework offers simultaneous market access across 27 member states through single marketing authorization applications. Manufacturers with centralized regulatory strategies can compress sequential national approval timelines.
Industry Challenges
- Psychiatric-Neonatal Cross-Training Scarcity:Clinicians with dual competency in perinatal mental health and lactation pharmacology remain concentrated in academic medical centers. Community hospital staffing models struggle to replicate this expertise density.
- Real-World Evidence Generation Infrastructure:Post-marketing safety surveillance for neurosteroid exposure during breastfeeding requires coordinated registry participation across dispersed delivery sites. Data fragmentation between electronic health record systems complicates outcome attribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Postpartum Depression Drugs Market |
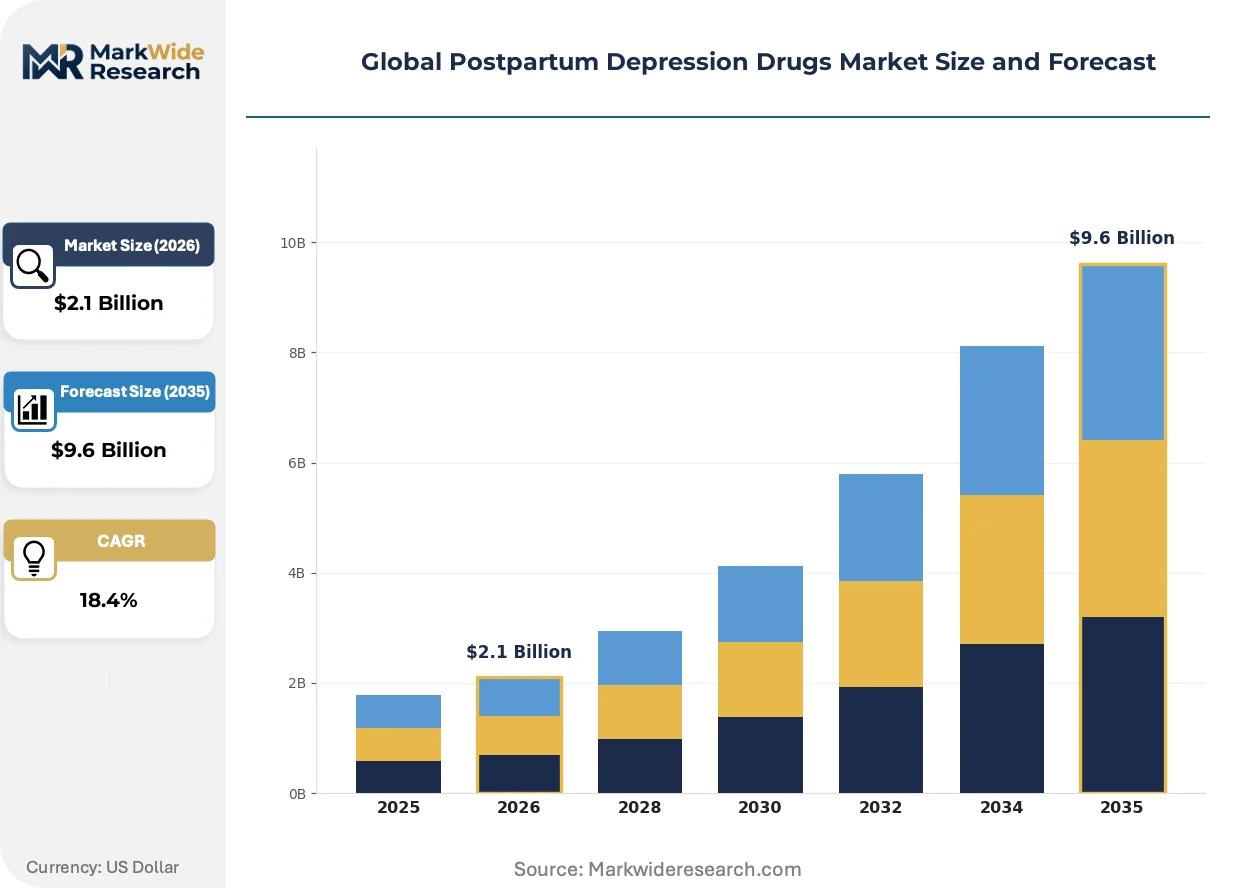
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $9.6 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Antidepressants, Hormonal Therapies, Selective Serotonin Reuptake Inhibitors, Antipsychotics Administration Route: Oral, Intravenous, Subcutaneous, Transdermal Therapeutic Area: Psychiatric Disorders, Mental Health, Maternal Health, Behavioral Health Patient Type: New Mothers, High-Risk Patients, postpartum Women, Geriatric Patients |
| Companies Covered | Eli Lilly and Company, Merck & Co., Inc., Sage Therapeutics, Inc., Teva Pharmaceutical Industries Ltd., Novartis AG, Biogen Inc., GSK plc., Marinus Pharmaceuticals, Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Postpartum Depression Drugs Market Shifts & Advancements
Neurosteroid mechanism validation is collapsing development risk premiums and attracting capital allocation toward GABA-A-targeted platforms. The convergence of biomarker stratification and rapid-acting pharmacology is redefining therapeutic expectations for postpartum depression intervention.
Allosteric modulation of extrasynaptic GABA-A receptors is collapsing the latency window between treatment initiation and symptomatic response. Maternal health clinics in the United States are prioritizing these mechanisms for patients with severe or refractory presentations. The structural consequence is a bifurcation between rapid-acting infusion therapies and maintenance-oriented oral regimens.
The FDA's Breakthrough Therapy designation pathway for postpartum depression indications is compressing Phase 3 enrollment timelines and enabling rolling review submissions. Neurosteroid developers are leveraging this mechanism to accelerate competitive positioning against established antidepressant portfolios. European manufacturers are observing this regulatory precedent to inform EMA qualification strategy for comparable designations.
Hospital outpatient departments are unbundling postpartum depression screening from routine obstetric follow-up, creating discrete reimbursement codes for mental health intervention. Primary care networks in suburban United States markets are absorbing this volume through collaborative care models with psychiatric consultation support. This channel migration is most visible in states with Medicaid expansion and maternal health quality metric tied to hospital reimbursement.
Global Postpartum Depression Drugs Market Segmentation
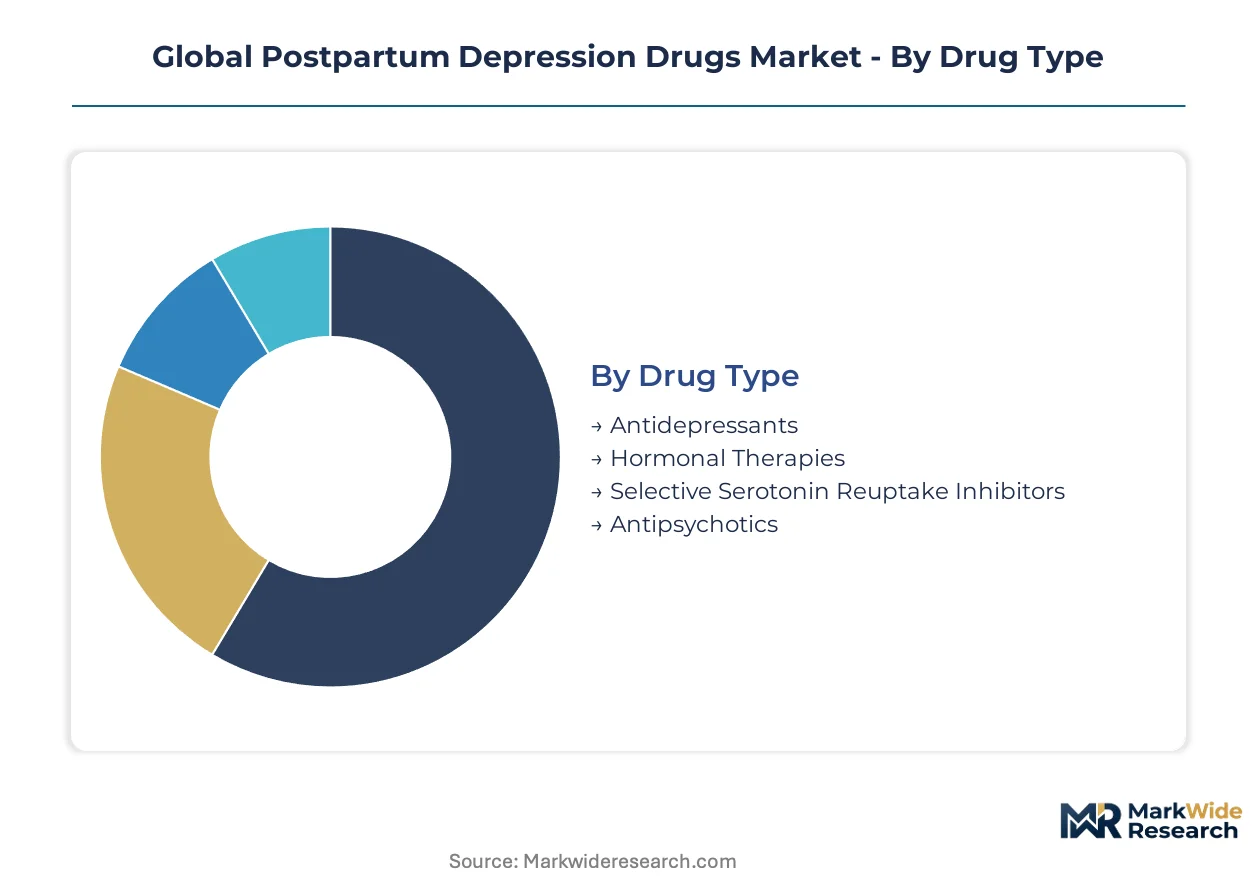
Segmentation in postpartum depression therapeutics reveals how formulation choices, clinical settings, and patient risk profiles determine prescription patterns and reimbursement pathways. Drug mechanism and administration route together shape site-of-care economics and prescriber channel selection.
Drug Type:
Mature antidepressant platforms anchor prescription volume while emerging neurosteroid mechanisms redefine clinical expectations for onset speed and lactation safety.
- Antidepressants:Selective serotonin reuptake inhibitors and serotonin-norepinephrine reuptake inhibitors dominate primary care prescribing through established lactation safety databases. United States Medicaid formularies prioritize these agents for first-line maternal mental health intervention due to cost containment protocols and generic availability.
- Hormonal Therapies:Allosteric GABA-A receptor modulators target the neurosteroid withdrawal hypothesis underlying postpartum biochemical dysregulation. Hospital outpatient departments in metropolitan United States clusters are expanding infusion capacity to accommodate supervised brexanolone administration under FDA Risk Evaluation and Mitigation Strategy requirements.
- Selective Serotonin Reuptake Inhibitors:First-line oral agents with extensive breast milk transfer data support community-based prescribing by obstetric and family medicine practitioners.
- Antipsychotics:Atypical formulations address psychotic features or bipolar spectrum presentations in severe postpartum cases requiring psychiatric emergency intervention.
Antidepressants retain volume leadership; hormonal therapies hold the steepest expansion curve.
Administration Route:
Cost tier stratification separates facility-based premium administration from self-directed oral maintenance regimens.
- Oral:Tablet and capsule formulations enable primary care dispensing with minimal site-of-care overhead. Suburban United States markets with collaborative care models between obstetrics and psychiatry drive prescription concentration for maintenance-phase therapy.
- Intravenous:Neurosteroid infusions require 60-hour supervised administration in certified healthcare facilities. CMS reimbursement rates for hospital outpatient department administration determine geographic availability, with concentration in states with maternal health quality metrics tied to hospital reimbursement.
- Subcutaneous:Self-administered injection platforms under development would bypass infusion center dependency for rapid-acting neurosteroid delivery.
- Transdermal:Patch-based delivery systems remain investigational for postpartum applications, with pharmacokinetic studies ongoing for lactation-compatible absorption profiles.
Oral routes dominate prescription counts; intravenous administration captures the highest per-treatment reimbursement.
Therapeutic Area:
Application focus determines prescriber specialty and regulatory oversight intensity across clinical settings.
- Psychiatric Disorders:Severe depressive episodes with suicidal ideation or psychotic features mandate psychiatric emergency department evaluation. Academic medical centers in the United States with perinatal psychiatry fellowship programs concentrate complex case referral networks.
- Mental Health:Moderate depressive presentations within twelve months of delivery drive the majority of screening-detected intervention opportunities.
- Maternal Health:Integrated obstetric-mental health clinics in United States hospital systems are unbundling postpartum depression screening from routine six-week follow-up appointments.
- Behavioral Health:Collaborative care models embed mental health specialists within pediatric or obstetric practices to reduce specialty access barriers.
Maternal Health channels drive screening volume; Psychiatric Disorders commands the highest per-patient resource allocation.
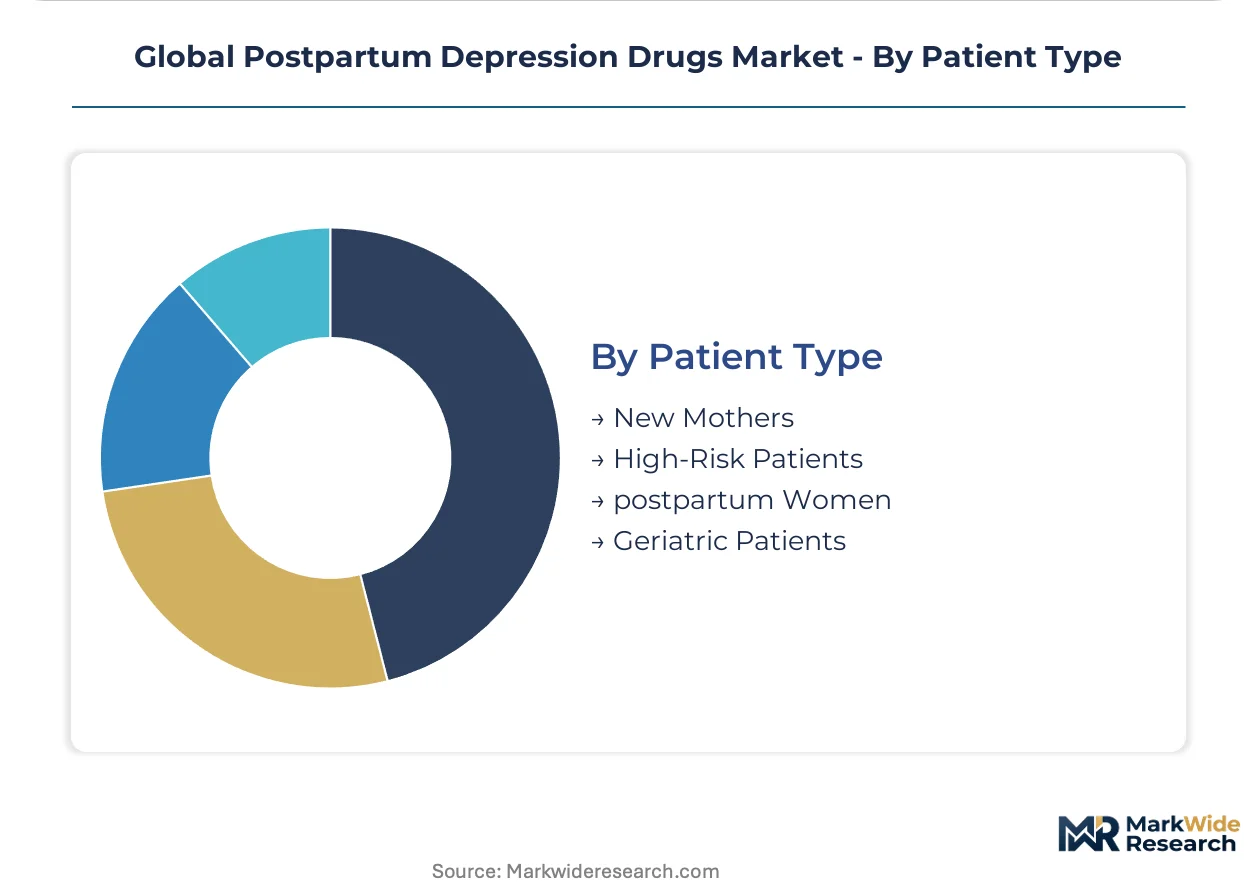
Patient Type:
Risk stratification separates universal screening populations from intensive intervention candidates requiring specialized pharmacologic approaches.
- New Mothers:Universal screening populations within twelve months of delivery represent the broadest addressable base for preventive intervention. United States states with Medicaid expansion and maternal mortality review committees are mandating depression screening at multiple postpartum touchpoints.
- High-Risk Patients:Prior psychiatric history, traumatic delivery, or neonatal intensive care unit admission trigger enhanced monitoring protocols. Maternal-fetal medicine specialists in United States academic centers coordinate care for these patients through dedicated perinatal psychiatry consultation services.
- Postpartum Women:The core diagnostic population experiencing depressive onset within the postpartum period as defined by DSM-5 criteria.
- Geriatric Patients:Late reproductive age mothers with advanced maternal age complications requiring modified pharmacokinetic considerations.
New Mothers represent the largest screening-eligible population; High-Risk Patients generate the highest per-capita pharmaceutical expenditure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States show the lowest price elasticity due to CMS reimbursement infrastructure, while emerging markets face steep access barriers from out-of-pocket payment requirements. Hospital outpatient capacity constraints in wealthy nations contrast with screening program expansion in middle-income jurisdictions.
United States
Medicaid expansion states drive screening volume through mandated maternal mental health quality metrics. The FDA's Risk Evaluation and Mitigation Strategy for neurosteroid infusions shapes site-of-care certification requirements. Academic medical centers in Massachusetts and California concentrate perinatal psychiatry fellowship programs and referral networks.
Germany
Statutory health insurance funds prioritize cost containment for oral antidepressant first-line therapy. The EMA's centralized psychiatric medicines framework enables streamlined marketing authorization across member states. Hospital systems in Bavaria and North Rhine-Westphalia pilot integrated obstetric-mental health screening protocols.
Japan
PMDA regulatory timelines for novel neurosteroid mechanisms lag FDA precedent by 18-24 months. METI industrial policy channels domestic pharmaceutical investment toward maternal health indications. Tokyo and Osaka metropolitan clusters concentrate psychiatric emergency departments with perinatal specialization.
India
CDSCO marketing authorization pathways for lactation-compatible formulations face post-marketing study requirements that extend commercialization timelines. The national health mission incorporates maternal depression screening into accredited social health activist training. Hospital chains in Maharashtra and Karnataka expand private-pay mental health service lines for urban postpartum populations.
United Kingdom
NHS England tariff structures reimburse hospital outpatient neurosteroid administration at rates below United States commercial benchmarks. MHRA post-Brexit regulatory autonomy permits divergence from EMA centralized decisions on psychiatric indications. London and Greater Manchester academic health science networks coordinate perinatal mental health clinical trial recruitment.
Global Postpartum Depression Drugs Market Competitive Landscape
Capability concentration sits with neurosteroid platform developers holding FDA breakthrough designations; scale advantage sits with established psychiatric pharmaceutical manufacturers with primary care sales infrastructure. The market structure separates into three tiers: rapid-acting infusion specialists, oral antidepressant incumbents, and emerging subcutaneous formulation developers. Dominant competitive moves include strategic partnerships for synthetic neurosteroid precursor supply and portfolio diversification into lactation-compatible pharmacokinetics.
Among neurosteroid platform specialists, Sage Therapeutics and Marinus Pharmaceuticals exemplify the rapid-acting mechanism archetype. Eli Lilly and Company anchors the established antidepressant tier with psychiatric sales infrastructure. GSK plc occupies a position bridging primary care channel access with maternal health indication development.
| Leading Market Players |
|---|
| Eli Lilly and Company |
| Merck & Co., Inc. |
| Sage Therapeutics, Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Novartis AG |
| Biogen Inc. |
| GSK plc. |
| Marinus Pharmaceuticals |
| Pfizer Inc. |
| Others |
Supply & Pricing Matrix
Synthetic neurosteroid precursor manufacturing concentrates among specialized contract manufacturers in the United States and Switzerland, anchoring margin capture in the intravenous infusion tier where facility fees and nursing labor compound drug acquisition costs. This upstream concentration downstreams into bifurcated pricing power between hospital outpatient departments commanding premium reimbursement and primary care channels competing on oral antidepressant accessibility.
Pricing Analysis
After-sales service revenue from infusion center administration and REMS compliance programs drives lifetime value per patient beyond the drug acquisition cost. Three-tier pricing structure across premium intravenous neurosteroids, standard oral antidepressants, and economy generic SSRIs stratifies the market by onset speed and supervision requirements. Cost compression in the oral tier intensifies as Medicaid formularies prioritize generic availability, while hospital outpatient departments face limited price sensitivity due to CMS reimbursement floors. Self-pay populations in non-expansion states exhibit highest price sensitivity, whereas commercially insured patients in metropolitan clusters show lowest elasticity.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for active pharmaceutical ingredient sourcing. Synthetic neurosteroid precursor production centers on the United States, Switzerland, and specialized facilities in India, drawing from allopregnanolone derivatives and GABA-A modulator intermediates. Single-source dependencies for GABA-A receptor allosteric modulators create vulnerability to batch failure, with limited qualified alternative suppliers. Distribution runs through hospital specialty pharmacies for infusion therapies and retail pharmacy networks for oral maintenance regimens.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Postpartum depression therapeutics function as a service-attach opportunity where infusion administration protocols and REMS compliance programs expand recurring revenue faster than drug manufacturing margins. The shift toward at-home subcutaneous delivery will further elevate attach rates for patient support services and monitoring infrastructure.
For Market Incumbents: Entrench position through backward integration into synthetic neurosteroid precursor production and exclusive supply agreements with certified infusion centers. Neurosteroid platform developers face margin compression from oral antidepressant incumbents with established primary care sales infrastructure; defensive capacity expansion in REMS-certified hospital networks preserves geographic exclusivity. Investment in lactation pharmacokinetic databases addresses prescriber liability exposure and differentiates against generic SSRI competitors. For New Entrants and Emerging Players: Rural and underserved metropolitan zones in Medicaid non-expansion states represent the most penetrable entry point for subcutaneous formulation developers seeking to bypass infusion center dependency. Collaborative care models between obstetrics and family medicine in suburban markets offer channel access without psychiatric specialty infrastructure requirements. Go-to-market positioning should emphasize at-home administration economics and reduced site-of-care overhead. For Investors and Strategic Acquirers: Capital is best deployed toward neurosteroid platform specialists with FDA Breakthrough Therapy designations and validated GABA-A mechanism intellectual property. The five-to-ten year viability window favors developers with subcutaneous delivery systems addressing the infrastructure bottleneck constraining intravenous volume scaling. The signal to watch is CMS reimbursement determination for self-administered neurosteroid formulations, which would restructure site-of-care economics and prescriber channel selection.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | At-home administration bypasses infusion center capacity constraints and expands geographic addressability. |
| REMS Certification Expansion | Hospital outpatient department credentialing creates exclusive distribution nodes for neurosteroid infusions. |
| Lactation Pharmacokinetic Investment | Breast milk transfer data reduces prescriber liability exposure and differentiates against oral competitors. |
| Primary Care Channel Integration | Collaborative care models embed mental health specialists within obstetric practices to broaden prescriber pools. |
| European Centralized Authorization | EMA psychiatric medicines framework enables simultaneous market access across member states. |
Research Methodology
A standing panel of maternal-fetal medicine specialists, psychiatric hospital pharmacy directors, payer formulary managers, and infusion center operations leads provided ongoing calibration across the primary research phase. This practitioner input combined with secondary validation from FDA REMS documentation, CMS reimbursement determinations, ClinicalTrials.gov neurosteroid trial records, and state Medicaid formulary databases. Bottom-up prescription volume modeling and top-down pharmaceutical expenditure triangulation anchored market size estimation.
Scenario-bracketing around regulatory approval timelines, reimbursement adoption curves, and subcutaneous formulation launch sequencing bounded the projection range. Segmentation dimensions modeled include drug mechanism class, administration route, site-of-care setting, patient risk stratification, and regional regulatory cluster. CAGRs were derived from prescription volume trajectories and per-treatment revenue evolution across the analysis window. Forecast inputs incorporated neurosteroid infusion capacity expansion plans and primary care collaborative care model penetration rates.
Macroeconomic conditions sit as an overlay; deviation in Medicaid expansion policy, maternal health quality metric reimbursement linkages, or neurosteroid precursor supply disruptions would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway acceleration and prescriber channel migration patterns. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Periodontal Therapeutics Market
Pharmaceuticals
Global Novel Drug Delivery Systems (NDDS) Market
Pharmaceuticals
Oxycodone Market
Pharmaceuticals
Sildenafil Drug Market
Pharmaceuticals
Tramadol Drug Market
Pharmaceuticals
Asia-Pacific Human Papillomavirus Vaccine Market
Pharmaceuticals
Non-Steroidal Anti-Inflammatory API Market
Pharmaceuticals
Valganciclovir Market
Pharmaceuticals
US Oral Solid Dosage Contract Manufacturing Market
Pharmaceuticals
Dermatological Drugs Market
Pharmaceuticals
Collagenase Clostridium Histolyticum Market
Pharmaceuticals
Dyslipidemia Drugs Market
Pharmaceuticals
Middle East and Africa Laxative Market
Pharmaceuticals
Intranasal Corticosteroids Market
Pharmaceuticals
Leukotriene Modifiers Market
Pharmaceuticals
Global Oxytocin Market