
 OTC Dry Eye Drops Market | 2026-2036
OTC Dry Eye Drops Market Size, Share, and Industry Trends Forecast 2026-2036
OTC Dry Eye Drops Market Analytics
Single-dose vial configurations is broadening buyer choice across pharmacy and online channels. Johnson & Johnson Services Inc. leverages its retail shelf presence to sustain volume leadership in multi-dose containers. Alcon anchors the premium segment through specialized contact lens comfort formulations. Santen Pharmaceutical Co. Ltd. competes with preservative-free technology leadership in Asian and European markets.
OTC dry eye drops are non-prescription ophthalmic solutions formulated with electrolytes, polymers, or lipid-based compounds to restore tear film stability and relieve ocular surface discomfort. Manufacturing employs aseptic filling processes under ISO 5 cleanroom conditions to maintain sterility without preservatives. Hydrating drops and artificial tears dominate current volume due to broad indication coverage and lower price positioning. Gel drops command higher margins among severe dry eye sufferers seeking prolonged corneal residence time. Single-dose vials represent the fastest-expanding delivery mode as consumers prioritize portability and contamination avoidance.
FDA ophthalmic guidance and EMA sterility requirements shape formulation decisions and facility investment across manufacturers. ISO 13485 quality management and CE marking under the EU Medical Device Regulation govern market access in Europe and influence design controls for dropper mechanisms. Stakeholders must monitor evolving preservative safety thresholds and digital health integration opportunities as telemedicine channels reshape how consumers select and replenish eye care products.
Market Dynamics
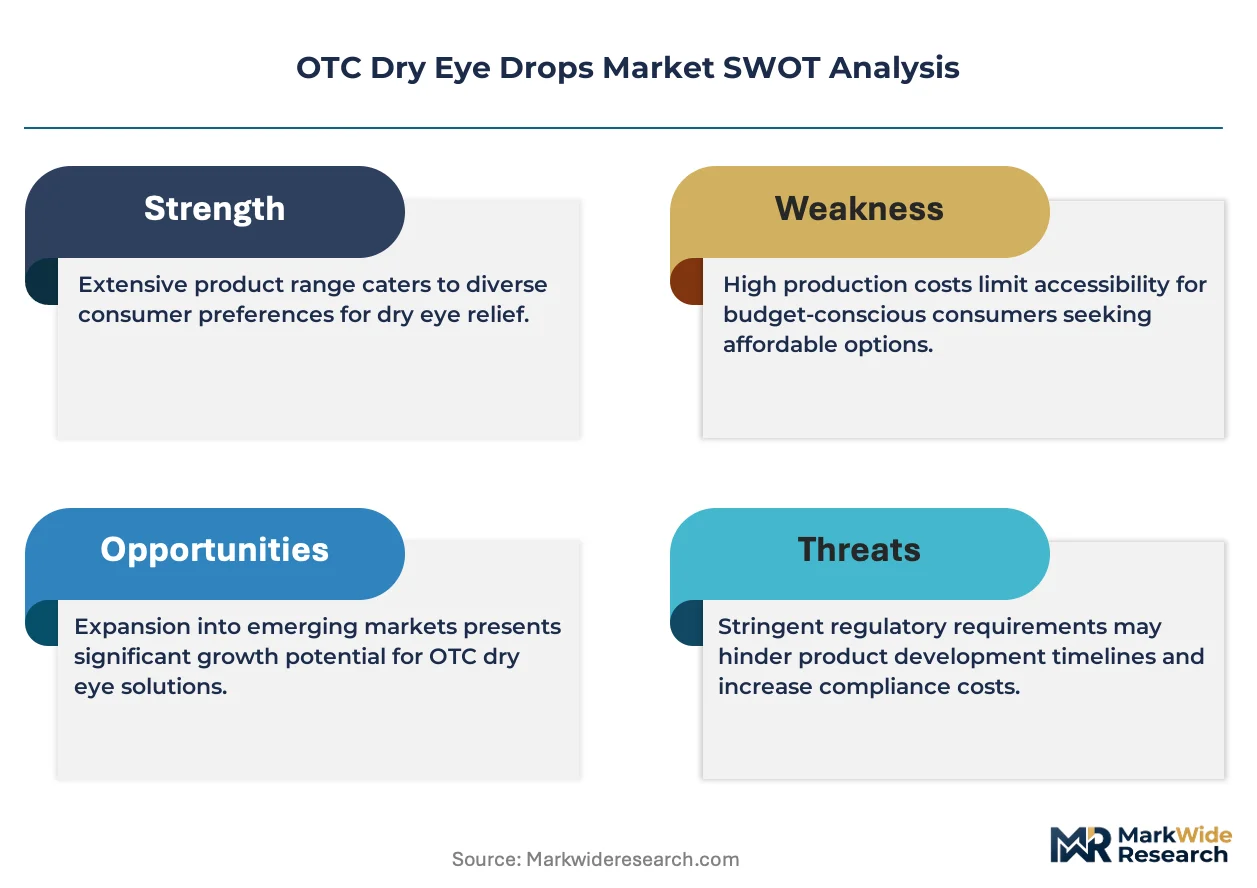
Preservative-free formulation adoption is restructuring manufacturing investment across the OTC dry eye drops sector, forcing capital reallocation toward aseptic filling infrastructure and single-dose vial production lines.
Growth Catalysts
- FDA Ophthalmic Guidance:The sterility mandate for multi-dose containers accelerates facility upgrades and validates premium positioning for preservative-free alternatives.
- Digital worker screen exposure:Remote work normalization sustains chronic dry eye incidence among knowledge workers aged 25-45, expanding the addressable consumer base beyond traditional elderly segments.
- ISO 13485 certification:Quality management standardization enables European manufacturers to access Asian pharmacy chains through mutual recognition agreements.
Market Restraints
- Propylene glycol supply volatility:Key polymer feedstock price swings compress margins for hydrating drop formulations during energy market disruptions.
- Cleanroom capex concentration:Aseptic filling equipment suppliers cluster in Germany and Switzerland, creating procurement bottlenecks for mid-tier manufacturers.
- EMA Medical Device Regulation:Extended CE marking timelines for novel dropper mechanisms delay product launches by 12-18 months versus previous directives.
Strategic Opportunities
- Telemedicine replenishment channels:Direct-to-consumer subscription models bypass pharmacy intermediaries and capture recurring revenue from chronic sufferers.
- India pharmacy retail expansion:Organized chain growth in tier-2 cities creates first-mover advantage for preservative-free education campaigns.
- Contact lens compatibility formulations:Silicone hydrogel lens wearer comfort positioning opens premium pricing corridors distinct from generic artificial tears.
Industry Challenges
- Aseptic technician scarcity:ISO 5 cleanroom operator certification programs lag production capacity expansion in emerging manufacturing hubs.
- Legacy preservative validation:Benzalkonium chloride safety dossier updates require toxicology study investments that smaller formulators cannot absorb.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | OTC Dry Eye Drops Market |
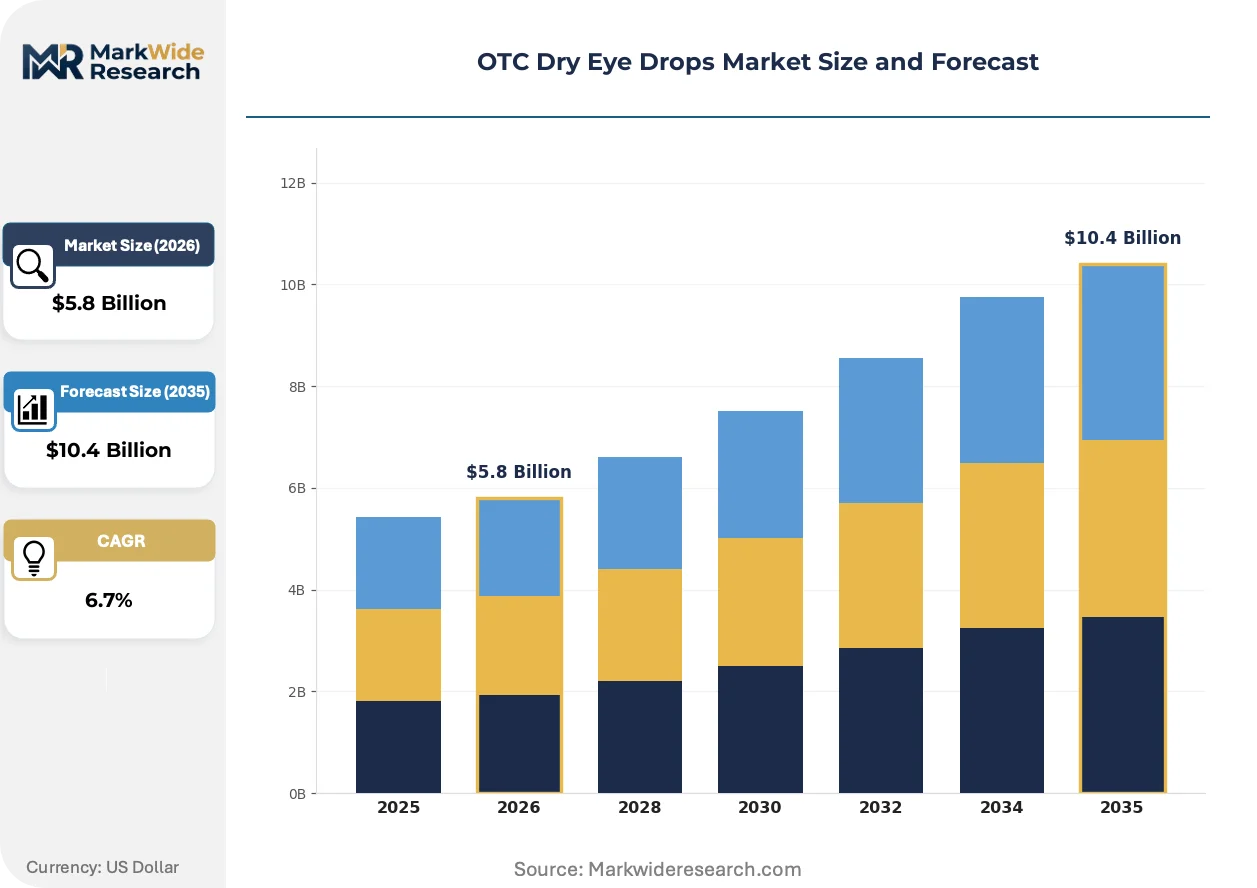
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.4 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrating Drops, Lubricating Drops, Artificial Tears, Gel Drops Application: Allergy Relief, Post-Surgery Care, General Use, Contact Lens Comfort Delivery Mode: Dropper Bottles, Spray Bottles, Single-Dose Vials, Multi-Dose Containers End User: Retail Consumers, Pharmacies, Clinics, Online Shoppers |
| Companies Covered | Rohto Pharmaceutical Co. Ltd., AbbVie, Inc., Johnson & Johnson Services Inc., Santen Pharmaceutical Co. Ltd., Novartis AG, Prestige Consumer Healthcare Inc., Bausch + Lomb, Alcon, Altaire Pharmaceuticals Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
OTC Dry Eye Drops Market Evolving Landscape
Automation of manufacturing processes and sterility assurance systems is compressing production timelines while elevating quality thresholds across the ophthalmic sector. Formulation science and digital health integration are converging to reshape how consumers select and replenish eye care products.
Closed-system aseptic filling technology is automating vial processing from formulation to final packaging without human intervention in the ISO 5 zone. Johnson & Johnson and Alcon deploy these systems at scale to reduce contamination risk and extend batch run lengths. The technology is automating workforce reduction in high-cost manufacturing geographies while enabling output expansion in regulated markets.
EMA Medical Device Regulation (MDR) implementation tightens clinical evidence requirements for Class IIa ophthalmic devices including preservative-free droppers. Manufacturers must generate post-market surveillance data that previous directives exempted. Smaller European formulators face portfolio rationalization as notified body capacity constrains certification throughput.
Subscription-based replenishment through telemedicine platforms displaces episodic pharmacy purchasing among chronic dry eye sufferers. Optometry networks in the United States pilot automated refill algorithms tied to symptom diary apps. This channel shift concentrates most visibly in metropolitan markets with established direct-to-consumer pharmacy infrastructure.
OTC Dry Eye Drops Market Segmentation
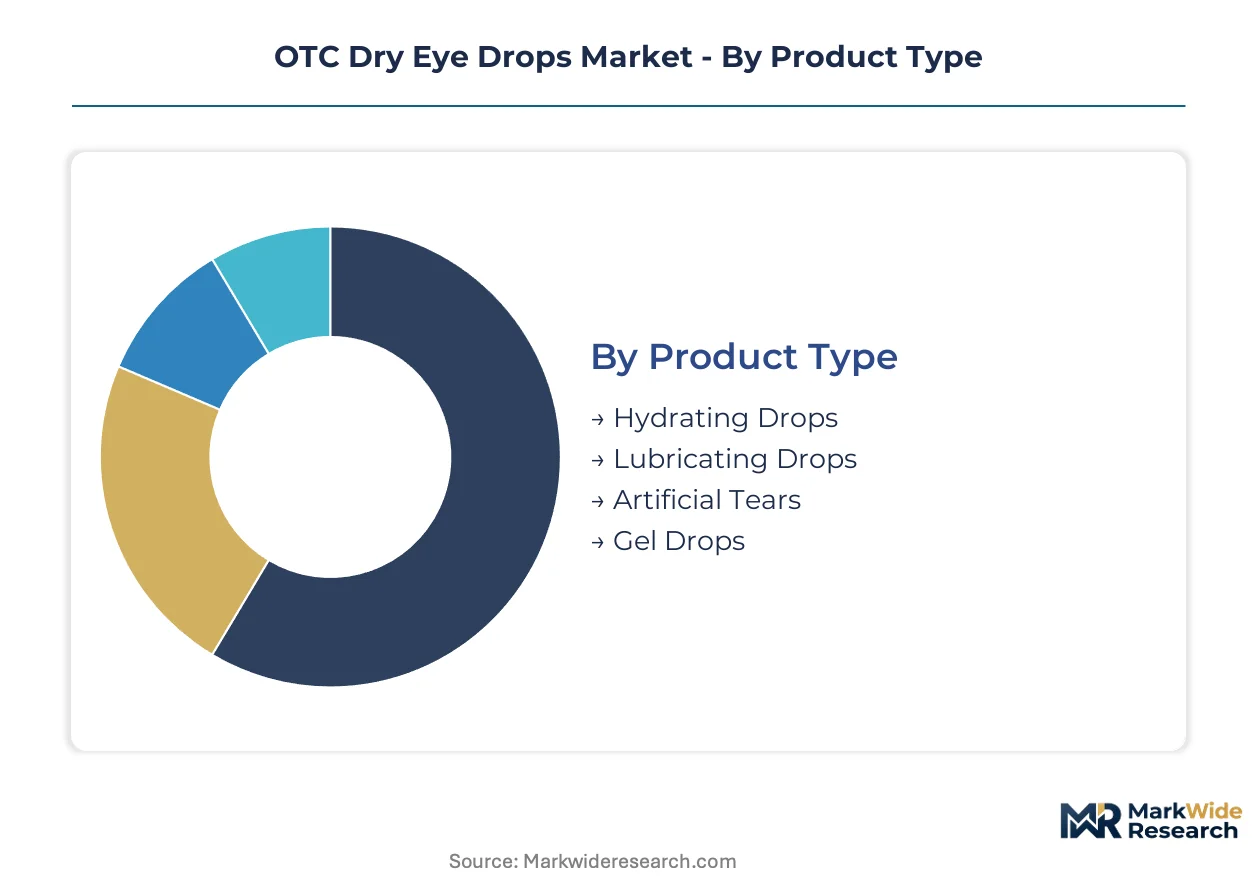
OTC dry eye drops segmentation reveals distinct performance tiers across formulation chemistry and delivery technology. Product type and delivery mode splits determine margin structure, while application and end-user dimensions shape channel strategy and geographic deployment priorities.
Product Type:
Hydrating drops anchor volume leadership through accessible price positioning, while gel drops concentrate premium margin capture.
- Hydrating Drops:Electrolyte-balanced aqueous formulations restore tear film osmolarity in mild-to-moderate dry eye cases. Demand concentrates among digital workers in the United States seeking midday refreshment without visual blurring.
- Gel Drops:Viscous polymer matrices including carbomer and carbopol extend corneal residence time for overnight or severe symptom management. Severe dry eye sufferers in Germany and Japan accept 3-4x price premiums for prolonged relief duration.
- Lubricating Drops:Lipid-based emulsions target evaporative dry eye with meibomian gland dysfunction etiology.
- Artificial Tears:Cellulose derivative formulations mimic natural tear viscosity for broad-spectrum daily use.
Mature deployment sits with Artificial Tears. Newer deployment is concentrated in Gel Drops.
Application:
General use applications dominate prescription-free volume, while post-surgery care commands specialized formulation requirements and clinical validation.
- General Use:Broad-indication formulations address environmental dryness, screen fatigue, and age-related tear deficiency without diagnostic prerequisites. Pharmacy chains in the United States and United Kingdom stock these as front-of-counter staples with high inventory turnover velocity.
- Post-Surgery Care:Preservative-free hyaluronate formulations support corneal epithelial healing following LASIK, cataract, or refractive procedures. Ophthalmology clinics in South Korea and Spain specify these for controlled post-operative regimens with documented outcomes.
- Allergy Relief:Antihistamine-mast cell stabilizer combinations target seasonal allergic conjunctivitis with dual-action mechanisms.
- Contact Lens Comfort:Compatible formulations lubricate without deposit formation on silicone hydrogel surfaces.
Volume leadership remains with General Use. Steepest expansion trajectory is emerging in Contact Lens Comfort.
Delivery Mode:
Multi-dose containers retain cost efficiency for chronic users, while single-dose vials capture portability-driven premium positioning.
- Single-Dose Vials:Blow-fill-seal aseptic units eliminate preservative requirements through unit-dose sterility assurance. Digital workers aged 25-45 in metropolitan United States markets prioritize these for desk drawers and travel kits despite per-dose cost premiums.
- Multi-Dose Containers:Preserved formulations in conventional dropper bottles minimize per-treatment cost for chronic daily users. Medicare-eligible populations in Florida and Arizona sustain volume through pharmacy loyalty programs and bulk purchasing habits.
- Dropper Bottles:Standard 10-15ml presentations dominate retail shelf allocation with familiar user interface.
- Spray Bottles:Mist delivery systems target pediatric and geriatric users with application difficulty on conventional drops.
Cost efficiency concentrates in Multi-Dose Containers. Contamination avoidance is driving fastest adoption in Single-Dose Vials.
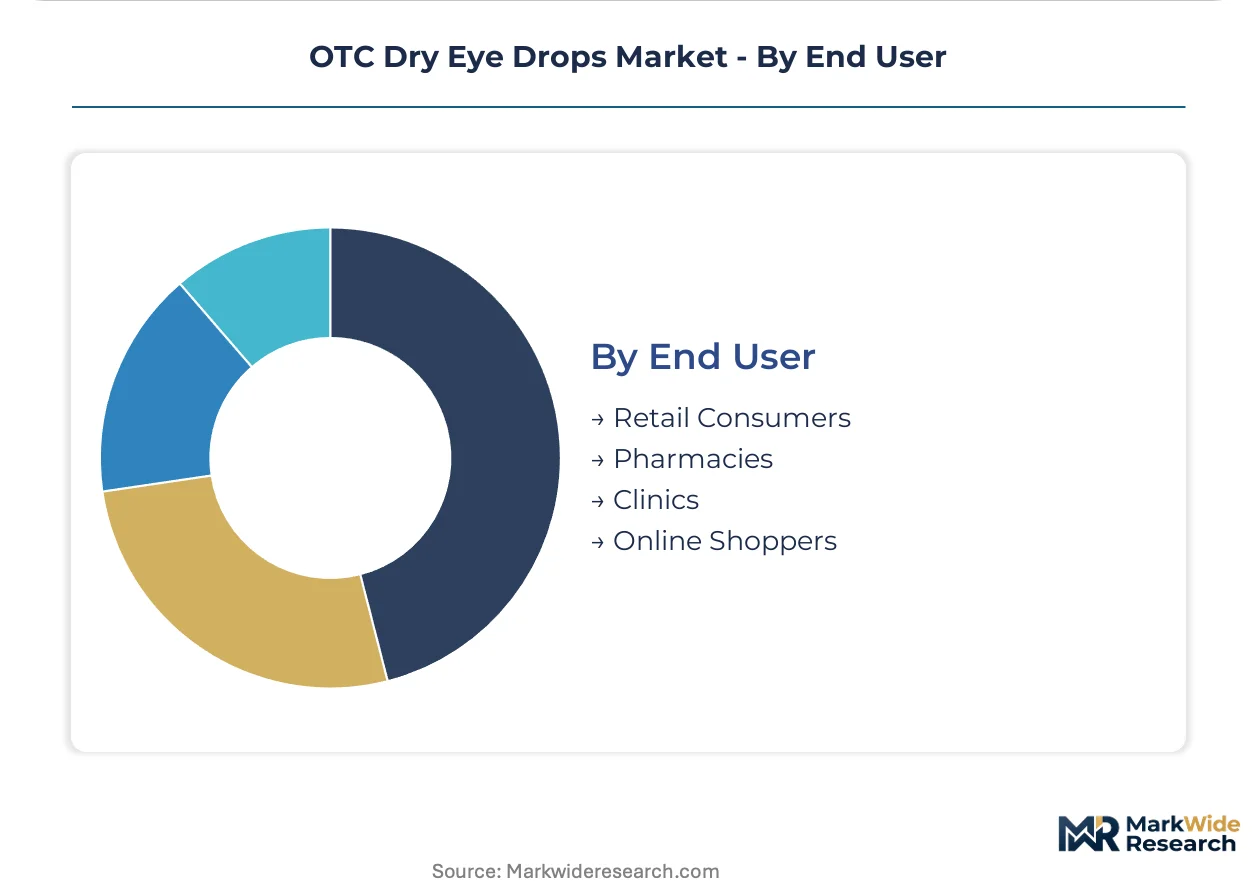
End User:
Retail consumers generate episodic purchase patterns, while online shoppers exhibit subscription-based replenishment behavior with higher lifetime value.
- Online Shoppers:Direct-to-consumer platforms enable automated refill algorithms tied to symptom tracking applications. Chronic sufferers in California and New York metropolitan corridors demonstrate 40% higher annual purchase frequency through subscription models versus pharmacy pickup.
- Retail Consumers:Supermarket and convenience channel purchasers respond to point-of-sale visibility and promotional pricing. Seasonal allergy sufferers in Texas and Illinois drive summer volume spikes through impulse and destination shopping patterns.
- Pharmacies:Professional consultation access influences brand switching and trial of premium formulations.
- Clinics:Healthcare provider recommendation carries authority for post-surgical and severe dry eye indications.
Transaction volume leadership sits with Retail Consumers. Recurring revenue concentration is expanding fastest among Online Shoppers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for pharmaceutical manufacturing in Hyderabad, Telangana, and Gujarat's Dahej SEZ concentrate sterile formulation capacity for export markets. These zones attract aseptic filling investments through tax holidays and duty exemptions on imported equipment.
United States
Aging demographics in Florida and Arizona sustain multi-dose container volume through pharmacy loyalty programs. FDA ophthalmic sterility guidance elevates facility investment thresholds for preservative-free alternatives. Johnson & Johnson's manufacturing presence in New Jersey anchors East Coast distribution networks serving metropolitan digital worker concentrations.
Germany
Severe dry eye sufferers in Bavaria and Baden-Württemberg accept premium pricing for gel drop formulations with extended residence time. EMA Medical Device Regulation extends CE marking timelines for novel dropper mechanisms. Heidelberg and Mannheim clusters host specialized aseptic equipment suppliers serving mid-tier European formulators.
Japan
Contact lens wearer comfort positioning drives silicone hydrogel-compatible formulation demand in Tokyo and Osaka metropolitan corridors. PMDA post-market surveillance requirements align with EMA MDR evidence standards. Santen Pharmaceutical's Kobe manufacturing base supplies preservative-free technology leadership across Asian pharmacy chains.
India
Organized pharmacy retail expansion in tier-2 cities creates education campaign opportunities for preservative-free adoption. CDSCO manufacturing license requirements for ophthalmic products tighten sterility validation protocols. Ahmedabad and Mumbai pharmaceutical clusters scale blow-fill-seal single-dose vial production for domestic and export markets.
South Korea
Post-surgical care formulations command specialized positioning following LASIK and refractive procedure volumes in Seoul and Busan. MFDS ophthalmic product registration requires stability data under accelerated aging protocols. Pangyo Bio Valley concentration attracts contract manufacturing organizations serving Japanese and Chinese brand owners.
OTC Dry Eye Drops Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation tiers. The sector exhibits moderate consolidation with three to four entities commanding significant retail shelf presence while mid-tier regional formulators fragment price-sensitive segments. Strategic archetypes include diversified healthcare conglomerates with ophthalmic divisions, pure-play eye care specialists, and contract manufacturing organizations serving private label brands. Capacity expansion in aseptic filling infrastructure and strategic partnerships for distribution access represent dominant competitive moves.
Among diversified healthcare conglomerates, Johnson & Johnson Services Inc. and Novartis AG occupy positions spanning consumer health and prescription ophthalmic boundaries. Johnson & Johnson exemplifies retail shelf dominance through pharmacy channel leverage. Novartis AG represents pharmaceutical-origin diversification into consumer-accessible formulations. Alcon sits within the pure-play eye care specialist archetype with concentrated expertise across surgical and vision care segments. These entities anchor competitive positioning through manufacturing scale and regulatory navigation capabilities rather than narrow product specialization.
| Leading Market Players |
|---|
| Rohto Pharmaceutical Co. Ltd. |
| AbbVie, Inc. |
| Johnson & Johnson Services Inc. |
| Santen Pharmaceutical Co. Ltd. |
| Novartis AG |
| Prestige Consumer Healthcare Inc. |
| Bausch + Lomb |
| Alcon |
| Altaire Pharmaceuticals Inc. |
| Others |
Value Network & Pricing Analysis
Preservative-free versus preserved formulation divergence splits pricing power and procurement geography across the OTC dry eye drops sector. Premium single-dose vials command manufacturing investment in Switzerland and Germany while commodity multi-dose bottles source from Indian pharmaceutical clusters, creating tier-specific supply chain configurations.
Pricing Analysis
Short lead-time premiums attach to single-dose vial orders from ISO 5 cleanroom facilities in Germany and Switzerland, while spot inventory discounts emerge from Indian contract manufacturers with excess blow-fill-seal capacity. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with FDA-validated facilities capturing margin premiums over CDSCO-registered alternatives. Pricing pressure stems from propylene glycol feedstock volatility tied to energy market disruptions. Chronic daily users in Medicare-eligible populations exhibit highest price sensitivity, whereas digital workers aged 25-45 accept per-dose premiums for portability.
Supply Chain Analysis
Single-source vulnerability sits with aseptic filling equipment suppliers concentrated in Heidelberg and Mannheim, where German precision engineering dominates blow-fill-seal machinery procurement. Active pharmaceutical ingredient production draws from India, China, and Switzerland, with carbomer and carbopol polymer supplies resting on petrochemical feedstocks from the US Gulf Coast and Rotterdam. Tariff exposure on imported equipment creates procurement bottlenecks for mid-tier formulators scaling preservative-free lines. Distribution runs through pharmacy chain consolidation in the United States, direct-to-consumer platforms in metropolitan California and New York, and organized retail expansion in Indian tier-2 cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Closed-system aseptic filling technology is displacing legacy manual cleanroom operations, forcing capital reallocation toward automation and single-dose vial infrastructure.
For Market Incumbents: Anchor market position through backward integration into blow-fill-seal equipment partnerships with German machinery suppliers, reducing single-source vulnerability. Defend against private-label erosion by locking pharmacy chain exclusivity through subscription algorithm integration with telemedicine platforms. Capacity addition in Gujarat's Dahej SEZ preserves cost competitiveness for export markets. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting chronic dry eye sufferers in California and New York metropolitan corridors, bypassing pharmacy intermediaries. White-space concentration sits with silicone hydrogel lens compatibility formulations, where premium pricing corridors remain underdeveloped outside Alcon's positioning. Tier-2 Indian pharmacy chains offer first-mover advantage for preservative-free education campaigns ahead of organized retail saturation. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified healthcare conglomerates seeking ophthalmic consumer health exposure. Long-term viability hinges on aseptic manufacturing certification scalability and telemedicine channel integration. Acquisition target archetype: mid-tier formulators with ISO 13485 certification and underutilized cleanroom capacity. Watch FDA preservative safety threshold revisions as inflection indicator for portfolio rationalization timing.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Filling Automation | Closed-system technology from German suppliers reduces contamination risk and extends batch run lengths. |
| Single-Dose Vial Scale-Up | Blow-fill-seal capacity expansion in Indian SEZs captures portability-driven demand from digital workers. |
| Telemedicine Platform Integration | Subscription algorithms tied to symptom tracking apps displace episodic pharmacy purchasing patterns. |
| Preservative-Free Formulation Pivot | EMA MDR compliance and FDA sterility guidance validate premium positioning for benzalkonium chloride alternatives. |
| Contact Lens Compatibility Development | Silicone hydrogel-specific formulations open pricing corridors distinct from generic artificial tears. |
Research Methodology
Multi-period observation of formulation approval timelines, cleanroom capacity utilization, and pharmacy channel inventory turns anchored the trend analysis, supplemented by interviews with ophthalmic manufacturing executives, regulatory affairs leads at notified bodies, pharmacy chain category managers, and aseptic equipment procurement directors. Secondary validation drew from FDA ophthalmic guidance documents, EMA MDR implementation updates, CDSCO manufacturing license registries, and ISO 13485 certification databases. Bottom-up facility capacity modeling and top-down prescription-free ophthalmic market sizing provided cross-check triangulation.
Segment-weighting across product type, delivery mode, application, and end-user dimensions shaped the analytical framework over the projection horizon. CAGRs derived from growth driver elasticity modeling against screen time exposure trends, aging demographic trajectories, and pharmacy channel evolution. Forecast inputs incorporated aseptic technician certification pipeline constraints and propylene glycol feedstock price volatility assumptions.
Regulatory timeline slippage, cleanroom equipment procurement bottlenecks, and telemedicine channel adoption velocity are the dominant revision risks. Forecasts reflect documented assumptions on FDA and EMA guidance implementation pacing. Deviation in preservative safety threshold determinations would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Systemic Lupus Erythematosus Drugs Market
Pharmaceuticals
Dermatological Drugs Market
Pharmaceuticals
Zoledronic Acid Market
Pharmaceuticals
Antihelminthics Market
Pharmaceuticals
Italy Healthcare Market
Pharmaceuticals
Carbapenem Market
Pharmaceuticals
Sulfonylureas Market
Pharmaceuticals
AI in Pharma Market
Pharmaceuticals
Generic Pharmaceuticals Contract Manufacturing Market
Pharmaceuticals
Canada Specialty Pharmacy Market
Pharmaceuticals
Europe Generic Drug Market
Pharmaceuticals
Asia-Pacific Anesthesia Drugs Market
Pharmaceuticals
Medicinal Fungi Market
Pharmaceuticals
Acetaminophen Market
Pharmaceuticals
Anticholinergic Drugs Market
Pharmaceuticals
Anti-Infective Vaccines Market