
 Anisole Derivatives Market | 2026-2036
Anisole Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Anisole Derivatives Market Analytics
Specialty intermediate profit pools is fragmenting across pharmaceutical-grade and fragrance-grade anisole derivatives as purity thresholds diverge. Atul Ltd leverages its integrated phenol-to-anisole chain to sustain cost leadership in 4-methoxybenzaldehyde output. Evonik Industries anchors European supply through high-specification methoxylated aromatics for regulated pharma applications. Solvay competes on crystallization technology to differentiate food-grade anisole from industrial grades.
Anisole derivatives comprise methoxy-substituted aromatic compounds synthesized via Williamson ether synthesis or methylation of phenolic precursors, serving primarily as intermediates for pharmaceuticals, agrochemicals, and perfumery materials. Pharmaceutical applications dominate value capture, with 4-methoxybenzaldehyde commanding premium pricing due to stringent impurity profiles required by drug master file submissions. Fragrance-grade anisole and 4-methoxyphenol represent faster-growing volume pools as clean-label personal care trends expand natural-identical ingredient demand. Powder and crystal forms concentrate margin retention where transportation costs and stability requirements favor solid-state logistics over liquid bulk.
EPA standards in the United States and REACH in Europe enforce residual solvent limits and mutagenic impurity thresholds that filter non-compliant Asian suppliers from Western pharma supply chains. India's CDSCO aligns with ICH Q3C guidelines, enabling domestic manufacturers to serve both regulated export markets and local generic API production. Stakeholders must monitor regulatory harmonization gaps between emerging market pharmacopoeias and USP/EP standards to anticipate qualification barriers for new derivative entrants.
Market Dynamics
Regulatory purity specifications from EPA and REACH are fragmenting supplier tiers, forcing pharmaceutical-grade anisole derivatives toward dedicated production lines while fragrance-grade volumes scale through commodity channels.
Growth Catalysts
- REACH compliance deadlines:European pharmaceutical manufacturers are qualifying Indian suppliers under ICH Q3C guidelines, redirecting procurement from non-compliant Asian sources toward CDSCO-aligned facilities.
- Clean-label personal care:Fragrance-grade 4-methoxyphenol demand is accelerating as natural-identical positioning replaces synthetic labeling in premium cosmetic formulations.
- Williamson ether synthesis optimization:Continuous-flow methylation technology is reducing solvent waste and enabling smaller-batch pharmaceutical intermediate production.
Market Restraints
- Phenol feedstock volatility:Crude oil-linked benzene pricing transmits directly to anisole derivative cost structures, compressing margins for non-integrated producers.
- Indian supply concentration:Export-oriented pharmaceutical intermediate output clusters in Gujarat and Maharashtra, creating single-point-of-failure exposure for Western API manufacturers.
- Mutagenic impurity thresholds:ICH M7 guidelines on nitrosamine and azo compound limits are disqualifying legacy batch processes from regulated pharma supply chains.
Strategic Opportunities
- Brazilian agrochemical formulation:ANVISA-aligned anisole derivative demand is underpenetrated relative to pharmaceutical applications, offering volume diversification for purity-flexible producers.
- Biocatalytic methoxylation:Enzymatic aromatic substitution is converging with flow chemistry to enable chiral anisole derivative production for specialty API intermediates.
- EU Green Deal carbon border adjustments:CBAM implementation on chemical imports is creating first-mover advantage for European producers with verified low-carbon phenol sourcing.
Industry Challenges
- Analytical method transfer:Drug master file submission requirements for impurity profiling are extending qualification timelines by 18-24 months for new derivative entrants.
- Specialized reactor fabrication:Hastelloy-lined continuous-flow systems for corrosive methylation chemistry require capital commitments that strain mid-scale producers.
- Cross-contamination protocols:Segregated production lines for fragrance-grade and pharmaceutical-grade anisole are forcing facility redesigns and redundant quality systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anisole Derivatives Market |
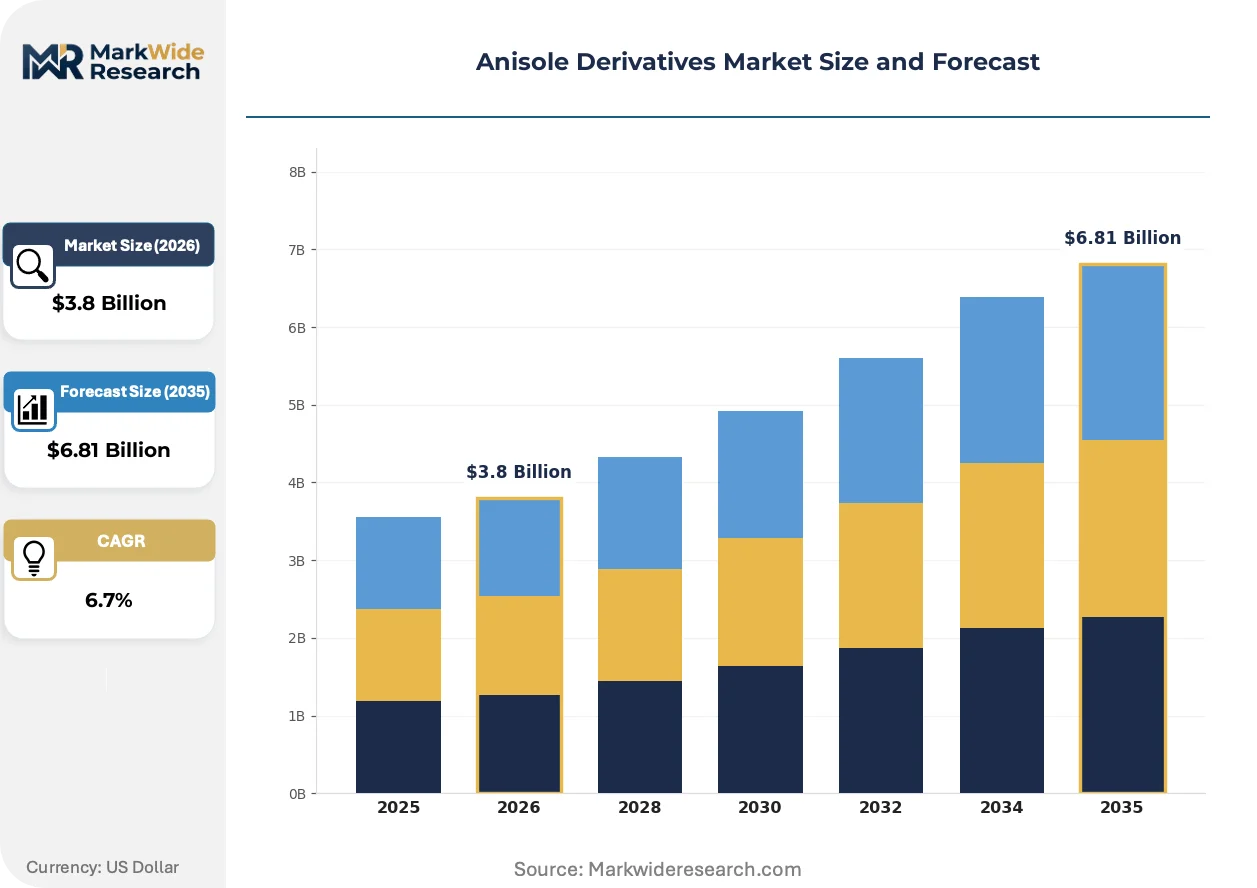
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anisole, 4-Methoxybenzaldehyde, 2-Methoxynitrobenzene, 4-Methoxyphenol Application: Pharmaceuticals, Agriculture, Fragrances, Dyes Form: Liquid, Powder, Granules, Crystals End User: Chemical Manufacturers, Textile Industry, Food Industry, Personal Care |
| Companies Covered | Atul Ltd, Benzo Chem Industries, Camlin Fine Sciences, Emmennar Chem, Evonik Industries, Solvay, Merck KGaA, Surya Life Sciences, Tokyo Chemical Industry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anisole Derivatives Market Evolving Landscape
Process intensification and regulatory digitization are compressing batch cycle times while fragmenting quality tiers across pharmaceutical and industrial applications.
Continuous-flow Williamson ether synthesis is digitizing batch record-keeping and real-time impurity monitoring. European pharmaceutical API manufacturers are adopting these systems fastest, with German and Swiss facilities leading implementation. The technology is digitizing quality assurance workflows and enabling parametric release protocols that slash holding times for 4-methoxybenzaldehyde shipments.
REACH Annex XVII restrictions on residual solvents are tightening specification windows for methoxylated aromatics entering European cosmetic and pharmaceutical supply chains. ECHA enforcement of updated mutagenicity thresholds is forcing reformulation of legacy synthesis routes. Fragrance-grade anisole producers in India and China are responding by segregating production lines and implementing dedicated analytical laboratories for European-bound volumes.
Buyer consolidation among generic API manufacturers is compressing supplier qualification cycles and unbundling technical service from material pricing. Large Indian pharmaceutical formulators are centralizing anisole derivative procurement through preferred supplier agreements, displacing spot-market purchases. This concentration is most visible in Hyderabad and Ahmedabad, where top-five generic producers now account for the majority of pharmaceutical-grade methoxybenzaldehyde offtake.
Anisole Derivatives Market Segmentation
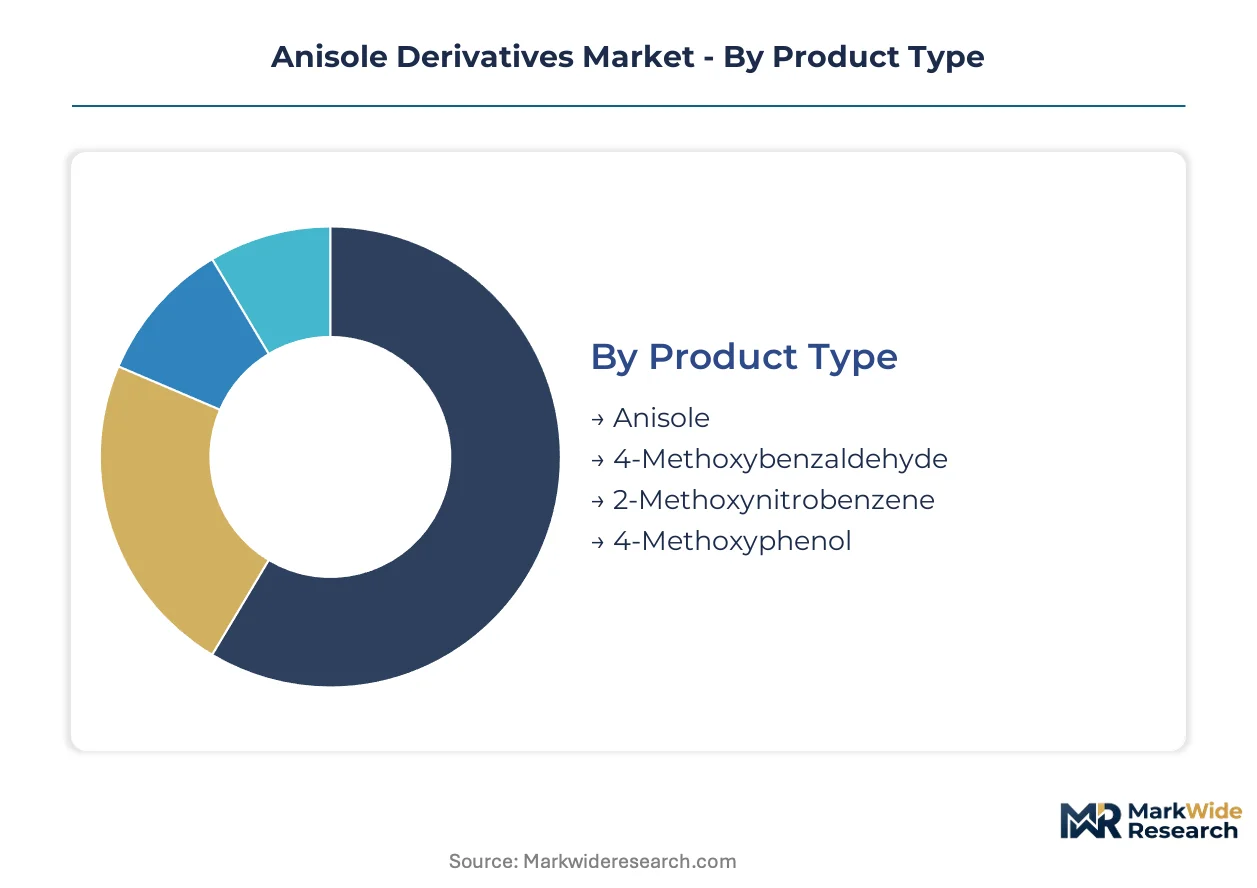
Anisole derivative specifications diverge sharply across end-use tiers, with pharmaceutical-grade intermediates commanding extended qualification cycles while fragrance-grade materials turn inventory faster. Form and purity requirements reshape supplier economics, forcing dedicated production lines for regulated versus industrial applications.
Product Type:
Cycle times stretch longest for pharmaceutical intermediates requiring drug master file documentation, while fragrance-grade anisole rotates inventory rapidly through commodity channels.
- Anisole:Methoxybenzene serves as the foundational feedstock for downstream methoxylated aromatics, with demand concentrating in Indian and Chinese bulk chemical manufacturing. Fragrance compound producers in Grasse and Mumbai absorb volumes for natural-identical perfumery formulations.
- 4-Methoxybenzaldehyde:This aldehyde intermediate commands premium positioning in active pharmaceutical ingredient synthesis, particularly for antihistamine and antipsychotic drug classes. Hyderabad and Ahmedabad API clusters drive procurement, with ICH Q3C-compliant suppliers capturing preferred supplier status from large generic formulators.
- 2-Methoxynitrobenzene:Nitro-substituted derivative feeds agrochemical intermediate production, with Brazilian and Indian crop protection sectors absorbing volumes.
- 4-Methoxyphenol:Antioxidant functionality anchors personal care applications, with clean-label cosmetic brands in South Korea and Germany substituting synthetic preservatives.
4-Methoxybenzaldehyde anchors the volume base while 4-methoxyphenol gains share at the steepest rate.
Application:
Margin structures stratify across regulatory intensity, with pharmaceutical applications supporting sustained pricing premiums against cyclical agricultural demand.
- Pharmaceuticals:Active pharmaceutical ingredient intermediates dominate value capture, with 4-methoxybenzaldehyde and methoxylated benzyl derivatives requiring impurity profiles below 0.1% for drug master file submissions. CDSCO-aligned Indian manufacturers serve both regulated export markets and domestic generic production.
- Agriculture:Crop protection formulation demand concentrates in fungicide and herbicide synthesis, with Brazilian ANVISA-registered derivatives showing underpenetrated growth potential relative to pharmaceutical applications.
- Fragrances:Natural-identical positioning drives cosmetic-grade anisole absorption, with EU REACH Annex XVII compliance separating European-bound from industrial-grade supply streams.
- Dyes:Textile colorant intermediates utilize methoxylated nitroaromatics, with Gujarat and Zhejiang dye house clusters driving spot-market procurement.
Pharmaceutical applications anchor the volume base while fragrances gain share at the steepest rate.
Form:
Logistics economics favor solid-state derivatives where transportation costs and stability requirements outweigh liquid bulk convenience.
- Liquid:Bulk anisole serves fragrance compound blending and continuous-flow pharmaceutical synthesis, with dedicated tanker logistics limiting supplier radius to 500-kilometer industrial corridors.
- Powder:Finely divided 4-methoxyphenol enables uniform dispersion in cosmetic formulations, with micronization capabilities differentiating European specialty chemical suppliers.
- Granules:Intermediate particle sizing balances flowability and dissolution kinetics for agrochemical formulation, with Brazilian and Indian crop protection blenders specifying narrow size distributions.
- Crystals:High-purity crystalline 4-methoxybenzaldehyde supports parametric release protocols, with Solvay's crystallization technology enabling food-grade specification from shared pharmaceutical-grade assets.
Crystals anchor the volume base while powder forms gain share at the steepest rate.
End User:
Procurement concentration among large chemical manufacturers compresses supplier margins while fragmenting technical service requirements across specialized end-use clusters.
- Chemical Manufacturers:Integrated phenol-to-derivative producers like Atul Ltd capture backward economics, with captive anisole output feeding downstream methoxylated aromatic portfolios for export-oriented pharmaceutical sectors.
- Textile Industry:Dye intermediate demand clusters in Surat and Shaoxing printing districts, with azo coupling chemistry consuming methoxynitrobenzene derivatives for reactive dye synthesis.
- Food Industry:Flavor and antioxidant applications require FSSAI and FDA food-grade certifications, with natural-identical positioning displacing synthetic labeling in premium product lines.
- Personal Care:Clean-label cosmetic brands specify REACH-compliant methoxyphenol antioxidants, with South Korean and German formulators driving specification tightening for natural-identical positioning.
Chemical manufacturers anchor the volume base while personal care gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. Western markets prioritize pharmaceutical-grade purity under stringent regulatory regimes, while Asian manufacturing hubs drive volume through fragrance and agrochemical intermediates. This bifurcation reshapes supplier qualification requirements and trade flows.
India
Pharmaceutical intermediate demand from Hyderabad and Ahmedabad API clusters anchors regional consumption. CDSCO alignment with ICH Q3C guidelines enables domestic manufacturers to serve regulated export markets. Gujarat's integrated phenol-to-anisole facilities supply methoxylated aromatics for European pharmaceutical formulators.
Germany
High-specification methoxylated aromatics for regulated pharma applications concentrate demand among specialty chemical consumers. ECHA enforcement of REACH Annex XVII residual solvent limits filters non-compliant imports. Ludwigshafen and Leverkusen industrial corridors host continuous-flow synthesis adoption for real-time impurity monitoring.
United States
Generic API manufacturers drive procurement of 4-methoxybenzaldehyde under FDA drug master file submission protocols. EPA standards on mutagenic impurity thresholds disqualify legacy batch processes from pharmaceutical supply chains. New Jersey and North Carolina pharmaceutical corridors centralize preferred supplier agreements with ICH M7-compliant sources.
China
Bulk anisole production for fragrance compound blending and dye intermediate synthesis dominates manufacturing output. MIIT industrial standards and evolving environmental enforcement reshape coastal chemical park operations. Zhejiang and Jiangsu dye house clusters absorb methoxynitrobenzene derivatives for textile colorant production.
Brazil
Agrochemical formulation demand for fungicide and herbicide synthesis shows underpenetrated growth relative to pharmaceutical applications. ANVISA registration requirements for crop protection intermediates create qualification barriers for non-aligned suppliers. São Paulo and Rio Grande do Sul crop protection blenders specify narrow particle size distributions for granular formulations.
Anisole Derivatives Market Competitive Landscape
Capability concentration sits with integrated phenol-to-derivative producers; scale advantage sits with bulk chemical manufacturers serving fragrance and industrial applications. The market structures around three tiers: backward-integrated specialists with captive feedstock, European high-purity specialists, and Asian volume exporters. Dominant competitive moves include segregated production line investments for pharmaceutical-grade certification and continuous-flow technology licensing for regulatory compliance.
Among Indian integrated producers, Atul Ltd and Emmennar Chem occupy positions exemplifying backward integration from phenol through methoxylated aromatics. European high-specification specialists include Evonik Industries and Solvay, representing the regulatory-compliant tier serving pharmaceutical and food-grade applications. Surya Life Sciences anchors the mid-scale pharmaceutical intermediate segment with CDSCO-aligned facilities.
| Leading Market Players |
|---|
| Atul Ltd |
| Benzo Chem Industries |
| Camlin Fine Sciences |
| Emmennar Chem |
| Evonik Industries |
| Solvay |
| Merck KGaA |
| Surya Life Sciences |
| Tokyo Chemical Industry |
| Others |
Value Network & Pricing Analysis
Phenol feedstock volatility transmits directly through anisole derivative cost structures, compressing margins for non-integrated producers while widening spreads between pharmaceutical-grade and fragrance-grade tiers. This commodity price exposure forces buyers toward long-term offtake contracts with backward-integrated suppliers in Gujarat and Maharashtra, reshaping procurement patterns across regulated and industrial applications.
Pricing Analysis
Long-term offtake agreements dominate pharmaceutical-grade 4-methoxybenzaldehyde procurement, with ICH Q3C-compliant Indian suppliers commanding premium positioning over spot-market fragrance-grade volumes. Price differentiation rests on certification tier and volume scale, with drug master file-aligned producers capturing sustained premiums against commodity methoxylated aromatics. Cost compression in fragrance-grade anisole intensifies as Chinese bulk manufacturers expand output, making generic API formulators the least price-sensitive segment due to regulatory switching costs.
Supply Chain Analysis
Tariff exposure between India and the European Union dominates supply chain risk planning for REACH-compliant pharmaceutical intermediates. Manufacturing concentrates in India, China, and Germany, with feedstock dependence on crude oil-linked benzene, methylating agents, and specialized Hastelloy reactor components. Single-source vulnerability clusters around Gujarat's integrated phenol-to-anisole facilities. Distribution runs through pharmaceutical intermediate distributors and direct preferred supplier agreements with large generic API manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from biocatalytic methoxylation routes that promise chiral specificity for specialty API intermediates, requiring defensive positioning around regulatory qualification moats.
For Market Incumbents: Harden ICH M7-compliant production lines against enzymatic aromatic substitution threats by investing in continuous-flow methylation technology for real-time impurity monitoring. Deepen backward integration into phenol feedstock through captive benzene supply agreements that insulate margin structures from crude oil volatility. Lock in preferred supplier status with Hyderabad and Ahmedabad API clusters through dedicated technical service teams.
For New Entrants and Emerging Players: Pursue ANVISA-registered agrochemical intermediates as the most penetrable white space, with Brazilian crop protection blenders showing underpenetrated demand relative to pharmaceutical applications. Target fragrance-grade 4-methoxyphenol for South Korean clean-label cosmetic brands seeking REACH Annex XVII-compliant natural-identical antioxidants. Lead with micronization capabilities as a technical differentiation wedge against commodity Chinese suppliers.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors backward-integrated specialists with captive phenol supply and CDSCO-aligned quality systems. Five-to-ten year viability hinges on regulatory harmonization between emerging market pharmacopoeias and USP/EP standards. Monitor ICH Q3C guideline adoption rates across Southeast Asian pharmaceutical regulators as the critical inflection signal for export-oriented capacity valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive phenol supply insulates Atul Ltd and Emmennar Chem from benzene price volatility. |
| Continuous-Flow Technology Licensing | German and Swiss pharmaceutical API manufacturers adopt real-time impurity monitoring for parametric release protocols. |
| CDSCO Certification Investment | Domestic Indian alignment with ICH Q3C guidelines unlocks regulated export market access. |
| Segregated Production Line Buildout | Dedicated pharmaceutical-grade assets prevent cross-contamination with fragrance-grade volumes for EU REACH compliance. |
| ANVISA Registration Pathway | Brazilian agrochemical formulation demand offers volume diversification beyond pharmaceutical applications. |
Research Methodology
Operator-level perspectives from plant managers at integrated phenol-to-anisole facilities, procurement leads at downstream pharmaceutical API manufacturers, distribution channel partners in Gujarat and Maharashtra, and technical R&D directors specializing in Williamson ether synthesis anchored the qualitative base. These primary interviews combined with customs and trade data, ACC and Cefic chemical industry reports, SEC 10-K filings from listed specialty chemical producers, and CDSCO regulatory filings for secondary validation. Bottom-up capacity and utilization estimates triangulated against top-down consumption models across pharmaceutical, agrochemical, and fragrance end-use segments.
Scenario-bracketing around phenol feedstock price bands, regulatory harmonization timelines, and continuous-flow technology adoption curves shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product grade tier, end-use industry application, form specification, and regional production hub. CAGRs derived from historical volume trajectories adjusted for capacity expansion announcements and buyer consolidation trends among generic API manufacturers. Forecast inputs incorporated ICH M7 guideline enforcement intensity and EU Green Deal carbon border adjustment implementation schedules.
Macroeconomic conditions sit as an overlay; deviation in crude oil pricing, currency volatility between rupee-euro-dollar crosses, and pharmaceutical inventory destocking cycles would shift the trajectory. Forecasts reflect documented assumptions on regulatory compliance timelines and technology diffusion rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Gamma-Butyrolactone (GBL) Market
Organic Chemicals
Organic Binders Market
Organic Chemicals
Asia-Pacific Synthetic Camphor Market
Organic Chemicals
4-Tert-Butylcyclohexanone Market
Organic Chemicals
2,5-Dimethyl-2,4-Hexadiene Market
Organic Chemicals
Dimethylformamide (DMF) Market
Organic Chemicals
Behenyl Alcohol Market
Organic Chemicals
Cyclic Ketones Market
Organic Chemicals
Aliphatic Amines Market
Organic Chemicals
Benzyl Cyanide Market
Organic Chemicals
Absolute Ethanol Market
Organic Chemicals
Diethyl Ketone Market
Organic Chemicals
Methacrylic Acid Market
Organic Chemicals
Global Ketones Market
Organic Chemicals
Pyridine Derivatives Market
Organic Chemicals
Global Carboxylic Acid Market