
 Ethylamine Market | 2026-2036
Ethylamine Market Size, Share, and Industry Trends Forecast 2026-2036
Ethylamine Market Foresight
Multi-source procurement for ethylamine feedstocks is shifting toward vertically integrated amine producers with captive ethanol and ammonia supply. BASF SE leverages its Ludwigshafen integrated site to sustain margin control across ethylamine and derivative chains. Eastman Chemical Company anchors North American supply through Kingsport manufacturing scale. Balaji Amines Ltd. dominates Indian domestic volume with specialized aliphatic amine output.
Ethylamine is a primary aliphatic amine with the formula C₂H₅NH₂, produced industrially via ethanol amination over heterogeneous catalysts at 150–250°C and 10–30 bar, serving mainly as an intermediate for pharmaceuticals, pesticides, and rubber accelerators. Triethylamine leads product-type revenue due to its role as a proton scavenger in antibiotic and antiviral synthesis. Pharmaceutical companies represent the fastest-growing end-user category as CDMOs expand generic API capacity in India and China.
EPA oversight under the Toxic Substances Control Act and OSHA permissible exposure limits shape US manufacturing site approvals and worker safety capital expenditure. ECHA REACH registration requirements and the EU Green Deal chemical sustainability targets are forcing European producers to document carbon intensity across ethylamine supply chains. Stakeholders must monitor catalyst technology shifts from copper-chrome to base-metal systems and assess which producers can retrofit existing reactors without extended downtime.
Market Dynamics
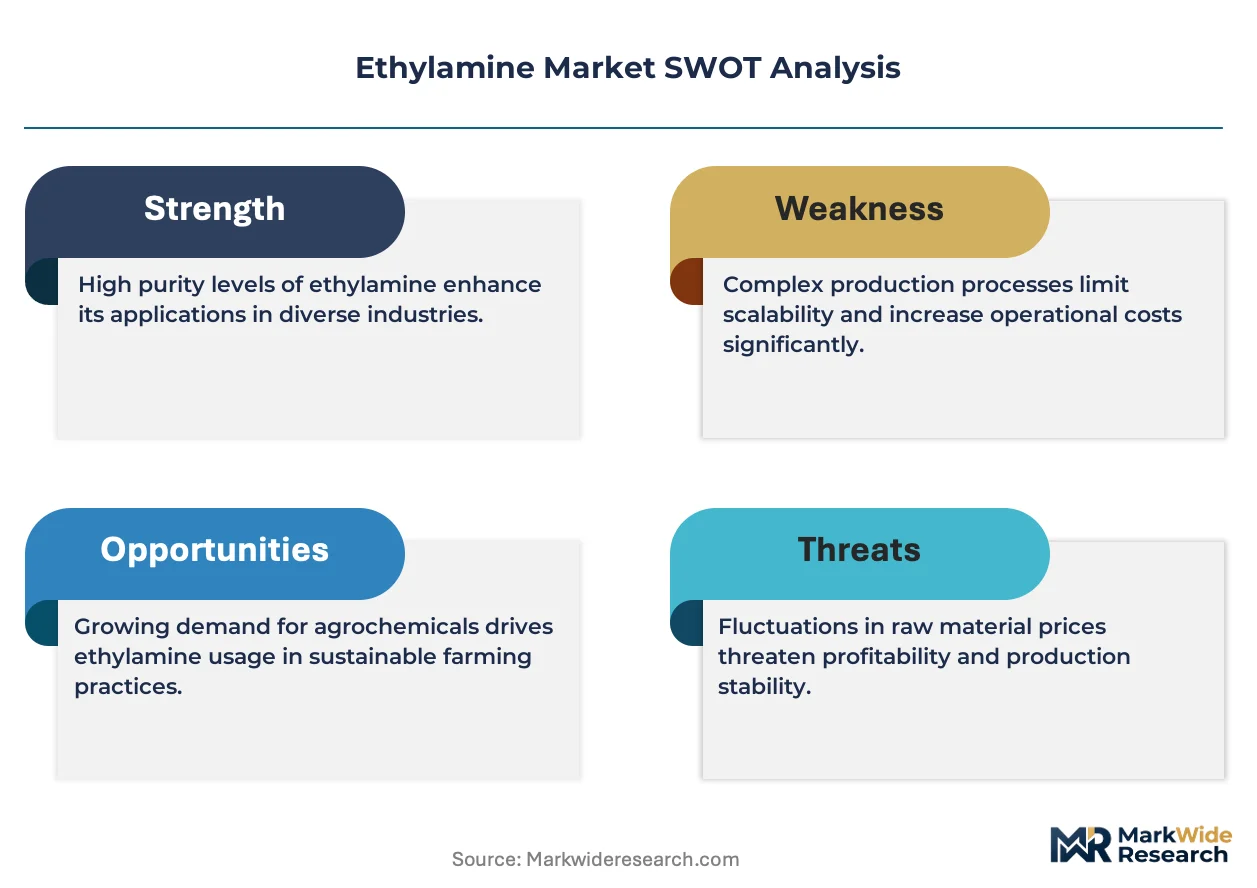
Feedstock volatility and regulatory purity mandates are compressing margins for non-integrated ethylamine producers while advantaging those with captive ethanol and ammonia supply chains.
Growth Catalysts
- Antibiotic synthesis expansion:CDMOs in India and China are scaling triethylamine consumption for proton scavenging in antiviral API production.
- REACH registration compliance:ECHA documentation requirements for carbon intensity disclosure are qualifying European suppliers for premium pharmaceutical contracts.
- Rubber accelerator demand:Tire manufacturers in Southeast Asia are increasing ethylamine derivative orders for vulcanization chemistry.
Market Restraints
- Ethanol price volatility:Corn and sugarcane feedstock fluctuations directly compress amination unit economics for non-captive producers.
- Chinese supply concentration:Zhejiang Jianye Chemical and domestic formulators control regional pricing through integrated captive consumption.
- Copper-chrome catalyst obsolescence:Environmental toxicity concerns are forcing premature reactor retrofits before base-metal catalyst validation completes.
Strategic Opportunities
- Brazilian agrochemical formulators:ANVISA registration pathways for imported ethylamine intermediates remain underpenetrated relative to Asian supply capacity.
- Continuous flow amination:Microreactor technology convergence with heterogeneous catalysis enables smaller-scale distributed production near pharmaceutical clusters.
- EU Green Deal chemical sustainability targets:Documented low-carbon ethylamine production qualifies for preferential procurement in European antibiotic supply chains.
Industry Challenges
- Process safety engineer scarcity:OSHA PEL compliance and TSCA site approvals require specialized talent that amine producers struggle to recruit.
- Reactor retrofit downtime:Catalyst transition from copper-chrome to base-metal systems demands extended shutdowns that disrupt contract fulfillment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethylamine Market |
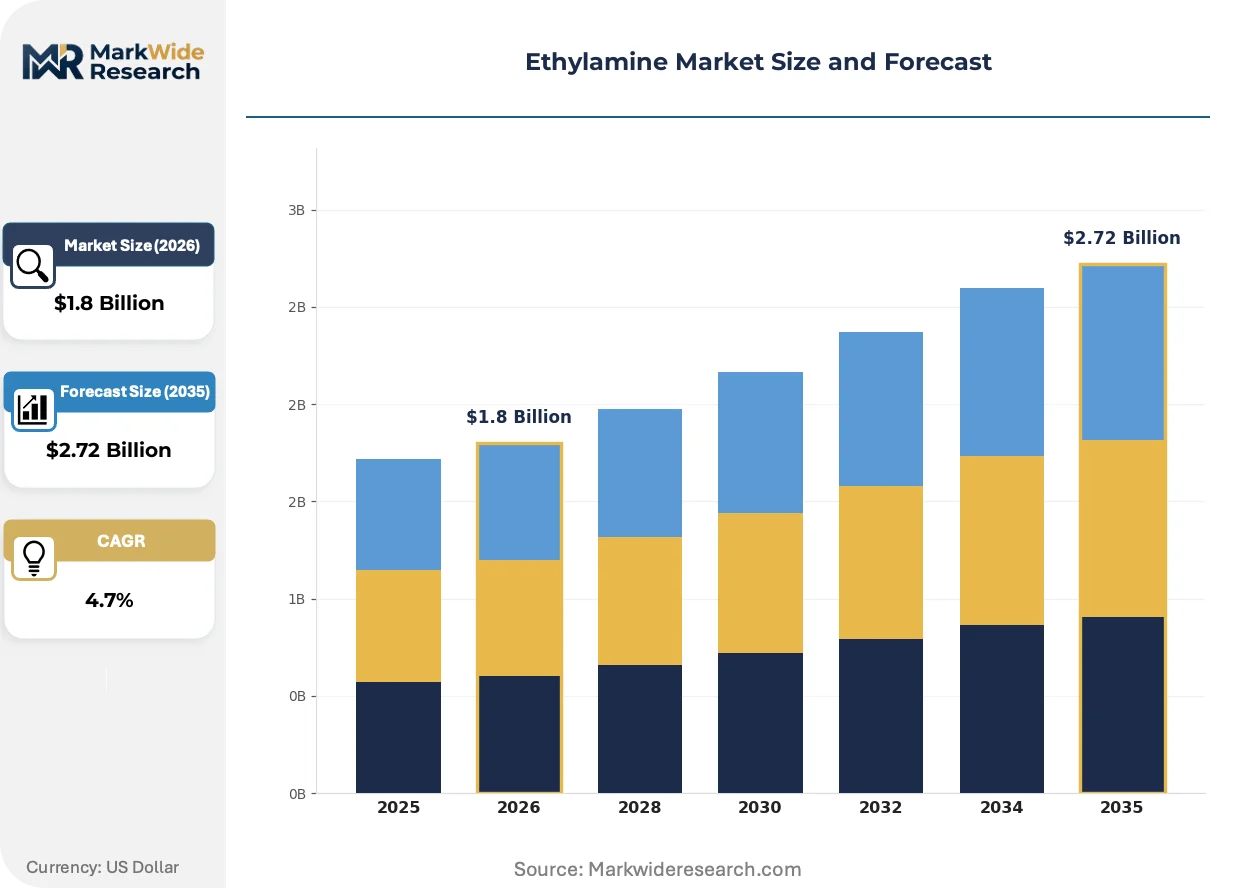
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethylamine, Diethylamine, Triethylamine, Ethanolamine Application: Pharmaceuticals, Agrochemicals, Dyes, Rubber Processing End User: Pharmaceutical Companies, Agricultural Enterprises, Chemical Manufacturers, Textile Industries Technology: Chemical Synthesis, Methanol Catalysis, Gas Phase Reactions, Liquid Phase Reactions |
| Companies Covered | Arkema S.A., Eastman Chemical Company, BASF SE, Zhejiang Jianye Chemical Co., Ltd., Balaji Amines Ltd., Huntsman International LLC, Delamine B.V., Nouryon Chemicals Holding B.V., Dow Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethylamine Market Shifts & Advancements
Catalyst chemistry, regulatory disclosure requirements, and procurement consolidation are simultaneously reshaping how ethylamine is produced, certified, and purchased across pharmaceutical and agrochemical value chains.
Continuous flow microreactor technology is automating temperature and pressure control in ethanol amination reactions. Pharmaceutical CDMOs in India are piloting these systems for on-demand API intermediate production. The technology is automating batch-to-batch variability reduction while compressing qualification timelines for GMP-grade material.
ECHA REACH registration requirements now mandate granular carbon intensity documentation across ethylamine supply chains. European producers must quantify Scope 1-3 emissions for derivative export eligibility. Pharmaceutical formulators in Germany and Switzerland are prioritizing suppliers with verified low-carbon process data.
Long-term offtake contracting is displacing spot market purchases among agrochemical multinationals. Buyers are consolidating supplier panels to three qualified sources with integrated feedstock security. This pattern is most visible in Chinese pesticide manufacturing clusters where Zhejiang-based formulators negotiate multi-year supply agreements.
Ethylamine Market Segmentation
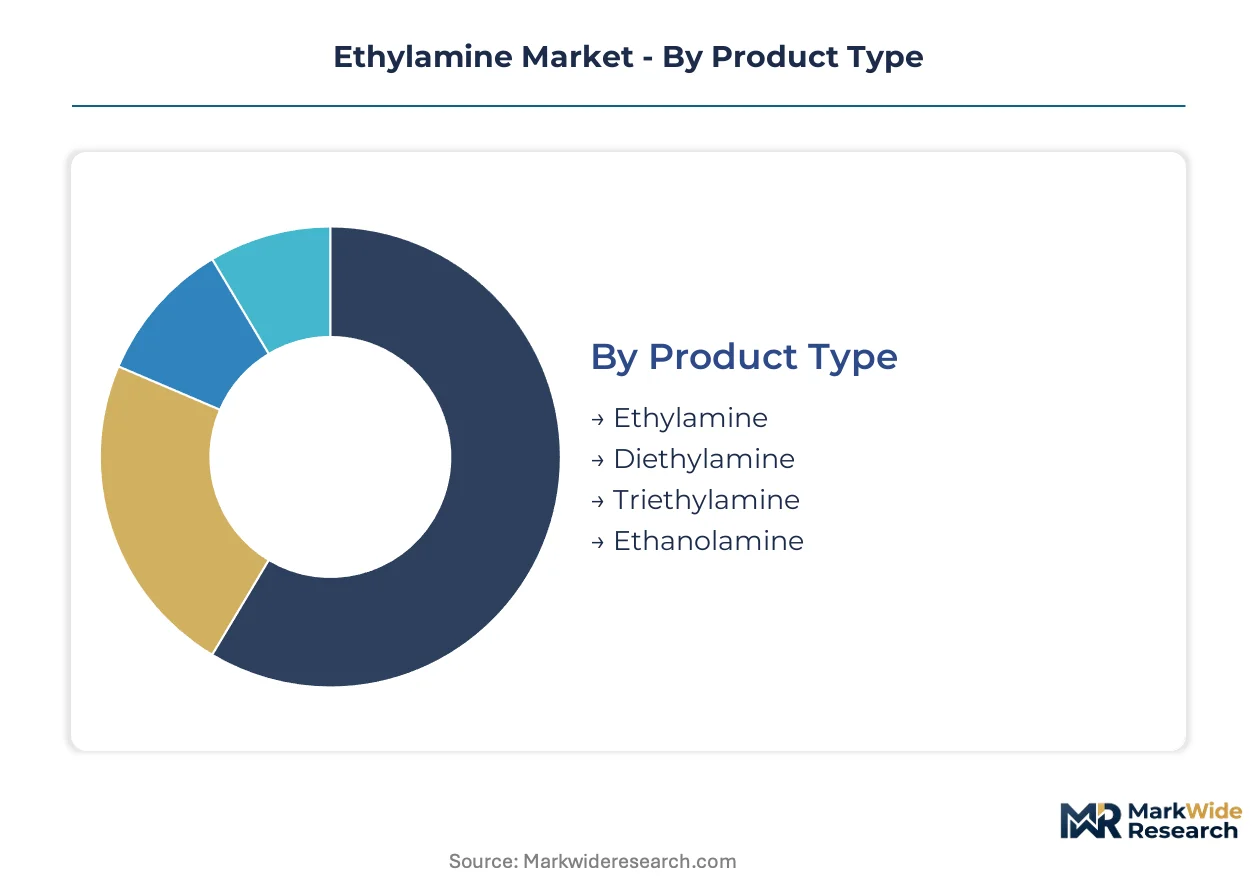
Ethylamine derivatives serve both as standalone commodity chemicals and as embedded intermediates within integrated pharmaceutical and agrochemical manufacturing. Understanding where each segment sits on this integration spectrum reveals margin capture patterns and supplier qualification requirements across value chains.
Product Type:
Integration depth varies sharply across amine grades, with mono- and di-substituted products dominating captive consumption while tri-substituted variants command premium merchant sales.
- Ethylamine:Primary aliphatic amine produced via ethanol amination over copper-chrome or emerging base-metal catalysts. BASF SE and Zhejiang Jianye Chemical consume the majority captively for downstream derivative synthesis, leaving limited merchant spot availability.
- Diethylamine:Secondary amine intermediate with dual use in rubber accelerators and pharmaceutical salt formation. CDMOs in Hyderabad and Shanghai are expanding diethylamine offtake for generic API manufacturing, though supply concentrates among Indian aliphatic amine specialists.
- Triethylamine:Tertiary amine functioning as proton scavenger in antibiotic and antiviral synthesis. Eastman Chemical Company anchors North American supply through Kingsport manufacturing scale.
- Ethanolamine:Hydroxy-functional amine overlapping with ethylene oxide derivatives, serving surfactant and gas treatment applications outside core ethylamine value chains.
Triethylamine leads volumes today; diethylamine is gaining share fastest through CDMO antibiotic expansion.
Application:
Cost tier stratification separates GMP-certified pharmaceutical grades from technical-grade agrochemical and industrial applications.
- Pharmaceuticals:Highest purity specifications with EMA and FDA validation requirements. REACH-registered European suppliers command premium positioning through documented carbon intensity disclosure under EU Green Deal chemical sustainability targets.
- Agrochemicals:Volume-driven technical-grade consumption concentrated in Chinese pesticide manufacturing clusters. Zhejiang-based formulators negotiate multi-year supply agreements with integrated domestic producers.
- Dyes:Intermediate-purity applications for azo and anthraquinone colorant synthesis, primarily serving textile clusters in Gujarat and Jiangsu provinces.
- Rubber Processing:Vulcanization accelerator derivatives for tire manufacturers in Southeast Asia, with demand tied to automotive production cycles in Thailand and Indonesia.
Agrochemicals anchor volume absorption; pharmaceuticals show the steepest expansion trajectory.
End User:
Customer type determines procurement modality, with pharmaceutical companies demanding audit-intensive qualification against agricultural enterprises prioritizing cost and security of supply.
- Pharmaceutical Companies:Multinationals in Basel and Mumbai enforce supplier panel consolidation to three qualified sources with integrated feedstock security and verified low-carbon process data.
- Agricultural Enterprises:Brazilian formulators represent underpenetrated demand relative to Asian supply capacity, with ANVISA registration pathways for imported intermediates still developing.
- Chemical Manufacturers:Merchant distributors and compounders serving fragmented industrial applications with lower barrier-to-entry qualification requirements.
- Textile Industries:Dye intermediate consumers in Surat and Shaoxing operating on spot-market purchasing with minimal technical specification negotiation.
Pharmaceutical companies concentrate value capture; agricultural enterprises are expanding procurement most aggressively.
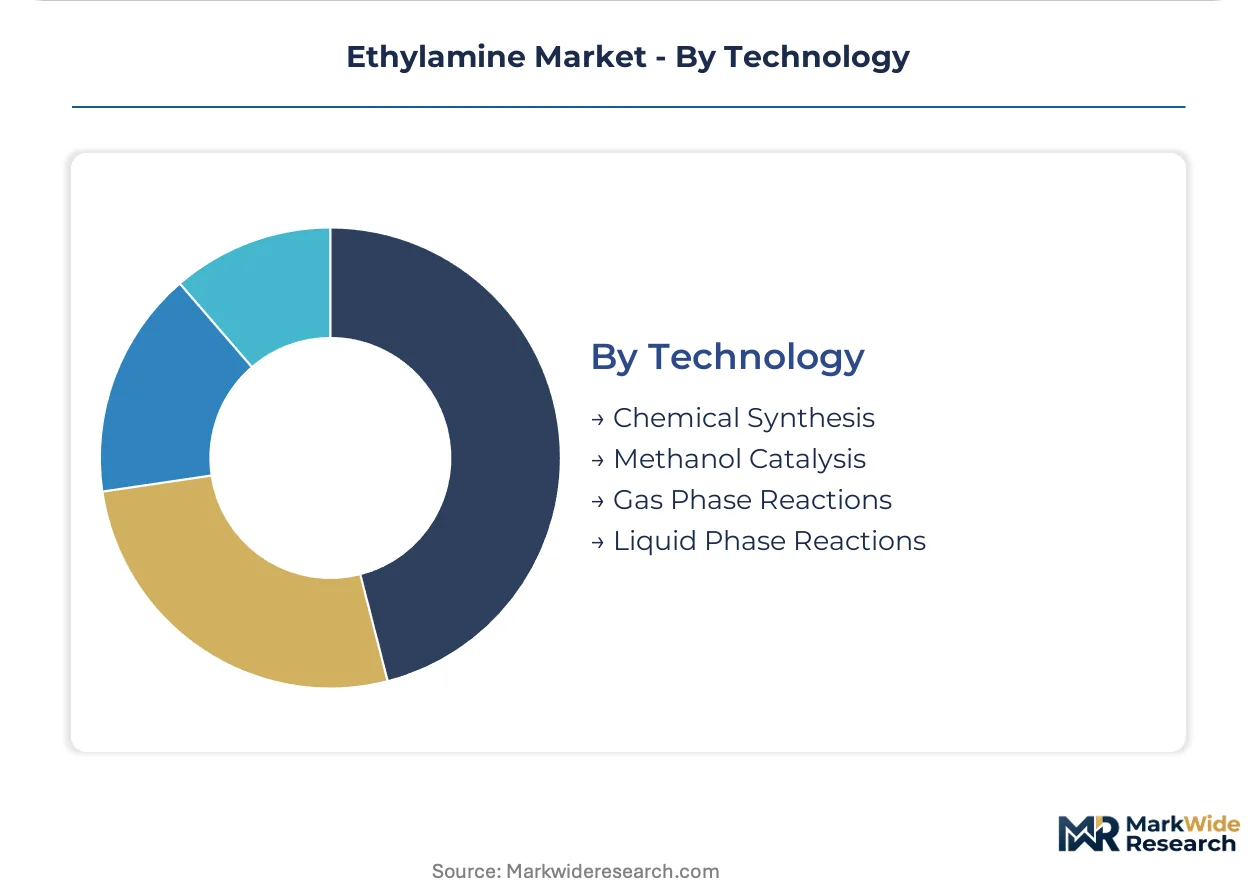
Technology:
Process maturity separates established heterogeneous catalysis from emerging continuous flow systems still undergoing GMP validation.
- Chemical Synthesis:Conventional batch ethanol amination at 150–250°C and 10–30 bar, dominant across legacy installed capacity.
- Methanol Catalysis:Alternative feedstock route bypassing ethanol price volatility, limited to specialized producers with proprietary catalyst intellectual property.
- Gas Phase Reactions:Continuous vapor-phase amination enabling higher throughput and reduced byproduct formation, favored for large-scale integrated sites.
- Liquid Phase Reactions:Lower-temperature processing with improved selectivity control, piloted by Indian CDMOs for on-demand API intermediate production using microreactor technology.
Gas phase reactions dominate installed capacity; liquid phase reactions are climbing the fastest through pharmaceutical microreactor adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ludwigshafen anchors European ethylamine manufacturing through integrated petrochemical infrastructure, while Kingsport sustains North American supply security. Chinese producers in Zhejiang province dominate captive consumption patterns. Indian CDMO clusters in Hyderabad and Mumbai drive pharmaceutical-grade demand expansion.
United States
Eastman Chemical Company's Kingsport facility processes ethanol amination at scale for North American pharmaceutical and agrochemical formulators. EPA oversight under the Toxic Substances Control Act mandates documented carbon intensity for derivative export eligibility. The Tennessee manufacturing corridor supplies proton scavenger volumes to antibiotic CDMOs in the Boston-Cambridge biotech cluster.
Germany
BASF SE leverages its Ludwigshafen Verbund site to sustain margin control across ethylamine and downstream derivative chains. ECHA REACH registration requirements and EU Green Deal chemical sustainability targets force granular Scope 1-3 emissions documentation. The Rhine-Neckar industrial region concentrates Europe's highest-purity pharmaceutical-grade output for Basel-based multinational formulators.
China
Zhejiang Jianye Chemical and domestic agrochemical formulators scale captive consumption through integrated ethanol and ammonia supply chains. MIIT industrial chemical standards and dual carbon goals reshape catalyst technology adoption timelines. The Yangtze River Delta manufacturing belt concentrates rubber accelerator derivative production for Southeast Asian tire manufacturers.
India
Balaji Amines Ltd. dominates domestic volume with specialized aliphatic amine output serving Hyderabad and Mumbai pharmaceutical clusters. CDSCO GMP validation requirements and PLI scheme incentives accelerate generic API manufacturing capacity expansion. The Gujarat chemical corridor absorbs technical-grade volumes for dye intermediate synthesis serving Surat textile processors.
Brazil
ANVISA registration pathways for imported ethylamine intermediates remain underpenetrated relative to Asian supply capacity. Agrochemical formulators in São Paulo state negotiate multi-year supply agreements amid developing regulatory harmonization. The Brazilian agrochemical manufacturing belt represents latent demand for proton scavenger volumes in generic pesticide synthesis.
Ethylamine Market Competitive Landscape
Global majors compete with regional champions across integrated feedstock security and pharmaceutical-grade certification capabilities. The vendor base stratifies into three tiers: petrochemical conglomerates with Verbund site economics, specialized aliphatic amine producers with regional captive markets, and merchant distributors serving fragmented industrial applications. Strategic archetypes include integrated producers controlling ethanol-ammonia supply chains, pharmaceutical-grade specialists with EMA/FDA validation, and emerging Chinese formulators with domestic captive consumption. Competitive moves concentrate on multi-year offtake contracting and catalyst technology retrofit partnerships.
Within the integrated producer tier, BASF SE and Eastman Chemical Company exemplify petrochemical conglomerates leveraging Verbund site economics for margin control across derivative chains. Zhejiang Jianye Chemical Co., Ltd. occupies a position representing Chinese regional champions with captive consumption scale in agrochemical manufacturing clusters. These three entities anchor distinct competitive vectors: European regulatory compliance leadership, North American pharmaceutical supply security, and Asian domestic market integration.
| Leading Market Players |
|---|
| Arkema S.A. |
| Eastman Chemical Company |
| BASF SE |
| Zhejiang Jianye Chemical Co., Ltd. |
| Balaji Amines Ltd. |
| Huntsman International LLC |
| Delamine B.V. |
| Nouryon Chemicals Holding B.V. |
| Dow Chemical Company |
| Others |
Supply & Pricing Matrix
Ethanol futures volatility on the Chicago Board of Trade cascades through ethylamine supply chains into three distinct pricing tiers: pharmaceutical-grade proton scavengers, technical-grade agrochemical intermediates, and commodity rubber accelerator derivatives. Captive producers with backward integration into ethanol and ammonia production capture margin insulation unavailable to merchant market participants.
Pricing Analysis
Input-cost pass-through dominates ethylamine pricing, with corn and sugarcane ethanol benchmarks transmitting directly into amination unit economics. Pricing stratifies across pharmaceutical-grade certification tiers, with EMA-validated material commanding substantial premiums over technical-grade agrochemical supply. Cost compression in non-integrated merchant tiers is intensifying because of Chinese supply concentration and catalyst retrofit capital requirements. Agrochemical formulators in Southeast Asia exhibit highest price sensitivity, while Basel-based pharmaceutical multinationals prioritize carbon intensity documentation over unit cost.
Supply Chain Analysis
Freight cost differentials between bulk liquid tanker and ISO container modalities shape regional procurement patterns for ethylamine derivatives. Supply concentrates in Germany, the United States, and China, with Ludwigshafen, Kingsport, and Zhejiang province anchoring integrated production. Raw material flows draw from corn belt ethanol, ammonia synthesis gas, and specialized heterogeneous catalysts. Single-source vulnerability runs through copper-chrome catalyst supply chains during base-metal transition periods. Distribution runs through long-term offtake contracts rather than spot market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ethylamine market represents a late-cycle quality story, with pharmaceutical CDMOs demanding documented carbon intensity and REACH registration compliance that only integrated producers with verified Scope 1-3 data can satisfy.
For Market Incumbents: Extend catalyst technology retrofit partnerships to compress reactor downtime during copper-chrome to base-metal transitions. Deepen backward integration into ethanol supply through corn processing joint ventures in the US Midwest, defending margin position against Chinese captive consumption scale. Prioritize ECHA carbon intensity documentation investments to qualify for premium European antibiotic supply contracts.
For New Entrants and Emerging Players: Pharmaceutical CDMOs in Hyderabad and Mumbai offer the most penetrable entry channel, with CDSCO GMP validation requirements creating qualification barriers that favor specialized over commodity positioning. Target continuous flow microreactor deployments for on-demand API intermediate production near Indian generic manufacturing clusters. Pursue ANVISA registration pathway partnerships with São Paulo agrochemical formulators as the fastest route to Brazilian market access.
For Investors and Strategic Acquirers: Asymmetric upside sits with Indian aliphatic amine specialists combining CDMO pharmaceutical relationships with PLI scheme incentive capture. Five-to-ten year viability hinges on catalyst technology transition execution and regulatory documentation capabilities. Watch for MIIT industrial chemical standard revisions in China as the inflection signal for accelerated base-metal catalyst adoption timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethanol Supply | BASF's Ludwigshafen model demonstrates margin control through captive corn processing infrastructure. |
| Continuous Flow Microreactor Deployment | Hyderabad CDMO pilots reduce batch-to-batch variability for GMP-grade triethylamine qualification. |
| REACH Carbon Intensity Documentation | ECHA Scope 1-3 disclosure qualifies European suppliers for Basel pharmaceutical procurement panels. |
| Long-term Offtake Contracting | Zhejiang formulators lock multi-year supply security with domestic integrated producers. |
| Base-Metal Catalyst Retrofit Partnership | Environmental toxicity concerns accelerate copper-chrome obsolescence before validation completes. |
Research Methodology
Bottom-up pharmaceutical and agrochemical end-use modeling reconciled against top-down ethanol amination capacity tracking forms the analytical core of this study. Primary interviews with plant managers at integrated amine sites, procurement leads at downstream CDMOs, distribution channel partners in Indian chemical corridors, and technical R&D directors at catalyst suppliers combined with secondary validation from customs/trade data, Cefic chemical industry reports, SEC 10-K filings, and ECHA registration databases. Triangulation between consumption-side demand signals and supply-side production economics ensures cross-verified volume and value estimates.
Historical trendline analysis across ethanol price cycles, catalyst technology adoption curves, and regulatory registration timelines informed projection framework construction. Segmentation dimensions modeled include amine substitution grade, end-use industry vertical, certification tier, and regional production hub configuration. CAGRs were derived through regression-weighted averaging of segment-level growth trajectories. Forecast inputs incorporated CDMO capacity expansion announcements, dual carbon goal implementation schedules, and rubber accelerator derivative demand from Southeast Asian tire manufacturing clusters.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to catalyst technology validation timelines, ethanol feedstock price volatility, and REACH documentation requirement evolution. Forecasts reflect documented assumptions about regulatory implementation pace and CDMO capacity realization rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
4-Tert-Amylphenol Market
Organic Chemicals
Asia-Pacific Organic Acid Market
Organic Chemicals
Benzethonium Chloride Market
Organic Chemicals
Crotonic Acid Market
Organic Chemicals
Methacrylic Acid Market
Organic Chemicals
Europe Organic Acid Market
Organic Chemicals
Organic Rheological Modifiers Market
Organic Chemicals
Chloro -Dimethylsilane (CAS 1066-35-9) Market
Organic Chemicals
North America Phenol Market
Organic Chemicals
Aminophenol Market
Organic Chemicals
Oxo Chemicals Market
Organic Chemicals
Synthetic Camphor Market
Organic Chemicals
Methyl Isobutyl Ketone (MIBK) Market
Organic Chemicals
Triethylene Glycol Market
Organic Chemicals
Aliphatic Amines Market
Organic Chemicals
Cyclopentanone Market