
 Organic Chemicals Market | 2026-2036
Organic Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Chemicals Market Analysis
The EU Green Deal is expanding compliance obligations for petrochemical-derived intermediates across European manufacturing. BASF SE leverages its integrated Verbund site network to sustain cost-advantaged production of specialty organic intermediates. Dow Inc. anchors its position through backward integration into ethylene feedstocks, while SABIC competes on scale from its Saudi Arabian manufacturing base.
Organic chemicals are carbon-based compounds produced through catalytic reforming, steam cracking, or fermentation processes, typically characterized by carbon-hydrogen bonding structures and boiling points that vary by molecular weight and functional group substitution. These substances serve as foundational inputs for polymer synthesis, pharmaceutical active ingredient production, and agrochemical formulation. Solvent demand leads in absolute volume within product-type segmentation, though pharmaceutical-grade categories command superior margin pools due to purity certification requirements. Application-level demand from coatings and personal care segments is shifting toward bio-derived alternatives, creating bifurcated growth trajectories between conventional petrochemical and renewable feedstock pathways.
REACH registration requirements in Europe, EPA Toxic Substances Control Act provisions in the United States, and China's MEE emissions standards collectively shape product formulation standards and market access conditions for cross-border chemical trade. Compliance with multi-jurisdictional purity and labeling mandates now determines supplier eligibility for pharmaceutical and food-grade procurement contracts. Stakeholders must monitor feedstock cost volatility and regulatory divergence between jurisdictions when allocating capital across conventional and bio-based organic chemical production platforms.
Market Dynamics
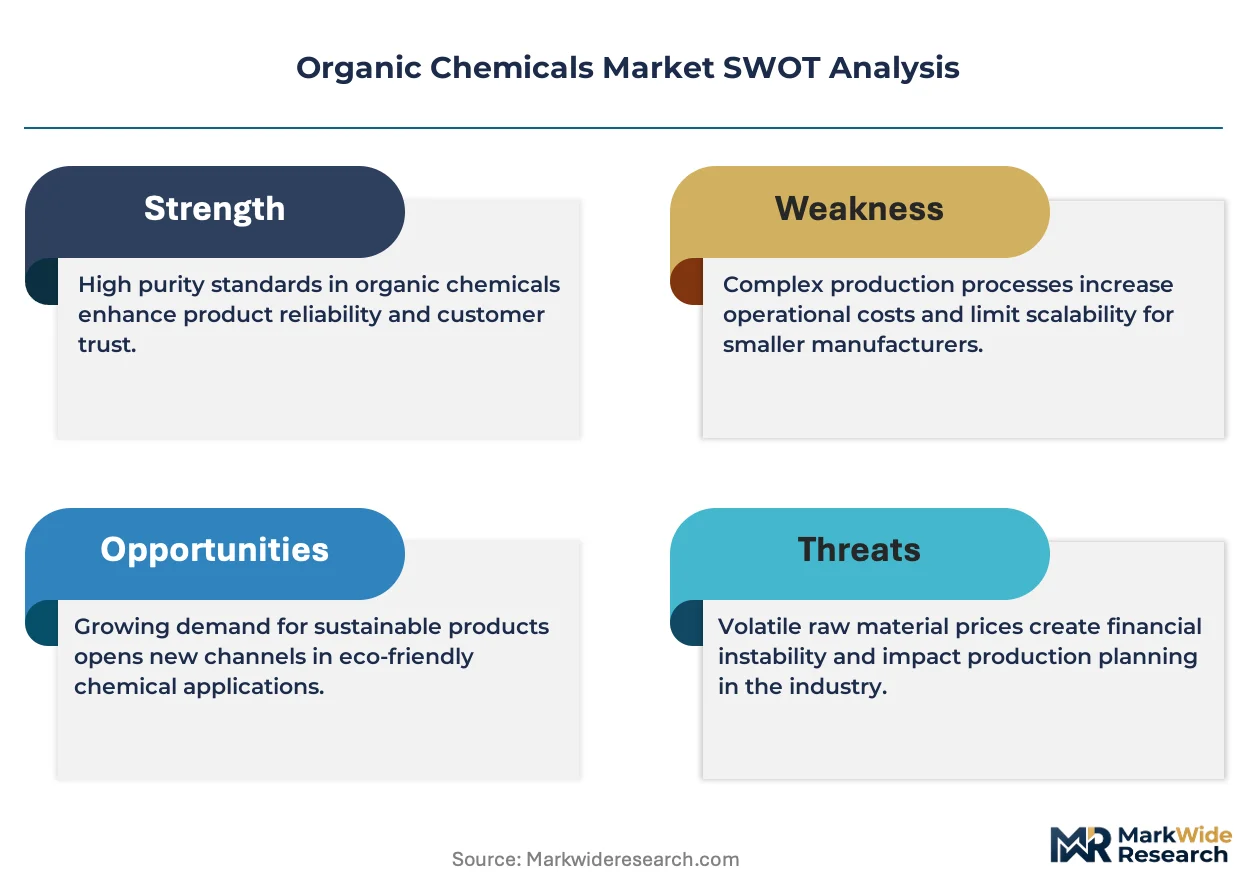
Feedstock cost volatility and regulatory divergence between petrochemical and bio-based pathways are compressing margin structures while forcing capital reallocation across production platforms.
Growth Catalysts
- REACH chemical safety framework:The EU Green Deal tightens purity standards for pharmaceutical-grade solvents, creating premium pricing tiers for compliant European suppliers.
- Asia-Pacific manufacturing clusters:Sinopec and domestic Chinese producers scale capacity for adhesives and surfactants serving regional electronics and automotive supply chains.
- Catalytic reforming efficiency gains:Steam cracking yield improvements in ethylene production lower unit costs for aromatic intermediates used in polymer synthesis.
Market Restraints
- Naphtha price volatility:Crude oil-linked feedstock costs swing unpredictably, eroding margin predictability for European and Asian crackers operating on spot naphtha.
- Saudi Arabian supply concentration:SABIC's scale advantages from low-cost ethane access limit competitive entry for new Middle Eastern capacity.
- Fermentation yield ceilings:Bio-based organic acid production faces technical barriers in titer rates that petrochemical routes bypass economically.
Strategic Opportunities
- India's specialty chemical demand:CDSCO pharmaceutical manufacturing incentives and PLI scheme subsidies attract investment in high-purity solvent production for export markets.
- Carbon capture integration:Fermentation-based organic chemical production couples with carbon utilization technologies to generate negative-emission feedstock credentials.
- Direct-to-formulator digital channels:Specialty chemical distributors bypass traditional merchant networks to serve coatings and personal care compounders with customized batch sizes.
Industry Challenges
- Multi-jurisdictional certification timelines:REACH, EPA TSCA, and China's MEE emissions standards impose overlapping purity and labeling mandates that delay pharmaceutical contract eligibility.
- Skilled process engineering scarcity:Catalytic reforming and biocatalysis expertise concentrates at legacy petrochemical hubs, constraining talent availability for greenfield bio-based facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Chemicals Market |
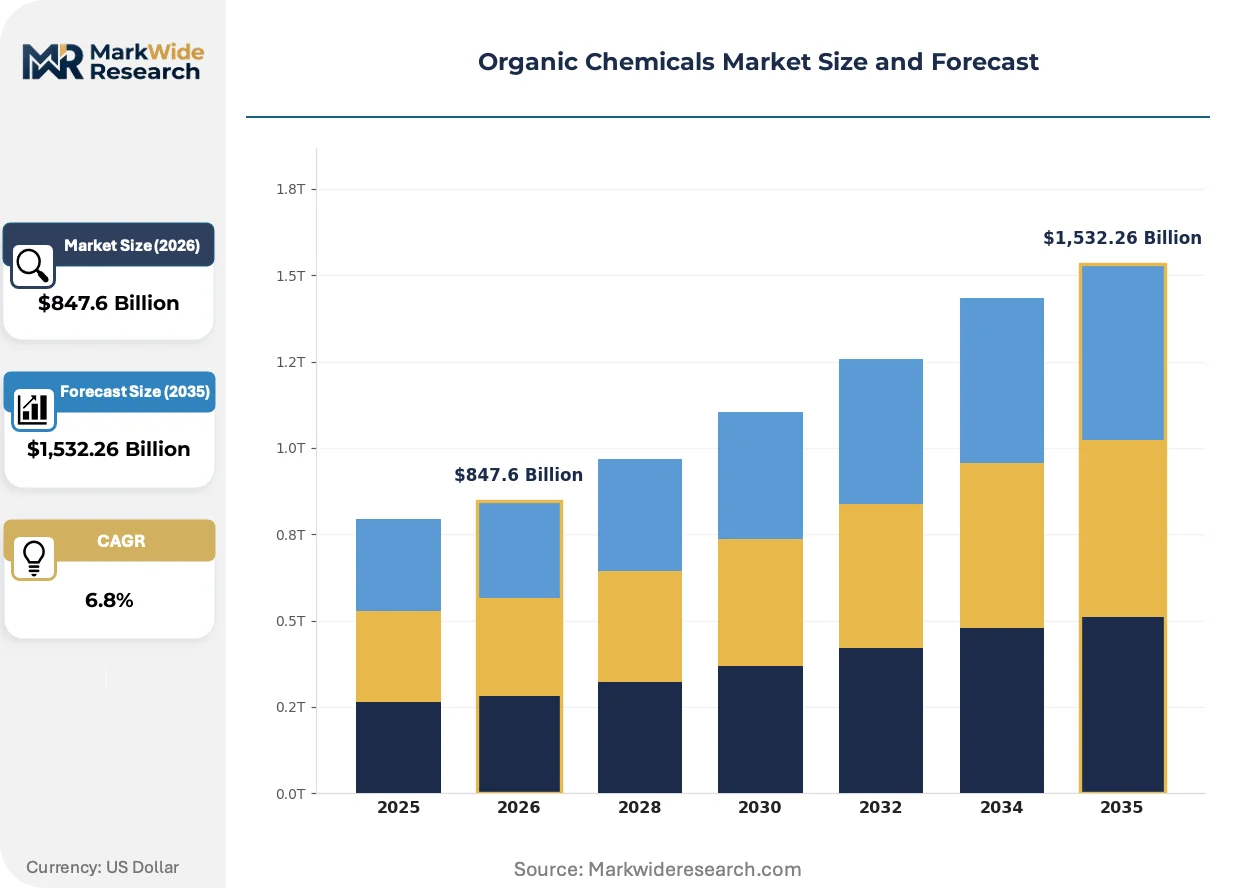
| Market Size in 2026 | $847.6 Billion |
| Market Size in 2035 | $1,532.26 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvents, Adhesives, Surfactants, Dyes Application: Agriculture, Pharmaceuticals, Coatings, Personal Care End User: Chemical Manufacturers, Food Industry, Textile Industry, Construction Grade: Industrial Grade, Food Grade, Pharmaceutical Grade, Cosmetic Grade |
| Companies Covered | BASF SE, Dow Inc., SABIC, Sinopec, Evonik Industries AG, LyondellBasell Industries, Eastman Chemical Company, AkzoNobel, PPG Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Chemicals Market Emerging Trajectories
Production technology, regulatory frameworks, and procurement patterns are simultaneously shifting, creating divergent competitive advantages for integrated petrochemical incumbents versus specialized bio-based entrants.
Biocatalytic processing is decentralizing organic chemical production away from mega-scale crackers. Enzymatic conversion of agricultural feedstocks enables modular manufacturing units with lower capital intensity. Pharmaceutical and personal care formulators in Germany and Switzerland are piloting distributed fermentation systems that bypass traditional merchant supply chains.
REACH registration requirements are tightening substance data obligations for imported intermediates. The EU Green Deal's carbon border adjustment mechanism penalizes high-emission petrochemical imports from non-European sources. Asian exporters to European pharmaceutical and coatings markets are accelerating life-cycle assessment documentation to maintain contract eligibility.
Compounders now specify certified renewable content in procurement tenders rather than accepting conventional petrochemical grades. Coatings manufacturers in the Netherlands and personal care brands in France are unbundling solvent supply contracts to source bio-derived alternatives through direct offtake agreements with fermentation specialists. This bypasses established merchant distributors who lack bio-based product portfolios.
Organic Chemicals Market Segmentation
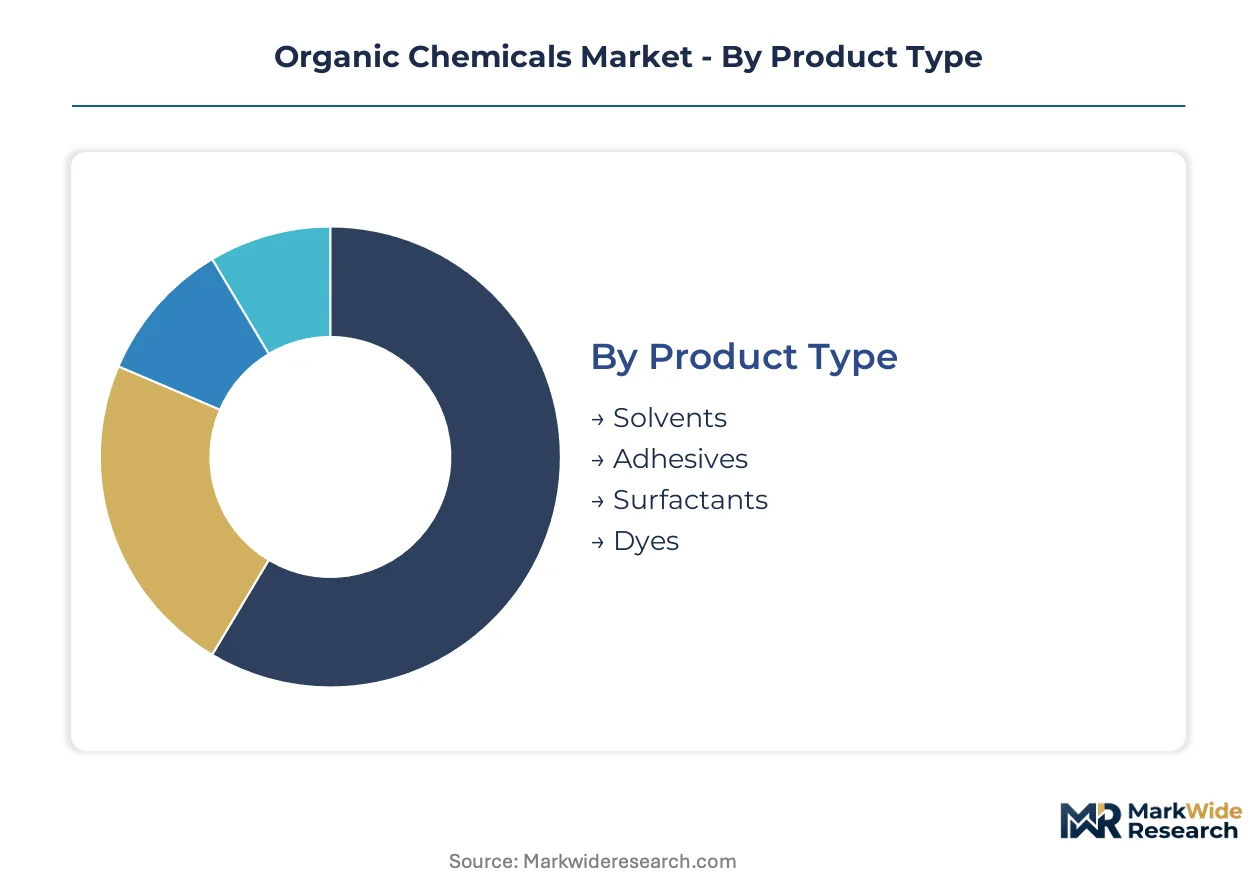
Organic chemicals serve divergent specification requirements across solvents, adhesives, and pharmaceutical intermediates. Segmentation by purity grade and end-use application determines pricing tiers, regulatory compliance burdens, and supplier qualification pathways for chemical manufacturers and formulators.
Product Type:
Product differentiation centers on molecular structure complexity and functional group substitution patterns that dictate solubility, volatility, and adhesion properties.
- Solvents:Carbon-based liquid compounds with controlled evaporation rates dissolve active ingredients in pharmaceutical and coatings formulations. Pharmaceutical-grade solvents command premium pricing in Germany and Switzerland due to REACH purity certification requirements for residual impurity limits.
- Adhesives:Polymerizable organic intermediates bond substrates through covalent cross-linking or physical entanglement mechanisms. Chinese electronics and automotive manufacturing clusters in Guangdong and Jiangsu provinces drive volume concentration for acrylic and epoxy-based adhesive precursors.
- Surfactants:Amphiphilic molecules reduce interfacial tension in cleaning and emulsification applications. Biosurfactant fermentation routes compete with petrochemical ethoxylation for personal care and industrial cleaning supply contracts.
- Dyes:Conjugated aromatic compounds absorb specific light wavelengths for textile and coatings coloration. Environmental discharge regulations in India and Bangladesh constrain azo dye production economics for cotton processing facilities.
Solvents lead on scale; adhesives lead on momentum.
Application:
Application-level demand splits between regulated life-science sectors and volume-driven industrial processing markets with divergent purity specifications.
- Agriculture:Organic chemical inputs formulate herbicides, insecticides, and fungicide actives through chlorinated aromatic and organophosphate intermediates. Brazil's ANVISA and India's Central Insecticides Board impose residue tolerance standards that determine supplier eligibility for agrochemical procurement.
- Pharmaceuticals:High-purity solvents and synthetic intermediates enable active pharmaceutical ingredient synthesis under cGMP conditions. FDA and EMA impurity profiling guidelines mandate dedicated production lines for pharmaceutical-grade categories, excluding cross-contamination risks from industrial chemical manufacturing.
- Coatings:Resin precursors and film-forming additives protect substrates in automotive, architectural, and industrial protective applications. Dutch and French coatings manufacturers specify bio-derived solvent content percentages in sustainability scorecards for supplier selection.
- Personal Care:Emollients, surfactants, and preservatives meet cosmetic safety assessments under EU Cosmetics Regulation and FDA oversight. Korean and Japanese beauty brands drive demand for fermentation-derived alternatives to petrochemical emollients in premium skincare formulations.
Pharmaceuticals lead on margin; personal care leads on specification innovation.
End User:
End-user segmentation reflects supply chain position and regulatory exposure, from commodity chemical processors to finished goods manufacturers with direct consumer contact.
- Chemical Manufacturers:Merchant producers and integrated petrochemical operators convert feedstocks into intermediates for downstream formulation. Sinopec and Saudi Aramco affiliates leverage ethane and naphtha access to supply aromatic and aliphatic building blocks to regional specialty chemical converters.
- Food Industry:Flavoring agents, preservatives, and acidulants require food-grade certification under FSSAI, FDA, and EFSA safety frameworks. Citric acid and acetic acid fermentation dominates natural-origin categories for clean-label positioning in packaged foods.
- Textile Industry:Dye carriers, finishing agents, and fiber processing chemicals face discharge compliance under China's MEE standards and India's CPCB norms. Zero liquid discharge mandates in Tirupur and Surat clusters shift procurement toward biodegradable wet processing aids.
- Construction:Adhesive resins, sealant polymers, and concrete additives provide structural bonding and durability enhancement. UAE and Saudi infrastructure expansion drives solvent-borne adhesive consumption for flooring and panel installation in commercial developments.
Chemical manufacturers lead on volume; food industry leads on certification stringency.
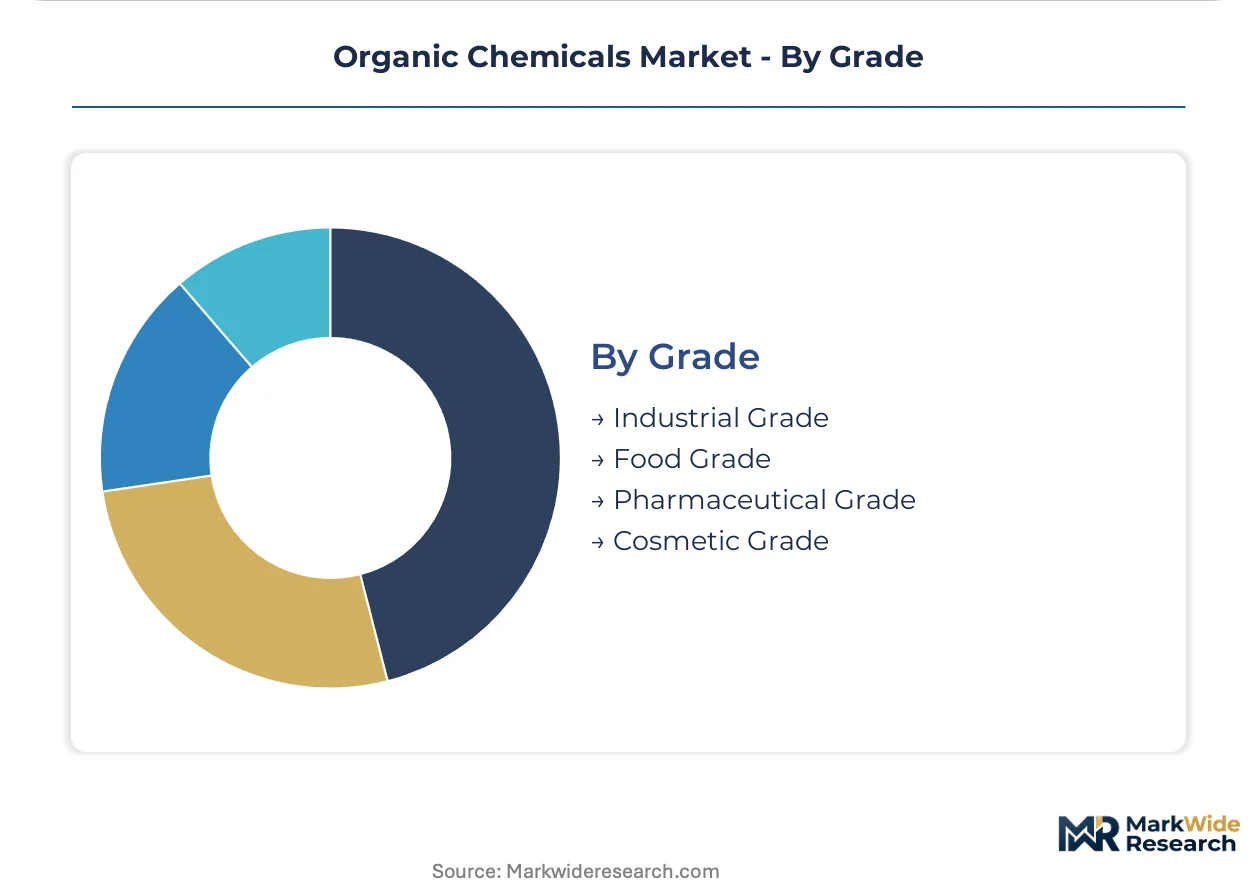
Grade:
Grade stratification creates pricing tiers based on impurity thresholds, documentation requirements, and audit protocols that multiply production costs across certification levels.
- Industrial Grade:Standard purity specifications serve bulk chemical processing with minimal analytical documentation. Commodity solvents and intermediates compete on delivered cost to coatings and adhesive formulators with flexible quality tolerances.
- Food Grade:FSSAI, FDA, and EFSA compliance mandates migration testing and toxicological clearance for direct or indirect food contact. Acetic acid and lactic acid fermentation routes achieve food-grade certification more readily than petrochemical synthesis pathways.
- Pharmaceutical Grade:ICH Q3C residual solvent guidelines and USP-NF monographs define impurity limits for drug substance and drug product manufacturing. Dedicated production equipment and batch release testing multiply unit costs threefold to fivefold above industrial grades.
- Cosmetic Grade:EU Cosmetics Regulation and FDA cosmetic safety requirements govern heavy metal limits and microbial specifications for topical application. Korean MFDS and Swissmedic standards add supplemental testing for premium skincare ingredient exports.
Industrial grade leads on volume; pharmaceutical grade leads on value capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ruhr Valley birthed industrial organic chemistry in the late 19th century, establishing the synthetic dye and pharmaceutical intermediate complexes that later spread to the United States and Asia. That historical foundation now shapes divergent regional trajectories as regulatory stringency, feedstock access, and manufacturing scale create distinct competitive environments across major producing nations.
China
Adhesive and surfactant demand from electronics and automotive supply chains drives capacity expansion. MEE emissions standards tighten discharge limits for chemical processors in coastal provinces. Sinopec scales aromatics production in the Yangtze River Delta to serve Jiangsu and Zhejiang manufacturing clusters.
United States
Shale-derived ethane feedstock advantages sustain cost-competitive olefin production for derivative organic chemicals. EPA Toxic Substances Control Act provisions impose pre-market notification burdens on novel intermediate introductions. Gulf Coast petrochemical corridors in Texas and Louisiana concentrate steam cracker and derivative capacity.
Germany
Pharmaceutical-grade solvent demand from domestic API manufacturers commands premium pricing tiers. REACH registration requirements and EU Green Deal carbon border adjustments constrain import competition from high-emission sources. BASF's Ludwigshafen Verbund site anchors integrated production of specialty intermediates for European formulators.
Saudi Arabia
Low-cost ethane access from associated gas production underpins scale advantages in basic organic chemical output. SFDA pharmaceutical manufacturing standards create compliance pathways for solvent exports to regulated markets. Jubail Industrial City concentrates SABIC's derivative chemical complexes serving Asian and European offtakers.
India
CDSCO pharmaceutical manufacturing incentives and PLI scheme subsidies attract investment in high-purity solvent production for export markets. FSSAI food-grade certification requirements differentiate fermentation-derived acid production for clean-label positioning. Gujarat and Maharashtra chemical clusters expand specialty intermediate capacity for agrochemical and pharmaceutical formulators.
Organic Chemicals Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification-grade stratification, with pharmaceutical-grade specialists capturing threefold to fivefold unit cost multiples over industrial-grade merchants. The vendor base concentrates around integrated petrochemical majors with backward feedstock control, mid-cap specialty distributors with formulation expertise, and emerging fermentation-based challengers with renewable credentials. Three archetypes dominate: scale-driven integrated producers, purity-certified pharmaceutical specialists, and bio-based modular operators. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with carbon capture integration and direct-to-formulator digital channels emerging as differentiation vectors.
Among Germany-based integrated producers, BASF SE and Evonik Industries AG exemplify the premium-tier archetype through Verbund site networks and pharmaceutical-grade certification depth. Dow Inc. represents scale-driven North American positioning with Gulf Coast feedstock integration. SABIC anchors Middle Eastern cost-advantaged production from Saudi Arabian manufacturing bases. Sinopec occupies the state-backed scale position serving Asia-Pacific demand concentration. These five entities collectively span the geographic and strategic spectrum, illustrating how feedstock access, regulatory compliance depth, and regional demand proximity determine competitive positioning without requiring uniform capability profiles.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| SABIC |
| Sinopec |
| Evonik Industries AG |
| LyondellBasell Industries |
| Eastman Chemical Company |
| AkzoNobel |
| PPG Industries |
| Others |
Supply Flow & Price Mechanics
Pharmaceutical formulators in Germany and Switzerland demanding REACH-certified pharmaceutical-grade solvents force merchant suppliers to maintain dedicated production lines and batch-specific documentation, compressing margins on compliant grades while widening price spreads against industrial alternatives.
Pricing Analysis
Three-tier pricing structure across pharmaceutical, food, and industrial grades anchors the market. Certification depth under EU REACH and FDA ICH Q3C guidelines separates premium tiers from commodity offerings, with dedicated equipment requirements multiplying unit costs. Cost compression in industrial solvents intensifies as Chinese merchant exporters scale aromatics capacity. Coatings compounders exhibit highest price sensitivity, while API manufacturers accept premium positioning for impurity-controlled inputs.
Supply Chain Analysis
Direct-to-formulator digital channels bypass traditional merchant distributors for specialty batch sizes. Feedstock access concentrates in Saudi Arabia, China, and the United States, with ethane-advantaged Middle Eastern producers and shale-backed Gulf Coast operators anchoring global supply. Naphtha, ethane, and bio-based agricultural feedstocks constitute primary input dependencies. Single-source vulnerability runs through SABIC's Saudi Arabian manufacturing base for basic aromatic intermediates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Organic chemicals function as a stable compounder, with pharmaceutical-grade certification requirements creating durable margin premiums that resist cyclical feedstock volatility.
For Market Incumbents: Acquire fermentation-based production assets to counter bio-based entrants displacing petrochemical solvents in personal care procurement tenders. Deepen backward integration into ethylene feedstocks through Gulf Coast cracker investments, defending against naphtha price volatility eroding European and Asian margin structures. For New Entrants and Emerging Players: Small-batch pharmaceutical formulators in India and Southeast Asia present underserved demand for customized high-purity solvents with localized regulatory documentation. Target CDSCO-compliant production for export-oriented API manufacturers in Gujarat and Maharashtra clusters, leveraging PLI scheme subsidies to offset dedicated equipment capital requirements. For Investors and Strategic Acquirers: Asymmetric upside sits with pharmaceutical-grade certification specialists possessing established FDA and EMA audit histories. Long-term viability centers on impurity-control capabilities that sustain pricing power across feedstock cycles. Monitor EU Green Deal carbon border adjustment implementation as inflection indicator for bio-based feedstock competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive ethylene supply from Gulf Coast crackers insulates Dow from naphtha volatility. |
| Green Manufacturing Transition | Fermentation-based organic acid production generates negative-emission credentials for EU pharmaceutical tenders. |
| Capacity Expansion | Sinopec's Yangtze River Delta aromatics buildout serves Jiangsu electronics adhesive demand. |
| Long-term Supply Agreement | Direct offtake contracts with Dutch coatings manufacturers bypass distributor margins for bio-derived solvents. |
| Joint Venture | Carbon capture partnerships with fermentation operators create differentiated feedstock positioning for REACH compliance. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged plant managers at steam cracking facilities, procurement leads at pharmaceutical API manufacturers, distribution channel partners serving coatings formulators, and technical R&D directors evaluating biocatalytic conversion pathways. Secondary validation drew from customs trade data, Cefic sector reports, SEC 10-K filings, and EPA TSCA substance inventories. Bottom-up capacity modeling and top-down demand estimation were cross-referenced for triangulation.
Segment-weighting approaches applied differential growth assumptions across grade tiers, end-use industries, and regional production hubs throughout the forecast period. CAGRs were derived from feedstock cost trajectory modeling and regulatory compliance cost escalation curves. Capacity utilization rates at naphtha crackers and fermentation titer improvement timelines served as industry-specific forecast inputs.
Inputs from customs databases and regulatory filing repositories were available through the study window; gaps in proprietary fermentation yield data introduce uncertainty bands around bio-based production cost projections. Forecasts reflect assumptions regarding REACH implementation timelines and MEE enforcement intensity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
N-Hexanol Market
Organic Chemicals
Absolute Ethanol Market
Organic Chemicals
Para-Tert-Octylphenol (POTP) Market
Organic Chemicals
Global Biphenyl Market
Organic Chemicals
Aliphatic Amines Market
Organic Chemicals
North America Phenol Market
Organic Chemicals
Asia-Pacific Synthetic Camphor Market
Organic Chemicals
Acetaldehyde Market
Organic Chemicals
Dimethylformamide (DMF) Market
Organic Chemicals
High Purity Metal Organics Market
Organic Chemicals
N-Hexyl Chloride Market
Organic Chemicals
Pentachlorophenol Market
Organic Chemicals
Methacrylic Acid Market
Organic Chemicals
Chlorocyclopentane Market
Organic Chemicals
Organic Hydrosols Market
Organic Chemicals
Cyclic Ketones Market