
 Dimethyl Carbonate Market | 2026-2036
Dimethyl Carbonate Market Size, Share, and Industry Trends Forecast 2026-2036
Dimethyl Carbonate Market Analysis
Specialty chemical distribution networks serving battery electrolyte manufacturers is tilting toward direct procurement partnerships with Chinese and South Korean producers. UBE Corporation leverages its integrated caprolactam-DMC production complex in Japan to sustain cost advantages across Asian supply chains. Shandong Hualu Hengsheng Group Co. anchors domestic Chinese demand through coal-based syngas integration, while LOTTE Chemical Corporation competes via petrochemical feedstock flexibility at its Yeosu complex.
Dimethyl carbonate is a colorless, flammable ester with formula C₃H₆O₃, manufactured primarily through transesterification of propylene glycol or direct synthesis from carbon dioxide and methanol, and functions as a methylating agent, polar aprotic solvent, and fuel oxygenate. The solvent product type dominates volume throughput due to paint and coating sector offtake, though intermediate-grade material for polycarbonate synthesis captures disproportionate margin pools. Automotive applications lead absolute consumption as DMC replaces methyl tert-butyl ether in fuel formulations, while electronics applications for lithium battery electrolytes represent the fastest-expanding demand segment.
EPA fuel additive standards and REACH chemical registration requirements in Europe shape product purity specifications and market access conditions for non-compliant producers. China's MEE enforces emissions controls on methanol carbonylation plants, while Japan's METI promotes carbon dioxide utilization technologies including direct DMC synthesis routes. Stakeholders must monitor regulatory divergence between jurisdictions on renewable content thresholds and carbon intensity accounting methods to align capacity investments with evolving compliance obligations.
Market Dynamics
The dimethyl carbonate market restructures around feedstock arbitrage between methanol carbonylation and propylene glycol transesterification routes, with carbon dioxide direct synthesis emerging as the pivotal technology differentiator for capital allocation decisions.
Growth Catalysts
- REACH solvent substitution mandates:European formulators face phased restrictions on N-methyl-2-pyrrolidone and other aprotic solvents, redirecting coatings sector procurement toward DMC-based systems.
- Lithium battery electrolyte expansion:Cell manufacturers in South Korea and Japan specify high-purity DMC for electrolyte salt dissolution, creating dedicated demand streams separate from industrial solvent offtake.
- Coal-to-chemicals integration:Chinese producers exploit syngas economics to capture margin from integrated methanol-DMC complexes serving domestic polycarbonate intermediates demand.
Market Restraints
- Methanol price volatility:Natural gas and coal feedstock swings transmit directly to DMC variable costs, compressing margins for non-integrated merchant producers.
- Shandong-Jiangsu supply corridor concentration:Over half of Chinese nameplate capacity clusters in two coastal provinces, exposing buyers to regional logistics disruptions and concentrated environmental enforcement actions.
- Ethylene carbonate substitution:Battery electrolyte formulators increasingly blend ethylene carbonate with DMC, creating formulation flexibility that caps DMC pricing power in premium grades.
Strategic Opportunities
- India specialty chemicals import substitution:Domestic pharmaceutical and agrochemical manufacturers currently rely on Chinese DMC imports, creating white space for local carbonylation investments under PLI scheme incentives.
- Carbon dioxide utilization mandates:Japan's METI funding for direct synthesis R&D accelerates technology maturation, potentially unlocking stranded carbon streams as competitive feedstock.
- Direct-to-electrolyte distribution:Bypassing traditional chemical distributor networks, producers are establishing dedicated supply contracts with battery material specialists, capturing margin from disintermediation.
Industry Challenges
- Battery-grade purification certification:Achieving sub-10 ppm chloride and moisture specifications for electrolyte applications requires capital-intensive distillation and adsorption trains, extending qualification timelines with cell manufacturers.
- Process safety engineering scarcity:Methanol carbonylation plants handling carbon monoxide and dimethyl ether intermediates demand specialized hazard analysis expertise that outstrips current talent pipelines in emerging production geographies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dimethyl Carbonate Market |
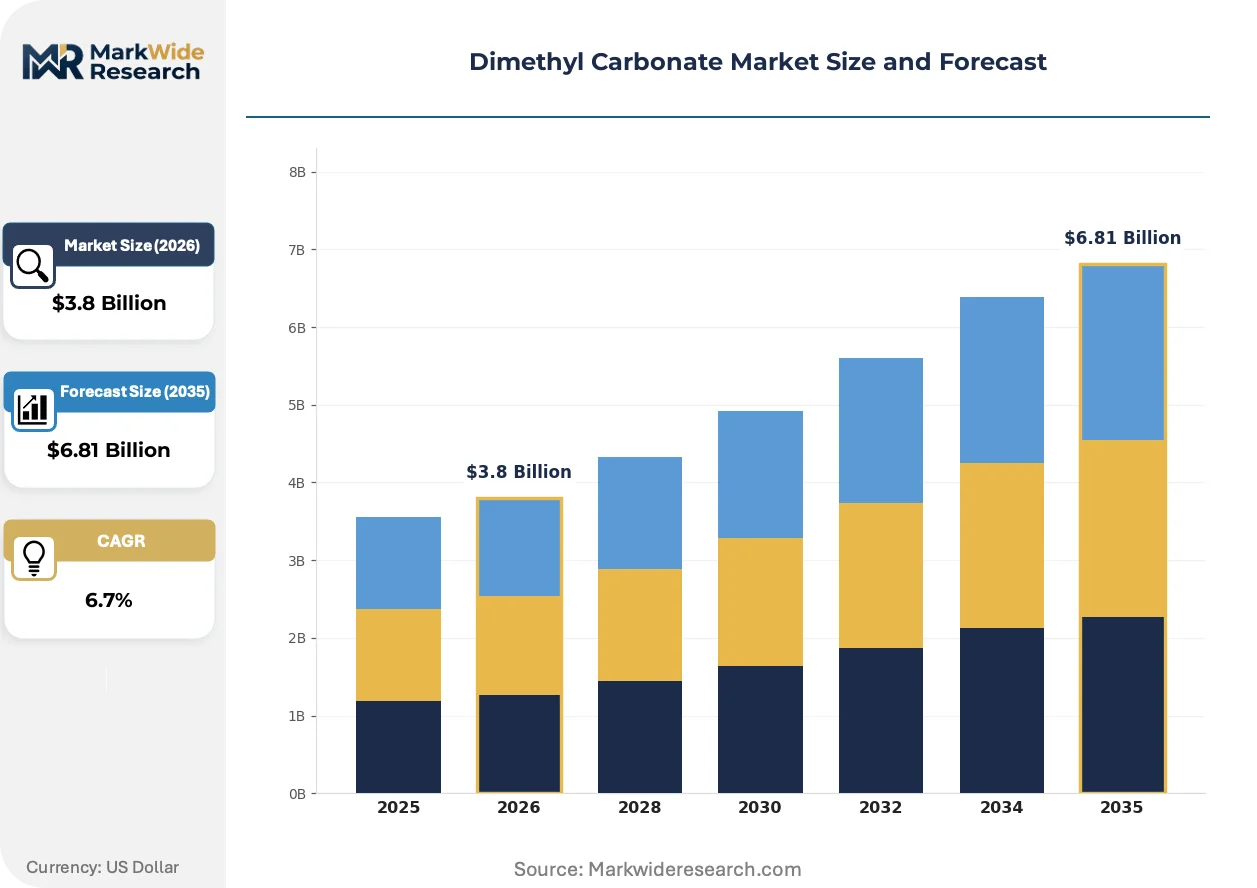
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent, Intermediate, Octanol, Coating Application: Automotive, Electronics, Cosmetics, Pharmaceuticals End User: Manufacturers, Distributors, Retailers, Exporters Distribution Channel: Online, Direct Sales, Wholesale, Retail |
| Companies Covered | UBE Corporation, LOTTE Chemical Corporation, Shandong Hualu Hengsheng Group Co., Shinghwa Advanced Material Group Co., Ltd., Hi-tech Spring, Merck KGaA, Haike Chemical Group, Shandong Shida Shenghua Chemical Group Co., Ltd., Sankyo Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dimethyl Carbonate Market Emerging Trajectories
Carbon dioxide direct synthesis routes and electrolyte-grade purification advances dominate technical investment, while regulatory pressure on solvent emissions accelerates substitution timelines in established industrial applications.
Heterogeneous catalysis for CO₂-methanol direct coupling is collapsing the capital intensity gap with conventional phosgene-free routes. Japanese and South Korean research consortia pilot continuous-flow reactors at demonstration scale. This technology compression threatens the cost advantage of legacy propylene glycol transesterification assets within the decade.
EPA fuel oxygenate waivers and California Air Resources Board low-carbon fuel standards tighten specifications for oxygenate blending components. Refiners face reformulation costs that favor DMC over ethanol in certain gasoline pools. The regulatory pressure concentrates in US Western states where seasonal volatility requirements intersect with carbon intensity scoring.
Electrolyte manufacturers consolidate supplier bases from multi-source spot purchasing toward single-source annual contracts with purity guarantees. South Korean cathode material specialists lead this consolidation, replacing regional distributors with direct mill-to-plant logistics. The procurement compression squeezes trading house margins and rewards integrated producers with captive carbon dioxide or methanol supply.
Dimethyl Carbonate Market Segmentation
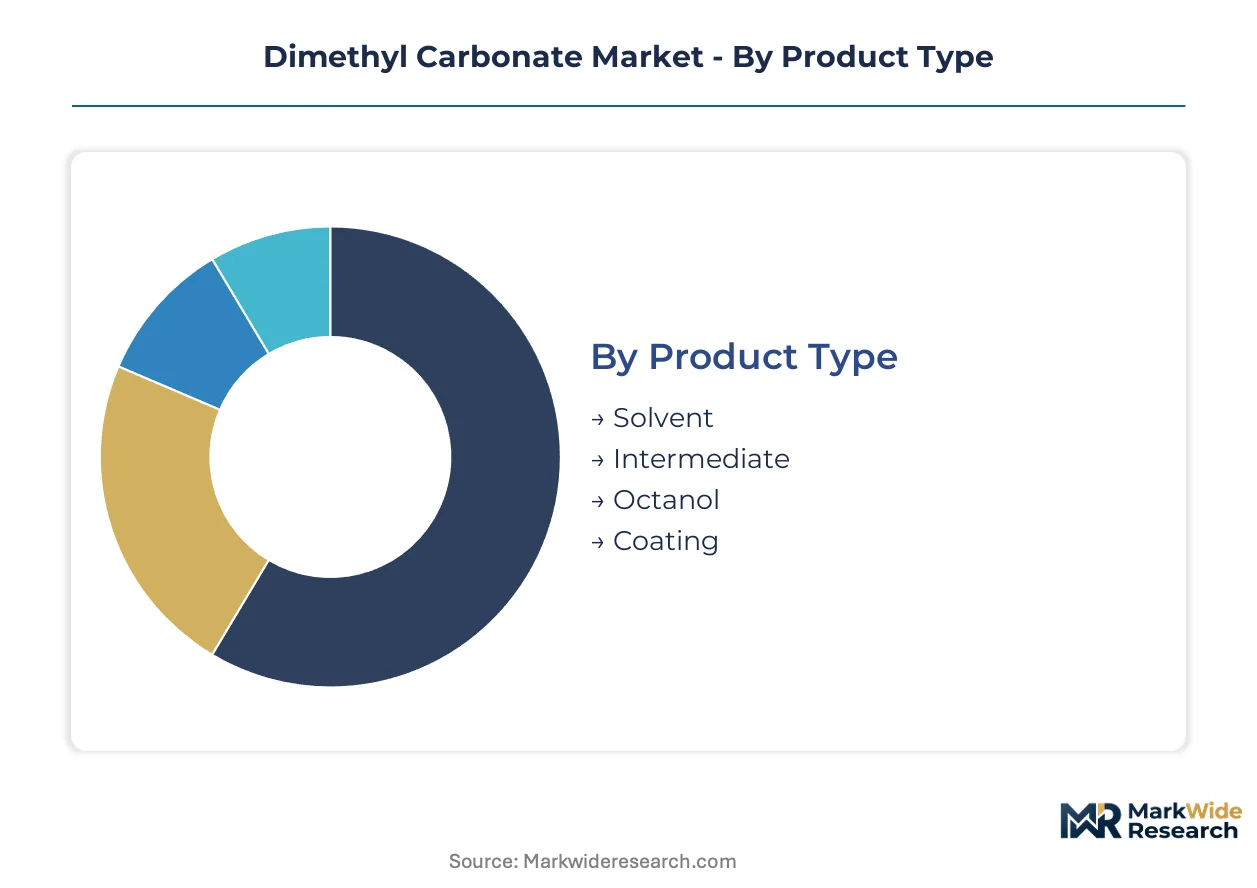
Segmentation in dimethyl carbonate markets tracks how purity grades, application specifications, and channel structures fragment pricing power. Buyers in battery electrolyte and pharmaceutical applications impose certification requirements that create tiered margin pools distinct from commodity solvent offtake.
Product Type:
After-sales service intensity varies sharply across product grades, with battery-grade material demanding technical support for impurity troubleshooting while industrial solvent sales require minimal post-delivery engagement.
- Solvent:Industrial-grade material serves paint stripping, coating formulations, and cleaning applications where polarity and low toxicity substitute for N-methyl-2-pyrrolidone. Demand concentrates in European coatings sector procurement responding to REACH substitution mandates for hazardous aprotic solvents.
- Intermediate:Polycarbonate synthesis feedstock requires precise ester specifications for melt transesterification with bisphenol A. Chinese coal-to-chemicals complexes in Shandong and Jiangsu provinces anchor demand through integrated methanol-DMC production economics.
- Octanol:Fuel oxygenate blending component competes with ethanol in reformulated gasoline pools, particularly where seasonal volatility requirements intersect with carbon intensity scoring in US Western states.
- Coating:Specialty formulations for electronics and automotive finishes leverage DMC's fast evaporation profile and low surface tension characteristics.
Solvent holds the largest share; momentum sits with Intermediate.
Application:
Cost tier differentiation separates premium-certified electrolyte grades from industrial commodity offtake, with purification investments creating threefold margin spreads between highest and lowest specification tiers.
- Automotive:Fuel oxygenate applications lead absolute consumption volume as refiners replace methyl tert-butyl ether in reformulated gasoline. EPA waivers and California Air Resources Board standards tighten oxygenate specifications favoring DMC in certain blend pools.
- Electronics:Lithium battery electrolyte formulations represent the steepest expansion trajectory, with South Korean and Japanese cell manufacturers specifying sub-10 ppm chloride and moisture grades for lithium hexafluorophosphate dissolution.
- Cosmetics:Personal care solvent applications exploit DMC's favorable toxicological profile for nail polish removers and skin care formulations, though volume remains constrained by higher cost relative to conventional solvents.
- Pharmaceuticals:Green methylation agent applications substitute for dimethyl sulfate and methyl halides in active pharmaceutical ingredient synthesis, with EMA and FDA impurity guidelines driving adoption.
Automotive commands current volume leadership; electronics gains share fastest.
End User:
Customer type determines contract structure, with manufacturers negotiating annual volume commitments while distributors absorb inventory risk for smaller accounts.
- Manufacturers:Integrated chemical producers and downstream formulators procure directly for captive consumption or captive resale, with battery material specialists consolidating toward single-source annual contracts with purity guarantees.
- Distributors:Regional chemical traders manage logistics for mid-sized coatings and pharmaceutical accounts, though margins compress as producers establish direct mill-to-plant electrolyte supply chains.
- Retailers:Specialty chemical resellers serve small-volume cosmetics and laboratory end-users with packaged quantities.
- Exporters:Trading houses arbitrage price differentials between Chinese production clusters and import-dependent markets in India and Southeast Asia.
Manufacturers dominate procurement volume; direct channel expansion displaces distributor intermediation.
Distribution Channel:
Supply concentration in coastal Chinese provinces shapes logistics economics, with bulk tanker shipments from Shandong-Jiangsu corridor determining landed costs for distant markets.
- Online:Digital procurement platforms aggregate small-lot buyers for standardized industrial grades, though battery and pharmaceutical specifications require offline technical qualification.
- Direct Sales:Producer-to-manufacturer contracts capture margin from disintermediation, with UBE Corporation and LOTTE Chemical leveraging integrated supply positions for electrolyte and polycarbonate intermediate offtake.
- Wholesale:Bulk tank and drum distribution serves regional coatings and fuel blending terminals, with inventory positioning critical to seasonal demand fluctuations.
- Retail:Packaged quantities for laboratory and small-scale industrial users carry highest per-unit pricing but minimal absolute contribution.
Direct sales expands fastest; wholesale retains volume dominance in industrial applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ningbo-Zhoushan Port complex handles bulk methanol feedstock arrivals that sustain the Shandong-Jiangsu chemical corridor, anchoring Asia-Pacific supply logistics. Rotterdam's liquid bulk terminals distribute DMC cargoes across Northwest European coatings clusters. Houston Ship Channel terminals serve US Gulf Coast fuel oxygenate blenders.
China
Coal-to-chemicals complexes in Shandong and Jiangsu provinces consume intermediate-grade DMC for polycarbonate synthesis. MEE emissions controls on methanol carbonylation plants tighten operating permits for coastal facilities. The Yangtze River Delta concentration faces restructuring pressure as environmental enforcement intensifies in Taizhou and Ningbo chemical parks.
Japan
UBE Corporation's integrated caprolactam-DMC complex at Chiba supplies battery electrolyte manufacturers in South Korea and domestic electronics clusters. METI carbon dioxide utilization funding accelerates direct synthesis pilot programs at Kansai research consortia. The Chubu region hosts demonstration-scale continuous-flow reactors testing heterogeneous catalysis routes.
South Korea
LOTTE Chemical's Yeosu complex leverages petrochemical feedstock flexibility for DMC production serving domestic cathode material specialists. MFDS pharmaceutical impurity guidelines drive adoption of green methylation agents in API synthesis. The Busan-Ulsan industrial belt concentrates electrolyte-grade demand from LG Energy Solution and Samsung SDI supply chains.
Germany
REACH solvent substitution mandates redirect coatings sector procurement from N-methyl-2-pyrrolidone toward DMC-based formulations. ECHA authorization requirements tighten hazardous substance controls on legacy aprotic solvents. The North Rhine-Westphalia chemical triangle hosts formulation R&D for automotive and industrial coating applications.
United States
EPA fuel oxygenate waivers favor DMC over ethanol in Western state reformulated gasoline pools. California Air Resources Board low-carbon fuel standards tighten oxygenate specifications for seasonal volatility requirements. Gulf Coast refiners at Houston and Beaumont terminals blend DMC into gasoline pools serving Western US distribution.
Dimethyl Carbonate Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream, supplying purified grades to battery and pharmaceutical formulators. The market structures around three tiers: integrated petrochemical conglomerates with captive feedstock, coal-chemicals specialists exploiting syngas economics, and merchant producers exposed to methanol price volatility. Dominant competitive moves include direct-to-electrolyte distribution partnerships and carbon dioxide utilization technology licensing.
Among Japanese and South Korean integrated producers, UBE Corporation and LOTTE Chemical Corporation represent platform-tier positioning with petrochemical complex integration. Shandong Hualu Hengsheng Group Co. exemplifies the coal-chemicals archetype with domestic syngas feedstock capture. Merck KGaA occupies a specialty-grade position serving pharmaceutical and electronics purity requirements. These three archetypes—integrated petrochemical, coal-chemicals, and specialty-grade merchant—define competitive positioning as procurement consolidates toward direct manufacturer contracts.
| Leading Market Players |
|---|
| UBE Corporation |
| LOTTE Chemical Corporation |
| Shandong Hualu Hengsheng Group Co. |
| Shinghwa Advanced Material Group Co., Ltd. |
| Hi-tech Spring |
| Merck KGaA |
| Haike Chemical Group |
| Shandong Shida Shenghua Chemical Group Co., Ltd. |
| Sankyo Chemical Corporation |
| Others |
Supply Flow & Price Mechanics
Methanol feedstock volatility transmits directly to DMC variable costs, compressing margins for non-integrated merchant producers while simultaneously widening spreads between battery-grade and industrial solvent tiers. This cost pressure concentrates pricing power among coal-chemicals complexes in Shandong and petrochemical integrators in Japan and South Korea.
Pricing Analysis
Volume-discount tiering structures separate electrolyte-grade premiums from industrial solvent spot pricing. Three-tier pricing stratifies across battery-certified, intermediate polycarbonate-feedstock, and commodity solvent levels. Cost compression in industrial grades intensifies because Chinese coal-to-chemicals complexes flood regional spot markets with undifferentiated material. Battery manufacturers exhibit least price sensitivity due to purity certification lock-in, while paint formulators face acute margin pressure from REACH-driven solvent substitution mandates.
Supply Chain Analysis
Export-control regimes on heterogeneous catalysis technology limit direct synthesis know-how transfer from Japanese and South Korean research consortia to emerging producers. Supply concentrates in China, Japan, and South Korea, with methanol carbonylation and propylene glycol transesterification routes drawing from coal syngas, natural gas, and petrochemical naphtha feedstocks. Single-source vulnerability runs through the Shandong-Jiangsu corridor where environmental enforcement actions disrupt coastal logistics. Distribution runs through direct mill-to-plant contracts for electrolyte grades and bulk tanker shipments for industrial solvent offtake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized process safety engineering for methanol carbonylation plants handling carbon monoxide intermediates represents the critical capability gap constraining capacity expansion in emerging production geographies.
For Market Incumbents: Build certification moats around battery-grade chloride and moisture specifications below 10 ppm. Deepen upstream control over methanol supply through coal-syngas integration or natural gas offtake agreements. Invest in continuous-flow reactor pilot programs to preempt CO₂ direct synthesis technology shifts threatening legacy propylene glycol transesterification assets. For New Entrants and Emerging Players: Establish a beachhead in India's pharmaceutical and agrochemical methylation agent demand currently served by Chinese imports. Target domestic carbonylation investments under PLI scheme incentives to capture import substitution margins. Lead with green methylation agent positioning to differentiate from dimethyl sulfate and methyl halide incumbents in API synthesis. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors integrated producers with captive carbon dioxide or methanol supply. Long-term viability hinges on direct synthesis route maturation and electrolyte-grade purification capabilities. Watch for METI funding disbursement velocity as inflection indicator for CO₂ utilization technology commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methanol Supply | Coal-syngas complexes in Shandong capture margin from integrated feedstock economics. |
| Electrolyte-Grade Purification Investment | Sub-10 ppm chloride specifications unlock single-source annual contracts with South Korean cathode material specialists. |
| Direct Synthesis Technology Licensing | Japanese METI-funded continuous-flow reactor pilots threaten legacy transesterification cost structures. |
| Direct-to-Electrolyte Distribution Partnership | Producer-to-manufacturer contracts displace trading house margins in battery material supply chains. |
| Green Methylation Agent Positioning | EMA and FDA impurity guidelines accelerate substitution of dimethyl sulfate in pharmaceutical synthesis. |
Methodological Framework
Operator-level perspectives from methanol carbonylation plant managers, battery electrolyte procurement leads at cathode material specialists, polycarbonate synthesis engineers, and specialty chemical distribution channel partners anchored the qualitative base. Secondary validation drew from MEE emissions enforcement records, METI carbon dioxide utilization funding disclosures, SEC filings from integrated petrochemical conglomerates, and REACH authorization timelines. Bottom-up capacity assessments triangulated against top-down demand modeling across solvent, intermediate, and fuel oxygenate applications.
Scenario-bracketing framed analytical sensitivity to methanol price volatility bands and regulatory enforcement intensity variations across the projection horizon. Segmentation dimensions modeled included product grade tier, end-use industry vertical, and regional production hub concentration. CAGRs derived from capacity expansion announcements, environmental permit issuance rates, and electrolyte demand trajectories from South Korean and Japanese cell manufacturers. Industry-specific inputs incorporated coal-to-chemicals economics and heterogeneous catalysis technology maturation curves.
Sensitivities concentrate around MEE enforcement actions disrupting Shandong-Jiangsu corridor operations and METI direct synthesis commercialization timelines. Forecasts reflect documented assumptions on methanol feedstock cost trajectories and REACH substitution mandate implementation schedules. Material shifts in carbon dioxide utilization technology economics or battery electrolyte formulation standards would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Global Ketones Market
Organic Chemicals
Dioxolane Market
Organic Chemicals
Asia-Pacific Organic Acid Market
Organic Chemicals
Humic Acid Market
Organic Chemicals
2,5-Dimethyl-2,4-Hexadiene Market
Organic Chemicals
Synthetic Camphor Market
Organic Chemicals
North America Cycloalkanes Market
Organic Chemicals
Organic Coating Market
Organic Chemicals
Long-Chain Dicarboxylic Acid Market
Organic Chemicals
Global Metal-Organic Framework Market
Organic Chemicals
Dioctyl Phthalate Market
Organic Chemicals
Global Benzoic Acid Market
Organic Chemicals
Absolute Ethanol Market
Organic Chemicals
Para-Tert-Octylphenol (POTP) Market
Organic Chemicals
1,3-Dioxolane Market
Organic Chemicals
Isophthalic Acid Market