
 Acetic Acid Market | 2026-2036
Acetic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Acetic Acid Market Analysis
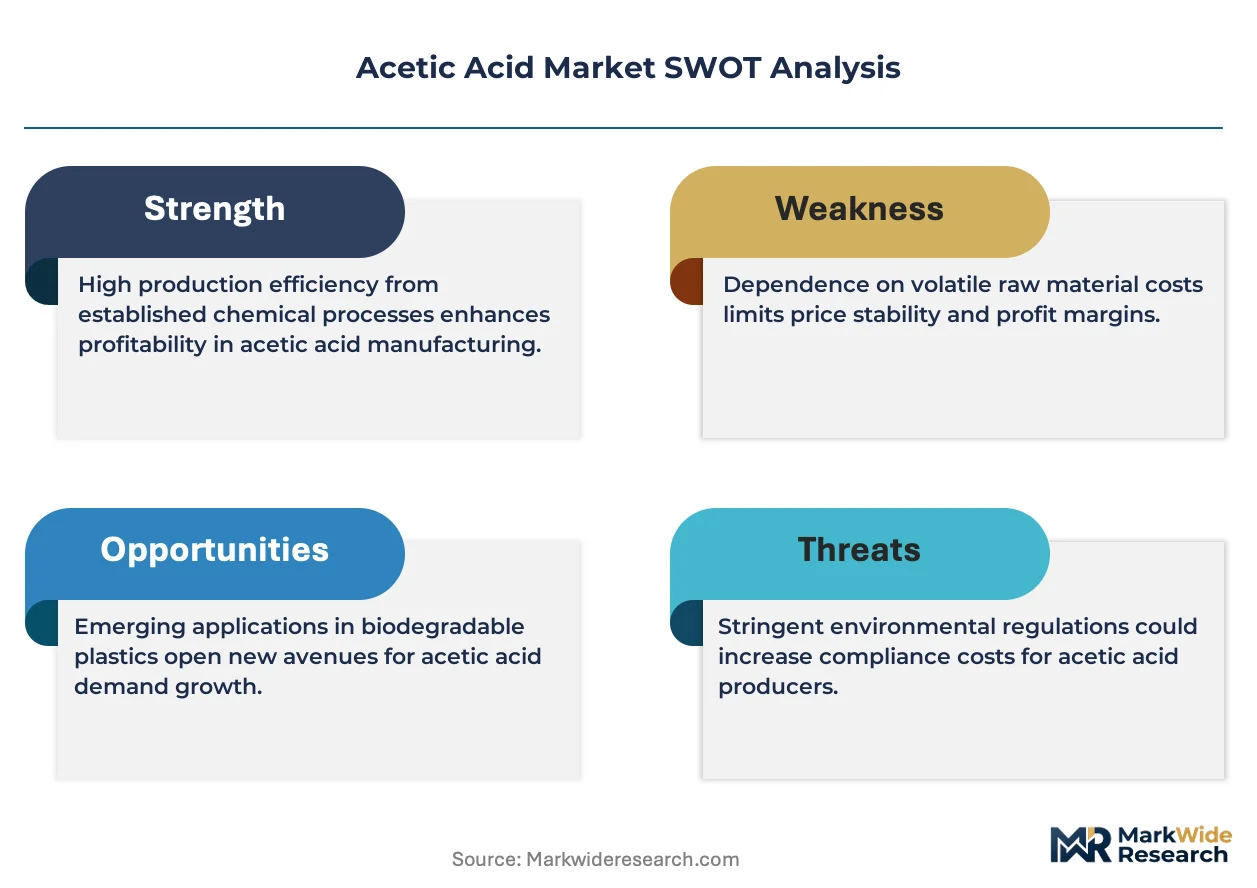
REACH compliance in Europe is hardening the cost-of-entry calculus for acetic acid suppliers seeking industrial-grade market access. Celanese Corporation leverages its integrated methanol-to-acetic acid chain to sustain margin resilience across European and North American supply corridors. Eastman Chemical Company anchors its position through specialized acetyl chemistry expertise that competes on specification consistency rather than volume alone.
Acetic acid is a carboxylic acid with the formula CH₃COOH, typically manufactured via methanol carbonylation or acetaldehyde oxidation, with glacial grades containing at least 99.5% purity for polymer and pharmaceutical synthesis. Its primary commercial purpose centers on vinyl acetate monomer production, acetate ester formulation, and purified terephthalic acid intermediation for polyester manufacturing. Industrial grade dominates volume throughput for chemical intermediates, while food grade commands premium positioning in additive applications where FSSAI and FDA purity thresholds apply. Vinyl acetate monomer absorbs the largest application share, though pharmaceutical-grade demand is expanding fastest as CDSCO and EMA tighten excipient documentation requirements.
EPA standards in the United States, REACH registration in Europe, and GB standards under China's SAMR collectively shape product specifications, emission limits, and cross-border market access for acetic acid producers. These frameworks force continuous purification upgrades and traceability investments that favor integrated manufacturers with captive analytical capabilities. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance fragmentation threatens to partition supply chains into region-specific qualification tiers that complicate global sourcing strategies.
Market Dynamics
PTA manufacturing capacity expansion in China is absorbing acetic acid volumes faster than alternative applications, compressing spot availability and forcing European buyers into longer-term contract structures to secure industrial-grade supply.
Growth Catalysts
- Vinyl Acetate Monomer Expansion:Adhesives and coatings producers in construction and packaging sectors are scaling VAM offtake, pulling acetic acid demand upward through dedicated offtake agreements with integrated methanol carbonylation facilities.
- REACH Compliance Thresholds:ECHA registration requirements for industrial-grade purity are filtering out non-compliant suppliers, concentrating volume among manufacturers with captive analytical and purification capabilities.
- Polyester Manufacturing Clustering:PTA intermediate demand for polyester fiber and resin production is concentrating acetic acid consumption in coastal Chinese chemical parks with dedicated pipeline infrastructure.
Market Restraints
- Methanol Feedstock Volatility:Natural gas and coal pricing swings directly transmit to acetic acid production economics, squeezing margin predictability for non-integrated producers lacking captive methanol supply.
- Supply Concentration Risk:Chinese state-owned enterprises and integrated Western majors control disproportionate global carbonylation capacity, limiting spot market liquidity and buyer negotiating leverage.
- Acetic Anhydride Substitution:Pharmaceutical and cellulose acetate applications in select European formulations are shifting toward alternative acetylating agents where process chemistry permits.
Strategic Opportunities
- Indian Pharmaceutical Excipient Grade:CDSCO documentation requirements for acetic acid in drug formulations are tightening faster than domestic supply qualification, creating import substitution potential for certified producers.
- Carbon Capture Integration:Carbonylation process CO₂ utilization is converging with emissions reduction mandates under EU Green Deal and China's dual carbon goals, enabling low-carbon acetic acid certification premiums.
- Direct-to-Formulator Distribution:Bypassing traditional chemical distributor networks through digital platforms is opening channel access for mid-scale producers to specialty adhesives and coatings compounders.
Industry Challenges
- Analytical Chemist Scarcity:Trace impurity detection and REACH-compliant documentation require specialized chromatography expertise that competes with pharmaceutical and food safety sectors for limited talent pools.
- Legacy Carbonylation Retrofit Costs:Rhodium catalyst recovery systems and corrosion-resistant reactor upgrades demand capital deployment that stretches beyond depreciation schedules for aging European assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acetic Acid Market |
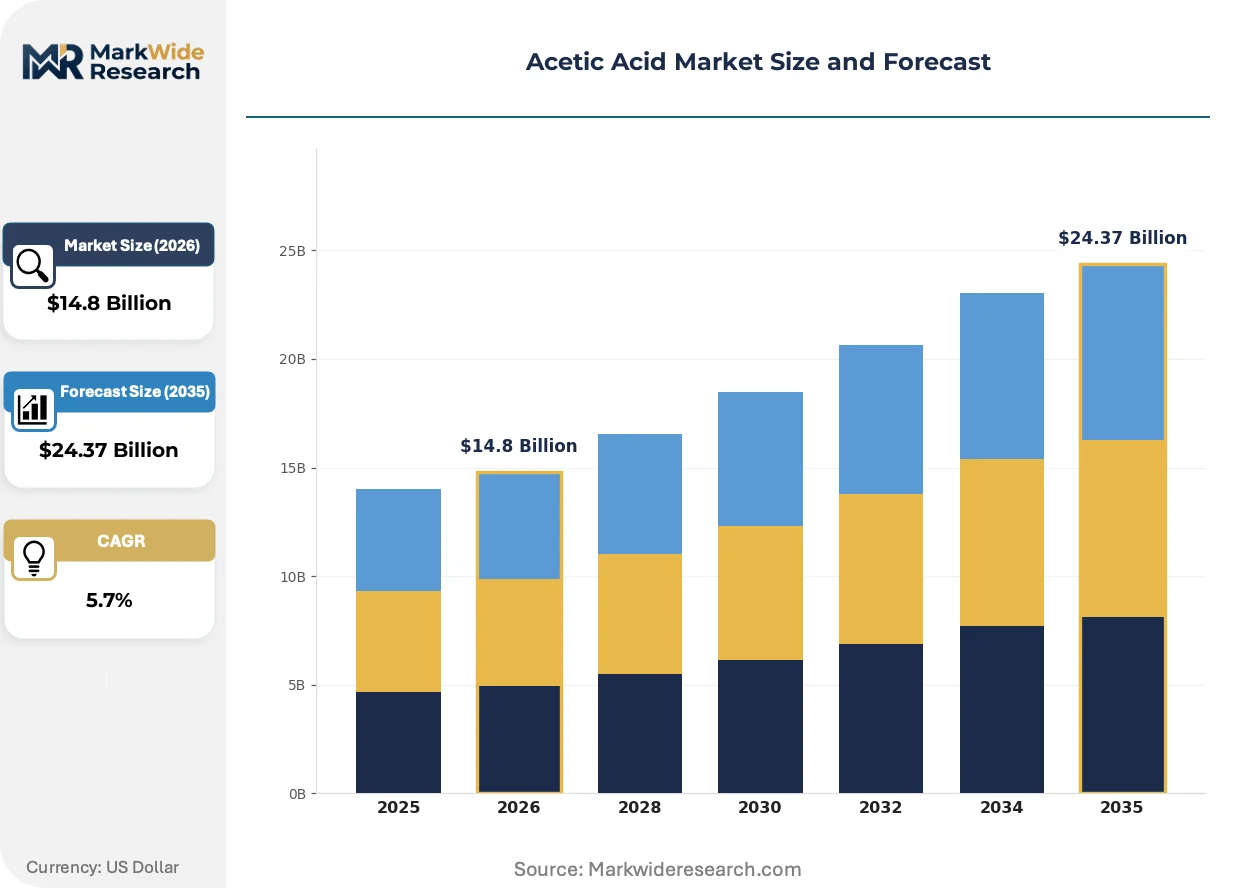
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glacial Acetic Acid, Dilute Acetic Acid, Food Grade, Industrial Grade, Reagent Grade Application: Vinyl Acetate Monomer, Acetate Esters, Purified Terephthalic Acid, Food & Beverage Additives, Pharmaceuticals End User Industry: Textile Processing, Adhesives Manufacturing, Chemical Intermediates, Personal Care Products Packaging Type: Drums, Bulk Tankers, ISO Containers, Flexible Intermediate Bulk Containers |
| Companies Covered | Celanese Corporation, Eastman Chemical Company, LyondellBasell Industries, INEOS, SABIC, Mitsubishi Chemical Group Corporation, Daicel Corporation, BASF SE, Shanghai Huayi (Group) Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acetic Acid Market Emerging Trajectories
Bio-based acetic acid production routes and digital supply chain traceability are compressing the qualification timeline between laboratory certification and commercial offtake, reshaping how buyers validate supplier compliance.
Biomass gasification-to-acetic acid pathways are decentralizing feedstock dependence away from fossil methanol. European specialty chemical buyers are piloting bio-based certification in cosmetics and food additive applications. This technology is decentralizing supply risk by enabling regional production from agricultural residue streams rather than centralized petrochemical complexes.
EPA hazard communication standards under TSCA Section 8 are tightening documentation requirements for industrial-grade acetic acid shipments into US manufacturing facilities. Chemical processors must now maintain granular batch-level impurity profiles. Food-grade and pharmaceutical-grade segments are responding by segregating production lines to prevent cross-contamination liability exposure.
Specification-driven procurement is consolidating buyer power among large PTA and VAM producers who mandate supplier audits beyond standard ISO certification. Distributor relationships are thinning as direct contracts with carbonylation operators offer volume discounts and priority allocation. This concentration is most visible in Chinese coastal chemical parks where integrated polyester producers have absorbed traditional spot market liquidity.
Acetic Acid Market Segmentation
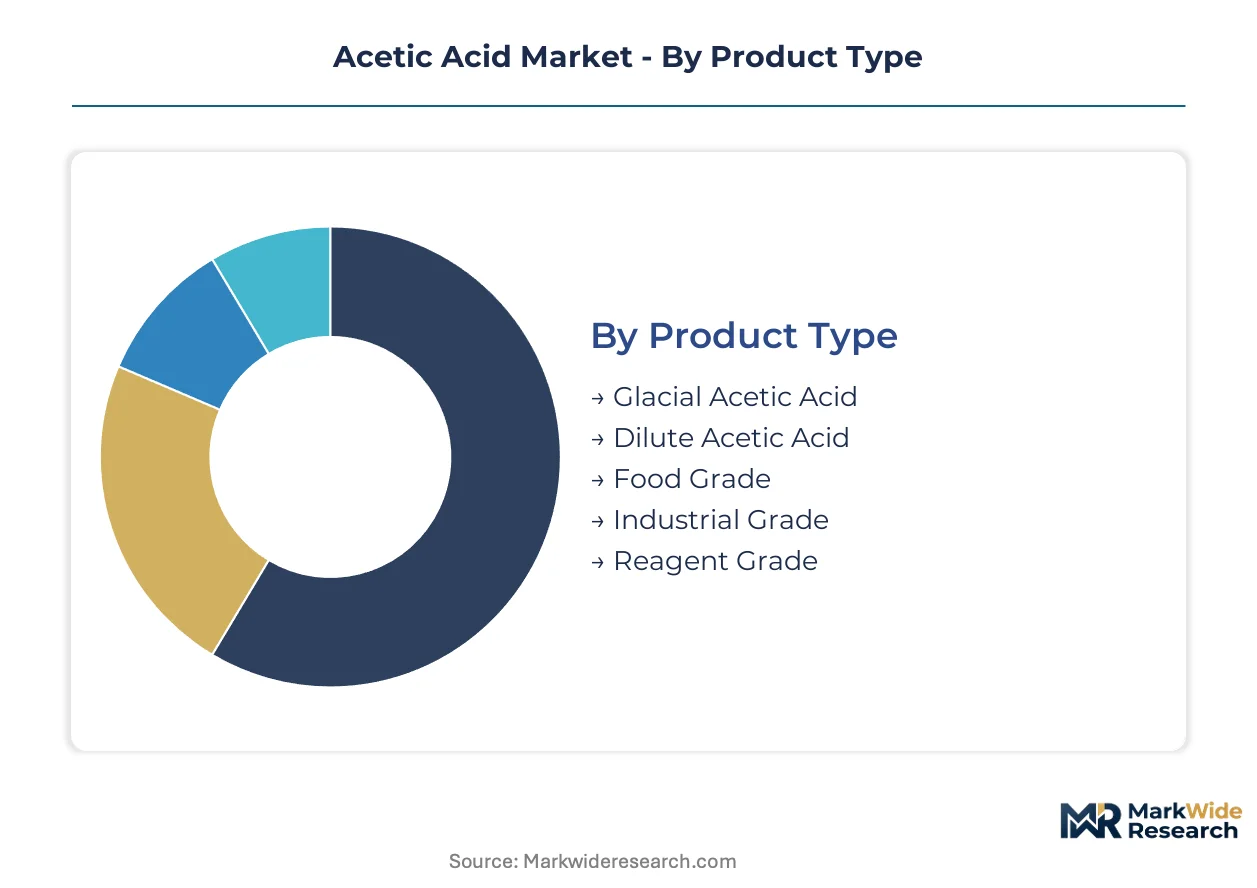
Acetic acid procurement patterns diverge sharply across purity grades and end-use specifications, with vinyl acetate monomer producers and pharmaceutical formulators demanding incompatible certification standards. Understanding these segment boundaries clarifies why integrated producers maintain separate production trains and why distributor relationships fragment by customer technical requirements.
Product Type:
Buyers in this category separate by contamination tolerance and documentation burden rather than unit price sensitivity alone.
- Glacial Acetic Acid:Concentrated form containing 99.5% minimum purity with freezing point near 16.6°C, essential for polymerization reactions where moisture disrupts catalyst systems. Demand concentrates in vinyl acetate monomer facilities along the US Gulf Coast and Chinese coastal chemical parks, where PTA producers absorb volumes through dedicated pipeline connections. Specifications here are tightening under EPA TSCA Section 8 documentation mandates.
- Industrial Grade:Standard commercial purity ranging 80-99% acetic acid content, serving chemical intermediate manufacturing where downstream purification steps tolerate higher water or trace metal loads. Textile processors in Gujarat and Shandong provinces dominate offtake, though REACH registration costs are filtering smaller European compounders out of supplier qualification pools.
- Food Grade:Meets FSSAI and FDA purity thresholds for direct food contact, with heavy metal and sulfide limits below 1 ppm. Acetic acid in this tier commands documentation trails from fermentation or carbonylation source through final packaging.
- Reagent Grade:Ultra-high purity for analytical and laboratory applications, with specifications traceable to ACS or ISO 6353 standards. Pharmaceutical QC labs and research institutions in Basel and Boston metro areas drive specialized demand.
- Dilute Acetic Acid:Pre-blended aqueous solutions reducing handling hazards for small-scale food processors and cleaning compound manufacturers. Convenience positioning limits this segment to regional distribution networks with blending capabilities.
Volume sits with Industrial Grade; growth tilts toward Reagent Grade.
Application:
Application selection here tracks the downstream industry's capital intensity and specification stringency.
- Vinyl Acetate Monomer:Dominant chemical transformation consuming acetic acid through ethylene or acetylene addition reactions, yielding monomers for adhesives, coatings, and textile sizing. Construction sector recovery in Germany and packaging film expansion across Southeast Asia are pulling carbonylation capacity toward dedicated offtake contracts rather than spot sales.
- Purified Terephthalic Acid:Intermediate for polyester resin and fiber production, where acetic acid serves as solvent and oxidation medium in paraxylene conversion. Chinese state-owned enterprises have integrated this consumption into coastal chemical parks with pipeline-linked acetic acid supply, compressing merchant market availability.
- Acetate Esters:Solvent applications in coatings, inks, and cosmetics formulations, with ethyl and butyl acetate dominating volume. European decorative paint producers are shifting toward bio-based ester certifications under EU Green Deal procurement guidelines.
- Pharmaceuticals:Excipient and active pharmaceutical intermediate uses, where CDSCO and EMA documentation requirements for impurity profiling are tightening faster than supply qualification. This application is expanding most quickly as generic drug manufacturing concentrates in India and Eastern Europe.
- Food & Beverage Additives:Acidulant and preservative functions in condiments, pickles, and processed foods, with FSSAI-mandated purity certificates required for import into Indian food processing facilities.
Volume concentrates in Vinyl Acetate Monomer; margins peak in Pharmaceuticals.
End User Industry:
End user selection correlates with batch size requirements and technical service intensity.
- Chemical Intermediates:Bulk consumers integrating acetic acid into acetic anhydride, chloroacetic acid, and other transformation products. Producers in Ludwigshafen and Nanjing maintain backward integration into captive carbonylation or methanol supply to hedge feedstock volatility.
- Adhesives Manufacturing:Polyvinyl acetate and ethylene-vinyl acetate formulators serving construction and packaging sectors. Mid-scale compounders in Milan and São Paulo metro areas are bypassing distributors through direct platform procurement.
- Textile Processing:Sizing, dyeing, and finishing operations consuming dilute grades, with clustered demand in Tamil Nadu and Jiangsu provinces where polyester weaving capacity concentrates.
- Personal Care Products:Cosmetic-grade acetic acid for pH adjustment and preservative systems, requiring allergen and heavy metal documentation beyond standard industrial certifications.
Volume flows to Chemical Intermediates; service intensity peaks in Personal Care Products.
Packaging Type:
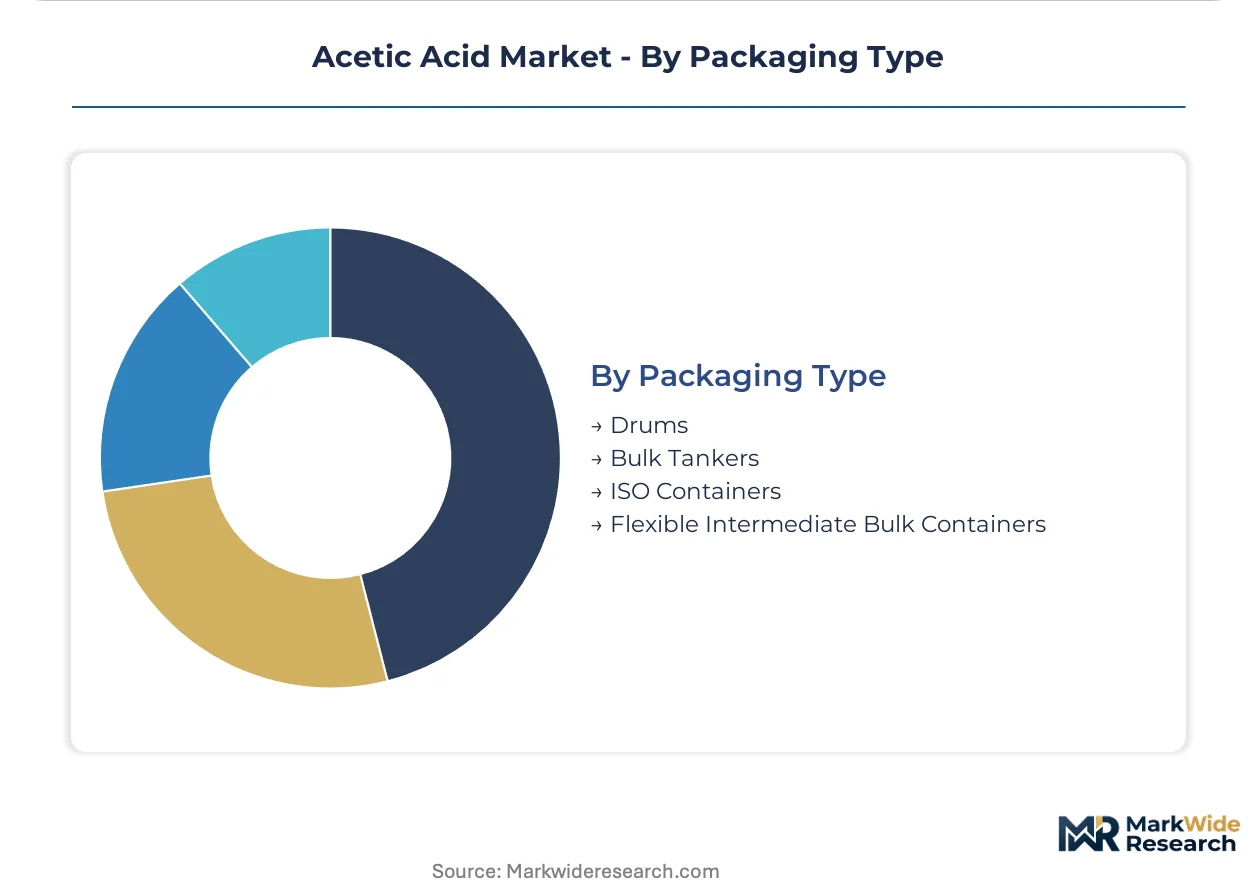
Packaging selection here divides by shipment scale and contamination risk tolerance.
- Bulk Tankers:Dedicated road and rail tank cars for integrated chemical park deliveries, with nitrogen blanketing and stainless steel construction preventing moisture ingress. Coastal Chinese PTA facilities and US Gulf Coast VAM plants absorb the majority of this volume through pipeline-equivalent logistics.
- ISO Containers:Intermodal tank units enabling ocean freight for mid-scale industrial buyers lacking direct pipeline access. European importers from Middle Eastern carbonylation sources rely on this format for Rotterdam and Antwerp terminal deliveries.
- Drums:Standard 200-liter steel or HDPE containers for batch chemical processors and small-scale formulators. Drum specifications are tightening under DOT and ADR hazardous material transport regulations, pushing toward UN-certified designs with secondary containment.
- Flexible Intermediate Bulk Containers:Bulk bags with liner systems for dilute acetic acid and salt forms where liquid containment is not required. Food-grade vinegar producers in Modena and Catalonia utilize this format for fermentation feedstock delivery.
Volume moves through Bulk Tankers; flexibility concentrates in ISO Containers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coastal chemical parks in China's Jiangsu and Zhejiang provinces operate as bonded zones offering VAT rebates and expedited customs clearance, concentrating PTA manufacturing capacity and absorbing acetic acid volumes through dedicated pipeline infrastructure.
China
PTA intermediate demand from polyester fiber producers in Ningbo and Zhoushan chemical parks anchors acetic acid consumption, with state-owned enterprises integrating backward into captive carbonylation capacity. SAMR's GB standards for industrial chemical purity are tightening documentation requirements for cross-provincial shipments. Yangtze River Delta clusters now host pipeline-linked acetic acid supply networks that bypass traditional merchant market liquidity.
United States
Vinyl acetate monomer facilities along the Texas and Louisiana Gulf Coast consume glacial grades through dedicated tank car logistics serving adhesives and coatings compounders. EPA TSCA Section 8 hazard communication mandates now require batch-level impurity profiling for industrial-grade shipments into manufacturing facilities. Houston Ship Channel petrochemical complexes maintain nitrogen-blanketed storage preventing moisture ingress for polymer-grade specifications.
Germany
REACH registration costs for industrial-grade acetic acid are filtering smaller compounders from supplier qualification pools, concentrating volume among carbonylation operators with captive analytical capabilities. ECHA documentation requirements for trace metal detection now exceed standard ISO certification thresholds. Ludwigshafen and Marl chemical parks house integrated acetyl chemistry chains serving European VAM and acetate ester demand.
India
Pharmaceutical excipient demand from generic drug manufacturers in Hyderabad and Ahmedabad is outpacing domestic supply qualification under CDSCO tightening documentation requirements. FSSAI-mandated purity certificates for food-grade imports are creating entry barriers for uncertified regional blenders. Gujarat's Dahej and Mundra port zones absorb bulk tanker deliveries from Middle Eastern carbonylation sources.
Saudi Arabia
Jubail Industrial City's methanol-to-acetic acid integration leverages feedstock access from adjacent gas processing facilities serving specialty chemical exporters. SABIC-affiliated operations supply ISO container shipments to Rotterdam and Antwerp terminals under long-term contract structures. Yanbu petrochemical complex expansions are adding carbonylation capacity targeting European industrial-grade specifications.
Acetic Acid Market Vendor Landscape
Chinese state-owned enterprises anchor one tier through integrated coastal chemical park infrastructure; Western diversified majors hold another through specification-grade certification and REACH-compliant documentation capabilities. Market structure tilts toward supply concentration with limited spot liquidity, favoring producers with captive methanol supply and backward integration into feedstock. Three archetypes dominate: integrated petrochemical conglomerates with pipeline-linked offtake, regional carbonylation specialists serving pharmaceutical-grade niches, and state-backed operators scaling PTA-dedicated supply. Competitive moves center on capacity expansion in Chinese bonded zones and strategic partnerships securing long-term VAM offtake agreements.
Among Western diversified majors, Celanese Corporation and Eastman Chemical Company exemplify contrasting positioning archetypes within specification-driven tiers. Celanese represents integrated methanol-to-acetic acid chain operators sustaining margin resilience across European and North American supply corridors through captive feedstock control. Eastman Chemical occupies a position competing on acetyl chemistry expertise and specification consistency rather than volume throughput alone. BASF SE anchors the German industrial base with Ludwigshafen complex integration serving REACH-registered industrial grades. These three entities illustrate how certification burden and feedstock integration separate competitive tiers in tightened regulatory environments.
| Leading Market Players |
|---|
| Celanese Corporation |
| Eastman Chemical Company |
| LyondellBasell Industries |
| INEOS |
| SABIC |
| Mitsubishi Chemical Group Corporation |
| Daicel Corporation |
| BASF SE |
| Shanghai Huayi (Group) Company |
| Others |
Supply Flow & Price Mechanics
State-owned enterprises controlling Chinese coastal chemical park infrastructure anchor supply discipline through pipeline-linked offtake agreements that compress spot market liquidity and sustain contract pricing premiums for European buyers facing REACH compliance costs.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as PTA producers in Ningbo and Zhoushan chemical parks absorb carbonylation capacity through dedicated pipeline connections, forcing spot buyers into premium pricing for immediate delivery. Pricing stratifies across pharmaceutical-grade certification, industrial-grade volume contracts, and spot merchant tiers, with CDSCO documentation requirements for Indian excipient imports widening spreads between qualified and unqualified supply. Cost compression in industrial-grade segments intensifies because methanol feedstock volatility transmits directly through non-integrated producer economics. Small-scale textile compounders in Gujarat and Shandong provinces exhibit highest price sensitivity, while pharmaceutical formulators in Basel and Boston metro areas prioritize specification consistency over unit cost.
Supply Chain Analysis
Acetic acid supply rests on methanol carbonylation capacity concentrated in China, the United States, and Saudi Arabia, with Chinese state-owned enterprises controlling disproportionate global throughput through integrated coastal chemical parks. Feedstock draws from natural gas processing in Jubail Industrial City, coal-to-methanol complexes in Shaanxi province, and Gulf Coast petrochemical infrastructure. Single-source vulnerability concentrates around rhodium catalyst supply and specialized reactor engineering for glacial-grade production. Distribution runs through pipeline-linked chemical parks for integrated PTA and VAM producers, ISO container shipments for European importers, and drum logistics for mid-scale batch processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bio-based acetic acid production via biomass gasification is displacing fossil methanol carbonylation in European specialty chemical procurement, creating a technology-transition phase where certification premiums reward early movers.
For Market Incumbents: Lock in long-term VAM offtake agreements with adhesives compounders in Germany and Southeast Asia to defend volume positions against bio-based substitution threats in EU Green Deal procurement. Prioritize backward integration into captive methanol supply to hedge feedstock volatility squeezing non-integrated competitor margins. Invest in rhodium catalyst recovery systems and corrosion-resistant reactor upgrades to extend asset life beyond depreciation schedules for aging European carbonylation facilities. For New Entrants and Emerging Players: Enter via Indian pharmaceutical excipient grade supply under CDSCO tightening documentation requirements, where domestic qualification lags demand expansion from generic drug manufacturers in Hyderabad and Ahmedabad. Target food-grade certification for FSSAI-mandated import requirements creating entry barriers for uncertified regional blenders. Deploy direct-to-formulator digital platforms bypassing traditional chemical distributor networks to reach mid-scale adhesives compounders in Milan and São Paulo metro areas. For Investors and Strategic Acquirers: Distressed-cycle entries favor European carbonylation assets with REACH-registered analytical capabilities and captive rhodium catalyst management systems. Long-term viability centers on producers with pipeline-linked coastal chemical park infrastructure and backward integration into feedstock. Watch bio-based certification adoption rates in European cosmetics and food additive applications as the inflection indicator for fossil-route margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methanol Supply | Celanese Corporation sustains margin resilience through captive feedstock control across North American supply corridors. |
| Carbon Capture Integration | EU Green Deal and China's dual carbon goals enable low-carbon acetic acid certification premiums for qualifying producers. |
| Pharmaceutical-Grade Certification Investment | CDSCO and EMA tightening excipient documentation requirements widen spreads for qualified suppliers in Indian and European markets. |
| Direct-to-Formulator Digital Platform Launch | Mid-scale adhesives compounders in Milan and São Paulo bypass traditional distributor networks for channel access. |
| Long-term PTA Supply Agreement | Chinese coastal chemical parks absorb carbonylation capacity through pipeline-linked offtake, compressing merchant market liquidity. |
Methodological Framework
Trade databases, SEC 10-K filings, and customs records formed the secondary backbone, supplemented by primary interviews with carbonylation plant managers, procurement leads at downstream PTA and VAM producers, distribution channel partners, and technical R&D directors in acetyl chemistry. Bottom-up capacity modeling across Chinese coastal chemical parks and top-down demand aggregation from polyester manufacturing clusters were triangulated against import-export flow data.
Historical trendline analysis of methanol carbonylation capacity additions, PTA manufacturing expansion rates, and VAM consumption patterns informed the projection framework across the analysis window. Segmentation dimensions modeled include purity grade tier, end-use application, packaging format, and regional production hub. CAGRs were derived from weighted average capacity utilization trajectories and demand elasticity estimates for vinyl acetate monomer and purified terephthalic acid intermediates, with bio-based production route penetration serving as a scenario-weighting input.
Forecast precision tightens around the base case; tail outcomes carry wider variance under methanol feedstock price volatility and regulatory divergence between REACH, EPA TSCA Section 8, and SAMR GB standards. Forecasts reflect assumptions regarding polyester manufacturing clustering continuity and pharmaceutical excipient documentation harmonization. A small set of triggers warrants ongoing watch: bio-based certification adoption thresholds, rhodium catalyst supply disruptions, and Chinese state-owned enterprise capacity allocation shifts between domestic and export markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Lithium Chemicals Market
Organic Chemicals
Chlorinated Isocyanurates Market
Organic Chemicals
Oxo Chemicals Market
Organic Chemicals
Cyclopentanone Market
Organic Chemicals
Asia-Pacific Organic Acid Market
Organic Chemicals
Bio-Acetic Acid Market
Organic Chemicals
Heterocyclic and Fluoro Organic Compounds Market
Organic Chemicals
North America Organic Acid Market
Organic Chemicals
1,3-Dioxolane Market
Organic Chemicals
Phenolic Board Market
Organic Chemicals
North America Humic Acid Market
Organic Chemicals
2,6-Dichloro Aniline Market
Organic Chemicals
Synthetic Antioxidants Market
Organic Chemicals
High Purity Metal Organics Market
Organic Chemicals
Organic Acids Market
Organic Chemicals
Para-Tert-Octylphenol (POTP) Market