
 Heterocyclic and Fluoro Organic Compounds Market | 2026-2036
Heterocyclic and Fluoro Organic Compounds Market Size, Share, and Industry Trends Forecast 2026-2036
Heterocyclic and Fluoro Organic Compounds Market Foresight
Specialty chemical distribution is fragmenting as regional distributors lose ground to direct manufacturer-to-laboratory platforms. Merck KGaA leverages its pharmaceutical-grade certification network to sustain premium positioning across European healthcare markets. Boehringer Ingelheim Pharma GmbH & Co. anchors its procurement strategy through captive synthesis of furan intermediates for internal drug pipelines. Tokyo Chemical Industry Co., Ltd. competes on catalog breadth and same-day dispatch from regional hubs in Asia-Pacific markets.
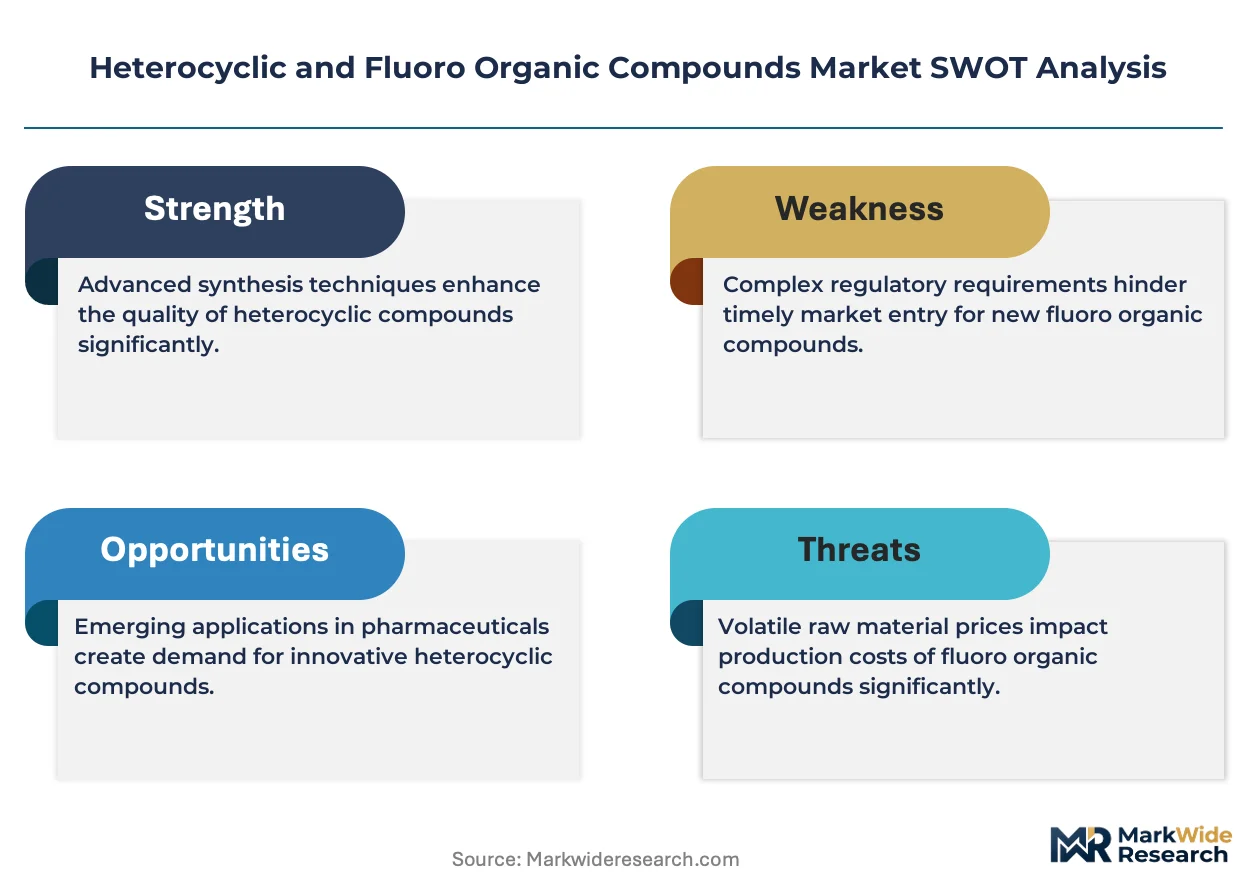
Heterocyclic and fluoro organic compounds constitute cyclic structures containing at least one non-carbon atom—nitrogen, oxygen, or sulfur—alongside carbon-fluorine bonded aromatic or aliphatic frameworks, typically synthesized through palladium-catalyzed cross-coupling or electrophilic fluorination at 80–150°C reaction temperatures. These compounds serve as molecular scaffolds for agrochemical active ingredients, pharmaceutical APIs, and high-performance dyes requiring thermal stability and metabolic resistance. Pharmaceutical-grade pyridine derivatives command the deepest margin pools due to FDA and EMA impurity profiling requirements, while agricultural chemical applications in thiophene-based fungicides represent the fastest-expanding volume segment. Reagent-grade furan compounds remain mature with thin margins, as academic and analytical laboratories prioritize cost over batch-to-batch consistency.
EPA toxics release inventory rules and REACH substance evaluation protocols force reformulation of legacy chlorinated intermediates toward fluorinated alternatives with lower environmental persistence. China's MEE hazardous chemical catalog revisions restrict unregistered thiophene derivatives from cross-border trade, redirecting supply toward SAMR-registered domestic producers. India's CDSCO active pharmaceutical ingredient traceability mandates tighten documentation for imported quinoxaline starting materials. Stakeholders must monitor regulatory divergence between EPA risk evaluation timelines and EU ECHA authorization lists to anticipate compound-specific market access shifts.
Market Dynamics
Pharmaceutical-grade certification requirements are concentrating procurement power among SAMR-registered Chinese producers and CDSCO-compliant Indian suppliers, squeezing mid-tier reagent-grade distributors across European laboratory markets.
Growth Catalysts
- Pyridine derivative demand:Active ingredient manufacturers in Gujarat and Jiangsu provinces are scaling GMP-certified capacity to serve FDA-inspected formulation facilities. CDSCO traceability mandates for imported starting materials reinforce domestic substitution trends.
- Electrophilic fluorination:Continuous-flow reactor technology at 80–150°C is reducing batch-to-batch variability for agrochemical intermediates. This process innovation attracts contract manufacturing investment from crop science multinationals.
- REACH authorization:ECHA substance evaluation protocols are accelerating reformulation of chlorinated legacy compounds toward fluorinated alternatives with lower environmental persistence, opening substitution contracts for registered suppliers.
Market Restraints
- Palladium cost volatility:Cross-coupling catalyst expenses constitute 15–25% of synthesis costs for specialty heterocycles, exposing margin structures to precious metal commodity swings.
- Thiophene supply concentration:MEE hazardous chemical catalog restrictions in China have eliminated unregistered cross-border trade, creating single-source dependency on SAMR-registered domestic producers for fungicide-grade material.
- Impurity profiling burden:EMA and FDA genotoxic impurity thresholds below 1.5 micrograms per day force extensive analytical validation, extending qualification timelines for new quinoxaline suppliers.
Strategic Opportunities
- Brazilian agrochemical expansion:ANVISA registration harmonization with OECD guidelines is opening import pathways for thiophene-based fungicide intermediates from Asia-Pacific producers with established dossier capabilities.
- Direct-to-laboratory platforms:Catalog distributors are bypassing regional chemical wholesalers to offer same-day dispatch from metropolitan hubs, capturing margin previously allocated to multi-tier distribution.
- F-Gas Regulation phase-down:EU restrictions on hydrofluorocarbon propellants are redirecting investment toward heterocyclic alternatives for inhalation drug delivery systems.
Industry Challenges
- Multinational regulatory divergence:EPA risk evaluation timelines for fluorinated compounds operate on 3–5 year cycles while EU ECHA authorization lists refresh annually, forcing parallel compliance investments without harmonized dossier acceptance.
- Specialized synthesis talent scarcity:Palladium-catalyzed cross-coupling expertise concentrates among aging cohorts in Basel and Tokyo, constraining technology transfer to emerging production clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heterocyclic and Fluoro Organic Compounds Market |
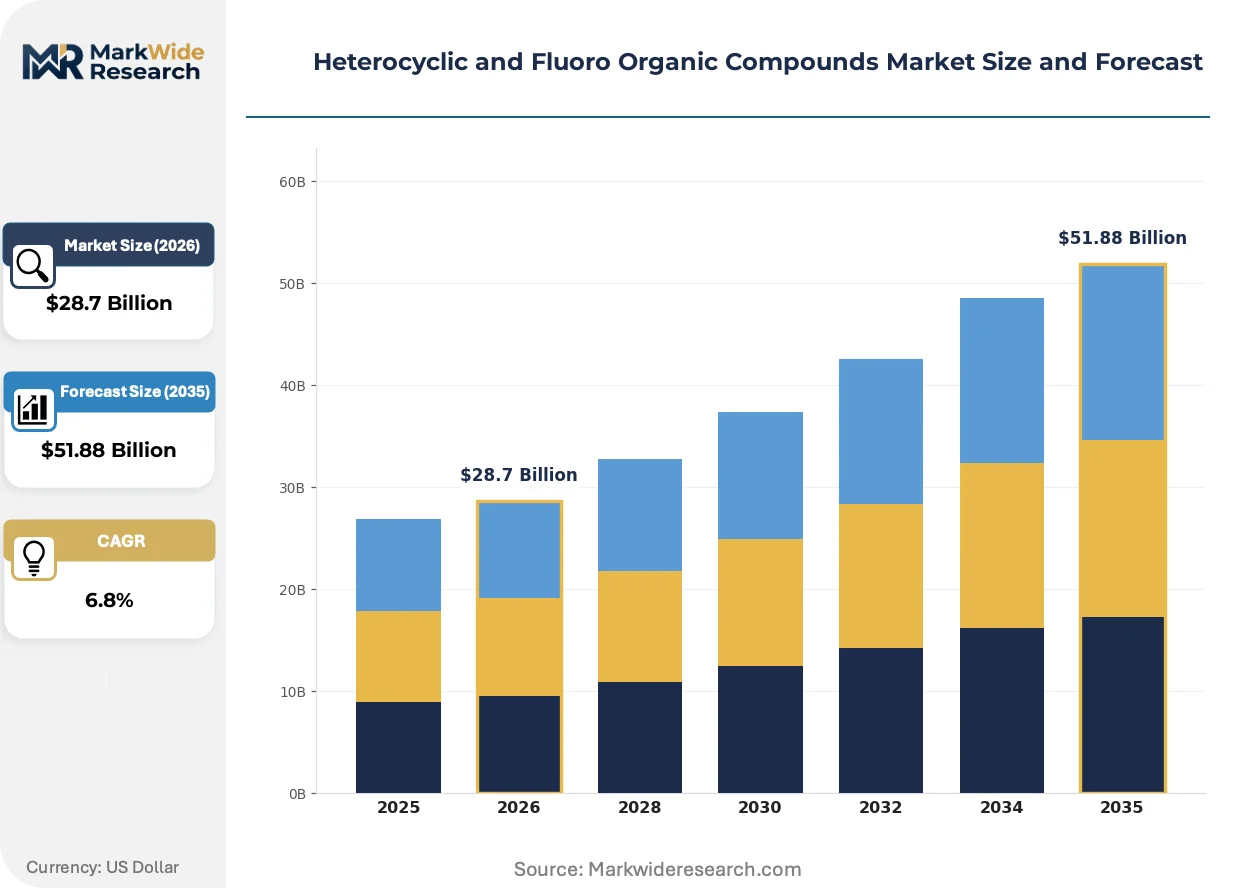
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $51.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pyridine, Furan, Thiophene, Quinoxaline Application: Agricultural Chemicals, Pharmaceuticals, Dyes, Fuel Additives Grade: Industrial Grade, Reagent Grade, Pharmaceutical Grade, Food Grade End Use Industry: Healthcare, Agriculture, Chemical Manufacturing, Rubber |
| Companies Covered | BLD Pharmatech Ltd, LLC SPE Enamin, Boehringer Ingelheim Pharma GmbH & Co., Merck KGaA, Sigma-Aldrich, Thermo Fisher Scientific, Tokyo Chemical Industry Co., Ltd., Biosynth Carbosynth, Survival Technologies Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heterocyclic and Fluoro Organic Compounds Market Shifts & Advancements
Flow chemistry and automated synthesis platforms are compressing development timelines for custom heterocyclic scaffolds, while regulatory pressure on persistent organic pollutants accelerates molecular redesign across agrochemical and pharmaceutical value chains.
Continuous-flow electrophilic fluorination is collapsing the batch-size economics that previously favored large-scale commodity producers. Mid-size contract manufacturers in Hyderabad and Shanghai are adopting modular reactor skids for multi-kilogram campaigns, enabling competitive quoting against legacy batch facilities for clinical-phase API intermediates. This technology diffusion is compressing minimum viable scale thresholds and fragmenting volume concentration.
REACH substance evaluation protocols are forcing systematic replacement of chlorinated aromatic intermediates with fluorinated analogues across European agrochemical formulation. ECHA authorization lists now classify multiple legacy thiophene derivatives as substances of very high concern, triggering reformulation investment from crop protection companies with significant EU revenue exposure. Suppliers with pre-registered fluorinated alternatives capture switching contracts during reregistration windows.
Research procurement from academic laboratories and biotech startups is migrating toward integrated e-commerce platforms with real-time inventory visibility and certificate-of-analysis download. Regional chemical distributors with legacy field sales models are losing share to direct manufacturer portals in Boston, Cambridge UK, and Singapore research corridors. This channel compression rewards catalog breadth and logistics integration over relationship-based account management.
Heterocyclic and Fluoro Organic Compounds Market Segmentation
Heterocyclic and fluoro organic compounds serve divergent performance requirements across pharmaceutical synthesis, agrochemical formulation, and specialty manufacturing. Segmentation reveals how purity thresholds, regulatory certification, and end-use thermal stability demands create distinct commercial tiers with unequal margin structures.
Product Type:
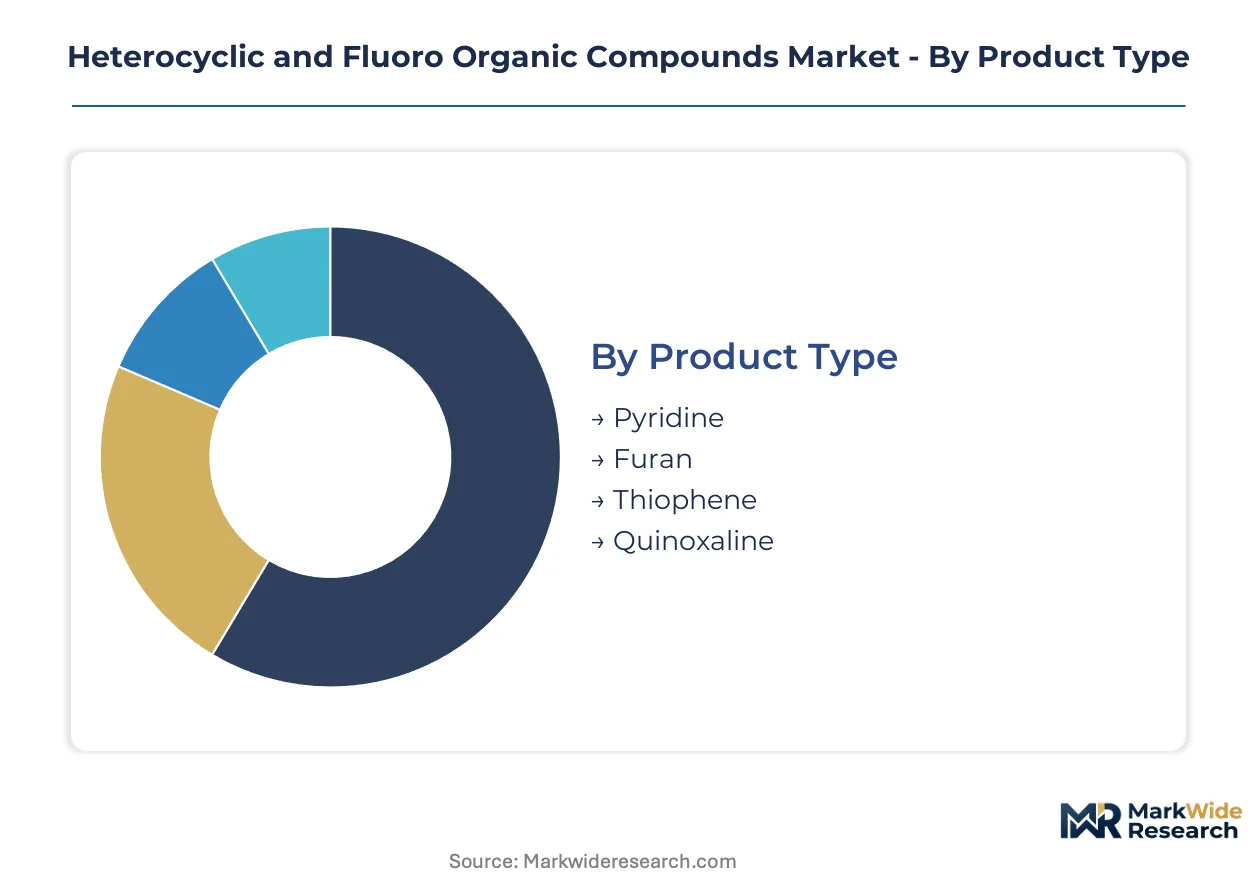
Pyridine derivatives anchor pharmaceutical API synthesis, while thiophene and furan compounds serve agrochemical and polymer applications with varying fluorination complexity.
- Pyridine:Six-membered nitrogen heterocycles with lone-pair donor characteristics enable metal coordination for palladium-catalyzed cross-coupling. Demand concentrates in Gujarat and Jiangsu province manufacturing clusters serving FDA-inspected formulation facilities, with CDSCO traceability mandates reinforcing domestic substitution.
- Furan:Five-membered oxygen heterocycles undergo electrophilic substitution at the 2-position for pharmaceutical intermediate synthesis. Academic and analytical laboratories in Boston and Cambridge UK prioritize catalog breadth and same-day dispatch over batch-to-batch consistency, compressing margins for reagent-grade material.
- Thiophene:Sulfur-containing aromatic rings provide electron-rich scaffolds for fungicide active ingredients.
- Quinoxaline:Fused bicyclic nitrogen heterocycles serve as molecular cores for antiviral and anticancer drug candidates.
The dominant share belongs to pyridine derivatives, while thiophene compounds are closing the gap fastest through agrochemical fungicide expansion.
Application:
Cost tier differentiation separates commodity-scale agricultural formulations from high-margin pharmaceutical APIs with genotoxic impurity thresholds below 1.5 micrograms per day.
- Agricultural Chemicals:Thiophene-based fungicides and pyridine-derived herbicides require thermal stability and metabolic resistance for field persistence. Brazil's ANVISA registration harmonization with OECD guidelines is opening import pathways for Asia-Pacific producers with established dossier capabilities.
- Pharmaceuticals:Heterocyclic scaffolds constitute molecular cores for kinase inhibitors and antiviral APIs. EMA and FDA impurity profiling requirements force extensive analytical validation, extending qualification timelines for new suppliers.
- Dyes:Fluorinated heterocycles deliver colorfastness and photostability for high-performance textile applications.
- Fuel Additives:Nitrogen-containing heterocycles serve as lubricity improvers and deposit control agents.
Agricultural chemicals command the largest volume position, though pharmaceuticals capture the steepest expansion trajectory through continuous-flow process adoption.
Grade:
Customer type segmentation distinguishes captive pharmaceutical manufacturers from spot-market industrial purchasers with divergent documentation and certification requirements.
- Pharmaceutical Grade:FDA and EMA-certified production with validated impurity profiles below ICH Q3D thresholds. Merck KGaA leverages its certification network to sustain premium positioning across European healthcare markets.
- Industrial Grade:Bulk quantities for agrochemical formulation and polymer synthesis with relaxed analytical specifications.
- Reagent Grade:Laboratory-scale batches for analytical method development and academic research.
- Food Grade:Furan derivatives for flavor and fragrance applications with FSSAI or FDA food additive approvals.
Pharmaceutical grade holds the value concentration, while industrial grade is gaining share fastest through Brazilian and Southeast Asian agrochemical capacity expansion.
End Use Industry:
Supply concentration patterns align with regional manufacturing clusters — pharmaceutical-grade production centers on Basel and Hyderabad, while agricultural chemical formulation dominates Jiangsu and São Paulo state.
- Healthcare:API manufacturers and contract research organizations demand GMP-certified heterocycles with complete chain-of-custody documentation. Boehringer Ingelheim anchors procurement through captive synthesis of furan intermediates for internal drug pipelines.
- Agriculture:Crop protection companies source thiophene fungicides and pyridine herbicides under REACH authorization protocols.
- Chemical Manufacturing:Specialty and commodity chemical producers use heterocyclic building blocks for dye and polymer synthesis.
- Rubber:Vulcanization accelerators and antioxidants incorporate sulfur-nitrogen heterocycles for tire manufacturing.
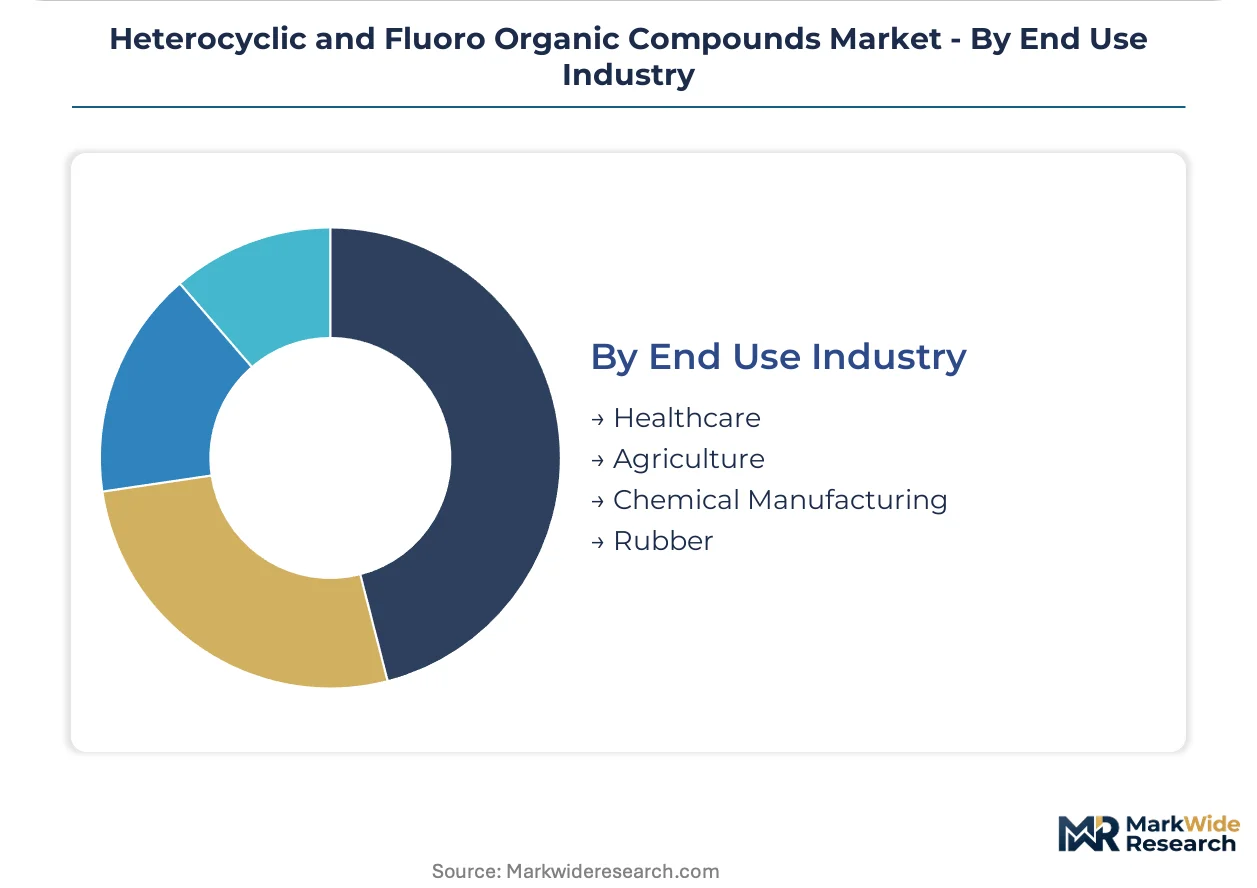
Healthcare consumes the dominant value share, while agriculture is climbing the fastest through thiophene-based fungicide volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's chemical terminal infrastructure underwrites China's dominance in heterocyclic compound exports, handling specialized refrigerated cargoes for temperature-sensitive fluorinated intermediates bound for formulation facilities worldwide.
China
Jiangsu province manufacturers scale GMP-certified pyridine capacity to serve FDA-inspected pharmaceutical facilities. SAMR registration protocols and MEE hazardous chemical catalog revisions restrict unregistered thiophene derivatives from cross-border trade, redirecting supply toward domestic producers. The Yangtze River Delta cluster around Nanjing and Changzhou anchors electrophilic fluorination capacity for agrochemical intermediates.
India
Gujarat's Ankleshwar and Vadodara industrial corridors concentrate pharmaceutical-grade quinoxaline synthesis for export markets. CDSCO active pharmaceutical ingredient traceability mandates tighten documentation requirements for imported starting materials, reinforcing domestic substitution. Hyderabad's Genome Valley contract manufacturers adopt continuous-flow reactor technology for clinical-phase API intermediates.
Germany
Basel-proximate production clusters in Baden-Württemberg leverage EMA certification networks for premium pharmaceutical-grade positioning. REACH authorization protocols and ECHA substance evaluation frameworks accelerate reformulation of chlorinated legacy compounds toward fluorinated alternatives. Ludwigshafen's chemical park infrastructure supports multi-kilogram campaigns for crop protection intermediates.
United States
Greater Boston and Research Triangle Park biotech corridors drive demand for reagent-grade furan compounds with same-day dispatch requirements. EPA toxics release inventory rules force reformulation of legacy chlorinated intermediates toward lower-persistence alternatives. Gulf Coast petrochemical infrastructure supports industrial-grade thiophene production for agricultural chemical formulation.
Brazil
São Paulo state agrochemical formulators expand procurement of thiophene-based fungicide intermediates from Asia-Pacific suppliers. ANVISA registration harmonization with OECD guidelines opens import pathways for producers with established dossier capabilities. The Port of Santos chemical terminal handles growing volumes of fluorinated heterocycles for domestic crop protection blending.
Heterocyclic and Fluoro Organic Compounds Market Competitive Landscape
On the supply side, the industry is bifurcating between certification-heavy pharmaceutical-grade specialists and volume-driven agrochemical intermediates suppliers. Consolidation pressures concentrate procurement power among SAMR-registered Chinese producers and CDSCO-compliant Indian suppliers, squeezing mid-tier European reagent-grade distributors. Three archetypes dominate: integrated pharmaceutical manufacturers with captive synthesis capabilities, catalog distributors leveraging logistics integration for research procurement, and contract manufacturers adopting continuous-flow technology for clinical-phase campaigns. Dominant competitive moves include backward integration into palladium catalyst supply chains and geographic expansion toward Brazilian and Southeast Asian agrochemical markets.
Within the certification-dependent tier, Merck KGaA and Boehringer Ingelheim Pharma GmbH & Co. exemplify divergent strategic positions. Merck KGaA occupies a position anchored in EMA-certified pharmaceutical-grade networks across European healthcare markets. Boehringer Ingelheim represents captive synthesis integration, maintaining in-house furan intermediate production for proprietary drug pipelines. Tokyo Chemical Industry Co., Ltd. sits within the catalog distribution archetype, competing on breadth and same-day dispatch from Asia-Pacific regional hubs.
| Leading Market Players |
|---|
| BLD Pharmatech Ltd |
| LLC SPE Enamin |
| Boehringer Ingelheim Pharma GmbH & Co. |
| Merck KGaA |
| Sigma-Aldrich |
| Thermo Fisher Scientific |
| Tokyo Chemical Industry Co., Ltd. |
| Biosynth Carbosynth |
| Survival Technologies Ltd. |
| Others |
Supply & Pricing Matrix
Palladium cost volatility constitutes the dominant risk vector, compressing margin structures for specialty heterocycle manufacturers while simultaneously forcing three-tier pricing stratification across pharmaceutical-grade, industrial-grade, and reagent-grade tiers. This commodity exposure anchors procurement decisions toward backward integration into catalyst supply chains and geographic diversification of synthesis capacity.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified pharmaceutical-grade pyridine derivatives from industrial-grade thiophene fungicide intermediates and reagent-grade furan compounds for academic laboratories. Price differentiation hinges on impurity profiling stringency and GMP certification status, with EMA genotoxic thresholds below 1.5 micrograms per day commanding substantial premiums. Cost compression in reagent-grade tiers is intensifying because catalog distributors bypass regional wholesalers to offer same-day dispatch, eroding legacy markup structures. Academic and analytical laboratories exhibit highest price sensitivity, while captive pharmaceutical manufacturers prioritize batch-to-batch consistency over unit cost.
Supply Chain Analysis
Contract manufacturing concentration rests on SAMR-registered producers in Jiangsu province and CDSCO-compliant facilities in Gujarat's Ankleshwar corridor, with continuous-flow reactor adoption accelerating in Hyderabad's Genome Valley. Geographic supply concentration centers on China, India, and Germany, with each hub serving distinct certification requirements. Raw material dependencies draw from palladium catalyst supply, fluorinating reagent availability, and starting material access for cross-coupling reactions. Single-source vulnerability pervades thiophene derivatives following MEE hazardous chemical catalog restrictions that eliminated unregistered cross-border trade. Distribution runs through direct manufacturer-to-laboratory platforms in research corridors alongside traditional bulk chemical distributors for agricultural formulation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty chemical procurement fragmentation creates multiple entry points, as regulatory divergence between EPA risk evaluation timelines and EU ECHA authorization lists forces parallel compliance investments that mid-tier suppliers cannot sustain.
For Market Incumbents: Pre-empt margin erosion in European reagent-grade distribution by acquiring continuous-flow reactor capabilities in Hyderabad or Shanghai, and secure palladium catalyst supply agreements to insulate synthesis costs from precious metal commodity swings. CDSCO and SAMR registration moats protect pharmaceutical-grade positioning against emerging contract manufacturers lacking dossier capabilities. For New Entrants and Emerging Players: Pursue Brazilian agrochemical formulation partnerships under ANVISA-OECD harmonization pathways, targeting thiophene-based fungicide intermediates where established Asia-Pacific suppliers face logistics bottlenecks. Direct-to-laboratory e-commerce platforms in Boston and Cambridge UK offer lowest customer acquisition friction for catalog distributors with real-time certificate-of-analysis capabilities. For Investors and Strategic Acquirers: ECHA substance evaluation protocols reshaping the acquisition landscape toward fluorinated alternative specialists with pre-registered REACH dossiers and established crop protection customer relationships. Long-term viability favors integrated manufacturers with captive synthesis capabilities and multi-regulatory certification rather than pure-play distributors. Monitor EPA risk evaluation timeline acceleration for fluorinated compounds as inflection signal for substitution contract velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Palladium Catalyst Supply | Merck KGaA and Boehringer Ingelheim secure synthesis cost predictability against metal commodity volatility. |
| Continuous-Flow Reactor Adoption | Hyderabad and Shanghai contract manufacturers compress batch-size economics for clinical-phase API campaigns. |
| SAMR and CDSCO Registration Investment | Chinese and Indian producers capture procurement concentration from mid-tier European reagent-grade distributors. |
| Direct-to-Laboratory Platform Expansion | Tokyo Chemical Industry bypasses regional wholesalers with same-day dispatch from Asia-Pacific regional hubs. |
| Fluorinated Alternative Portfolio Development | Suppliers with pre-registered ECHA dossiers capture switching contracts during chlorinated legacy compound phase-out. |
Research Methodology
Cross-validation between primary interviews with pharmaceutical procurement directors, agrochemical formulation specialists, contract manufacturing executives, and regulatory affairs leads anchors the qualitative findings against secondary validation from customs trade data, CDSCO registration databases, ECHA authorization lists, and SEC filings from specialty chemical distributors. Bottom-up demand modeling triangulates against top-down market sizing across grade tiers and end-use industries.
Calibration against historical capacity announcements and regulatory implementation timelines informs the projection framework across the analysis window. Segmentation dimensions include product type heterocycle class, application sector purity requirements, grade certification tier, and regional production hub regulatory cluster. CAGRs derive from elasticity-adjusted demand curves incorporating fluorination technology diffusion rates and substitution contract velocity from chlorinated legacy compounds.
Sensitivities concentrate around palladium price volatility, ECHA authorization list refresh frequency, and MEE hazardous chemical catalog expansion scope. Quarterly review of EPA risk evaluation pipeline status, SAMR registration approval velocity, and continuous-flow reactor adoption rates among mid-size contract manufacturers is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Global Ketones Market
Organic Chemicals
2-Iodophenol Market
Organic Chemicals
Pentachlorophenol Market
Organic Chemicals
Acrylic Acid Market
Organic Chemicals
Dioxolane Market
Organic Chemicals
North America Phenol Market
Organic Chemicals
Global Biphenyl Market
Organic Chemicals
Trimethylcyclohexanone Market
Organic Chemicals
2-Amino-5-Nitrobenzophenone Market
Organic Chemicals
Chloroethylene Market
Organic Chemicals
Aminophenol Market
Organic Chemicals
Lithium Chemicals Market
Organic Chemicals
Phenol Market
Organic Chemicals
Europe Organic Acid Market
Organic Chemicals
Isophthalic Acid Market
Organic Chemicals
Chlorinated Methane Market