
 Europe Organic Acid Market | 2026-2036
Europe Organic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Organic Acid Market Foresight
Pharmaceutical formulation demand is hardening across Europe as biologic drug manufacturing expands. BASF SE leverages its integrated petrochemical feedstock position to supply acetic acid derivatives for active pharmaceutical ingredient synthesis. Jungbunzlauer Suisse AG anchors the citric acid segment through fermentation expertise and Swiss manufacturing scale. Corbion N.V. specializes in lactic acid polymers for medical device applications, differentiating through biobased carbon credentials.
Organic acids comprise carboxylic compounds with at least one -COOH functional group, typically produced through petrochemical oxidation or microbial fermentation of carbohydrate feedstocks at controlled pH and temperature parameters. These chemicals serve as acidity regulators, chelating agents, and intermediate building blocks across industrial formulations. Citric acid dominates volume flows due to its GRAS status and versatility in food preservative and pH control applications, while lactic acid captures expanding margin pools from polylactic acid biopolymer feedstock demand. The food and beverage end use industry maintains structural leadership through preservative and flavor enhancer applications, though personal care represents the fastest-growing demand vector as natural cosmetic formulations gain shelf space across European retail channels.
EMA pharmaceutical purity standards and REACH chemical registration requirements shape product specifications and market access conditions for organic acid suppliers operating across EU member states. The EU Green Deal carbon border adjustments are redirecting capital toward fermentation-based production pathways with lower Scope 1-2 emissions profiles. Stakeholders must monitor bio-based feedstock cost curves and regulatory taxonomy alignment to preserve margin structures as chemical substitution mandates deepen.
Market Dynamics
Fermentation-based production pathways are hardening their cost advantage over petrochemical oxidation as EU Green Deal carbon border adjustments redirect capital toward lower-emission manufacturing clusters. REACH chemical registration requirements and EMA pharmaceutical purity standards simultaneously tighten product specifications while favoring incumbent suppliers with established compliance infrastructure.
Growth Catalysts
- REACH chemical substitution mandates:Regulatory pressure to replace synthetic preservatives with bio-based alternatives is pulling organic acids into food and beverage formulations across EU member states.
- Polylactic acid biopolymer feedstock demand:Medical device manufacturers are expanding lactic acid offtake for biodegradable polymer applications in surgical implants and drug delivery systems.
- Clean-label preservative adoption:German fermentation clusters supply citric acid derivatives to pan-European personal care brands reformulating around natural cosmetic claims.
Market Restraints
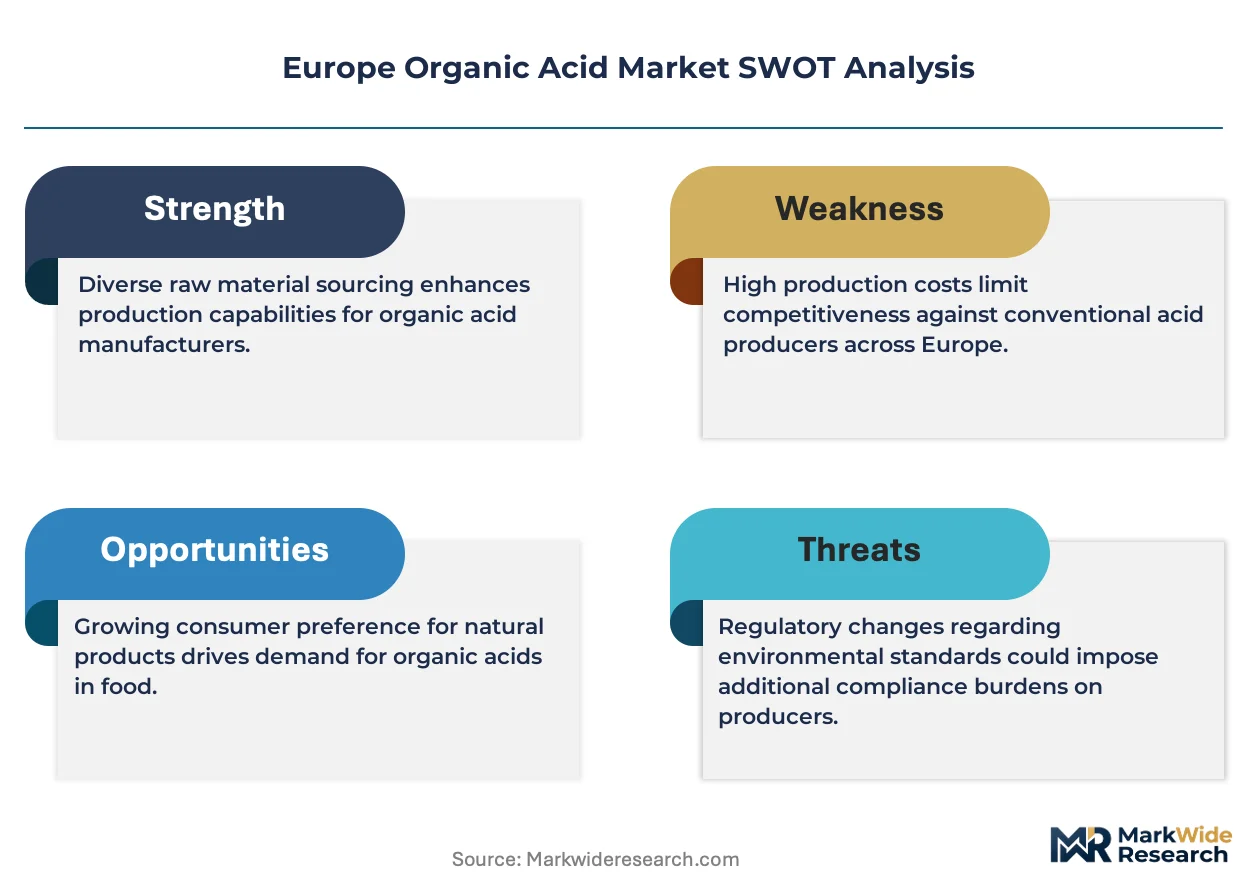
- Molasses and corn starch feedstock volatility:Carbohydrate raw material costs fluctuate with agricultural commodity cycles, compressing fermentation pathway margins when grain prices spike.
- Petrochemical oxidation capacity concentration:Acetic acid derivatives remain tethered to integrated refinery complexes in the Netherlands and Belgium, creating supply vulnerability during energy price shocks.
- Technical substitution ceiling:High-performance synthetic preservatives retain cost and efficacy advantages in extended-shelf-life applications where organic acid efficacy degrades.
Strategic Opportunities
- Eastern European manufacturing greenfield:Poland and Romania offer fermentation capacity expansion sites with lower labor costs and proximity to expanding Central European food processing corridors.
- Carbon capture integration:Fermentation off-gas utilization technologies enable Scope 1 emission reductions that align with EU taxonomy for sustainable activities.
- Direct-to-brand pharmaceutical partnerships:Biologic drug manufacturers are contracting dedicated organic acid supply for buffer and excipient applications outside traditional distributor channels.
Industry Challenges
- Bioprocess engineering talent scarcity:Industrial microbiology and metabolic pathway optimization expertise concentrates in Swiss and German research clusters, constraining scale-up velocity elsewhere.
- EMA certification timeline compression:Pharmaceutical-grade organic acid qualification cycles extend 18-24 months, delaying revenue recognition for new production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Organic Acid Market |
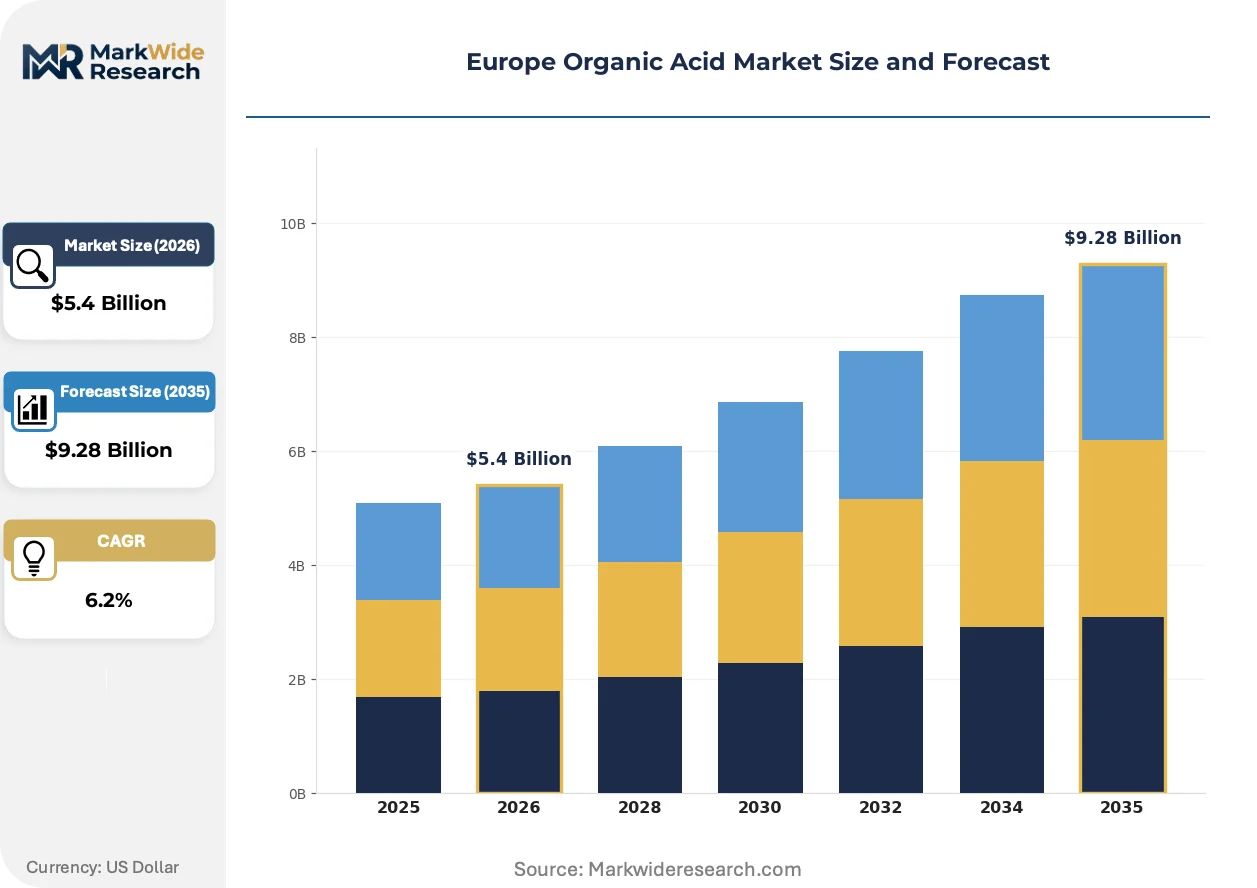
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citric Acid, Acetic Acid, Lactic Acid, Fumaric Acid End Use Industry: Food & Beverage, Pharmaceuticals, Agriculture, Personal Care Application: Food Preservative, Flavor Enhancer, pH Control, Solvent Distribution Channel: Online Retail, Wholesalers, Direct Sales, Supermarkets |
| Companies Covered | Cargill, Incorporated, BASF SE, Jungbunzlauer Suisse AG, Tate & Lyle PLC, Corbion N.V., DuPont de Nemours, Inc., BP Plc, The Dow Chemical Company, Koninklijke DSM N.V., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Organic Acid Market Shifts & Advancements
Continuous fermentation technology and cell-free enzymatic synthesis are compressing production economics while regulatory carbon accounting hardens preference for bio-based manufacturing pathways. These shifts are reconfiguring competitive advantage toward integrated biotechnology operations.
Cell-free enzymatic synthesis is absorbing capital investment from venture and corporate sources seeking to bypass cellular metabolism constraints. Specialty chemical manufacturers in the Netherlands are piloting this technology for C4-C6 dicarboxylic acid production. The approach is absorbing market share from traditional fermentation in high-purity pharmaceutical intermediate applications where batch-to-batch consistency commands premium pricing.
EU Green Deal carbon border adjustment mechanisms are tightening cost structures for petrochemical oxidation imports while privileging fermentation-based domestic production. ECHA registration dossiers now require comprehensive lifecycle emission disclosures that favor suppliers with integrated bio-based feedstock chains. Pharmaceutical and personal care formulators in France and Italy are revising procurement specifications to prioritize suppliers with verified Scope 1-2 emission profiles.
Direct long-term contracting is displacing spot-market purchasing among large food and beverage manufacturers seeking supply security for clean-label reformulations. Multinational brands are negotiating three-to-five-year offtake agreements with fermentation cluster operators in Germany and Switzerland. This pattern is most pronounced in dairy alternative and ready-to-drink beverage segments where preservative system transitions require multi-year formulation stability commitments.
Europe Organic Acid Market Segmentation
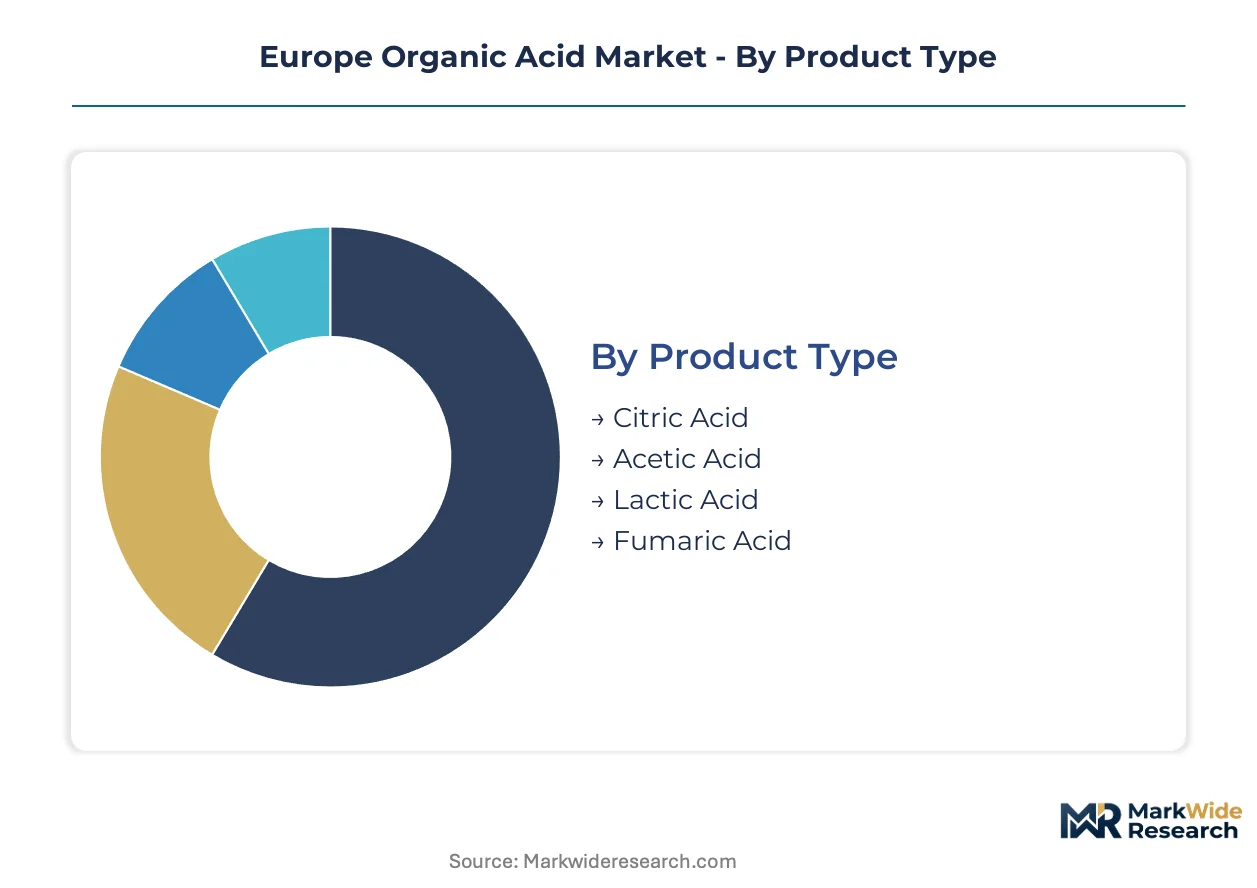
Organic acid suppliers configure production assets around divergent purity specifications and regulatory pathways. Segmentation reveals where capital deployment concentrates and which demand vectors reshape capacity planning across European manufacturing clusters.
Product Type:
Fermentation-based citric and lactic acid production demands substantially higher upfront capex than petrochemical oxidation routes for acetic acid derivatives. Swiss and German facilities anchor the continent's fermentation capacity.
- Citric Acid:Microbial fermentation of carbohydrate feedstocks yields tricarboxylic acid crystals meeting EFSA food-grade and EMA pharmaceutical specifications. German fermentation clusters supply pan-European food preservative demand, though molasses cost volatility compresses margins during agricultural commodity spikes.
- Lactic Acid:Carbohydrate fermentation at controlled pH produces chiral hydroxy acid for polylactic acid biopolymer synthesis. Corbion's Netherlands operations serve medical device manufacturers expanding biodegradable polymer offtake for surgical implants.
- Acetic Acid:Petrochemical oxidation of ethylene or methanol carbonylation supplies carboxylic acid for industrial solvent and derivative synthesis.
- Fumaric Acid:Catalytic isomerization of maleic anhydride or fermentation-derived biosynthesis yields dicarboxylic acid for food acidulant and resin applications.
Most installed capacity flows through citric acid. Expansion is steepest in lactic acid.
End Use Industry:
Customer concentration varies sharply: pharmaceutical buyers demand multi-year supply contracts with EMA-certified purity, while food processors negotiate on price and volume flexibility.
- Food & Beverage:Acidity regulators and preservative systems for clean-label reformulations dominate organic acid offtake. REACH chemical substitution mandates pull bio-based alternatives into dairy alternatives and ready-to-drink beverages.
- Pharmaceuticals:Buffer and excipient applications for biologic drug manufacturing require 18-24 month EMA qualification cycles. BASF supplies acetic acid derivatives for active pharmaceutical ingredient synthesis from integrated petrochemical positions.
- Personal Care:Natural cosmetic formulations drive citric acid demand for pH adjustment and chelation in French and Italian premium skincare.
- Agriculture:Feed acidification and silage preservation applications consume fermentation-derived acids for livestock nutrition optimization.
Food and beverage absorbs the largest volume share. Pharmaceuticals command the highest unit margins.
Application:
Functional requirements dictate specification tiers: food preservatives face EFSA additive limits, while pharmaceutical solvents must meet ICH Q3C residual solvent guidelines.
- Food Preservative:Antimicrobial activity against spoilage organisms enables shelf-life extension in clean-label formulations. German suppliers coordinate with pan-European dairy processors transitioning from synthetic preservatives.
- pH Control:Buffer capacity and acidulant function serve beverage, pharmaceutical, and personal care formulation stability. Citric acid dominates this application due to GRAS status and taste profile neutrality.
- Flavor Enhancer:Taste modulation and sourness perception adjustment in confectionery and savory applications.
- Solvent:Pharmaceutical intermediate synthesis and industrial cleaning applications requiring high-purity grades.
Food preservative applications deploy the broadest supplier base. pH control applications are expanding most quickly across pharmaceutical and personal care segments.
Distribution Channel:
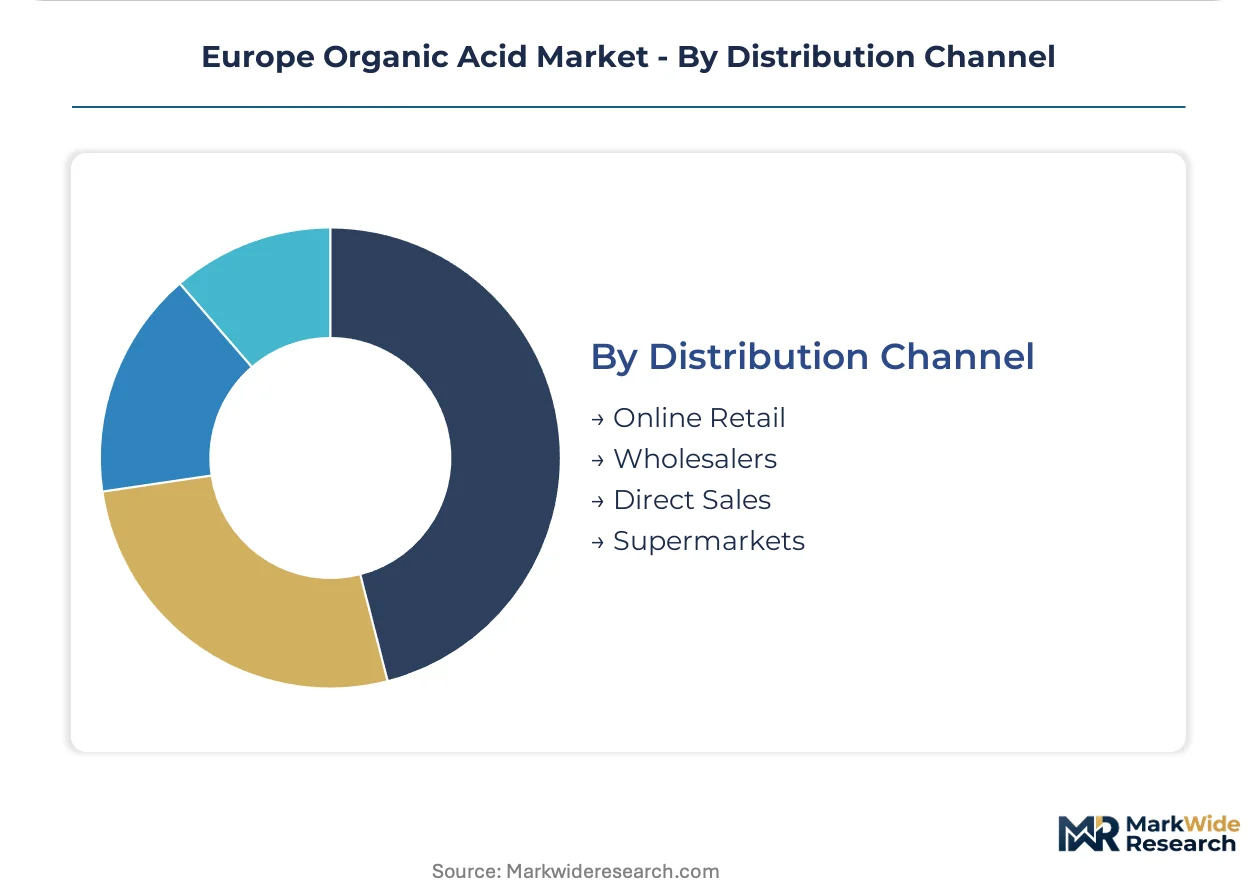
Channel selection tracks buyer scale and specification complexity: bulk pharmaceutical manufacturers bypass distributors entirely, while small food processors rely on wholesaler technical support.
- Direct Sales:Long-term offtake agreements between fermentation cluster operators and multinational food and beverage brands secure supply for multi-year reformulation commitments. Three-to-five year contracts displace spot purchasing in dairy alternative segments.
- Wholesalers:Technical distributor networks serve mid-tier food processors and regional personal care formulators requiring smaller batch sizes and formulation guidance.
- Online Retail:E-commerce platforms supply laboratory-scale quantities and specialty grades to research institutions and small compounders.
- Supermarkets:Consumer-packaged goods and small-volume industrial sales through retail channels.
Direct sales channels carry the highest contract value. Online retail is gaining share fastest among specialty and research-grade segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal carbon border adjustments create compliance-cost differentials that redirect fermentation capacity toward jurisdictions with integrated bio-based feedstock chains and streamlined ECHA registration pathways.
Germany
Pharmaceutical buffer demand and clean-label food preservative reformulations pull organic acid volumes through Hamburg and North Rhine-Westphalia fermentation clusters. REACH chemical substitution mandates accelerate synthetic-to-bio-based transitions across dairy alternative processors. BASF SE anchors acetic acid derivative supply from Ludwigshafen integrated petrochemical positions.
Switzerland
Swissmedic pharmaceutical purity standards and EMA certification infrastructure concentrate high-grade citric acid production around Jungbunzlauer Suisse AG facilities. Geneva and Basel research clusters supply metabolic pathway optimization expertise constraining competitor scale-up velocity. Carbon-neutral manufacturing claims align with EU taxonomy for sustainable activities.
Netherlands
Corbion N.V. operations in Gorinchem serve medical device manufacturers expanding polylactic acid biopolymer offtake for surgical implants. Rotterdam petrochemical corridors retain acetic acid oxidation capacity vulnerable to energy price shocks. ECHA registration dossier requirements favor incumbent suppliers with established lifecycle emission disclosure infrastructure.
France
ANSM pharmaceutical regulations and premium personal care formulation demand in Île-de-France drive citric acid procurement for natural cosmetic pH adjustment. Paris-based brands negotiate three-to-five-year direct offtake agreements bypassing traditional distributor channels. EFSA additive limits shape food preservative application specifications.
Poland
Lower labor costs and proximity to Central European food processing corridors attract fermentation greenfield investment from German and Swiss operators. Warsaw and Łódź logistics hubs enable pan-European distribution without carbon border adjustment exposure. Agricultural feedstock availability supports molasses-based citric acid production economics.
Europe Organic Acid Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with fermentation-based purity grades commanding premium positioning against petrochemical oxidation commodity supply. The vendor base concentrates around integrated biotechnology operations with EMA-certified infrastructure and Swiss-German research cluster proximity. Three archetypes dominate: integrated petrochemical majors with derivative synthesis capabilities, dedicated fermentation specialists with pharmaceutical-grade certification, and diversified nutrition-ingredient suppliers leveraging agricultural feedstock integration. Capacity expansion and direct-to-brand pharmaceutical partnerships represent the dominant competitive vectors reshaping procurement relationships.
Within the fermentation specialist tier, Jungbunzlauer Suisse AG and Corbion N.V. exemplify players anchoring high-purity organic acid supply through integrated bio-based manufacturing positions. BASF SE occupies a distinct archetype representing petrochemical oxidation pathways for industrial derivative applications. Cargill, Incorporated and Tate & Lyle PLC sit within diversified agricultural processing conglomerates leveraging captive carbohydrate feedstock access. Koninklijke DSM N.V. represents the nutrition-to-pharmaceutical convergence archetype with bioprocess engineering depth. DuPont de Nemours, Inc. and The Dow Chemical Company exemplify multinational chemical majors with portfolio breadth spanning multiple acid categories and end-use specifications.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| BASF SE |
| Jungbunzlauer Suisse AG |
| Tate & Lyle PLC |
| Corbion N.V. |
| DuPont de Nemours, Inc. |
| BP Plc |
| The Dow Chemical Company |
| Koninklijke DSM N.V. |
| Others |
Supply & Pricing Matrix
Molasses and corn starch futures indices cascade through fermentation pathway economics into three-tier pricing structure across premium, standard, and economy levels. EMA pharmaceutical certification premiums widen spreads between food-grade citric acid and high-purity excipient grades as REACH substitution mandates harden bio-based procurement specifications.
Pricing Analysis
Direct-to-brand distributor margins compress as multinational food manufacturers negotiate three-to-five-year offtake agreements bypassing wholesaler markups. Pharmaceutical-grade lactic acid commands premium positioning against commodity acetic acid derivatives due to EMA qualification timelines and chiral purity requirements. Pricing pressure stems from molasses feedstock volatility during agricultural commodity spikes. Small regional food processors exhibit highest price sensitivity; biologic drug manufacturers show lowest sensitivity due to formulation stability requirements.
Supply Chain Analysis
Regional distribution centers in Hamburg, Rotterdam, and Basel orchestrate hub-and-spoke patterns serving pan-European pharmaceutical and personal care clusters. Manufacturing concentrates in Germany, Switzerland, and the Netherlands. Raw material flows draw from Ukrainian beet molasses, French wheat starch, and Brazilian sugarcane derivatives. Single-source vulnerability concentrates in Swiss-German fermentation engineering talent pools. Distribution runs through integrated biotechnology operators with captive carbohydrate feedstock chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH chemical substitution mandates compound demand for bio-based preservatives as EU Green Deal carbon border adjustments redirect procurement toward fermentation-based suppliers. This regulatory momentum hardens structural advantages for integrated biotechnology operations.
For Market Incumbents: To counter Eastern European greenfield entrants with lower labor costs, deepen captive molasses supply agreements in Poland and Romania while accelerating EMA certification infrastructure investments. Backward integration into agricultural feedstock processing preserves margin structures during commodity volatility cycles.
For New Entrants and Emerging Players: Enter via Polish fermentation capacity greenfields serving Central European dairy alternative processors transitioning from synthetic preservatives. White-space concentrates in pharmaceutical-grade fumaric acid for medical device resin applications. Direct long-term contracting with French personal care brands bypasses entrenched distributor relationships.
For Investors and Strategic Acquirers: Asymmetric upside sits with diversified nutrition-ingredient conglomerates leveraging captive carbohydrate access and pharmaceutical certification infrastructure. Long-term viability favors operations with verified Scope 1-2 emission profiles aligned to EU taxonomy. Monitor EMA certification timeline compression as inflection indicator for revenue recognition velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Processing | Captive molasses supply from Polish agricultural corridors insulates margin compression during commodity spikes. |
| EMA Certification Infrastructure Expansion | Swissmedic-aligned qualification pathways accelerate pharmaceutical-grade revenue recognition timelines. |
| Carbon Capture Integration | Fermentation off-gas utilization aligns production with EU taxonomy for sustainable activities. |
| Long-term Supply Agreement with Biologic Manufacturers | Direct buffer and excipient contracting bypasses traditional distributor channels in pharmaceutical segments. |
| Eastern European Manufacturing Greenfield | Polish and Romanian sites exploit labor cost differentials while serving expanding Central European food processing corridors. |
Research Methodology
Bottom-up food and beverage end-use modeling reconciled against top-down fermentation capacity tracking forms the analytical core of this study. Primary interviews with plant managers at German and Swiss fermentation clusters, procurement leads at pan-European dairy processors, EMA regulatory affairs specialists, and distribution channel partners in Rotterdam and Hamburg were validated against secondary sources including ECHA registration dossiers, Cefic chemical industry reports, EU customs trade data, and SEC filings of listed organic acid suppliers.
Historical production volume trendlines across citric, lactic, and acetic acid categories were projected over the forecast period using grade tier, end-use industry, and regional production hub segmentation. CAGRs were derived from elasticity-adjusted demand curves incorporating REACH substitution mandate implementation timelines and EU Green Deal carbon border adjustment phase-in schedules. Forecast inputs included molasses feedstock cost curves and pharmaceutical certification queue lengths.
Inputs from EMA qualification databases and Cefic capacity surveys were available through the study window; gaps in real-time spot pricing for pharmaceutical-grade segments introduce uncertainty bands around margin projections. Forecasts reflect documented assumptions regarding regulatory implementation velocity and feedstock cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Acrylic Acid Market
Organic Chemicals
Global Ketones Market
Organic Chemicals
Global Metal-Organic Framework Market
Organic Chemicals
Organic Chemicals Market
Organic Chemicals
Methyl Isobutyl Ketone (MIBK) Market
Organic Chemicals
Global Glycolic Acid Market
Organic Chemicals
Organic Polysulfide Market
Organic Chemicals
Organic Coating Market
Organic Chemicals
Long-Chain Dicarboxylic Acid Market
Organic Chemicals
High Purity Metal Organics Market
Organic Chemicals
N-Hexyl Chloride Market
Organic Chemicals
Cycloalkanes Market
Organic Chemicals
Anthracene Market
Organic Chemicals
Oryzenin Market
Organic Chemicals
Isophthalic Acid Market
Organic Chemicals
N-Pentane Market