
 Aspartic Acid Market | 2026-2036
Aspartic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Aspartic Acid Market Intelligence
Supply chain traceability services are broadening the value proposition beyond the core chemical product, offering buyers verifiable data on sourcing and quality. Ajinomoto Co., Inc. leverages its extensive fermentation technology and manufacturing scale in the broader amino acids space. Evonik Industries AG specializes in high-purity aspartic acid grades for demanding pharmaceutical applications. Meanwhile, CJ CheilJedang Corp. competes through its efficient production processes and a well-established global distribution network reaching key end-use markets.
Aspartic acid is a non-essential amino acid synthesized primarily through the enzymatic conversion of fumarate and ammonia. It functions as a crucial building block for proteins and a precursor to other amino acids and nucleotides. Its primary commercial applications are as a key intermediate in the synthesis of the artificial sweetener aspartame and as a performance-enhancing ingredient in nutraceuticals. The nutraceuticals product type is expanding quickly, driven by consumer focus on dietary supplements. Its application as a flavoring agent remains a mature, high-volume segment.
The market operates under strict regulatory oversight concerning food and drug safety. The US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) define purity standards and acceptable daily intake levels for aspartic acid and its derivatives used as food additives. Conformance with Good Manufacturing Practices (GMP) is mandatory for pharmaceutical-grade material. Future competitive advantage depends on navigating evolving clean-label trends and securing access to sustainable, bio-based feedstocks.
Market Dynamics
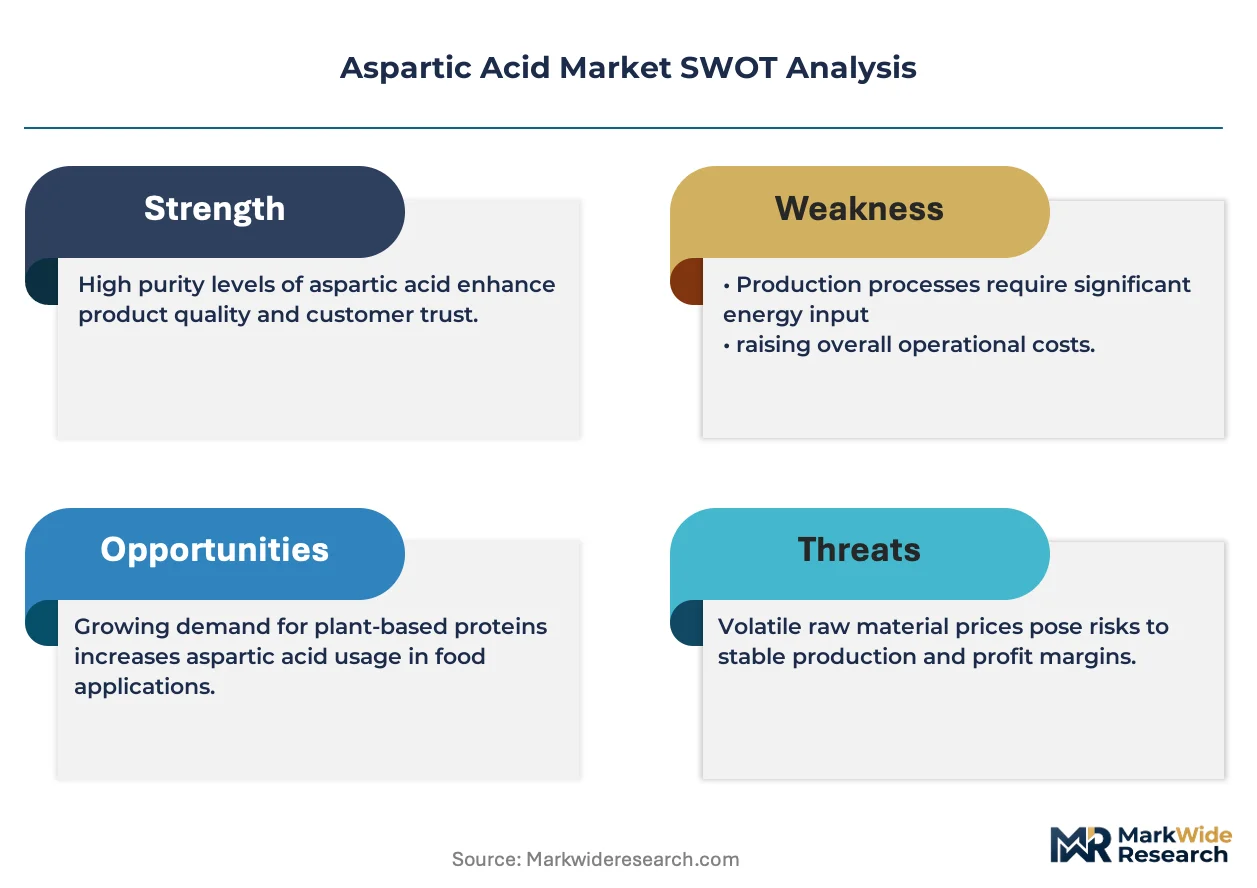
The market's central dynamic is the divergence between high-volume, price-sensitive applications like aspartame synthesis and the rapidly expanding, high-margin nutraceutical sector. This split is driven by stricter food additive regulations and evolving consumer health priorities.
Growth Catalysts
- Nutraceutical Expansion:The use of aspartic acid in sports nutrition and dietary supplements as a performance and cognitive enhancer is a primary growth vector, especially in developed economies.
- Chinese Industrial Demand:China's large-scale food processing and pharmaceutical sectors create sustained, high-volume demand for aspartic acid as a key intermediate chemical and food additive.
- Process Efficiency Gains:Advances in enzymatic conversion and fermentation technologies are improving production yields and lowering costs, making aspartic acid more competitive against alternative amino acids.
Market Restraints
- Feedstock Price Volatility:Production costs are directly tied to the prices of key raw materials like fumarate and ammonia, which are subject to fluctuations in the broader chemical and agricultural markets.
- Stringent Regulatory Hurdles:Conforming to the purity standards and documentation requirements of bodies like the US FDA and Europe's EFSA increases operational costs and slows market entry for new producers.
- Threat of Substitution:In flavoring applications, other compounds like glutamic acid can serve as substitutes, while in sweeteners, a wide array of alternatives to aspartame exists, limiting pricing power.
Strategic Opportunities
- Bio-based Polymers:There is an opportunity to develop and market polyaspartic acid as a biodegradable and water-soluble polymer for applications in agriculture, water treatment, and as a corrosion inhibitor.
- Clean Label Formulations:Manufacturers can leverage fermentation-derived aspartic acid to appeal to the clean label trend, marketing products as bio-based and non-GMO to command premium pricing in food and supplements.
- Geographic Expansion:Targeting growing middle-class populations in Southeast Asia and Latin America, where the dietary supplement market is expanding but local production infrastructure is limited, offers new growth.
Industry Challenges
- Supply Chain Integrity:Ensuring end-to-end traceability and preventing contamination for pharmaceutical-grade aspartic acid across complex global logistics networks is a significant operational challenge for suppliers.
- Capital-Intensive Production:The construction and validation of fermentation plants that meet Good Manufacturing Practices (GMP) require substantial upfront capital investment, creating high barriers to entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aspartic Acid Market |
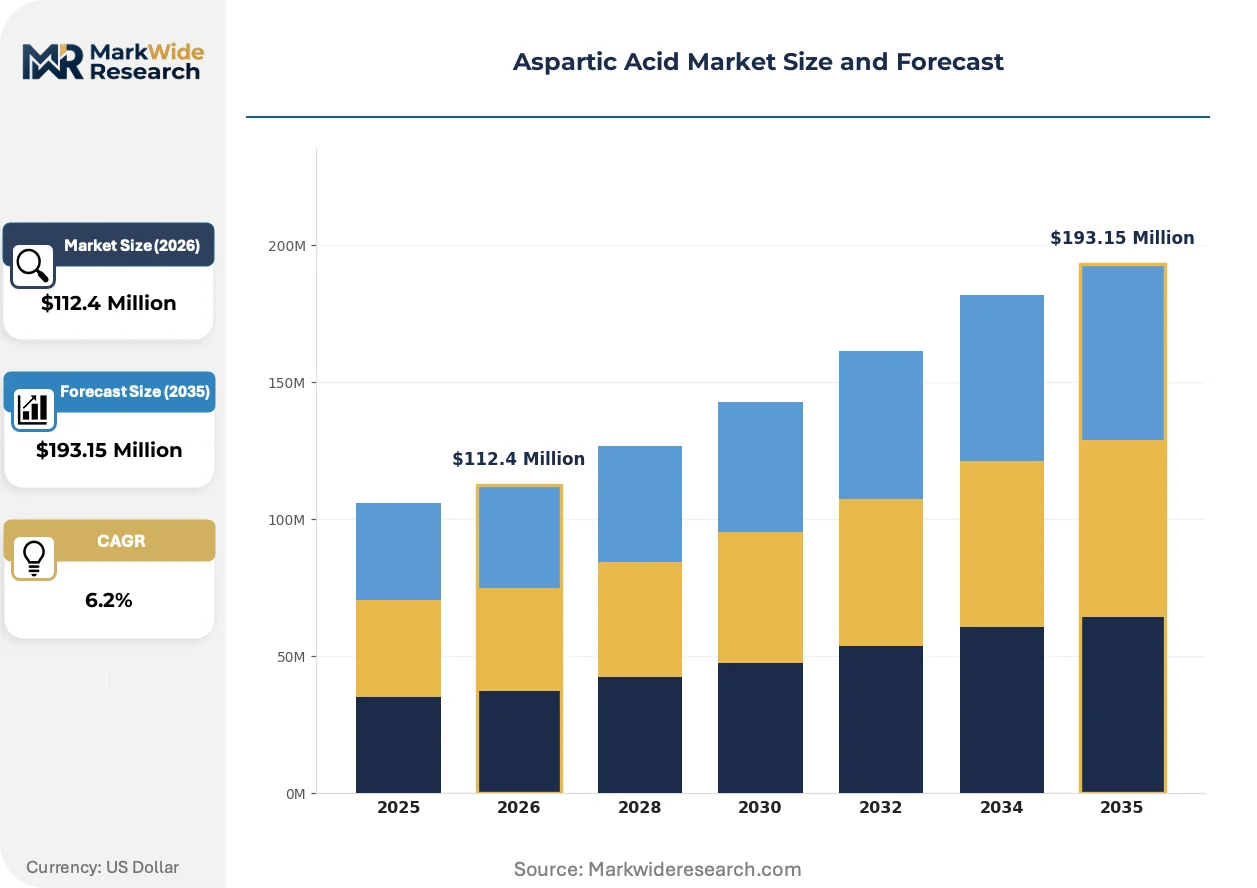
| Market Size in 2026 | $112.4 Million |
| Market Size in 2035 | $193.15 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Additives, Nutraceuticals, Pharmaceuticals, Industrial Chemicals End User: Food Industry, Health Supplements, Pharmaceutical Companies, Chemical Manufacturers Application: Flavoring Agent, Performance Enhancer, Fertilizer Additive, Pharmaceutical Intermediate Form: Liquid, Powder, Crystals, Granules |
| Companies Covered | Ajinomoto Co., Inc., Evonik Industries AG, CJ CheilJedang Corp., Kyowa Hakko Bio Co., Ltd., Prinova Group LLC, Kirin Holdings Company, Merck KGaA, Iris Biotech GmbH, Arkema S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aspartic Acid Market Strategic Shifts & Innovations
A clear bifurcation defines the aspartic acid market, separating high-purity, value-added grades from commoditized volumes. This division is being deepened by advancements in bioprocessing technology and the tightening of global food safety standards.
Advanced enzymatic synthesis is the primary production method for high-grade aspartic acid. Nutraceutical and pharmaceutical manufacturers are rapidly adopting suppliers who use this technology to ensure purity and consistency. This technology is consolidating the high-purity segment into a group of large producers with proprietary bioprocessing expertise.
China's updated GB standards for food additives, enforced by the State Administration for Market Regulation (SAMR), mandate stricter purity and testing protocols. This regulation compels suppliers to invest in quality control and process verification to maintain access to the Chinese market. The aspartame and beverage industries are most affected, re-evaluating their supply chains to ensure compliance.
Buyer preference is shifting toward suppliers providing verifiable data on sourcing, a move away from procurement based only on price. This is disrupting traditional distribution channels, as end-users in the supplement sector bypass intermediaries to engage directly with certified producers. The trend is most visible in European markets, driven by consumer demand for transparency.
Aspartic Acid Market Segmentation
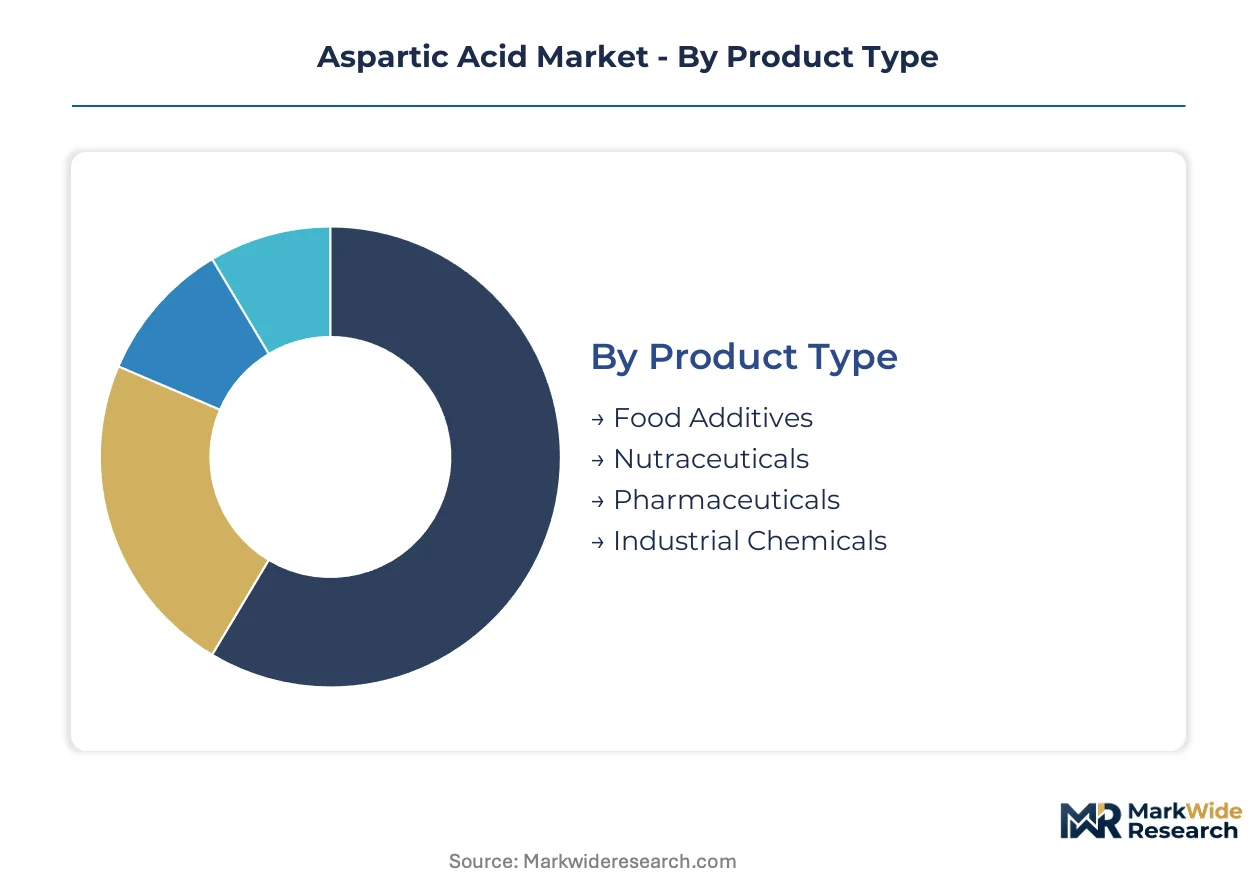
The aspartic acid market is segmented to reveal distinct value propositions and demand drivers across its diverse applications. Understanding these segments clarifies the varying purity requirements, regulatory considerations, and commercial dynamics influencing supply and procurement strategies.
Product Type:
Aspartic acid product types differentiate based on purity levels and intended application specifications, influencing production methods and market pricing.
- Nutraceuticals:Formulated for dietary supplements, this product type often requires specific purity and bioavailability for human consumption. Demand is expanding in developed economies, driven by consumer focus on health and performance enhancement.
- Pharmaceuticals:This segment demands the highest purity grades and strict adherence to Good Manufacturing Practices (GMP) for drug synthesis. Regulatory bodies like the US FDA and Europe's EMA mandate rigorous quality control for these applications.
- Food Additives:Utilized in food processing as an ingredient in artificial sweeteners like aspartame. This segment represents a high-volume, price-sensitive market.
- Industrial Chemicals:Serves as a chemical intermediate in various industrial processes, including the production of biodegradable polymers and resins.
Mature deployment sits with Food Additives. Newer deployment is concentrated in Nutraceuticals.
End User:
End-user segments for aspartic acid are defined by their primary application focus and regulatory environments, dictating product specifications and distribution channels.
- Health Supplements:Companies in this sector formulate aspartic acid into performance enhancers and cognitive support products. Consumer demand for bio-based and clean-label ingredients drives product innovation in this segment.
- Pharmaceutical Companies:These firms utilize high-purity aspartic acid as a critical building block for drug synthesis and active pharmaceutical ingredients. Strict regulatory compliance from bodies like China's NMPA shapes procurement practices.
- Food Industry:This segment integrates aspartic acid primarily for artificial sweetener production and flavor enhancement in various food products, adhering to food safety standards.
- Chemical Manufacturers:These entities consume aspartic acid as an intermediate for synthesizing other chemicals, including specialty polymers and resins for diverse industrial uses.
Health Supplements exhibits the steepest expansion trajectory. The Food Industry continues to represent substantial volume consumption.
Application:
Aspartic acid applications are categorized by their distinct functional roles within various commercial products, each facing unique market dynamics and growth prospects.
- Performance Enhancer:Aspartic acid is incorporated into sports nutrition products and dietary supplements to support energy metabolism and muscle function. This application benefits from rising consumer interest in health and wellness in developed markets.
- Pharmaceutical Intermediate:This application involves aspartic acid as a crucial chemical precursor in the synthesis of diverse pharmaceutical compounds. Production requires adherence to stringent purity standards and Good Manufacturing Practices.
- Flavoring Agent:Aspartic acid functions in food and beverage products, often as a component of artificial sweeteners like aspartame. This remains a high-volume, mature market segment.
- Fertilizer Additive:Utilized in agriculture to improve nutrient uptake and soil health, contributing to enhanced crop yields and sustainable farming practices.
Innovation activity is concentrated in Performance Enhancer applications. Flavoring Agent applications maintain a stable market presence.
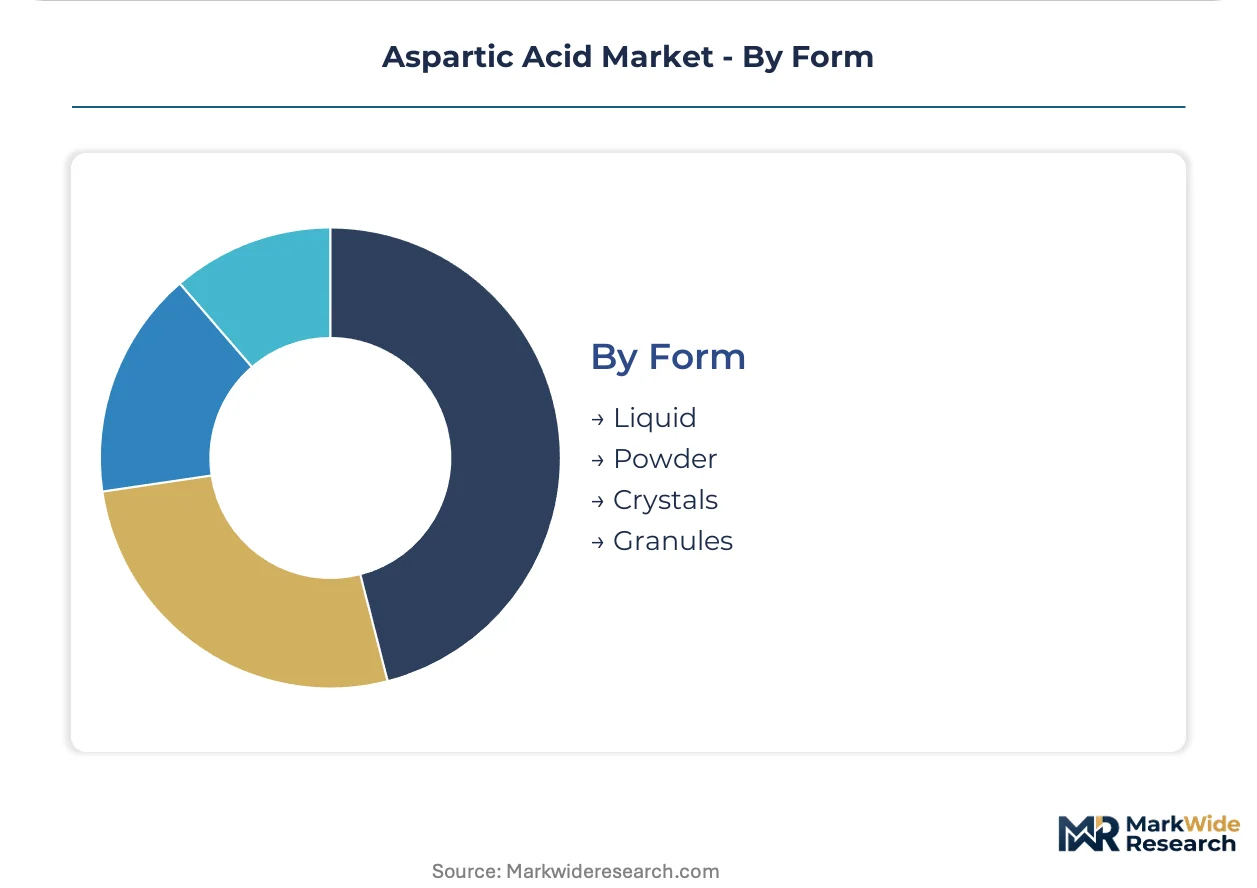
Form:
Aspartic acid is supplied in various physical forms to suit diverse manufacturing requirements and end-user preferences, impacting handling and integration into final products.
- Powder:This form offers high versatility for blending and dissolution across numerous applications including nutraceuticals and food additives. Ease of handling and transportation makes powdered aspartic acid a preferred choice for many manufacturers.
- Crystals:Characterized by high purity and consistent particle size, crystalline aspartic acid is often preferred for pharmaceutical formulations and precision chemical synthesis. Suppliers like Evonik Industries AG specialize in these high-grade forms.
- Liquid:Used in specific industrial processes where ease of mixing and solution stability are paramount, often for bulk applications.
- Granules:This form offers improved flowability and reduced dust, making it suitable for certain automated dosing and blending applications in food and feed industries.
Powdered forms dominate market supply for ease of integration. Specialized applications increasingly seek crystalline variants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global aspartic acid market exhibits a clear divergence between major production hubs and significant consumption centers. Demand for high-purity grades is driven by nutraceutical and pharmaceutical sectors in developed economies. Meanwhile, high-volume production for food additives often concentrates in specific industrial regions.
China
China's large-scale food processing and pharmaceutical sectors drive substantial aspartic acid consumption. The State Administration for Market Regulation (SAMR) enforces updated GB standards for food additives, mandating stricter purity. Production facilities in the Yangtze River Delta focus on high-volume output for domestic and export markets.
United States
United States demand for aspartic acid stems from its expanding health supplements sector and pharmaceutical synthesis. The US Food and Drug Administration (FDA) sets rigorous purity standards for both food additives and drug components. Research and manufacturing clusters in the Northeast Corridor advance specialized pharmaceutical-grade aspartic acid production.
Germany
Germany represents a significant market for high-purity aspartic acid, particularly in pharmaceutical and specialized chemical applications. Europe's EFSA and the EMA define strict quality and safety standards for its use in food and medicine. Chemical manufacturing centers in the Rhine-Main region develop advanced production methods for crystalline aspartic acid variants.
Japan
Japanese companies leverage advanced fermentation technology for efficient aspartic acid production and its use in nutraceuticals. The Pharmaceuticals and Medical Devices Agency (PMDA) regulates pharmaceutical-grade amino acids, ensuring product safety and efficacy. Industrial complexes in the Kansai region house major manufacturers specializing in amino acid synthesis.
India
India's expanding pharmaceutical industry and food processing sector generate consistent demand for aspartic acid as a key intermediate. The Central Drugs Standard Control Organization (CDSCO) and the FSSAI ensure compliance for drug synthesis and food additive applications. Manufacturing hubs in Gujarat are increasing capacity to serve both domestic and regional markets.
Aspartic Acid Market Key Industry Players
Top-tier vendors anchor the high-purity aspartic acid segment, while a broader base of producers competes in commoditized volumes. The market exhibits a tiered structure, with specialized players focusing on pharmaceutical and nutraceutical grades. Strategic archetypes include large-scale amino acid producers and niche manufacturers for specific industrial applications. Companies pursue capacity expansion and strategic partnerships to secure feedstock and distribution channels.
Among the established players, Ajinomoto Co., Inc. represents a global leader leveraging its extensive fermentation technology and manufacturing scale within the broader amino acids space. Germany-based Evonik Industries AG exemplifies a specialist in high-purity aspartic acid grades, particularly for demanding pharmaceutical applications requiring stringent quality and consistency. These companies often anchor the supply of advanced chemical intermediates. Meanwhile, CJ CheilJedang Corp. from South Korea occupies a position characterized by efficient production processes and a well-established global distribution network, effectively reaching various end-use markets worldwide.
| Leading Market Players |
|---|
| Ajinomoto Co., Inc. |
| Evonik Industries AG |
| CJ CheilJedang Corp. |
| Kyowa Hakko Bio Co., Ltd. |
| Prinova Group LLC |
| Kirin Holdings Company |
| Merck KGaA |
| Iris Biotech GmbH |
| Arkema S.A. |
| Others |
Cost & Logistics Intelligence
Stricter food safety mandates from bodies like the US FDA and Europe's EFSA gate access to qualified supply, directly influencing premium-tier pricing for high-purity aspartic acid grades. This regulatory environment shapes both production processes and market access for specialized applications.
Pricing Analysis
Cost-down pressure on food additive applications accelerates because of high-volume, commoditized production and the availability of substitutes. The dominant pricing model is contract-based long-term offtake for large industrial buyers, with spot pricing for smaller, immediate needs. Price differentiation stems from quality grade, particularly for pharmaceutical applications, and certification levels from regulatory bodies like the US FDA. Nutraceutical buyers exhibit lower price sensitivity due to product performance requirements, while the food industry remains highly price-sensitive for aspartame synthesis.
Supply Chain Analysis
Reverse logistics for high-purity aspartic acid are minimal, as product integrity and shelf-life typically preclude returns or remanufacturing. Geographic supply concentrates in China, Germany, and Japan, leveraging established chemical manufacturing infrastructure. The supply chain draws from raw material dependencies on fumarate and ammonia. Commodity price volatility for these chemical inputs presents a significant structural risk. Downstream distribution primarily operates through established channels for industrial customers, increasingly shifting towards direct engagement for specialized nutraceutical and pharmaceutical buyers seeking transparency.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aspartic acid market is fundamentally supply-constrained, with the substantial capital investment required for GMP-compliant fermentation plants propping up pricing in high-purity segments.
For Market Incumbents: Deploy advanced bioprocessing R&D to enhance production yields and purity, mitigating feedstock price volatility. Pursue strategic partnerships with bio-based feedstock suppliers to secure long-term, sustainable inputs. This defends against emerging clean-label trends and strengthens competitive positioning in premium segments.
For New Entrants and Emerging Players: Enter via niche applications in bio-based polymers, targeting agricultural or water treatment sectors where polyaspartic acid offers a biodegradable alternative. Focus initial market penetration on Southeast Asian and Latin American dietary supplement markets, leveraging efficient production processes. A go-to-market angle emphasizing non-GMO and fermentation-derived claims can secure early market share.
For Investors and Strategic Acquirers: Stricter global purity mandates, such as China's updated GB standards, are the leading indicator that consolidation will continue among high-grade producers. Long-term viability favors companies with proprietary enzymatic synthesis technologies and strong regulatory compliance records. Target acquisition archetypes include mid-sized specialists with established intellectual property in bioprocessing or unique access to sustainable raw material streams.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in High-Purity Grades | Increases supply for rapidly expanding nutraceutical and pharmaceutical sectors. |
| Investment in Bio-based Feedstock Sourcing | Secures sustainable raw materials and aligns with clean-label consumer preferences. |
| Enhanced Traceability and Certification Programs | Meets stringent regulatory requirements and buyer demand for verifiable product data. |
| Targeted R&D for Polyaspartic Acid | Unlocks new high-value applications in agriculture and water treatment. |
| Strategic Partnerships in Emerging Markets | Expands distribution networks and accesses growing dietary supplement consumer bases. |
Research Approach
Trade association data, regulatory filings from bodies like the US FDA and Europe's EFSA, and customs records anchored secondary inputs for this analysis. Primary research involved in-depth interviews with R&D directors, procurement leads at chemical manufacturers, regulatory affairs specialists, and plant managers across key geographies. This dual approach ensured comprehensive data collection and validation through both top-down market sizing and bottom-up supply chain perspectives.
The analytical framework reconciled multiple data streams to construct a robust forecast across the analysis window. Segmentation dimensions included grade tier, end-use industry, application, physical form, and regional regulatory cluster. Compound annual growth rates were derived from historical data trends and projected future demand scenarios. Industry-specific forecast inputs included anticipated growth in nutraceutical consumption and the evolution of global food additive standards.
Revisions become necessary when significant shifts in feedstock prices, new regulatory mandates, or the market introduction of competitive substitute technologies materialize. Forecasts reflect assumptions regarding economic stability and technological advancement over the projection horizon. Practitioners should monitor global trade policies and bioprocessing innovations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Europe Lactic Acid Market
Organic Chemicals
North America Phenol Market
Organic Chemicals
Dioctyl Maleate (DOM) Market
Organic Chemicals
Cyclic Ketones Market
Organic Chemicals
Heterocyclic and Fluoro Organic Compounds Market
Organic Chemicals
Gamma-Butyrolactone (GBL) Market
Organic Chemicals
Global Ketones Market
Organic Chemicals
Long-Chain Dicarboxylic Acid Market
Organic Chemicals
Trimethylcyclohexanone Market
Organic Chemicals
Acetaldehyde Market
Organic Chemicals
Global Pseudocumene Market
Organic Chemicals
Acrylonitrile Market
Organic Chemicals
2,6-Dichloro Aniline Market
Organic Chemicals
Global Biphenyl Market
Organic Chemicals
Phenol Market
Organic Chemicals
Crotonic Acid Market