
 Oryzenin Market | 2026-2036
Oryzenin Market Size, Share, and Industry Trends Forecast 2026-2036
Oryzenin Market Intelligence
Modular ingredient bundling is repositioning how oryzenin suppliers package protein systems for food manufacturers. Kerry Group PLC leverages its flavor-protein integration expertise to anchor clean-label formulation partnerships. Axiom Foods Inc. specializes in allergen-free protein isolates that dominate premium sports nutrition channels. BENEO GmbH extends its functional ingredient portfolio to compete on digestive health positioning in European markets.
Oryzenin denotes the globulin storage protein fraction extracted from rice (Oryza sativa), typically comprising 80% protein by dry weight with a balanced amino acid profile including substantial cysteine and methionine content, produced through aqueous extraction followed by isoelectric precipitation or membrane filtration for use as a hypoallergenic plant protein ingredient. The isolate segment commands premium pricing due to superior protein content and minimal carbohydrate carryover, while the concentrate grade sustains volume leadership in cost-sensitive applications such as bakery and meat analogs. Sports nutrition represents the fastest-growing end use industry as athletic consumers shift from whey toward dairy-free alternatives, whereas food and beverage maintains the deepest installed base across dairy-alternative beverages and infant nutrition.
The FDA governs oryzenin labeling and GRAS self-affirmation pathways in the United States, while the EMA and EFSA shape novel food approvals and health claim substantiation across European markets. China's NMPA and GB standards dictate import thresholds and protein purity requirements for rice-derived ingredients entering Asia-Pacific supply chains. Stakeholders must monitor evolving protein quality scoring methodologies and regional allergen threshold definitions as these standards increasingly determine market access and formulation eligibility.
Market Dynamics
Modular ingredient bundling is compressing traditional protein supply relationships as food manufacturers demand pre-integrated flavor-protein systems rather than discrete raw materials.
Growth Catalysts
- EU Green Deal plant-protein targets:The framework mandates procurement redirection toward sustainable sources, accelerating reformulation of dairy-alternative portfolios across European food manufacturers.
- Sports nutrition channel expansion:Athletic consumers are displacing whey with dairy-free alternatives, creating concentrated demand for hypoallergenic rice protein isolates in premium supplement formulations.
- Germany:Food manufacturers in this market are concentrating reformulation activity, establishing the country as the primary demand anchor for oryzenin procurement within the European Union.
Market Restraints
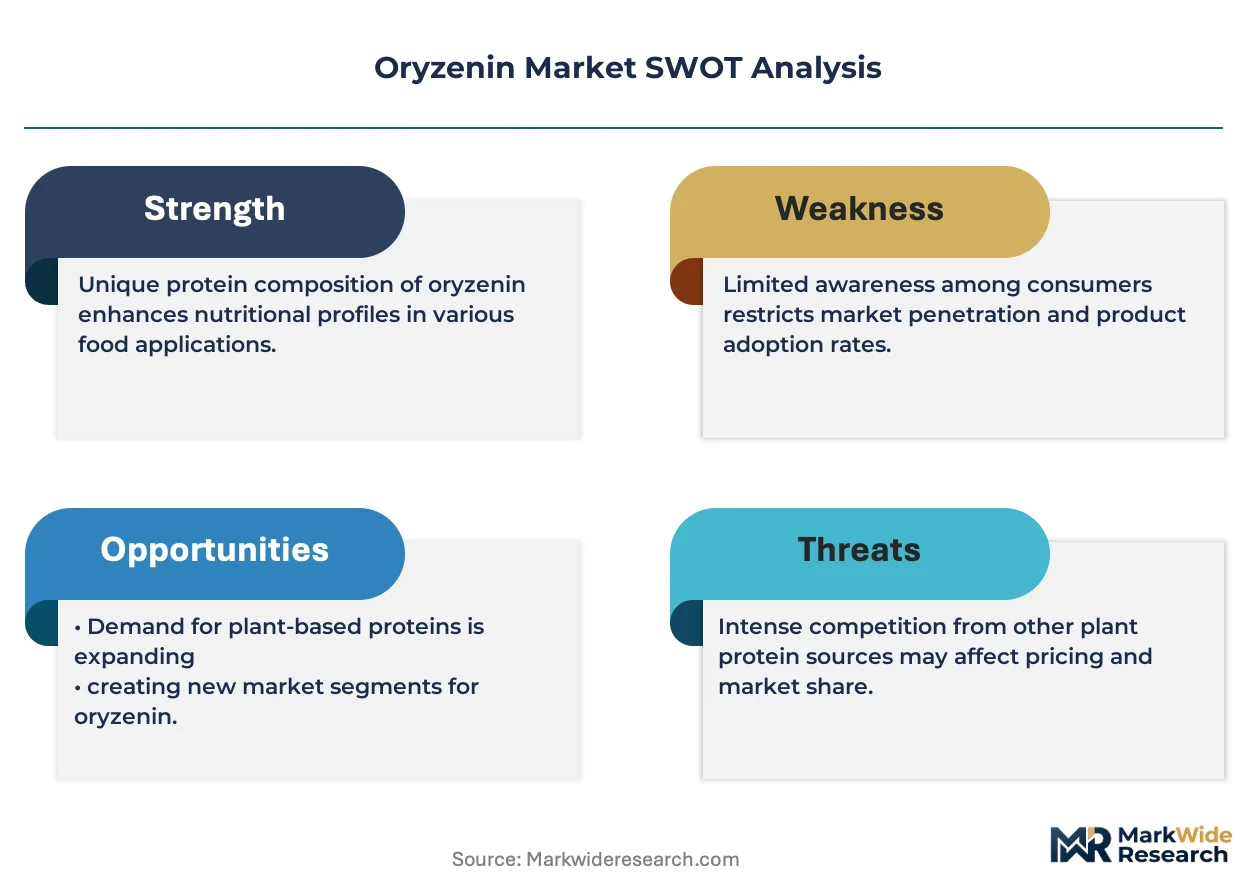
- Input cost volatility:Rice grain prices fluctuate with climate-induced harvest variability, compressing margin predictability for isolate producers dependent on specific Oryza sativa cultivars.
- Technical limitation:Aqueous extraction yields remain below 85% for high-purity isolates, constraining throughput scalability relative to pea and soy protein processes.
- Substitution threat:Pea protein isolates offer comparable amino acid completeness at lower unit economics, pressuring oryzenin positioning in cost-sensitive bakery and meat analog applications.
Strategic Opportunities
- Infant nutrition underpenetration:Hypoallergenic positioning creates white space in pediatric formula segments where dairy and soy sensitivities drive caregiver preference for rice-derived alternatives.
- Membrane filtration technology convergence:Integration of ceramic microfiltration with isoelectric precipitation is enabling protein purity thresholds above 90% with reduced carbohydrate carryover.
- Clean-label certification tailwind:Non-GMO Project and EU organic standards create premium pricing tiers that reward oryzenin's natural extraction pathway versus chemically processed alternatives.
Industry Challenges
- Specialized process engineering talent:Scarcity of technicians trained in aqueous protein extraction and membrane system operation constrains facility expansion timelines for isolate producers.
- GRAS self-affirmation complexity:FDA documentation requirements for novel food applications create 18-24 month approval cycles that delay market entry for innovative oryzenin formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oryzenin Market |
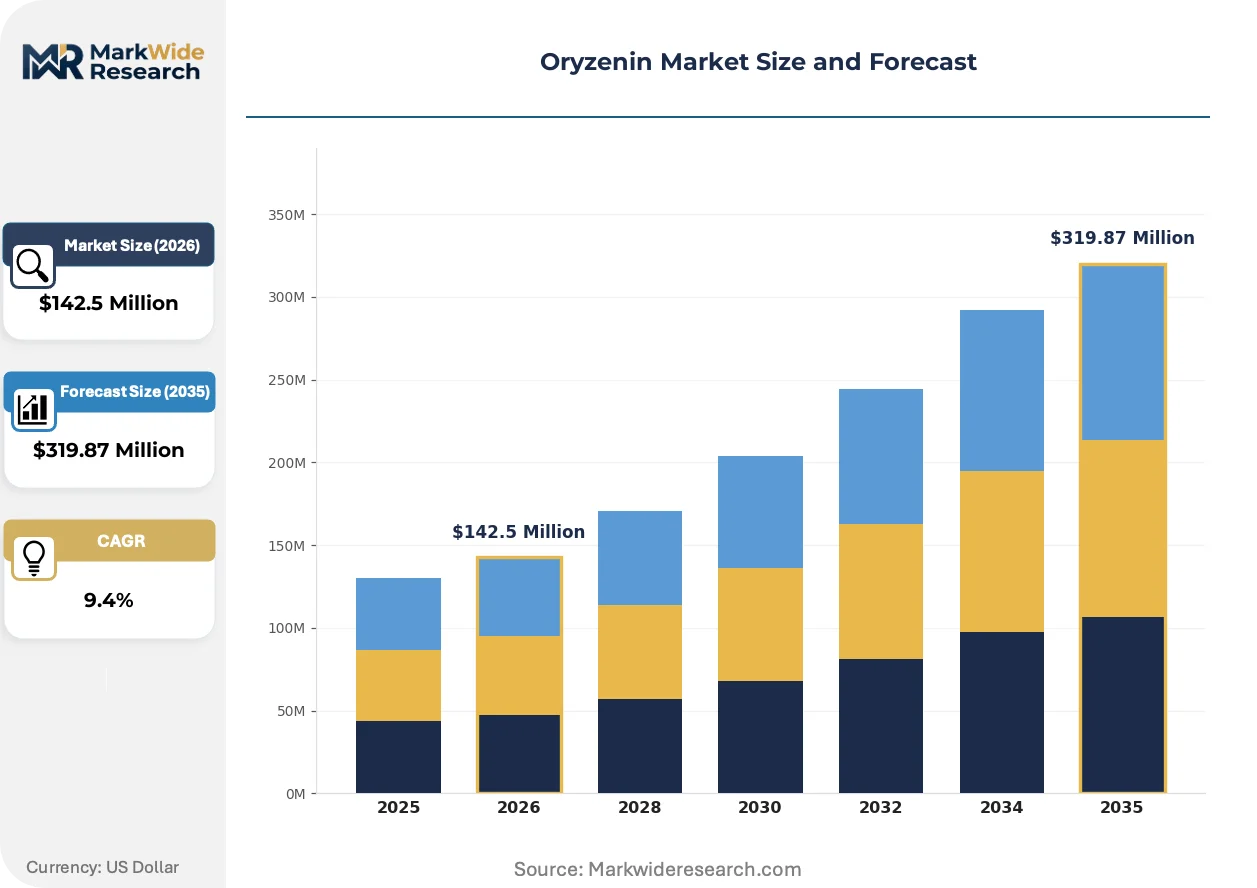
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $319.87 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolate, Concentrate, Hydrolysate, Textured End Use Industry: Food & Beverage, Sports Nutrition, Animal Feed, Pharmaceuticals Form: Powder, Liquid, Granule, Capsule Distribution Channel: Online, Offline, Direct Sales, Third-Party Retailers |
| Companies Covered | Axiom Foods Inc., Kerry Group PLC, Südzucker AG, AIDP Inc., RiceBran Technologies, Bioway Organic Group Ltd., BENEO GmbH, Shaanxi Fuheng Biotechnology Co. Ltd., The Green Labs LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oryzenin Market Strategic Shifts & Innovations
Protein ingredient architecture is fragmenting into configurable subsystems that let manufacturers swap functional components without reformulating entire product lines.
Membrane filtration cascades are modularizing oryzenin production workflows. Equipment suppliers now deliver skid-mounted separation units that isolate processors can reconfigure for varying protein purity targets. Sports nutrition brands are adopting these modular inputs fastest, enabling rapid SKU proliferation without captive processing infrastructure. This compression of technical barriers is democratizing access to pharmaceutical-grade protein specifications.
REACH substance registration requirements are tightening purity documentation for rice-derived ingredients entering European cosmetic and nutraceutical channels. ECHA compliance deadlines are forcing suppliers to invest in analytical testing infrastructure for heavy metal and pesticide residue quantification. Infant nutrition manufacturers face the steepest certification burden, as EFSA novel food opinions now require extended toxicological datasets for protein isolates used in pediatric applications.
Athletic consumers are compressing their supplement switching cycles as dairy-free alternatives proliferate across retail and direct-to-commerce channels. Brand loyalty is eroding in favor of rapid trial of emerging protein sources, with Amazon and specialized sports nutrition e-commerce platforms capturing share from traditional brick-and-mortar distribution. Germany and the United States exhibit the most pronounced channel fragmentation, where influencer-driven discovery is displacing physician or trainer recommendations as the primary purchase trigger.
Oryzenin Market Segmentation
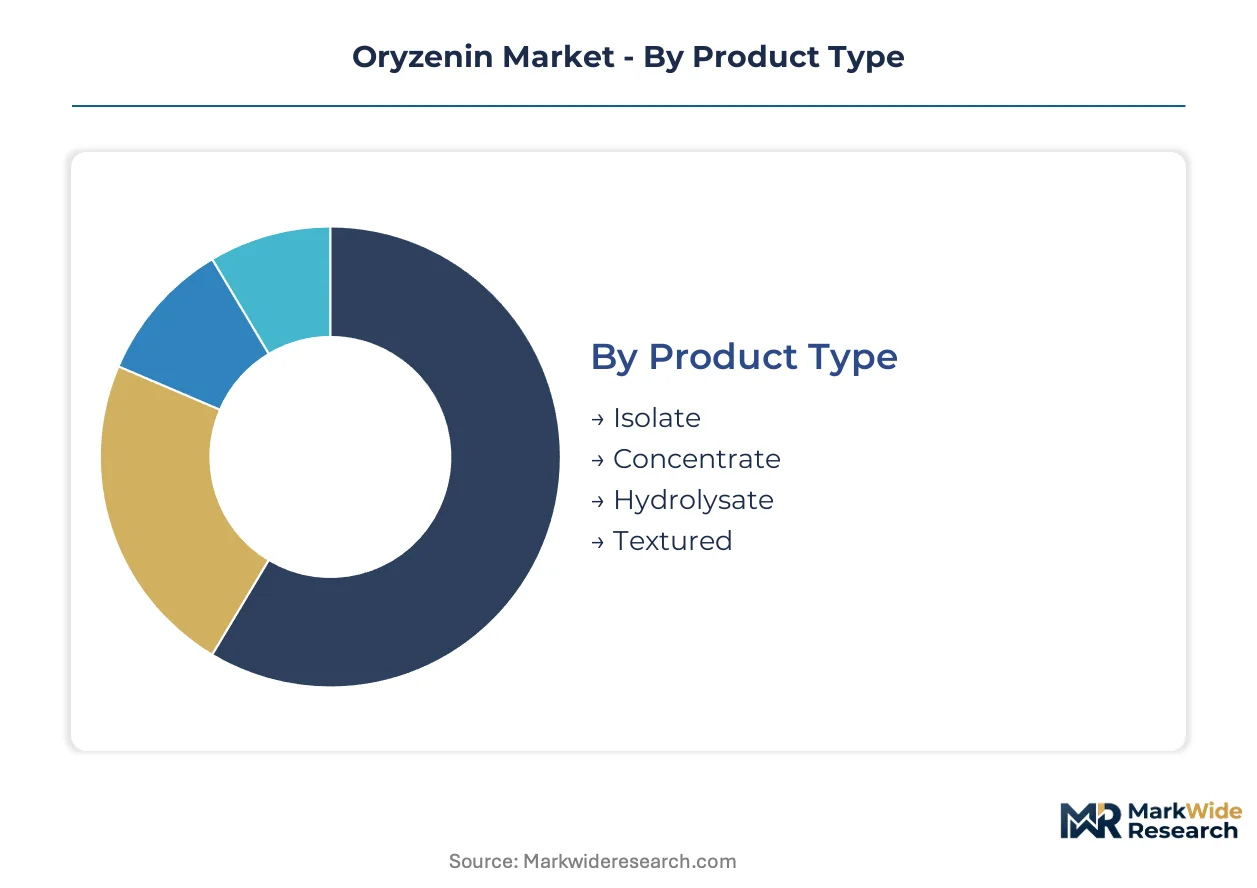
Oryzenin suppliers must align product specifications with distinct regulatory pathways across infant nutrition, sports supplements, and pharmaceutical applications. Each segment carries unique certification burdens that determine formulation eligibility and market access timelines.
Product Type:
EFSA novel food opinions and FDA GRAS self-affirmation requirements vary sharply by purity tier, with isolate and hydrolysate grades facing the steepest toxicological documentation burdens for pediatric and clinical applications.
- Isolate:Comprising 80-90% protein by dry weight with minimal carbohydrate carryover, this grade demands aqueous extraction followed by isoelectric precipitation or membrane filtration. Demand concentrates in Germany's sports nutrition channel as athletic consumers displace whey with dairy-free alternatives, though EFSA extended toxicological datasets delay pediatric formulation approvals by 18-24 months.
- Concentrate:Lower purity specifications (50-70% protein) sustain cost-sensitive volume applications across European bakery and meat analog portfolios. Germany's food manufacturers anchor procurement for this grade, prioritizing EU Green Deal compliance over premium certification tiers.
- Hydrolysate:Enzymatically pre-digested for rapid absorption, this grade serves clinical nutrition and premium infant formula segments where hypoallergenic positioning commands regulatory scrutiny.
- Textured:Extruded protein structures replicate meat fibrousness for European plant-based meat analogs, with texture specifications governed by EFSA food additive frameworks rather than novel food pathways.
Leading the category by volume: Concentrate. Growing fastest: Isolate.
End Use Industry:
Cost tier stratification separates pharmaceutical-grade specifications from commodity food applications, with certification investment determining margin structure across each vertical.
- Food & Beverage:Dairy-alternative beverages and infant nutrition sustain the deepest installed base, with EU organic and Non-GMO Project certifications creating premium pricing tiers that reward natural extraction pathways.
- Sports Nutrition:Athletic consumers compress supplement switching cycles as dairy-free alternatives proliferate across Amazon and specialized e-commerce platforms. Germany and the United States exhibit the most pronounced channel fragmentation, where influencer-driven discovery displaces traditional retail.
- Animal Feed:Pet food manufacturers leverage hypoallergenic positioning for premium companion animal nutrition, though regulatory oversight remains lighter than human food applications.
- Pharmaceuticals:Clinical nutrition and medical foods demand pharmaceutical-grade protein specifications with REACH substance registration and ECHA compliance for heavy metal documentation.
Highest certification investment: Pharmaceuticals. Steepest expansion trajectory: Sports Nutrition.
Form:
Supply concentration in powder processing infrastructure shapes competitive dynamics, with liquid and capsule formats requiring downstream conversion partnerships that compress margin capture for isolate producers.
- Powder:Dominates bulk ingredient procurement for food manufacturers and sports nutrition brands, with spray-dried specifications enabling extended shelf stability and transport efficiency.
- Liquid:Ready-to-drink dairy alternatives and clinical nutrition products drive demand, though cold chain requirements constrain distribution reach relative to dry formats.
- Granule:Intermediate flow properties serve instant beverage and dry mix applications where dispersibility specifications determine formulation acceptance.
- Capsule:Pre-measured dosing for supplement convenience commands premium positioning, with encapsulation equipment investment creating barriers for mid-tier suppliers.
Deepest volume penetration: Powder. Narrowest supplier base: Capsule.
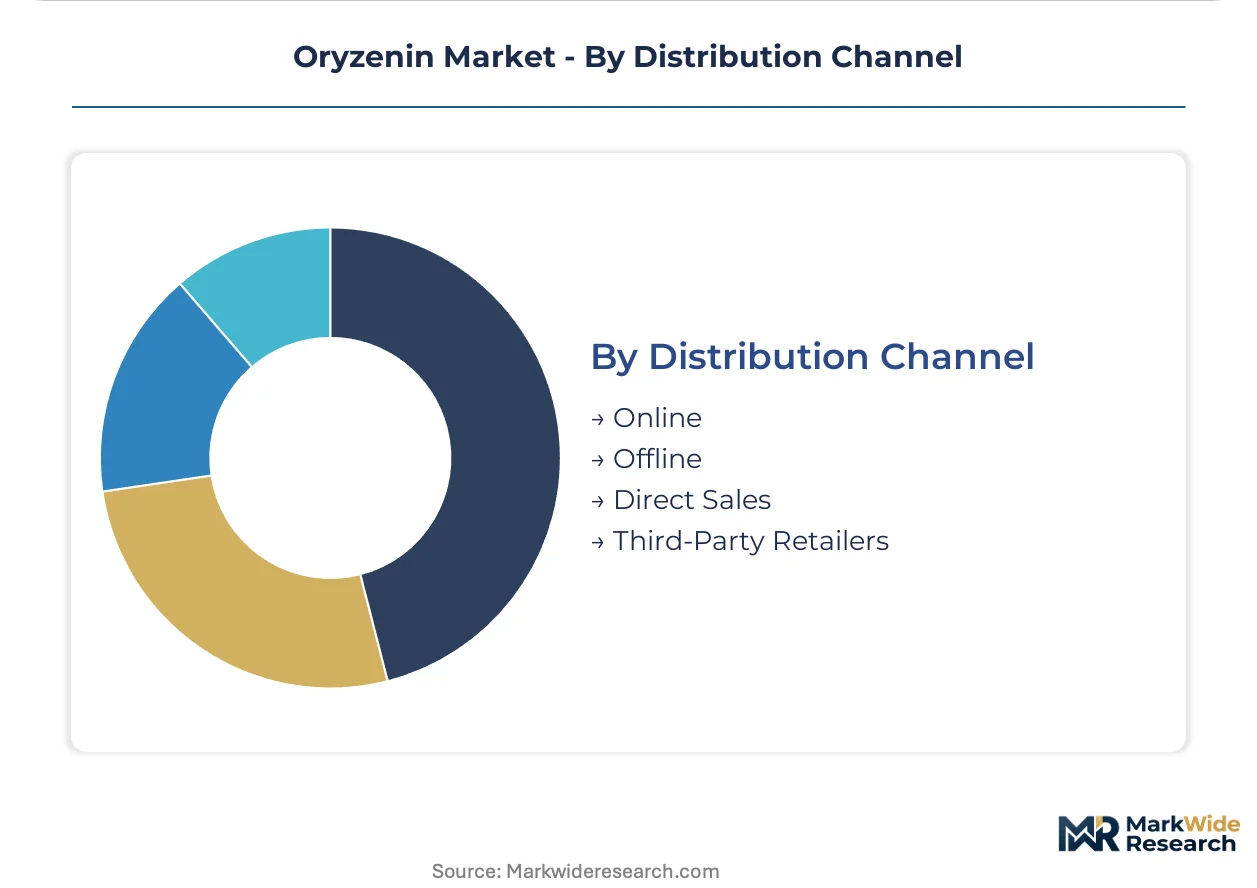
Distribution Channel:
Customer type fragmentation between institutional procurement and direct-to-consumer brands is restructuring channel economics, with third-party retailers ceding share to specialized e-commerce platforms.
- Online:Amazon and sports nutrition direct-to-commerce platforms capture share from brick-and-mortar as athletic consumers prioritize rapid trial of emerging protein sources over brand loyalty.
- Offline:Traditional retail and food service distribution sustain volume for cost-sensitive concentrate grades, particularly across German supermarket private label programs.
- Direct Sales:Ingredient suppliers bypass intermediaries to anchor clean-label formulation partnerships with major food manufacturers, compressing traditional protein supply relationships.
- Third-Party Retailers:Supplement specialty stores and natural products distributors face margin pressure as influencer-driven discovery shifts purchase triggers away from trained recommendations.
Fastest channel shift: Online. Most relationship-dependent: Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Asia-Pacific rice-growing regions while consumption concentrates in Western sports nutrition and infant formula markets. Germany anchors European procurement as food manufacturers accelerate dairy-alternative reformulation. The United States drives premium isolate demand through direct-to-commerce supplement channels.
Germany
Food manufacturers in Bavaria and North Rhine-Westphalia concentrate reformulation of dairy-alternative portfolios under EU Green Deal procurement mandates. EFSA novel food opinions govern oryzenin approvals for pediatric applications, extending certification timelines. Cologne and Hamburg host ingredient distributors serving clean-label formulation partnerships across the European Union.
United States
Athletic consumers displace whey protein with rice-derived alternatives across Amazon and specialized sports nutrition platforms. FDA GRAS self-affirmation pathways regulate novel food applications, creating documentation-intensive approval cycles. California and Texas anchor direct-to-commerce brand concentration where influencer-driven discovery reshapes purchase behavior.
China
Domestic rice processing infrastructure supplies concentrate grades for cost-sensitive Asian bakery and meat analog applications. NMPA and GB standards dictate protein purity thresholds for ingredient exports. Yangtze River Delta processors invest in membrane filtration capacity to serve pharmaceutical-grade specifications for Western nutraceutical brands.
India
Growing sports nutrition channel adoption drives isolate imports for premium supplement formulations targeting urban athletic consumers. FSSAI regulates plant protein labeling and safety standards for domestic and export markets. Maharashtra and Karnataka concentrate food technology startups reformulating traditional dairy alternatives with hypoallergenic positioning.
Japan
Clinical nutrition and elderly care segments sustain demand for hydrolysate grades with rapid absorption properties. PMDA and METI shape functional food and medical food regulatory frameworks. Tokyo-Osaka corridor hosts pharmaceutical-grade protein distributors serving aging-population nutrition applications.
Oryzenin Market Key Industry Players
The competitive structure tilts toward integrated ingredient systems providers over discrete raw material suppliers. Tiered specialization separates flavor-protein integrators from allergen-free isolate specialists and functional fiber extension players. Dominant competitive moves include clean-label certification investment and membrane filtration technology licensing to compress purity thresholds.
Within the integrated systems tier, Kerry Group PLC and BENEO GmbH represent archetypes of flavor-protein bundling and functional portfolio extension respectively. Axiom Foods Inc. occupies a position exemplifying allergen-free specialization for premium sports nutrition channels. These three anchors illustrate how geographic origin and corporate structure shape strategic positioning: Irish-incorporated PLC, German GmbH, and US-based Inc. each leverage distinct regulatory familiarity and customer relationship architectures.
| Leading Market Players |
|---|
| Axiom Foods Inc. |
| Kerry Group PLC |
| Südzucker AG |
| AIDP Inc. |
| RiceBran Technologies |
| Bioway Organic Group Ltd. |
| BENEO GmbH |
| Shaanxi Fuheng Biotechnology Co. Ltd. |
| The Green Labs LLC |
| Others |
Cost & Logistics Intelligence
EU Green Deal procurement mandates for sustainable plant-protein sourcing are forcing food manufacturers to absorb certification premiums, compelling isolate suppliers to reconfigure extraction workflows around membrane filtration investments that compress margin structures.
Pricing Analysis
Margin tightening in pharmaceutical-grade isolates reflects EFSA extended toxicological dataset requirements and REACH substance registration burdens. Three-tier pricing structure across premium, standard, and economy levels separates Non-GMO Project certified isolates from EU organic concentrates and commodity bakery grades. Pricing pressure intensifies in concentrate tiers as pea protein isolates offer comparable amino acid completeness at lower unit economics. Food and beverage manufacturers exhibit highest price sensitivity, while infant nutrition formulators accept premium positioning for hypoallergenic certification.
Supply Chain Analysis
Specialized technicians trained in aqueous protein extraction and ceramic microfiltration operation remain scarce across Yangtze River Delta and Maharashtra processing clusters. Supply concentrates in China, India, and Germany, with membrane filtration equipment and Oryza sativa cultivar selection as critical input dependencies. Single-source vulnerability in pharmaceutical-grade ceramic membrane supply creates chokepoint exposure for isolate purity thresholds above 90%. Distribution runs through direct sales partnerships with major food manufacturers and Amazon-direct sports nutrition platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The oryzenin market functions as a cost-of-compliance arena where EFSA novel food opinion timelines and FDA GRAS self-affirmation cycles erect 18-24 month barriers that reward pre-certified incumbents with formulation lock-in advantages.
For Market Incumbents: Acquire membrane filtration technology licensing to anchor pharmaceutical-grade purity thresholds above 90% before pea protein competitors match hypoallergenic positioning. Consolidate clean-label certification portfolios around Non-GMO Project and EU organic standards to defend against emerging Asian isolate producers. Capacity addition in Germany's North Rhine-Westphalia cluster secures EU Green Deal procurement anchoring. For New Entrants and Emerging Players: Pediatric formula manufacturers underserved by extended EFSA toxicological approval timelines represent the most penetrable white space for hydrolysate-grade specialists. Clinical nutrition channels in Japan's aging-population corridor offer premium absorption-grade positioning with lighter competitive density than sports nutrition. Direct-to-commerce influencer partnerships bypass brick-and-margin retail gatekeepers. For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with captive membrane filtration infrastructure and existing EFSA novel food dossiers. Long-term viability hinges on consolidation of analytical testing capabilities for heavy metal and pesticide residue quantification under REACH compliance deadlines. Watch EFSA pediatric formulation opinion acceleration as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Technology Licensing | Enables protein purity thresholds above 90% with reduced carbohydrate carryover for pharmaceutical specifications. |
| EFSA Novel Food Dossier Investment | Compresses 18-24 month pediatric formulation approval cycles into competitive moat against unqualified entrants. |
| Clean-Label Certification Portfolio | Non-GMO Project and EU organic standards unlock premium pricing tiers that reward natural extraction pathways. |
| Direct Sales Partnership Expansion | Bypasses intermediaries to anchor formulation relationships with Kerry Group PLC and BENEO GmbH tier customers. |
| Specialized Process Engineering Talent Acquisition | Alleviates technician scarcity constraining facility expansion timelines for aqueous extraction operations. |
Research Approach
Independent corroboration across primary interviews with isolate production plant managers, sports nutrition brand procurement leads, EFSA regulatory affairs specialists, and infant nutrition formulation directors, plus secondary validation through FDA GRAS notices, EFSA novel food opinions, REACH substance registrations, and customs trade data, underwrites the qualitative findings. Bottom-up protein purity tier demand modeling triangulates against top-down EU Green Deal procurement mandate tracking.
Comparable-period anchoring to historical sports nutrition channel shifts and infant formula reformulation cycles structures the projection horizon. Segmentation dimensions span isolate-concentrate-hydrolysate-textured grades, food and beverage-sports nutrition-pharmaceutical end uses, and powder-liquid-granule-capsule forms. CAGRs derive from installed base erosion rates in whey displacement and membrane filtration capacity expansion trajectories. Rice grain harvest variability and climate-induced input cost volatility feed scenario-weighted outputs.
Revisions become necessary when EFSA accelerates pediatric toxicological dataset requirements, FDA modifies GRAS self-affirmation pathways, or membrane filtration equipment lead times extend beyond facility commissioning schedules. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Dimethylformamide (DMF) Market
Organic Chemicals
Heterocyclic and Fluoro Organic Compounds Market
Organic Chemicals
1,3-Dioxolane Market
Organic Chemicals
Cyclohexanone Market
Organic Chemicals
Pentachlorophenol Market
Organic Chemicals
Bio-Acetic Acid Market
Organic Chemicals
North America Cycloalkanes Market
Organic Chemicals
Alanine Market
Organic Chemicals
1,3-Dichloroacetone Market
Organic Chemicals
N-Hexanol Market
Organic Chemicals
Dioctyl Phthalate Market
Organic Chemicals
Asia-Pacific Synthetic Camphor Market
Organic Chemicals
Methyl Isobutyl Ketone (MIBK) Market
Organic Chemicals
Lithium Chemicals Market
Organic Chemicals
Cycloalkanes Market
Organic Chemicals
Dioctyl Maleate (DOM) Market